
 Singapore ICT Market | 2026-2036
Singapore ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore ICT Market Outlook
Enterprise buyer concentration is expanding as Singapore's financial services and government agencies consolidate procurement around fewer, larger technology contracts. Singtel anchors domestic connectivity infrastructure through extensive fiber and 5G assets. Google Asia Pacific Pte. Ltd. leverages its hyperscale cloud footprint to serve regional headquarters clustered in the city-state. Amazon Web Services (AWS) Singapore competes aggressively on managed service breadth for regulated industries.
Information and communications technology encompasses the integrated systems of hardware, software, networking, and services that enable data processing, storage, transmission, and retrieval across organizational boundaries. Cloud Services leads product type revenue as enterprises migrate legacy workloads to elastic infrastructure. Hybrid Cloud deployment models represent the fastest-growing architecture as banks and healthcare providers balance sovereignty requirements with scalability needs. Consulting and system integration services capture disproportionate margin pools from complex multi-cloud transformations.
Singapore's Infocomm Media Development Authority (IMDA) shapes market access through accreditation frameworks and digital infrastructure standards. The Personal Data Protection Commission (PDPC) enforces data localization and breach notification rules that dictate product design for both local vendors and foreign cloud operators. Enterprise buyers must weigh IMDA's cloud security standards against PDPC compliance costs when selecting between public, private, and hybrid architectures.
Market Dynamics
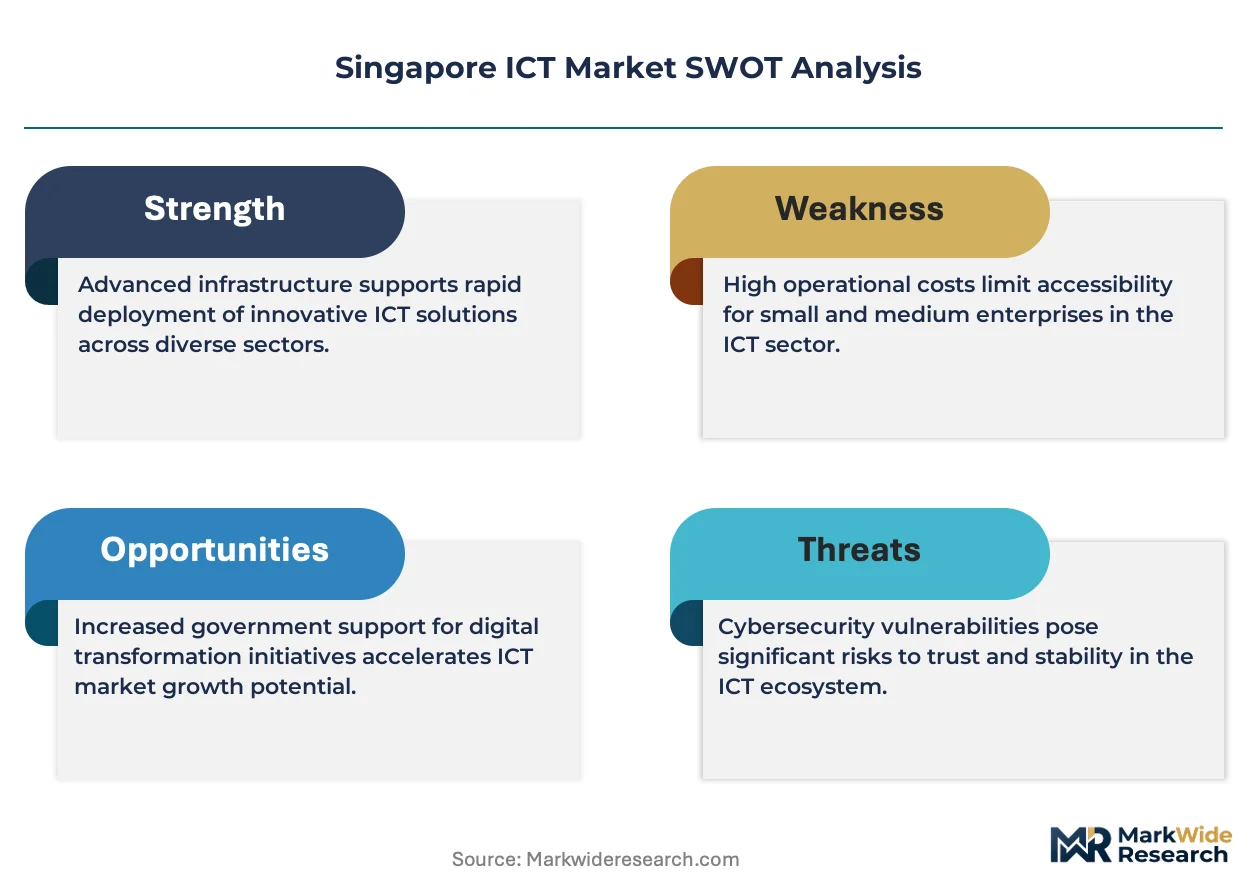
Enterprise procurement consolidation around hybrid cloud architectures is compressing vendor margins while amplifying compliance costs from Singapore's Personal Data Protection Act amendments. Financial institutions and government agencies now demand sovereign data controls alongside hyperscale elasticity.
Growth Catalysts
- PDPA Amendment Obligations:Singapore's tightened breach notification and data localization rules compel banks and healthcare providers to refresh legacy infrastructure. Compliance spending flows directly into accredited cloud and security services.
- IMDA Accreditation Frameworks:The Infocomm Media Development Authority's cloud security standards create procurement shortcuts for certified vendors. Enterprise buyers default to pre-approved providers, accelerating contract velocity.
- Financial Services Digitalization:Wealth management and insurance firms in Singapore's central business district are unbundling core banking systems. This generates demand for API-native infrastructure and managed service wrappers.
Market Restraints
- Cross-Border Data Transfer Friction:PDPC adequacy requirements limit Singapore-headquartered multinationals from freely routing data through regional hyperscale nodes. Compliance overhead constrains architecture flexibility.
- Specialized Talent Scarcity:Multi-cloud engineering and sovereign security architecture skills command premium compensation. Skills gaps extend implementation timelines for complex hybrid deployments.
- Concentrated Fiber Infrastructure:Singtel's dominance in submarine cable landing stations and last-mile fiber creates single-point vulnerability. Enterprise buyers face limited redundancy options for mission-critical connectivity.
Strategic Opportunities
- Green Data Center Incentives:Singapore's temporary moratorium on new data center construction has shifted toward sustainability-linked capacity allocations. Operators with carbon-neutral designs gain preferential access to power grid connections.
- AI Governance Services:The IMDA's AI Verify testing framework creates advisory revenue pools. System integrators can package compliance tooling with model deployment services for regulated sectors.
- Submarine Cable Diversification:New cable systems landing in Tuas and Changi reduce latency to Southeast Asian markets. Singapore-based enterprises can capture regional workload orchestration contracts.
Industry Challenges
- Legacy System Entanglement:Core banking and claims processing platforms at Singapore's incumbent financial institutions resist containerization. Migration complexity inflates consulting costs and extends payback periods.
- Certification Backlogs:IMDA's Multi-Tier Cloud Security accreditation queue delays go-to-market timelines for new entrants. Foreign hyperscale operators face extended compliance validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore ICT Market |
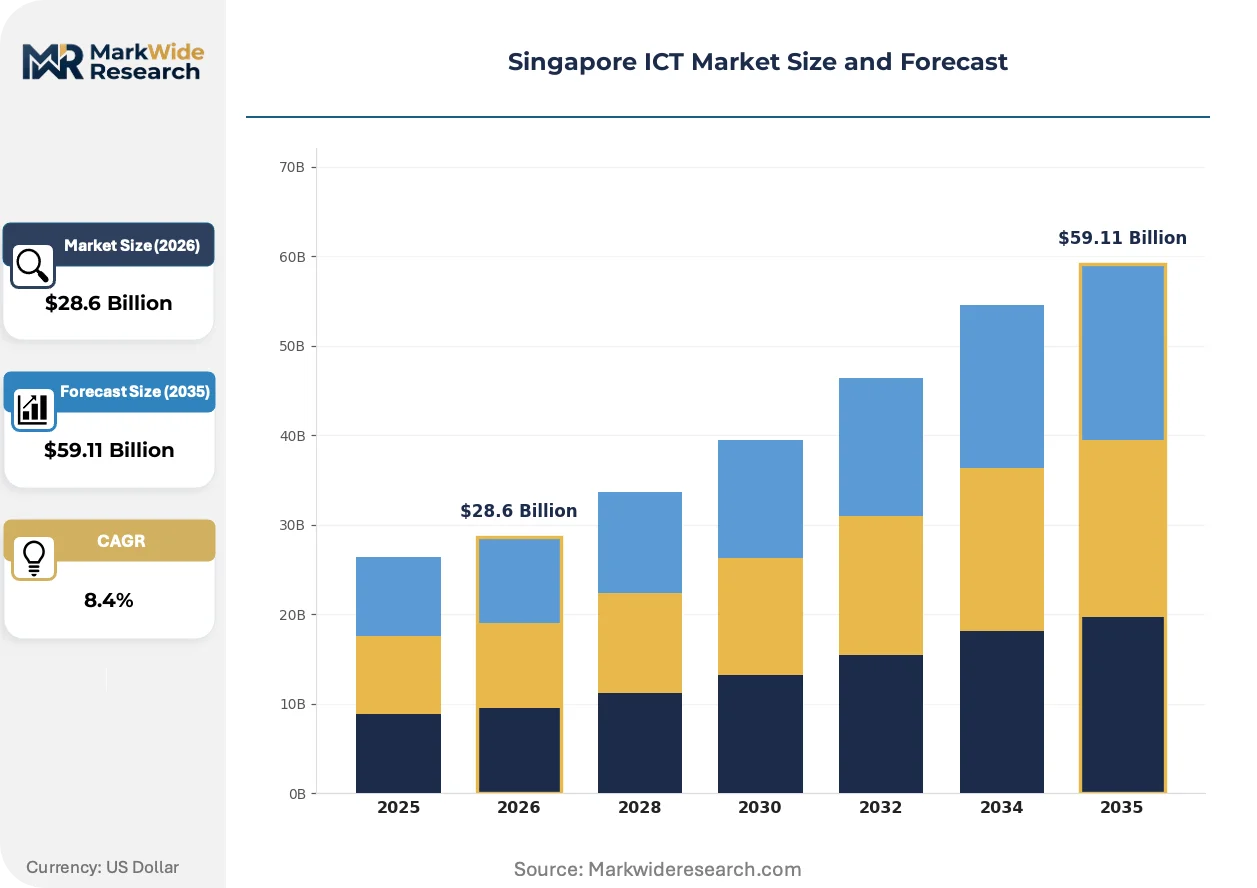
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud Services, Software Solutions, Hardware Components, Networking Equipment End User: Government Agencies, Educational Institutions, Financial Services, Healthcare Providers Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Service Type: Managed Services, Consulting, System Integration, Technical Support |
| Companies Covered | Micron Semiconductor Asia Operations Pte. Ltd., Google Asia Pacific Pte. Ltd., Singapore Telecommunications Ltd. (Singtel), TPG Telecom Pte. Ltd., Intel Technology Asia Pte. Ltd., Amazon Web Services (AWS) Singapore, Cognizant Technology Solutions Asia Pacific Pte. Ltd., M1 Ltd., StarHub Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore ICT Market Strategic Shifts
Artificial intelligence workloads are forcing infrastructure redesigns across Singapore's enterprise base. Sovereignty requirements and sustainability mandates now filter technology choices before performance specifications.
Confidential computing architectures are expanding into regulated sectors. These hardware-based isolation technologies encrypt data during processing. Singapore's banking consortiums are piloting confidential nodes for cross-institutional analytics without exposing raw customer records. The technology is expanding into credit risk modeling and fraud detection pipelines previously blocked by data sharing restrictions.
Singapore's PDPC has tightened enforcement timelines for breach notification, compressing incident response windows to seventy-two hours. Financial institutions must now maintain always-on forensic capabilities. The regulation is reshaping managed security service contracts, with enterprise buyers demanding sub-hour escalation clauses and local security operations center presence.
Enterprise technology sourcing is consolidating around outcome-based contracts with penalty clauses. Large banks and government agencies now procure infrastructure as operational expenditure with availability guarantees. System integrators absorb capital risk while competing on automation efficiency. This model is most visible in Singapore's public healthcare cluster, where multi-year managed service agreements replace traditional hardware refresh cycles.
Singapore ICT Market Segmentation
Singapore's ICT procurement patterns fragment sharply across compliance sensitivity, sovereignty requirements, and legacy modernization urgency. Buyers in financial services and government clusters select technology architectures through fundamentally different filters than healthcare or education segments.
Product Type:
Cost tier differentiation separates buyers seeking operational expenditure flexibility from those preserving capital-intensive infrastructure control.
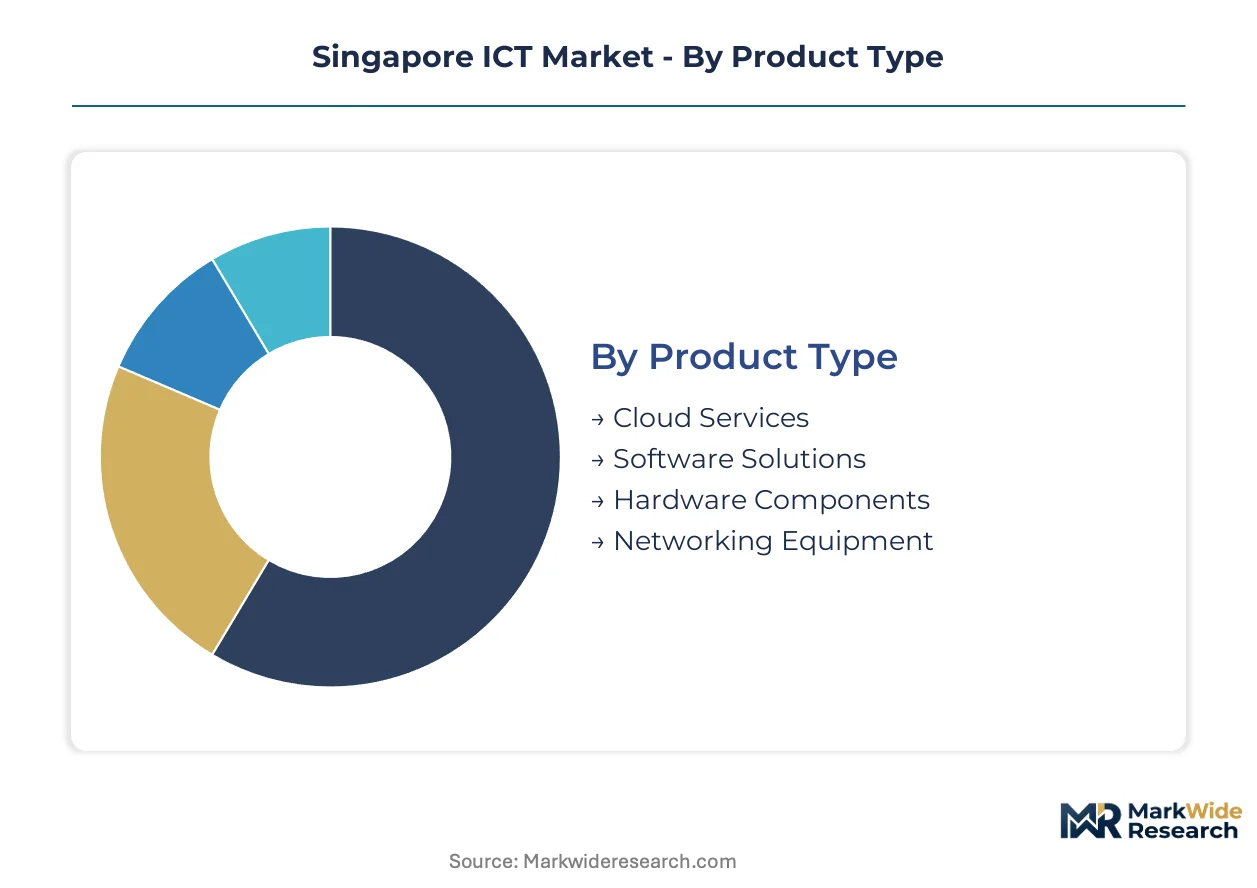
- Cloud Services:Elastic compute, storage, and platform resources delivered via subscription models dominate enterprise procurement. Financial services firms in the central business district and government agencies under IMDA accreditation frameworks drive demand for sovereign cloud instances with localized data residency controls.
- Software Solutions:Enterprise applications span ERP, CRM, and sector-specific platforms requiring PDPA-compliant data handling modules. Healthcare providers at Singapore's public hospital clusters prioritize clinical workflow systems with embedded consent management and audit trail functionality.
- Hardware Components:Servers, storage arrays, and endpoint devices support regulated workloads requiring physical infrastructure ownership.
- Networking Equipment:Routers, switches, and SD-WAN appliances enable low-latency connectivity across Singtel-dominated fiber infrastructure.
Volume sits with Cloud Services; growth tilts toward Software Solutions.
End User:
Application criticality shapes procurement sophistication — transaction-intensive sectors demand sovereign controls while service-delivery sectors prioritize interoperability.
- Government Agencies:Ministries and statutory boards operate under IMDA cloud security standards and PDPC data localization mandates. These buyers require accredited vendors with local security operations centers and sub-hour incident escalation protocols.
- Financial Services:Banks, insurers, and wealth managers face compressed breach notification windows under amended PDPA rules. Core banking unbundling generates demand for API-native infrastructure with confidential computing capabilities for cross-institutional analytics.
- Healthcare Providers:Public hospital clusters and private medical groups manage patient data under strict consent and purpose limitation requirements.
- Educational Institutions:Universities and polytechnics procure collaboration platforms and research computing with lighter sovereignty constraints.
Procurement sophistication concentrates in Financial Services; expansion momentum favors Healthcare Providers.
Deployment Model:
Margin structures diverge sharply — standardized public offerings compress vendor returns while customized hybrid architectures capture premium pricing.
- Hybrid Cloud:Workload placement across public elasticity and private sovereignty domains addresses banks and healthcare providers balancing scalability with data residency. This architecture demands complex orchestration tooling and multi-cloud engineering expertise that commands premium implementation fees.
- Private Cloud:Dedicated infrastructure instances serve government agencies and financial institutions with zero-tolerance for multi-tenancy risk. Singtel and accredited hyperscale operators compete for contracts requiring local data center presence and carbon-neutral power sourcing.
- Public Cloud:Shared infrastructure resources suit development environments and non-regulated workloads.
- On-Premises:Legacy data center retention persists where containerization of core systems remains incomplete.
Architecture complexity peaks in Hybrid Cloud; standardization pressure weighs most heavily on Public Cloud.
Service Type:
Customer maturity determines whether buyers purchase discrete capabilities or integrated outcome-based contracts with availability guarantees.
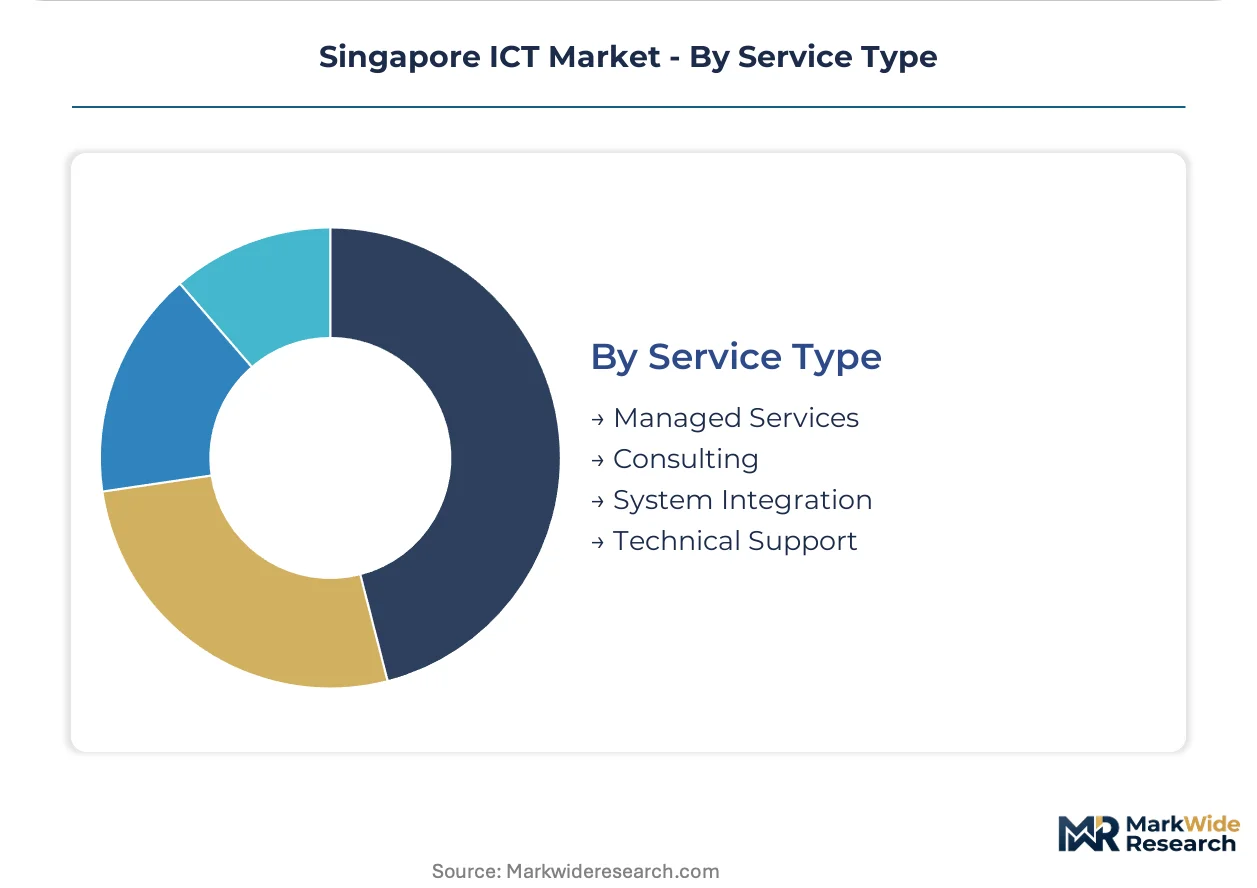
- System Integration:Multi-cloud transformation projects combine legacy migration, API development, and compliance tooling into multi-year engagements. Singapore's public healthcare cluster and large banks now procure these services through operational expenditure models with penalty clauses for downtime.
- Managed Services:Continuous infrastructure operations and security monitoring absorb capital risk from enterprise buyers. Financial institutions demand local security operations center presence and seventy-two-hour breach notification capabilities under tightened PDPC enforcement timelines.
- Consulting:Advisory engagements span cloud strategy, AI governance under IMDA's AI Verify framework, and PDPA compliance roadmap development.
- Technical Support:Break-fix and maintenance contracts sustain legacy infrastructure estates.
Contract value concentrates in System Integration; recurring revenue stability favors Managed Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial services and government agencies concentrate procurement in Singapore's central business district and digital infrastructure corridors. The IMDA's accreditation frameworks and PDPA amendments shape vendor selection across the city-state's enterprise base.
Central Region
Marina Bay and Raffles Place host regional headquarters of multinational banks driving hybrid cloud demand. The Monetary Authority of Singapore's technology risk management guidelines mandate resilient infrastructure for trading platforms. Data center clusters in Tanjong Kling and Jurong support sovereign cloud instances for regulated workloads.
East Region
Changi Business Park anchors logistics and aviation technology procurement. The Civil Aviation Authority of Singapore's digital transformation programs generate demand for edge computing and IoT infrastructure. Submarine cable landings at Changi reduce latency to Southeast Asian markets for regional workload orchestration.
West Region
Jurong Innovation District and Tuas host advanced manufacturing and biomedical technology investments. The Economic Development Board's incentives attract semiconductor packaging and testing operations. New cable systems landing in Tuas diversify connectivity routes away from Singtel-dominated infrastructure.
North Region
Woodlands and Yishun concentrate public sector agencies and healthcare technology procurement. The Ministry of Health's digital health initiatives drive demand for clinical workflow systems with embedded consent management. Public hospital clusters here prioritize PDPA-compliant patient data architectures.
Northeast Region
Punggol Digital District and Seletar emerging as media and cybersecurity hubs. The IMDA's PIXEL innovation space anchors content technology and AI governance advisory services. Educational institutions here procure research computing with lighter sovereignty constraints than financial or healthcare sectors.
Singapore ICT Market Competitive Environment
Established telecommunications operators occupy the standard tier; emerging hyperscale entrants pursue cloud-native infrastructure dominance. The vendor base stratifies around connectivity ownership, cloud platform scale, and compliance certification depth. Three archetypes dominate: national carriers with fiber assets, hyperscale operators with regional cloud footprints, and system integrators with sovereign security expertise. Competitive moves center on sustainability-linked data center capacity allocation and AI governance advisory service packaging.
Within the national carrier tier, Singapore Telecommunications Ltd. anchors domestic connectivity through submarine cable landing stations and 5G infrastructure. Google Asia Pacific Pte. Ltd. and Amazon Web Services Singapore exemplify the hyperscale archetype, leveraging regional cloud footprints to serve headquarters-clustered enterprises. These three occupy positions across the infrastructure stack from physical connectivity through platform services to managed security operations.
| Leading Market Players |
|---|
| Micron Semiconductor Asia Operations Pte. Ltd. |
| Google Asia Pacific Pte. Ltd. |
| Singapore Telecommunications Ltd. (Singtel) |
| TPG Telecom Pte. Ltd. |
| Intel Technology Asia Pte. Ltd. |
| Amazon Web Services (AWS) Singapore |
| Cognizant Technology Solutions Asia Pacific Pte. Ltd. |
| M1 Ltd. |
| StarHub Ltd. |
| Others |
Value Chain & Pricing Dynamics
Confidential computing hardware and sovereign cloud architectures are simultaneously inflating infrastructure costs and concentrating procurement around IMDA-accredited providers with certified security operations centers. Singapore's PDPA amendments compress vendor selection timelines while amplifying compliance premiums for data localization capabilities.
Pricing Analysis
Volume concentrates in standardized public cloud subscriptions while margins migrate to hybrid orchestration and managed security services. Pricing stratifies across sovereign-certified tiers, carbon-neutral data center premiums, and outcome-based availability guarantees. Cost compression in public compute is intensifying as AWS and Google Asia Pacific compete on reserved instance discounts. Government agencies exhibit lowest price sensitivity due to mandate-driven procurement, while educational institutions prioritize cost-per-seat metrics.
Supply Chain Analysis
Regional distribution centers in Singapore, Malaysia, and Indonesia anchor hardware fulfillment for Southeast Asian enterprise deployments. Semiconductor components for servers and networking equipment draw from Taiwan, South Korea, and USA fabrication facilities. Single-source vulnerability concentrates in Singtel's submarine cable landing stations and last-mile fiber infrastructure. Distribution runs through systems integrators with IMDA Multi-Tier Cloud Security accreditation, who bundle hardware procurement with compliance tooling and local security operations center staffing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's ICT market sits in a technology-transition phase as confidential computing and sovereign cloud architectures displace legacy on-premises data center estates. Hybrid deployment models are replacing pure public cloud strategies across financial services and government segments.
For Market Incumbents: Deploy carbon-neutral data center capacity expansion to capture sustainability-linked power grid allocations from Singapore's Economic Development Board. Defend against hyperscale encroachment by deepening fiber infrastructure redundancy through Tuas and Changi cable landing diversification. Certification investment in IMDA's AI Verify framework creates advisory revenue moats around model governance services.
For New Entrants and Emerging Players: AI governance tooling and compliance automation software represent the most penetrable white-space adjacent to saturated infrastructure markets. Target healthcare providers and public sector agencies with lighter existing cloud penetration than financial services. A channel partnership strategy with accredited system integrators accelerates procurement velocity through pre-approved vendor shortlists.
For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscale acquisition of sovereign security specialists and private equity rollup of regional managed services platforms. Long-term viability favors operators with IMDA accreditation depth and local security operations center presence rather than pure connectivity plays. The signal to watch is enforcement intensity of PDPA breach notification timelines compressing incident response vendor selection criteria.
| Strategic Initiative | Industry Significance |
|---|---|
| IMDA Multi-Tier Cloud Security Certification | Accreditation unlocks procurement shortcuts with government and financial services buyers under tightened compliance mandates. |
| Carbon-Neutral Data Center Buildout | Sustainability-linked power grid allocations from Singapore's Economic Development Board confer preferential capacity access. |
| AI Verify Framework Advisory Services | IMDA's testing standard creates packaged compliance revenue for model deployment in regulated banking and healthcare sectors. |
| Submarine Cable Diversification Investment | New Tuas and Changi landings reduce latency to Southeast Asian markets and dilute Singtel infrastructure concentration risk. |
| Outcome-Based Managed Service Contracts | Operational expenditure models with availability guarantees absorb capital risk from public healthcare and government agency buyers. |
Study Parameters
Trade databases, IMDA accreditation registries, and hyperscaler regional capex disclosures formed the secondary backbone for supply-side sizing. Primary interviews with cloud procurement officers at financial institutions, government technology leads, and system integrator practice heads validated demand assumptions. Bottom-up and top-down triangulation cross-checked segment-level projections against aggregate market estimates derived from infrastructure investment tracking.
Bottom-up modeling aggregated individual contract values across deployment models while top-down analysis calibrated totals against national ICT expenditure surveys. Segmentation dimensions spanned product type, end-user vertical, deployment architecture, and service delivery model across the analysis window. CAGRs were derived from fitted growth curves applied to infrastructure investment cycles and regulatory compliance spending waves. Forecast inputs incorporated PDPA amendment implementation timelines and IMDA cloud security standard adoption curves.
Several conditions sit outside the modeled scope, including unforeseen regulatory enforcement intensity shifts and geopolitical disruptions to submarine cable routing. Forecasts reflect assumptions about sustained financial services digitalization and government cloud migration commitments. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart City Technology
City Data Platform Market
Smart City Technology
Global Smart Pole Market
Smart City Technology
Smart Communities Market
Smart City Technology
Global Smart/Connected Street Lights Market
Smart City Technology
Global Smart Hubs Market
Smart City Technology
Smart City Framework Market
Smart City Technology
Smart Shade Device Market
Smart City Technology
Global Smart Ticketing Market
Smart City Technology
UAE Smart Furniture Market
Smart City Technology
US Smart Cities Market
Smart City Technology
Smart Ticketing Solutions Market
Smart City Technology
Smart Parking Meters Market
Smart City Technology
Smart Parcel Locker Market
Smart City Technology
Smart Signaling Market
Smart City Technology
Global Smart City ICT Infrastructure Market
Smart City Technology
India Smart City Market