
 Global Smart Ticketing Market | 2026-2036
Global Smart Ticketing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Ticketing Market Foresight
Modular fare bundling across transit, parking, and event access is hardening as the dominant product configuration. NXP Semiconductors leverages its secure element portfolio to anchor chip-level trust in multi-application cards. Thales competes through integrated back-office platforms that unify account-based ticketing across operator networks. Cubic Corporation specializes in open-payment convergence, enabling bank card and mobile wallet acceptance without proprietary media.
Smart ticketing comprises electronic fare collection systems using contactless chips, mobile tokens, or biometric identifiers to authenticate and record passenger or attendee journeys. NFC-enabled cards and smartphone wallets transmit encrypted credentials through ISO 14443-compliant radio interfaces at 13.56 MHz, with transaction authorization typically completing in under 300 milliseconds. The technology serves to eliminate cash handling, reduce boarding dwell time, and generate granular origin-destination data for network optimization. Near Field Communication occupies the largest installed base among technologies, though Bluetooth Low Energy is gaining traction for hands-free gateless validation in high-volume environments. Public Transit generates the dominant revenue pool, while Event Management presents the fastest expansion trajectory as organizers replace paper credentials with digital wallet passes.
The European Commission's GDPR and the EU AI Act constrain biometric facial recognition deployments in transport settings, compelling vendors to architect privacy-by-design tokenization. The US Federal Transit Administration and the UK's Department for Transport enforce interoperability mandates that prevent vendor lock-in through open standards like ITSO and Calypso. India's Ministry of Housing and Urban Affairs drives national common mobility card integration across metro and bus networks. Stakeholders must monitor whether emerging EU digital identity wallet frameworks will subsume proprietary ticketing apps or create parallel credential ecosystems.
Market Dynamics
The migration from card-based closed-loop systems to account-based open-payment architectures is compressing hardware refresh cycles and forcing incumbents to recalibrate platform economics around transaction fees rather than media sales.
Growth Catalysts
- India's National Common Mobility Card:The Ministry of Housing and Urban Affairs mandates interoperable credentials across metro and bus networks, aggregating fragmented municipal procurements into standardized tenders.
- Bluetooth Low Energy validation:Hands-free gateless entry in high-volume environments reduces physical infrastructure requirements while cutting passenger processing time below 200 milliseconds.
- Germany's contactless fare acceleration:Deutsche Bahn and regional transit authorities are retiring magnetic stripe systems ahead of federal interoperability deadlines.
Market Restraints
- Secure element supply concentration:Semiconductor fabrication for payment-grade chips clusters in Taiwan and South Korea, exposing procurement timelines to geopolitical friction.
- GDPR biometric friction:The EU AI Act's strictures on facial recognition in public transport force vendors to maintain parallel tokenized and biometric authentication stacks.
- Legacy system stranded costs:Calypso and MIFARE Classic deployments in Southern European transit networks resist write-off acceleration despite security vulnerabilities.
Strategic Opportunities
- Brazil's urban mobility digitization:São Paulo and Rio de Janeiro metro expansions lack incumbent vendor relationships, creating greenfield procurement windows for integrated platform providers.
- Event-wallet convergence:Sports stadiums and music festivals are adopting transit-integrated credentialing, bundling parking, transit, and venue access into single-token experiences.
- EU Digital Identity Wallet frameworks:The European Commission's eIDAS 2.0 implementation may subsume proprietary ticketing apps, creating API-layer revenue models for credential verification services.
Industry Challenges
- Embedded systems cybersecurity specialization:Shortage of engineers fluent in both ISO 27001 compliance and real-time fare transaction processing extends platform certification timelines.
- Multi-operator settlement complexity:Revenue allocation across competing transit agencies demands blockchain or distributed ledger architectures that most back-office platforms lack natively.
- Interoperability testing fragmentation:ITSO, Calypso, and EMV specifications require separate certification tracks, multiplying pre-deployment validation costs for multi-market vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Ticketing Market |
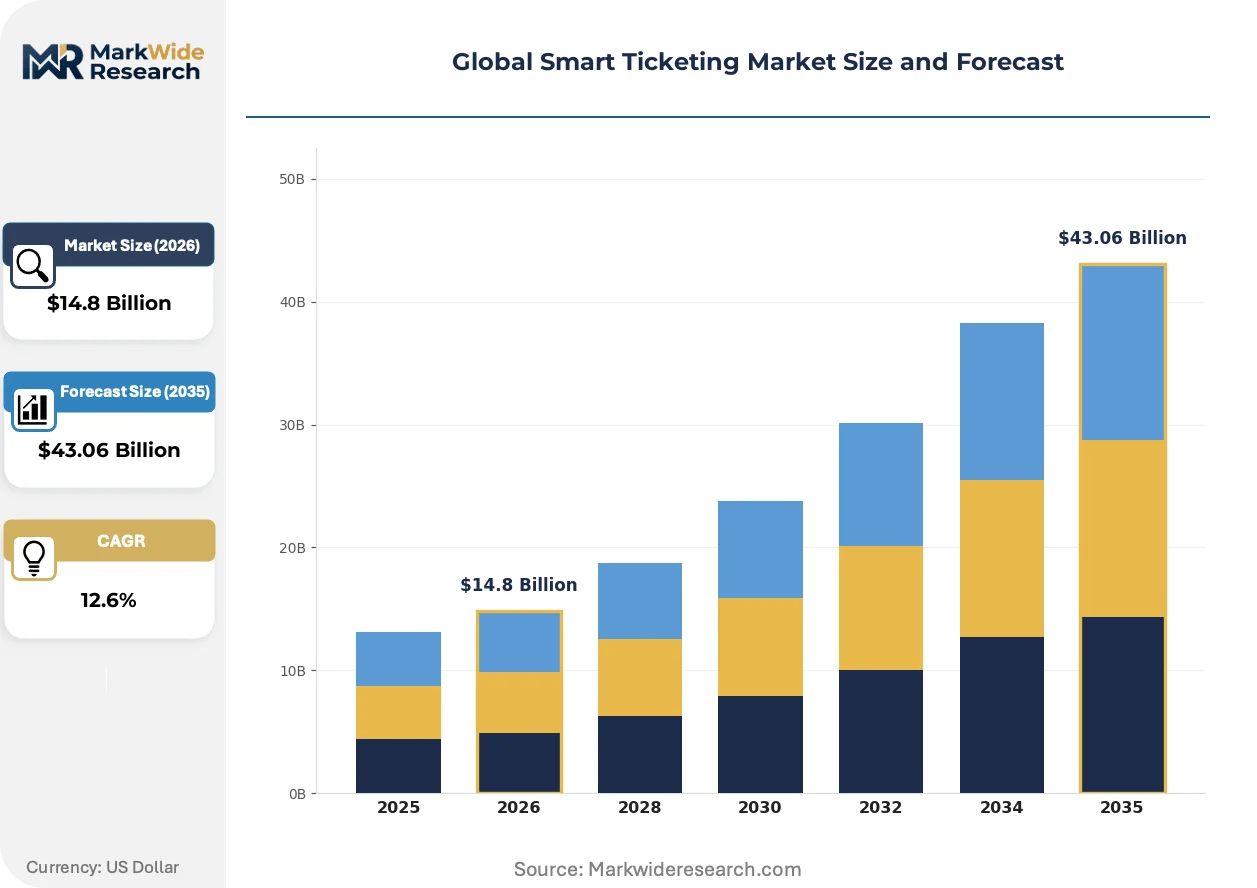
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $43.06 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Near Field Communication, QR Code, Bluetooth Low Energy, Magnetic Stripe, Radio Frequency Identification, Barcode Application: Public Transit, Event Management, Theme Parks, Toll Collection, Parking Management, Corporate Access End User: Government Agencies, Transportation Operators, Event Organizers, Parking Authorities Distribution Channel: Online Platforms, Mobile Apps, Kiosks, Retail Outlets, Authorized Resellers |
| Companies Covered | Giesecke+Devrient, NXP Semiconductors, Conduent, Siemens Mobility, Infineon Technologies, Thales, HID Global, Hitachi, Cubic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Ticketing Market Shifts & Advancements
Architectural shifts in credential storage and authentication methods are redistributing value capture between hardware manufacturers, software platforms, and financial intermediaries.
Biometric tokenization is integrating facial and palm-vein recognition into privacy-preserving cryptographic protocols that bind identity to ephemeral transaction keys rather than persistent identifiers. Transit operators in Singapore and Dubai are piloting these systems for frequent-traveler lanes, compressing enrollment friction for account-based ticketing while satisfying data minimization principles. The structural consequence is a compression in card manufacturing demand as physical media becomes optional for enrolled users.
The EU AI Act's risk-based classification system for biometric identification in public spaces is forcing vendors to architect explainability and human-in-the-loop override capabilities into automated fare gates. Systems deployed in France and the Netherlands now default to tokenized fallback authentication when confidence thresholds drop below regulatory thresholds. This compliance burden most affects airport and cross-border rail segments where biometric convenience promises the highest passenger throughput gains.
Subscription-based mobility-as-a-service bundling is displacing single-journey ticket purchases among corporate commuter programs and university campus deployments. Employers in the United Kingdom and Germany are consolidating transit, bike-share, and ride-hail allowances into pre-tax benefit platforms that require deep API integration with smart ticketing back-ends. This shift is most visible in metropolitan labor markets where talent retention depends on frictionless commute subsidies.
Global Smart Ticketing Market Segmentation
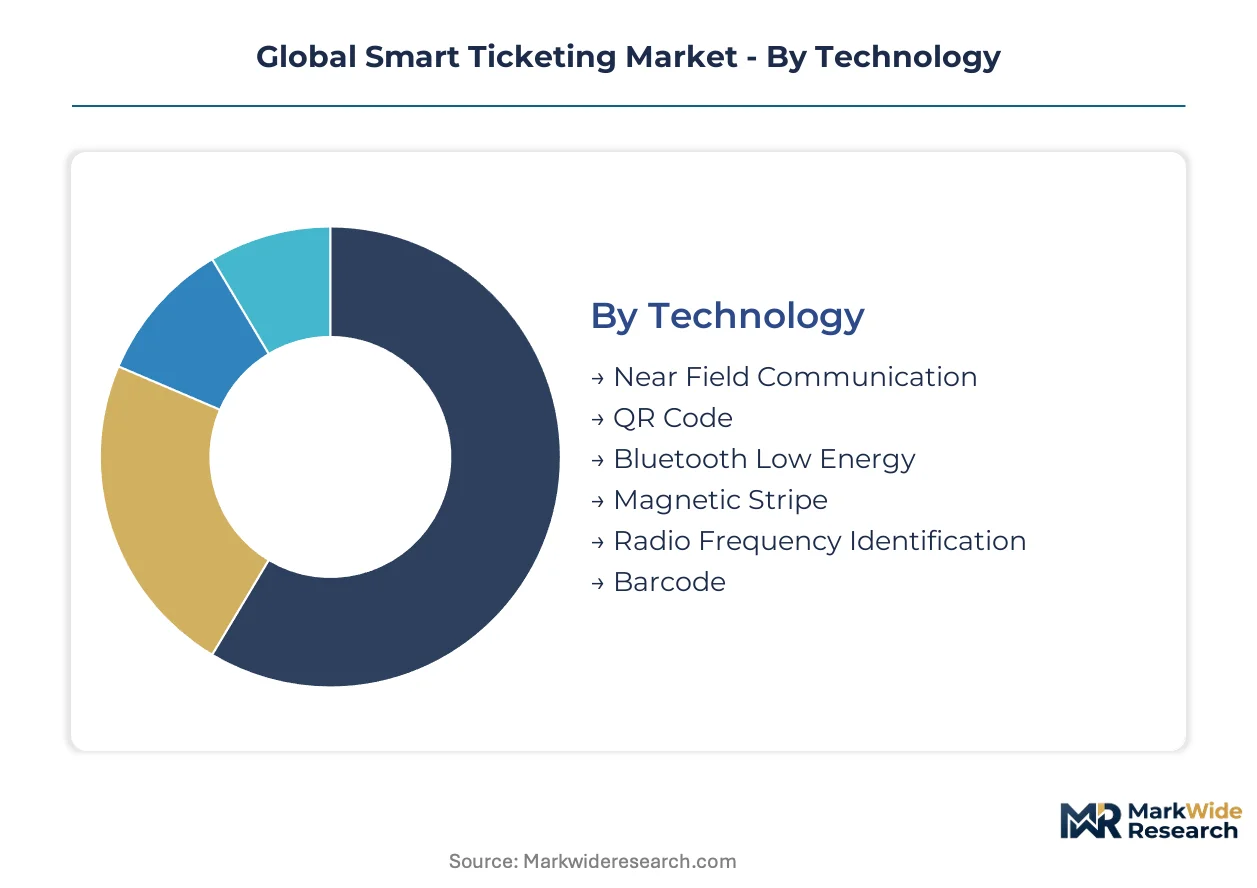
Smart ticketing technology fragments across credential formats, deployment contexts, and procurement channels. Each segment carries distinct hardware refresh cycles, regulatory exposure, and margin structures that shape vendor strategy.
Technology:
Hardware upgrade timelines diverge sharply across credential technologies, with contactless standards displacing legacy magnetic infrastructure in transit networks.
- Near Field Communication:ISO 14443-compliant radio interfaces at 13.56 MHz dominate installed transit bases, with encrypted credential exchange completing in under 300 milliseconds. Demand concentrates in German and British rail networks retiring proprietary closed-loop cards for open-payment convergence.
- Bluetooth Low Energy:Hands-free gateless validation operates at 2.4 GHz with passenger processing below 200 milliseconds, eliminating physical infrastructure in high-volume environments. Singapore and Dubai airports pilot these systems for frequent-traveler lanes where enrollment friction must compress.
- QR Code:Optical scanning enables low-cost smartphone credentialing without dedicated hardware terminals.
- Magnetic Stripe:Legacy transit deployments in Southern Europe resist accelerated write-offs despite security vulnerabilities.
- Radio Frequency Identification:UHF passive tags serve long-range vehicle identification in toll collection corridors.
- Barcode:Printed credentials persist in event access and parking validation where smartphone penetration remains uneven.
Volume placements concentrate in Near Field Communication; the faster expansion belongs to Bluetooth Low Energy.
Application:
Functional requirements vary by venue throughput, credential durability demands, and integration complexity with existing access control.
- Public Transit:Account-based architectures now displace card-centric closed-loop systems, compressing hardware refresh cycles while forcing platform economics toward transaction fees. India's National Common Mobility Card mandates drive standardized tenders across metro and bus networks.
- Event Management:Digital wallet passes replace paper credentials, bundling transit, parking, and venue access into single-token experiences. Sports stadiums and music festivals in Brazil and the United Kingdom adopt these configurations fastest.
- Theme Parks:Multi-day credentialing with ride-reservation integration demands durable waterproof media.
- Toll Collection:Vehicle-mounted RFID tags enable non-stop highway passage with automatic account debiting.
- Parking Management:License plate recognition convergence reduces dedicated credential issuance.
- Corporate Access:Building entry and cafeteria payment unification drives smart card deployment in enterprise campuses.
Public Transit captures the dominant revenue pool; Event Management climbs the fastest.
End User:
Procurement authority shapes specification rigor, with government tenders enforcing interoperability mandates that private operators often bypass.
- Government Agencies:Federal interoperability deadlines in Germany and the United Kingdom prevent vendor lock-in through ITSO and Calypso standards compliance. India's Ministry of Housing and Urban Affairs aggregates fragmented municipal procurements into national frameworks.
- Transportation Operators:Deutsche Bahn and regional British authorities accelerate contactless deployments ahead of regulatory cutoffs.
- Event Organizers:Sports and entertainment venues prioritize rapid credential issuance over long-term interoperability.
- Parking Authorities:Municipal and private operators diverge on open-payment acceptance requirements.
Procurement volume clusters with Government Agencies; Transportation Operators expand credential issuance most aggressively.
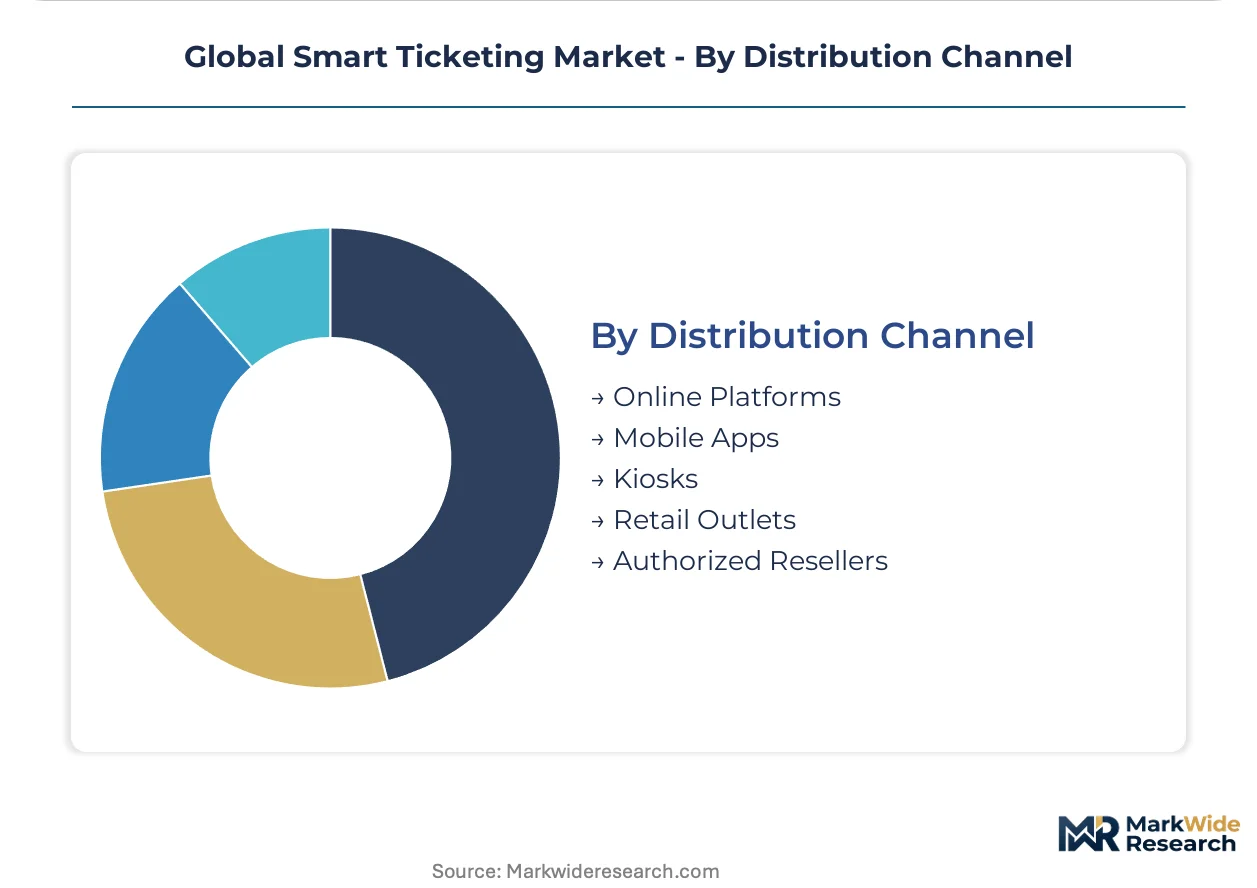
Distribution Channel:
Customer acquisition costs and enrollment friction vary dramatically across physical and digital touchpoints.
- Online Platforms:Web-based account creation enables pre-trip credential provisioning, reducing station queuing. Corporate commuter programs in Germany and the United Kingdom consolidate transit, bike-share, and ride-hail allowances through these channels.
- Mobile Apps:Smartphone wallet integration dominates in markets with high digital payment penetration.
- Kiosks:Self-service terminals serve unbanked populations and tourist segments lacking local app store access.
- Retail Outlets:Convenience store networks extend credential availability in underserved corridors.
- Authorized Resellers:System integrators bundle hardware and software for mid-sized transit operators.
Transaction volume concentrates in Online Platforms; Mobile Apps gain share fastest in digitally mature markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's National Common Mobility Card program and Germany's federal interoperability deadlines are concentrating procurement authority in government-led standardization frameworks across major transit networks.
Germany
Deutsche Bahn and regional transit authorities are accelerating contactless deployments ahead of federal deadlines. The country's ITSO and Calypso standards compliance mandates prevent vendor lock-in across operator networks. Berlin and Munich anchor the largest hardware refresh cycles as magnetic stripe systems retire.
United Kingdom
The Department for Transport enforces open standards that compress procurement timelines for account-based ticketing platforms. London's Transport for London leads contactless bank card acceptance integration across bus and underground networks. Manchester and Birmingham are expanding smart ticketing to regional rail corridors.
India
The Ministry of Housing and Urban Affairs aggregates fragmented municipal procurements into national tender frameworks. Mumbai Metro and Delhi Metro anchor the largest credential issuance volumes as urban rail expansions concentrate demand. Bangalore and Hyderabad are integrating bus networks with metro interoperability.
Singapore
LTA Corporation pilots Bluetooth Low Energy hands-free validation for frequent-traveler lanes at Changi Airport. The country's data protection authority shapes biometric tokenization requirements for transport settings. The Jurong Lake District smart city cluster tests integrated mobility-as-a-service bundling.
Brazil
São Paulo and Rio de Janeiro metro expansions lack incumbent vendor relationships, creating greenfield procurement windows. ANVISA and municipal transit regulators are drafting interoperability specifications for open-payment convergence. The São Paulo metropolitan rail network is tendering integrated platform contracts.
Global Smart Ticketing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware, software, and integrated platform layers. The vendor base clusters around three strategic archetypes: semiconductor fabricators supplying secure elements, systems integrators delivering end-to-end transit platforms, and software specialists enabling mobile wallet convergence. Consolidation pressure is accelerating through strategic partnerships between chip manufacturers and back-office platform providers, alongside geographic expansion into greenfield transit markets lacking incumbent relationships.
Within the semiconductor archetype, NXP Semiconductors and Infineon Technologies anchor secure element supply for multi-application credentialing. Thales and Cubic Corporation exemplify the integrated platform tier, occupying positions that unify account-based ticketing across operator networks. Siemens Mobility represents the diversified industrial conglomerate model, leveraging rail infrastructure relationships to bundle signaling and fare collection systems.
| Leading Market Players |
|---|
| Giesecke+Devrient |
| NXP Semiconductors |
| Conduent |
| Siemens Mobility |
| Infineon Technologies |
| Thales |
| HID Global |
| Hitachi |
| Cubic Corporation |
| Others |
Supply & Pricing Matrix
India's National Common Mobility Card mandates and Germany's federal interoperability deadlines are compressing procurement timelines and forcing secure element suppliers to absorb certification rush fees while transit operators demand volume discounts for standardized tenders.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to payment-grade secure element orders below 90-day windows, while spot inventory from non-qualified fabs trades at distressed discounts. The dominant pricing model runs through project-based platform licensing with per-transaction SaaS tiers for account-based ticketing back-ends. Price differentiation hinges on EMV certification tier and geographic delivery cost to Indian metro authorities versus European rail operators. Cost compression in hardware tiers is intensifying because Taiwan foundry allocation constraints extend procurement cycles. Municipal transit agencies in Southern Europe exhibit highest price sensitivity; airport operators in Singapore and Dubai show least sensitivity due to throughput-critical deployment schedules.
Supply Chain Analysis
Dual-sourcing requirements from Deutsche Bahn and Transport for London mandate multi-supplier qualification across NXP Semiconductors and Infineon Technologies for secure element procurement. Geographic supply concentrates in Taiwan, South Korea, and Germany for semiconductor fabrication; back-office platform development clusters in France, the United Kingdom, and the United States. Raw material dependencies include silicon wafers, copper laminate substrates, and cryptographic key injection services. Single-source vulnerability in Taiwan foundry capacity exposes procurement timelines to geopolitical friction. Distribution runs through authorized systems integrators for mid-sized transit operators and direct OEM relationships for national rail authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
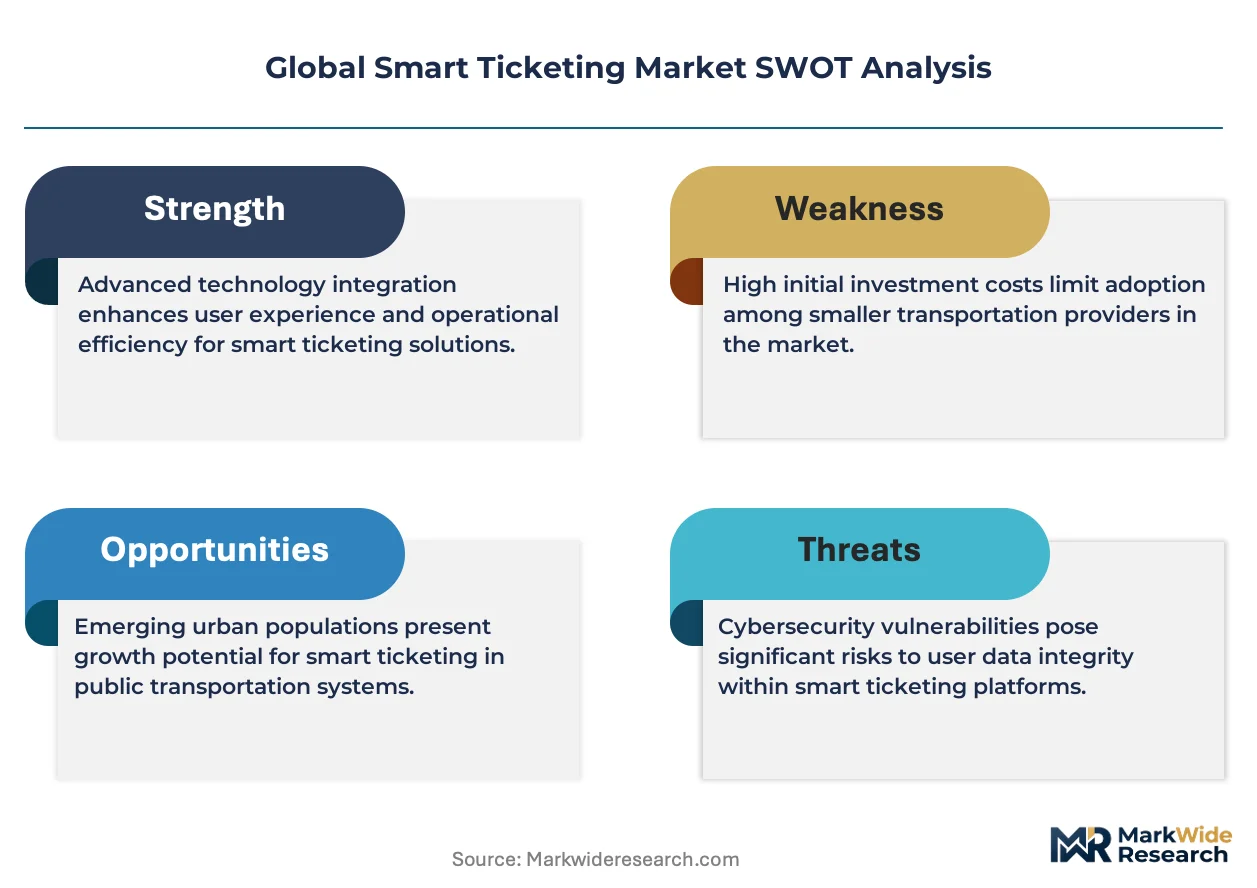
The smart ticketing market is becoming a vertical-integration race as platform providers pursue captive control over secure element supply to capture hardware margins and accelerate certification timelines.
For Market Incumbents: Deepen backward integration into cryptographic key injection services to defend margin position against fabless software entrants. Consolidate around account-based ticketing API layers before EU Digital Identity Wallet frameworks subsume proprietary apps. The threat of biometric tokenization commoditizing card manufacturing demands accelerated R&D in privacy-preserving facial recognition stacks. For New Entrants and Emerging Players: Mid-sized Brazilian municipal transit authorities lacking incumbent vendor relationships represent the most penetrable buyer archetype for integrated platform providers. Event-wallet convergence bundling transit, parking, and venue access offers white-space expansion with lower interoperability compliance burdens than government tenders. A direct-to-transit-authority sales model bypassing systems integrator markups accelerates initial footprint. For Investors and Strategic Acquirers: The window for entry favors semiconductor-back-office platform convergence plays with established EMV certification pipelines. Long-term viability over the next decade hinges on biometric tokenization IP and EU regulatory pre-qualification. The signal to watch is ANVISA interoperability specification finalization in Brazil triggering greenfield procurement waves.| Strategic Initiative | Industry Significance |
|---|---|
| Secure Element Supply Agreement | Captive silicon supply from Taiwan foundries insulates Thales and Cubic from allocation shocks. |
| Biometric Tokenization Platform Launch | Facial recognition pilots at Singapore's Changi Airport compress enrollment friction for account-based ticketing. |
| EU Digital Identity Wallet Integration | API-layer credential verification services position vendors for eIDAS 2.0 procurement frameworks. |
| Brazil Greenfield Market Entry | São Paulo metropolitan rail tenders lack incumbent relationships, creating platform consolidation opportunities. |
| Mobility-as-a-Service Bundling Partnership | Corporate commuter programs in Germany demand deep API integration with transit back-ends. |
Research Methodology
Trade publications, semiconductor foundry capacity reports, and transit authority procurement databases formed the secondary backbone of this analysis. Primary interviews with fare collection system engineers, transit procurement officers, and secure element product managers validated demand assumptions. Bottom-up credential volume estimates from Indian metro expansions and German rail refresh cycles were cross-referenced against top-down platform revenue disclosures. The analysis triangulates across vendor shipment data, government tender announcements, and regulatory filing timelines.
Bottom-up modeling of credential issuance volumes by technology tier and deployment context was reconciled with top-down platform revenue segmentation. The analytical framework projects adoption curves across the analysis window for NFC, Bluetooth Low Energy, and biometric tokenization formats. Segmentation dimensions include credential technology, application context, end-user procurement authority, and distribution channel. CAGRs were derived from installed base replacement cycles and greenfield expansion pipelines. Forecast inputs incorporate India's National Common Mobility Card rollout schedule and Germany's federal interoperability deadline compliance curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act biometric deployment restrictions and Taiwan foundry allocation volatility. Forecasts reflect assumptions around transit agency budget continuity and secure element supply normalization. A model refresh is warranted upon material change in ANVISA interoperability specification timelines or EU Digital Identity Wallet framework implementation dates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart City Technology
Smart City Kiosk Market
Smart City Technology
UAE Smart Furniture Market
Smart City Technology
Global Smart Hubs Market
Smart City Technology
Smart City Platform Market
Smart City Technology
Global Smart City ICT Infrastructure Market
Smart City Technology
Global Smart/Connected Street Lights Market
Smart City Technology
US Smart Cities Market
Smart City Technology
Smart Parcel Delivery Locker Market
Smart City Technology
Smart Shade Device Market
Smart City Technology
E-Governance Market
Smart City Technology
Outdoor LED Smart Lighting Solution Market
Smart City Technology
Smart Signaling Market
Smart City Technology
Singapore ICT Market
Smart City Technology
Smart Parcel Locker Market
Smart City Technology
Smart Mailbox Market
Smart City Technology
Smart Street Lights Market