
 Global Smart Pole Market | 2026-2036
Global Smart Pole Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Pole Market Foresight
Market Context
The gap between premium intelligent poles with integrated edge-computing cabinets and basic LED retrofit poles is realigning procurement strategies across municipal budgets. Signify Holding leverages its lighting heritage to dominate European smart streetlight tenders with modular upgrade paths. Huawei Technologies anchors Asian deployments through bundled 5G small-cell and surveillance packages. Delta Electronics competes on power electronics integration, sustaining margin pools in solar-hybrid configurations.
Technical Definition and Structural Segments
A smart pole is a multi-service urban infrastructure node that typically incorporates a steel or aluminum mast, integrated power distribution, environmental housings rated to IP65 or higher, and mounting interfaces for communications equipment, sensors, and displays. Its primary purpose is to consolidate discrete city services—illumination, connectivity, monitoring, and energy harvesting—into a single footprint, reducing street clutter and lifecycle civil works costs. Communication poles and hybrid poles capture the fastest expansion as 5G densification and multi-tenant utility sharing reshape deployment economics, while lighting poles remain the volume base with compressed margins. IoT sensors and environmental monitoring modules concentrate value growth because cities pay premiums for real-time air quality, noise, and flood data streams.
Regulatory Frame and Outlook
The FCC in the United States streamlines small-cell siting rules that directly expand addressable pole volumes, while the EU Green Deal and F-Gas Regulation push LED and refrigerant-free thermal management standards across member states. India's BIS certification and CDSCO-equivalent telecom equipment approvals create compliance gateways that favor pre-certified integrated suppliers. Stakeholders must monitor how spectrum auction timelines and national broadband targets rewrite pole density requirements before committing manufacturing capacity.
Market Dynamics
5G densification mandates from regulators are compressing deployment timelines and forcing pole specifications toward multi-tenant, high-load designs that accommodate small-cell arrays, edge cabinets, and sensor payloads simultaneously.
Growth Catalysts
- FCC Small-Cell Siting Reform:Streamlined federal rules in the United States eliminate municipal permitting delays, accelerating pole installation velocity in dense urban corridors.
- India National Smart Cities Mission:Central government funding for 100 urban clusters drives integrated procurement of lighting, surveillance, and connectivity infrastructure as unified packages.
- Edge Computing Hardware Miniaturization:Reduced thermal footprints and power draw enable cabinet integration directly within pole bases, expanding addressable retrofit sites.
Market Restraints
- Steel and Aluminum Price Volatility:Raw material cost swings compress fabrication margins and destabilize municipal budget forecasting for multi-year rollout programs.
- China Supply Concentration:Dependence on Asian manufacturing clusters for LED modules, power electronics, and structural steel creates geopolitical exposure and tariff uncertainty.
- Legacy Grid Interconnection Standards:Inconsistent electrical code enforcement across jurisdictions forces costly customization of power distribution subsystems.
Strategic Opportunities
- Brazil Urban Digitization Gap:Underpenetrated smart infrastructure in São Paulo and Rio de Janeiro corridors offers first-mover positioning for integrated pole-plus-service models.
- EU Green Deal Thermal Mandates:Refrigerant-free cooling requirements for outdoor electronics create demand for advanced passive thermal management pole designs.
- Vehicle-to-Everything (V2X) Convergence:Integration of roadside unit mounts with 5G small-cell arrays positions poles as critical nodes in autonomous traffic management networks.
Industry Challenges
- Multi-Discipline Installation Labor Scarcity:Shortage of technicians certified simultaneously in electrical, telecommunications, and civil works disciplines delays commissioning timelines.
- IP65+ Enclosure Certification Backlogs:Testing queue congestion at accredited laboratories extends product validation cycles and locks working capital in pre-certified inventory.
- Legacy Streetlight Asset Database Fragmentation:Incomplete municipal GIS records of existing pole locations, load ratings, and grid connections impede precise retrofit site selection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Pole Market |
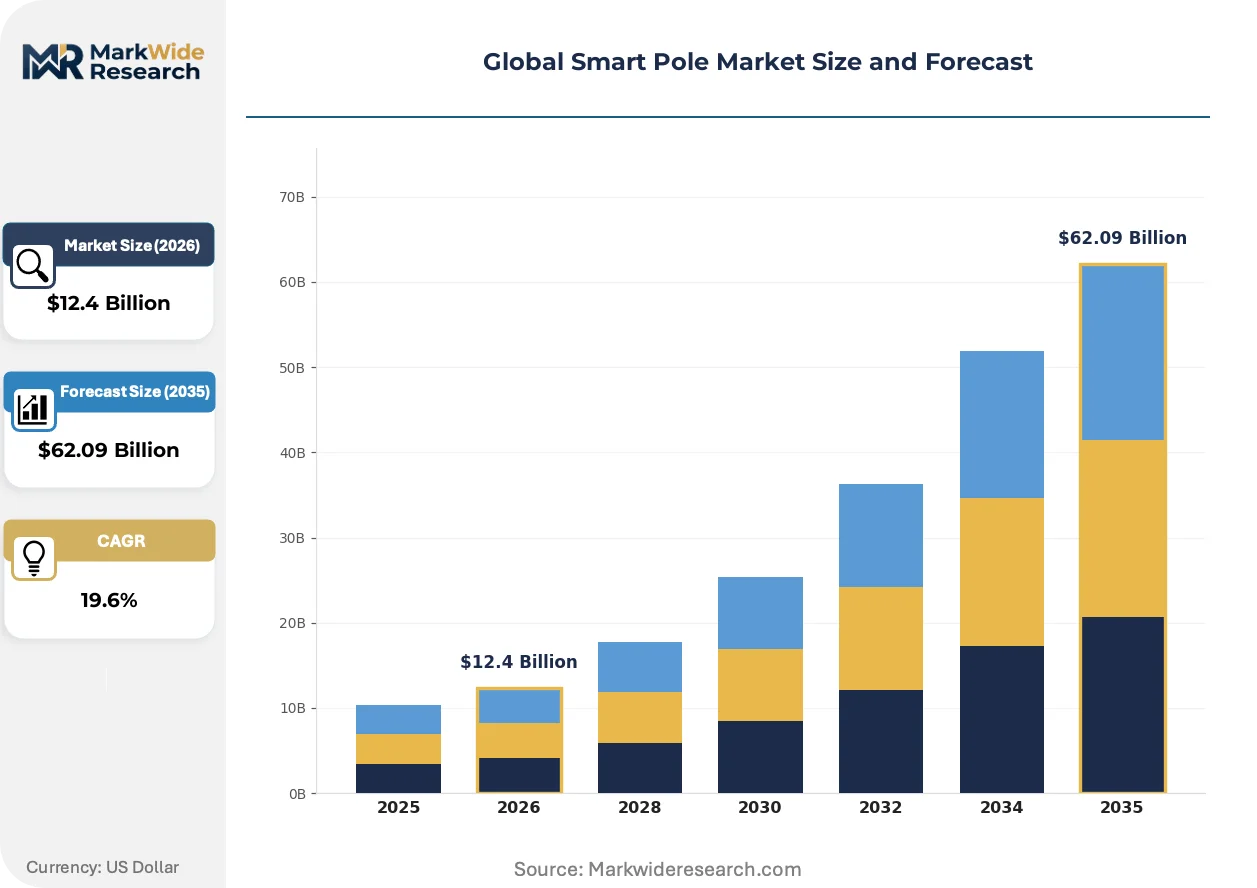
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $62.09 Billion |
| CAGR (2026 – 2036) | 19.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lighting Poles, Surveillance Poles, Communication Poles, Utility Poles, Hybrid Poles Technology: 5G Connectivity, IoT Sensors, LED Displays, Environmental Monitoring, Solar Power Integration Application: Street Lighting, Traffic Management, Public Safety, Urban Surveillance, Smart Parking End User: Municipal Corporations, Smart Cities, Infrastructure Developers, Transportation Agencies, Commercial Complexes |
| Companies Covered | Signify Holding, Delta Electronics, Huawei Technologies, Schréder, Omniflow, Telensa, Acuity Brands, Valmont Industries, Shanghai Sansi Electronic Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Pole Market Shifts & Advancements
Active materials substitution and regulatory thermal mandates are reshaping pole engineering priorities, while procurement centralization is altering how vendors access municipal decision-makers.
Galvanized steel construction is overtaking aluminum in high-wind coastal zones due to superior structural rigidity at equivalent cost points. Municipal engineers in Florida and Queensland specify steel masts for hurricane-rated installations. This material shift is compressing aluminum suppliers into specialty lightweight applications where transport cost dominates.
EU F-Gas Regulation phase-down schedules are forcing refrigerant-dependent active cooling out of pole-mounted electronics housings. Manufacturers now engineer vapor-chamber and heat-pipe thermal solutions to maintain processor performance in sealed IP65 enclosures. Asian export-oriented suppliers face redesign urgency to maintain European market access.
Municipal procurement consolidation into regional cooperative purchasing agreements is disintermediating traditional distributor networks. State-level aggregators in Texas and Baden-Württemberb now negotiate master service agreements that lock in multi-year supply commitments. Vendor sales organizations are restructuring to direct municipal engagement, bypassing electrical wholesaler channels entirely.
Global Smart Pole Market Segmentation
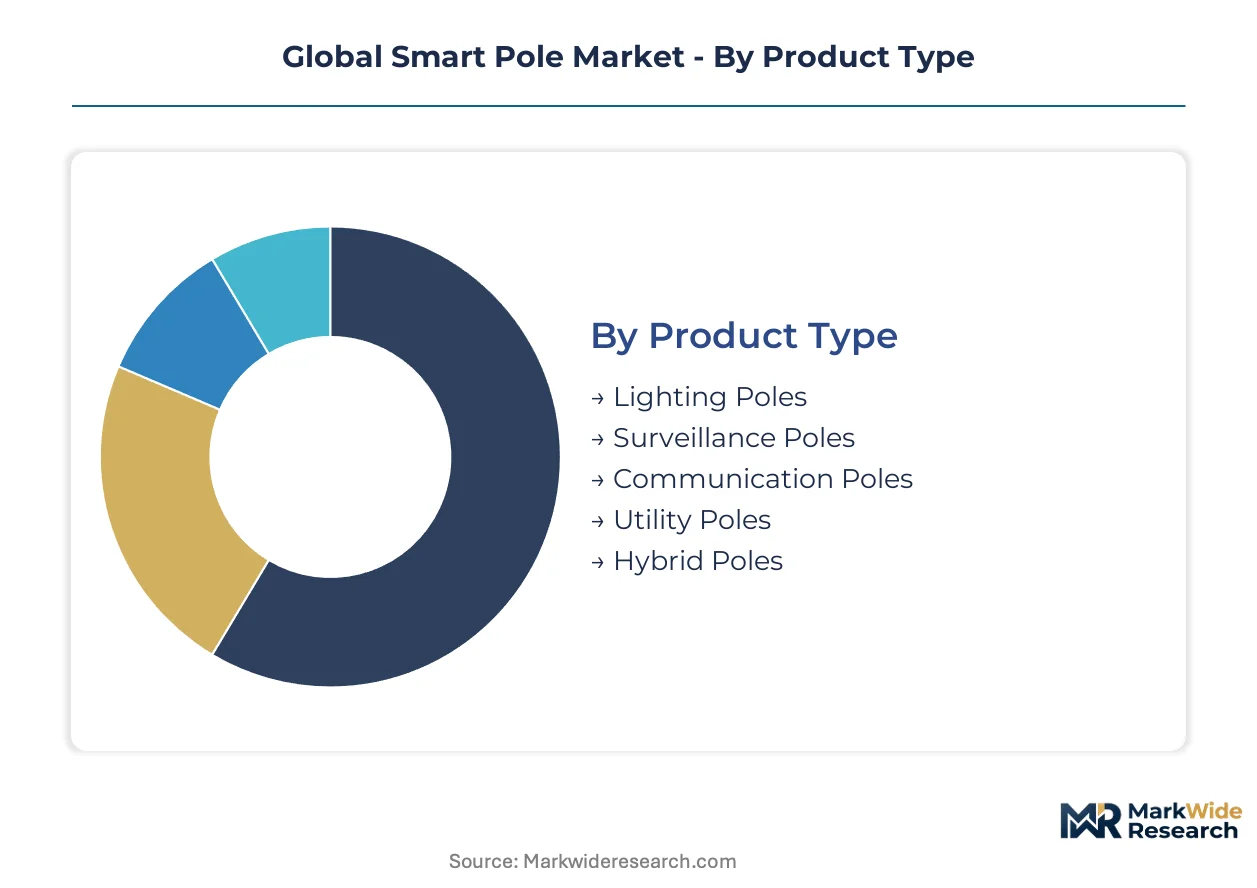
Smart pole procurement decisions pivot on load-bearing specifications, multi-tenant revenue models, and retrofit compatibility with legacy street infrastructure. Municipal buyers evaluate segments through lifecycle cost lenses rather than upfront capital expenditure alone. Understanding how technical specifications align with deployment economics clarifies why certain configurations dominate specific urban corridors.
Product Type:
Structural load capacity and tenant density determine municipal procurement priorities across pole configurations.
- Lighting Poles:Steel or aluminum masts with integrated LED drivers and photocell controls form the volume foundation of municipal retrofits. India's National Smart Cities Mission and China's Yangtze River Delta urban clusters drive concentrated demand for basic-to-smart upgrade paths where existing grid connections reduce civil works costs.
- Communication Poles:Reinforced structures engineered for 5G small-cell arrays, edge cabinets, and multiple carrier attachments capture premium positioning. FCC small-cell siting reforms in the United States and similar spectrum allocation policies in Germany accelerate deployment velocity in dense urban corridors where zoning compliance previously delayed installation.
- Surveillance Poles:Camera mounting interfaces with integrated power and fiber backhaul serve public safety applications.
- Utility Poles:Multi-service configurations consolidating power distribution, telecommunications, and sensor housings reduce street clutter.
- Hybrid Poles:Configurations combining solar-hybrid power electronics with communications and lighting payloads address off-grid or resilience-critical sites.
Lighting poles lead on scale; communication poles lead on momentum.
Technology:
Integration complexity and thermal management requirements differentiate technology tiers for pole-mounted systems.
- 5G Connectivity:Small-cell radio units and millimeter-wave antenna mounts demand reinforced structural engineering and power distribution upgrades. EU spectrum harmonization directives and India's TRAI equipment certification requirements shape vendor qualification pathways for cross-border deployment.
- IoT Sensors:Air quality, noise, flood, and particulate monitoring modules concentrate value growth as cities pay recurring data stream premiums. Environmental monitoring contracts in Germany's industrial corridors and India's pollution-critical urban centers drive specification standardization for sensor interoperability.
- LED Displays:Digital signage housings with IP65-rated enclosures and thermal management for high-brightness operation.
- Environmental Monitoring:Discrete sensor packages for meteorological and pollution data collection.
- Solar Power Integration:Photovoltaic panels, battery storage, and charge controllers for grid-independent operation.
5G connectivity commands the highest integration investment; IoT sensors deliver the steepest expansion trajectory.
Application:
Revenue model clarity—capital subsidy versus operational service fees—shapes application prioritization for municipal buyers.
- Street Lighting:Energy efficiency retrofits with smart controls and remote monitoring form the baseline deployment case. Municipal corporations across India, China, and Germany prioritize LED conversions with upgradeable connectivity backbones to preserve future optionality.
- Public Safety:Integrated camera, emergency call point, and gunshot detection configurations justify premium pricing through crime reduction metrics. Urban surveillance deployments in São Paulo and Rio de Janeiro corridors demonstrate first-mover positioning for integrated pole-plus-service models in underpenetrated markets.
- Traffic Management:Signal control, V2X roadside unit mounting, and congestion sensing for intelligent transportation systems.
- Urban Surveillance:Dedicated camera networks with centralized video management integration.
- Smart Parking:Occupancy detection, payment integration, and guidance display configurations.
Street lighting anchors deployment volume; public safety generates the fastest margin expansion.
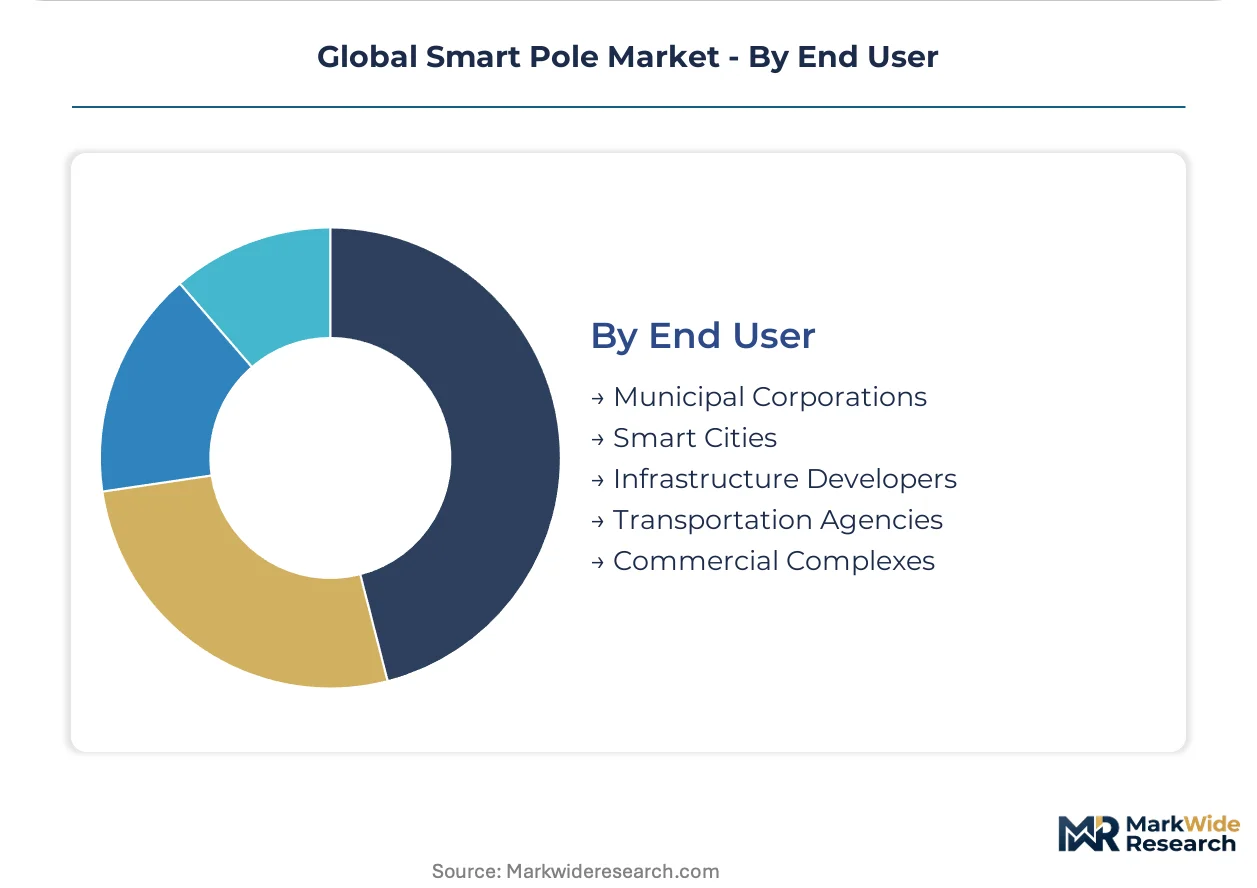
End User:
Budget authority and procurement centralization patterns determine vendor access and contract structure preferences.
- Municipal Corporations:City engineering departments with dedicated street lighting budgets and multi-year capital improvement programs represent the traditional procurement channel. State-level cooperative purchasing agreements in Texas and Baden-Württemberg consolidate negotiation leverage and lock in multi-year supply commitments.
- Smart Cities:Integrated urban management authorities with cross-departmental coordination mandates favor unified infrastructure packages. India's National Smart Cities Mission and China's Yangtze River Delta clusters exemplify procurement consolidation that bundles lighting, surveillance, and connectivity as single tenders.
- Infrastructure Developers:Private concession holders and public-private partnership operators with lifecycle performance obligations.
- Transportation Agencies:State and regional authorities with dedicated intelligent transportation system budgets.
- Commercial Complexes:Private campus and mixed-use development operators with aesthetic and branding requirements.
Municipal corporations dominate transaction frequency; smart cities command the largest average contract value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban infrastructure engineering talent concentrates in German industrial corridors, Chinese manufacturing hubs, and Indian municipal planning departments, anchoring deployment velocity across three continents.
United States
FCC small-cell siting reforms eliminate municipal permitting bottlenecks, accelerating pole installation velocity in dense urban corridors. The IRA and infrastructure spending bills channel federal funding toward intelligent transportation and grid modernization. Texas state-level cooperative purchasing agreements now negotiate master service agreements that lock in multi-year supply commitments for municipal buyers.
Germany
EU F-Gas Regulation phase-down schedules force refrigerant-dependent active cooling out of pole-mounted electronics housings. The EU Green Deal thermal mandates create demand for advanced passive thermal management pole designs. Industrial corridors in Baden-Württemberg exemplify procurement consolidation that bundles lighting, surveillance, and connectivity as single tenders.
China
MIIT spectrum allocation policies and dual carbon goals reshape pole specifications toward multi-tenant, high-load designs. GB standards certification requirements favor pre-certified integrated suppliers with domestic manufacturing footprints. Yangtze River Delta urban clusters drive concentrated demand for basic-to-smart upgrade paths where existing grid connections reduce civil works costs.
India
BIS certification and TRAI equipment approvals create compliance gateways that favor pre-certified integrated suppliers. The National Smart Cities Mission central government funding for 100 urban clusters drives integrated procurement of lighting, surveillance, and connectivity infrastructure. Municipal corporations in pollution-critical urban centers pay recurring data stream premiums for real-time air quality monitoring modules.
Brazil
Underpenetrated smart infrastructure in São Paulo and Rio de Janeiro corridors offers first-mover positioning for integrated pole-plus-service models. ANVISA-equivalent telecom equipment regulations and municipal procurement fragmentation create entry barriers for foreign suppliers. Urban surveillance deployments demonstrate how public safety applications justify premium pricing through crime reduction metrics.
Global Smart Pole Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the smart pole value chain, creating a tiered competitive structure where integrated manufacturing groups face pressure from modular system architects. The market fragments across lighting heritage players, telecommunications equipment giants, and power electronics specialists, each defending distinct margin pools. Three archetypes dominate: legacy lighting vendors with retrofit upgrade paths, telecom infrastructure providers with bundled connectivity packages, and industrial power electronics firms with solar-hybrid configurations. Competitive moves concentrate on strategic partnerships for multi-tenant utility sharing and geographic expansion through regional cooperative purchasing agreements.
Among European lighting heritage players, Signify Holding and Schréder occupy positions exemplifying the modular upgrade path archetype, while Delta Electronics anchors the power electronics integration tier with its solar-hybrid focus. Huawei Technologies represents the telecommunications infrastructure bundling model prevalent in Asian deployments.
| Leading Market Players |
|---|
| Signify Holding |
| Delta Electronics |
| Huawei Technologies |
| Schréder |
| Omniflow |
| Telensa |
| Acuity Brands |
| Valmont Industries |
| Shanghai Sansi Electronic Engineering |
| Others |
Supply & Pricing Matrix
Municipal cooperative purchasing agreements in Texas and Baden-Württemberg anchor procurement volume and compress vendor margins through multi-year master service agreements that eliminate distributor markups.
Pricing Analysis
Bundled infrastructure-as-a-service contracts separate from unbundled equipment-only sales. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling. Cost compression in basic LED retrofit poles is intensifying because aluminum and steel price volatility destabilizes fabrication margins. Municipal corporations with rigid capital improvement budgets exhibit highest price sensitivity; smart city authorities with cross-departmental funding show lowest.
Supply Chain Analysis
Regional distribution centers in Guangdong, Rotterdam, and Dallas-Fort Worth enable hub-and-spoke fulfillment to reduce last-mile logistics costs for pole structures. Manufacturing concentration in China, India, and Germany draws from galvanized steel, LED modules, and power electronics inputs. Single-source vulnerability for millimeter-wave antenna arrays creates geopolitical exposure. Distribution runs through state-level cooperative purchasing agreements that disintermediate electrical wholesaler channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU F-Gas thermal mandates elevate passive cooling engineering costs in Europe while China's MIIT spectrum policies accelerate deployment velocity at lower unit economics.
For Market Incumbents: Acquire certified installation labor pools to address multi-discipline technician scarcity delaying commissioning timelines. Backward integration into solar-hybrid power electronics secures margin pools against Delta Electronics' positioning. Prioritize BIS and TRAI pre-certification investments to lock out late entrants from India's National Smart Cities Mission tenders.
For New Entrants and Emerging Players: Mid-sized Brazilian municipalities with fragmented procurement represent the most penetrable buyer archetype for integrated pole-plus-service models. Underpenetrated urban surveillance deployments in São Paulo and Rio de Janeiro corridors offer white-space positioning. Lead with public safety outcome-based pricing that justifies premiums through crime reduction metrics rather than capital expenditure competition.
For Investors and Strategic Acquirers: Telecommunications infrastructure providers are the most active acquirer in this space, seeking pole-mounted real estate for 5G densification. Long-term viability hinges on multi-tenant revenue models spanning connectivity, surveillance, and environmental data streams. Target acquisition archetype: regional pole fabricators with pre-certified IP65+ enclosure portfolios and municipal relationships. The signal to monitor is FCC spectrum auction timelines rewriting pole density requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Tenant Utility Sharing Partnerships | Enables carriers to split 5G small-cell siting costs across municipal and commercial users. |
| Passive Thermal Management Redesign | Positions suppliers for EU F-Gas compliance without refrigerant-dependent cooling systems. |
| Regional Cooperative Purchasing Agreement Entry | Locks multi-year supply commitments through Texas and Baden-Württemberg state aggregators. |
| Edge Computing Cabinet Miniaturization | Expands retrofit addressability to legacy streetlight sites with constrained base footprints. |
| V2X Roadside Unit Mount Integration | Captures autonomous traffic management infrastructure spend as transportation agencies upgrade corridors. |
Research Methodology
Bottom-up municipal procurement modeling reconciled against top-down manufacturing capacity tracking forms the analytical core. Primary interviews with municipal engineering directors, smart city program managers, telecom infrastructure procurement leads, and pole fabrication plant managers combined with secondary validation from FCC small-cell deployment databases, EU Green Deal implementation reports, and BIS certification registries. Triangulation across supply-side capacity announcements and demand-side tender awards calibrated volume estimates.
Historical tender award analysis across lighting retrofit waves and 5G densification cycles established baseline penetration patterns. Segmentation dimensions modeled include pole structural configuration, integration technology tier, application revenue model, and end-user procurement centralization level. CAGRs derived from slope analysis of announced municipal capital improvement programs and spectrum allocation timelines. Forecast inputs incorporated steel and aluminum futures curves, plus FCC and MIIT equipment certification queue data.
Inputs from municipal procurement databases and telecom carrier capex disclosures were available through the study window; gaps in legacy streetlight asset GIS records introduce uncertainty bands around retrofit site identification. Forecasts reflect documented assumptions regarding spectrum auction schedules and raw material price trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart City Technology
Outdoor LED Smart Lighting Solution Market
Smart City Technology
Smart Signaling Market
Smart City Technology
E-Governance Market
Smart City Technology
Global Smart City ICT Infrastructure Market
Smart City Technology
Smart City Kiosk Market
Smart City Technology
Smart Space Market
Smart City Technology
Smart Package Lockers Market
Smart City Technology
Smart City Platform Market
Smart City Technology
Smart Parking Meters Market
Smart City Technology
Smart City Kiosk Deployment Market
Smart City Technology
City Data Platform Market
Smart City Technology
Smart Shade Device Market
Smart City Technology
Smart Ticketing Solutions Market
Smart City Technology
Smart Mailbox Market
Smart City Technology
Saudi Arabia Smart Cities Market
Smart City Technology
Singapore ICT Market