
 Ireland E-Commerce Market | 2026-2036
Ireland E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Ireland E-Commerce Market Foresight
Irish fulfillment center operators is broadening warehouse capacity across the Greater Dublin Area to match cross-border order velocity. Amazon.com Inc leverages its pan-European distribution backbone to offer next-day delivery to Republic of Ireland postcodes. Tesco Ireland anchors its hybrid model through click-and-collect integration with its nationwide store estate. Shopify-Irish Merchants competes by enabling direct-to-consumer storefronts that bypass centralized marketplace fees.
E-commerce in Ireland denotes the digital exchange of goods and services through internet-connected platforms, relying on encrypted payment gateways, real-time inventory management systems, and last-mile logistics orchestration to complete transactions. The sector serves retail distribution, B2B procurement, and consumer convenience by collapsing geographical distance between buyers and sellers. Electronics and clothing product categories carry the deepest margin pools due to high purchase frequency and return-driven repeat visits. Individual consumers dominate transaction volume, though small businesses represent the fastest-growing customer type as SaaS storefront tools lower entry barriers. Subscription service delivery models are displacing one-off purchases in beauty products, creating predictable revenue streams that justify dedicated inventory holding.
The EU Digital Services Act and GDPR framework shape platform liability and data handling obligations for all operators serving Irish consumers. The Central Bank of Ireland supervises buy-now-pay-later payment providers under strengthened consumer credit rules. Stakeholders must monitor how forthcoming EU packaging waste regulations alter fulfillment economics for cross-border sellers shipping into Ireland.
Market Dynamics
The EU Digital Services Act is forcing platform operators serving Irish consumers to restructure content moderation systems and audit algorithms, while GDPR enforcement tightens data residency requirements for cross-border fulfillment networks.
Growth Catalysts
- Cross-border fulfillment infrastructure:Pan-European distribution networks now route through Dublin Port and Rosslare Europort, compressing delivery windows for Republic of Ireland postcodes. This infrastructure expansion supports SME participation in digital trade.
- SaaS storefront democratization:Low-code commerce tools reduce technical barriers for Irish micro-retailers entering direct-to-consumer channels. Independent merchants bypass centralized marketplace fee structures through owned digital storefronts.
- GDPR-compliant data handling:Strengthened consumer data protections under EU frameworks build transaction trust, reducing cart abandonment rates for Irish e-commerce operators investing in consent management infrastructure.
Market Restraints
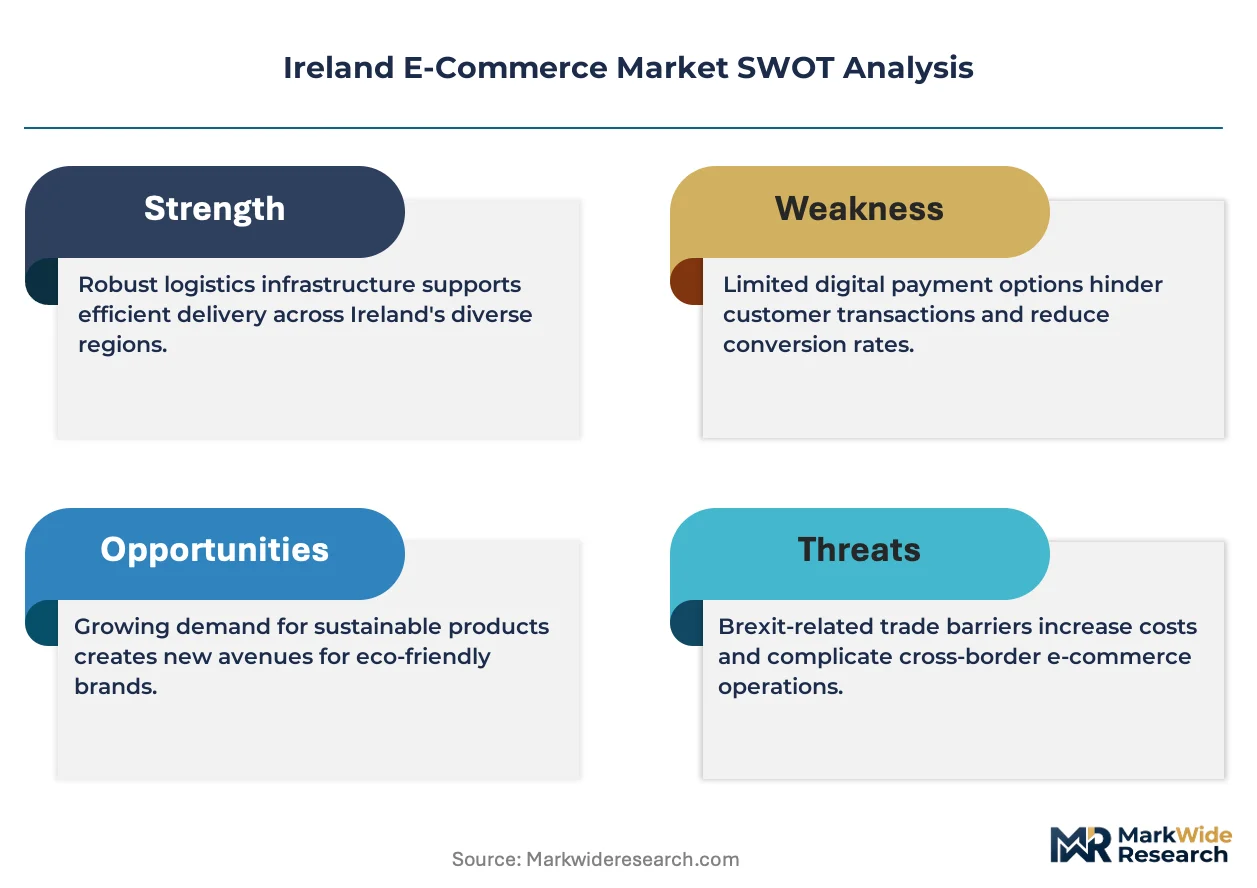
- Last-mile cost concentration:Sparse population density outside Greater Dublin Area inflates per-unit delivery costs for rural County Kerry and County Donegal postcodes. Fulfillment economics degrade beyond 50km from urban centers.
- Single-market dependency:Republic of Ireland e-commerce volumes route through UK-based distribution nodes for non-EU origin goods. Brexit customs friction adds processing delays and duty complexity.
- Return logistics burden:High-frequency return categories including apparel and footwear absorb margin through reverse logistics costs. Free return policies, now consumer-expected, strain working capital for mid-size operators.
Strategic Opportunities
- Regional fulfillment hub status:Ireland's EU membership and English-language workforce position the island as a transatlantic e-commerce gateway for US brands entering European markets. Dublin and Cork warehouse zones attract foreign direct investment.
- Subscription commerce expansion:Beauty and personal care categories show white space for recurring revenue models. Predictable demand patterns justify dedicated inventory holding and automated replenishment systems.
- Green logistics differentiation:EU packaging waste regulations create first-mover advantage for operators investing in circular packaging and carbon-neutral last-mile fleets. Consumer willingness-to-pay premiums for sustainable delivery options is testing positively.
Industry Challenges
- Technical talent scarcity:Demand for full-stack developers and logistics data scientists exceeds supply in Irish labor markets. Compensation inflation for platform engineering roles squeezes operator margins.
- Legacy system integration friction:Established Irish retailers operate on-premise ERP architectures that resist cloud-native commerce stack connectivity. API compatibility gaps delay real-time inventory synchronization.
- Regulatory compliance velocity:Evolving EU platform accountability rules require continuous legal and operational adaptation. Smaller operators lack dedicated compliance functions to track notification deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ireland E-Commerce Market |
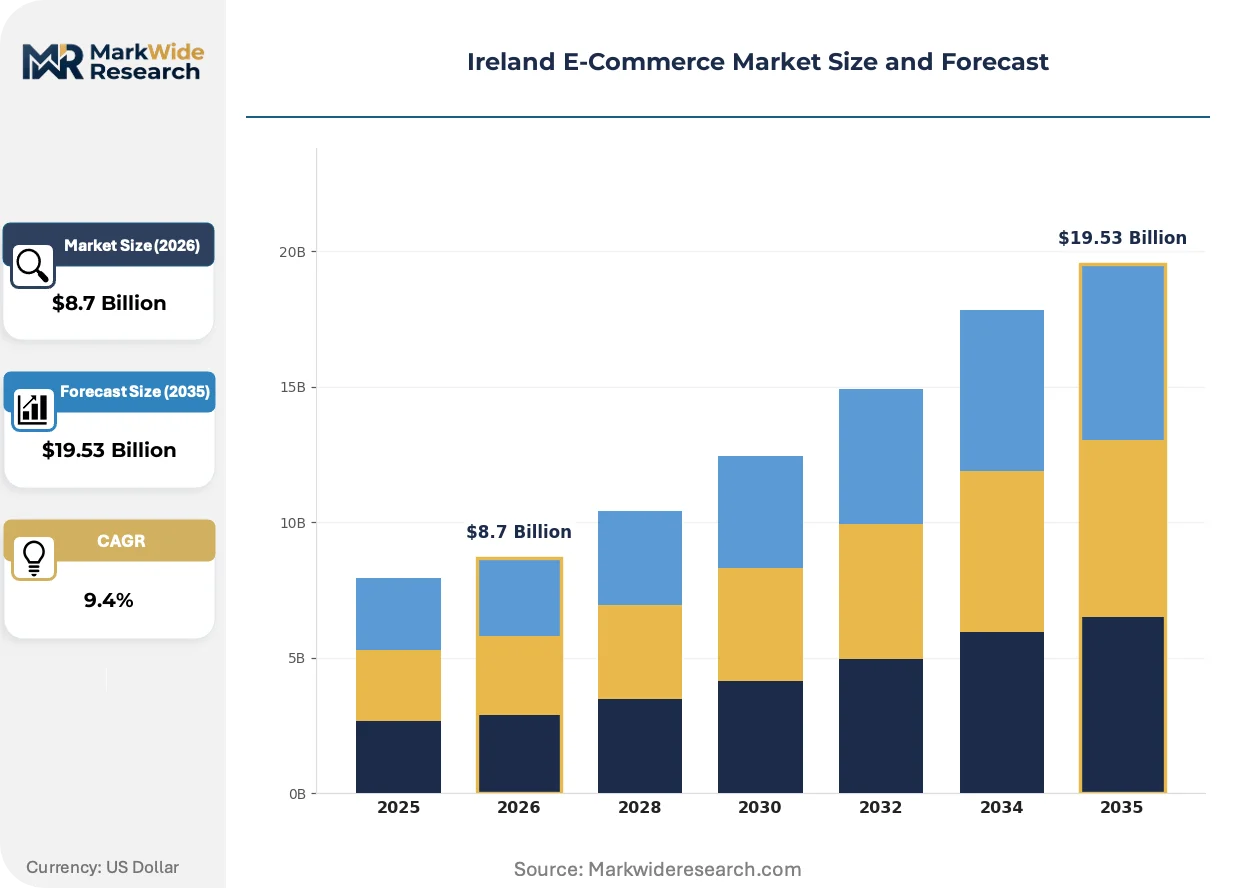
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics, Clothing, Home Goods, Beauty Products Customer Type: Individual Consumers, Small Businesses, Corporates, Non-Profits Delivery Model: Direct Shipping, Click-and-Collect, Subscription Service, In-Store Pickup Payment Method: Credit Cards, Digital Wallets, Bank Transfers, Buy Now Pay Later |
| Companies Covered | Etsy Ireland Unlimited, Amazon.com Inc, eBay Inc, Tesco Ireland, Argos Distributors (Ireland) Limited, Currys Ireland Limited, Littlewoods Ireland, Next.ie, Shopify-Irish Merchants, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ireland E-Commerce Market Shifts & Advancements
Headless commerce architectures and AI-powered personalization engines are restructuring how Irish merchants build customer relationships, while regulatory pressure on platform transparency accelerates investment in explainable algorithms.
Distributed ledger technology for supply chain provenance is decentralizing trust verification in cross-border e-commerce transactions. Irish food and beverage exporters adopt blockchain-tracked batch records to satisfy EU integrity requirements. This verification shift reduces documentary friction for customs clearance while compressing dispute resolution timelines.
The EU Digital Services Act mandates algorithmic transparency for recommendation systems and targeted advertising deployed to Irish consumers. Platform operators must disclose ranking parameters and provide ad-archive access. Marketplace sellers in electronics and fashion verticals face new audit obligations for promotional content accuracy.
Click-and-collect integration with physical retail estates is displacing pure-play home delivery as the preferred fulfillment mode for Irish grocery and general merchandise shoppers. Tesco Ireland's nationwide store network anchors this hybrid model. Urban consumers in Dublin and Cork demonstrate strongest adoption, valuing schedule flexibility over door-step convenience.
Ireland E-Commerce Market Segmentation
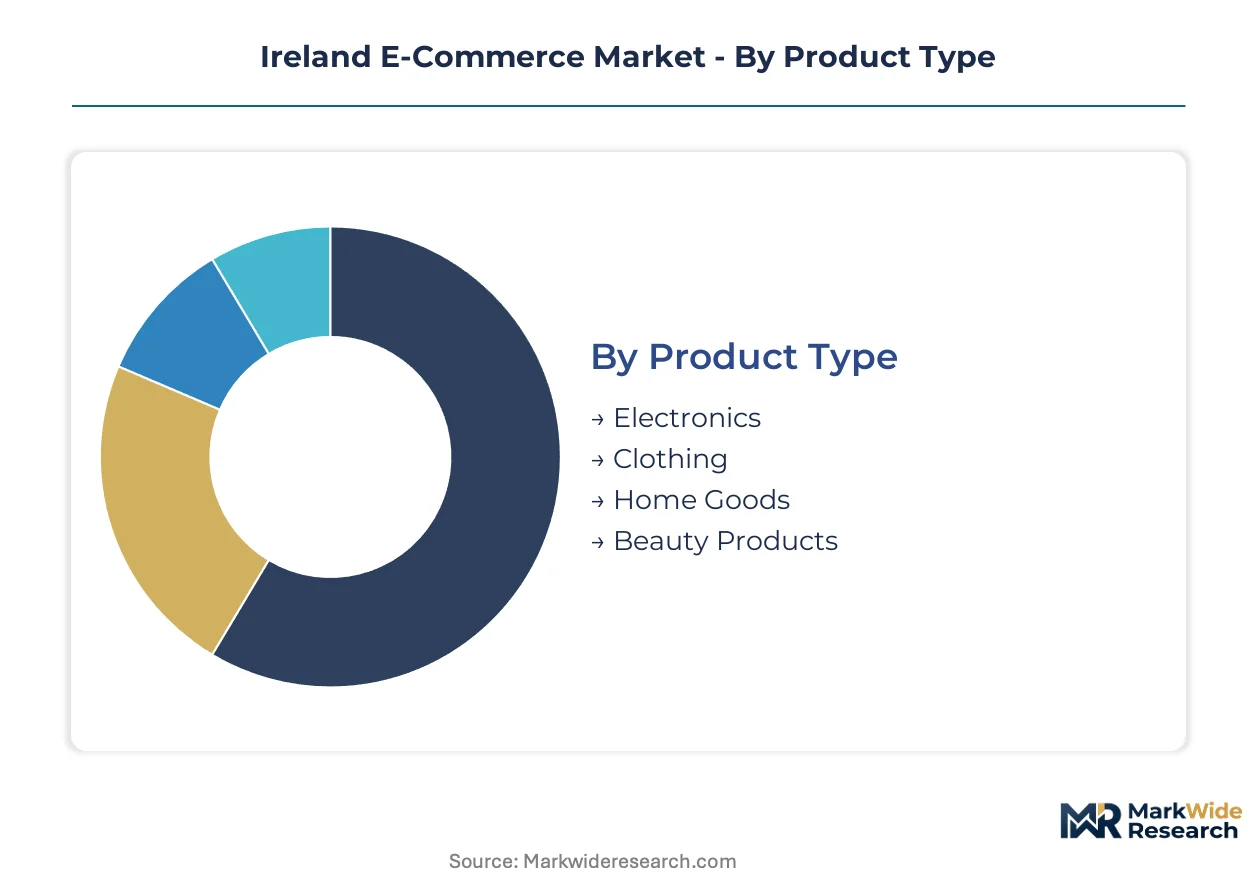
E-commerce segmentation in Ireland reveals how platform operators allocate capital across fulfillment modes and payment infrastructures. Distinct customer types and product categories drive divergent margin structures and inventory holding patterns across the Republic of Ireland.
Product Type:
Standalone digital storefronts dominate high-velocity categories, while embedded marketplace listings persist in lower-margin goods where discovery costs outweigh ownership benefits.
- Electronics:High-specification devices with serialized inventory tracking and manufacturer warranty obligations. Demand concentrates in Greater Dublin Area postcodes where same-day fulfillment networks operate, though customs friction on UK-routed non-EU goods creates stock-out risk during peak periods.
- Clothing:Size-variant SKUs with elevated return rates requiring reverse logistics infrastructure. Dublin and Cork urban corridors absorb the deepest inventory investment as click-and-collect integration with physical retail estates reduces last-mile cost exposure.
- Home Goods:Bulky freight categories where dimensional weight pricing shapes fulfillment economics. Cork distribution zones capture regional demand through palletized delivery networks serving County Kerry and County Limerick postcodes.
- Beauty Products:Subscription-ready consumables with recurring replenishment cycles. Subscription service delivery models displace one-off purchases, creating predictable revenue streams that justify dedicated inventory holding in temperature-controlled Dublin warehouses.
Electronics leads volumes today; beauty products are gaining share fastest through subscription commerce expansion.
Customer Type:
Volume concentration varies sharply by procurement sophistication, with enterprise buyers demanding API-integrated procurement stacks that smaller operators cannot support.
- Individual Consumers:Transaction-scale buyers with mobile-first purchasing behavior and high sensitivity to delivery window promises. Dublin's dense postcode clustering enables cost-efficient same-day service, while rural Donegal and Mayo postcodes suffer degraded fulfillment economics.
- Small Businesses:B2B procurement accounts with invoice-based payment terms and bulk SKU requirements. SaaS storefront democratization reduces technical barriers for Irish micro-retailers entering direct-to-consumer channels, accelerating digital procurement adoption across County Galway and County Waterford.
- Corporates:Enterprise procurement functions with negotiated rate cards and centralized purchasing mandates. Central Bank of Ireland supervision of payment providers under consumer credit rules shapes B2B financing options available to this segment.
- Non-Profits:Grant-funded purchasing with restricted payment methods and compliance documentation requirements. EU Digital Services Act platform accountability rules affect donation processing transparency for Irish charitable organizations.
Individual consumers anchor transaction volumes today; small businesses are expanding most quickly as SaaS tools lower entry barriers.
Delivery Model:
Cost tier differentiation separates premium speed guarantees from economy options, with hybrid models capturing margin through inventory positioning rather than pure velocity.
- Direct Shipping:Doorstep delivery through third-party logistics networks with variable service level agreements. Amazon.com Inc leverages its pan-European distribution backbone to offer next-day delivery to Republic of Ireland postcodes through this model.
- Click-and-Collect:Order-online-pickup-in-store fulfillment integrating digital storefronts with physical retail estates. Tesco Ireland anchors this hybrid model through nationwide store network integration, with strongest adoption in Dublin and Cork urban corridors.
- Subscription Service:Automated replenishment with predictive inventory allocation and fixed delivery scheduling. Beauty and personal care categories show white space for recurring revenue models with predictable demand patterns.
- In-Store Pickup:Immediate availability confirmation with reduced last-mile cost burden. This model concentrates in grocery and general merchandise verticals where existing store density supports fulfillment coverage.
Direct shipping leads volumes today; click-and-collect is climbing the fastest as hybrid retail models mature.
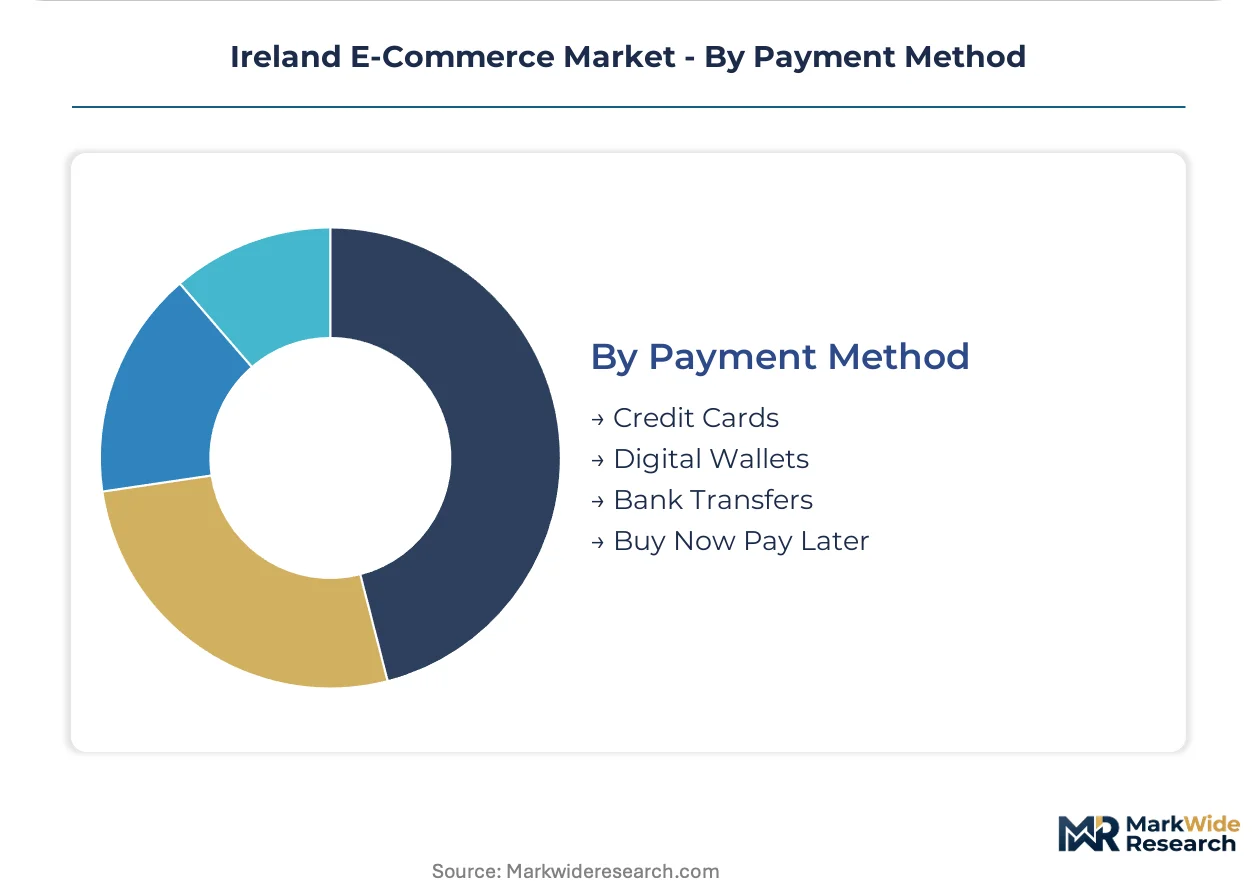
Payment Method:
Geography of issuer concentration shapes processing cost structures, with domestic Irish-issued instruments commanding preferential interchange rates.
- Credit Cards:Revolving credit instruments with chargeback protection and reward program integration. Central Bank of Ireland supervision ensures compliance with strengthened consumer credit rules for Irish-issued products.
- Digital Wallets:Tokenized payment credentials with biometric authentication and one-click checkout. GDPR-compliant data handling requirements under EU frameworks build transaction trust for Irish e-commerce operators investing in consent management infrastructure.
- Bank Transfers:Direct account debits with lower processing fees but extended settlement timelines. This method persists in B2B procurement where invoice reconciliation demands audit trails.
- Buy Now Pay Later:Point-of-sale installment credit with instant approval and no hard credit check. Central Bank of Ireland supervision of buy-now-pay-later payment providers under strengthened consumer credit rules shapes product availability.
Credit cards lead volumes today; digital wallets are expanding most quickly through mobile commerce adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between Irish and UK compliance costs is redirecting fulfillment infrastructure toward Dublin and Cork, as EU Digital Services Act obligations create a cost-of-compliance gap favoring Republic of Ireland-based operations over UK-domiciled competitors serving cross-border demand.
Greater Dublin Area
Cross-border order velocity drives warehouse expansion across South Dublin and Fingal County. The Central Bank of Ireland supervises payment providers under strengthened consumer credit rules. Dublin Port absorbs pan-European distribution flows, with Amazon.com Inc leveraging this gateway for next-day coverage of Leinster postcodes.
Cork Metropolitan Area
Regional demand for bulky home goods and palletized freight concentrates fulfillment investment in Little Island and Ringaskiddy zones. GDPR enforcement tightens data residency requirements for cross-border networks. Cork distribution zones capture Munster demand through temperature-controlled facilities serving Kerry and Limerick postcodes.
Galway and the West
SaaS storefront adoption accelerates among micro-retailers in County Galway and Mayo as technical barriers fall. EU packaging waste regulations alter fulfillment economics for cross-border sellers. Sparse population density beyond 50km from Galway City inflates per-unit delivery costs, degrading fulfillment economics in rural Connacht corridors.
Limerick-Shannon Corridor
B2B procurement accounts with invoice-based payment terms drive warehouse leasing in Raheen and Castletroy. The EU Digital Services Act reshapes platform accountability for operators serving Irish consumers. Shannon Free Zone logistics parks attract foreign direct investment targeting transatlantic e-commerce gateway positioning.
Northern Ireland Border Region
Brexit customs friction adds processing delays for non-EU origin goods routed through UK distribution nodes. Single-market dependency creates regulatory complexity for Donegal and Monaghan postcodes. Dundalk and Derry logistics clusters face divergent compliance obligations depending on final destination routing.
Ireland E-Commerce Market Competitive Landscape
US-based platform operators anchor the marketplace tier; Irish and UK omnichannel retailers hold the hybrid fulfillment tier. The vendor base fragments across pure-play digital natives, legacy retail estates with click-and-collect integration, and SaaS-enabled independent merchants. Three archetypes dominate: pan-European logistics networks, store-anchored hybrid operators, and direct-to-consumer storefront tools. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as operators secure warehouse zones and last-mile delivery coverage.
Among US-based platform operators, Amazon.com Inc and eBay Inc exemplify the pan-European logistics archetype, leveraging distribution backbone scale to compress delivery windows. Within the hybrid retail tier, Tesco Ireland and Argos Distributors (Ireland) Limited occupy positions anchored by nationwide store estate integration, representing the click-and-collect fulfillment model against pure-play competition.
| Leading Market Players |
|---|
| Etsy Ireland Unlimited |
| Amazon.com Inc |
| eBay Inc |
| Tesco Ireland |
| Argos Distributors (Ireland) Limited |
| Currys Ireland Limited |
| Littlewoods Ireland |
| Next.ie |
| Shopify-Irish Merchants |
| Others |
Supply & Pricing Matrix
Pan-European logistics integration anchors fulfillment economics for Irish e-commerce operators, compressing delivery windows while concentrating pricing power among operators with cross-border warehouse networks. Amazon.com Inc's distribution backbone and Tesco Ireland's store-anchored model illustrate how vertical control over last-mile infrastructure determines margin capture against marketplace-dependent merchants.
Pricing Analysis
Retailer markup layers separate pure-play digital storefronts from marketplace-dependent sellers, with direct-to-consumer channels capturing margin through bypassed platform fees. Three-tier pricing structure across premium, standard, and economy levels stratifies by delivery velocity and return policy generosity. Cost compression in rural last-mile tiers is intensifying because sparse population density inflates per-unit logistics costs beyond 50km from urban centers. Small businesses demonstrate highest price sensitivity to fulfillment fees, while individual consumers in Dublin and Cork show willingness to absorb premiums for same-day guarantees.
Supply Chain Analysis
Direct-to-retail channels handle hyperscale demand from Amazon.com Inc and Tesco Ireland, while SaaS-enabled independent merchants rely on third-party logistics networks with variable service agreements. Distribution runs through UK-based nodes for non-EU origin goods, creating Brexit-related customs friction that delays processing. Inventory positioning draws from Netherlands, Germany, and UK distribution hubs for EU-sourced electronics and apparel. Semiconductor components, lithium-ion batteries, and temperature-controlled packaging materials constitute critical input dependencies. Single-source vulnerability through UK routing for transatlantic goods exposes operators to tariff complexity and documentary delays at Rosslare Europort.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ireland's EU membership and English-language workforce create a geographic-arbitrage opportunity against UK-domiciled competitors, as GDPR compliance costs and Digital Services Act obligations diverge across the Irish Sea. The regulatory cost differential favors Republic of Ireland-based fulfillment infrastructure for US brands entering European markets.
For Market Incumbents: Anchor defensive positioning through backward integration into temperature-controlled warehouse capacity across Greater Dublin Area and Cork Metropolitan zones. Threats from Shopify-Irish Merchants' direct-to-consumer storefront tools demand channel control investments, while EU packaging waste regulations require certification in circular logistics infrastructure. Capacity addition in Shannon Free Zone logistics parks secures transatlantic gateway positioning against emerging competitors.
For New Entrants and Emerging Players: The EU Digital Services Act in Ireland opens a window for compliance-native platform architectures that incumbent UK operators struggle to retrofit. White-space targets include subscription commerce in beauty and personal care categories, plus B2B procurement tools for County Galway and County Waterford micro-retailers. Go-to-market leverage rests on GDPR-compliant data handling as a trust-building differentiator against legacy marketplace operators.
For Investors and Strategic Acquirers: Roll-up economics work for SaaS-enabled fulfillment specialists because technical talent scarcity in Irish labor markets prevents organic scaling by fragmented operators. Long-term viability hinges on consolidation of last-mile networks serving rural Connacht and Munster corridors. Acquisition targets include temperature-controlled facility operators with established Kerry and Limerick postcode coverage. Signal to watch: Central Bank of Ireland enforcement actions against buy-now-pay-later providers reshaping B2B financing availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Pan-European Distribution Network Expansion | Amazon.com Inc leverages Dublin Port gateway to compress delivery windows for Leinster postcodes. |
| Click-and-Collect Infrastructure Integration | Tesco Ireland anchors hybrid fulfillment through nationwide store estate connectivity with digital storefronts. |
| Subscription Commerce Platform Development | Beauty category operators capture recurring revenue through automated replenishment and predictive inventory allocation. |
| Green Logistics Certification Investment | EU packaging waste regulations create first-mover advantage for circular packaging and carbon-neutral fleet operators. |
| SaaS Storefront Democratization | Low-code commerce tools reduce technical barriers for County Galway and Mayo micro-retailers entering direct-to-consumer channels. |
Research Methodology
Coverage spans Republic of Ireland sub-regions including Greater Dublin Area, Cork Metropolitan Area, Galway and the West, and Limerick-Shannon Corridor, with primary inputs from each. The analysis combines structured interviews with e-commerce platform operators, fulfillment center managers, logistics data scientists, and Central Bank of Ireland regulatory affairs specialists with secondary validation. Secondary sources include EU Digital Services Act implementation guidance, GDPR enforcement notices, Central Bank of Ireland consumer credit supervision reports, and customs flow data through Dublin Port and Rosslare Europort. Bottom-up transaction volume estimates triangulate against top-down market sizing from pan-European distribution network disclosures.
Rate-of-change decomposition separates volume growth drivers from pricing evolution across the projection horizon. Segmentation dimensions modeled include product type, customer archetype, delivery model, and payment method, with cross-border fulfillment intensity as an industry-specific overlay. CAGRs derive from logistic curve fitting to historical penetration rates, adjusted for EU regulatory velocity and Brexit-related friction persistence. Forecast inputs incorporate SaaS storefront adoption curves, warehouse capacity expansion timelines, and mobile commerce payment mix shifts.
Revisions become necessary when Brexit customs friction intensifies, EU packaging waste regulations accelerate compliance deadlines, or Central Bank of Ireland supervision expands to additional payment provider categories. Forecasts reflect documented assumptions regarding cross-border infrastructure investment continuity and SME digital procurement adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Mexico E-Commerce Market
E-Commerce Solutions
Switzerland E-Commerce Market
E-Commerce Solutions
Online to Offline Commerce Market
E-Commerce Solutions
UAE Q-Commerce Industry Market
E-Commerce Solutions
US SMS Marketing Market
E-Commerce Solutions
Latin America E-Commerce Logistics Market
E-Commerce Solutions
M-Commerce Market
E-Commerce Solutions
South Africa E-Commerce Market
E-Commerce Solutions
Saudi Arabia E-Commerce Logistics Market
E-Commerce Solutions
United Kingdom Same Day Delivery Market
E-Commerce Solutions
China E-Commerce Market
E-Commerce Solutions
Social Commerce Market
E-Commerce Solutions
Conversational Commerce Market
E-Commerce Solutions
Global Digital Commerce Market
E-Commerce Solutions
Middle East and Africa E-Commerce Apparel Market
E-Commerce Solutions
Romania E-Commerce Market