
 Smart Parking Meters Market | 2026-2036
Smart Parking Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Parking Meters Market Analytics
Cloud-native payment integration is tilting the technology stack away from standalone coin-operated hardware toward API-connected platforms that feed real-time occupancy data into municipal back offices. IPS Group Inc. leverages in-house manufacturing in San Diego to control hardware margins and accelerate custom chassis production for city-specific curb designs. Flowbird Group anchors its competitive position through dense European service networks and long-term maintenance contracts with French and UK municipal operators. J.J. MacKay Canada Limited dominates North American university campus deployments where seasonal permit integration with student ID systems creates sticky institutional relationships.
Smart parking meters are electromechanical or solid-state curb devices that accept digital payment, enforce time limits via onboard sensors, and transmit transaction and occupancy data wirelessly to centralized enforcement platforms; most units operate on 4G/LTE or NB-IoT modems with IP65-rated enclosures for outdoor durability. Their primary commercial purpose is to automate revenue collection while generating granular data streams that support dynamic pricing and traffic-flow optimization for urban transportation departments. Multi-space meters lead installed base value in dense downtown corridors where sidewalk footprint constraints favor consolidated payment kiosks serving eight to twelve parking bays. Mobile payment technology is expanding fastest among end-user segments as cities bypass hardware capital outlays by retrofitting existing meters with QR-code and NFC overlays that push transactions to smartphone apps. Single space meters remain the margin pool for specialized applications including residential permit zones and loading bays where individualized enforcement tracking prevents revenue leakage.
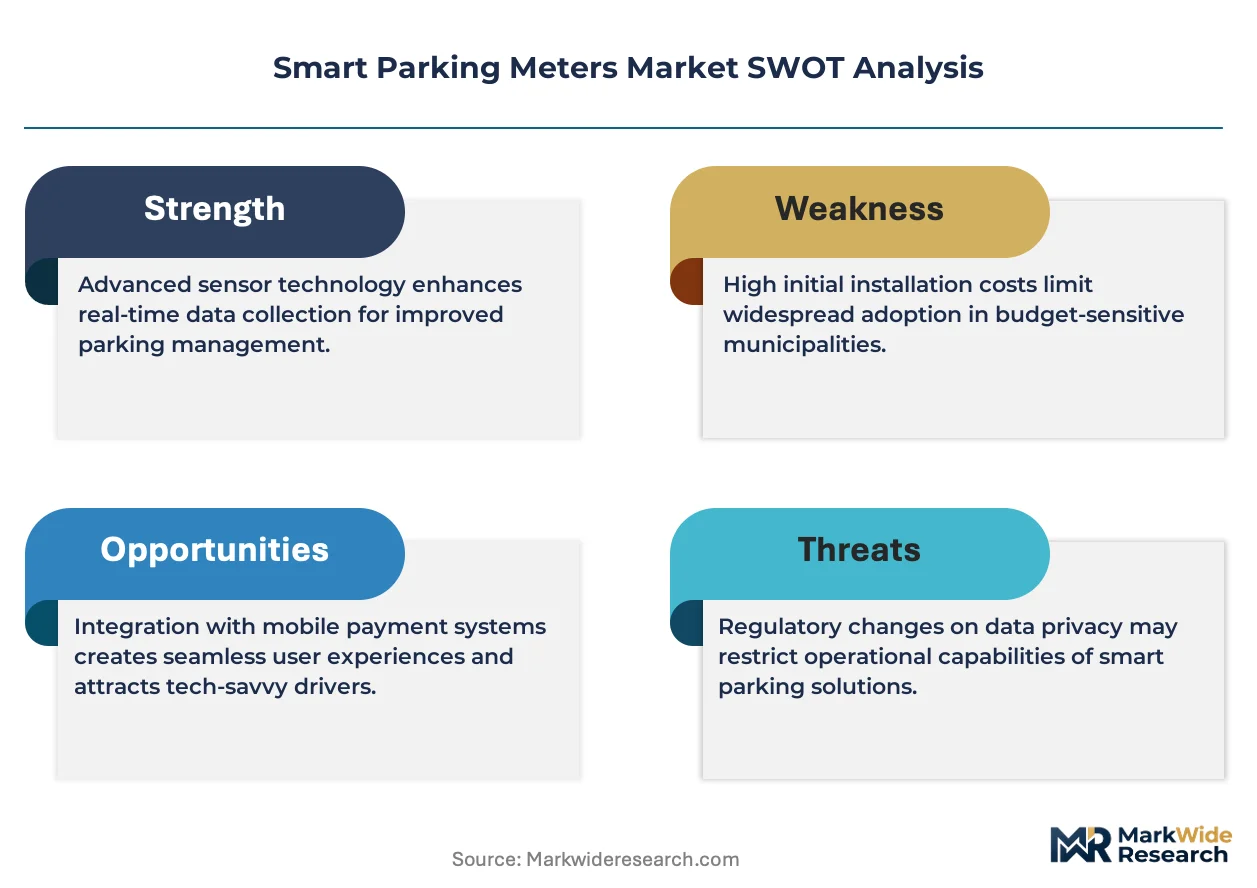
The Federal Communications Commission governs wireless spectrum allocation for meter telemetry modules in the United States, while the European Union's GDPR and national data-protection authorities shape how occupancy and payment data may be stored, shared, or monetized across municipal vendor contracts. California's SB 743 and similar state-level complete-street mandates indirectly accelerate smart meter deployment by tying transportation funding to vehicle-miles-traveled reduction metrics that demand granular curb-usage data. Stakeholders must monitor whether emerging cybersecurity certification requirements for critical infrastructure devices restrict vendor qualification to firms with demonstrated secure-development lifecycle credentials.
Market Dynamics
Municipal procurement officers now prioritize API-connected platforms over standalone hardware, compressing vendor qualification timelines and favoring suppliers with captive cloud infrastructure. This shift is restructuring competitive advantage around software integration depth rather than manufacturing scale alone.
Growth Catalysts
- Congestion pricing mandates:London's Ultra Low Emission Zone and New York City's pending central business district tolling require granular curb-occupancy data that only connected meters can supply.
- NB-IoT module cost collapse:Narrowband cellular chipsets from semiconductor foundries in Taiwan and South Korea have fallen below price thresholds that make retrofitting legacy meters economically viable for mid-sized cities.
- University campus digitization:Student ID system integration with permit management creates recurring revenue streams that offset hardware depreciation cycles.
Market Restraints
- Aluminum enclosure volatility:IP65-rated housing production depends on spot metal markets in Shanghai and Rotterdam, exposing hardware margins to commodity swings.
- GDPR data localization:European Union privacy rules restrict cross-border transfer of occupancy patterns, forcing redundant server deployment and raising operational complexity for multinational vendors.
- Smartphone app substitution:Camera-based license plate recognition systems eliminate physical meter requirements entirely in surface lots.
Strategic Opportunities
- Indian smart-city missions:Ministry of Housing and Urban Affairs funding for 100 designated cities lacks established vendor relationships, creating first-mover advantages for platform providers willing to localize payment gateways.
- Dynamic pricing convergence:Machine learning algorithms layered over real-time occupancy feeds enable demand-responsive rate adjustments that maximize revenue per space-hour.
- Loading bay monetization:Commercial freight operators in dense urban cores represent an untapped segment willing to pay premium rates for guaranteed curb access windows.
Industry Challenges
- Firmware security certification:Emerging IEC 62443 standards for industrial cybersecurity require documented secure-development lifecycles that smaller hardware vendors lack resources to implement.
- Legacy mainframe integration:Municipal finance departments in older cities operate on COBOL-based revenue systems that resist REST API connectivity without expensive middleware layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Parking Meters Market |
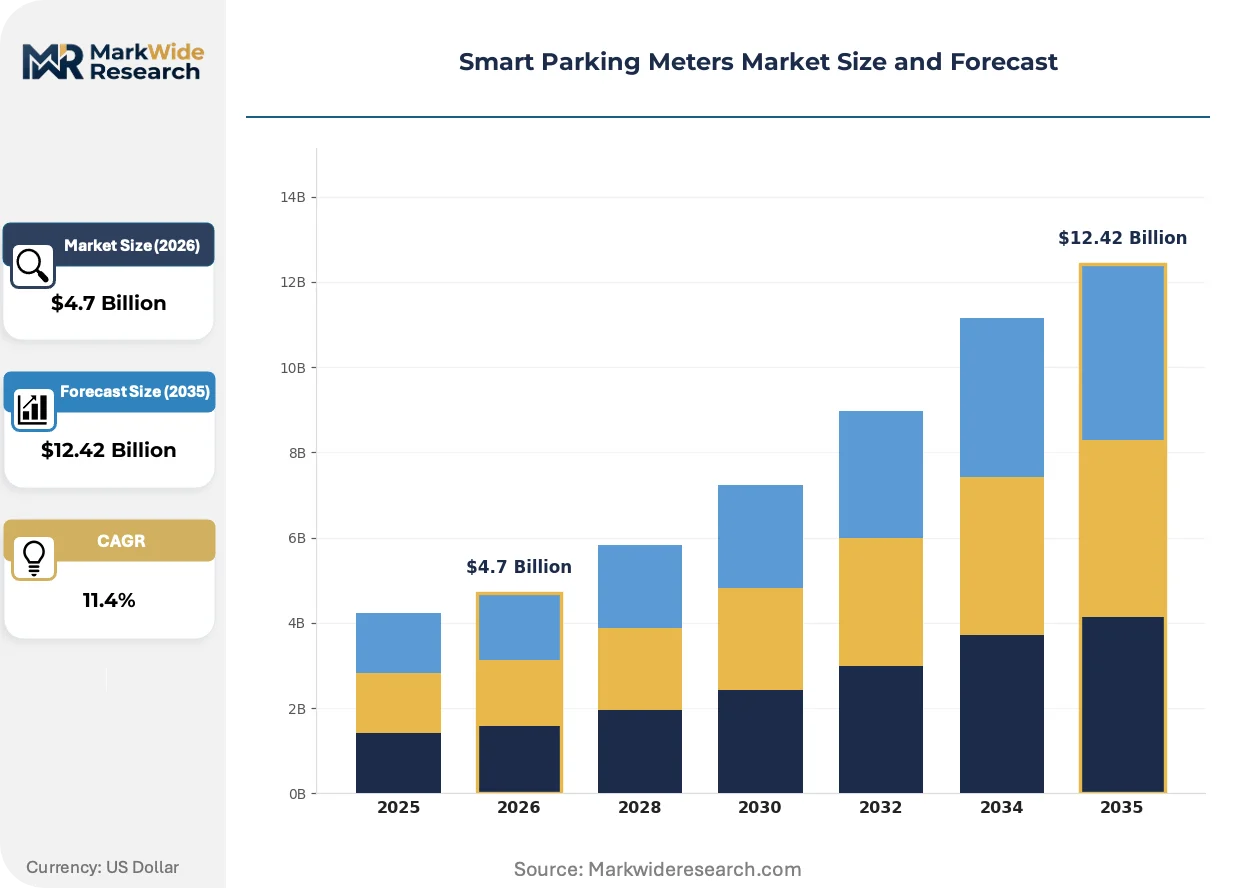
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.42 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Space Meters, Multi-Space Meters, Smart Meters, Pay-and-Display Meters Technology: Parking Sensors, RFID, Mobile Payment, Cloud Computing End User: Cities, Municipalities, Universities, Private Operators Distribution Channel: Online, Direct Sales, Distributors, Wholesale |
| Companies Covered | IPS Group Inc., Flowbird Group, J.J. MacKay Canada Limited, Parking BOXX Inc., CivicSmart Inc., Duncan Solutions, Hectronic GmbH, IEM SA, Ventek International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Parking Meters Market Evolving Landscape
Payment modality is fragmenting across multiple interfaces simultaneously, forcing hardware architects to support coin, card, QR, and NFC in single units while reducing physical footprint. This multiplicity is compressing design cycles and elevating software-defined feature delivery.
Solid-state lidar occupancy sensors are rendering obsolete mechanical induction loops embedded in asphalt for bay detection. San Diego and Barcelona procurement specifications now specify optical-only verification to reduce pavement disruption during installation. The technology is compressing deployment timelines from weeks to days while eliminating the concrete-cutting permits that delay municipal projects.
California's SB 743 vehicle-miles-traveled reduction mandates require transportation departments to demonstrate curb-usage efficiency gains for funding eligibility. The regulation forces cities to replace revenue-focused parking management with throughput-optimized systems that prioritize turnover over dwell time. Downtown Los Angeles and San Francisco districts are responding with maximum two-hour limits enforced through automatic license plate recognition integration.
Buyer committees now unbundle hardware procurement from decade-long maintenance contracts, fragmenting vendor relationships that previously locked cities into single-source ecosystems. Municipal fleet managers in Germany and the United Kingdom are separately sourcing payment platform licenses from cloud providers while soliciting competitive bids for meter installation. This separation is exposing hardware margins to direct price competition while shifting profit pools toward SaaS recurring revenue models.
Smart Parking Meters Market Segmentation
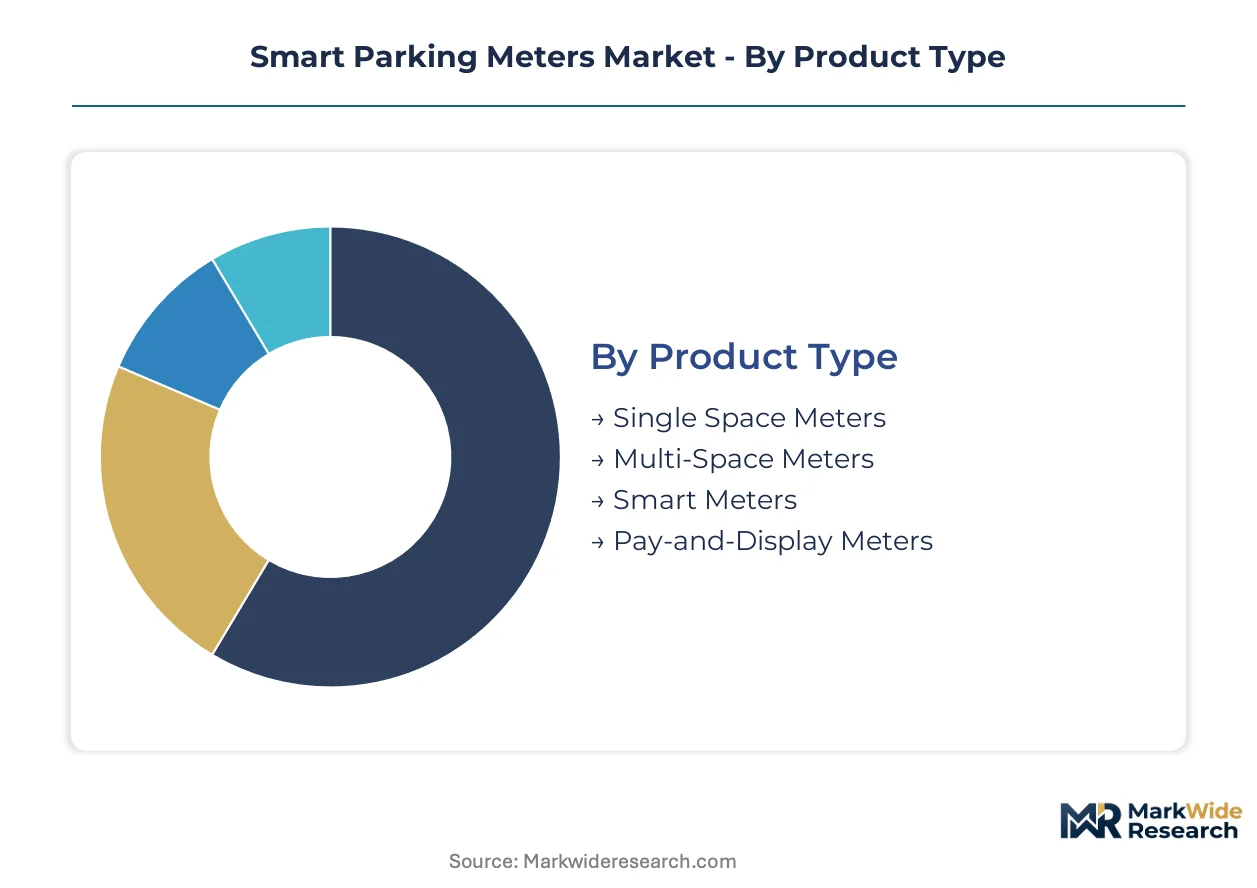
Smart parking meter procurement varies sharply by deployment context, with after-sales service intensity ranging from minimal for simple pay-and-display units to intensive for cloud-integrated municipal networks. Understanding these segment boundaries clarifies where vendor profitability concentrates and which customer relationships demand dedicated field engineering teams.
Product Type:
After-sales service intensity escalates dramatically with connectivity depth, creating divergent margin profiles across hardware categories.
- Single Space Meters:Individualized curb devices with coin, card, and NFC acceptance. Demand clusters in residential permit zones and loading bays across Germany and California where individualized enforcement tracking prevents revenue leakage. Firmware update cycles and vandalism repair drive recurring service contracts.
- Multi-Space Meters:Consolidated payment kiosks serving eight to twelve parking bays in dense downtown corridors. Cities including London and San Francisco prioritize these units where sidewalk footprint constraints limit hardware proliferation. Cloud backhaul integration demands 24/7 network operations support.
- Smart Meters:Solid-state devices with real-time occupancy sensing and dynamic pricing capability. Municipalities in the United Kingdom accelerate deployment where congestion pricing mandates require granular curb data feeds.
- Pay-and-Display Meters:Basic thermal-printing units without network connectivity. Smaller French and Italian cities favor these for low-traffic peripheral zones with minimal enforcement staffing.
Multi-space meters hold the largest share; momentum sits with smart meters.
Technology:
Technology selection dictates capital intensity and determines whether deployments require embedded hardware or smartphone-mediated interactions.
- Parking Sensors:Solid-state lidar and ultrasonic modules replacing mechanical induction loops for bay detection. San Diego and Barcelona procurement specifications now mandate optical-only verification to eliminate concrete-cutting permits. Installation timelines compress from weeks to days.
- Mobile Payment:QR-code and NFC overlays retrofitting legacy meters to push transactions toward smartphone apps. Mid-sized cities across the United States bypass hardware capital outlays through this approach. Transaction fees flow to platform providers rather than meter vendors.
- Cloud Computing:API-connected platforms feeding real-time occupancy data into municipal transportation management centers. German cities demand GDPR-compliant EU data residency for these deployments.
- RFID:Contactless permit validation for university campuses and corporate fleets. Student ID integration at North American universities creates sticky institutional relationships with multi-year renewal cycles.
Parking sensors anchor installed value; mobile payment climbs the fastest.
End User:
End-user type shapes procurement authority, budget cycles, and integration complexity with adjacent urban systems.
- Cities:Large metropolitan transportation departments with congestion pricing mandates and smart-city infrastructure grants. Los Angeles and New York City drive demand for machine learning-enabled dynamic pricing algorithms layered over occupancy feeds.
- Municipalities:Mid-sized urban governments combining parking revenue collection with traffic-flow optimization goals. Procurement committees in the United Kingdom and Germany increasingly unbundle hardware from maintenance contracts.
- Universities:Campus facilities departments requiring seasonal permit integration with student ID and payroll deduction systems. J.J. MacKay Canada Limited dominates this segment through pre-integrated enrollment management workflows.
- Private Operators:Commercial parking garage and surface lot managers prioritizing rapid deployment over customization. License plate recognition systems threaten to displace physical meters entirely in this segment.
Cities command the deepest technology stacks; universities deliver the stickiest recurring revenue.
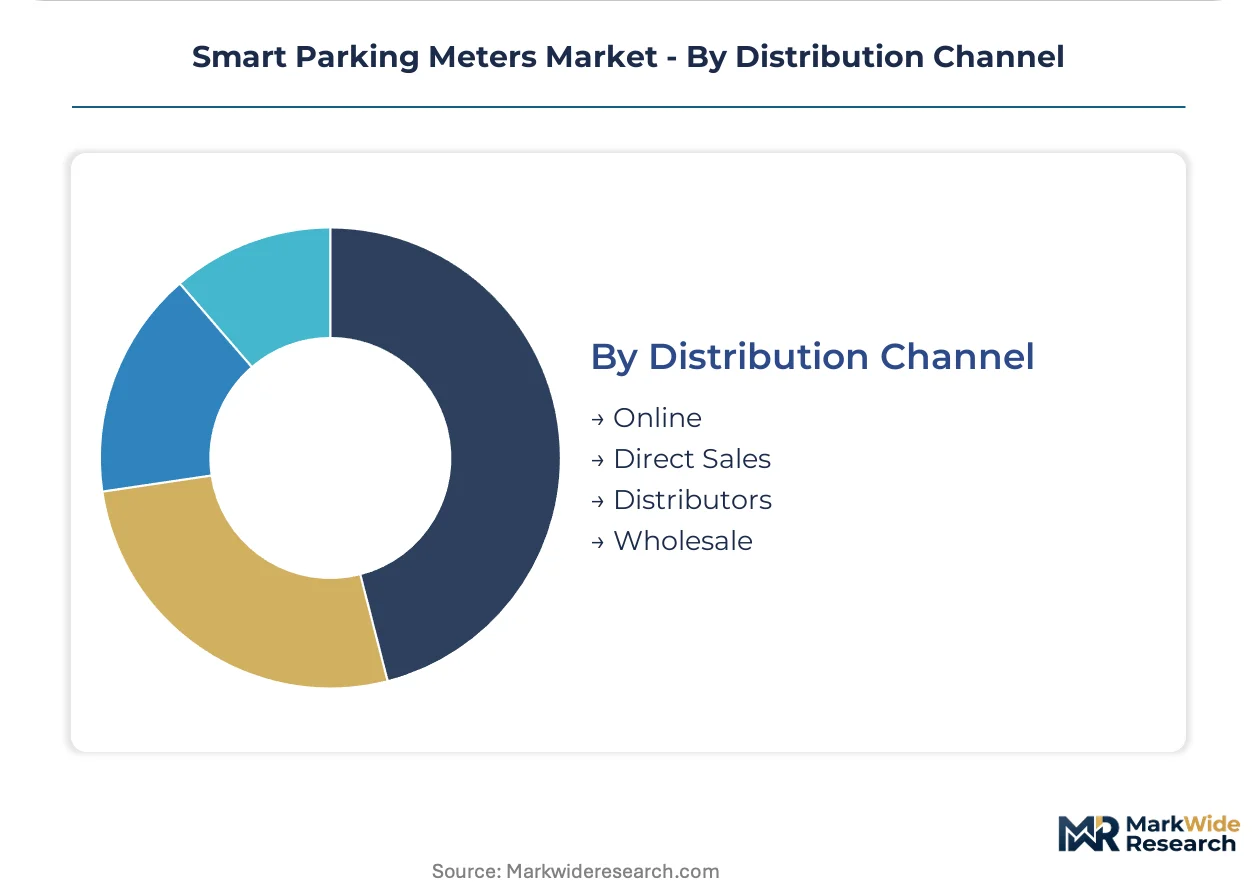
Distribution Channel:
Channel structure reflects customer technical sophistication and the balance between standardized products and customized curb-management solutions.
- Direct Sales:Municipal procurement officers negotiate multi-year framework agreements with meter manufacturers for citywide deployment. Flowbird Group leverages dense European service networks to anchor these relationships.
- Distributors:Regional system integrators bundling hardware with installation and maintenance services. Smaller French and Italian municipalities rely on these intermediaries for localized support.
- Online:Self-service procurement of replacement components and retrofit kits. University facilities departments and private operators favor this channel for speed.
- Wholesale:Volume supply to third-party parking management platforms white-labeling hardware. Cloud-native vendors source commoditized enclosures through this channel.
Direct sales capture the highest-value municipal contracts; online channels expand most quickly among smaller end users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal procurement officers in Germany, the United Kingdom, and California drive the deepest technology stacks, while mid-sized cities across France and Italy favor simpler pay-and-display configurations that minimize enforcement staffing.
United States
The FCC governs wireless spectrum allocation for meter telemetry modules, while California's SB 743 mandates vehicle-miles-traveled reduction metrics that demand granular curb-usage data. Los Angeles and San Francisco districts deploy maximum two-hour limits enforced through automatic license plate recognition integration.
Germany
German cities prioritize API-connected platforms with GDPR-compliant EU data residency requirements for cloud deployments. The KBA influences connected vehicle infrastructure standards that intersect with smart curb management. Procurement committees in Berlin and Munich increasingly unbundle hardware from decade-long maintenance contracts.
United Kingdom
London's Ultra Low Emission Zone requires granular curb-occupancy data that only connected meters can supply. National data-protection authorities shape how occupancy and payment data may be stored or monetized across municipal vendor contracts. Birmingham and Manchester accelerate smart meter deployment where congestion pricing mandates tighten.
France
French municipal operators favor dense service networks and long-term maintenance contracts for multi-space meter deployments. The CNIL enforces GDPR data localization rules that restrict cross-border transfer of occupancy patterns. Smaller cities in Provence and the Loire Valley rely on regional distributors for localized support of basic pay-and-display units.
India
The Ministry of Housing and Urban Affairs funds smart-city missions across 100 designated cities lacking established vendor relationships. TRAI regulates telecommunications infrastructure that supports mobile payment overlays retrofitting legacy meters. Bangalore and Hyderabad create first-mover advantages for platform providers willing to localize payment gateways.
Smart Parking Meters Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement cycles that now prioritize software integration depth over manufacturing scale alone. Municipal framework agreements favor suppliers with captive cloud infrastructure and dense regional service networks. Three archetypes dominate: vertically integrated hardware manufacturers, European service-network anchors, and campus-focused permit integration specialists. Competitive moves concentrate on unbundling hardware from maintenance contracts and accelerating custom chassis production for city-specific curb designs.
Among North American fabricators, IPS Group Inc. and J.J. MacKay Canada Limited exemplify divergent strategic positions—one anchored in municipal-scale manufacturing control, the other in sticky institutional relationships through student ID system integration. Flowbird Group represents the European service-network archetype, occupying a position shaped by long-term maintenance contracts with French and UK municipal operators. These three companies illustrate how competitive advantage now flows from either in-house production capabilities or recurring revenue streams tied to enrollment management workflows.
| Leading Market Players |
|---|
| IPS Group Inc. |
| Flowbird Group |
| J.J. MacKay Canada Limited |
| Parking BOXX Inc. |
| CivicSmart Inc. |
| Duncan Solutions |
| Hectronic GmbH |
| IEM SA |
| Ventek International |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor anchors aluminum enclosure logistics for IP65-rated meter housings, with spot metal volatility compressing hardware margins while municipal procurement unbundling shifts pricing power toward SaaS platform providers.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate municipal framework agreements for multi-space meter deployments. Three-tier pricing structure across premium API-connected platforms, standard cellular-enabled units, and economy pay-and-display configurations separates vendors by cloud integration depth. Cost compression in economy tiers intensifies because smartphone app substitution eliminates physical meter requirements in surface lots. University campuses exhibit lowest price sensitivity due to sticky student ID system integration, while mid-sized French municipalities drive hardest bargain on hardware-only bids.
Supply Chain Analysis
Taiwanese and South Korean semiconductor foundries hold concentrated capacity for NB-IoT cellular chipsets that enable meter connectivity. Hardware production draws from China for aluminum enclosure stamping, Mexico for final assembly integration, and Germany for precision sensor modules. Single-source vulnerability in narrowband modem supply exposes deployment timelines to foundry allocation decisions. Distribution runs through direct municipal procurement in North America and dense European service networks anchored by maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal procurement committee consolidation is concentrating buyer power, with unbundling of hardware from decade-long service contracts fragmenting vendor relationships that previously locked cities into single-source ecosystems.
For Market Incumbents: Insulate recurring revenue streams by deepening captive cloud infrastructure and accelerating firmware security certification under emerging IEC 62443 standards. License plate recognition systems threaten physical meter displacement in private operator segments; backward integration into solid-state lidar sensor production secures optical-only verification specifications now mandated by San Diego and Barcelona procurement officers. For New Entrants and Emerging Players: Establish a beachhead in Indian smart-city missions where Ministry of Housing and Urban Affairs funding lacks entrenched vendor relationships. Localized payment gateway integration for Bangalore and Hyderabad creates first-mover advantage before multinational platforms adapt. Target university campus digitization through student ID system interoperability as the most penetrable segment with multi-year renewal cycles. For Investors and Strategic Acquirers: Campus-focused permit integration specialists with pre-enrollment management workflows represent the most defensible acquisition archetype in a five-to-ten year window. Their sticky institutional relationships generate recurring revenue that offsets hardware depreciation cycles. Watch for GDPR data localization enforcement as the inflection signal that forces redundant EU server deployment and raises operational complexity for cloud-native entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Integration | API-connected occupancy data feeds satisfy London Ultra Low Emission Zone mandates. |
| Firmware Security Certification | IEC 62443 compliance qualifies vendors for critical infrastructure procurement. |
| Payment Gateway Localization | India TRAI-regulated mobile overlays bypass hardware capital outlays in smart-city missions. |
| Optical Sensor Manufacturing | Solid-state lidar eliminates concrete-cutting permits that delay Barcelona deployments. |
| Maintenance Contract Unbundling | Separate SaaS licensing from hardware bids exposes margins to direct price competition. |
Research Methodology
Desk research of municipal procurement databases, FCC spectrum allocation filings, and EU GDPR enforcement precedents preceded structured interviews with transportation department procurement officers, smart city infrastructure directors, parking enforcement technology managers, and university facilities executives. Bottom-up unit economics triangulated against top-down municipal budget allocations across the analysis window.
Assumptions held fixed include continued NB-IoT module cost decline, persistent aluminum spot price volatility, and steady congestion pricing mandate expansion. Segmentation dimensions modeled encompass product connectivity tier, payment modality, end-user procurement authority, and regional regulatory framework. CAGRs derived from installed base replacement cycles overlaid with smart-city infrastructure grant disbursement patterns.
Stress conditions across cellular chipset availability, GDPR cross-border data transfer restrictions, and COBOL mainframe integration costs were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of municipal framework agreement unbundling rates and firmware security certification adoption is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart City Technology
Singapore ICT Market
Smart City Technology
Smart Ticketing Solutions Market
Smart City Technology
Smart City Kiosk Deployment Market
Smart City Technology
Smart Package Lockers Market
Smart City Technology
Global Smart City ICT Infrastructure Market
Smart City Technology
Outdoor LED Smart Lighting Solution Market
Smart City Technology
Saudi Arabia Smart Cities Market
Smart City Technology
Smart City Kiosk Market
Smart City Technology
Global Smart Hubs Market
Smart City Technology
Global Smart/Connected Street Lights Market
Smart City Technology
Smart Signaling Market
Smart City Technology
Global Smart Pole Market
Smart City Technology
Smart Space Market
Smart City Technology
Smart Street Lights Market
Smart City Technology
Global Smart City Market
Smart City Technology
E-Governance Market