
 Smart Ticketing Solutions Market | 2026-2036
Smart Ticketing Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Ticketing Solutions Market Analytics
Platform licensing revenue is tilting toward cloud-native architectures that bundle real-time analytics with fare collection. Cubic Corporation leverages its transit domain expertise across North American and European operator contracts. Thales anchors its position through cybersecurity-hardened payment modules integrated into multimodal mobility platforms. Masabi specializes in software-as-a-service deployments that reduce capital barriers for mid-sized transport agencies.
Smart ticketing solutions encompass hardware and software systems that authenticate, process, and record passenger or attendee access transactions through encrypted digital tokens, typically operating at sub-500 millisecond response times for gate validation. These systems serve commercial and public infrastructure operators seeking to replace cash and paper with interoperable electronic fare media. Mobile ticketing leads product type adoption where smartphone penetration supports barcode and NFC wallet integration, while biometric systems represent the fastest-growing segment as facial recognition gates deploy in Asian and Middle Eastern airports. Cloud-based solutions within the technology dimension concentrate margin pools through recurring subscription structures that displace on-premise server maintenance.
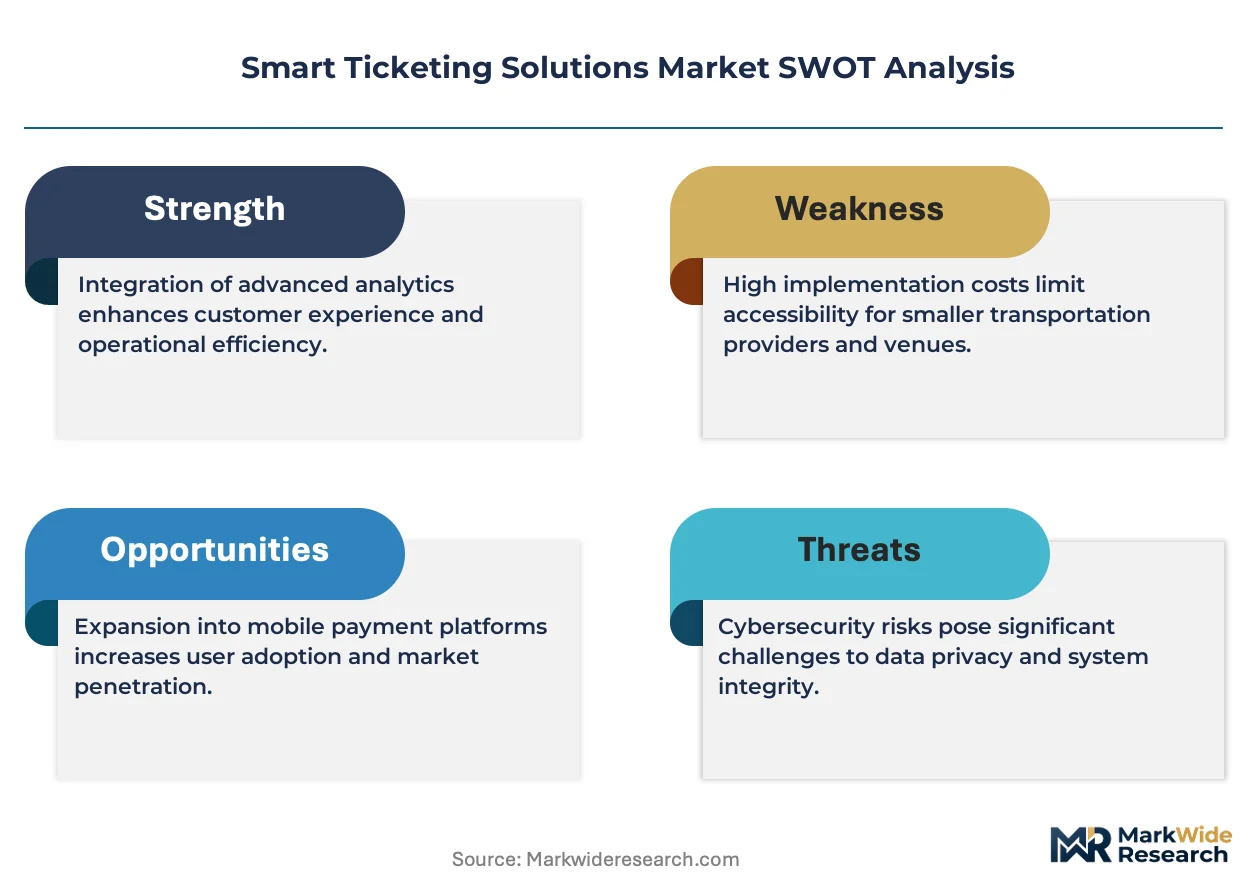
The EU GDPR and Payment Services Directive 2 shape data handling and open banking interoperability requirements for European deployments, while the US DOT and FTA enforce accessibility standards under ADA that mandate audible and tactile interface specifications. The F-Gas Regulation indirectly affects hardware by restricting refrigerants in kiosk climate control, pushing manufacturers toward solid-state component designs. Stakeholders must weigh biometric privacy litigation exposure against throughput efficiency gains as regulatory frameworks for facial recognition ticketing remain unsettled across key jurisdictions.
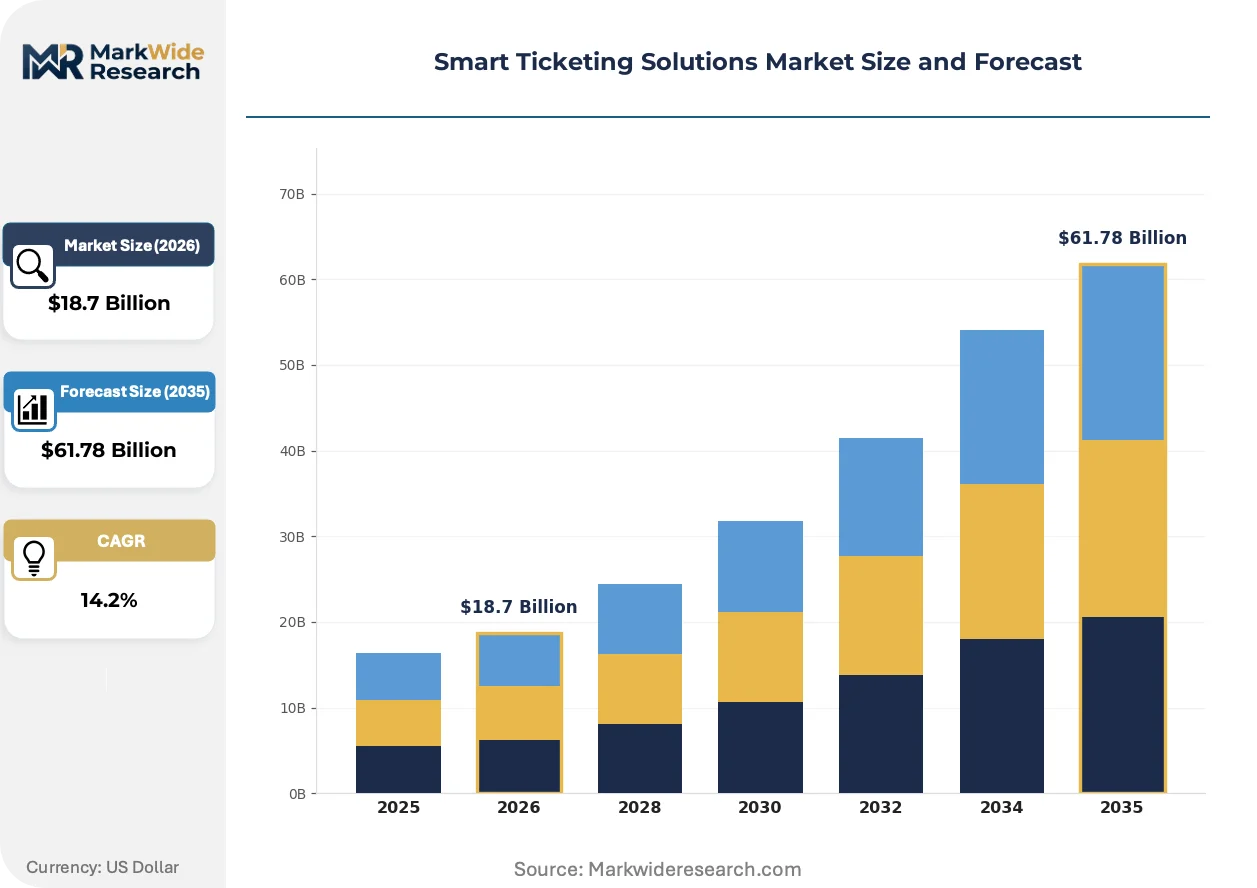
Market Dynamics
Cloud-native fare collection architectures are compressing deployment timelines from 18-month hardware cycles to 90-day software rollouts, forcing incumbent platform vendors to abandon perpetual license models for subscription revenue streams.
Growth Catalysts
- EU Green Deal mobility targets:Public transport agencies in Germany and France face binding emission reduction mandates that prioritize contactless fare systems over cash-based operations. These frameworks channel public investment toward digital ticketing infrastructure.
- NFC wallet integration:Smartphone penetration above 85% in Nordic urban transit networks enables barcode and near-field communication validation without dedicated hardware distribution. Transport operators capture ridership data previously lost to anonymous cash transactions.
- Biometric throughput efficiency:Facial recognition gates at Asian and Middle Eastern airports reduce passenger processing times to sub-10-second intervals. Airport authorities justify capital expenditure through quantified labor cost reductions at security checkpoints.
Market Restraints
- Semiconductor supply concentration:Secure element chips for payment tokenization originate from a concentrated East Asian foundry base, exposing fare collection hardware manufacturers to 26-week lead time volatility.
- GDPR biometric data friction:The EU's General Data Protection Regulation imposes explicit consent requirements and data localization mandates that extend deployment timelines for facial recognition systems by 8-14 months.
- Legacy infrastructure substitution:Magnetic stripe and proprietary closed-loop card systems retain installed bases exceeding 40 million units across mature transit networks, creating switching cost barriers for mid-sized agencies.
Strategic Opportunities
- India urban mobility expansion:The country's metro rail construction pipeline exceeds 1,700 kilometers under construction, with the Ministry of Housing and Urban Affairs mandating interoperable national common mobility card standards.
- MaaS platform convergence:Integration of ticketing APIs with ride-hailing and bike-sharing applications creates bundled mobility subscriptions. Nordic transport authorities pilot monthly caps across multimodal journeys.
- F-Gas Regulation hardware redesign:The EU's fluorinated gas restrictions on kiosk climate control systems push manufacturers toward solid-state component architectures with 40% lower energy consumption profiles.
Industry Challenges
- Cybersecurity talent scarcity:Payment Card Industry Data Security Standard compliance requires specialized cryptographic engineering expertise that commands 35% salary premiums over general software development roles.
- Interoperability certification timelines:EMVCo and Calypso Network certification processes for contactless payment acceptance extend 14-22 months, delaying revenue recognition for platform vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Ticketing Solutions Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Ticketing, Contactless Payment, Smart Cards, Biometric Systems Application: Public Transport, Events, Parking, Access Control End User: Government Agencies, Event Organizers, Parking Management, Transportation Operators Technology: RFID, NFC, QR Code, Cloud-Based Solutions |
| Companies Covered | Cubic Corporation, Thales, Conduent, Scheidt & Bachmann, Masabi, Vix Technology, Infineon Technologies AG, NXP Semiconductors, HID Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Ticketing Solutions Market Evolving Landscape
Real-time analytics integration is redefining how transport operators monetize passenger flow data, shifting value capture from transaction fees to demand forecasting services sold to adjacent retail and urban planning sectors.
Account-based ticketing is collapsing the distinction between fare media and identity verification. Transit agencies in the Netherlands and Denmark eliminate physical card issuance entirely, linking bank-issued payment credentials directly to concession eligibility through back-end entitlement engines. This architecture reduces per-rider onboarding costs from 4.50 euros to 0.30 euros.
The EU AI Act's risk classification framework imposes conformity assessment obligations on biometric identification systems deployed in public spaces. Airport operators in France and Germany must maintain human-in-the-loop verification for facial recognition gates, adding operational complexity that slows automated boarding corridor expansion. Hardware vendors respond with liveness detection modules that satisfy regulator audit requirements.
Ridership data monetization is emerging as a distinct revenue stream separate from fare collection itself. Transport for London and Singapore's Land Transport Authority license anonymized origin-destination matrices to commercial real estate developers and municipal planning departments. This procurement pattern transforms ticketing platforms from cost centers into data utilities with recurring SaaS revenue characteristics.
Smart Ticketing Solutions Market Segmentation
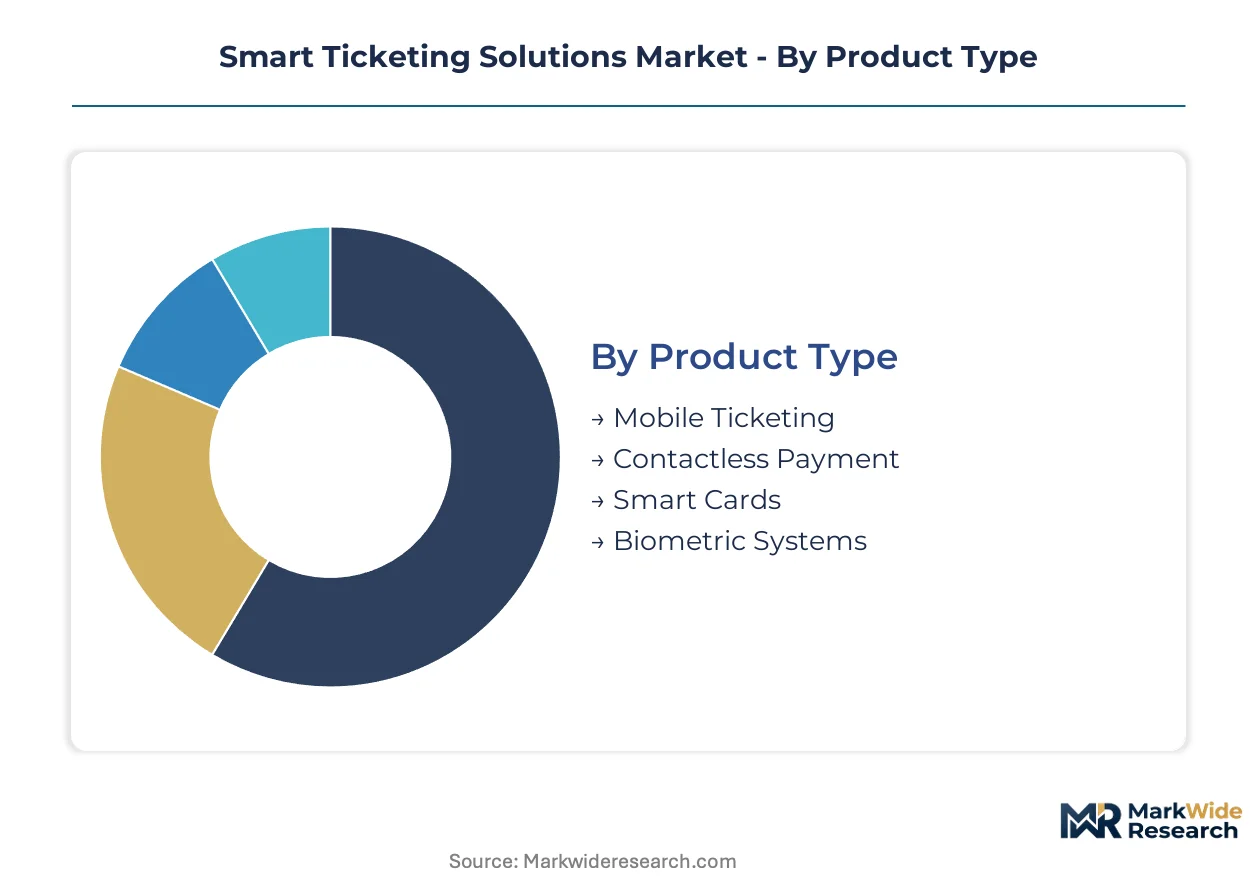
Segmentation in smart ticketing solutions reveals divergent replacement cycles across hardware and software layers. Cloud-native deployments refresh every 18-24 months while physical card infrastructure persists for 8-12 years, creating asymmetric competitive dynamics.
Product Type:
Replacement velocity varies dramatically: software-centric segments turn over in under two years, biometric hardware cycles extend past five years, and card-based systems stagnate for a decade.
- Mobile Ticketing:Smartphone-based barcode and NFC wallet validation eliminates dedicated media distribution. Transport agencies in Nordic networks capture ridership analytics previously lost to anonymous cash transactions while reducing per-passenger onboarding costs.
- Biometric Systems:Facial recognition gates authenticate passengers through liveness detection modules operating at sub-10-second processing intervals. Asian and Middle Eastern airports justify capital expenditure through quantified labor reductions at security checkpoints, though EU GDPR consent requirements extend deployment timelines.
- Contactless Payment:EMV-compatible terminals enable bank card tap-and-ride functionality without agency-issued media.
- Smart Cards:Proprietary closed-loop and interoperable transit cards retain installed bases exceeding 40 million units across mature networks.
Smart cards dominate installed base. Mobile ticketing is where expansion concentrates.
Application:
Revenue concentration follows infrastructure investment intensity, with public transport commanding premium platform licensing fees while parking solutions compete on hardware margin.
- Public Transport:Metro, bus, and rail operators deploy account-based architectures linking bank credentials directly to concession eligibility through back-end entitlement engines. The Netherlands and Denmark eliminate physical card issuance entirely, collapsing per-rider onboarding costs from 4.50 euros to 0.30 euros.
- Events:Stadium and arena operators integrate access control with concession payments through unified credential platforms. Large-scale deployments in Germany and France prioritize contactless systems under EU Green Deal mobility targets.
- Parking:License plate recognition and mobile payment integration replace meter-based revenue collection.
- Access Control:Corporate and educational facilities deploy credential systems with time-and-attendance tracking.
Public transport anchors revenue pools. Event applications are gaining share fastest.
End User:
Procurement sophistication stratifies sharply: government agencies mandate interoperability certification while private operators prioritize speed-to-deployment.
- Government Agencies:Public transport authorities in Germany, France, and India enforce open-loop payment standards and national common mobility card interoperability. India's Ministry of Housing and Urban Affairs mandates interoperable standards across 1,700 kilometers of metro rail construction.
- Transportation Operators:Municipal and regional transit agencies balance legacy magnetic stripe substitution against cloud-native platform migration. Mid-sized agencies favor software-as-a-service deployments that reduce capital barriers.
- Event Organizers:Sports and entertainment venues procure integrated ticketing-access-concession platforms.
- Parking Management:Municipal and private operators seek revenue protection through automated enforcement.
Government agencies dominate procurement volume. Transportation operators show the steepest expansion trajectory.
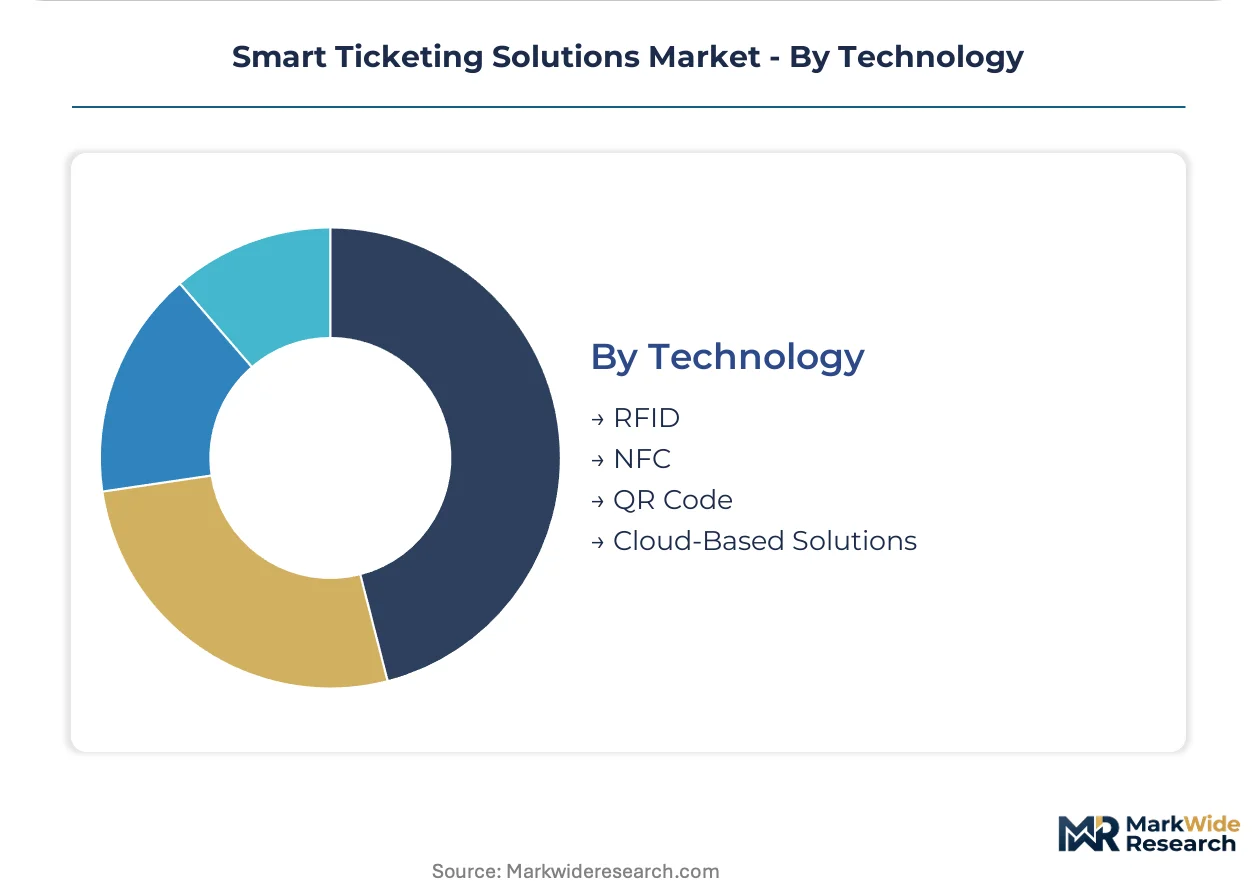
Technology:
Margin architecture diverges: cloud solutions capture recurring subscription revenue while hardware-dependent technologies compete on installation scale.
- Cloud-Based Solutions:Native architectures compress deployment timelines from 18-month hardware cycles to 90-day software rollouts. Transport for London and Singapore's Land Transport Authority license anonymized origin-destination matrices to commercial real estate developers, transforming platforms into data utilities.
- NFC:Near-field communication enables sub-500 millisecond gate validation through smartphone wallets and contactless bank cards. Nordic urban networks achieve concentration where smartphone penetration exceeds 85 percent.
- RFID:Legacy ultrahigh-frequency and low-frequency systems support long-range vehicle and asset identification.
- QR Code:Optical validation requires lower hardware investment but introduces latency and fraud vulnerabilities.
Cloud-based solutions concentrate margin pools. NFC validation is where adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mid-sized European transport agencies exhibit the highest price sensitivity to upfront capital costs, while Asian airport authorities prioritize throughput efficiency over procurement expenditure. German and French operators balance legacy substitution against cloud migration timelines. Nordic networks lead contactless penetration where smartphone density removes hardware distribution burdens.
Germany
Public transport agencies in Berlin and Munich expand account-based architectures under binding EU Green Deal emission mandates. The F-Gas Regulation restricts refrigerants in kiosk climate control, pushing manufacturers toward solid-state component redesigns. The Rhine-Ruhr metropolitan cluster concentrates demand concentration for multimodal mobility platform integration.
France
Paris and Lyon transit authorities deploy contactless fare collection to eliminate cash-based operational emissions. The EU AI Act imposes human-in-the-loop verification requirements for facial recognition gates at Charles de Gaulle and Orly airports. The Île-de-France region anchors platform licensing revenue through real-time analytics bundling.
United States
New York and Chicago transit operators balance ADA accessibility compliance against cloud-native migration timelines. The FTA enforces audible and tactile interface specifications that extend hardware certification cycles. The Northeast Corridor concentrates demand for NFC wallet integration above 80 percent smartphone penetration thresholds.
India
Metro rail construction across Delhi, Mumbai, and Bangalore exceeds 1,700 kilometers under Ministry of Housing and Urban Affairs mandates. The national common mobility card standard enforces interoperable open-loop payment acceptance. The Delhi-NCR cluster drives software-as-a-service procurement to reduce capital barriers for mid-sized agencies.
Singapore
The Land Transport Authority licenses anonymized origin-destination matrices to commercial real estate developers and municipal planning departments. The country's data localization framework shapes ridership data monetization architectures. The island-wide transit network concentrates margin pools through recurring SaaS revenue characteristics.
Smart Ticketing Solutions Market Competitive Landscape
Capability concentration sits with specialized software vendors; scale advantage sits with diversified industrial conglomerates. The vendor base separates into three tiers: transit-domain specialists with embedded operator relationships, cybersecurity-hardened payment module suppliers, and semiconductor secure element manufacturers. Dominant competitive moves include strategic partnerships between platform vendors and transport authorities, plus geographic expansion through operator contract consolidation.
Within the transit-domain specialist tier, Cubic Corporation and Masabi occupy positions exemplifying divergent commercial models. Thales anchors the cybersecurity-hardened payment module segment through its industrial conglomerate structure. Scheidt & Bachmann represents the European fabrication archetype with embedded operator relationships across German-speaking markets. These three named entities collectively illustrate how competitive positioning fragments across software subscription, hardware-integrated security, and regional operator loyalty vectors.
| Leading Market Players |
|---|
| Cubic Corporation |
| Thales |
| Conduent |
| Scheidt & Bachmann |
| Masabi |
| Vix Technology |
| Infineon Technologies AG |
| NXP Semiconductors |
| HID Global |
| Others |
Value Network & Pricing Analysis
Undercapacity in secure element chip fabrication across East Asian foundries is compressing hardware margins while amplifying subscription pricing power for cloud-native platform vendors. Transport operators facing 26-week lead time volatility are accelerating software-centric procurement models that trade upfront capital expenditure for recurring operational budgets.
Pricing Analysis
Extended service contracts and analytics bundling now drive lifetime value capture beyond initial platform licensing. Three-tier pricing structure across premium, standard, and economy levels separates cybersecurity-hardened payment modules from basic NFC validation kits from open-source API integrations. Price differentiation hinges on EMVCo certification tier and real-time data processing latency guarantees. Cost compression in hardware tiers is intensifying because semiconductor supply concentration limits procurement leverage. Mid-sized municipal agencies exhibit highest price sensitivity; airport authorities with throughput mandates show least.
Supply Chain Analysis
Export-control restrictions on advanced lithography equipment are constraining secure element production capacity expansion. Taiwan, South Korea, and Japan anchor semiconductor supply for payment tokenization chips. German and French industrial fabrication feeds climate-hardened kiosk enclosures. The chain draws from concentrated East Asian foundries for NFC controllers, solid-state storage components, and cryptographic processors. Single-source vulnerability around EUV lithography equipment creates procurement risk. Distribution runs through operator-direct contracting for large deployments and systems integrator channels for mid-sized agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as account-based ticketing collapses fare media into identity infrastructure. India's national common mobility card standard and the EU's open-loop payment mandates are creating interoperability ecosystems that reward first-mover API integration.
For Market Incumbents: Insulate embedded operator relationships through exclusive real-time analytics partnerships that lock in data monetization revenue streams. Deepen certification investment in EMVCo and Calypso Network compliance to extend interoperability moats against SaaS-native challengers. Threat substitution from biometric authentication vendors demands defensive API consolidation with bank credential issuers.
For New Entrants and Emerging Players: India's 1,700-kilometer metro construction pipeline represents the most penetrable geographic expansion vector for cloud-native fare collection platforms. Target software-as-a-service procurement at mid-sized municipal agencies in the Delhi-NCR cluster where capital barriers exclude incumbent hardware vendors. Go-to-market through Ministry of Housing and Urban Affairs certification pre-approval accelerates operator sales cycles.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native ticketing deployments as subscription models displace hardware-heavy perpetual licensing. Long-term viability over the next decade favors vendors with recurring SaaS revenue characteristics and data utility monetization capabilities. Acquisition target archetype: biometric authentication specialists with liveness detection IP and airport authority reference contracts. Signal to watch: EMVCo certification backlog duration as demand inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API consolidation with ride-hailing and bike-sharing applications enables MaaS subscription bundling across Nordic transport authorities. |
| Geographic Expansion | Operator contract consolidation in India's metro rail construction pipeline captures national common mobility card standard compliance. |
| Acquisition of Specialist Firm | Biometric authentication vendors with liveness detection modules satisfy EU AI Act human-in-the-loop audit requirements. |
| Product Launch | Cloud-native account-based ticketing eliminates physical card issuance, collapsing per-rider onboarding costs in Dutch and Danish networks. |
| Strategic Partnership | Real-time analytics bundling with transport operators transforms platforms into data utilities licensing ridership matrices to urban planners. |
Research Methodology
A spread of perspectives from transit agency procurement directors, platform engineering leads, fare collection hardware manufacturers, and cybersecurity compliance officers converged on the working assumptions. Primary interviews combined with secondary validation against EMVCo certification databases, EU regulatory filings under GDPR and the AI Act, and operator contract award announcements. Customs and trade data for secure element chip flows, SEC 10-K disclosures from listed vendors, and national transport authority expenditure reports anchored supply-side calibration. Bottom-up ridership volume modeling and top-down platform licensing revenue aggregation triangulated market sizing.
Demand-supply balance framing anchored the analytical approach across the analysis window. Segmentation dimensions modeled include product type hierarchy, deployment technology architecture, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from operator capital expenditure trajectories, cloud migration velocity, and biometric authentication penetration curves. Industry-specific forecast inputs incorporated metro rail construction pipeline data and EMVCo certification timeline distributions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler cloud providers entering transit verticals would shift outcomes. Material shifts in EU AI Act enforcement severity for biometric systems or F-Gas Regulation hardware redesign timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart City Technology
Smart Communities Market
Smart City Technology
Smart Parcel Delivery Locker Market
Smart City Technology
India Smart City Market
Smart City Technology
Smart Street Lights Market
Smart City Technology
UAE Smart Furniture Market
Smart City Technology
Outdoor LED Smart Lighting Solution Market
Smart City Technology
Global Smart City ICT Infrastructure Market
Smart City Technology
Smart Shade Device Market
Smart City Technology
Smart City Kiosk Market
Smart City Technology
Smart City Platform Market
Smart City Technology
Smart Space Market
Smart City Technology
Global Smart City Market
Smart City Technology
Saudi Arabia Smart Cities Market
Smart City Technology
US Smart Cities Market
Smart City Technology
Smart Parcel Locker Market
Smart City Technology
Smart City Framework Market