
 Europe Smart Water Meter Market | 2026-2036
Europe Smart Water Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart Water Meter Market Analysis
CE marking under the EU Measuring Instruments Directive is unwinding competitive access for non-compliant hardware vendors. Itron Inc. leverages its AMI software stack to anchor large-scale municipal contracts across France and Spain. Kamstrup competes through ultrasonic R&D intensity, while Diehl Stiftung & Co. KG sustains manufacturing scale from its German production base.
Europe smart water meters are precision flow measurement devices integrating ultrasonic or electromagnetic sensors with bi-directional communication modules, typically operating at IP68 ingress protection for submersible pit deployment. Their primary purpose is to automate consumption billing, detect distribution network leaks, and enable demand-side management for water utilities. Ultrasonic technology leads product type margins due to zero moving parts and extended calibration intervals, while NB-IoT dominates technology adoption where cellular infrastructure already blankets urban cores. Retrofit implementation type captures the fastest volume growth as cash-strapped utilities prioritize communication module overlays over full meter replacement.
EU Green Deal efficiency targets and the F-Gas Regulation are forcing utilities to quantify distribution losses with meter-level granularity, directly accelerating smart meter procurement timelines. EMA harmonization of metrological standards reduces cross-border certification friction for vendors serving multiple member states. Stakeholders must monitor how the EU AI Act classifies predictive analytics running on meter data streams, as compliance obligations could reshape software architecture investments.
Market Dynamics
The EU Green Deal's efficiency mandates are compressing replacement timelines for aging mechanical meters across municipal utilities, forcing capital allocation toward bi-directional communication infrastructure before full asset depreciation cycles conclude.
Growth Catalysts
- Non-Revenue Water Mandates:Southern European utilities face acute pressure to quantify distribution losses, accelerating procurement of ultrasonic meters with leak-detection algorithms.
- NB-IoT Network Density:Cellular infrastructure now blankets urban cores in France, Germany, and Spain, eliminating proprietary network build-out costs for AMI deployments.
- F-Gas Regulation Compliance:The EU directive forces utilities to document infrastructure efficiency gains, creating audit-trail requirements that only granular meter data satisfies.
Market Restraints
- Semiconductor Supply Concentration:Communication module production depends on Taiwanese foundry capacity, exposing deployment schedules to geopolitical disruption risk.
- Metrological Certification Friction:CE marking under the EU Measuring Instruments Directive imposes 18-24 month validation timelines, freezing product iterations.
- Copper Price Volatility:Electromagnetic meter coil winding costs fluctuate with London Metal Exchange pricing, compressing margins on economy-tier hardware.
Strategic Opportunities
- Polish Retrofit White Space:Municipal utilities in Warsaw and Krakow operate 40-year-old mechanical meter bases, creating overlay module demand without full replacement capex.
- Predictive Analytics Convergence:Machine learning pipelines trained on consumption patterns enable demand-side management services beyond billing automation.
- CSRD Disclosure Tailwinds:The Corporate Sustainability Reporting Directive mandates water stewardship metrics, pushing industrial off-takers toward sub-metering granularity.
Industry Challenges
- Cybersecurity Skill Scarcity:Utilities lack in-house capability to harden NB-IoT endpoints against firmware injection attacks, forcing reliance on vendor-managed security.
- Legacy AMI Protocol Fragmentation:Proprietary data formats from first-generation deployments block seamless migration to open-standards architectures.
- Submersible IP68 Validation Bottlenecks:Pit-deployment certification requires accelerated aging tests that extend product launch timelines by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart Water Meter Market |
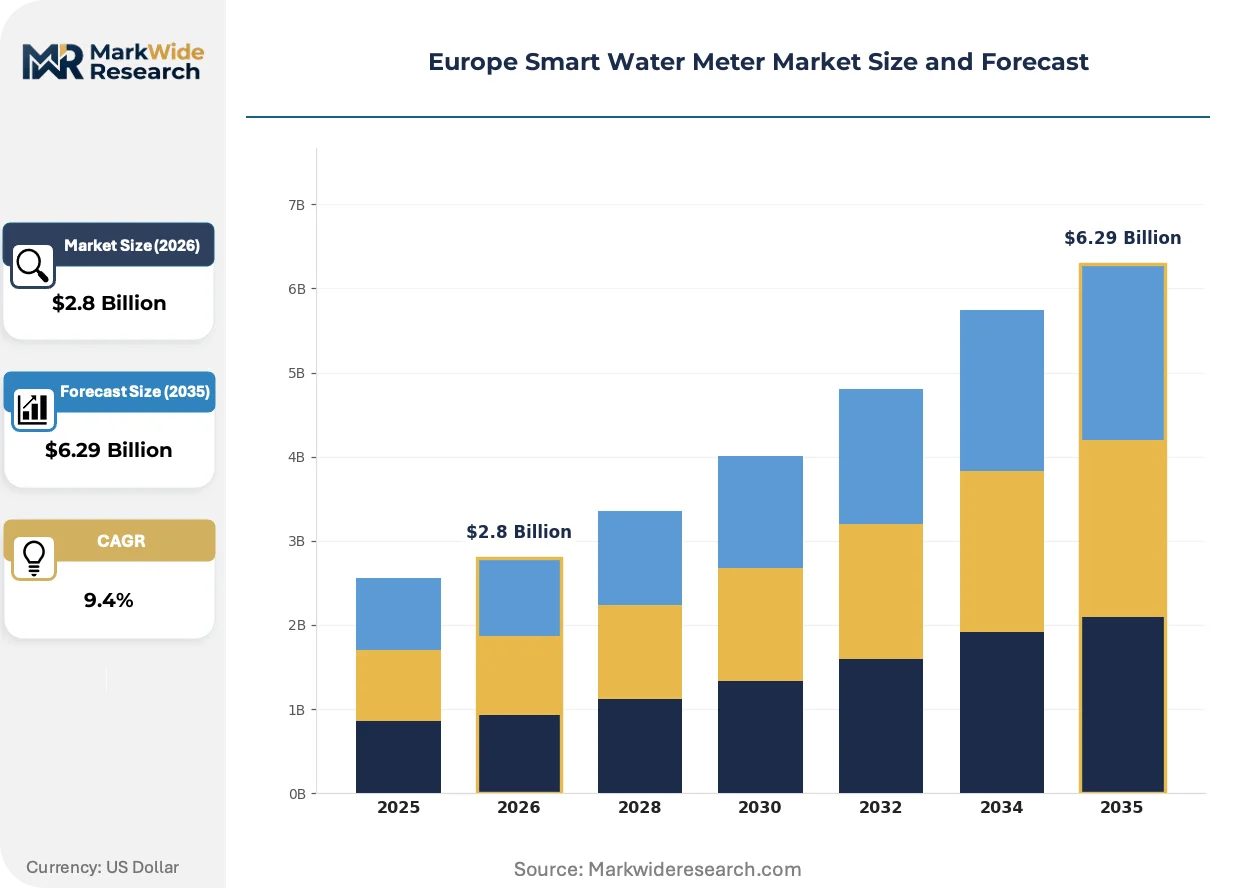
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic, Electromagnetic, Mechanical, Smart Ultrasonic End User: Residential, Commercial, Industrial, Municipal Technology: Cellular, LoRaWAN, NB-IoT, Wi-Fi Implementation Type: Retrofit, New Installation, Upgrade, Expansion |
| Companies Covered | Itron Inc., Schneider Electric, Landis+Gyr, ABB, Xylem, Kamstrup, Siemens, Honeywell International Inc., Diehl Stiftung & Co. KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart Water Meter Market Emerging Trajectories
Ultrasonic sensing architectures are compressing maintenance intervals and enabling new revenue streams through real-time anomaly detection, while regulatory disclosure requirements reclassify meter data as strategic infrastructure assets.
Ultrasonic flow measurement eliminates moving parts entirely, replacing turbine rotors with piezoelectric transducers that calculate velocity from time-of-flight differentials. German municipal utilities now specify zero-mechanical-wear designs for all new-build districts, prioritizing 15-year calibration intervals over 5-year mechanical service cycles. This reliability profile is supplanting electromagnetic technology in premium-tier procurement specifications across Northern Europe.
The EU AI Act's risk classification framework subjects predictive leak-detection algorithms to conformity assessment when deployed in critical water infrastructure. Vendors must document training data provenance and model drift monitoring protocols, adding compliance overhead to software development roadmaps. French utilities are responding by segregating meter data streams between billing systems and analytics sandboxes to limit regulatory exposure.
Outcome-based service contracts now bundle hardware, connectivity, and data analytics into per-connection fees rather than capital purchase models. Spanish municipal water authorities favor this structure to bypass municipal debt issuance constraints for infrastructure renewal. The shift transfers technology obsolescence risk from utility balance sheets to vendor retained-ownership structures.
Europe Smart Water Meter Market Segmentation
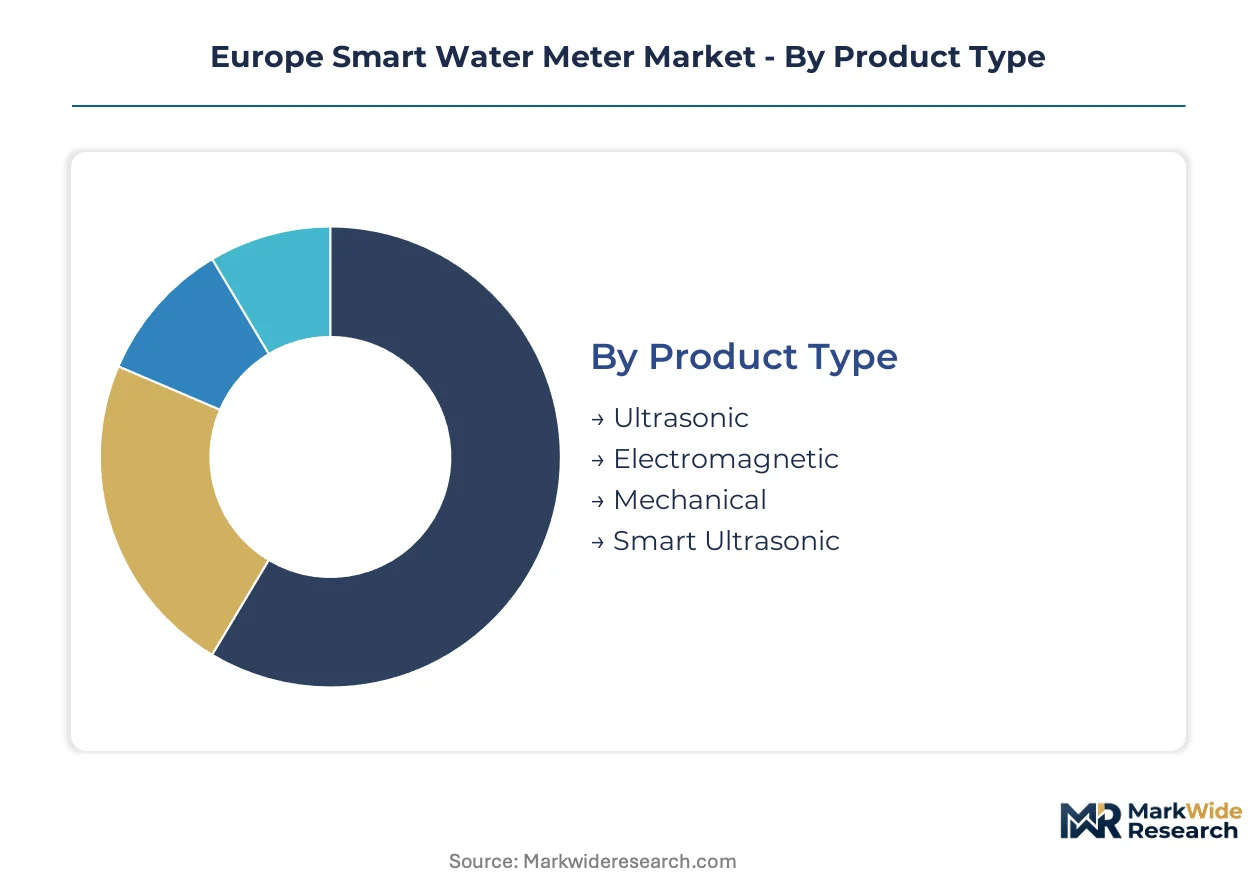
Smart water meter procurement in Europe fragments across hardware generations, connectivity protocols, and deployment models. Regulatory pressure under the EU Measuring Instruments Directive and F-Gas Regulation forces utilities to match segment selection to specific compliance timelines and infrastructure maturity.
Product Type:
CE marking requirements under the EU Measuring Instruments Directive impose divergent validation burdens across sensor architectures, favoring designs with extended calibration intervals.
- Ultrasonic:Piezoelectric transducers measure time-of-flight differentials without moving parts. German municipal utilities specify these for new-build districts to achieve 15-year calibration cycles under EMA harmonized standards. Zero mechanical wear eliminates turbine maintenance costs in submersible pit deployments.
- Electromagnetic:Coil-wound sensors generate magnetic fields to induce voltage proportional to flow velocity. French water authorities favor these for large-diameter commercial connections where copper price volatility from London Metal Exchange fluctuations squeezes economy-tier margins.
- Mechanical:Traditional turbine rotors dominate legacy installed bases across Southern Europe.
- Smart Ultrasonic:Integrated communication modules overlay ultrasonic cores for AMI readiness.
Established volume favors Mechanical; emerging adoption favors Ultrasonic.
End User:
Capital allocation patterns diverge sharply between rate-regulated municipal operators and industrial off-takers facing CSRD disclosure mandates.
- Residential:Single-family and multi-unit dwellings drive unit volume. Spanish utilities deploy NB-IoT-enabled meters to eliminate manual reading costs in dense urban cores where cellular infrastructure blankets service territories.
- Commercial:Office complexes and retail properties demand sub-metering granularity. The Corporate Sustainability Reporting Directive forces disclosure of water stewardship metrics, pushing facility managers toward real-time consumption monitoring.
- Industrial:Manufacturing and processing plants require high-precision flow measurement for process control.
- Municipal:City-owned distribution networks prioritize leak detection algorithms to quantify non-revenue water losses.
Municipal procurement dominates current deployment; Commercial installations are climbing the fastest.
Technology:
Network infrastructure maturity across France, Germany, and Spain determines protocol economics for utility AMI strategies.
- Cellular:2G/3G/4G modules leverage existing carrier infrastructure. Polish utilities in Warsaw and Krakow favor these to avoid proprietary network build-out costs for retrofit overlays on 40-year-old mechanical bases.
- LoRaWAN:Unlicensed spectrum protocols suit rural deployments with sparse cellular coverage.
- NB-IoT:Narrowband cellular standard optimized for low-power wide-area IoT. Urban cores in France, Germany, and Spain now blanket coverage, eliminating gateway infrastructure investment for municipal utilities.
- Wi-Fi:Consumer-grade connectivity serves residential sub-metering applications with existing home network availability.
Cellular retains installed-base dominance; NB-IoT shows the steepest expansion trajectory.
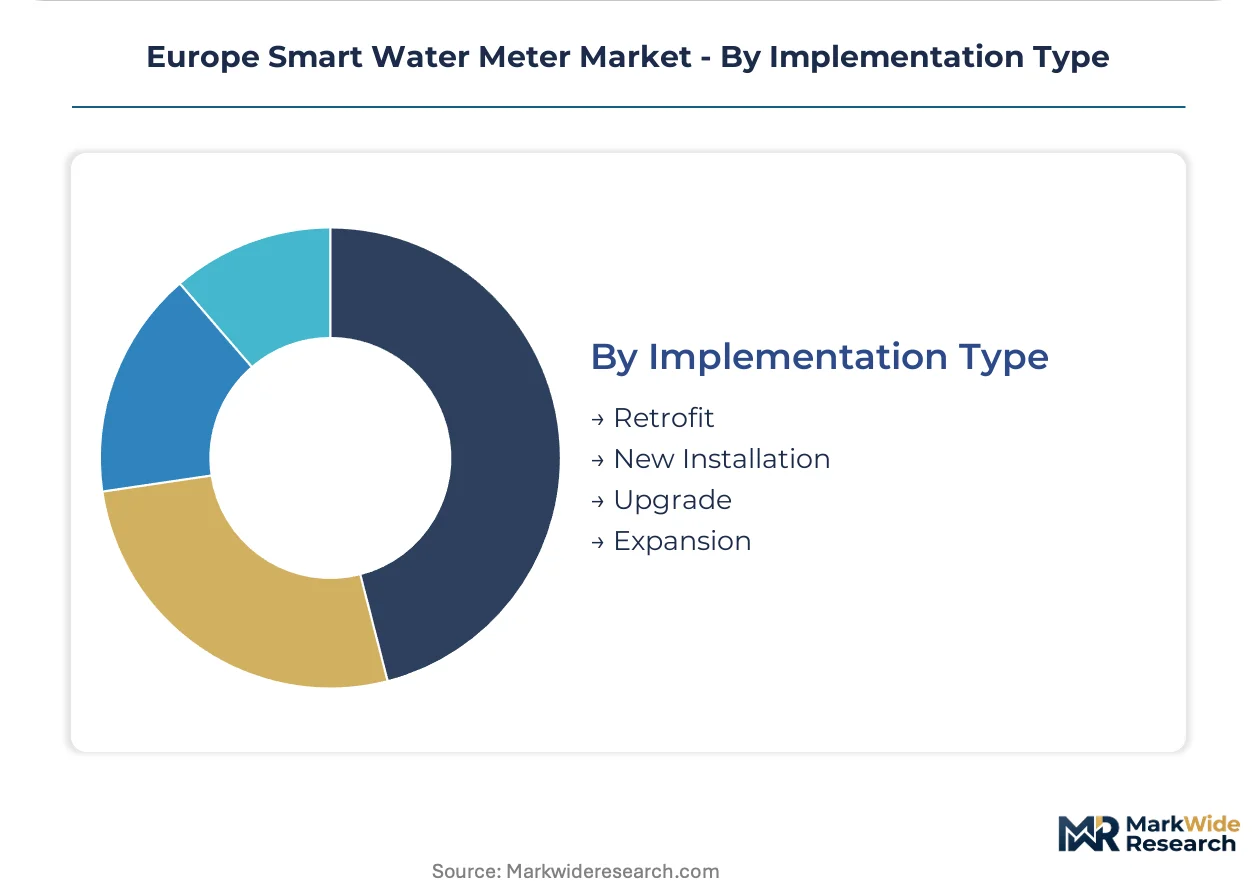
Implementation Type:
Budget constraints and asset depreciation cycles force utilities to choose between full replacement and communication module overlays.
- Retrofit:Communication modules attach to existing mechanical meter registers. Southern European utilities facing acute non-revenue water pressure favor this approach to accelerate AMI deployment without full capital replacement cycles.
- New Installation:Complete meter-communication integrated units deploy in greenfield developments. German building codes for new districts mandate smart-ready infrastructure under EU Green Deal efficiency targets.
- Upgrade:Partial hardware refresh extends functional life of aging assets.
- Expansion:Network extension into previously unmetered service connections.
New Installation commands premium pricing; Retrofit delivers the fastest volume growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal utilities concentrate procurement authority across Western and Southern Europe, with German, French, and Spanish operators driving replacement cycles for aging mechanical infrastructure.
Germany
Municipal utilities in North Rhine-Westphalia and Bavaria specify zero-mechanical-wear ultrasonic designs for new-build districts. The EU Green Deal efficiency mandates compress replacement timelines before full asset depreciation. Stuttgart and Munich water authorities prioritize 15-year calibration intervals under EMA harmonized standards.
France
Urban cores in Paris and Lyon deploy NB-IoT-enabled meters to eliminate manual reading costs where cellular infrastructure blankets service territories. The EU AI Act subjects predictive leak-detection algorithms to conformity assessment for critical infrastructure. French utilities segregate meter data streams between billing systems and analytics sandboxes to limit regulatory exposure.
Spain
Madrid and Barcelona municipal authorities favor outcome-based service contracts to bypass municipal debt issuance constraints. The F-Gas Regulation forces documentation of infrastructure efficiency gains through granular meter data. Southern utilities face acute pressure to quantify distribution losses, accelerating procurement of ultrasonic meters with leak-detection algorithms.
Poland
Warsaw and Krakow utilities operate 40-year-old mechanical meter bases, creating demand for communication module overlays without full replacement capital expenditure. Cellular modules leverage existing carrier infrastructure to avoid proprietary network build-out costs. Polish retrofit white space captures the fastest volume growth as cash-strapped utilities prioritize AMI acceleration.
Italy
Milan and Rome water authorities confront acute non-revenue water losses, driving retrofit deployments across aging distribution networks. The Corporate Sustainability Reporting Directive pushes industrial off-takers toward sub-metering granularity for water stewardship disclosure. Southern regions prioritize communication module overlays to accelerate AMI deployment without full capital replacement cycles.
Europe Smart Water Meter Market Vendor Landscape
Player mix skews toward integrated industrial conglomerates with captive metering divisions alongside specialized flow-measurement pure-plays. Market structure consolidates around three to four dominant AMI platform vendors with established utility relationships, while mid-tier electromagnetic specialists compete on price for commercial connection segments. Strategic archetypes include full-stack AMI providers, component-scale ultrasonic specialists, and diversified industrial automation houses. Competitive moves center on software stack anchoring for municipal contracts and manufacturing scale defense through German production bases.
Within the full-stack AMI tier, Itron Inc. and Landis+Gyr occupy positions as North American-anchored platform vendors with established European utility relationships. Kamstrup represents the ultrasonic R&D-intensive archetype among Danish specialists, while Diehl Stiftung & Co. KG exemplifies the diversified industrial house with captive German manufacturing scale. Siemens and ABB sit within the automation conglomerate category, leveraging existing electrical infrastructure relationships for cross-selling into water metering. These groupings reflect competitive positioning around software integration depth, sensor technology specialization, and manufacturing geography rather than pure hardware differentiation.
| Leading Market Players |
|---|
| Itron Inc. |
| Schneider Electric |
| Landis+Gyr |
| ABB |
| Xylem |
| Kamstrup |
| Siemens |
| Honeywell International Inc. |
| Diehl Stiftung & Co. KG |
| Others |
Supply Flow & Price Mechanics
Outcome-based service contracts with municipal utilities in Spain and Poland lock in multi-year revenue visibility while transferring technology obsolescence risk from utility balance sheets to vendor retained-ownership structures. These arrangements bundle hardware, connectivity, and data analytics into per-connection fees that bypass municipal debt issuance constraints.
Pricing Analysis
Cost-plus contracts with London Metal Exchange copper indexation dominate electromagnetic meter procurement for French commercial connections. Three-tier pricing structure across premium, standard, and economy levels separates ultrasonic designs with 15-year calibration intervals from electromagnetic alternatives with coil-wound sensors. Cost compression in economy-tier hardware is intensifying because copper price volatility squeezes margins on coil winding components. Municipal utilities in Southern Europe exhibit highest price sensitivity due to acute non-revenue water pressures, while German new-build districts show lowest sensitivity as EU Green Deal mandates override procurement cost considerations.
Supply Chain Analysis
Taiwan anchors communication module wafer fabrication while Germany sustains captive manufacturing scale for ultrasonic sensor assemblies. Taiwanese foundry capacity feeds NB-IoT chipset production, and German precision engineering clusters source piezoelectric transducers for time-of-flight measurement cores. Single-source vulnerability concentrates in semiconductor lithography equipment, exposing deployment schedules to geopolitical disruption risk. Distribution runs through direct municipal procurement channels with established AMI platform vendors, supplemented by systems integrator partnerships for retrofit overlay deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capability gaps in cybersecurity firmware hardening and predictive analytics compliance under the EU AI Act are constraining vendor differentiation and locking procurement decisions to incumbent relationships with proven utility track records.
For Market Incumbents: Consolidate software stack anchoring through AMI platform deepening in France and Spain, where cellular infrastructure density eliminates proprietary network build-out costs. Acquire ultrasonic R&D specialists in Denmark to defend sensor technology leadership against electromagnetic price competition. Prioritize CE marking pre-certification investments to compress 18-24 month validation timelines under the EU Measuring Instruments Directive. For New Entrants and Emerging Players: Anchor in Polish retrofit white space where Warsaw and Krakow utilities operate 40-year-old mechanical meter bases, creating communication module overlay demand without full replacement capital expenditure. Target Southern European leak-detection algorithm deployments where non-revenue water mandates accelerate procurement timelines. Pursue outcome-based service contract structures to bypass municipal debt issuance constraints. For Investors and Strategic Acquirers: Capital is best deployed toward ultrasonic technology pure-plays with established EMA harmonized calibration certifications and proven utility relationships across multiple member states. Long-term viability hinges on software-defined revenue expansion beyond hardware transactional models. Monitor NB-IoT network coverage expansion in Eastern European urban cores as inflection indicator for retrofit deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AMI Platform Integration | Itron Inc. and Landis+Gyr leverage established utility relationships to cross-sell analytics modules. |
| Ultrasonic R&D Scale-Up | Kamstrup intensifies piezoelectric transducer development to extend calibration intervals under EMA standards. |
| Retrofit Communication Overlay | Polish utilities in Warsaw deploy cellular modules on aging mechanical bases without full replacement capex. |
| Predictive Analytics Compliance | French utilities segregate meter data streams to limit EU AI Act conformity assessment exposure. |
| Outcome-Based Service Contracting | Spanish municipal authorities bypass debt issuance constraints through per-connection fee structures. |
Methodological Framework
Cross-validation between primary interviews with municipal utility planning officers, AMI procurement managers, and water distribution network engineers anchors the qualitative findings against secondary validation from EMA harmonized standards documentation, EU Green Deal implementation reports, and F-Gas Regulation compliance filings. Bottom-up triangulation aggregates deployment data across German, French, Spanish, Polish, and Italian municipal operators, while top-down verification cross-checks against cellular infrastructure coverage maps and copper price index movements.
Sensitivity analysis across the analysis window tests forecast robustness against semiconductor supply disruption scenarios and regulatory timeline compression under the EU AI Act. Segmentation dimensions modeled include sensor architecture, connectivity protocol, implementation type, and end-user category. CAGRs derive from utility capital expenditure planning cycles, asset depreciation schedules, and replacement timeline acceleration under efficiency mandates. Industry-specific inputs incorporate NB-IoT network density metrics and metrological certification pipeline data.
Decision-makers should treat outputs as directional under assumptions of sustained EU regulatory pressure and stable Taiwanese semiconductor supply; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in F-Gas Regulation enforcement intensity and EMA standards harmonization progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Smart Electric Meter Market
Smart Meters
US Water Meter Market
Smart Meters
Asia Pacific Smart Water Metering Market
Smart Meters
Power Quality Meter Market
Smart Meters
US Smart Meter Data Management Market
Smart Meters
United States (US) Water Meter Market
Smart Meters
United States (US) Residential Smart Meters Market
Smart Meters
Residential Water Submetering Market
Smart Meters
Residential Smart Water Metering Market
Smart Meters
Middle East Distribution Meter Market
Smart Meters
Commercial Non IC Card Gas Smart Meter Sales Market
Smart Meters
Smart Water Metering Market
Smart Meters
South and Central America Smart Metering Market
Smart Meters
Electricity Meters (Smart Meters) Market
Smart Meters
Europe Water Meter Market
Smart Meters
Global Smart Electricity Meter Market