
 US EV Battery Pack Market | 2026-2036
US EV Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
US EV Battery Pack Market Insights
Project finance tied to gigafactory construction is rewriting competitive entry barriers for battery pack assembly in the United States. LG Energy Solution Ltd. leverages vertical integration into cathode precursor production to secure feedstock certainty. Panasonic Holdings Corporation anchors its position through joint venture structures with domestic OEMs. SK Innovation Co. Ltd. navigates tariff exposure by expanding cell-to-pack manufacturing footprints inside US trade zones.
A US EV battery pack integrates hundreds to thousands of individual lithium-ion cells within thermal management enclosures, delivering direct current outputs typically ranging from 300 to 800 volts to power electric traction motors. Passenger vehicle applications dominate current volume, though commercial vehicle configurations represent the fastest-expanding margin pool as fleet operators seek extended-range capacity tiers. Solid-state chemistry remains pre-commercial but attracts disproportionate R&D allocation, while standard range packs face pricing compression from lithium iron phosphate cell substitutions.
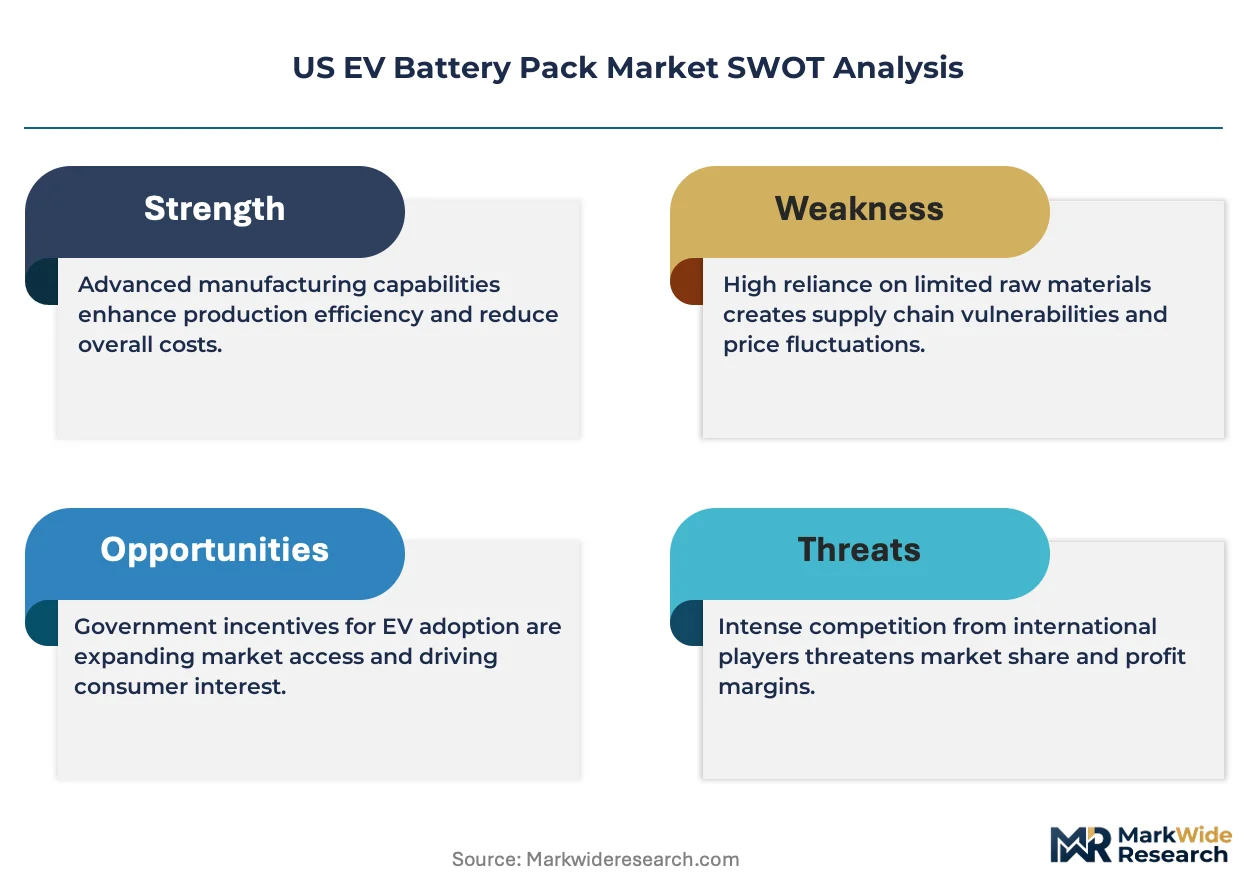
The Inflation Reduction Act (IRA) domestic content thresholds, enforced by the Department of Treasury, redirect procurement toward North American-assembled cells and packs. NHTSA crashworthiness standards for battery enclosure integrity, alongside EPA lifecycle emissions tracking, shape pack architecture and material selection decisions. Stakeholders must monitor how Treasury guidance on foreign entity of concern rules reshapes joint venture partner eligibility and capital deployment timelines.
Market Dynamics
IRA domestic content thresholds are rewiring procurement flows toward North American cell assembly, compressing pack economics for foreign-assembled alternatives and accelerating capital deployment into US-based manufacturing corridors.
Growth Catalysts
- Fleet electrification mandates:Commercial vehicle operators across California and New York face binding zero-emission deadlines under state-level clean fleet regulations. Extended-range pack configurations capture disproportionate investment as operators prioritize route flexibility over upfront cost minimization.
- Lithium iron phosphate chemistry:Standard-range passenger applications are absorbing LFP cell substitutions that reduce cobalt dependency and compress pack-level bill-of-materials. Thermal management architectures adapt to accommodate LFP's distinct voltage profiles and cycle characteristics.
- Michigan gigafactory clustering:Cell-to-pack assembly capacity concentrates along I-94 corridor infrastructure, anchoring supplier ecosystems and reducing inbound logistics exposure for cathode active material streams.
Market Restraints
- Lithium carbonate volatility:Pack cost structures remain exposed to South American and Australian spodumene concentrate pricing swings that transmit directly to cell cathode input costs.
- Graphite anode concentration:Synthetic and natural graphite supply chains concentrate among East Asian refiners, creating tariff and qualification risk for US-assembled packs under foreign entity of concern screening.
- Fast-charging degradation limits:Current-generation silicon-anode blends face cycle-life tradeoffs that constrain ultra-rapid charging deployment in commercial duty cycles.
Strategic Opportunities
- Texas and Southeast manufacturing corridors:Greenfield sites in Georgia and Tennessee offer port access and right-to-work labor frameworks for pack assembly serving southeastern OEM footprints.
- Second-life stationary storage:Retired automotive packs retain 70-80% usable capacity for grid-buffer applications, opening circular revenue streams through disassembly and module reconfiguration.
- IRA transferability mechanics:Commercial lessors can monetize manufacturing and clean vehicle credits through pass-through structures that improve total cost of ownership calculations for fleet buyers.
Industry Challenges
- Battery management system firmware talent:Pack integrators compete for embedded systems engineers capable of cell-level state estimation across heterogeneous cell aging profiles.
- NHTSA crashworthiness certification timelines:Enclosure designs face 18-24 month validation cycles for thermal runaway propagation resistance under FMVSS 305 interpretations.
- Legacy DC fast-charging protocol fragmentation:Pack designers must accommodate CCS, NACS, and emerging megawatt charging standards simultaneously, complicating power electronics architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US EV Battery Pack Market |
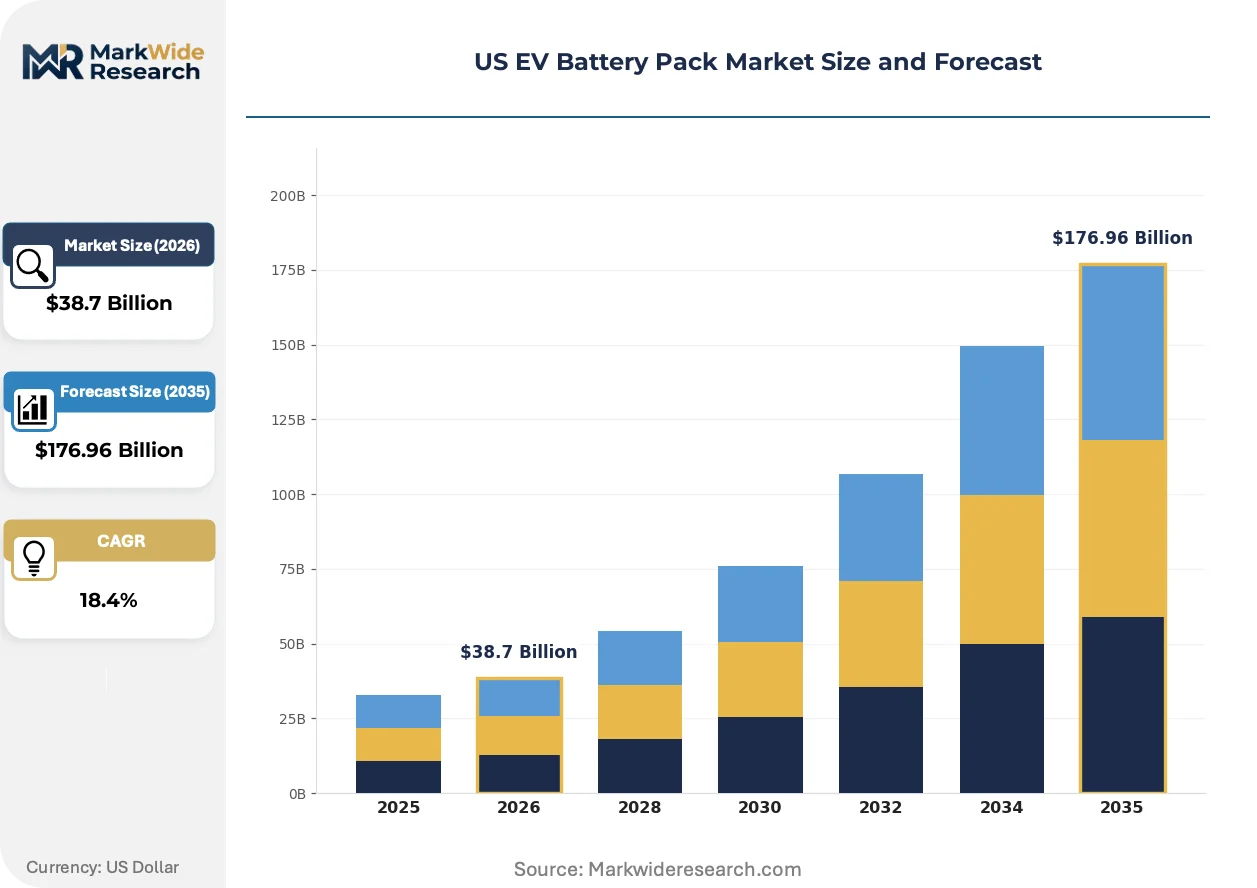
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $176.96 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Chemistry: Lithium-Ion, Nickel-Metal Hydride, Solid-State, Lithium Polymer Application: Passenger Vehicles, Commercial Vehicles, Urban Mobility, Fleet Services End User: Automakers, Battery Manufacturers, Distributors, Fleet Operators Capacity: Standard Range, Extended Range, High Capacity, Ultra High Capacity |
| Companies Covered | LG Energy Solution Ltd., Panasonic Holdings Corporation, Contemporary Amperex Technology Co. Ltd. (CATL), SK Innovation Co. Ltd., Envision AESC Japan Co. Ltd., Samsung SDI Co. Ltd., A123 Systems LLC, QuantumScape Corp., Nikola Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US EV Battery Pack Market Trends and Innovations
Cell chemistry diversification and thermal architecture advances are compressing pack cost curves while extending operational envelopes. Structural battery integration and solid-state prototyping represent parallel innovation tracks with distinct commercialization horizons.
Solid-state electrolyte research is hybridizing conventional liquid-cell manufacturing with sulfide and oxide ceramic separator trials. Toyota Motor Corporation and QuantumScape Corporation pilot lines target automotive qualification cycles by decade-end. The technology promises energy density gains that would compress pack mass for equivalent range targets.
Treasury guidance on IRA foreign entity of concern rules is forcing joint venture restructuring among Korean cell producers. Partnership eligibility now hinges on beneficial ownership thresholds that exclude certain state-affiliated investors. Domestic OEMs are responding by accelerating wholly owned cell plant development in Ohio and South Carolina.
Commercial fleet operators are consolidating procurement through national leasing structures that unbundle pack ownership from vehicle acquisition. Ryder System and Penske Truck Leasing negotiate directly with pack assemblers for standardized mid-duty configurations. This channel shift concentrates volume among fewer buyer entities with customized thermal management specifications.
US EV Battery Pack Market Segmentation
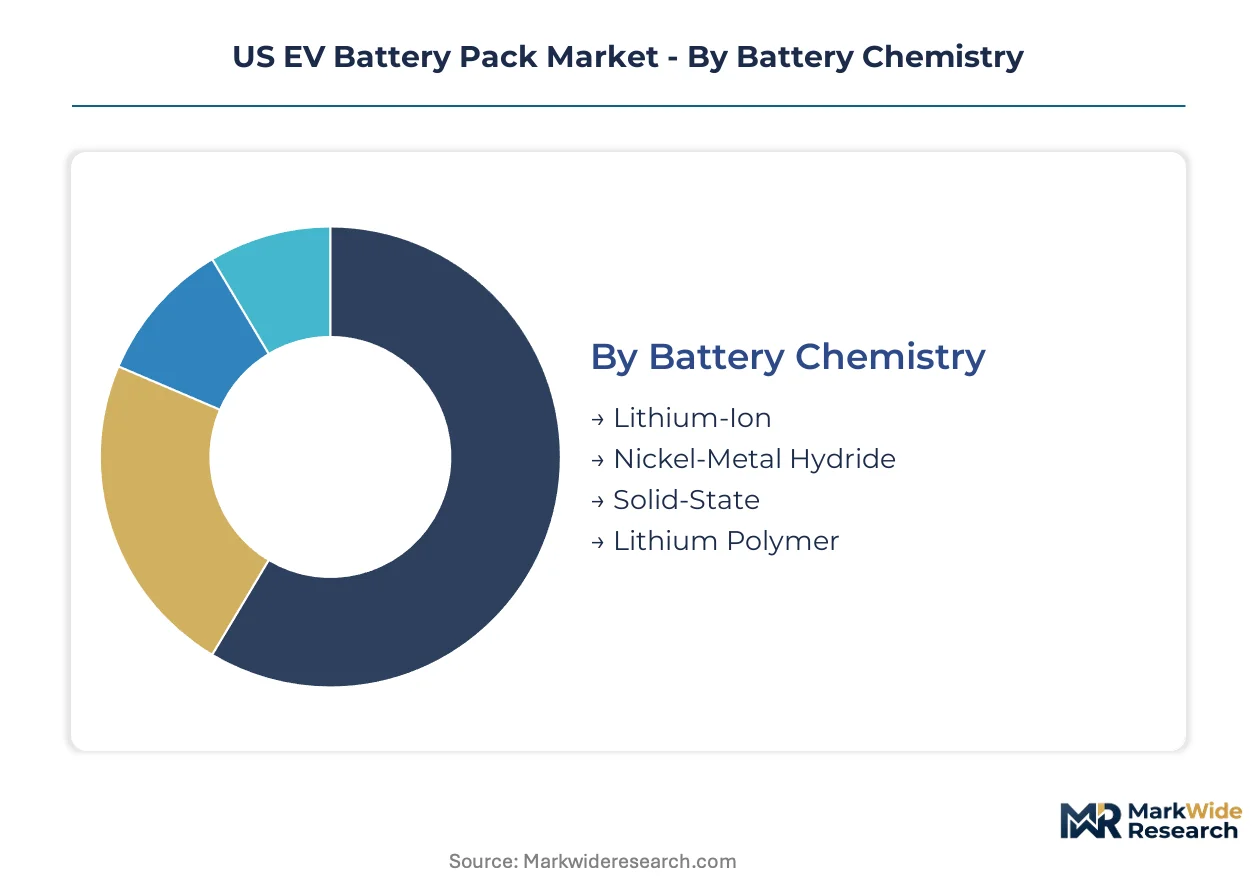
Segmentation reveals how procurement cycles, technical specifications, and customer economics diverge across the US EV battery pack landscape. Chemistry choices and capacity tiers carry distinct replacement timelines and margin profiles that reshape supplier priorities.
Battery Chemistry:
Cycle times vary dramatically: LFP formulations degrade slower and extend replacement windows, while solid-state prototypes promise decade-long service lives once commercialized.
- Lithium-Ion:NMC and NCA cathode architectures dominate current pack assembly, delivering 300-800V outputs through cylindrical or prismatic cell configurations. Michigan gigafactory clusters concentrate cathode precursor supply for these chemistries, though cobalt sourcing faces IRA foreign entity screening.
- Solid-State:Sulfide and oxide ceramic electrolyte prototypes target automotive qualification with energy density advantages that would compress pack mass for equivalent range. Toyota Motor Corporation pilot lines in Japan and domestic joint ventures are accelerating US-specific validation timelines.
- Lithium Polymer:Pouch cell formats enable flexible pack geometries for urban mobility applications with constrained installation volumes.
- Nickel-Metal Hydride:Legacy hybrid applications retain niche demand in commercial fleet retrofits where capital constraints limit full electrification.
Lithium-Ion anchors the volume base while Solid-State gains share at the steepest rate.
Application:
Cost tier separation runs deepest here: passenger configurations optimize for per-kWh minimization while commercial variants absorb premium pricing for durability and thermal resilience.
- Passenger Vehicles:Pack designs prioritize mass reduction and cabin space preservation through structural battery integration. California and Texas absorb the highest deployment volumes as OEM assembly plants concentrate in those states.
- Commercial Vehicles:Extended-range configurations with reinforced thermal management enclosures command pricing premiums for route flexibility. Fleet operators across New York and California face binding zero-emission deadlines that compress procurement timelines.
- Urban Mobility:Two-wheeler and micro-mobility packs emphasize swappable architectures with simplified battery management systems.
- Fleet Services:Standardized mid-duty configurations consolidate procurement through national leasing structures with customized warranty terms.
Passenger Vehicles anchor the volume base while Commercial Vehicles expand most quickly.
End User:
Customer type determines specification authority: automakers dictate cell-to-pack integration standards while fleet operators increasingly unbundle pack ownership from vehicle acquisition.
- Automakers:Vertical integration into cell assembly through joint ventures with Korean producers reshapes procurement leverage. NHTSA crashworthiness certification timelines constrain enclosure design choices.
- Fleet Operators:National leasing structures concentrate buying power among fewer entities with customized thermal management specifications. Ryder System and Penske Truck Leasing negotiate directly with pack assemblers for standardized configurations.
- Battery Manufacturers:Cell-to-pack integrators compete on firmware talent for cell-level state estimation across heterogeneous aging profiles.
- Distributors:Aftermarket channels service legacy hybrid retrofits and second-life stationary storage redeployment.
Automakers anchor the volume base while Fleet Operators climb the fastest.
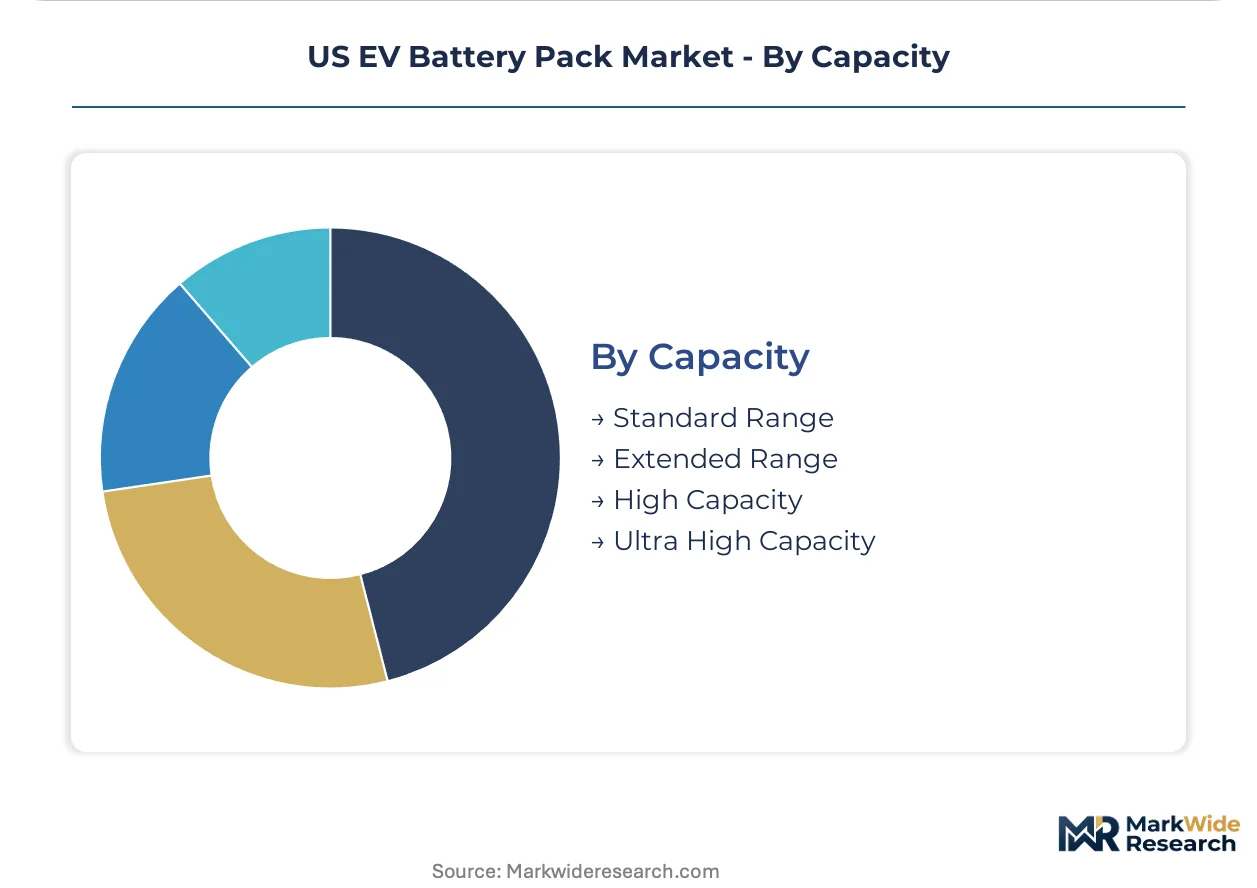
Capacity:
Maturity gradients separate established tiers from emerging ultra-high configurations: standard-range packs face pricing compression from LFP substitutions while ultra-high capacities remain pre-commercial for mass-market penetration.
- Extended Range:75-100 kWh configurations balance upfront cost against route flexibility for commercial duty cycles. Georgia and Tennessee greenfield assembly sites target this tier for southeastern OEM footprints.
- Standard Range:50-75 kWh packs absorb lithium iron phosphate cell substitutions that reduce cobalt dependency and compress bill-of-materials. Thermal management architectures adapt to accommodate LFP voltage profiles.
- High Capacity:100-150 kWh configurations serve premium passenger segments and heavy-duty commercial applications with reinforced enclosure requirements.
- Ultra High Capacity:Prototype 150+ kWh architectures target long-haul electrification with solid-state chemistry dependencies.
Standard Range anchors the volume base while Extended Range shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US EV battery pack market operates with a net import dependency for raw materials while domestic assembly capacity expands. Cathode precursor refining concentrates abroad, yet IRA manufacturing credits accelerate cell-to-pack localization along automotive corridors.
Michigan
The Detroit-to-Lansing corridor anchors North American cell assembly with three operational gigafactories supplying Ford and General Motors. NHTSA maintains its crashworthiness testing facility in East Liberty, Ohio, validating enclosure designs for thermal runaway resistance. The I-94 supplier ecosystem reduces inbound logistics costs for nickel-manganese-cobalt precursor streams.
California
Fleet electrification mandates under the Advanced Clean Trucks regulation compress procurement timelines for extended-range commercial configurations. The California Air Resources Board enforces zero-emission deadlines for drayage and last-mile operators. Bay Area engineering talent pools concentrate battery management system firmware development for Silicon Valley-backed mobility startups.
Texas
Tesla's Austin gigafactory outputs structural battery packs integrating directly into vehicle chassis, eliminating module-level assembly steps. The Texas Commission on Environmental Quality administers air permits for cathode active material processing facilities. Port of Houston access positions the state for graphite anode import qualification under foreign entity screening protocols.
Georgia
SK Innovation's Commerce facility supplies Hyundai Motor Group's Metaplant with cell-to-pack capacity for the southeastern OEM footprint. The Georgia Environmental Protection Division oversees hazardous waste permits for electrolyte blending operations. Savannah port infrastructure handles inbound lithium hydroxide shipments from South American producers.
Tennessee
Volkswagen's Chattanooga assembly plant sources localized pack production from nearby cell facilities under construction by joint venture partners. The Tennessee Department of Environment and Conservation coordinates with EPA on lifecycle emissions tracking for regional manufacturing. Nashville-Davidson County attracts second-life stationary storage startups repurposing retired automotive packs.
US EV Battery Pack Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers anchored by Korean conglomerates, Japanese industrial groups, and emerging domestic specialists. Korean chaebols dominate cathode precursor integration and high-nickel cell chemistry. Japanese incumbents leverage joint venture structures with Detroit automakers. Domestic startups occupy solid-state prototyping and commercial vehicle niche configurations. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players racing to qualify for IRA domestic content thresholds.
Among Korean-based producers, LG Energy Solution Ltd. and SK Innovation Co. Ltd. exemplify the integrated manufacturing archetype, while Panasonic Holdings Corporation anchors the Japanese joint venture model with domestic OEM partners. These three entities represent divergent responses to Treasury foreign entity of concern guidance, with varying degrees of beneficial ownership restructuring.
| Leading Market Players |
|---|
| LG Energy Solution Ltd. |
| Panasonic Holdings Corporation |
| Contemporary Amperex Technology Co. Ltd. (CATL) |
| SK Innovation Co. Ltd. |
| Envision AESC Japan Co. Ltd. |
| Samsung SDI Co. Ltd. |
| A123 Systems LLC |
| QuantumScape Corp. |
| Nikola Corporation |
| Others |
Pricing and Supply Chain Analysis
East Asian graphite anode refiners concentrate upstream supply, anchoring margin capture in cathode active material processing and cell-to-pack assembly tiers where IRA domestic content thresholds now redirect procurement economics.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the US EV battery pack landscape. Price differentiation rests on certification grade—UL 2580 thermal runaway validation commands premiums—and volume scale commitments from fleet operators. Cost compression in standard-range tiers intensifies because lithium iron phosphate cell substitutions erode cobalt-linked pricing premiums. Fleet leasing entities exhibit highest price sensitivity, while premium passenger OEMs absorb elevated pricing for high-nickel cathode configurations.
Supply Chain Analysis
Upstream spodumene concentrate streams from Australia and Chile feed cathode precursor production, while synthetic graphite processing concentrates in China and South Korea. Raw material dependencies span lithium hydroxide, nickel sulfate, and cobalt metal for NMC architectures, with LFP formulations reducing cobalt exposure. Tariff vulnerability runs through graphite anode qualification under Treasury foreign entity screening protocols. Distribution runs through direct cell-to-pack integration at gigafactory clusters, bypassing traditional tiered component distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where IRA domestic content thresholds erect switching costs that cement incumbent positioning through qualified joint venture structures.
For Market Incumbents: Build captive cathode precursor supply as the defensive moat. LG Energy Solution and SK Innovation should accelerate backward integration into nickel sulfate refining in Indonesia and Australia to preempt foreign entity screening disruption. Panasonic Holdings must deepen joint venture exclusivity with Detroit OEMs before Treasury guidance hardens beneficial ownership thresholds. Solid-state R&D pipelines represent the critical lever against silicon-anode cycle-life limitations threatening commercial vehicle penetration. For New Entrants and Emerging Players: Second-life stationary storage repurposing in Texas and Tennessee represents the most penetrable entry point for capital-constrained specialists. Georgia and Southeast manufacturing corridors offer greenfield sites with port access and right-to-work labor frameworks outside incumbent clustering. A direct go-to-market angle through national fleet leasing structures—bypassing OEM integration barriers—enables volume aggregation without platform engineering investments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solid-state prototyping and commercial vehicle thermal management specialization. Long-term viability favors acquisition targets with IRA-qualified manufacturing footprints and firmware talent pools for battery management system development. The signal to watch is Treasury guidance on foreign entity of concern beneficial ownership thresholds, which would force joint venture restructuring and create distressed asset opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Backward Integration | Captive nickel sulfate refining in Australia secures IRA-qualified feedstock certainty for Michigan gigafactory supply. |
| Cell-to-Pack Manufacturing Scale-Up | Greenfield Georgia and Tennessee facilities capture southeastern OEM volume under domestic content thresholds. |
| Solid-State Joint Venture Formation | Toyota-QuantumScape pilot line acceleration targets decade-end automotive qualification with energy density advantages. |
| Second-Life Stationary Storage Channel Development | Retired automotive pack repurposing in Nashville-Davidson County opens circular revenue streams through module reconfiguration. |
| Fleet Leasing Direct Procurement Partnership | Ryder System and Penske Truck Leasing negotiations concentrate commercial volume with customized thermal specifications. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, EPA lifecycle emissions databases, and NHTSA FMVSS 305 validation records. Primary interviews engaged cell production executives at Korean and Japanese manufacturers, procurement leads at Detroit OEMs, and fleet operations directors at national commercial lessors. Secondary validation drew from Department of Treasury IRA guidance documents, state environmental permit filings, and customs trade data for lithium hydroxide and graphite anode flows. Bottom-up cell production capacity modeling triangulated against top-down vehicle production forecasts across the analysis window.
Forecast inputs span battery chemistry adoption curves, IRA credit monetization mechanics, and commercial fleet electrification mandate compliance timelines. Segmentation dimensions include vehicle class, cathode chemistry tier, capacity configuration, and regional production cluster proximity to OEM assembly plants. CAGRs derive from installed capacity ramp schedules, cell cost learning curves, and substitution elasticity between NMC and LFP formulations. Industry-specific inputs incorporate NHTSA crashworthiness certification cycle durations and Treasury foreign entity screening implementation pacing.
Macroeconomic conditions sit as an overlay; deviation in lithium carbonate spot pricing, graphite anode tariff rates, or federal EV incentive continuity would shift the trajectory. Forecasts reflect documented assumptions regarding IRA domestic content threshold enforcement and solid-state chemistry commercialization timelines. Material shifts in Treasury beneficial ownership guidance or NHTSA thermal runaway propagation standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
South America Hybrid Electric Vehicle Battery Market
EV Batteries
Europe Electric Vehicle Solid State Battery Market
EV Batteries
Solar DC Coupled Battery Market
EV Batteries
Europe Electric Vehicle Battery Electrolyte Market
EV Batteries
Traction Battery Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Market
EV Batteries
Electric Vehicle Battery Thermal Management Systems Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
France EV Battery Pack Market
EV Batteries
North America Electric Vehicle Battery Materials Market
EV Batteries
China EV Battery Pack Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
China Electric Vehicle Battery Market
EV Batteries
Europe Electric Vehicle VRLA Batteries Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Electric Vehicle Battery Conditioners Market