
 China Big Data Analytics in Energy Market | 2026-2036
China Big Data Analytics in Energy Market Size, Share, and Industry Trends Forecast 2026-2036
China Big Data Analytics in Energy Market Insights
China's dual carbon goals is broadening the addressable market for emissions-tracking analytics platforms across the national power grid. State Grid Corporation of China leverages proprietary sensor networks to monitor ultra-high voltage transmission corridors spanning twenty-six provinces. Alibaba Cloud competes on public-sector cloud contracts for provincial energy bureaus, while Huawei Cloud anchors infrastructure deployments in state-owned utility data centers.
Big Data Analytics in Energy denotes the computational processing of high-velocity, high-volume datasets generated by generation assets, transmission networks, and consumption endpoints to extract operational intelligence, typically involving time-series ingestion rates exceeding one million data points per second and latency requirements below fifty milliseconds for grid balancing decisions. Its primary purpose centers on optimizing dispatch schedules, predicting equipment failures before thermal or mechanical thresholds breach, and arbitraging spot power prices across regional markets. Predictive Maintenance commands the deepest margin pools due to the catastrophic cost of unplanned outages in coal and nuclear baseload plants, while Demand Forecasting grows fastest as intermittent renewable penetration forces sub-hourly scheduling recalibrations. Cloud Computing underpins nearly all new deployments, though edge-native Machine Learning inference is gaining traction for substation-level automation where backhaul bandwidth constraints persist.
MIIT's GB standards for industrial data security and MEE's emissions monitoring mandates jointly shape procurement specifications, requiring domestic encryption and localized data residency for grid operators. The national carbon trading scheme administered by the Ministry of Ecology and Environment further compels real-time verification of generation-unit emissions intensity, creating compliance-driven demand for auditable analytics pipelines. Stakeholders must monitor how provincial implementation timelines for these standards diverge, as lagging regions may delay platform rollouts while advanced municipalities accelerate toward autonomous grid operations.
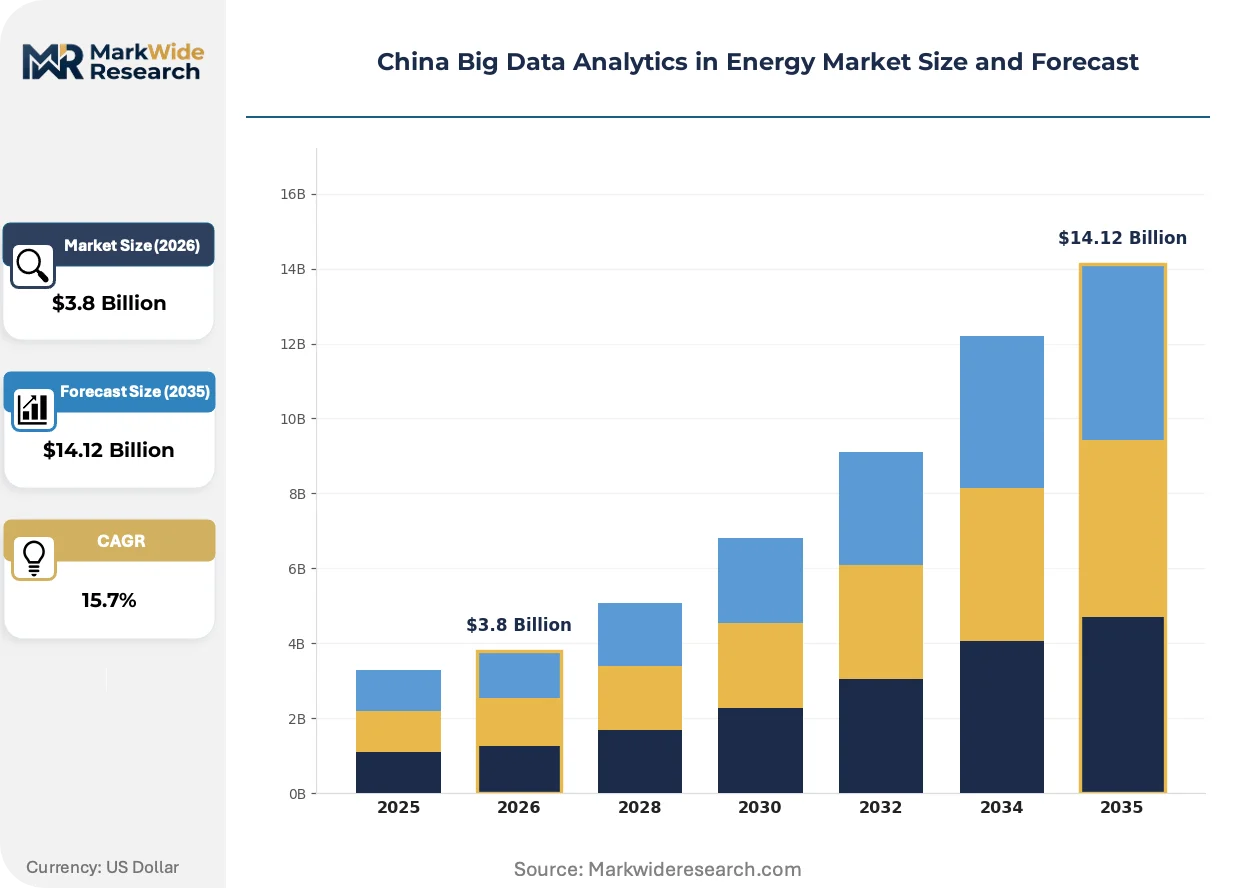
Market Dynamics
MIIT's GB standards for industrial data security and MEE's emissions monitoring mandates are forcing utilities to re-architect legacy data infrastructure around domestic encryption and localized data residency requirements. State Grid Corporation of China and provincial energy bureaus now face procurement specifications that privilege compliant domestic vendors over international platforms.
Growth Catalysts
- Dual carbon goals:MEE's national carbon trading scheme compels real-time emissions verification across generation units, creating compliance-driven demand for auditable analytics pipelines.
- Ultra-high voltage corridors:Predictive analytics deployment across twenty-six provinces generates massive time-series data ingestion requirements exceeding one million points per second.
- Yangtze River Delta clustering:Shanghai and Jiangsu province host China's densest smart grid pilot zones, concentrating demand for sub-fifty-millisecond latency grid balancing systems.
Market Restraints
- Domestic encryption mandates:GB standards require localized data residency that fragments platform architectures and extends integration timelines for multi-province operators.
- Edge bandwidth constraints:Substation-level automation in western provinces faces persistent backhaul limitations that throttle cloud-native machine learning deployments.
- Intermittency forecasting costs:Sub-hourly scheduling recalibrations for wind and solar assets demand computational infrastructure that strains provincial energy bureau budgets.
Strategic Opportunities
- Autonomous grid operations:Advanced municipalities in the Yangtze River Delta are accelerating toward fully automated dispatch systems that eliminate manual intervention.
- Distributed solar optimization:Independent power producers seek demand forecasting models to arbitrage spot power prices across regional markets.
- Edge-native inference:Machine learning deployment at substation level bypasses bandwidth constraints while enabling real-time equipment failure prediction.
Industry Challenges
- Cross-province data governance:Divergent implementation timelines for MIIT security standards create compliance complexity for operators spanning multiple jurisdictions.
- Legacy SCADA integration:Real-time data platforms must interface with decades-old control systems that lack standardized APIs, extending deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Big Data Analytics in Energy Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.12 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Predictive Maintenance, Demand Forecasting, Energy Management, Asset Optimization Technology: Machine Learning, Data Mining, Cloud Computing, Data Visualization End User: Utilities, Oil & Gas Companies, Renewable Energy Firms, Industrial Manufacturers Service Type: Consulting Services, Data Integration, Custom Software Development, Training Services |
| Companies Covered | State Grid Corporation of China, China Southern Power Grid, China National Petroleum Corporation, Envision Energy, Alibaba Cloud, Tencent Cloud, Huawei Cloud, ByteDance Enterprise Solutions, Baidu Cloud, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Big Data Analytics in Energy Market Trends and Innovations
Computational architectures for grid analytics are pivoting from centralized cloud deployments toward distributed edge inference, driven by latency requirements and data sovereignty pressures. Three concurrent developments are restructuring how utilities ingest, process, and act on operational intelligence.
Edge-native machine learning is decentralizing predictive maintenance workflows from regional cloud data centers to individual substations. State Grid Corporation of China deploys tensor processing units at corridor endpoints to enable sub-fifty-millisecond anomaly detection without backhaul dependency. This topology compresses response windows for thermal threshold breaches while satisfying GB standards for data localization.
MEE's emissions monitoring mandates are tightening verification protocols for generation-unit carbon intensity under the national carbon trading scheme. Real-time verification requirements are compelling utilities to deploy continuous emissions monitoring systems with auditable blockchain-anchored data trails. Coal and nuclear baseload plants face the steepest compliance burden as they must demonstrate intensity benchmarks to maintain trading eligibility.
Independent power producers are unbundling analytics procurement from bundled equipment contracts, shifting toward specialized software vendors for demand forecasting and price arbitrage. This fragmentation disrupts traditional state-owned utility procurement hierarchies that previously specified integrated hardware-software packages. Distributed solar and wind asset operators in Jiangsu province demonstrate the most aggressive unbundling behavior as they seek competitive advantage in spot market participation.
China Big Data Analytics in Energy Market Segmentation
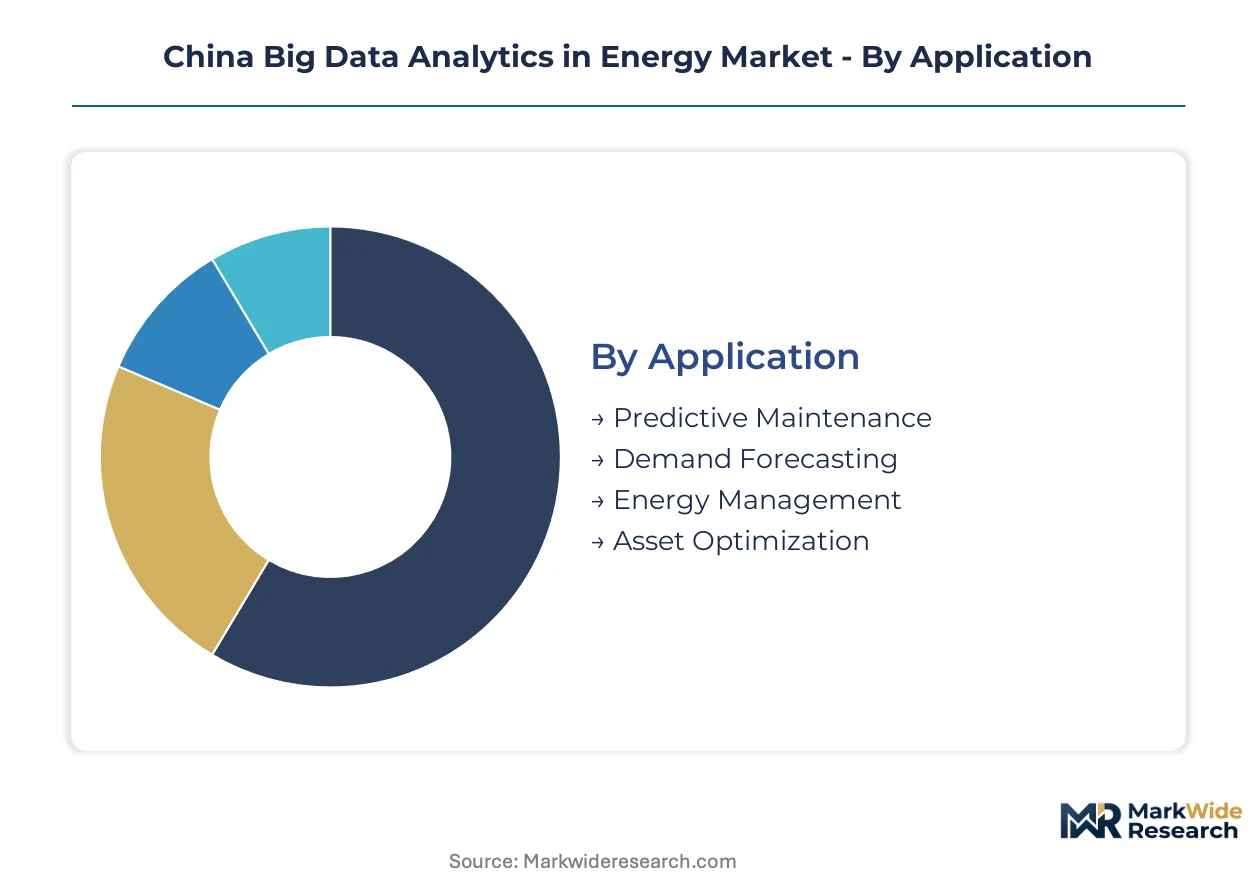
Segmentation reveals how procurement priorities diverge between state-owned grid operators and independent power producers in China's energy analytics market. Technology choices and service models vary sharply by end-user type, with utilities demanding compliant domestic platforms while renewables firms prioritize price arbitrage capabilities.
Application:
Predictive Maintenance commands premium pricing due to catastrophic outage costs, while Demand Forecasting scales fastest through renewable intermittency pressures.
- Predictive Maintenance:Algorithms process thermal and vibration signatures from coal and nuclear baseload plants to flag mechanical degradation before threshold breaches. State Grid Corporation of China deploys these systems across ultra-high voltage corridors spanning twenty-six provinces, driven by the catastrophic cost of unplanned outages in baseload infrastructure.
- Demand Forecasting:Sub-hourly scheduling recalibrations absorb meteorological and consumption data to optimize dispatch against spot market prices. Independent power producers in Jiangsu province adopt these models most aggressively as distributed solar and wind penetration forces continuous generation adjustments.
- Energy Management:Real-time consumption analytics for industrial load centers integrate with carbon accounting platforms under MEE emissions mandates.
- Asset Optimization:Cross-asset performance benchmarking tools help utilities arbitrage generation mix across regional pricing zones.
Today's leader: Predictive Maintenance. Tomorrow's challenger: Demand Forecasting.
Technology:
Cloud Computing dominates new deployments, though edge-native architectures gain share where backhaul constraints persist.
- Cloud Computing:Provincial energy bureaus and State Grid data centers rely on domestic cloud infrastructure for centralized analytics, with Alibaba Cloud and Huawei Cloud anchoring public-sector contracts. MIIT's GB standards for data security and localized residency privilege compliant domestic vendors over international platforms.
- Machine Learning:Tensor processing units at substation endpoints enable sub-fifty-millisecond inference for grid balancing decisions without backhaul dependency. Yangtze River Delta municipalities accelerate toward autonomous operations using these edge-native deployments.
- Data Mining:Pattern extraction from decades of SCADA archives supports legacy system integration for equipment failure prediction.
- Data Visualization:Dashboard layers translate time-series ingestion exceeding one million points per second into actionable dispatch instructions for control room operators.
Cloud Computing anchors current procurement budgets. Machine Learning at the edge shows the steepest expansion trajectory.
End User:
Utilities concentrate spending on compliance-driven platforms, while renewable energy firms chase spot market arbitrage.
- Utilities:State Grid Corporation of China and provincial operators dominate procurement, re-architecting legacy infrastructure around MIIT encryption mandates and MEE emissions verification requirements. Their ultra-high voltage corridors generate massive time-series data ingestion needs.
- Renewable Energy Firms:Distributed solar and wind operators in Shanghai and Jiangsu unbundle analytics from equipment contracts, seeking specialized forecasting vendors for price arbitrage.
- Oil & Gas Companies:Upstream and midstream operators apply predictive models to pipeline integrity monitoring and refinery energy efficiency.
- Industrial Manufacturers:Energy-intensive factories deploy consumption analytics to optimize load profiles against time-of-use pricing and carbon intensity benchmarks.
Utilities lock in multi-year platform commitments. Renewable Energy Firms gain procurement flexibility fastest.
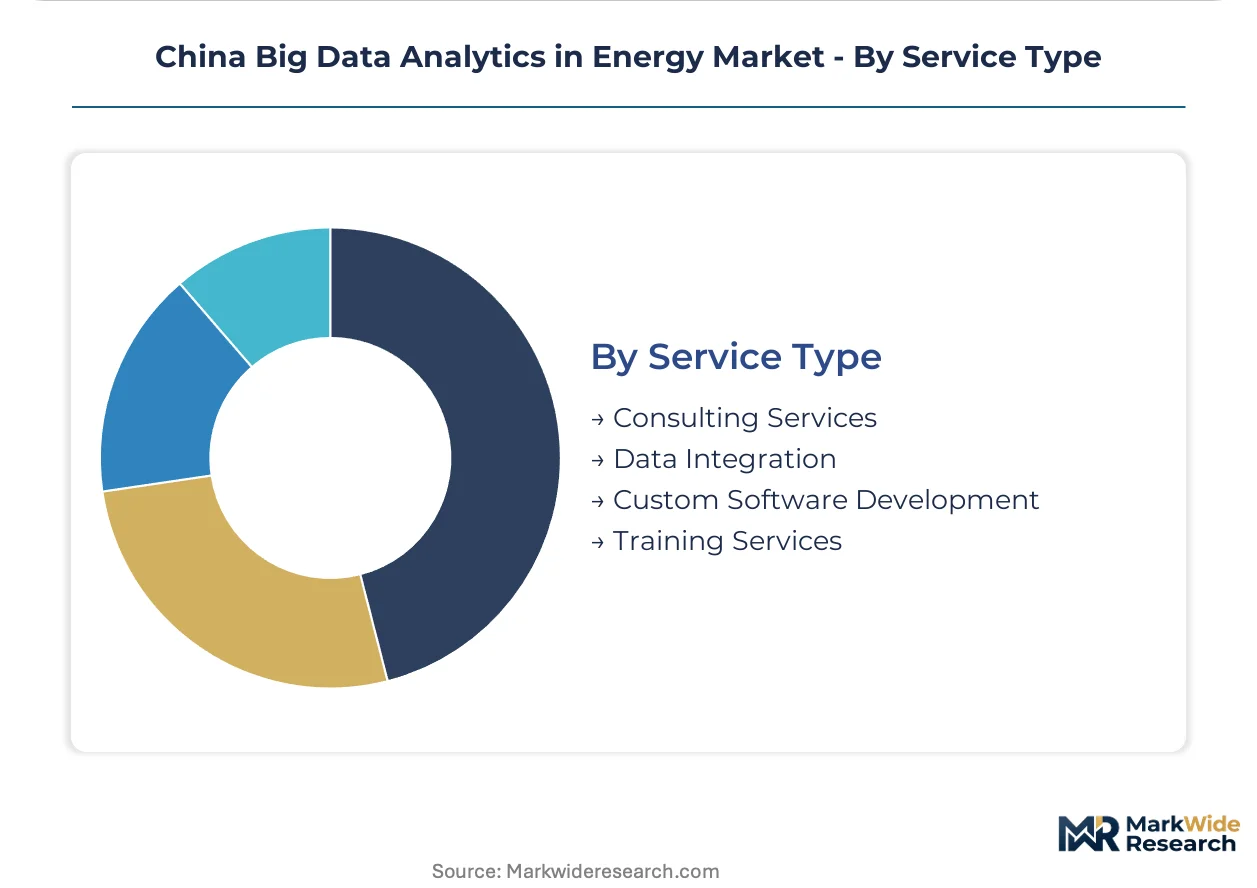
Service Type:
Consulting Services capture upfront transformation budgets, while Data Integration secures recurring revenue through platform complexity.
- Data Integration:Plumbing between legacy SCADA systems and real-time analytics platforms extends deployment cycles due to non-standardized APIs in decades-old control infrastructure. This service type locks in recurring revenue as operators expand across provinces with divergent implementation timelines.
- Consulting Services:Strategy and compliance advisory around MIIT security standards and MEE carbon trading protocols commands premium fees from state-owned utilities. Firms navigate cross-province data governance complexity for multi-jurisdictional operators.
- Custom Software Development:Tailored applications for specific generation assets or regional market rules address gaps in standardized platform offerings.
- Training Services:Capability building for control room staff and data science teams supports autonomous grid operations adoption in advanced municipalities.
Data Integration builds defensive revenue moats. Consulting Services face margin pressure from in-house utility capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data science talent clusters along China's eastern seaboard, concentrating platform development capacity in municipalities with established smart grid infrastructure. Provincial energy bureaus in advanced regions accelerate procurement timelines while western provinces confront bandwidth and compliance gaps.
Yangtze River Delta
Shanghai and Jiangsu province host China's densest smart grid pilot zones, generating sub-fifty-millisecond latency requirements for grid balancing systems. MIIT's GB standards for industrial data security privilege compliant domestic vendors in procurement specifications. State Grid Corporation of China deploys predictive analytics across ultra-high voltage corridors terminating in this cluster.
Pearl River Delta
Guangdong province's manufacturing base drives demand forecasting adoption among independent power producers optimizing distributed solar assets. MEE's emissions monitoring mandates compel real-time verification systems for generation-unit carbon intensity. Shenzhen-based cloud providers anchor infrastructure deployments for provincial energy bureau contracts.
Beijing-Tianjin-Hebei
Northern China's industrial corridor concentrates consulting services around MIIT security standard compliance and MEE carbon trading protocol navigation. The national capital region hosts policy formulation for dual carbon goals implementation. State-owned utility data centers in Beijing prioritize localized data residency architectures.
Sichuan-Chongqing
Western China's hydropower dominance creates unique demand for intermittency forecasting as renewable penetration forces sub-hourly scheduling recalibrations. Edge bandwidth constraints throttle cloud-native machine learning deployments in substation-level automation. Chongqing's industrial energy consumption drives real-time analytics adoption for load profile optimization.
Shandong Peninsula
Shandong province's coal and nuclear baseload infrastructure commands predictive maintenance spending due to catastrophic outage costs. Provincial implementation timelines for MIIT encryption standards lag eastern municipalities, delaying platform rollouts. Qingdao's port industrial zone anchors energy management analytics for carbon accounting integration.
China Big Data Analytics in Energy Market Competitive Landscape
Capital-heavy state-owned grid operators compete with asset-light cloud service providers for analytics procurement contracts across China's energy sector. The vendor structure bifurcates between integrated utility platforms and specialized software vendors unbundling from equipment contracts. Three archetypes dominate: state-owned infrastructure incumbents with proprietary sensor networks, domestic cloud hyperscalers with public-sector compliance credentials, and independent power producer-focused forecasting specialists. Strategic moves center on cross-province data governance navigation and edge-native inference capability acquisition.
Among state-owned infrastructure incumbents, State Grid Corporation of China anchors the utility-tier with ultra-high voltage corridor coverage spanning twenty-six provinces. Domestic cloud hyperscalers occupy the compliance-critical tier, with Alibaba Cloud and Huawei Cloud representing the archetype of vendors privileged by MIIT's localized data residency requirements. These three entities exemplify how procurement specifications favor domestic encryption-compliant platforms over international alternatives.
| Leading Market Players |
|---|
| State Grid Corporation of China |
| China Southern Power Grid |
| China National Petroleum Corporation |
| Envision Energy |
| Alibaba Cloud |
| Tencent Cloud |
| Huawei Cloud |
| ByteDance Enterprise Solutions |
| Baidu Cloud |
| Others |
Pricing and Supply Chain Analysis
Edge-native machine learning deployment at substation endpoints is simultaneously compressing latency economics and fragmenting procurement architectures across China's energy analytics market. This technology shift privileges domestic tensor processing unit vendors while forcing international platform providers to localize data residency compliance, reshaping both cost structures and supplier concentration.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts, with premium tiers commanding fees for sub-fifty-millisecond latency guarantees and MIIT-compliant encryption modules. Price differentiation hinges on certification tier under GB standards and customization depth for legacy SCADA integration. Cost compression in standard tiers is intensifying because provincial energy bureaus consolidate vendor panels. Renewable energy firms in Jiangsu province exhibit the highest price sensitivity, while State Grid Corporation of China shows minimal elasticity for predictive maintenance modules.
Supply Chain Analysis
Tensor processing unit supply rests on domestic semiconductor fabrication capacity concentrated in Shanghai and Hefei, with advanced packaging dependencies drawing from South Korea and Taiwan. Cloud infrastructure hardware sources from domestic server assembly clusters, while specialized sensor networks for ultra-high voltage corridors hinge on State Grid proprietary manufacturing. Single-source vulnerability persists in high-bandwidth memory components for edge inference units. Distribution runs through provincial energy bureau procurement frameworks that privilege compliant domestic vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's Big Data Analytics in Energy Market represents a late-cycle quality story as MIIT's GB standards and MEE emissions mandates shift procurement toward premium-tier compliance specifications. Utilities now prioritize auditable analytics pipelines with localized data residency over cost-optimized alternatives.
For Market Incumbents: Cement dominance in ultra-high voltage corridor analytics by deepening proprietary sensor network coverage across western provinces. Acquire edge-native machine learning specialists to neutralize cloud hyperscaler encroachment into substation-level automation. State Grid Corporation of China's twenty-six-province footprint provides defensive scale against Alibaba Cloud and Huawei Cloud vertical integration moves. For New Entrants and Emerging Players: Independent power producers in Sichuan-Chongqing represent the most penetrable buyer archetype, as hydropower intermittency forecasting demands outstrip incumbent service capacity. Target distributed solar operators in Shandong Peninsula where provincial implementation timelines for MIIT standards lag, creating temporary vendor flexibility. Lead with spot market price arbitrage modules that unbundle from legacy equipment contracts. For Investors and Strategic Acquirers: Roll-up economics work for specialized demand forecasting vendors because renewable penetration fragments procurement across hundreds of distributed solar and wind operators. Five-to-ten-year viability favors asset-light software specialists with proven Jiangsu province deployments over hardware-integrated legacy players. Watch provincial carbon trading scheme participation rates as the inflection signal for compliance-driven analytics spending acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native ML Acquisition | Tensor processing unit deployment at substation level bypasses bandwidth constraints while satisfying MIIT data localization mandates. |
| GB Standards Compliance Certification | Domestic encryption module integration opens provincial energy bureau procurement panels previously closed to international platforms. |
| Carbon Trading Analytics Module Launch | Real-time emissions verification tools capture MEE-mandated spending from coal and nuclear baseload plant operators. |
| Cross-Province Data Integration Partnership | Unified platforms resolve governance complexity for operators spanning multiple jurisdictions with divergent implementation timelines. |
| Autonomous Grid Operations Pilot | Sub-fifty-millisecond latency systems in Yangtze River Delta municipalities establish reference architectures for national rollout. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with utility planning officers, IPP project developers, grid operators, and provincial energy bureau procurement leads with secondary validation. Bottom-up and top-down triangulation anchored projections, drawing from MIIT policy circulars, MEE emissions monitoring protocols, State Grid infrastructure disclosures, and provincial smart grid pilot documentation.
Segment-weighting across application type, technology deployment model, and end-user category structured the analytical framework over the projection horizon. CAGRs derived from time-series modeling of infrastructure investment flows and regulatory compliance spending trajectories. Forecast inputs incorporated ultra-high voltage corridor expansion schedules and renewable capacity addition targets under dual carbon goals.
Underlying measurement precision varies by segment; predictive maintenance and cloud computing carry tighter precision than emerging edge-native machine learning categories. Forecasts reflect documented assumptions around MIIT implementation timeline convergence and MEE carbon trading scheme participation rates. A small set of triggers—provincial encryption standard acceleration, western province bandwidth infrastructure deployment, and spot market liberalization pace—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
Automated Power Generation Dispatch Software Market
Energy Analytics and Software
Canada Big Data Analytics in Energy Market
Energy Analytics and Software
AI in Energy Market
Energy Analytics and Software
Oil Condition Monitoring Market
Energy Analytics and Software
Europe Big Data Analytics in Energy Market
Energy Analytics and Software
Asia-Pacific Big Data Analytics in Energy Market
Energy Analytics and Software
Solar Analyzer Market
Energy Analytics and Software
Carbon and Energy Software Market
Energy Analytics and Software
Digital Energy Platform Market
Energy Analytics and Software
Power System Analysis Software Market
Energy Analytics and Software
Power Monitoring and Control Software Market
Energy Analytics and Software
Utility Analytics and Energy Analytics Market
Energy Analytics and Software
France Big Data Analytics in Energy Market
Energy Analytics and Software
Big Data Analytics in Energy Market
Energy Analytics and Software
Netherlands Big Data Analytics in Energy Market
Energy Analytics and Software
Global Wind Turbine Condition Monitoring System Market