
 Smart Grid Communications Market | 2026-2036
Smart Grid Communications Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Grid Communications Market Insights
Software-defined network management is shifting how vendors monetize smart grid deployments, transforming one-time hardware sales into recurring service relationships. Cisco Systems Inc leverages its enterprise networking heritage to dominate secure IP backhaul for utility substations. Siemens AG anchors European deployments with IEC 61850-compliant industrial ethernet portfolios. ABB Ltd specializes in fiber optic trunk lines that sustain high-availability links between control centers and remote terminal units.
Smart grid communications encompasses the bidirectional data transport layer that connects sensors, meters, and control systems across electrical distribution networks, typically operating over fiber, RF mesh, or power line carrier media with latency requirements below 100 milliseconds for protection signaling. Its primary purpose is enabling real-time visibility into grid state to optimize load flows and integrate variable renewable generation. Fiber optics commands the highest capital commitment per node but captures premium margins from transmission-grade utilities requiring synchronous optical networking resilience. RF Mesh leads in North American AMI deployments where self-healing neighborhood area networks reduce truck rolls for meter connectivity. PLC retains relevance in dense European urban environments where power line infrastructure avoids right-of-way negotiations for new cable burial.
The Federal Energy Regulatory Commission shapes wholesale market participation rules for distributed energy resources, while the EU Green Deal and F-Gas Regulation mandate metering granularity that drives communications endpoint density. IEEE 2030 and IEC 61968 standards create compliance baselines for multi-vendor interoperability that vendors must satisfy for utility procurement eligibility. Stakeholders should monitor how cybersecurity certification requirements from NERC CIP and ETSI evolve as attack surfaces expand with cloud-based deployment models.
Market Dynamics
Software-defined network management is compressing vendor business models from capital-intensive hardware cycles toward recurring service revenues, forcing incumbents to rebuild their go-to-market architectures around subscription-based network orchestration.
Growth Catalysts
- FERC Order 2222:The Federal Energy Regulatory Commission's mandate for distributed energy resource participation in wholesale markets compels utilities to deploy bidirectional metering infrastructure that supports real-time telemetry.
- RF Mesh Networks:Self-healing neighborhood area architectures reduce operational expenditure through automated route optimization and eliminate truck rolls for meter connectivity failures across North American deployments.
- EU Green Deal Digitalization Mandates:Granular metering requirements under the European Union's decarbonization framework drive endpoint density expansion and communications hardware procurement cycles.
Market Restraints
- Fiber Optic Capital Intensity:Synchronous optical networking equipment and trenching costs constrain deployment velocity for transmission-grade utilities seeking sub-50 millisecond protection signaling.
- Power Line Carrier Interference:Electromagnetic noise from distributed solar inverters and electric vehicle chargers degrades signal integrity in dense urban environments where PLC remains entrenched.
- NERC CIP Compliance Burden:North American Electric Reliability Corporation cybersecurity standards impose certification timelines and audit costs that extend procurement cycles for critical cyber assets.
Strategic Opportunities
- Edge Computing Convergence:Integration of containerized applications with field area routers enables localized grid analytics and reduces backhaul bandwidth requirements for distribution automation.
- India Smart Meter National Program:The country's distribution company reform initiative targets 250 million smart meter installations, creating demand for hybrid RF-cellular communications modules.
- Cloud-Native Network Management:SaaS-based orchestration platforms allow smaller municipal utilities to access enterprise-grade visibility without capital investment in on-premises control centers.
Industry Challenges
- Multi-Protocol Integration Complexity:Utilities must bridge IEC 61850, IEEE 2030, and proprietary legacy protocols within single network architectures, requiring specialized systems integration expertise that remains scarce.
- Operational Technology Cybersecurity Skills Gap:The convergence of information technology and operational technology networks demands personnel proficient in both industrial control systems and zero-trust security frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Grid Communications Market |
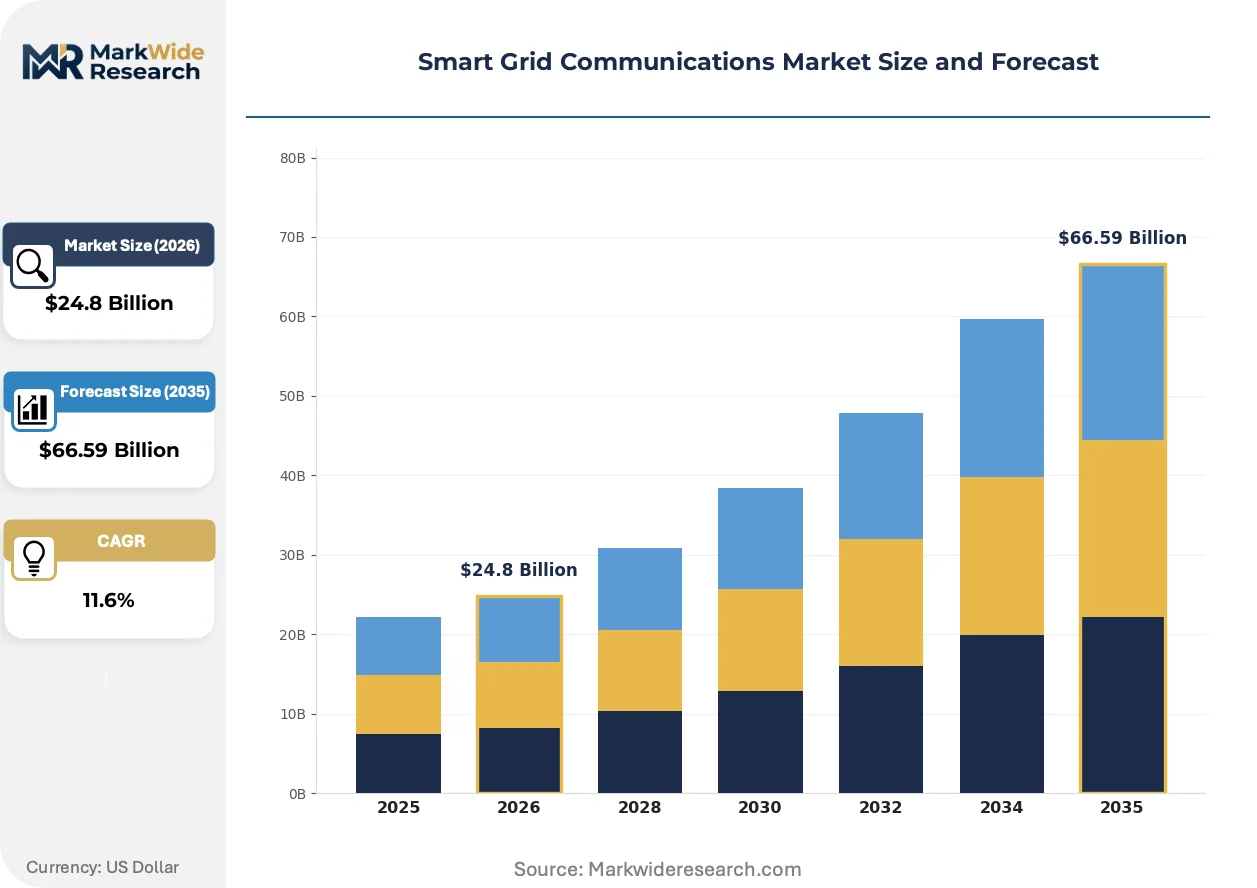
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $66.59 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fiber Optics, RF Mesh, PLC, WiMAX Application: Demand Response, Metering Solutions, Grid Management, Renewable Integration End User: Utilities, Energy Providers, Government Agencies, Industrial Customers Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | ABB Ltd, General Electric Co, Schneider Electric SE, Siemens AG, Cisco Systems Inc, Honeywell International Inc, Eaton Corporation Plc, Fujitsu Ltd, Itron Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Grid Communications Market Trends and Innovations
Network virtualization and edge intelligence are reconfiguring how grid operators architect their communications hierarchies, collapsing traditional layered models into flatter, software-defined topologies that prioritize latency over capital efficiency.
Private 5G networks are consolidating field area communications for distribution automation and mobile workforce applications. Transmission utilities in Germany and Japan are deploying dedicated spectrum slices to replace licensed microwave links. The technology is consolidating multiple legacy radio services into unified platforms that support both protection-grade latency and massive machine-type communications.
The EU AI Act and accompanying cybersecurity certification schemes for critical infrastructure are mandating formal risk management frameworks for automated grid decision systems. European utilities must now document algorithmic transparency and data lineage for load forecasting models that influence network operations. Distribution system operators in France and the Netherlands are restructuring procurement specifications to prioritize vendors with EU Cybersecurity Act certification.
Utility procurement is fragmenting from single-vendor turnkey contracts toward multi-source best-of-breed strategies. Large North American investor-owned utilities are unbundling network hardware, software, and integration services into separate competitive solicitations. This pattern is most visible in California and Texas, where grid operators seek to avoid vendor lock-in while accelerating interoperability testing against IEEE 2030 standards.
Smart Grid Communications Market Segmentation
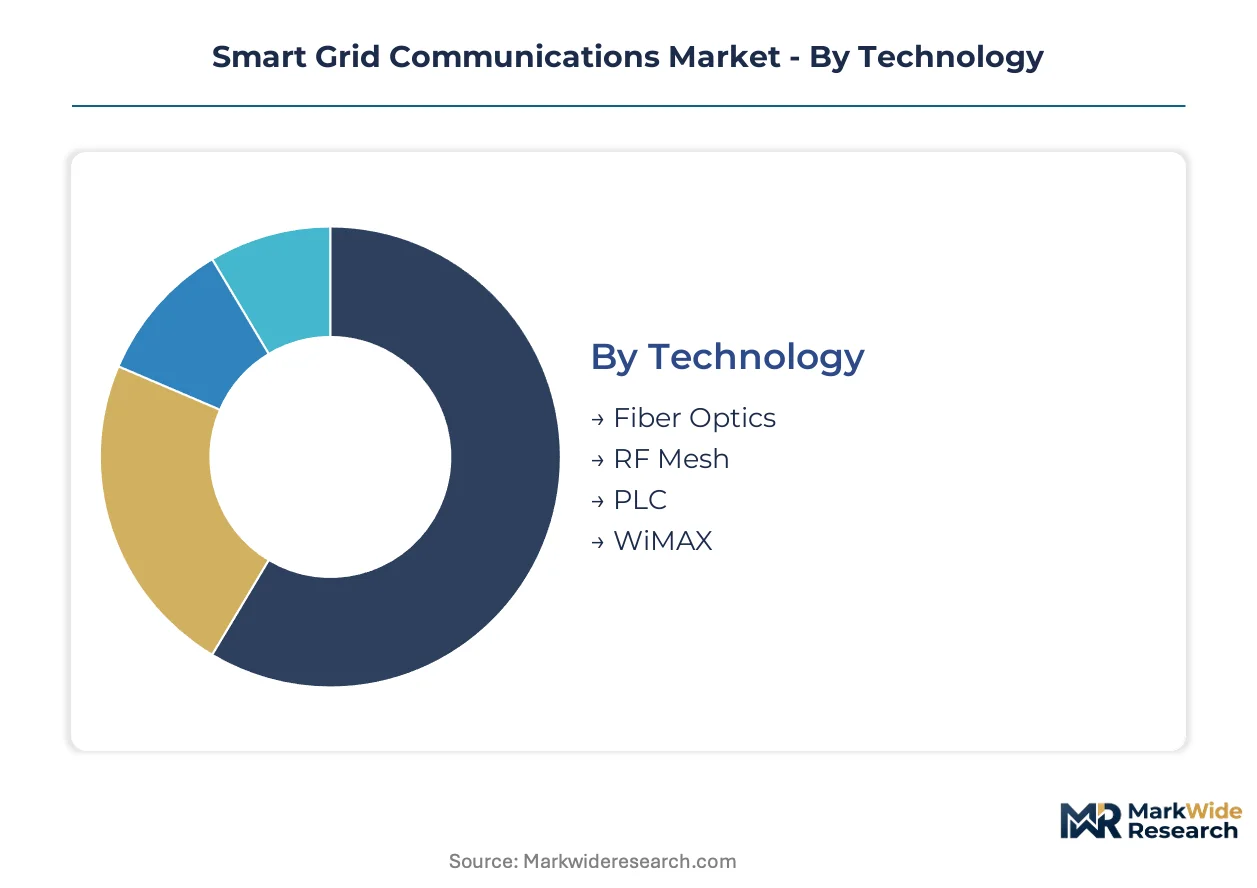
Smart grid communications architectures diverge sharply by latency tolerance, capital availability, and regulatory mandate. Each segment category reflects distinct procurement patterns among transmission utilities, distribution operators, and behind-the-meter aggregators. Understanding these divisions reveals where vendor business models concentrate versus where substitution threats emerge.
Technology:
Fiber optics commands premium pricing for synchronous protection signaling, while RF Mesh dominates volume deployments across North American AMI programs. Volume versus margin splits sharply across these four transport media.
- Fiber Optics:Synchronous optical networking delivers sub-50 millisecond latency for transmission-grade protection relaying. Demand concentrates among German and Japanese utilities deploying dedicated private networks for substation backhaul, driven by NERC CIP and EU Cybersecurity Act certification requirements.
- RF Mesh:Self-healing neighborhood area networks eliminate truck rolls for meter connectivity failures across United States and Canadian deployments. Investor-owned utilities in California and Texas favor this architecture for AMI density, though spectrum congestion in urban cores creates interference management costs.
- PLC:Power line carrier retains relevance in dense European urban environments where right-of-way negotiations for new cable burial prove prohibitive.
- WiMAX:Licensed broadband wireless serves rural distribution automation where fiber trenching costs exceed utility capital budgets.
Today's leader: RF Mesh. Tomorrow's challenger: Fiber Optics.
Application:
Procurement patterns shift from capital-intensive infrastructure toward recurring service revenues as software-defined architectures mature. Application segments reflect this transition in vendor-customer contracting structures.
- Demand Response:FERC Order 2222 compliance requires bidirectional telemetry for distributed energy resource participation in wholesale markets. United States utilities face procurement deadlines for telemetry infrastructure that supports real-time price signals and automated load curtailment.
- Grid Management:Distribution system operators in France and the Netherlands deploy edge-computing field area routers for localized analytics. EU AI Act documentation requirements for algorithmic transparency reshape vendor selection criteria toward certified cybersecurity frameworks.
- Metering Solutions:India's national smart meter program targets 250 million installations, creating demand for hybrid communications modules.
- Renewable Integration:Variable generation forecasting models require sub-100 millisecond state estimation updates.
Grid Management captures the steepest expansion trajectory as distribution automation budgets displace traditional AMI spending.
End User:
Customer type determines procurement sophistication, from municipal utilities with constrained IT staff to federal agencies with mandatory cybersecurity frameworks.
- Utilities:Investor-owned and public power entities constitute the core revenue base, unbundling hardware, software, and integration services into separate competitive solicitations to avoid vendor lock-in.
- Energy Providers:Competitive retail suppliers and distributed energy resource aggregators require communications infrastructure for behind-the-meter telemetry and virtual power plant orchestration.
- Government Agencies:Federal and state entities mandate specific certification timelines under NERC CIP and comparable cybersecurity regimes.
- Industrial Customers:Large manufacturing facilities and data center operators deploy private networks for microgrid islanding and power quality monitoring.
Utilities anchor current procurement volumes. Energy Providers represent the fastest-climbing customer category as aggregation business models proliferate.
Deployment Model:
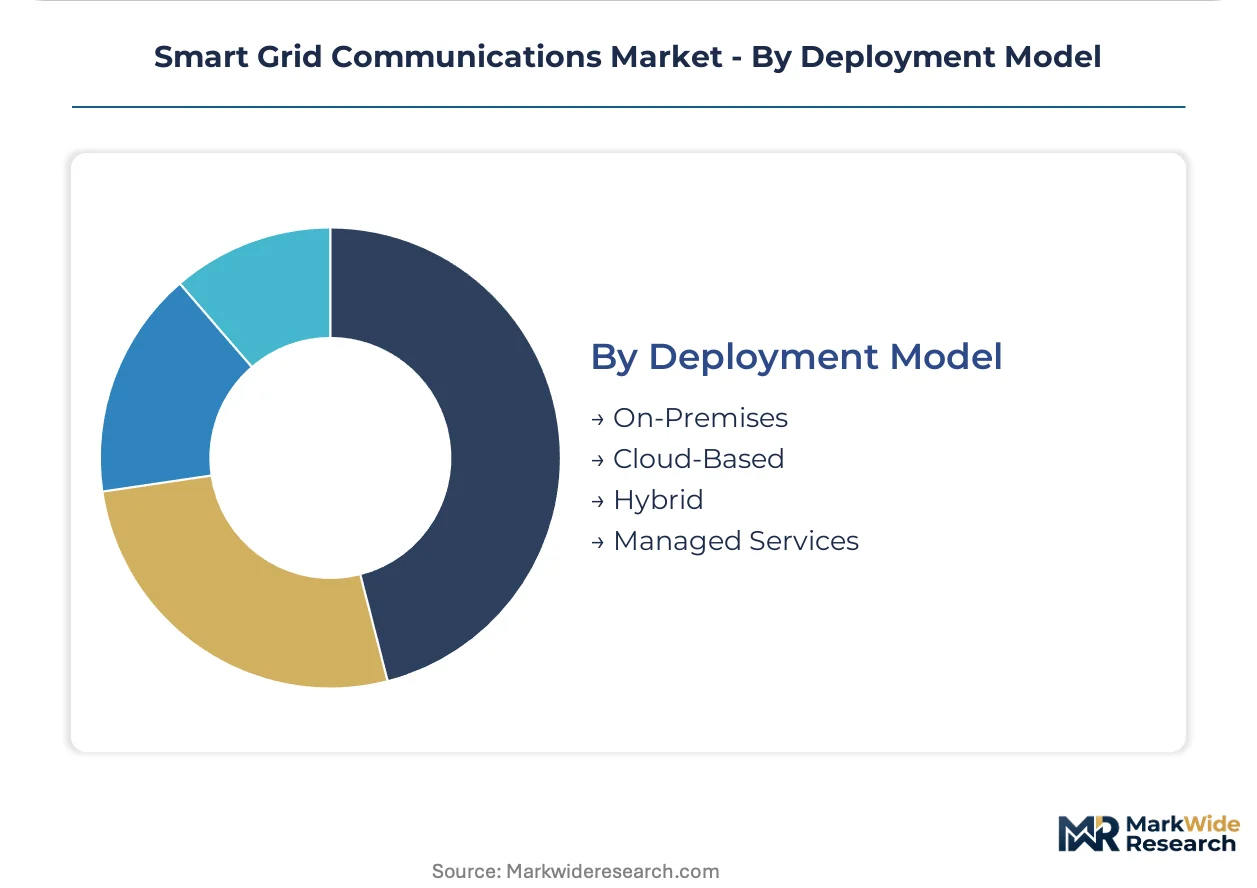
Cloud-native architectures are displacing on-premises control centers among smaller municipal utilities lacking capital for dedicated facilities.
- Cloud-Based:SaaS orchestration platforms deliver enterprise-grade visibility without upfront infrastructure investment. European distribution system operators prioritize EU Cybersecurity Act certified vendors for hosted network management.
- Hybrid:Split architectures retain critical protection signaling on-premises while offloading non-critical analytics to cloud instances. United States utilities favor this model for NERC CIP boundary compliance.
- On-Premises:Traditional control center deployments persist among transmission utilities requiring synchronous optical networking resilience.
- Managed Services:Third-party network operations contracts transfer operational technology cybersecurity risk to specialized vendors.
Hybrid deployments dominate current implementations. Cloud-Based models are gaining share fastest as procurement shifts toward subscription contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys synchronous optical networking for transmission-grade protection signaling, while the United States dominates RF mesh neighborhood area networks for AMI density. China scales fiber-to-the-meter programs under national digitalization mandates. India targets 250 million smart meter installations through its distribution company reform initiative.
United States
Investor-owned utilities in California and Texas unbundle hardware, software, and integration services into separate competitive solicitations to avoid vendor lock-in. FERC Order 2222 compels bidirectional metering infrastructure for distributed energy resource participation in wholesale markets. The Pacific Northwest hosts advanced metering infrastructure deployments where self-healing architectures reduce truck rolls for meter connectivity failures.
Germany
Transmission utilities deploy dedicated private 5G spectrum slices to replace licensed microwave links for protection-grade latency. The EU AI Act mandates formal risk management frameworks for automated grid decision systems requiring algorithmic transparency documentation. Bavaria anchors industrial ethernet portfolio deployments with IEC 61850-compliant substation backhaul networks.
China
State Grid Corporation scales fiber-to-the-meter programs across provincial distribution networks under national smart grid digitalization targets. MIIT standards govern multi-vendor interoperability for communications hardware procurement eligibility. The Yangtze River Delta concentrates manufacturing capacity for hybrid RF-cellular communications modules serving domestic and export demand.
India
The national smart meter program targets 250 million installations, creating procurement waves for communications endpoints across distribution company territories. CEA guidelines mandate metering granularity that drives endpoint density expansion in reform-linked states. Maharashtra and Gujarat lead deployment velocity where distribution companies access results-linked funding for infrastructure modernization.
Japan
METI directs investment toward resilient grid communications supporting renewable integration and disaster recovery requirements. Private 5G networks consolidate field area communications for distribution automation in transmission utility service territories. The Kanto region hosts demonstration projects for edge-computing field area routers enabling localized grid analytics.
Smart Grid Communications Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated industrial conglomerates commanding transmission-grade fiber deployments while focused communications vendors capture AMI volume. The vendor base concentrates around three strategic archetypes: diversified industrial technology groups with substation heritage, enterprise networking specialists pivoting to utility cybersecurity, and meter-centric communications pure-plays. Competitive dynamics center on M&A activity consolidating protocol integration capabilities and strategic partnerships securing cloud-native orchestration platforms.
Within the industrial technology tier, ABB Ltd, Siemens AG, and Schneider Electric SE exemplify divergent geographic anchoring and standardization approaches. ABB occupies a position emphasizing fiber optic trunk line specialization for high-availability control center links. Siemens represents European IEC 61850 compliance leadership across industrial ethernet portfolios. Schneider Electric sits within the integrated power distribution and automation convergence space, reflecting the pattern where diversified conglomerates leverage existing utility relationships against networking specialists.
| Leading Market Players |
|---|
| ABB Ltd |
| General Electric Co |
| Schneider Electric SE |
| Siemens AG |
| Cisco Systems Inc |
| Honeywell International Inc |
| Eaton Corporation Plc |
| Fujitsu Ltd |
| Itron Inc |
| Others |
Pricing and Supply Chain Analysis
Software-defined network management is compressing hardware margins while concentrating procurement power among cloud-native orchestration vendors. This shift simultaneously elevates recurring service revenues and reduces supplier fragmentation as utilities consolidate vendor relationships under subscription frameworks.
Pricing Analysis
Capacity additions in China are reshaping price floors for RF mesh and fiber optic modules as domestic manufacturers scale hybrid communications production. Three-tier pricing structure across premium, standard, and economy levels separates NERC CIP-certified hardware from uncertified alternatives and commodity meter modules. Cost compression in economy-tier PLC equipment is intensifying because electromagnetic interference from distributed solar degrades signal reliability. Municipal utilities in India exhibit highest price sensitivity, while German transmission operators prioritize synchronous optical networking resilience over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Chinese manufacturers of optical transceivers and RF chipsets that feed global smart meter assembly. Component sourcing draws from Malaysia for semiconductor packaging, Japan for precision optical components, and Germany for industrial ethernet controllers. Tariff exposure on Chinese communications hardware threatens cost structures for North American AMI deployments. Distribution runs through utility procurement consortia and systems integrators rather than direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where FERC Order 2222 and EU AI Act certification requirements are shifting procurement toward premium cybersecurity specifications and algorithmic transparency documentation.
For Market Incumbents: Deploy cloud-native orchestration platforms to capture recurring service revenues as utilities abandon capital-intensive control center builds. Backward integration into edge-computing silicon reduces exposure to semiconductor supply constraints. Cisco Systems and Siemens AG already anchor this transition through subscription-based network management offerings that lock in multi-year utility relationships. For New Entrants and Emerging Players: SaaS-based field area router management offers the most penetrable white-space for municipal utilities lacking IT infrastructure capital. Target India's distribution company reform territories where 250 million smart meter installations demand hybrid RF-cellular modules at scale. Partner with European systems integrators holding EU Cybersecurity Act certification to bypass lengthy vendor qualification timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among meter-centric communications pure-plays lacking software-defined networking portfolios. Long-term viability hinges on protocol integration capabilities bridging IEC 61850, IEEE 2030, and proprietary legacy standards. Monitor private 5G spectrum allocation decisions in Germany and Japan as inflection indicators for field area communications consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Network Management Platform | SaaS orchestration captures recurring revenues from municipal utilities avoiding capital expenditure. |
| EU Cybersecurity Act Certification Investment | Certification enables procurement eligibility for French and Dutch distribution system operators. |
| Private 5G Spectrum Deployment | Dedicated spectrum slices replace licensed microwave links for protection-grade latency in Germany. |
| Edge Computing Field Area Router Integration | Containerized applications reduce backhaul bandwidth requirements for distribution automation. |
| Backward Integration into Optical Components | In-house transceiver production mitigates single-source vulnerability from Chinese suppliers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining utility planning officers, AMI program directors, systems integration specialists, and regulatory affairs leads with secondary validation. Primary fieldwork drew from FERC filings, EIA infrastructure databases, EU Green Deal implementation reports, and IEC standardization committee documentation. Bottom-up endpoint enumeration triangulated against top-down utility capital expenditure forecasts to anchor market sizing.
Historical reference periods established baseline deployment velocities for fiber, RF mesh, and power line carrier technologies across the analysis window. Segmentation modeling incorporated technology type, application latency requirements, end-user procurement sophistication, and deployment model architecture. CAGRs derived from utility-reported AMI installation schedules and transmission infrastructure modernization budgets. Forecast inputs included FERC Order 2222 compliance deadlines and EU AI Act certification timelines.
The model assumes a particular technology adoption path; alternative pathways for private 5G field area networks would alter the outlook for RF mesh and fiber optic demand trajectories. Forecasts reflect assumptions about regulatory enforcement consistency and utility capital availability under evolving cybersecurity mandates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Global Smart Grid Security Market
Smart Grid
Microgrid Market
Smart Grid
North America Microgrid Market
Smart Grid
China Smart Power Distribution Systems Market
Smart Grid
Asia-Pacific Demand Response Management Systems Market
Smart Grid
Power Grid Market
Smart Grid
Renewable Energy Integration with Smart Grid Market
Smart Grid
Smart Grid Data Management Market
Smart Grid
Smart Grid Market
Smart Grid
Asia-Pacific Smart Grid Network Market
Smart Grid
Global Self-Healing Grid Market
Smart Grid
China Smart Grid Network Market
Smart Grid
North America Automated Demand Response Management System Market
Smart Grid
Smart Water Grid Market
Smart Grid
United States Smart Grid Security Market
Smart Grid
South Africa Smart Grid Network Market