
 Dosing Units Market | 2026-2036
Dosing Units Market Size, Share, and Industry Trends Forecast 2026-2036
Dosing Units Market Analytics
Aftermarket calibration and validation services is reconfiguring margin pools away from hardware-only transactions in the Dosing Units Market. ProMinent GmbH leverages its German manufacturing base to dominate precision chemical dosing systems for water treatment and pharmaceutical applications. IDEX Corporation sustains a diversified portfolio across life science fluidics and industrial metering through disciplined vertical integration. Grundfos Holding A/S anchors its position via energy-efficient pump architectures that reduce total cost of ownership in high-volume installations.
Dosing units are precision-engineered fluid or solid delivery mechanisms designed to dispense exact quantities of active substances, with specifications typically ranging from microliter accuracy in syringe pumps to milligram precision in capsule dispensers. These systems serve critical functions in pharmaceutical manufacturing, clinical therapeutics, and chemical processing where deviation from target dosage compromises efficacy or safety. Pump-based systems command the largest installed base due to their versatility across liquid formulations and continuous processing workflows. Smart dosing technology represents the fastest-expanding segment as connectivity features enable real-time flow monitoring and closed-loop adjustment in regulated environments. Solid-form dosing equipment retains mature demand profiles in generic oral drug manufacturing where capital replacement cycles dominate purchasing decisions.
FDA validation requirements for 21 CFR Part 11 compliance shape product development priorities for suppliers targeting US pharmaceutical manufacturing. EMA's Annex 1 revision on sterile manufacturing and the EU MDR framework elevate barrier-isolation and single-use dosing system demand across European production facilities. China's NMPA implementation of ICH Q12 lifecycle management guidelines accelerates local substitution toward domestically certified automated dosing platforms. Stakeholders must evaluate regulatory divergence between jurisdictions when configuring platform architectures intended for multi-region deployment.
Market Dynamics
Automated validation protocols are compressing procurement cycles for sterile injectable manufacturers, forcing equipment suppliers to embed 21 CFR Part 11 compliance into base system architectures rather than treating it as a premium add-on.
Growth Catalysts
- FDA 21 CFR Part 11 Mandates:Pharmaceutical manufacturers must deploy electronic batch recording and audit trail capabilities, accelerating replacement of mechanical dosing systems with connected alternatives.
- EMA Annex 1 Revision:Updated sterile manufacturing guidelines require barrier-isolated dosing operations, driving demand for single-use fluid paths and closed-system designs across European facilities.
- Biologics Manufacturing Expansion:Complex protein formulations require microliter-precision delivery systems, pulling advanced syringe pump technology into cell culture and fill-finish workflows.
Market Restraints
- Stainless Steel Input Volatility:Grade 316L price swings compress margins for precision pump housings and valve assemblies, forcing suppliers to absorb cost spikes or risk volume losses.
- German Component Concentration:Precision motor and sensor supply clusters around Stuttgart and Munich create geographic vulnerability to regional logistics disruptions or energy price shocks.
- Mechanical System Longevity:Legacy diaphragm pumps operate 15-20 years with minimal maintenance, extending replacement cycles in cost-constrained generic drug manufacturing.
Strategic Opportunities
- India CDMO Expansion:Contract development and manufacturing organizations in Hyderabad and Bengaluru require validated dosing infrastructure to serve US and EU export markets.
- Cell and Gene Therapy:Personalized medicine production demands ultra-low-volume precision delivery for viral vector manufacturing and patient-specific dosing.
- Digital Twin Integration:Convergence of dosing hardware with process simulation software enables virtual commissioning and predictive maintenance contracts.
Industry Challenges
- Validation Engineer Scarcity:FDA and EMA qualification protocols require specialized expertise that outpaces university training programs and internal development pipelines.
- Legacy System Integration:Brownfield pharmaceutical facilities struggle to retrofit 1990s-era distributed control systems with modern Ethernet-based dosing networks without production shutdowns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dosing Units Market |
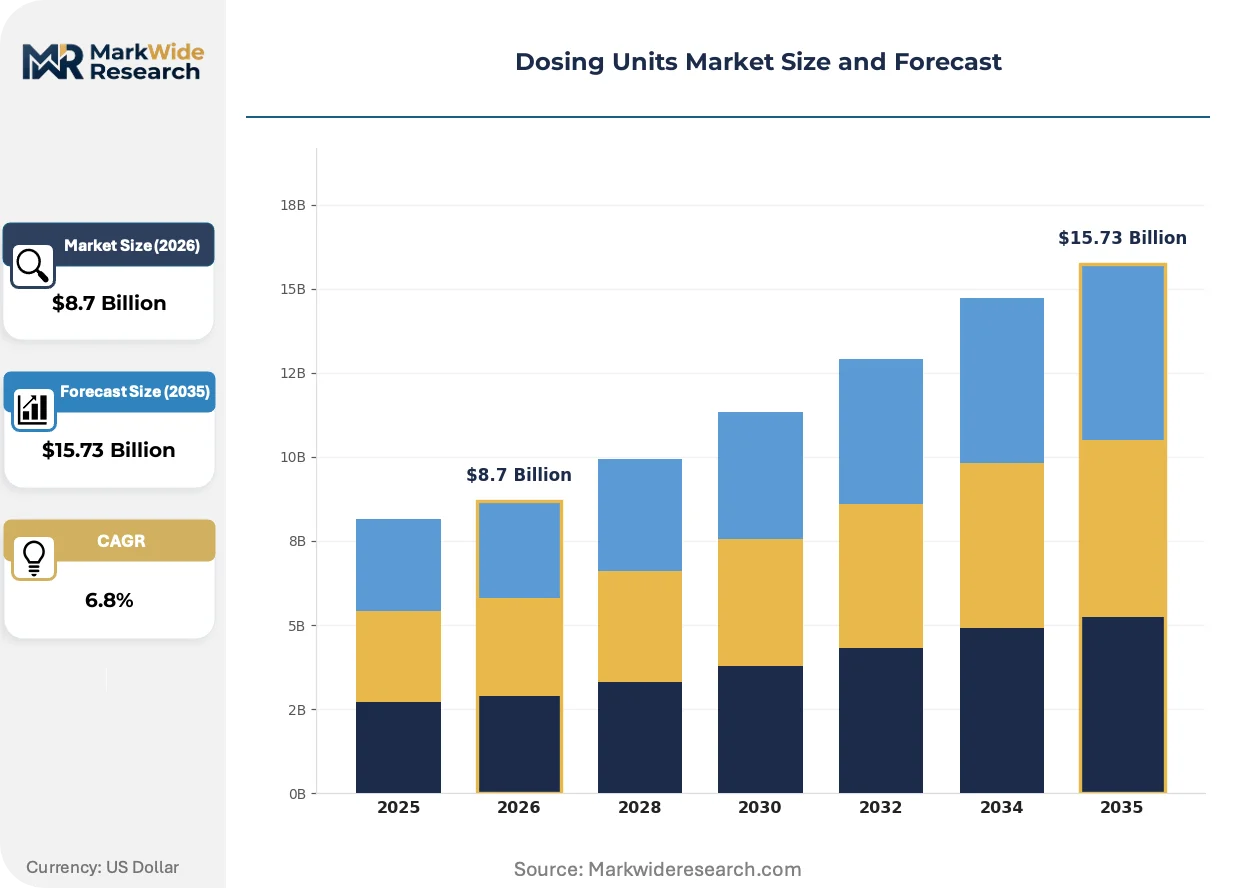
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syringe, Pump, Inhaler, Capsule Form: Liquid, Solid, Gel, Powder End User: Hospitals, Pharmacies, Homecare, Clinics Technology: Smart Dosing, Manual Dosing, Automated Systems, Disposable |
| Companies Covered | ProMinent GmbH, IDEX Corporation, Grundfos Holding A/S, EMEC S.r.l., Netzsch Pumpen & Systeme GmbH, Nikkiso Co. Ltd., Blue-White Industries, SEKO S.P.A., LEWA GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dosing Units Market Evolving Landscape
Connectivity architectures are displacing isolated mechanical systems across regulated manufacturing environments, creating new revenue pools in data services and predictive maintenance rather than hardware alone.
Single-use dosing assemblies are digitizing sterile fluid handling by eliminating cleaning validation requirements and enabling rapid product changeovers. Biologics manufacturers in Massachusetts and North Carolina are deploying these systems at scale for multi-product facilities. This shift is digitizing asset utilization metrics, compressing batch turnover times from days to hours while reducing cross-contamination risk profiles.
EMA's 2022 Annex 1 revision on sterile manufacturing mandates continuous viable and non-viable environmental monitoring, forcing dosing system suppliers to integrate particle counting and microbial detection sensors directly into fluid path designs. European fill-finish operations are responding by specifying barrier-isolated dosing modules with built-in sampling ports and automated environmental monitoring feedback loops.
Service unbundling is fragmenting traditional capital equipment transactions, with pharmaceutical buyers separating hardware procurement from validation, calibration, and maintenance contracts. This pattern concentrates in German and Swiss facilities where total cost of ownership modeling dominates capital allocation decisions, compressing upfront equipment margins while expanding recurring revenue streams for technical service providers.
Dosing Units Market Segmentation
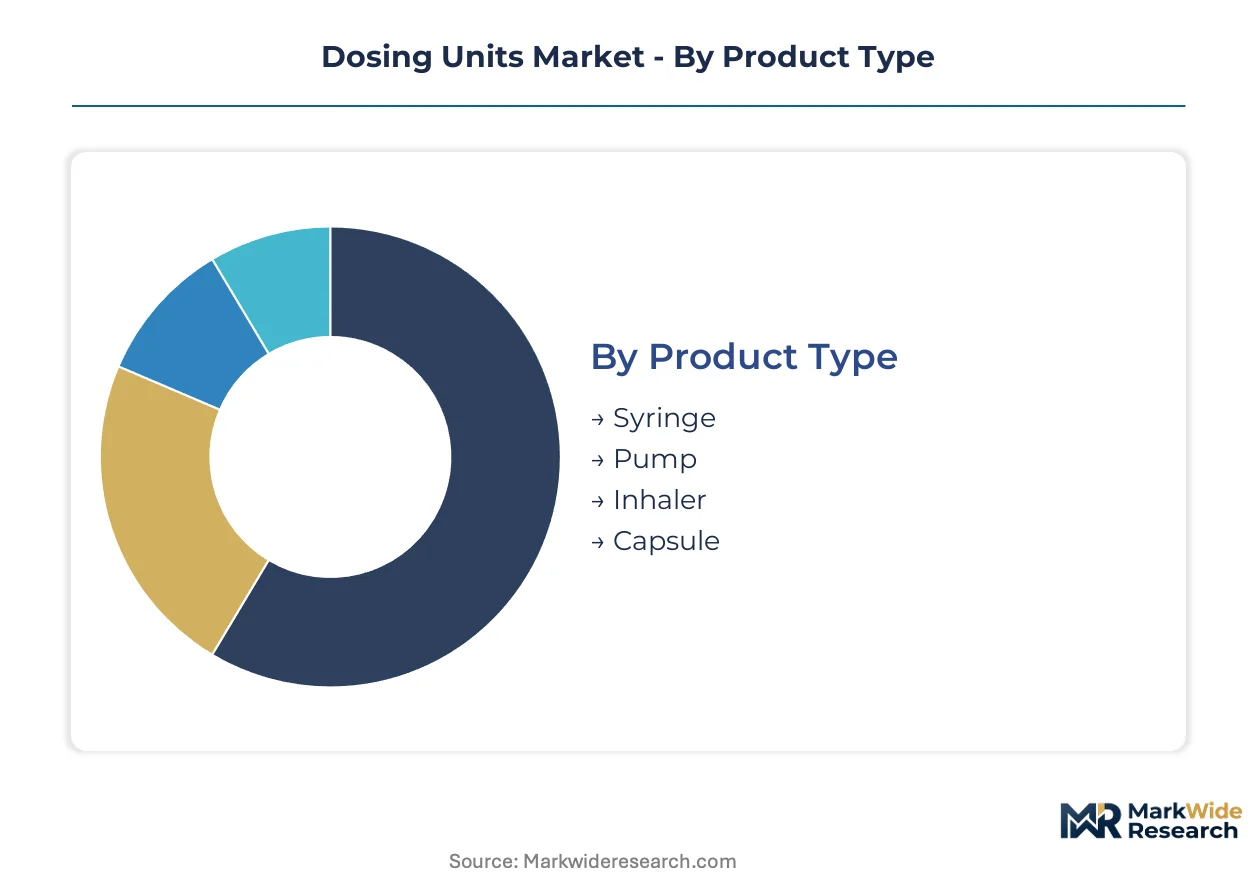
Dosing units fragment across four intersecting dimensions that dictate procurement cycles, validation burdens, and margin structures. Product type and technology choices determine capital intensity, while end-user configuration shapes service attachment rates and regulatory exposure.
Product Type:
Pump systems turn over slowest due to stainless steel construction and 15-20 year service lives, while disposable syringe assemblies cycle fastest through single-use biologics workflows.
- Pump:Reciprocating diaphragm and peristaltic architectures deliver continuous flow control for high-volume sterile manufacturing. Demand concentrates in German pharmaceutical clusters where EMA Annex 1 compliance drives specification of barrier-isolated pump skids with integrated environmental monitoring.
- Syringe:Glass and polymer barrel systems with precision plunger mechanisms enable microliter-accurate bolus delivery for cell therapy and viral vector production. Massachusetts and North Carolina biologics facilities are deploying these at scale for multi-product suites requiring rapid changeover.
- Inhaler:Metered-dose and dry-powder devices deliver pulmonary therapeutics through propellant or breath-actuated mechanisms.
- Capsule:Hard-shell gelatin and HPMC encapsulation systems dispense solid oral doses with milligram precision for generic drug manufacturing.
Pump systems anchor the volume base while syringe configurations gain share at the steepest rate.
Form:
Capital allocation across formulation states tracks the shift from batch oral solids to continuous biologics processing, with liquid and gel forms commanding premium pricing for aseptic handling requirements.
- Liquid:Aqueous and solvent-based formulations requiring sterile filtration and closed-system transfer. Parenteral manufacturers in Switzerland and Germany specify disposable fluid paths to eliminate cleaning validation.
- Solid:Tablet and capsule formulations with established USP dissolution specifications. Indian CDMOs in Hyderabad drive procurement of high-speed capsule dispensers for US and EU export compliance.
- Gel:Semisolid viscous formulations for topical and transdermal delivery with shear-sensitive rheology requirements.
- Powder:Micronized active pharmaceutical ingredients and excipient blends for inhalation and reconstitution applications.
Solid forms dominate current installed capacity while liquid formulations expand most quickly through biologics capacity buildouts.
End User:
Procurement sophistication escalates from homecare price sensitivity through hospital capital committees to pharmaceutical manufacturing validation protocols.
- Hospitals:Inpatient infusion and anesthesia delivery requiring FDA 510(k) cleared devices with drug library safety software. US health systems consolidate purchasing through group purchasing organizations demanding interoperability with electronic health records.
- Pharmacies:Compounding and patient-specific dosing operations subject to USP 797 and 800 sterile handling guidelines.
- Homecare:Patient-operated insulin pens and nebulizers with simplified interfaces and connectivity for remote monitoring.
- Clinics:Outpatient chemotherapy and infusion centers requiring portable pumps with ambulatory mobility features.
Hospital procurement anchors the revenue base while homecare applications climb the fastest as chronic disease management shifts beyond acute facilities.
Technology:
Connectivity premiums compress as 21 CFR Part 11 compliance shifts from optional to baseline, eroding price differentiation between smart and conventional architectures.
- Smart Dosing:Ethernet-connected systems with real-time flow monitoring, automated feedback adjustment, and electronic batch recording. EMA Annex 1 revision mandates environmental sensor integration, forcing European suppliers to embed particle counting and microbial detection.
- Automated Systems:Robotic dispensing and closed-loop control for high-throughput manufacturing with minimal operator intervention.
- Manual Dosing:Mechanical syringes and graduated dispensers for low-volume compounding and research applications.
- Disposable:Single-use fluid path assemblies eliminating cleaning validation and enabling rapid product changeovers in multi-suite biologics facilities.
Automated systems retain the largest installed base while smart dosing platforms gain share at the steepest rate through regulatory mandate penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. German pharmaceutical buyers absorb 30-40% hardware premiums for validated systems, while Indian CDMOs prioritize total cost of ownership with compressed service attach rates.
United States
FDA 21 CFR Part 11 mandates electronic batch recording for sterile injectable manufacturers. Massachusetts and North Carolina biologics clusters drive syringe pump procurement for cell therapy workflows. Disposable fluid path adoption accelerates in multi-product facilities around Boston.
Germany
EMA Annex 1 revision on barrier-isolated manufacturing elevates single-use dosing specifications. Stuttgart and Munich precision motor clusters supply sensor-integrated pump architectures. ProMinent GmbH and LEWA GmbH anchor fluid handling engineering concentrated in Baden-Württemberg and Bavaria.
India
CDMO expansion in Hyderabad and Bengaluru requires validated dosing infrastructure for US and EU export compliance. CDSCO implementation of ICH Q12 lifecycle management guidelines accelerates domestic platform certification. Generic drug manufacturers in Gujarat and Maharashtra extend replacement cycles for legacy diaphragm systems.
China
NMPA adoption of ICH Q12 standards drives substitution toward domestically certified automated platforms. Yangtze River Delta pharmaceutical manufacturers deploy smart dosing with environmental sensor integration. Local suppliers capture share in standard pump segments while import dependence persists in microliter-precision applications.
Switzerland
Swissmedic requirements for sterile manufacturing elevate barrier-isolation specifications in Basel and Zurich pharmaceutical clusters. Precision pump procurement concentrates in contract manufacturing facilities serving global biologics sponsors. Service unbundling patterns separate hardware from validation contracts in total cost of ownership modeling.
Dosing Units Market Competitive Landscape
Capability concentration sits with precision engineering specialists; scale advantage sits with diversified industrial conglomerates. The market structures around three tiers: German precision fluid handling houses, diversified pump manufacturers with pharmaceutical verticals, and regional specialists serving water treatment and chemical processing. Consolidation pressure operates through validation service bundling rather than pure hardware scale. Geographic expansion and strategic partnerships constitute the dominant competitive vectors as regulatory divergence fragments platform architectures.
Within the German precision engineering tier, ProMinent GmbH and LEWA GmbH occupy positions exemplifying barrier-isolated system integration for EMA-compliant manufacturing. IDEX Corporation represents the diversified conglomerate archetype with life science fluidics exposure across multiple end markets. SEKO S.P.A. anchors Italian dosing specialization serving water treatment and industrial chemical applications. These three entities illustrate the competitive spectrum from focused engineering depth to portfolio breadth.
| Leading Market Players |
|---|
| ProMinent GmbH |
| IDEX Corporation |
| Grundfos Holding A/S |
| EMEC S.r.l. |
| Netzsch Pumpen & Systeme GmbH |
| Nikkiso Co. Ltd. |
| Blue-White Industries |
| SEKO S.P.A. |
| LEWA GmbH |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor's energy cost volatility transmits directly into dosing unit landed costs, amplifying price spreads between German-engineered precision systems and Asian-standard alternatives while compressing margins for mid-tier suppliers without captive service revenue.
Pricing Analysis
Aftermarket calibration contracts and validation service bundles now generate the majority of lifetime customer value, shifting supplier economics from hardware margins to recurring revenue streams. Pricing stratifies across FDA-validated premium tiers, CE-marked standard configurations, and non-certified economy units for water treatment applications. Cost compression in the mid-tier is intensifying because stainless steel input volatility forces suppliers to absorb price spikes or sacrifice volume. Generic drug manufacturers in India exhibit the highest price sensitivity, while Swiss biologics sponsors absorb substantial premiums for single-use barrier-isolated systems.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for European pharmaceutical OEMs, squeezing working capital for component suppliers. Precision motor and sensor production concentrates in Germany, Switzerland, and Japan, with Grade 316L stainless steel sourcing anchored in Chinese and Indian mills. Single-source vulnerability sits with Stuttgart-area sensor clusters serving EMA-compliant pump architectures. Distribution runs through authorized system integrators in regulated markets and direct OEM relationships in water treatment segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dosing units market sits in early-cycle expansion as FDA and EMA validation mandates force replacement of mechanical systems with connected alternatives, creating sustained procurement tailwinds through the forecast window.
For Market Incumbents: Pre-empt emerging Indian and Chinese dosing platform competitors by embedding 21 CFR Part 11 compliance as baseline architecture rather than premium tiering. Deepen backward integration into precision sensor production to insulate margins from Stuttgart supply cluster disruptions. Capture validation engineer scarcity through captive training pipelines and university partnerships.
For New Entrants and Emerging Players: Southeast Asian CDMO corridors in Singapore and Thailand offer underpenetrated demand for validated single-use dosing assemblies serving US and EU export markets. Target cell and gene therapy viral vector manufacturing with ultra-low-volume precision delivery systems. Establish beachheads through validation service partnerships rather than direct hardware competition.
For Investors and Strategic Acquirers: Regional specialists with EMA Annex 1 compliance capabilities and installed bases in Swiss and German biologics clusters represent attractive consolidation targets. Long-term viability hinges on recurring service revenue attachment rather than hardware transaction cycles. Watch for inflection when CDSCO and NMPA accelerate domestic substitution timelines in India and China.
| Strategic Initiative | Industry Significance |
|---|---|
| Validation Service Bundling | Captures recurring revenue from FDA 21 CFR Part 11 compliance mandates in sterile manufacturing. |
| Single-Use Fluid Path Expansion | Eliminates cleaning validation burdens for EMA Annex 1 barrier-isolated biologics production. |
| Precision Sensor Backward Integration | Reduces exposure to Stuttgart motor cluster supply disruptions and energy cost volatility. |
| Digital Twin Platform Development | Enables predictive maintenance contracts and virtual commissioning for pharmaceutical OEMs. |
| India CDMO Infrastructure Partnership | Positions suppliers for CDSCO ICH Q12 certification requirements in Hyderabad and Bengaluru. |
Research Methodology
A spread of perspectives from pharmaceutical manufacturing engineers, validation specialists, GPO procurement managers, and aftermarket service directors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation across FDA 510(k) filings, EMA submission databases, CDSCO regulatory notices, and SEC equipment supplier disclosures. Bottom-up demand modeling from end-user procurement cycles triangulated against top-down supply capacity assessments.
Demand-supply balance dynamics anchored the forecast framework, with segmentation across product type, technology tier, end-user configuration, and regional regulatory cluster modeled throughout the projection horizon. CAGRs derived from weighted average replacement cycles, capacity expansion announcements, and validation protocol adoption curves. Industry-specific inputs included biologics manufacturing buildouts, stainless steel price indices, and precision component lead time surveys.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified industrial conglomerates would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Fluorescence-Guided Surgery Systems Market
Medical Devices
Facial Pumps Market
Medical Devices
Brazil Aesthetic Equipment Market
Medical Devices
Phoropters Market
Medical Devices
Intracranial Pressure (ICP) Monitoring Devices Market
Medical Devices
EMG Biosensors Market
Medical Devices
Global Retinoscopes Market
Medical Devices
Global 3D Printed Surgical Models Market
Medical Devices
Global Acetabular Prostheses Market
Medical Devices
Digital Ureteroscopes Market
Medical Devices
Arthroscopy Devices Market
Medical Devices
Digital Stethoscope Market
Medical Devices
Lactate Meter Market
Medical Devices
Anti-Fatigue Lenses Market
Medical Devices
Global Intragastric Balloon Market
Medical Devices
Global Oxygen Cylinders and Concentrators Market