
 Slovakia Home Appliances Market | 2026-2036
Slovakia Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Slovakia Home Appliances Market Insights
Connected appliance ecosystems and AI-driven energy optimization is rewriting how manufacturers engineer product portfolios for Central European households. BSH Hausgeräte GmbH leverages its embedded manufacturing footprint in the region to sustain competitive lead times for built-in oven and dishwasher lines. Gorenje anchors its position through specialized design-led refrigeration that commands premium placement in Slovak retail channels. Hisense Group Co., Ltd. competes aggressively on cost-engineered washing machine platforms distributed through hypermarket networks.
Slovakia home appliances encompass electrically powered machines designed for domestic tasks such as food preservation, fabric cleaning, and meal preparation, typically operating at 230V/50Hz with energy efficiency ratings scaled from A to G under EU labeling frameworks. Their primary commercial purpose centers on reducing household labor time while minimizing electricity and water consumption against rising utility tariffs. Refrigerators occupy the largest value share among product types as replacement cycles shorten for units failing tightened EU Ecodesign minimums, while smart appliances represent the fastest-expanding technology tier as Wi-Fi-enabled remote diagnostics gain traction among younger buyers in urban centers. Energy-efficient models command superior margin pools due to qualification for national green subsidy schemes tied to building renovation programs.
The EU Ecodesign Directive and Energy Labeling Regulation, enforced through Slovakia's national market surveillance authority, mandate progressively stricter efficiency thresholds that disqualify lower-grade imports from non-compliant manufacturers. CE marking requirements under the EU's Low Voltage Directive and EMC standards govern electrical safety and electromagnetic compatibility for all appliances sold within Slovak territory. Stakeholders must monitor how Brussels' forthcoming right-to-repair mandates alter spare parts availability obligations and warranty term structures across the value chain.
Market Dynamics
EU Ecodesign Directive transposition is compressing replacement cycles for cooling appliances while Wi-Fi-enabled diagnostics reshape manufacturer service models across Slovak households. Bratislava's renovation boom concentrates demand for built-in kitchen suites, creating geographic polarization in premium product uptake.
Growth Catalysts
- National green subsidy schemes:Energy-efficient models qualify for building renovation program incentives, accelerating trade-ins of pre-2021 refrigeration units in Bratislava and Košice districts.
- Connected appliance ecosystems:AI-driven energy optimization platforms reduce household electricity bills against rising utility tariffs, appealing to younger buyers in urban centers.
- Tightened EU Ecodesign minimums:Cooling appliances failing updated efficiency thresholds face automatic disqualification from Slovak retail channels, forcing inventory turnover.
Market Restraints
- Import compliance costs:CE marking under the Low Voltage Directive and EMC standards adds certification overhead for Asian manufacturers targeting Slovak hypermarket networks.
- Spare parts availability mandates:Brussels' forthcoming right-to-repair regulations will extend warranty obligations and inventory carrying costs across distributor balance sheets.
- Disposable income concentration:Demand clusters disproportionately in Bratislava region, leaving eastern districts with thinner addressable markets for premium built-in lines.
Strategic Opportunities
- Underpenetrated eastern districts:Košice and Prešov regions show lagging smart appliance penetration relative to EU averages, offering first-mover positioning for Wi-Fi-enabled platforms.
- Hypermarket channel digitization:Click-and-collect integration with in-store diagnostics creates new touchpoints for cost-engineered washing machine sales outside capital region.
- Building renovation program alignment:National subsidies tied to residential energy efficiency upgrades create bundled sales opportunities for kitchen suite replacements.
Industry Challenges
- Service technician certification gaps:Connected appliance diagnostics require software competency that legacy repair networks in smaller Slovak cities lack.
- Dual inventory management:Retailers must stock parallel SKUs for pre- and post-Ecodesign efficiency tiers during regulatory transition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slovakia Home Appliances Market |
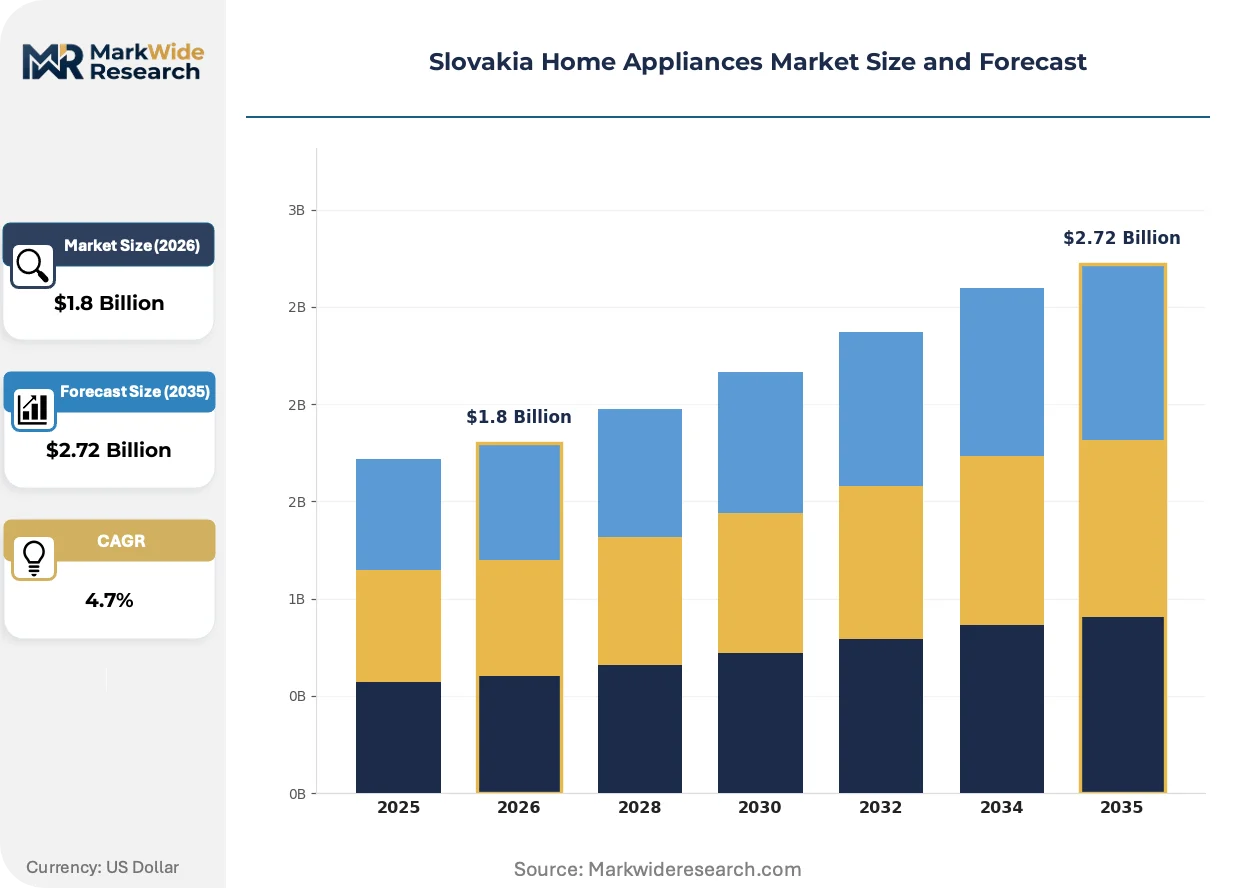
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Ovens, Dishwashers End User: Residential, Commercial, Hospitality, Retail Technology: Smart Appliances, Energy-Efficient, Conventional, Hybrid Distribution Channel: Online, Retail Stores, Direct Sales, Distributors |
| Companies Covered | Electrolux AB, BSH Hausgeräte GmbH, Whirlpool Corporation, Hisense Group Co., Ltd., Samsung Electronics Co., Ltd., Gorenje, Bosch, Siemens, LG Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slovakia Home Appliances Market Trends and Innovations
Smart diagnostics and predictive maintenance capabilities are redefining manufacturer-customer relationships in Central European home appliances. Three forces are compressing traditional ownership and service models.
Wi-Fi-enabled remote diagnostics is rendering obsolete the break-then-repair service paradigm for Slovak households. Younger buyers in Bratislava urban districts adopt predictive maintenance subscriptions at accelerating rates. This technology is compressing warranty claim resolution timelines from weeks to hours while shifting margin pools toward software-enabled service contracts.
EU Ecodesign Directive enforcement through Slovakia's national market surveillance authority tightens minimum efficiency thresholds for imported cooling appliances annually. Non-compliant manufacturers face automatic retail channel exclusion, forcing portfolio rationalization. Refrigeration lines bearing A-grade labels command shelf priority in Bratislava's premium kitchen showrooms while lower-tier imports retreat to secondary markets.
Buyer concentration in renovation-driven purchasing is displacing episodic replacement patterns across Slovak residential districts. Bratislava's building upgrade wave consolidates kitchen suite decisions into single project timelines, shortening vendor evaluation windows. This behavioral shift concentrates annual demand into Q2-Q3 construction seasons, pressuring manufacturer inventory positioning and installer capacity allocation.
Slovakia Home Appliances Market Segmentation
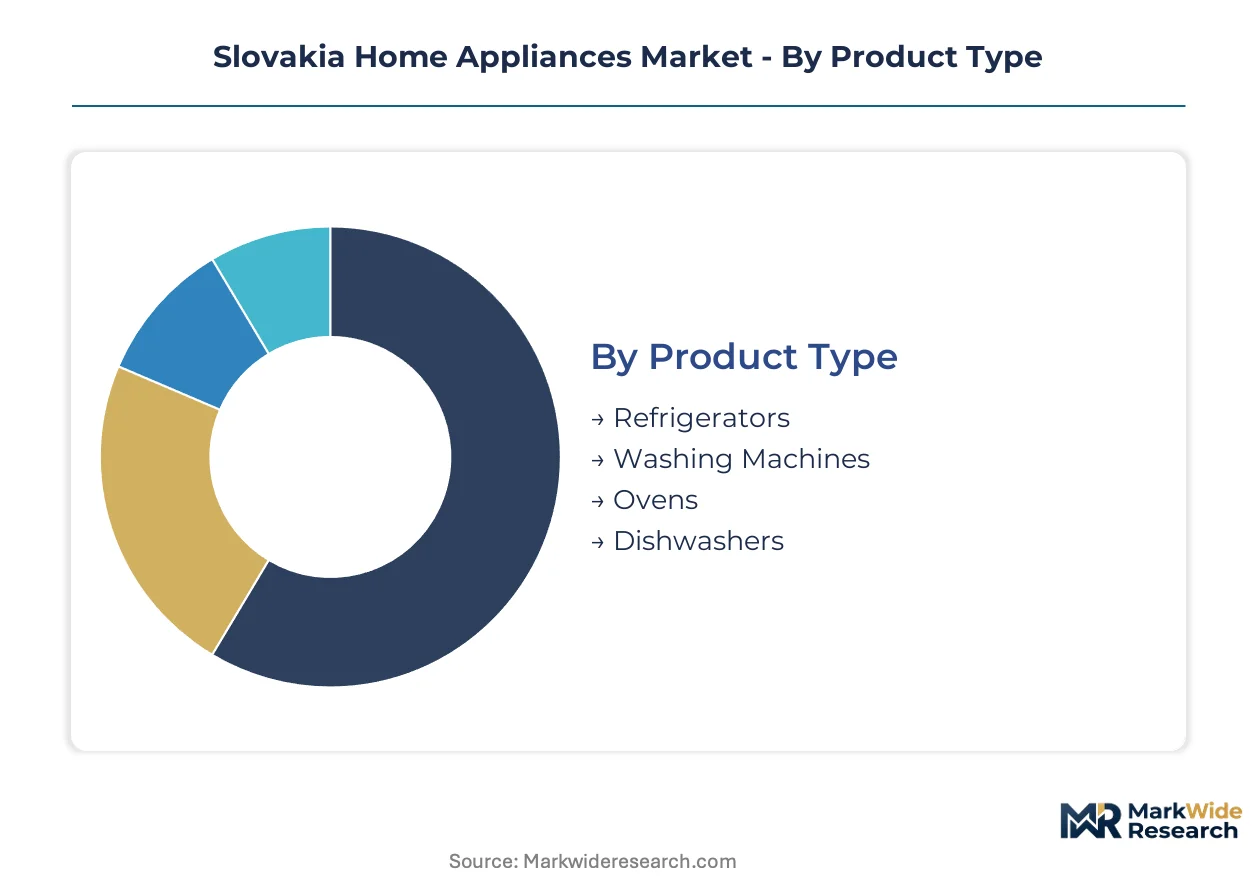
Slovakia's home appliances market fragments across four distinct dimensions that shape procurement patterns and margin structures. Product type alignment with EU Ecodesign tiers, end-user renovation cycles, technology adoption curves, and channel digitization maturity each create separate competitive battlegrounds for manufacturers and retailers.
Product Type:
Cost tier stratification across product categories determines which SKUs qualify for national green subsidy schemes and premium kitchen showroom placement.
- Refrigerators:Cooling appliances dominate value capture as replacement cycles compress under tightened EU Ecodesign minimums. Bratislava's building renovation wave concentrates demand for A-grade labeled units that secure subsidy eligibility and shelf priority in premium channels.
- Washing Machines:Fabric cleaning equipment spans cost-engineered platforms for hypermarket distribution and connected models with AI-driven load optimization. Košice and Prešov districts show lagging smart penetration relative to EU averages, creating first-mover positioning for Wi-Fi-enabled lines.
- Ovens:Built-in cooking appliances ride Bratislava's residential upgrade boom, with installer capacity constraining Q2-Q3 seasonal demand spikes.
- Dishwashers:Automated dish cleaning units align with kitchen suite bundling trends in renovation-driven purchasing decisions.
Refrigerators command the established base. The steepest expansion runs through washing machines.
End User:
Application context determines specification requirements, with residential renovation timelines and commercial procurement cycles operating on fundamentally different rhythms.
- Residential:Household buyers consolidate kitchen suite decisions into single project timelines during building upgrades, compressing vendor evaluation windows and concentrating annual demand into construction seasons.
- Commercial:Business purchasers prioritize total cost of ownership calculations against rising utility tariffs, driving specification of energy-efficient models with predictive maintenance capabilities.
- Hospitality:Hotel and restaurant operators demand durability-rated equipment with rapid spare parts availability to minimize operational downtime.
- Retail:Reseller procurement focuses on inventory turnover velocity and margin protection through parallel SKU management across pre- and post-Ecodesign efficiency tiers.
Residential buyers anchor volume. Hospitality applications are climbing the fastest as tourism infrastructure expands.
Technology:
Maturity gradients across technology tiers separate legacy replacement demand from upgrade-driven premium capture.
- Smart Appliances:Wi-Fi-enabled remote diagnostics platforms reduce warranty claim resolution timelines from weeks to hours. Younger buyers in Bratislava urban districts adopt predictive maintenance subscriptions at accelerating rates, shifting margin pools toward software-enabled service contracts.
- Energy-Efficient:A-grade labeled models qualify for national green subsidy schemes tied to building renovation programs, creating bundled sales opportunities and superior margin pools.
- Conventional:Non-connected, standard-efficiency equipment retains presence in eastern districts where disposable income concentration thins addressable markets for premium lines.
- Hybrid:Mixed-technology platforms bridge connectivity gaps with partial automation features at mid-tier price points.
Energy-efficient models command the established base. Smart appliances show the steepest expansion trajectory as remote diagnostics gain traction.
Distribution Channel:
Channel digitization maturity creates geographic polarization in customer touchpoint effectiveness.
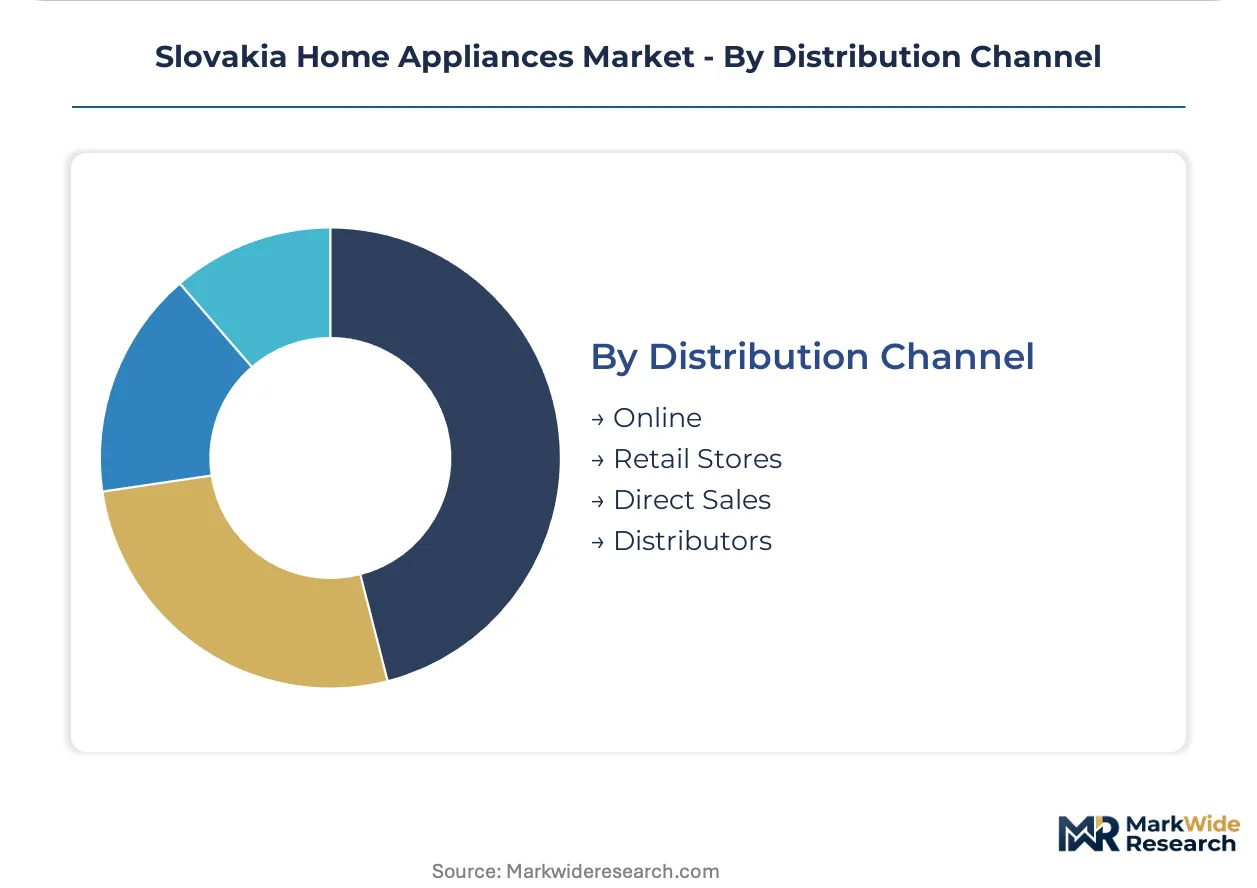
- Online:Digital commerce platforms capture growing share among younger demographics in urban centers, with click-and-collect integration reducing delivery friction.
- Retail Stores:Physical showrooms dominate premium built-in kitchen suite transactions, particularly in Bratislava where tactile evaluation drives high-consideration purchases.
- Direct Sales:Manufacturer-controlled channels bypass distributor margins for large-volume commercial and hospitality contracts.
- Distributors:Wholesale networks extend reach into underpenetrated eastern districts where hypermarket density remains limited.
Retail stores command the established base. Online channels are expanding most quickly through click-and-collect integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Czech manufacturing corridors supply Slovakia's appliance trade flows, with cross-border logistics networks routing finished goods through Bratislava's distribution hubs toward Hungarian and Austrian retail channels.
Bratislava Region
Residential renovation waves concentrate demand for built-in kitchen suites and A-grade refrigeration units. EU Ecodesign Directive enforcement through Slovakia's national market surveillance authority disqualifies lower-efficiency imports from capital region showrooms. Bratislava's premium retail channels command shelf priority for connected appliance ecosystems with Wi-Fi-enabled diagnostics.
Košice Region
Eastern Slovakia's second-largest urban center shows lagging smart appliance penetration relative to EU averages, creating positioning opportunities for cost-engineered washing machine platforms. National green subsidy schemes tied to building renovation programs extend eligibility to Košice district households upgrading pre-2021 cooling units. Hypermarket networks in the region face thinner addressable markets for premium built-in lines due to disposable income distribution.
Prešov Region
Underpenetrated districts in northeastern Slovakia offer first-mover positioning for Wi-Fi-enabled platforms targeting younger demographics. CE marking requirements under the EU's Low Voltage Directive add certification overhead for Asian manufacturers distributing through regional retail channels. Local installer capacity constraints compress seasonal demand windows during Q2-Q3 construction peaks.
Žilina Region
Northwestern industrial zones anchor logistics corridors connecting Czech manufacturing bases to Slovak distribution networks. Click-and-collect integration with in-store diagnostics creates new touchpoints for mid-tier appliance sales outside the capital. Regional retailers manage dual inventory SKUs across pre- and post-Ecodesign efficiency tiers during regulatory transition periods.
Banská Bystrica Region
Central Slovak districts exhibit mixed technology adoption curves between conventional equipment and energy-efficient models qualifying for national subsidies. The country's central bank monitors household credit flows tied to renovation-driven purchasing decisions. Service technician certification gaps in smaller cities complicate connected appliance deployment for predictive maintenance subscriptions.
Slovakia Home Appliances Market Competitive Landscape
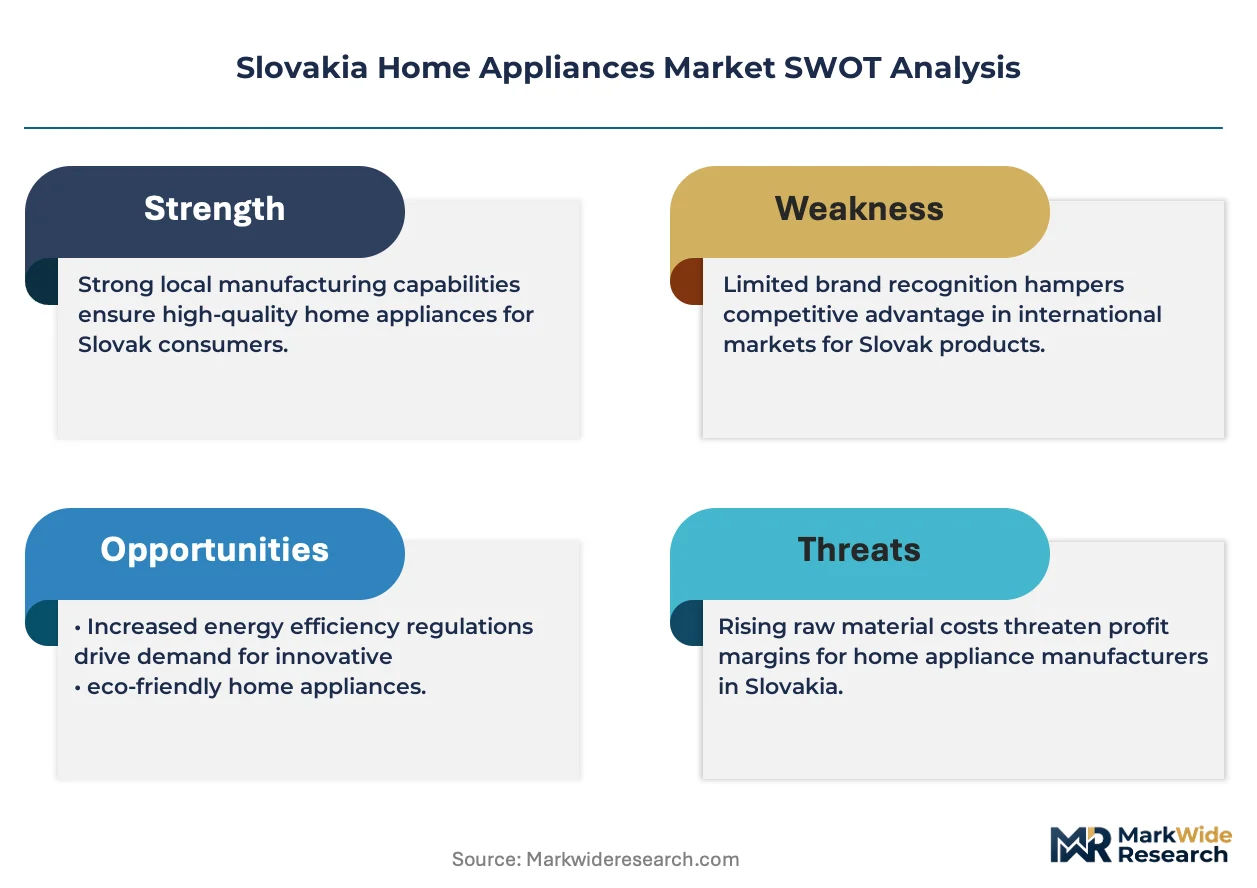
Channel-controlling players compete with product-specialist players across Slovakia's fragmented retail architecture. Bratislava's premium showroom networks concentrate around built-in kitchen specialists, while hypermarket chains dominate volume distribution in eastern districts. Three archetypes define competitive positioning: German-engineered premium brands, Asian cost-leaders, and regional design specialists. Capacity expansion and portfolio diversification represent the dominant competitive moves, with manufacturers rationalizing refrigeration lines to meet tightened EU Ecodesign minimums.
Among German-engineered premium players, BSH Hausgeräte GmbH and Bosch occupy positions exemplifying embedded manufacturing footprint advantages in Central European lead-time competition. Hisense Group Co., Ltd. represents the Asian cost-engineering archetype distributing through hypermarket density. Gorenje anchors the regional design-specialist tier with premium placement in Slovak retail channels. These three companies illustrate the tripartite structure governing competitive dynamics across efficiency tiers and distribution channels.
| Leading Market Players |
|---|
| Electrolux AB |
| BSH Hausgeräte GmbH |
| Whirlpool Corporation |
| Hisense Group Co., Ltd. |
| Samsung Electronics Co., Ltd. |
| Gorenje |
| Bosch |
| Siemens |
| LG Electronics |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Czech refrigeration component plants is compressing supplier margins and forcing Bratislava distributors to absorb freight premiums rather than pass through cost increases. This utilization imbalance grants buyers leverage in annual contract negotiations while pressuring manufacturers to bundle predictive maintenance subscriptions to protect net revenue per unit.
Pricing Analysis
Current-gen Wi-Fi-enabled appliances command 25-40% premiums over prior-gen non-connected units, while next-gen AI-optimized platforms sit in limited pilot distribution. Three-tier pricing structure across premium, standard, and economy levels aligns with EU energy efficiency grades A, C, and F respectively. Pricing pressure stems from Asian cost-engineered washing machines flooding hypermarket channels. Residential renovation buyers show lowest price sensitivity due to subsidy qualification, while eastern district households exhibit highest elasticity.
Supply Chain Analysis
Contract manufacturing concentrates at BSH's Trnava facility and Gorenje's Velenje complex, with Hisense leveraging third-party EMS partners for Slovak-bound production. Component sourcing draws from Germany for control systems, Poland for steel enclosures, and China for compressors. Raw material dependencies include copper wiring, refrigerant gases, and semiconductor chips for connected features. Single-source vulnerability runs through Taiwanese chip foundries serving smart appliance lines. Distribution runs through Bratislava hub-and-spoke networks reaching Košice and Prešov via Czech rail corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance subscription attach rates in Bratislava urban districts are expanding faster than hardware unit growth, reframing this market as a service-attach opportunity where software-enabled recurring revenue pools exceed one-time appliance margins.
For Market Incumbents: Build installer network certification moats by embedding software diagnostics training into authorized service partnerships before right-to-repair mandates extend spare parts obligations. Defensive consolidation should prioritize backward integration into compressor manufacturing to hedge refrigerant supply volatility, while channel control investments in Bratislava premium showroom networks protect against Asian cost-leader encroachment. For New Entrants and Emerging Players: Košice and Prešov smart appliance underpenetration relative to EU averages offers first-mover positioning for Wi-Fi-enabled platforms targeting younger demographics. White-space targets include cost-engineered washing machine distribution through digitizing hypermarket click-and-collect networks, and bundled kitchen suite sales aligned with national green subsidy schemes in renovation-driven purchasing cycles. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated regional specialists with captive component supply and established installer certification programs. Long-term viability favors manufacturers bridging hardware production with software service contract revenue. Watch smart appliance warranty claim resolution timelines as the inflection signal—compression from weeks to hours indicates successful platform monetization.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Wi-Fi-enabled diagnostics subscriptions shift margin pools from hardware toward recurring software revenue in Bratislava households. |
| Backward Integration into Compressor Manufacturing | In-house refrigerant component production hedges supply volatility from tightened EU F-Gas Regulation import restrictions. |
| Installer Certification Program Expansion | Software competency training addresses technician gaps in Košice and Prešov that constrain connected appliance deployment. |
| Hypermarket Channel Digitization Partnership | Click-and-collect integration with in-store diagnostics creates touchpoints for cost-engineered washing machine sales outside capital region. |
| Building Renovation Program Alignment | National green subsidy qualification bundles kitchen suite replacements into single project timelines compressing vendor selection windows. |
Research Methodology
A spread of perspectives from appliance manufacturing executives, hypermarket category buyers, authorized service technicians, and national energy efficiency program administrators converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through EU Ecodesign Directive enforcement notices, Slovakia's national market surveillance authority compliance bulletins, and customs trade flow records. Bottom-up unit shipment modeling triangulated against top-down household penetration benchmarks across the analysis window.
Demand-supply-balance framing anchored the forecast framework, with installation capacity constraints and renovation project pipelines modeled alongside manufacturing output schedules. Segmentation dimensions included product type, technology tier, end-user application, and distribution channel maturity. CAGRs were derived from slope analysis of replacement cycle compression and subsidy program uptake curves. Industry-specific inputs incorporated EU energy label revision timelines and Bratislava residential construction permit data.
Practitioners should monitor right-to-repair regulatory finalization and F-Gas quota allocation announcements for early signals requiring forecast revision. Quarterly review of installer certification completion rates and smart appliance warranty claim resolution timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
UAE Major Home Appliances Market
Home Appliances
Europe Personal Care Appliances Market
Home Appliances
Range Hood Market
Home Appliances
Germany Washing Machine Market
Home Appliances
Oman Home Appliances Market
Home Appliances
United Kingdom Major Home Appliances Market
Home Appliances
India Small Home Appliances Market
Home Appliances
Russia Home Appliances Market
Home Appliances
Smart Small Home Appliances Market
Home Appliances
North America Electric Fireplace Market
Home Appliances
Europe Laundry Appliances Market
Home Appliances
Bahrain Home Appliances Market
Home Appliances
North America Major Home Appliances Market
Home Appliances
Europe Washing Machine Market
Home Appliances
India Home Appliances Market
Home Appliances
Japan Home Appliances Market