
 North America Built-In Home Appliances Market | 2026-2036
North America Built-In Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
North America Built-In Home Appliances Market Insights
Stainless steel is rebalancing toward composite and recycled aluminum panels across built-in refrigerator and oven chassis, trimming raw material costs without sacrificing structural rigidity. Robert Bosch GmbH leverages its captive steel-forming operations in New Bern, North Carolina to stabilize input costs. Whirlpool Corporation anchors its North American margin structure through in-house production of compressor assemblies for integrated refrigeration units. LG Electronics differentiates via direct-to-builder channel control in the southeastern United States.
Built-in home appliances comprise permanently installed cooking, cooling, and cleaning equipment designed for flush cabinet integration, typically requiring 24-inch or 30-inch standardized cutout dimensions and hardwired electrical or plumbed water connections. These products serve residential and light commercial kitchens where spatial efficiency and aesthetic continuity command priority. Refrigerators lead product type revenue contribution due to compressor complexity and replacement frequency, while cooktops capture faster volume growth from induction technology conversion. Urban homeowners dominate the consumer segment, though builders represent the margin pool through bulk specification contracts on multifamily developments.
The U.S. Department of Energy enforces minimum efficiency standards under its Appliance and Equipment Standards Program, compelling compressor and insulation upgrades that raise manufacturing costs but bar low-efficiency imports. EPA Energy Star certification operates as a de facto market access filter for premium distribution channels. Canada's Natural Resources Canada administers parallel EnerGuide labeling that harmonizes with U.S. testing protocols. Stakeholders must monitor pending DOE rulemakings on cooking products and provincial efficiency variations across Canadian provinces.
Market Dynamics
The U.S. Department of Energy's escalating efficiency mandates are compressing product development cycles while forcing compressor and insulation technology upgrades across the built-in refrigeration segment. Manufacturers must now engineer for stricter energy consumption thresholds before products reach Texas and Florida residential construction corridors.
Growth Catalysts
- Induction cooktop conversion:Urban homeowners in high-density metros are replacing gas cooktops with electromagnetic heating systems, eliminating venting requirements and enabling tighter kitchen footprints.
- EPA Energy Star certification:Premium distribution channels now treat this label as a mandatory filter, channeling procurement toward certified manufacturers and raising baseline efficiency across the product mix.
- Texas and Florida construction corridors:New home starts in these states favor integrated appliance packages specified by builders, concentrating volume demand for 24-inch and 30-inch standardized cutout dimensions.
Market Restraints
- Steel and aluminum input volatility:Raw material cost swings for chassis-grade stainless steel and recycled aluminum panels compress margin predictability for refrigerator and oven manufacturers.
- Compressor supply concentration:Inverter-driven compressor technology remains concentrated among a limited supplier base, creating bottleneck risk for manufacturers scaling production.
- DOE rulemaking uncertainty:Pending efficiency standards on cooking products create product planning friction, delaying capital allocation for next-generation platform development.
Strategic Opportunities
- Multifamily builder channel penetration:Bulk specification contracts for rental and condominium developments in southeastern U.S. metros offer volume anchoring with lower customer acquisition costs.
- Canada EnerGuide harmonization:Parallel efficiency labeling with U.S. testing protocols enables single-product certification for cross-border distribution, reducing compliance overhead.
- Smart appliance connectivity convergence:Integration of Wi-Fi-enabled diagnostics with utility demand-response programs creates new revenue streams through energy management services.
Industry Challenges
- Refrigerant transition complexity:Migration to lower-global-warming-potential refrigerants requires retooling of compressor assembly lines and requalification of insulation systems.
- Installation skill scarcity:Hardwired electrical and plumbed water connections for built-in units demand certified technicians, creating service bottlenecks in rapid-growth construction markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Built-In Home Appliances Market |
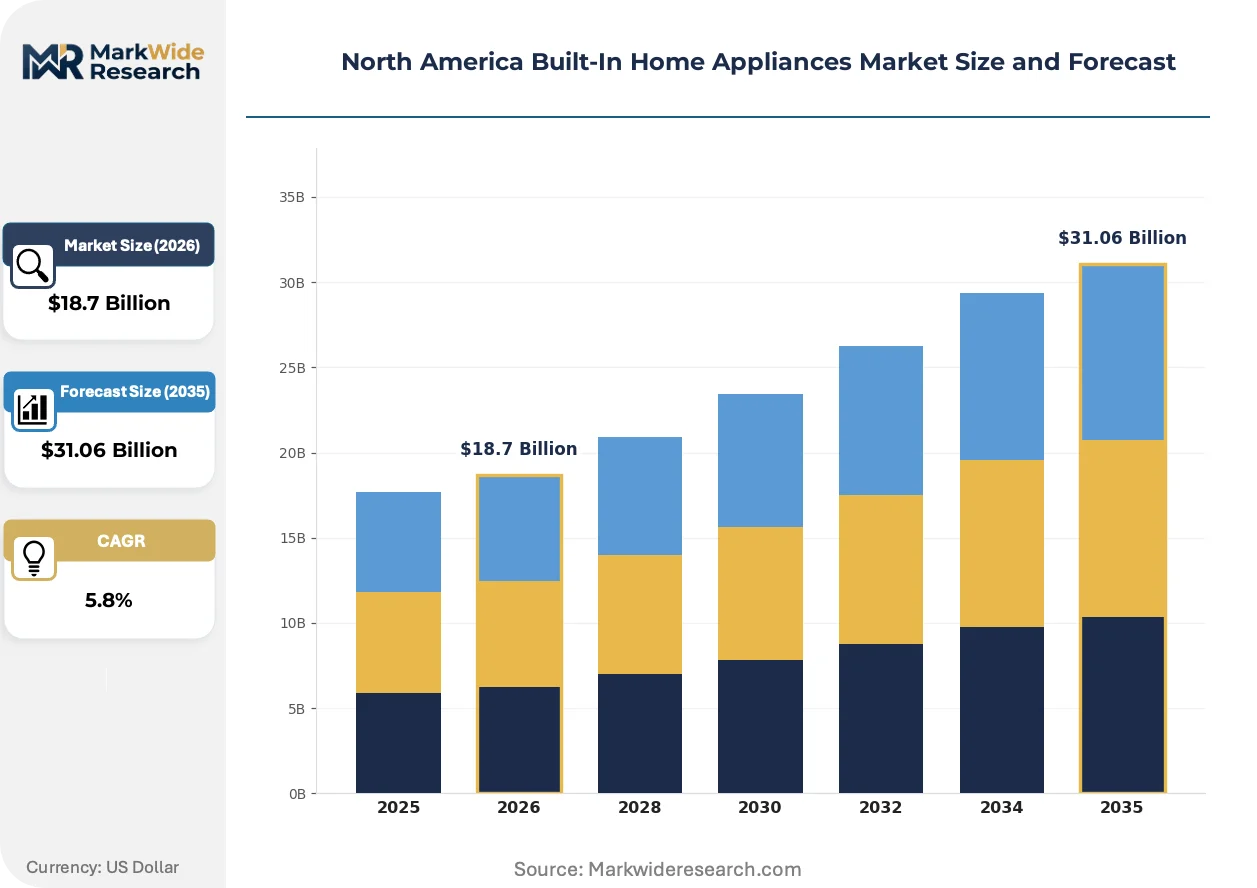
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Ovens, Dishwashers, Cooktops Consumer Segment: Urban Homeowners, Builders, Designers, Renovators Distribution Channel: Online Retail, Specialty Stores, Wholesalers, Home Improvement Stores Installation Type: New Construction, Remodeling, Replacement, Integrated Solutions |
| Companies Covered | Robert Bosch GmbH, AB Electrolux, Haier Smart Home Co., Ltd., Whirlpool Corporation, Panasonic Holdings Corporation, LG Electronics, Samsung Electronics Co., Ltd., GE Appliances, Miele, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Built-In Home Appliances Market Trends and Innovations
Three distinct vectors are compressing traditional product lifecycles while expanding the addressable market for integrated kitchen systems. Technology automation, regulatory stringency, and builder-channel consolidation are converging to reshape competitive positioning.
Sensor-driven cooking automation is automating temperature control and timing adjustments across induction cooktop platforms. High-end urban homeowners are specifying these systems in luxury renovation projects at accelerating rates. This capability compression is reducing operator error claims while enabling premium pricing for connected appliance tiers.
The U.S. Department of Energy's Appliance and Equipment Standards Program is mandating minimum efficiency thresholds that bar low-efficiency imports from premium channels. Compressor and insulation upgrades are raising manufacturing costs but simultaneously filtering competition. The built-in refrigeration segment is responding by accelerating inverter technology adoption ahead of compliance deadlines.
Builder-direct procurement is consolidating specification authority away from traditional retail channels. Multifamily developers in Texas and Florida now negotiate bulk appliance packages directly with manufacturers, compressing distributor margins. This channel shift is most visible in new construction submarkets where standardized cutout dimensions enable volume configuration efficiency.
North America Built-In Home Appliances Market Segmentation
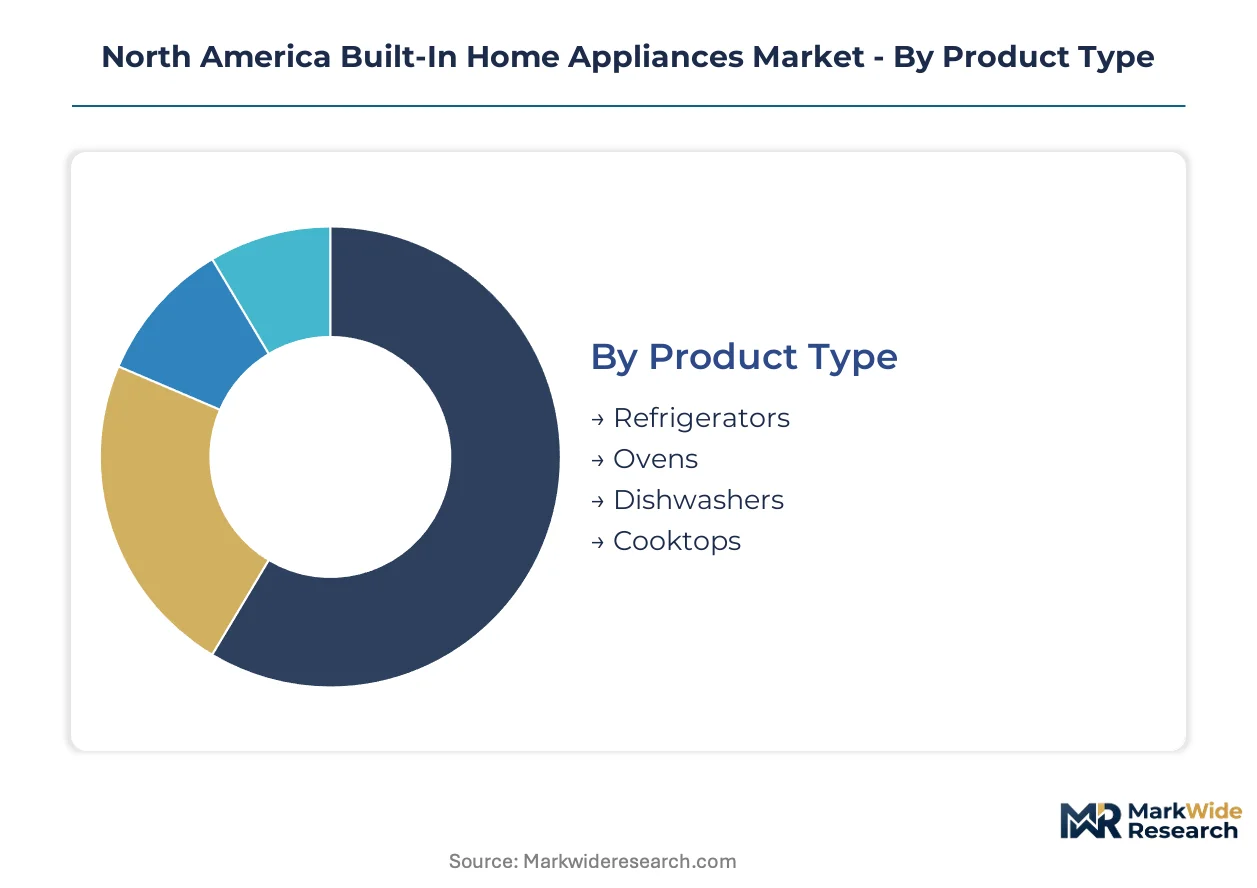
Segmentation in the North America Built-In Home Appliances Market reveals how certification requirements, installation complexity, and channel economics concentrate margin pools. Each dimension exposes distinct regulatory burdens and procurement patterns that shape manufacturer strategy.
Product Type:
EPA Energy Star certification applies universally across this category, while DOE efficiency standards impose tiered compliance thresholds that favor inverter-driven refrigeration platforms over conventional compressor architectures.
- Refrigerators:Compressor complexity and insulation density drive the highest manufacturing cost structure in the category. Demand concentrates in Texas and Florida residential construction corridors where builder-specified integrated packages require 24-inch and 30-inch standardized cutout dimensions alongside hardwired electrical connections.
- Cooktops:Electromagnetic induction systems are displacing gas configurations in high-density urban kitchens, eliminating venting requirements and enabling tighter footprints. Urban homeowners in luxury renovation segments specify these platforms at accelerating rates, particularly where municipal gas connection moratoriums apply.
- Ovens:Composite and recycled aluminum chassis panels are trimming raw material costs without sacrificing structural rigidity for built-in wall oven installations.
- Dishwashers:Plumbed water connections and hardwired electrical requirements create installation skill scarcity bottlenecks in rapid-growth construction markets.
Refrigerators sit at the top of the volume ranking, with cooktops climbing the fastest.
Consumer Segment:
Cost tier stratification separates specification authority between end-users who prioritize aesthetic continuity and intermediaries who control bulk procurement economics.
- Urban Homeowners:Luxury kitchen renovations in high-density metros accelerate adoption of sensor-driven cooking automation and connected appliance tiers. This segment commands premium pricing tolerance but requires direct-to-consumer marketing investment.
- Builders:Bulk specification contracts on multifamily developments in southeastern United States metros offer volume anchoring with lower customer acquisition costs. This segment controls margin pools through standardized cutout dimension requirements.
- Designers:Aesthetic continuity specifications drive flush cabinet integration requirements and influence material selection for chassis finishes.
- Renovators:Replacement frequency concentrates in aging housing stock submarkets where existing cutout dimensions constrain product selection flexibility.
Builders dominate absolute volume procurement, with urban homeowners generating the steepest expansion trajectory for premium connected tiers.
Distribution Channel:
Channel consolidation is displacing traditional retail intermediaries as builder-direct procurement captures specification authority in new construction submarkets.
- Online Retail:Wi-Fi-enabled diagnostics and utility demand-response program integration create digital service attachment opportunities. This channel captures replacement demand from technically sophisticated urban homeowners.
- Specialty Stores:Premium distribution channels treat EPA Energy Star certification as a mandatory filter, channeling procurement toward certified manufacturers and raising baseline efficiency across product mix presentation.
- Wholesalers:Bulk logistics infrastructure serves builder channel concentration in Texas and Florida construction corridors.
- Home Improvement Stores:Standardized cutout dimension compatibility enables DIY installation segments for replacement applications.
Specialty stores anchor premium tier positioning, with online retail gaining share fastest in connected appliance categories.
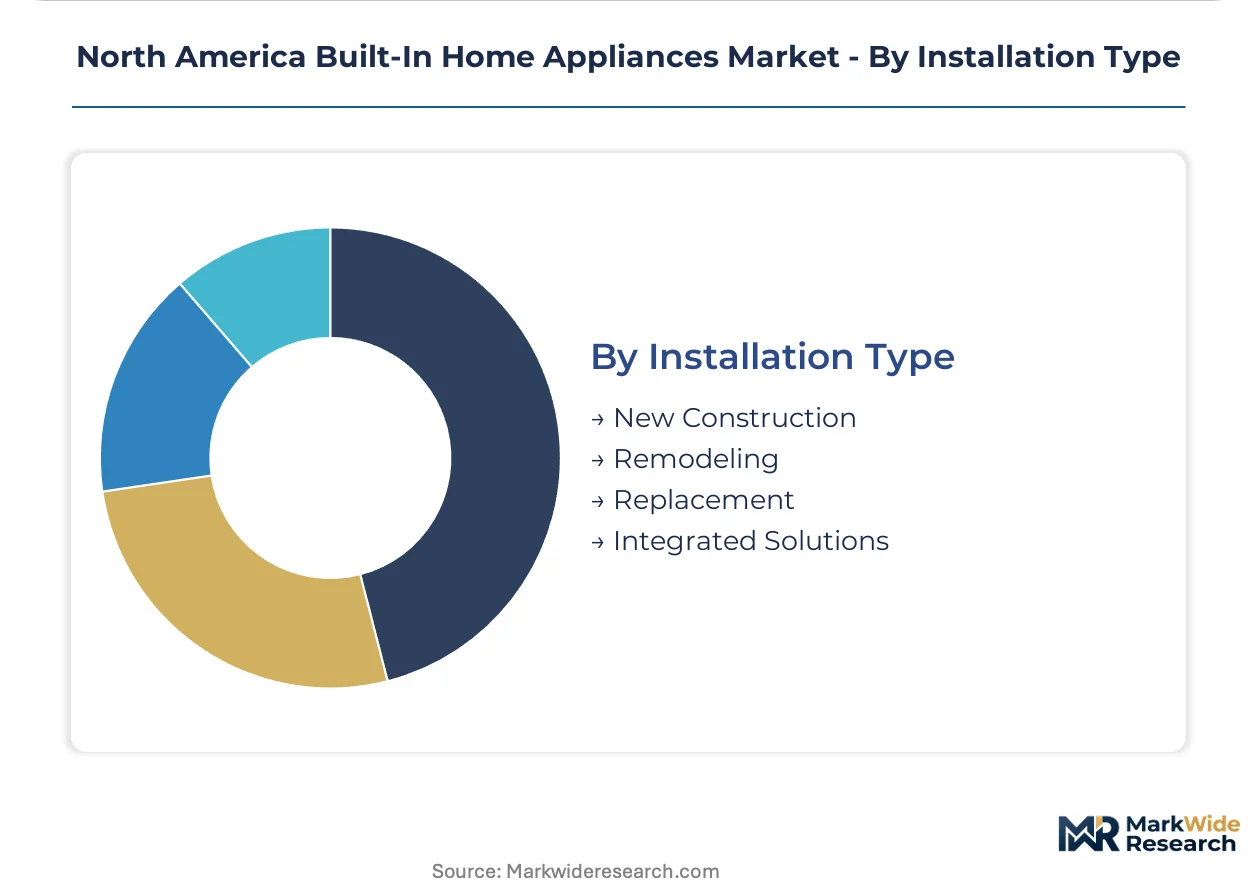
Installation Type:
Application timing determines regulatory exposure and technician certification requirements, with new construction offering standardized installation protocols versus remodeling complexity.
- New Construction:Integrated appliance packages specified during framing enable optimized electrical and plumbing rough-in coordination. Texas and Florida residential construction corridors favor this installation type through volume builder procurement.
- Remodeling:Existing cabinet constraints and utility connection relocation create labor cost premiums and extend project timelines in luxury renovation segments.
- Replacement:Standardized cutout dimension compatibility determines product selection feasibility, with 24-inch and 30-inch formats dominating retrofit applications.
- Integrated Solutions:Flush cabinet aesthetic requirements demand precise installation tolerances and certified technician engagement for warranty validation.
New construction commands the largest volume base, with integrated solutions expanding most quickly in luxury urban renovation markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas and Florida residential construction corridors anchor North American demand for integrated appliance packages, with builder-specified volumes concentrating in metropolitan submarkets where standardized cutout dimensions enable procurement efficiency.
United States
Urban homeowners in high-density metros accelerate luxury kitchen renovations featuring sensor-driven cooking automation and connected appliance tiers. The U.S. Department of Energy enforces escalating efficiency mandates under its Appliance and Equipment Standards Program, compelling compressor technology upgrades ahead of compliance deadlines. Texas and Florida construction corridors dominate volume concentration, with multifamily developers negotiating bulk specification contracts directly with manufacturers.
Canada
Natural Resources Canada administers EnerGuide labeling that harmonizes with U.S. testing protocols, enabling single-product certification for cross-border distribution. Parallel efficiency standards reduce compliance overhead for manufacturers serving Ontario and Quebec metropolitan markets. Toronto and Vancouver urban cores concentrate premium-tier demand where flush cabinet integration commands specification priority.
Mexico
Manufacturing clusters in Nuevo León and Baja California supply component assemblies for North American refrigerator and cooktop production. Proximity to U.S. distribution networks supports just-in-time logistics for builder-channel procurement. Monterrey anchors industrial capacity for compressor housing and chassis-grade steel forming operations serving integrated appliance platforms.
North America Built-In Home Appliances Market Competitive Landscape
Backward integration into captive manufacturing operations dominates the current landscape as manufacturers stabilize input costs against raw material volatility. The vendor base organizes around three strategic archetypes: diversified conglomerates with captive component production, specialist premium brands with direct-to-builder channel control, and scale-driven manufacturers with in-house compressor assembly capabilities. M&A activity and capacity expansion represent the dominant competitive moves, with players acquiring regional distributors and expanding southeastern U.S. production footprints to capture builder-channel volume.
Among diversified conglomerates with captive manufacturing, Robert Bosch GmbH and Whirlpool Corporation exemplify the integration archetype. Bosch leverages steel-forming operations in New Bern, North Carolina to stabilize chassis input costs, while Whirlpool anchors margin structures through in-house compressor assembly production. LG Electronics occupies a distinct position with direct-to-builder channel control in southeastern U.S. metros, capturing bulk specification contracts through distributor bypass strategies.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| AB Electrolux |
| Haier Smart Home Co., Ltd. |
| Whirlpool Corporation |
| Panasonic Holdings Corporation |
| LG Electronics |
| Samsung Electronics Co., Ltd. |
| GE Appliances |
| Miele |
| Others |
Pricing and Supply Chain Analysis
Certified appliance installer concentrations in Texas and Florida construction corridors feed directly into pricing-tier spreads across the built-in home appliances category. Labor-cost differentials between these rapid-growth markets and legacy manufacturing regions widen the premium-to-economy price gap as installation skill scarcity intensifies.
Pricing Analysis
Input-cost pass-through from steel and aluminum chassis-grade materials runs through to end-product pricing with limited absorption capacity. Three-tier pricing structure across premium, standard, and economy levels separates EPA Energy Star-certified platforms from baseline efficiency imports. Pricing pressure stems from DOE rulemaking uncertainty on cooking products, compressing margin predictability for manufacturers. Builders demonstrate highest price sensitivity through bulk procurement leverage, while urban homeowners in luxury renovation segments show lowest sensitivity to premium connected tiers.
Supply Chain Analysis
Compressor housing and inverter-driven component supply rests on manufacturing clusters in Mexico, South Korea, and domestic U.S. facilities. Raw material dependencies center on chassis-grade stainless steel, recycled aluminum panels, and refrigerant-grade copper tubing. Single-source vulnerability concentrates in inverter compressor technology among limited qualified suppliers. Distribution runs through builder-direct channels in southeastern U.S. metros, bypassing traditional wholesale intermediaries for new construction volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
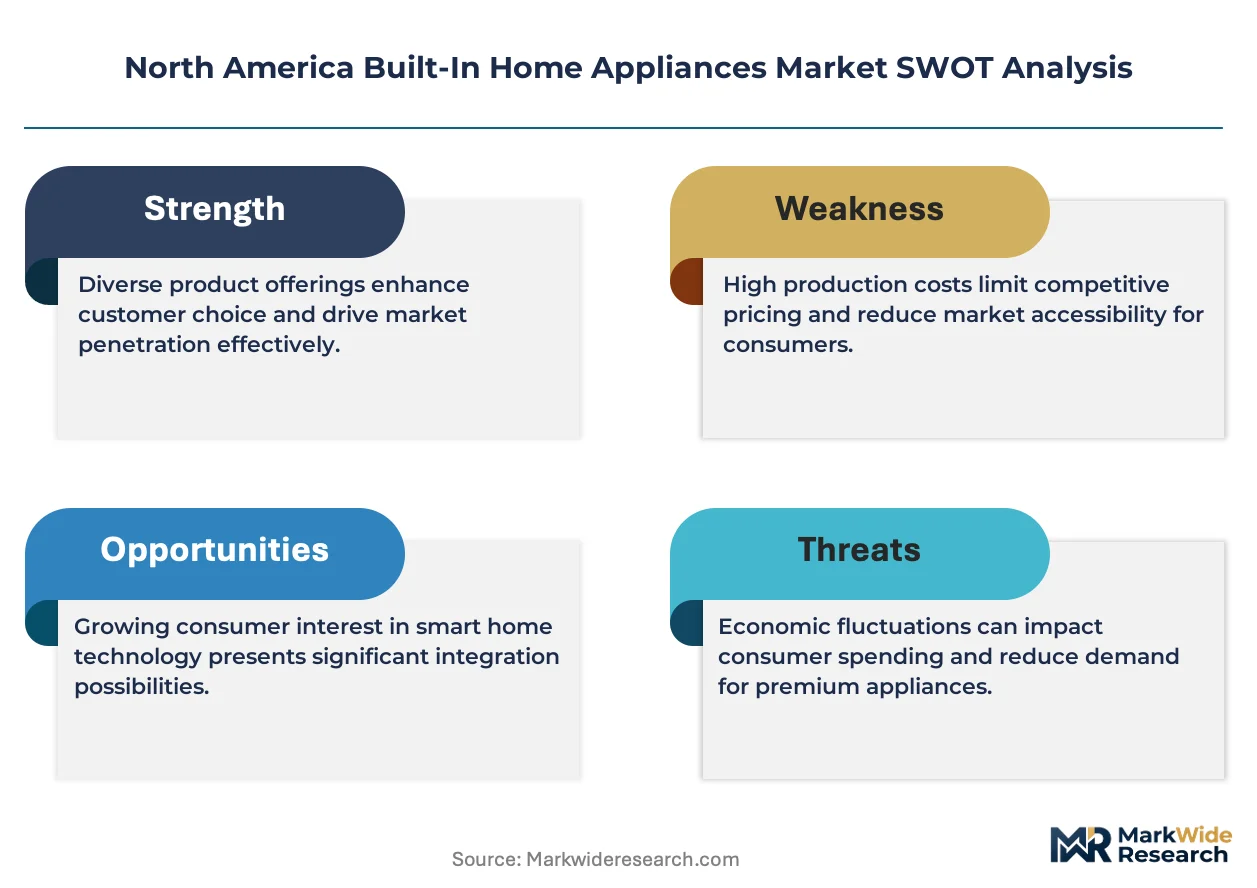
The North America Built-In Home Appliances Market functions as a stable compounder anchored by regulatory efficiency mandates that force replacement cycles and technology upgrades. DOE appliance standards create predictable demand refresh mechanics across the analysis window.
For Market Incumbents: Acquire regional distributor networks to secure builder-channel specification authority in Texas and Florida construction corridors. Backward integration into captive steel-forming operations stabilizes input cost volatility against raw material swings. Compressor supply concentration among limited suppliers represents the primary threat; in-house assembly capabilities defend margin structures.
For New Entrants and Emerging Players: Direct-to-builder digital procurement platforms offer the most penetrable route for bypassing established wholesale relationships. White-space targets concentrate in multifamily rental developments in southeastern U.S. metros where standardized cutout dimensions enable volume configuration efficiency. Wi-Fi-enabled diagnostics integration with utility demand-response programs provides a differentiated go-to-market angle.
For Investors and Strategic Acquirers: Diversified home appliance conglomerates are the most active acquirer in this space, consolidating regional distributors and component manufacturers. Long-term viability frames around regulatory compliance capabilities and builder-channel relationships over a multi-year holding period. Acquisition target archetypes include compressor technology specialists and southeastern U.S. distributor networks. Pending DOE rulemakings on cooking products serve as the signal to watch for inflection timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Component Manufacturing | Bosch's captive steel-forming in New Bern, North Carolina stabilizes chassis input costs against volatility. |
| Builder-Direct Channel Expansion | LG Electronics bypasses distributors to capture bulk specification contracts in southeastern U.S. metros. |
| Inverter Compressor Technology Investment | Whirlpool's in-house assembly production anchors refrigeration margin structures against supply bottlenecks. |
| Smart Appliance Connectivity Development | Wi-Fi-enabled diagnostics integration creates energy management service revenue streams with utilities. |
| Regional Distributor Acquisition | Consolidation of Texas and Florida wholesale networks secures specification authority in construction corridors. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market. The analysis combines structured interviews with appliance manufacturing executives, builder procurement managers, certified installation technicians, and distributor operations heads with secondary validation from DOE appliance standards filings, EPA Energy Star certification databases, Natural Resources Canada EnerGuide protocols, and U.S. Census Bureau construction starts data. Bottom-up volume modeling and top-down value triangulation cross-validate segment outputs.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include product type, consumer segment, distribution channel, and installation type, with regional regulatory cluster as an industry-specific overlay. CAGRs derive from historical trajectory analysis adjusted for policy mandate timing and construction cycle correlation. Forecast inputs incorporate DOE rulemaking calendars, refrigerant transition schedules, and builder channel consolidation patterns.
The model assumes a particular technology adoption path; alternative pathways for inverter-driven compressor penetration would alter the outlook. Forecasts reflect assumptions around DOE efficiency standard implementation timing, Texas and Florida construction corridor momentum, and refrigerant transition compliance schedules. Regulatory delay, raw material cost spikes, or installation technician supply constraints represent specific risk factors that could revise projections. A small set of named triggers—DOE cooking product rulemakings, compressor supplier consolidation events, and municipal gas connection moratoriums—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Europe Residential Water Heaters Market
Home Appliances
Kuwait Small Home Appliances Market
Home Appliances
France Household Appliances Market
Home Appliances
UAE Laundry Appliances Market
Home Appliances
Home Appliance (Wet and Cold) Market
Home Appliances
China Laundry Appliances Market
Home Appliances
Saudi Arabia Home Appliances Market
Home Appliances
Side-By-Side Smart Refrigerator Market
Home Appliances
Qatar Home Appliances Market
Home Appliances
India Laundry Appliances Market
Home Appliances
India Small Home Appliances Market
Home Appliances
Kuwait Home Appliances Market
Home Appliances
United Kingdom Small Home Appliances Market
Home Appliances
Egypt Small Home Appliances Market
Home Appliances
Electrical Appliances Market
Home Appliances
Canada Home Appliances Market