
 India Smart Grid Network Market | 2026-2036
India Smart Grid Network Market Size, Share, and Industry Trends Forecast 2026-2036
India Smart Grid Network Market Foresight
Software-defined grid management is recalibrating what utilities procure, shifting capital expenditure toward subscription-based analytics platforms. General Electric Company leverages its digital twin portfolio to anchor utility modernization contracts across state discoms. Siemens AG sustains technology leadership in distribution management systems through deep R&D partnerships with Indian engineering institutes. Cisco Systems Inc. dominates communication network layers, extending its edge-to-cloud architecture into substation automation deployments.
Smart grid networks integrate sensing, communication, and control technologies to enable bidirectional electricity flows and real-time demand balancing across transmission and distribution infrastructure. These systems employ IEC 61850 protocol standards for substation automation and typically operate through IP/MPLS backbones with latency thresholds below 100 milliseconds for protection signaling. Advanced Metering Infrastructure commands the largest share of technology spending as utilities prioritize meter data management and revenue protection. Grid Analytics represents the fastest-expanding solution category, where margin pools deepen around predictive asset health algorithms and non-technical loss detection models.
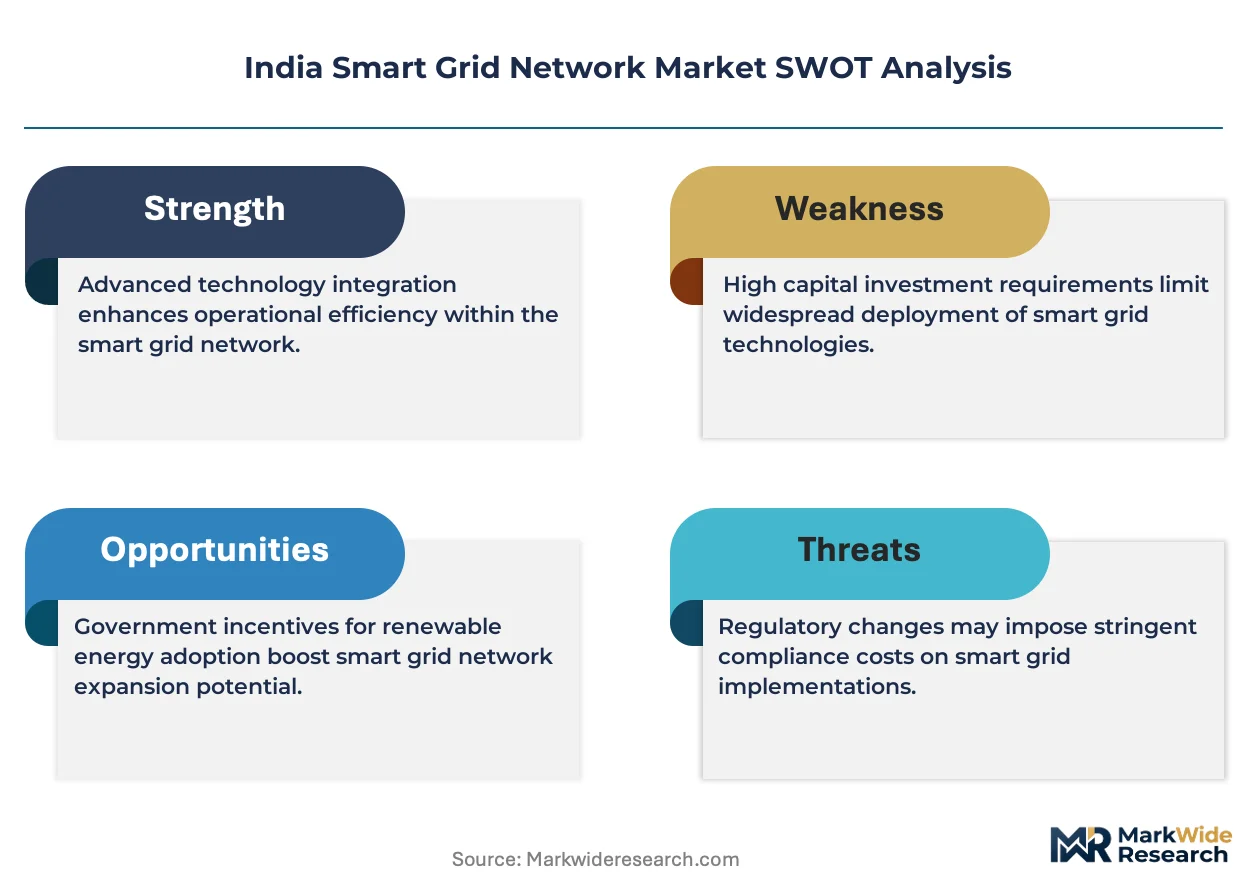
The Central Electricity Authority mandates smart grid standards under the National Smart Grid Mission, while BIS certification governs metering equipment interoperability and cyber-physical security benchmarks. State regulators in Tamil Nadu and Rajasthan have issued tariff orders that accelerate AMI rollout timelines and mandate time-of-day pricing pilots. Stakeholders must monitor how state-level renewable purchase obligations reshape grid stability requirements and whether discom financial restructuring under the Revamped Distribution Sector Scheme unlocks delayed procurement cycles.
Market Dynamics
State electricity distribution companies in Maharashtra and Gujarat are accelerating AMI deployments under the National Smart Grid Mission, compressing procurement cycles and forcing vendors to restructure contract terms around outcome-based delivery models.
Growth Catalysts
- The Revamped Distribution Sector Scheme:Central government financial restructuring unlocks delayed capital expenditure cycles across state discoms, enabling long-deferred smart grid procurement.
- Renewable Purchase Obligations:State-level mandates for solar and wind integration force utilities to deploy real-time grid balancing technologies to manage intermittency.
- Advanced Metering Infrastructure:Revenue protection imperatives drive priority spending on meter data management systems with non-technical loss detection capabilities.
Market Restraints
- Discom Financial Distress:Accumulated losses across state distribution companies constrain balance sheet capacity for upfront smart grid capital investment.
- Copper and Semiconductor Input Volatility:Communication network hardware faces margin pressure from fluctuating commodity prices and constrained chip supply.
- Legacy Substation Infrastructure:Pre-digital switchgear and protection systems create technical debt that complicates IEC 61850 protocol migration.
Strategic Opportunities
- Rajasthan and Tamil Nadu Regulator Mandates:State tariff orders requiring time-of-day pricing pilots create immediate demand for smart metering and demand response platforms.
- Grid Analytics Convergence:Machine learning algorithms fused with AMI data streams enable predictive asset health monitoring and dynamic load forecasting.
- Edge-to-Cloud Architecture:Communication layer vendors can capture recurring revenue through managed network services replacing one-time hardware sales.
Industry Challenges
- Cyber-Physical Security Certification:BIS interoperability benchmarks and CEA security mandates impose extended compliance timelines on equipment vendors.
- SCADA-DMS Integration Complexity:Distribution management system deployments require costly reconfiguration of existing control center workflows and operator retraining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Smart Grid Network Market |
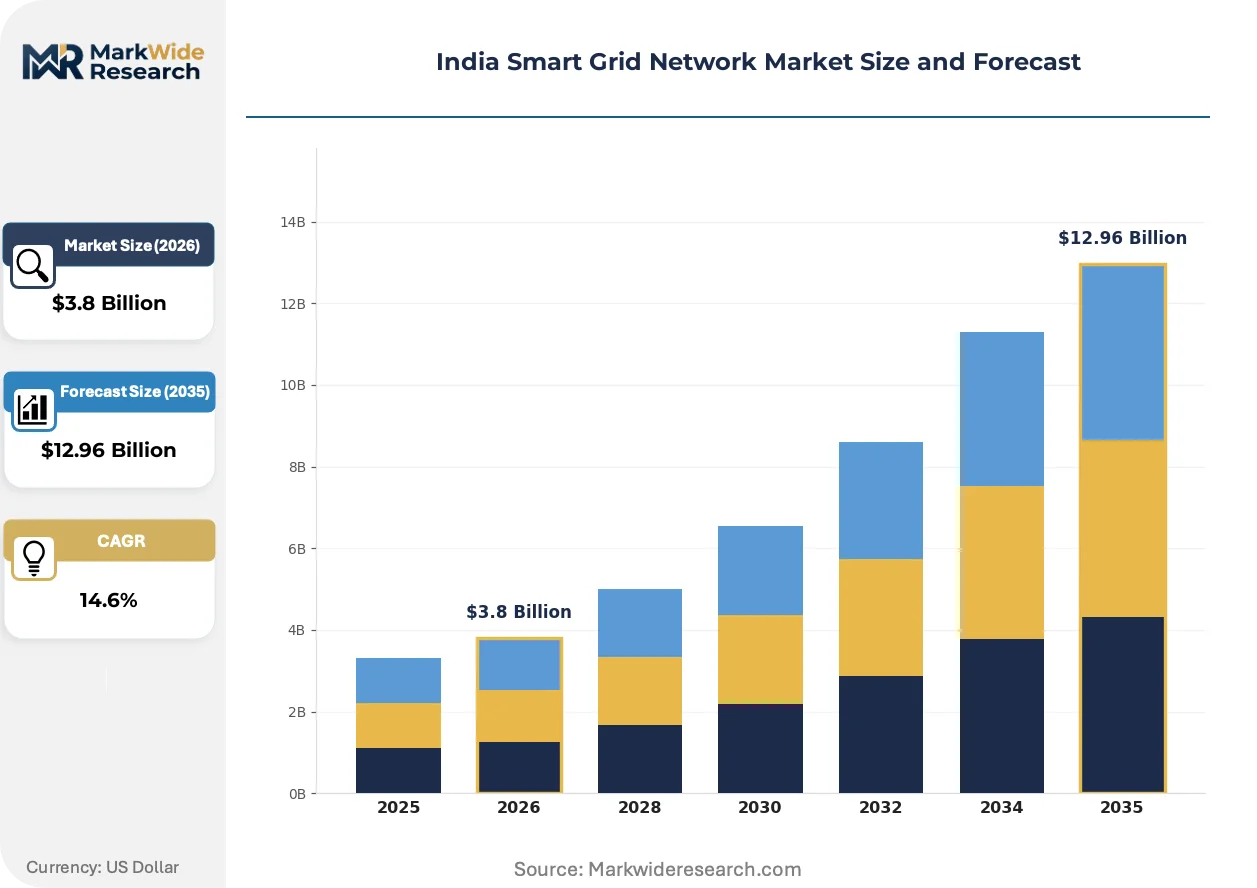
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Advanced Metering Infrastructure, Distribution Management Systems, SCADA Systems, Demand Response Solutions End User: Utilities, Industrial Sector, Commercial Facilities, Residential Solution: Energy Management Systems, Communication Networks, Cybersecurity Solutions, Grid Analytics Installation: Onshore, Offshore, Retrofitting, New Installations |
| Companies Covered | General Electric Company, Accenture PLC, Siemens AG, Power Grid Corporation of India Limited, HCL Technologies Ltd., Schneider Electric SE, Cisco Systems Inc., Honeywell International Inc., ABB Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Smart Grid Network Market Shifts & Advancements
Software-defined architectures are dissolving traditional boundaries between hardware and service layers, enabling utilities to procure grid management capabilities through subscription models rather than capital-intensive system purchases.
Digital twin technology is modularizing how utilities approach asset management, creating virtual replicas of physical grid infrastructure for simulation and optimization. State discoms in Gujarat and Maharashtra are piloting these platforms for transformer fleet management. The technology is modularizing vendor relationships from equipment suppliers to continuous service partners.
The Central Electricity Authority's smart grid standards mandate under the National Smart Grid Mission is hardening procurement specifications across state utilities. Equipment vendors must now demonstrate BIS certification and IEC 61850 compliance before contract eligibility. Distribution automation vendors face compressed development cycles to meet these evolving technical benchmarks.
Discoms are consolidating vendor relationships around integrated platform providers capable of spanning metering, communication, and analytics layers. Procurement teams in Tamil Nadu and Rajasthan now prioritize single-contract accountability over best-of-breed component sourcing. This concentration pattern favors technology conglomerates with end-to-end smart grid portfolios.
India Smart Grid Network Market Segmentation
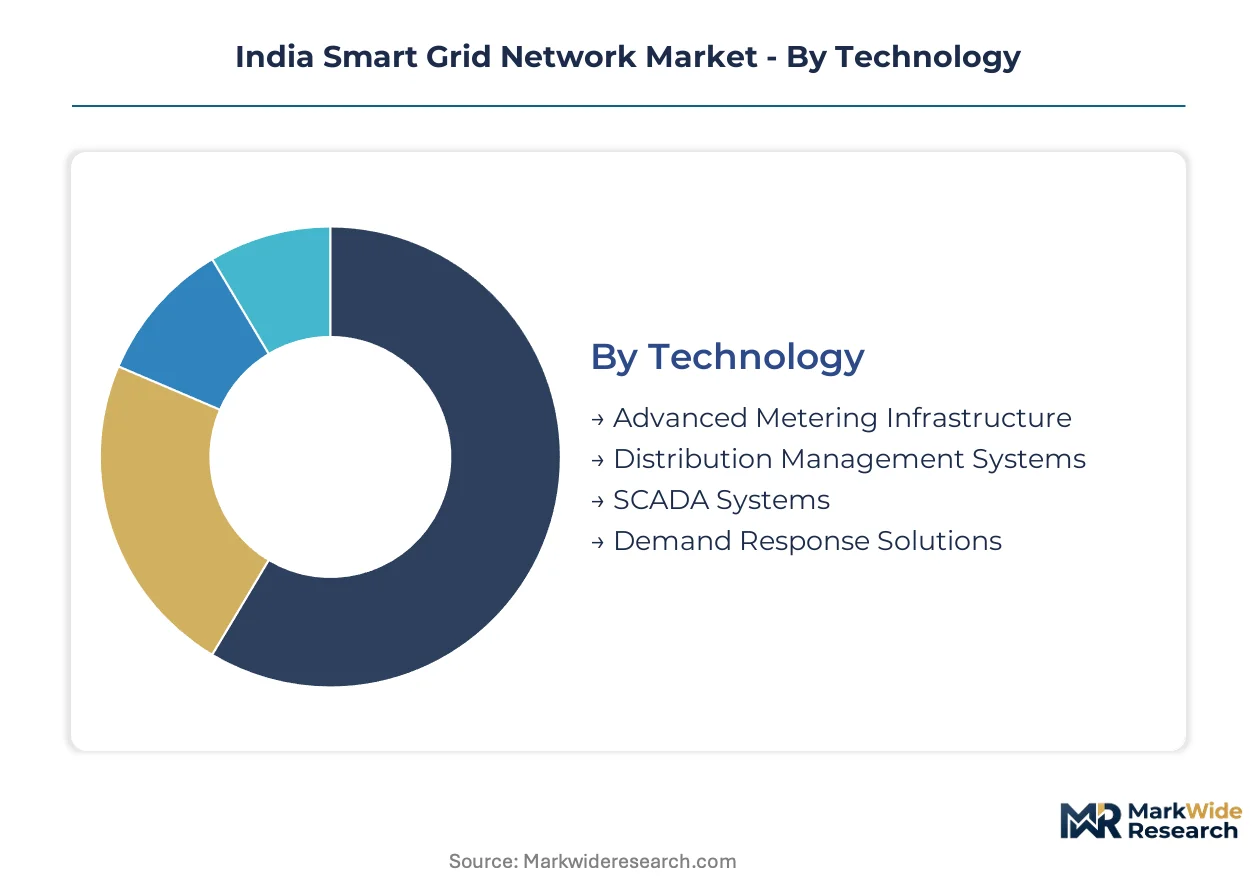
Smart grid procurement patterns in India diver sharply across technology maturity, buyer financial capacity, and regulatory compliance timelines. Understanding these segment boundaries clarifies where vendor resources concentrate and which customer profiles justify specialized solution architectures.
Technology:
Utility procurement teams distinguish technologies by deployment risk profile and revenue protection potential rather than technical sophistication alone.
- Advanced Metering Infrastructure:Meter data management platforms with non-technical loss detection algorithms dominate capital allocation across Maharashtra and Gujarat discoms. State regulators in Tamil Nadu and Rajasthan have compressed AMI rollout timelines through mandatory time-of-day pricing pilots, forcing vendors to accelerate BIS certification cycles.
- Distribution Management Systems:Real-time grid balancing software integrates SCADA feeds with outage management protocols for utilities managing high renewable penetration. Siemens AG sustains technology leadership through deep R&D partnerships with Indian engineering institutes, anchoring DMS procurement decisions.
- SCADA Systems:Legacy protocol migration toward IEC 61850 standards imposes technical debt reconfiguration costs on pre-digital substations.
- Demand Response Solutions:Load curtailment platforms gain traction among industrial consumers facing peak tariff penalties under state-level renewable purchase obligations.
Advanced Metering Infrastructure leads volumes today; Grid Analytics convergence with AMI data streams is gaining share fastest.
End User:
Buyer financial health and regulatory exposure determine contract structure preferences across the customer base.
- Utilities:State electricity distribution companies command the dominant share of procurement value, though accumulated losses constrain upfront capital investment capacity. The Revamped Distribution Sector Scheme unlocks deferred smart grid spending through central government financial restructuring.
- Industrial Sector:Large manufacturing facilities deploy private microgrids with embedded metering to manage renewable purchase obligations and avoid peak demand penalties.
- Commercial Facilities:Shopping complexes and IT parks pilot demand response participation under state tariff orders mandating time-of-day pricing.
- Residential:Smart meter penetration remains concentrated in urban clusters under Smart Cities Mission jurisdiction, with rural deployment lagging discom balance sheet recovery.
Utilities anchor procurement volumes today; Industrial Sector microgrid investments are climbing the fastest.
Solution:
Vendor margin pools stratify by software-versus-hardware composition and recurring revenue potential.
- Energy Management Systems:Software platforms for real-time consumption optimization command premium pricing in industrial and commercial deployments.
- Communication Networks:IP/MPLS backbones with sub-100 millisecond latency thresholds for protection signaling represent the infrastructure layer where Cisco Systems Inc. dominates through edge-to-cloud architecture extensions.
- Cybersecurity Solutions:BIS certification and CEA security mandates impose extended compliance timelines, favoring vendors with established certification track records.
- Grid Analytics:Machine learning algorithms for predictive asset health monitoring and dynamic load forecasting represent the steepest expansion trajectory as utilities shift from capital-intensive system purchases toward subscription-based analytics platforms.
Communication Networks lead installed base today; Grid Analytics subscriptions are expanding most quickly.
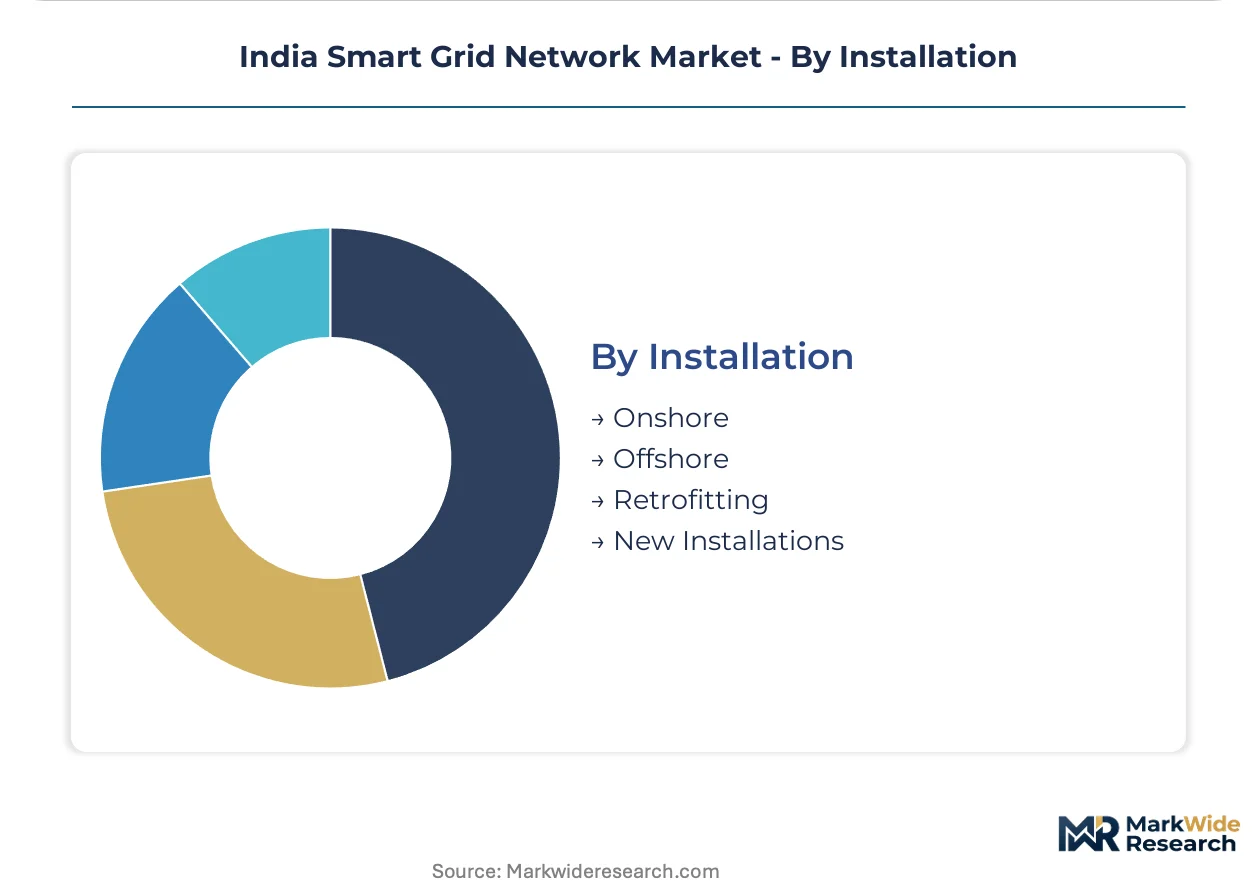
Installation:
Project economics hinge on legacy asset utilization versus greenfield standardization opportunities.
- Onshore:Substation automation and metering deployments across terrestrial distribution infrastructure constitute the overwhelming majority of project value.
- Offshore:Limited applicability given India's land-based grid topology, with minor relevance to coastal renewable integration projects.
- Retrofitting:IEC 61850 protocol migration for pre-digital switchgear creates complex technical debt scenarios requiring costly workflow reconfiguration and operator retraining.
- New Installations:Greenfield smart cities and industrial zones enable standardized deployments without legacy compatibility constraints, accelerating procurement cycles.
Retrofitting dominates project pipelines today; New Installations under Smart Cities Mission are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level regulatory arbitrage across Indian discoms is redistributing smart grid procurement toward jurisdictions with accelerated AMI mandates and tariff reform timelines. The Central Electricity Authority's standards harmonization under the National Smart Grid Mission compresses compliance cost differentials between advanced and lagging states.
Maharashtra
Maharashtra State Electricity Distribution Company Limited commands the largest AMI deployment pipeline among Indian utilities. The state regulator's mandatory time-of-day pricing directives force compressed rollout schedules for smart metering infrastructure. Mumbai-Pune industrial corridor utilities pilot digital twin platforms for transformer fleet optimization under vendor partnerships with technology conglomerates.
Gujarat
Gujarat Urja Vikas Nigam Limited sustains technology leadership through early National Smart Grid Mission adoption and standardized procurement frameworks. The state's renewable purchase obligations exceed national thresholds, necessitating real-time grid balancing investments across high solar-penetration districts. Ahmedabad-Surat distribution zones deploy integrated platform contracts spanning metering, communication, and analytics layers.
Tamil Nadu
Tamil Nadu Generation and Distribution Corporation faces regulatory pressure from state tariff orders mandating AMI completion timelines ahead of national averages. The Tamil Nadu Electricity Regulatory Commission's time-of-day pricing pilots create immediate demand for demand response platforms among Chennai metropolitan commercial consumers. Industrial clusters in Coimbatore-Tiruppur deploy private microgrids with embedded metering to manage peak tariff penalties.
Rajasthan
Rajasthan Rajya Vidyut Prasaran Nigam Limited navigates extreme renewable intermittency through accelerated distribution automation procurement. The Rajasthan Electricity Regulatory Commission's compressed AMI rollout mandates coincide with high solar-wind penetration requiring grid stability investments. Jaipur-Udaipur distribution circles prioritize predictive asset health monitoring for renewable integration zones.
Karnataka
Bangalore Electricity Supply Company Limited leverages Smart Cities Mission jurisdiction for greenfield smart grid deployments without legacy technical debt. Karnataka's renewable energy policy exceeds national RPO thresholds, forcing real-time balancing technology procurement across the Bangalore-Tumkur industrial belt. The state's engineering institute partnerships anchor distribution management system R&D collaborations with technology vendors.
India Smart Grid Network Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform providers capturing consolidated procurement contracts while component specialists defend niche communication and analytics layers. The vendor structure stratifies around three archetypes: technology conglomerates with end-to-end smart grid portfolios, communication infrastructure specialists with edge-to-cloud architectures, and software-defined analytics platforms with subscription revenue models. Competitive positioning sharpens through two dominant moves: vendor consolidation around single-contract accountability requirements and outcome-based delivery restructuring that shifts risk from utilities to suppliers.
Within the technology conglomerate tier, General Electric Company, Siemens AG, and Cisco Systems Inc. exemplify integrated platform positioning across Indian state discom procurement cycles. General Electric anchors utility modernization contracts through digital twin portfolio extensions. Siemens sustains distribution management system leadership via deep R&D partnerships with Indian engineering institutes. Cisco dominates communication network layers, extending edge-to-cloud architecture into substation automation deployments across Maharashtra and Gujarat utilities.
| Leading Market Players |
|---|
| General Electric Company |
| Accenture PLC |
| Siemens AG |
| Power Grid Corporation of India Limited |
| HCL Technologies Ltd. |
| Schneider Electric SE |
| Cisco Systems Inc. |
| Honeywell International Inc. |
| ABB Ltd |
| Others |
Supply & Pricing Matrix
Compressed AMI rollout timelines under Tamil Nadu and Rajasthan state tariff orders force vendors to absorb BIS certification costs and restructure contracts around outcome-based delivery, squeezing margins on hardware while elevating subscription-based analytics pricing power.
Pricing Analysis
Distributor margins on communication network hardware compress under copper and semiconductor input volatility, while direct-to-utility contracts for grid analytics platforms command premium pricing through SaaS-tiered models. Three-tier pricing structure across premium, standard, and economy levels differentiates by BIS certification grade and after-sales service bundling. Cost compression in metering equipment intensifies because state discoms consolidate procurement around single-contract accountability. Industrial microgrid operators show least price sensitivity; residential segments under Smart Cities Mission jurisdiction exhibit highest.
Supply Chain Analysis
Regional distribution centers in Maharashtra and Gujarat anchor hub-and-spoke patterns for substation automation hardware, with secondary nodes in Tamil Nadu and Rajasthan accelerating under compressed regulator mandates. Manufacturing concentrates in China, South Korea, and domestic Indian facilities for communication chipsets, with copper cabling sourced from Chile and Zambia. Single-source vulnerability in semiconductor fabrication for protection signaling equipment elevates supply risk. Distribution runs through state discom procurement consortia and EPC contractor networks for integrated platform deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India Smart Grid Network Market functions as a regulatory compounder where CEA standards harmonization and state-level AMI mandates continuously refresh procurement cycles across state electricity distribution companies.
For Market Incumbents: Cement technology leadership through deep R&D partnerships with Indian engineering institutes for distribution management system advancement, insulating against software-defined analytics entrants. Lock in multi-year managed network service contracts with Maharashtra and Gujarat utilities to convert hardware sales into recurring revenue streams.
For New Entrants and Emerging Players: Capture white-space in Rajasthan and Tamil Nadu demand response platforms where state tariff orders mandate time-of-day pricing pilots ahead of national timelines. Target industrial microgrid investments in Coimbatore-Tiruppur and Bangalore-Tumkur belts with embedded metering solutions. Lead with edge-to-cloud architecture partnerships rather than component sales.
For Investors and Strategic Acquirers: Asymmetric upside sits with grid analytics specialists possessing IEC 61850 compliance track records and established BIS certification pathways. Long-term viability over the projection horizon hinges on subscription revenue models displacing capital-intensive system purchases. Monitor discom financial restructuring milestones under the Revamped Distribution Sector Scheme as inflection indicators for deferred procurement unlocking.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates vendor relationships across metering, communication, and analytics layers for Tamil Nadu utilities. |
| Backward Integration | Captures margin on semiconductor and copper inputs amid supply volatility for communication network hardware. |
| Strategic Partnership | Anchors distribution management system R&D through Indian engineering institute collaborations. |
| Geographic Expansion | Penetrates Rajasthan and Karnataka regulatory jurisdictions with accelerated AMI rollout mandates. |
| Acquisition of Specialist Firm | Absorbs predictive asset health algorithm capabilities for grid analytics convergence with AMI data streams. |
Research Methodology
Coverage spans Maharashtra, Gujarat, Tamil Nadu, Rajasthan, and Karnataka, with primary inputs from each combining interviews with utility planning officers, EPC contractors, state regulatory commission staff, and technology vendor account managers alongside secondary validation through CEA smart grid standards documentation, state electricity regulatory tariff orders, BIS certification records, and project development databases. Bottom-up and top-down triangulation reconciles discom procurement pipeline data with national mission spending allocations.
Granularity-level modeling disaggregates the analysis window by technology deployment risk profile, end-user financial capacity tier, solution software-versus-hardware composition, and installation legacy-versus-greenfield status. CAGRs derive from utility capital expenditure cycle recovery trajectories under central government financial restructuring schemes and state-level renewable purchase obligation enforcement patterns. Forecast inputs incorporate IEC 61850 protocol migration timelines and BIS cybersecurity certification completion rates.
Underlying measurement precision varies by segment; Advanced Metering Infrastructure and Distribution Management Systems carry tighter precision than Demand Response Solutions where pilot-scale deployment creates higher variance. Forecasts reflect documented assumptions around discom balance sheet recovery and regulator mandate enforcement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Asia-Pacific Demand Response Management Systems Market
Smart Grid
South and Central America Smart Grid Market
Smart Grid
Global Smart Grid Networking Market
Smart Grid
North America Automated Demand Response Management System Market
Smart Grid
Smart Grid Technology Market
Smart Grid
Global Self-Healing Grid Market
Smart Grid
Europe Microgrid Market
Smart Grid
Automated Demand Response Management Systems Market
Smart Grid
Middle-East Smart Grid Network Market
Smart Grid
Smart Energy Switch Market
Smart Grid
South Korea Smart Grid Network Market
Smart Grid
North America Smart Grid Market
Smart Grid
United Kingdom Smart Grid Market
Smart Grid
Smart Water Grid Market
Smart Grid
Smart Grid Adoption Market
Smart Grid
Smart Demand Response Market