
 Smart Grid Network Market | 2026-2036
Smart Grid Network Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Grid Network Market Analytics
ISO/IEC 61968 interoperability certification is collapsing the supplier base for utility-scale deployments, as only vendors with demonstrated CIM-compliant middleware can qualify for major tenders. Siemens AG leverages its end-to-end digital grid portfolio to dominate European transmission modernization programs. ABB Group anchors its position through in-house production of high-voltage switchgear integrated with SCADA layers. Schneider Electric SE differentiates via deep specialization in demand response orchestration software for commercial and industrial loads.
A smart grid network constitutes a digitally instrumented electrical infrastructure that uses two-way communication protocols, synchrophasor measurement units with sub-second sampling rates, and automated control systems to balance generation with fluctuating load patterns in real time. Its primary purpose is to reduce technical losses, integrate variable renewable sources, and restore service autonomously after fault events. Advanced Metering Infrastructure currently occupies the largest technology spend pool as utilities replace electromechanical meters with IP-enabled endpoints. Demand Response is recording the fastest uptake among segments because grid operators require flexible load resources to offset intermittency from wind and solar assets. Distribution Management Systems retain the highest margin concentration since these platforms require continuous software customization and utility-specific algorithm tuning.
FERC Order 2222 in the United States mandates regional grid operators to allow aggregated distributed energy resources into wholesale markets, directly expanding addressable demand for distributed control platforms. The EU Green Deal and F-Gas Regulation together enforce accelerated transformer upgrades and SF6-phaseout timelines that channel procurement toward digitally monitored substation equipment. Grid operators and technology vendors must monitor how cybersecurity standards from NERC CIP and IEC 62351 evolve, as compliance thresholds for critical infrastructure protection are tightening faster than product development cycles can absorb.
Market Dynamics
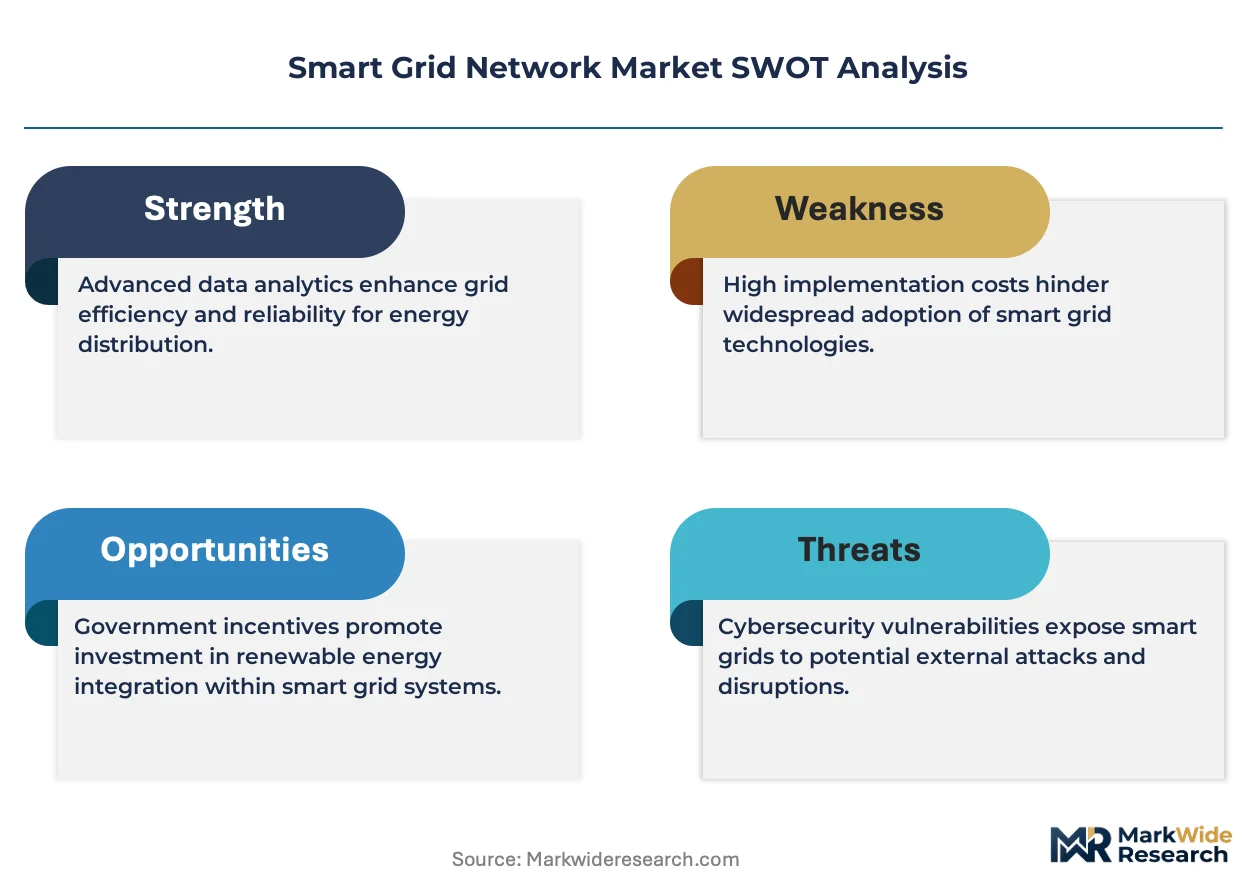
Grid operators face mounting pressure to absorb distributed solar and wind assets while maintaining voltage stability, forcing capital allocation toward real-time control platforms and substation automation. The shift from centralized dispatch to edge-orchestrated networks is compressing procurement timelines for utilities.
Growth Catalysts
- FERC Order 2222:US regional transmission organizations must now clear aggregated distributed energy resources into wholesale markets, opening revenue streams for battery and EV fleet operators.
- AMI replacement cycles:German utilities are retiring first-generation smart meters installed under the 2012 Messstellenbetriebsgesetz, triggering hardware refresh demand.
- SF6 phaseout mandates:The EU F-Gas Regulation is accelerating procurement of digitally monitored gas-insulated switchgear with alternative insulation mediums.
Market Restraints
- Copper and rare earth volatility:Transformer and cable manufacturers face margin compression from commodity price swings in lithium and neodymium supply chains.
- Semiconductor foundry concentration:Power electronics and PMU chipsets rely on concentrated East Asian fabrication capacity, creating single-source vulnerability.
- Interoperability certification bottlenecks:ISO/IEC 61968 CIM compliance testing delays vendor qualification by 8-14 months, throttling deployment velocity.
Strategic Opportunities
- India rural electrification gaps:The country's Smart Meter National Programme targets 250 million residential endpoints, creating demand for low-cost RF mesh networks.
- Vehicle-to-grid convergence:Bidirectional charging infrastructure integrates EV batteries as dispatchable storage assets for frequency regulation services.
- EU Green Deal funding windows:Recovery and Resilience Facility allocations for grid modernization are channeling procurement toward digital substation retrofits.
Industry Challenges
- Cybersecurity workforce scarcity:NERC CIP compliance requires specialized industrial control security expertise that utilities cannot source at scale.
- Legacy SCADA integration friction:Proprietary protocols in existing distribution management systems obstruct API-based interoperability with cloud-native platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Grid Network Market |
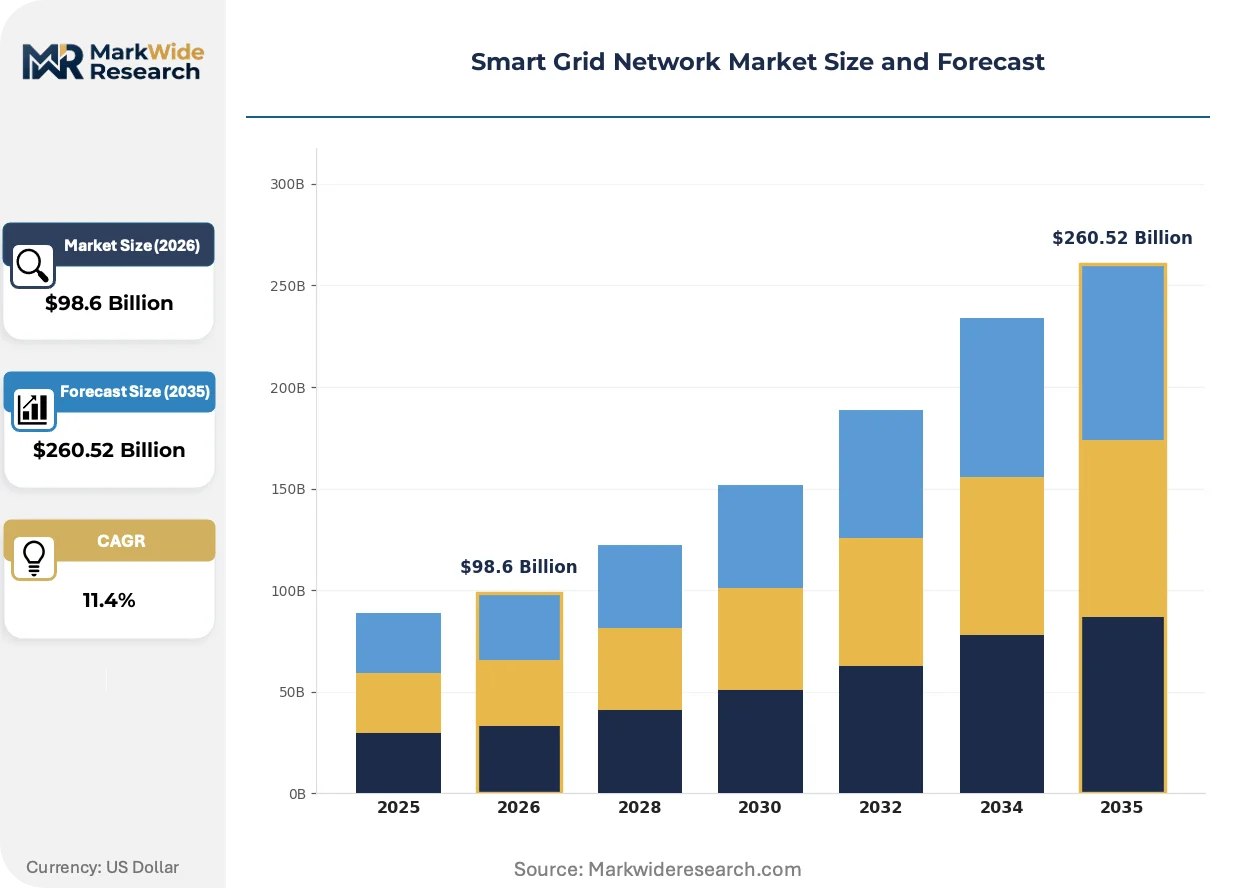
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $260.52 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Advanced Metering Infrastructure, Demand Response, Distribution Management Systems, Supervisory Control and Data Acquisition End User: Utilities, Industrial Sector, Commercial Sector, Residential Sector Solution: Energy Management Systems, Home Automation Systems, Demand Side Management, Microgrid Solutions Installation: On-Premises, Cloud-Based, Hybrid, Remote |
| Companies Covered | Siemens AG, ABB Group, Schneider Electric SE, General Electric Company, Itron Inc., Honeywell International Inc., Cisco Systems Inc., Eaton Corporation plc, Landis+Gyr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Grid Network Market Evolving Landscape
Digital architectures are fragmenting traditional vendor lock-in patterns as open-source middleware and containerized applications gain traction in utility IT departments. Control functions are migrating from centralized data centers toward edge nodes.
Synchrophasor measurement units with sub-second sampling rates are decomposing the traditional separation between transmission and distribution operations. Grid operators in Texas and California are deploying PMU networks to detect angular instability before cascading failures propagate. This visibility layer is compressing the market for conventional fault-detection relays by exposing their latency limitations.
The EU Green Deal's F-Gas Regulation is accelerating transformer replacement schedules across member states by banning sulfur hexafluoride in new medium-voltage equipment. Manufacturers are pivoting toward vacuum interrupters and solid insulation designs. German TSOs are absorbing the capital cost premiums through accelerated depreciation mechanisms.
Commercial and industrial load operators are unbundling demand response services from bundled utility tariffs, contracting directly with aggregators for price-responsive curtailment. Data centers in Virginia and manufacturing clusters in Ohio are negotiating interruptible rate structures with independent DR providers. This disintermediation is eroding the traditional utility monopoly over flexible capacity procurement.
Smart Grid Network Market Segmentation
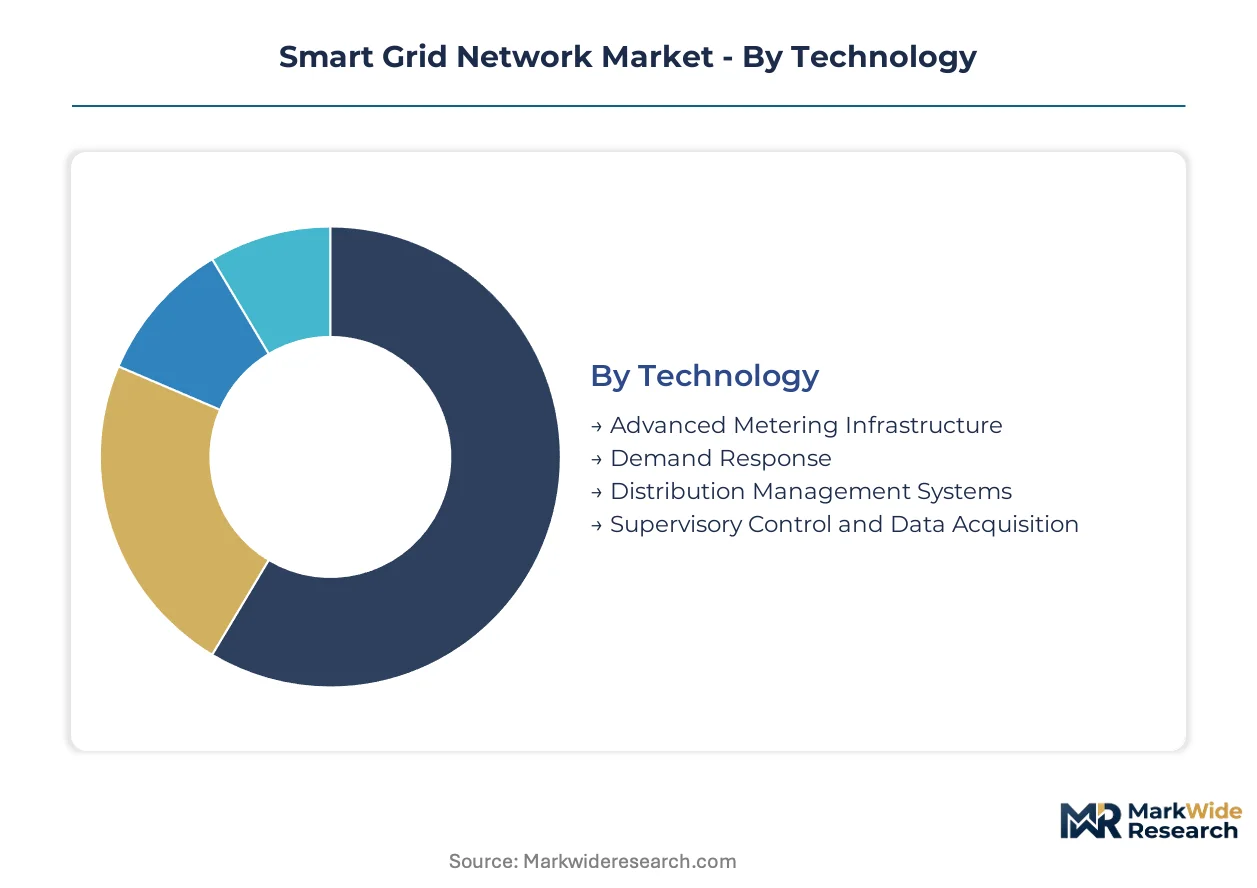
Smart grid procurement patterns diverge sharply across technology layers, end-use requirements, and deployment architectures. Vendors must align portfolio investments with where utility capital plans concentrate versus where emerging revenue pools form.
Technology:
Margin concentration varies substantially across the technology stack, with software-intensive platforms commanding premium pricing over hardware-centric deployments.
- Advanced Metering Infrastructure:IP-enabled meter endpoints with integrated RF mesh or cellular backhaul form the physical data layer for consumption visibility. German utilities under the Messstellenbetriebsgesetz replacement cycle and India's Smart Meter National Programme are absorbing the largest hardware volumes, though margin compression from commoditized meter manufacturing is forcing vendors toward data analytics overlays.
- Demand Response:Aggregated load curtailment platforms with real-time telemetry interfaces to wholesale market operators capture the steepest expansion trajectory. FERC Order 2222 compliance requirements in the United States are accelerating procurement of distributed control systems that can bid EV fleets and battery assets into frequency regulation markets.
- Distribution Management Systems:SCADA-integrated outage management and voltage optimization software requiring continuous algorithm customization.
- Supervisory Control and Data Acquisition:Industrial-grade control networks with hardened cybersecurity profiles per NERC CIP standards.
The dominant share belongs to Advanced Metering Infrastructure, while Demand Response is closing the gap fastest.
End User:
Customer scale determines procurement complexity, with large integrated utilities driving standardization versus fragmented smaller buyers requiring configurable solutions.
- Utilities:Vertically integrated transmission and distribution operators with centralized procurement functions and multi-year capital planning horizons. European TSOs under EU Green Deal funding windows and U.S. investor-owned utilities responding to state renewable portfolio standards are channeling investment toward substation automation and digital retrofit programs.
- Industrial Sector:Energy-intensive manufacturing and data center operators with on-site generation assets and interruptible rate structures. Ohio manufacturing clusters and Virginia hyperscale data centers are contracting directly with demand response aggregators, bypassing traditional utility intermediaries for flexible capacity procurement.
- Commercial Sector:Mid-scale facility operators with building management system integration requirements.
- Residential Sector:Distributed endpoints targeted by mass-market AMI deployments and home automation pilots.
Utilities retain the largest absolute spend, though Industrial Sector procurement is expanding most quickly.
Solution:
Functional integration depth separates premium platforms from point solutions, with cross-system orchestration commanding higher pricing.
- Energy Management Systems:Enterprise-grade software platforms with predictive analytics and automated dispatch algorithms. German industrial complexes and U.S. federal facilities are deploying integrated EMS layers that coordinate on-site solar, battery storage, and building loads against real-time tariff signals.
- Home Automation Systems:Consumer-facing interfaces with smart thermostat and appliance control capabilities. California's Title 24 building efficiency standards and similar mandates in New York are embedding HAS functionality into new construction compliance frameworks.
- Demand Side Management:Utility-directed load shaping programs with direct load control and time-of-use rate structures.
- Microgrid Solutions:Island-capable distributed generation clusters with seamless grid interconnection controls.
Energy Management Systems holds the revenue concentration, with Home Automation Systems gaining share fastest.
Installation:
Deployment architecture choices reflect cybersecurity risk tolerance and legacy system integration constraints.
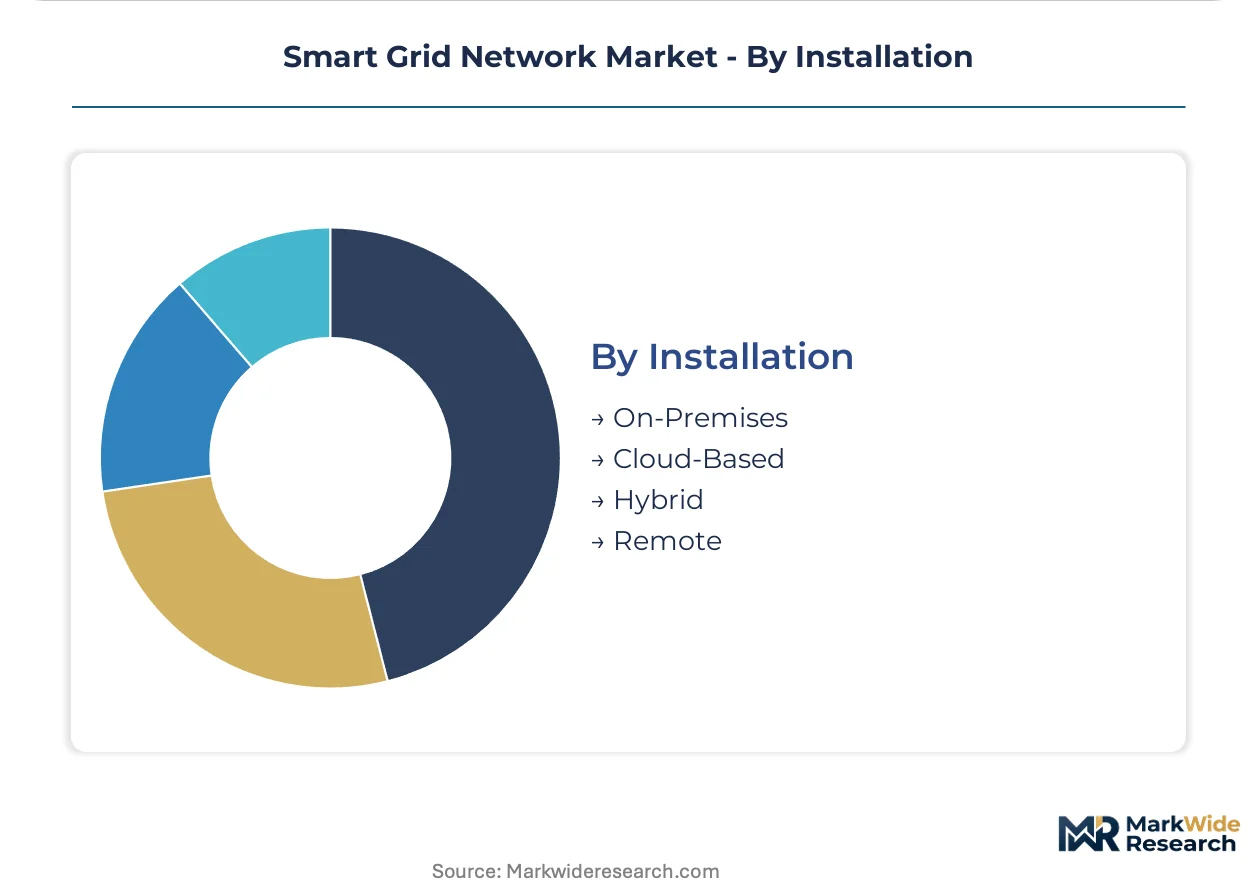
- On-Premises:Air-gapped control systems with physical security perimeters and localized data sovereignty. Critical infrastructure operators in Texas and California are maintaining on-premises SCADA deployments despite cloud migration pressure, citing NERC CIP compliance requirements and insurance underwriting conditions.
- Cloud-Based:SaaS-delivered analytics platforms with API-based integration to edge devices. Municipal utilities with limited IT staffing are adopting cloud-native distribution management systems to access enterprise-grade cybersecurity patching and scalability without capital-intensive data center builds.
- Hybrid:Split architectures with real-time control on-premises and analytics workloads in cloud environments.
- Remote:Satellite or cellular-connected monitoring for geographically dispersed assets.
On-Premises retains the largest installed base, while Cloud-Based deployments are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC Order 2222 and the EU Green Deal are redirecting utility capital toward distributed control platforms and digital substation retrofits. Procurement concentrates in Germany, the United States, China, India, and Japan as grid operators absorb renewable intermittency and replace aging electromechanical infrastructure.
United States
Regional transmission organizations under FERC Order 2222 must clear aggregated battery and EV fleet assets into wholesale frequency regulation markets. Texas and California grid operators are deploying synchrophasor measurement unit networks to detect angular instability before cascading failures propagate across their transmission interconnections.
Germany
Utilities are retiring first-generation smart meters installed under the 2012 Messstellenbetriebsgesetz, triggering hardware refresh demand for IP-enabled endpoints. The EU F-Gas Regulation is accelerating transformer replacement schedules by banning sulfur hexafluoride in new medium-voltage equipment, with German TSOs absorbing capital cost premiums through accelerated depreciation mechanisms.
China
Dual carbon goals under the national climate commitment are channeling state grid investment toward ultra-high voltage transmission corridors and distribution automation. Manufacturing clusters in Jiangsu and Zhejiang provinces are scaling production of digitally monitored gas-insulated switchgear with alternative insulation mediums to serve domestic and export demand.
India
The Smart Meter National Programme targets 250 million residential endpoints, creating demand for low-cost RF mesh networks in rural electrification gaps. State distribution companies in Maharashtra and Gujarat are piloting demand response aggregations for commercial and industrial loads under regulatory sandbox frameworks established by the Central Electricity Authority.
Japan
METI is directing investment toward grid-edge orchestration platforms to balance distributed solar penetration in Kyushu and Hokkaido. Tokyo Electric Power and regional utilities are procuring battery energy storage systems with sub-second response capabilities to manage frequency deviations from nuclear plant cycling and renewable intermittency.
Smart Grid Network Market Competitive Landscape
Player mix skews toward diversified electrical equipment conglomerates with captive software development capabilities. Market structure concentrates around vendors with demonstrated ISO/IEC 61968 interoperability certification, as CIM-compliant middleware qualification collapses the supplier base for utility-scale tenders. Two strategic archetypes dominate: end-to-end digital grid portfolio providers and specialized demand response orchestration software vendors. Competitive moves center on strategic partnerships for cloud-native platform integration and portfolio diversification into vehicle-to-grid bidirectional charging infrastructure.
Within the diversified conglomerate tier, Siemens AG and ABB Group represent the archetype of vertically integrated electrical equipment manufacturers with in-house high-voltage switchgear production. Schneider Electric SE exemplifies the specialization vector through its demand response orchestration focus for commercial and industrial load segments. These three entities occupy positions that mirror the technology segmentation of the market itself, anchoring competitive dynamics around software customization depth versus hardware manufacturing scale.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Group |
| Schneider Electric SE |
| General Electric Company |
| Itron Inc. |
| Honeywell International Inc. |
| Cisco Systems Inc. |
| Eaton Corporation plc |
| Landis+Gyr |
| Others |
Value Network & Pricing Analysis
SF6-to-vacuum insulation substitution in medium-voltage switchgear simultaneously relocates manufacturing gravity toward Jiangsu and Zhejiang provinces and compresses pricing premiums for gas-insulated equipment as Chinese producers scale solid-insulation alternatives.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO/IEC 61968 CIM-compliant middleware commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by cybersecurity hardening depth and after-sales service bundling. Cost compression in economy-tier AMI hardware is intensifying because meter manufacturing has commoditized. Municipal utilities with constrained capital budgets exhibit highest price sensitivity, while German TSOs under EU Green Deal funding windows show lowest.
Supply Chain Analysis
Port congestion on Shanghai-Rotterdam lanes elevates inbound logistics costs for European-bound switchgear and transformer shipments, forcing manufacturers to absorb carrying cost premiums or accelerate regional production footprints. Manufacturing concentrates in China, Germany, and the United States for high-voltage equipment and switchgear assemblies. Semiconductor foundry capacity in Taiwan and South Korea feeds power electronics and PMU chipset demand. Single-source vulnerability in rare earth processing creates structural exposure to neodymium and lithium supply disruptions. Distribution runs through utility-direct procurement channels and EPC contractor intermediaries for large-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated German TSOs and U.S. regional transmission organizations with multi-year capital planning horizons, fragmenting vendor pricing leverage across fewer procurement counter-parties.
For Market Incumbents: Compound defensive positioning through captive software development capabilities and ISO/IEC 61968 certification maintenance. Deepen backward integration into high-voltage switchgear production to offset margin compression from commodity-linked transformer costs. Prioritize NERC CIP compliance investment as cybersecurity workforce scarcity threatens implementation timelines.
For New Entrants and Emerging Players: Differentiate on cloud-native distribution management system architectures with API-based interoperability. Target India's Smart Meter National Programme rural electrification gaps with low-cost RF mesh network solutions. Pursue vehicle-to-grid bidirectional charging infrastructure partnerships as the most penetrable white-space segment.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized demand response orchestration software vendors with demonstrated FERC Order 2222 compliance capabilities. Long-term viability over the coming decade rests on regulatory alignment with distributed energy resource aggregation mandates. Monitor NERC CIP enforcement intensity as the critical inflection signal for cybersecurity service demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Switchgear Manufacturing | German TSOs absorb capital premiums through accelerated depreciation under EU F-Gas Regulation timelines. |
| ISO/IEC 61968 Certification Investment | CIM-compliant middleware qualification collapses supplier bases for major European transmission tenders. |
| Cloud-Native Platform Development | Municipal utilities adopt SaaS-delivered analytics to bypass capital-intensive data center builds. |
| Vehicle-to-Grid Infrastructure Partnership | Bidirectional charging integrates EV batteries as dispatchable assets for Texas and California frequency regulation markets. |
| Cybersecurity Workforce Expansion | NERC CIP compliance requirements outpace available industrial control security expertise across North American utilities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FERC filings, EIA project databases, EU Recovery and Resilience Facility allocation records, and IEA grid investment reports. Utility planning officers, IPP project developers, EPC contractors, and grid operators provided operational perspectives on procurement timelines and technology adoption constraints. Bottom-up segment sizing triangulates against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled include technology layer, end-user scale, solution integration depth, and deployment architecture across the projection horizon. CAGRs derive from installed base replacement cycles, regulatory mandate enforcement schedules, and renewable penetration trajectories. Forecast inputs incorporate AMI replacement wave timing under Germany's Messstellenbetriebsgesetz and India's Smart Meter National Programme deployment velocity.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal funding availability or FERC Order 2222 enforcement consistency would require recalibration. Forecasts reflect assumptions regarding semiconductor supply normalization and rare earth price stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Microgrid Controller Market
Smart Grid
Europe Smart Grid Network Market
Smart Grid
Saudi Arabia Smart Grid Market
Smart Grid
Europe Smart Grid Security Market
Smart Grid
Asia-Pacific Smart Grid Network Market
Smart Grid
China Smart Grid Network Market
Smart Grid
Smart Microgrid Market
Smart Grid
Smart Grid Adoption Market
Smart Grid
AC Grid Connected Microgrid Market
Smart Grid
Europe Automated Demand Response Market
Smart Grid
United States Smart Grid Security Market
Smart Grid
South and Central America Smart Grid Market
Smart Grid
Asia-Pacific Demand Response Management Systems Market
Smart Grid
Smart Microgrid Controller Market
Smart Grid
Smart Grid Home Area Network (HAN) Market
Smart Grid
South Korea Smart Grid Network Market