
 Smart Grid Technology Market | 2026-2036
Smart Grid Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Grid Technology Market Insights
Capital-intensity divergence between full-stack platform providers and component specialists is rotating competitive dynamics across the smart grid value chain. General Electric Company leverages its Predix platform and turbine-generator heritage to dominate utility-scale grid management software. ABB sustains leadership in digital substations and power electronics through deep manufacturing scale across Europe and Asia. Cisco Systems anchors communication network layers, competing on cybersecurity-hardened IoT architectures that utilities increasingly mandate.
Smart grid technology encompasses digitally enabled electrical infrastructure integrating advanced sensing, two-way communication, and automated control systems to optimize electricity generation, distribution, and consumption across voltage classes from low-voltage residential to extra-high-voltage transmission. Its primary industrial purpose centers on reducing technical losses, enabling renewable intermittency management, and deferring capital-intensive peaking capacity investments. Software and communication networks command expanding margin pools as utilities shift from hardware-centric procurement to subscription-based analytics and managed services. Demand response technology grows fastest among technology segments, driven by wholesale market reforms and distributed energy resource aggregation platforms. Smart meters remain the most mature component category, with replacement cycles now driving volume in North American and European installed bases.
The US Federal Energy Regulatory Commission shapes interstate transmission planning and cost allocation rules that directly determine smart grid investment recovery timelines. State-level public utility commissions across California, New York, and Texas enforce renewable portfolio standards and grid reliability mandates that accelerate AMI and energy storage procurement. The European Union's F-Gas Regulation and CE marking requirements constrain switchgear specifications, pushing manufacturers toward SF6-free alternatives. Stakeholders must monitor how evolving cybersecurity standards from NERC CIP and emerging state data privacy frameworks reshape product certification burdens and vendor qualification criteria.
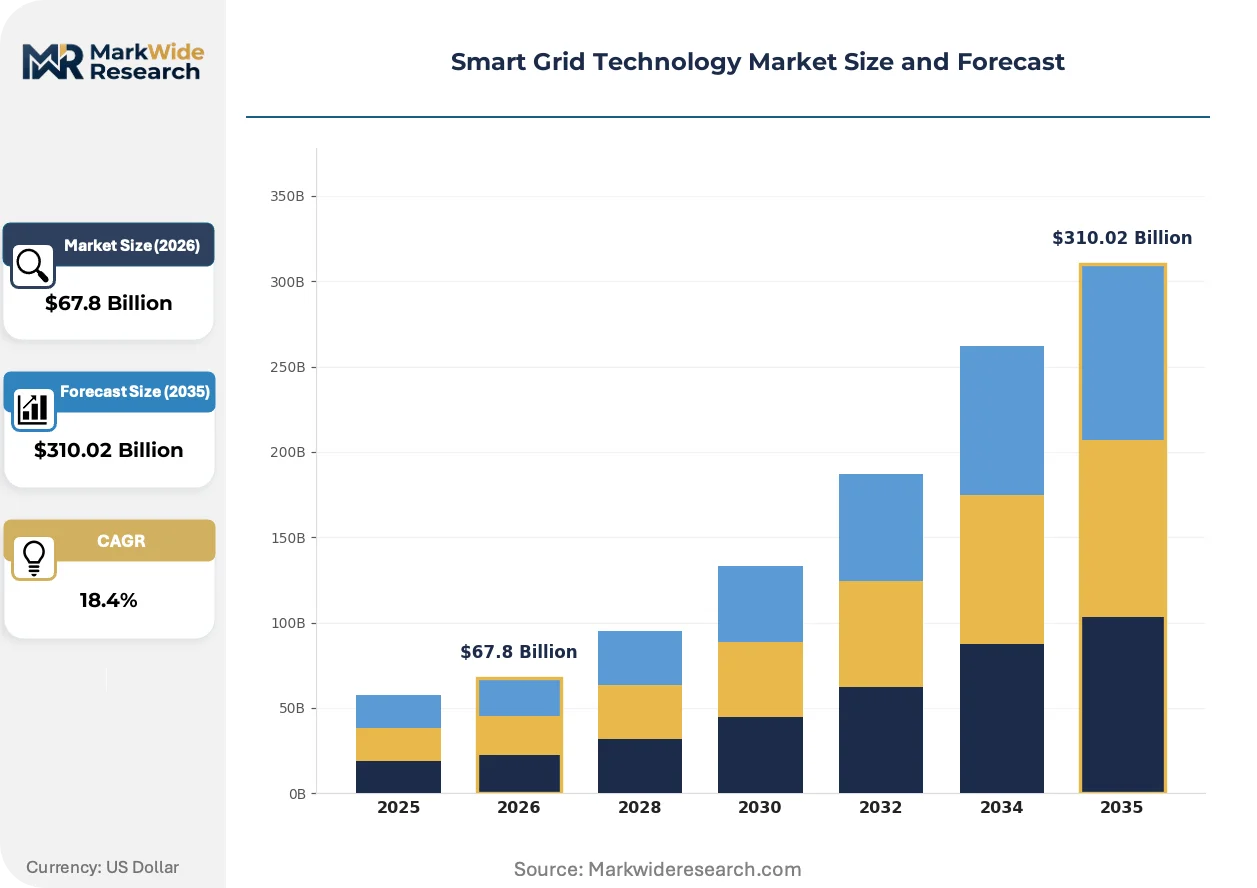
Market Dynamics
Intermittency management requirements from distributed solar and wind assets are forcing utilities to reconfigure control architectures, migrating from centralized SCADA toward edge-computing nodes that process telemetry locally before upstream transmission.
Growth Catalysts
- Inflation Reduction Act provisions:The US IRA channels direct investment tax credits toward grid modernization, accelerating AMI and energy storage procurement timelines for investor-owned utilities.
- China's dual carbon targets:State Grid Corporation mandates digital substation retrofits and ultra-high voltage transmission corridors to accommodate renewable generation from western provinces.
- Wholesale market reforms:FERC Order 2222 enables distributed energy resource aggregation platforms, creating revenue streams for demand response technology vendors.
Market Restraints
- Semiconductor supply concentration:Power electronics and sensor modules depend on fabrication capacity concentrated in Taiwan and South Korea, exposing AMI rollout schedules to foundry allocation volatility.
- SF6 switchgear phaseout:The EU F-Gas Regulation imposes strict emissions quotas on sulfur hexafluoride, forcing manufacturers to redesign gas-insulated switchgear around vacuum interruption or fluoronitrile alternatives.
- Utility capex cycles:Rate-base recovery timelines stretch 5-8 years in many US jurisdictions, compressing near-term procurement volumes despite long-term replacement needs.
Strategic Opportunities
- India's rural electrification gaps:The country's national smart grid mission targets microgrid deployment across unelectrified districts, opening demand for modular AMI and distributed control systems.
- Vehicle-to-grid convergence:Bidirectional charging infrastructure creates new revenue pools for aggregators managing EV battery dispatch against wholesale price signals.
- Cybersecurity certification tailwinds:NERC CIP Version 7 mandates expand vendor qualification criteria, favoring specialists with hardened IoT architectures over commodity hardware suppliers.
Industry Challenges
- Legacy protocol fragmentation:Utilities operate multi-vendor environments spanning DNP3, IEC 61850, and proprietary fieldbus implementations, complicating unified analytics deployment.
- Field engineering scarcity:Substations and distribution automation require technicians trained in both power systems and IT networking, a skill intersection with limited pipeline capacity.
- Interoperability certification delays:Multi-vendor integration testing for digital substation projects extends project timelines by 12-18 months beyond hardware delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Grid Technology Market |
| Market Size in 2026 | $67.8 Billion |
| Market Size in 2035 | $310.02 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Smart Meters, Sensors, Communication Networks, Software Technology: Automated Metering Infrastructure, Demand Response, Distributed Generation, Energy Storage Application: Energy Management, Grid Automation, Smart Lighting, Electric Vehicle Integration End User: Utilities, Government, Industrial, Residential |
| Companies Covered | General Electric Company, ABB, Siemens Energy, Schneider Electric, Itron, Honeywell International, Cisco Systems, Eaton Corporation, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Grid Technology Market Trends and Innovations
Software-defined control architectures are displacing hardware-centric protection relays, compressing substation footprints while enabling remote firmware updates that extend asset lifecycles without truck rolls.
Edge intelligence platforms process feeder telemetry locally, reducing latency for fault location and isolation while minimizing backhaul bandwidth costs. Mid-sized municipal utilities in Germany and California are deploying these systems fastest, driven by renewable hosting capacity constraints. This distributed architecture is displacing centralized SCADA as the default control paradigm for distribution networks with high distributed energy resource penetration.
The EU F-Gas Regulation tightens sulfur hexafluoride emissions quotas through 2030, compelling switchgear manufacturers to accelerate vacuum interruption and clean air insulation development. Industrial consequence includes extended product validation cycles and retooling of European assembly facilities. Medium-voltage primary switchgear categories face the steepest compliance burden, with ABB and Siemens prioritizing SF6-free portfolio transitions for German and Nordic utility tenders.
Subscription-based analytics contracts are replacing perpetual software licenses across North American investor-owned utilities, unbundling hardware procurement from ongoing algorithm access. Channel disruption concentrates in grid management software, where AWS and Azure cloud instances host third-party applications that utilities consume via annual SaaS agreements. Texas and California utilities lead this transition, driven by regulatory pressure to demonstrate operational expenditure efficiency in rate cases.
Smart Grid Technology Market Segmentation
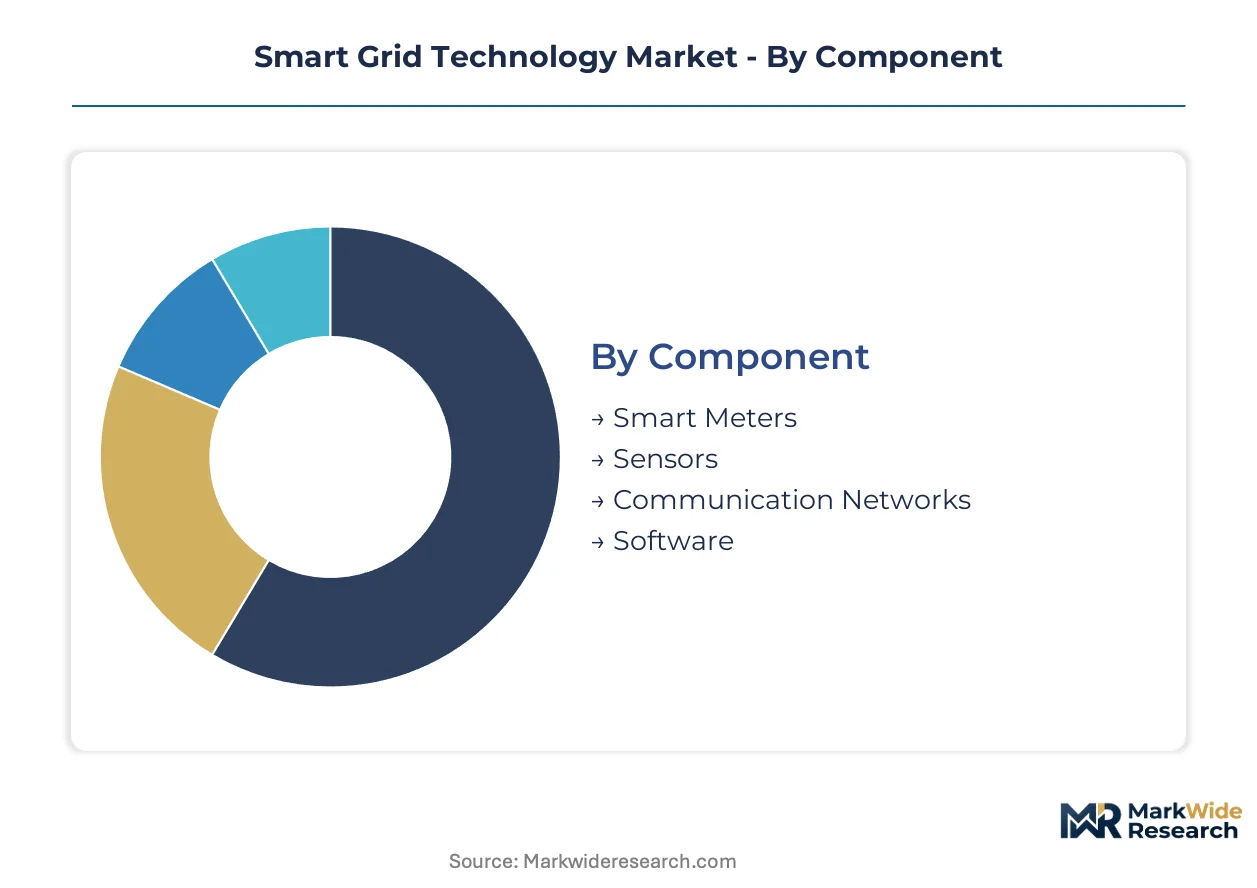
Smart grid technology procurement patterns diverge sharply across component types, technology maturity, and end-user sophistication. Regulatory mandates from FERC, State Grid Corporation, and EU F-Gas Regulation reshape which segments command capital allocation priority.
Component:
FERC Order 2222 and EU cybersecurity frameworks differentiate procurement standards across hardware versus software categories, with NERC CIP Version 7 imposing distinct certification burdens on communication network vendors.
- Smart Meters:Two-way communication endpoints measuring consumption intervals and enabling remote disconnect. North American utilities concentrate replacement demand as first-generation AMI systems reach end-of-life, with California IOUs and Texas cooperatives driving volume.
- Sensors:Voltage, current, and temperature monitoring devices deployed across distribution feeders and transformers. German and California utilities deploy phasor measurement units fastest to manage renewable intermittency, constrained by semiconductor supply allocation from Taiwan and South Korea.
- Communication Networks:Fiber, cellular, and RF mesh infrastructure connecting field devices to control centers.
- Software:Grid management platforms, analytics engines, and DER aggregation applications.
Established volume favors Smart Meters; emerging adoption favors Software.
Technology:
Cost tier differentiation separates mature infrastructure deployments from emerging revenue-generating platforms, with subscription-based models displacing capital-intensive hardware procurement.
- Automated Metering Infrastructure:Integrated systems combining meters, communication networks, and data management platforms. Investor-owned utilities in Texas and New York concentrate deployment to satisfy regulatory audit requirements and reduce non-technical losses.
- Demand Response:Load curtailment and shifting programs aggregating distributed resources for wholesale market participation. FERC Order 2222 enables aggregation platforms across US organized markets, with California ISO and PJM Interconnection creating revenue streams for technology vendors.
- Distributed Generation:Solar, wind, and combined heat and power integration at distribution voltage levels.
- Energy Storage:Battery systems providing frequency regulation, peak shaving, and backup power services.
Maturity concentration favors Automated Metering Infrastructure; policy tailwinds favor Demand Response.
Application:
Customer type fragmentation separates municipal utilities prioritizing operational expenditure efficiency from investor-owned utilities defending rate-base growth.
- Energy Management:Consumption optimization platforms for commercial and industrial facilities. German manufacturing clusters and California data center operators concentrate demand to manage time-of-use tariff exposure and sustainability reporting obligations.
- Grid Automation:Self-healing distribution networks with automated fault location, isolation, and restoration. State Grid Corporation mandates digital substation retrofits across western China provinces to accommodate renewable generation from Xinjiang and Gansu.
- Smart Lighting:Networked streetlight controls with dimming and outage detection capabilities.
- Electric Vehicle Integration:Bidirectional charging infrastructure and managed charging platforms.
Utility procurement favors Grid Automation; emerging mobility electrification favors Electric Vehicle Integration.
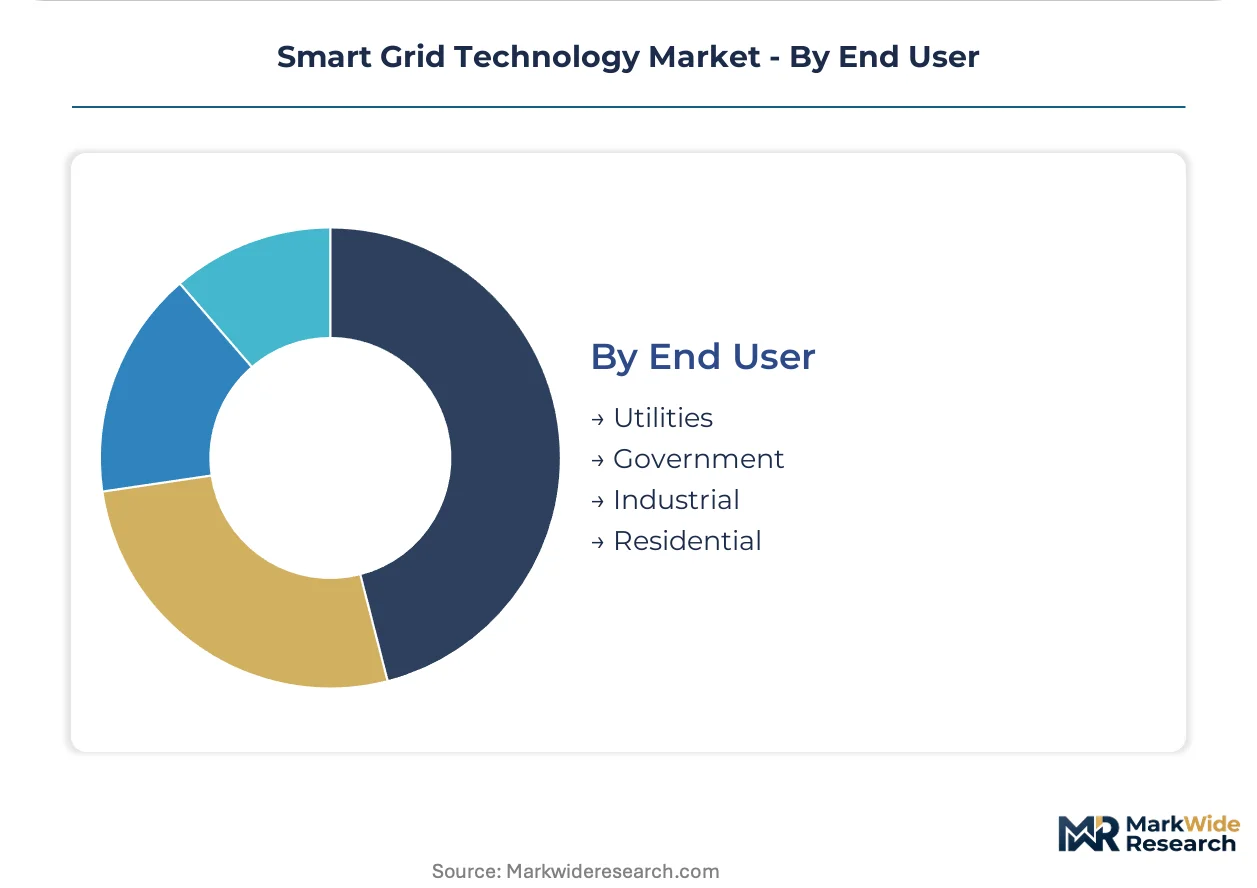
End User:
Volume concentration reflects rate-base recovery mechanisms, with regulatory lag compressing near-term procurement from cost-of-service utilities.
- Utilities:Investor-owned, municipal, and cooperative electricity providers. US IOUs concentrate AMI and energy storage procurement to capture IRA investment tax credits, while European utilities prioritize SF6-free switchgear to satisfy F-Gas Regulation quotas.
- Government:Federal, state, and municipal agencies funding demonstration projects and rural electrification. India's national smart grid mission targets microgrid deployment across unelectrified districts in Bihar and Uttar Pradesh.
- Industrial:Manufacturing, mining, and petrochemical facilities with captive generation and high reliability requirements.
- Residential:Single-family and multi-family dwellings with rooftop solar, battery storage, and smart appliances.
Rate-base scale favors Utilities; grant-funded deployment favors Government.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. US utilities prioritize demand response platforms and AMI replacements, while Chinese State Grid Corporation concentrates investment on ultra-high voltage transmission and digital substations at unprecedented scale.
United States
Investor-owned utilities in Texas and California drive AMI replacement cycles and energy storage procurement to capture IRA investment tax credits. FERC Order 2222 enables distributed energy resource aggregation platforms across organized wholesale markets. The PJM Interconnection territory concentrates demand response technology deployment.
China
State Grid Corporation mandates massive digital substation retrofits and ultra-high voltage corridors to transmit renewable generation from western provinces. The country's dual carbon targets compress deployment timelines for grid automation infrastructure. Xinjiang and Gansu provinces host the highest concentration of renewable integration projects.
Germany
Manufacturing clusters and municipal utilities deploy phasor measurement units fastest to manage renewable intermittency constraints. The EU F-Gas Regulation imposes strict SF6 emissions quotas, forcing switchgear manufacturers toward vacuum interruption alternatives. Bavarian and Baden-Württemberg utilities lead SF6-free procurement.
India
The national smart grid mission targets microgrid deployment across unelectrified districts in Bihar and Uttar Pradesh. Rural electrification gaps create demand for modular AMI and distributed control systems. Telangana and Gujarat concentrate pilot projects for distributed generation integration.
Japan
Tokyo Electric Power and regional utilities invest in grid automation to accommodate distributed solar penetration and earthquake resilience requirements. METI policies encourage demand response participation in wholesale capacity markets. The Kanto region concentrates smart meter deployment and EV charging infrastructure.
Smart Grid Technology Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. Full-stack platform providers compete on utility-scale software integration and turbine-generator heritage. Component specialists defend position through manufacturing scale in power electronics and switchgear. Dominant competitive moves include portfolio diversification into SF6-free alternatives and strategic partnerships for edge-computing architectures.
Within the integrated platform tier, General Electric Company and ABB occupy anchor positions representing divergent competitive strategies. Cisco Systems exemplifies the communication infrastructure specialist archetype. These three entities collectively illustrate how vendor qualification criteria under NERC CIP Version 7 and EU cybersecurity frameworks reshape competitive positioning across hardware and software categories.
| Leading Market Players |
|---|
| General Electric Company |
| ABB |
| Siemens Energy |
| Schneider Electric |
| Itron |
| Honeywell International |
| Cisco Systems |
| Eaton Corporation |
| IBM |
| Others |
Pricing and Supply Chain Analysis
NERC CIP Version 7 certification gates both vendor qualification and price differentiation simultaneously, forcing utilities to pay premiums for cybersecurity-hardened architectures while excluding commodity hardware suppliers from rate-base recovery eligibility. This regulatory filter compresses margins for uncertified tiers while concentrating pricing power among compliant full-stack providers.
Pricing Analysis
Long-term subscription contracts dominate utility procurement, displacing perpetual software licenses with annual SaaS agreements that bundle algorithm access with cloud hosting. Price differentiation rests on cybersecurity certification tier and deployment scale, with municipal utilities exhibiting highest price sensitivity due to constrained operational expenditure budgets. Cost compression in communication network hardware is intensifying because semiconductor allocation volatility from Taiwan and South Korea foundries pressures component costs. Investor-owned utilities show lowest price sensitivity, prioritizing rate-base growth and IRA tax credit capture over upfront cost minimization.
Supply Chain Analysis
Taiwan Strait transit risk underwrites supply vulnerability for power electronics and sensor modules that feed AMI and digital substation deployments. Manufacturing concentrates in Taiwan, South Korea, and Germany for semiconductors and precision switchgear components. Raw material dependencies span rare earth elements for magnetics, high-purity silicon for sensors, and copper for power distribution. Single-source vulnerability concentrates in advanced node fabrication for grid-edge processors. Distribution runs through authorized utility channel partners with NERC CIP qualification rather than open market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates switching costs that lock utilities into multi-decade vendor relationships. Certification burdens and rate-base recovery timelines erect barriers that protect incumbent positions.
For Market Incumbents: Shield installed base relationships through backward integration into SF6-free switchgear manufacturing and edge-computing firmware development. Emerging cybersecurity mandates from state data privacy frameworks threaten commodity hardware suppliers most severely. Prioritize certification investment for NERC CIP Version 7 compliance to maintain rate-base eligibility. For New Entrants and Emerging Players: Subscription analytics under-service in mid-sized municipal utilities creates white-space opportunity where incumbents focus on investor-owned utility scale. India's rural electrification gaps offer most penetrable geography for modular AMI and microgrid control systems. Pursue partnership-based go-to-market with established channel partners holding existing utility relationships rather than direct sales buildout. For Investors and Strategic Acquirers: FERC Order 2222 implementation reshapes the acquisition landscape by validating revenue models for distributed energy resource aggregation platforms. Five-to-ten year viability favors specialists with hardened IoT architectures over hardware-centric component vendors. Signal to monitor: state-level data privacy framework proliferation that expands certification burdens beyond federal NERC CIP requirements.| Strategic Initiative | Industry Significance |
|---|---|
| SF6-Free Switchgear Transition | EU F-Gas Regulation compliance secures German and Nordic utility tender eligibility for ABB and Siemens. |
| Edge-Computing Architecture Partnership | Cisco Systems anchors communication layers through cybersecurity-hardened IoT platform integration with municipal utilities. |
| Subscription Analytics Platform Launch | AWS and Azure cloud instances host third-party grid management applications consumed via annual SaaS agreements. |
| Digital Substation Retrofit Scale-Up | State Grid Corporation mandates accelerate demand for ABB and General Electric utility-scale software integration. |
| Microgrid Deployment Joint Venture | India's national smart grid mission opens modular AMI demand across Bihar and Uttar Pradesh electrification gaps. |
Research Methodology
A standing panel of utility planning officers, grid operators, EPC contractors, and IPP project developers provided ongoing calibration across primary interview rounds. Secondary validation drew from FERC filings, EIA data, IEA reports, and project development databases. Bottom-up unit economics triangulated against top-down regulatory mandate tracking.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include component type, technology maturity tier, application function, and end-user regulatory framework. CAGRs were derived from utility capex cycle analysis and rate-base recovery timeline projections. Forecast inputs incorporated renewable intermittency management requirements and wholesale market reform implementation schedules.
Underlying assumptions cover IRA tax credit continuity and semiconductor supply normalization, with deviation risk concentrated in foundry allocation volatility and EU F-Gas Regulation enforcement intensity. Practitioners should keep alternative scenarios live as state-level cybersecurity frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
United Arab Emirates Smart Grid Market
Smart Grid
North America Automated Demand Response Management System Market
Smart Grid
Smart Microgrid Market
Smart Grid
Smart Demand Response Market
Smart Grid
Europe Smart Grid Security Market
Smart Grid
Smart Grid Communications Market
Smart Grid
Smart Grid Adoption Market
Smart Grid
South Africa Smart Grid Market
Smart Grid
Smart Grid Data Management Market
Smart Grid
Middle-East Smart Grid Network Market
Smart Grid
Renewable Energy Integration with Smart Grid Market
Smart Grid
Power Grid Market
Smart Grid
Smart Microgrid Controller Market
Smart Grid
Smart Water Grid Market
Smart Grid
China Smart Grid Network Market
Smart Grid
Europe Microgrid Market