
 Latin America Smart Grid Security Market | 2026-2036
Latin America Smart Grid Security Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Smart Grid Security Market Intelligence
Cloud-native security architecture is fragmenting legacy on-premises deployments across Latin American utilities. Siemens AG leverages deep SCADA integration to anchor large-scale contracts in Brazil and Mexico. Schneider Electric SE competes through edge-computing security stacks purpose-built for tropical climate resilience. WEG S.A. dominates domestically manufactured hardware, extending its control over utility procurement channels in its home market.
Latin America smart grid security encompasses cryptographic protection, access control, and threat monitoring systems engineered to safeguard digital electricity infrastructure against cyber intrusion and operational disruption. These systems typically operate across IEC 61850 and IEEE 2030 communication protocols, with latency requirements under 100 milliseconds for real-time substation protection. Encryption and intrusion detection technologies lead current deployment spending, while cloud and hybrid deployment models are expanding fastest as utilities seek operational flexibility without full infrastructure overhaul. Services and software components capture expanding margin pools as recurring subscription models replace perpetual licensing across the region's fragmented utility base.
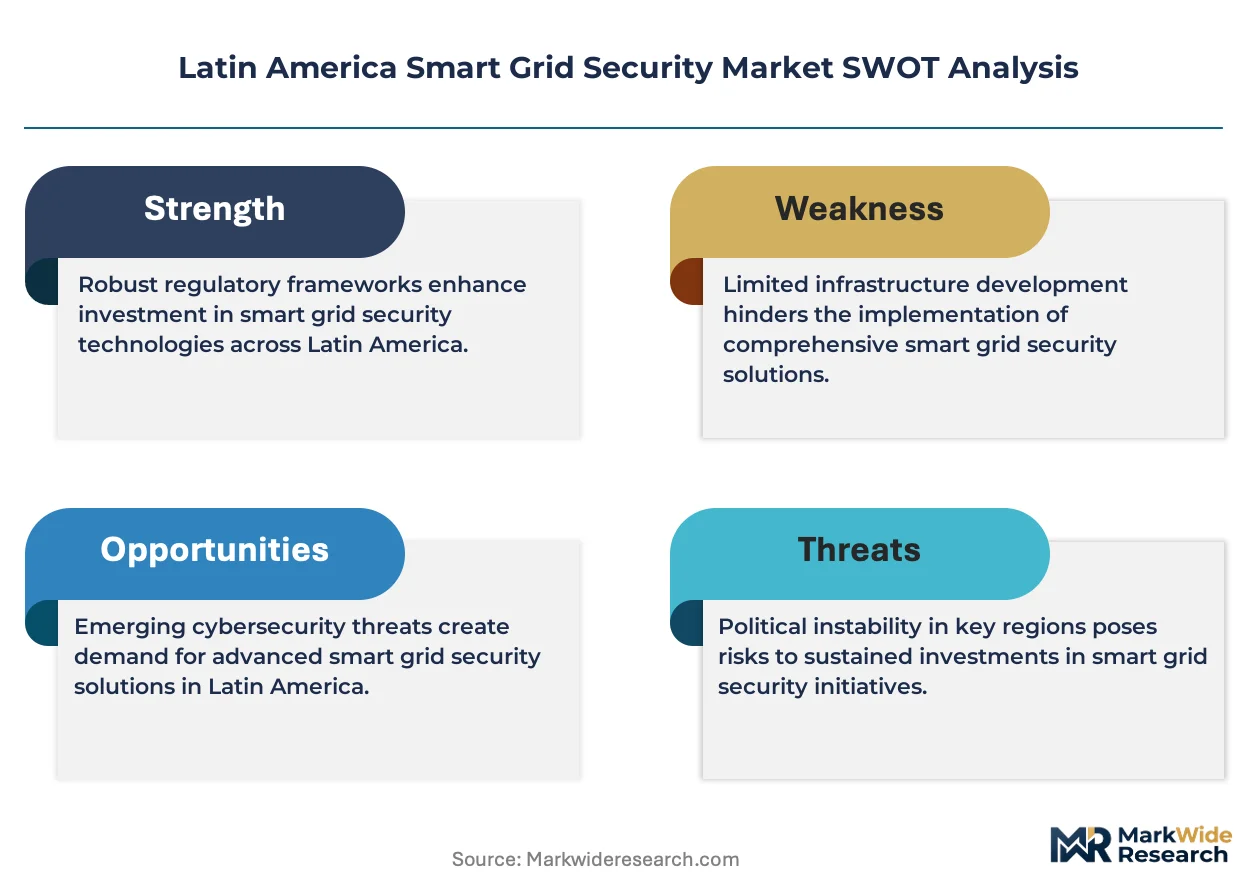
Brazil's ANEEL mandates and Mexico's national cybersecurity strategy shape procurement standards, compelling utilities to certify systems against evolving critical infrastructure requirements. Argentina's ENRE and Chile's SEC are developing parallel frameworks, tightening market access for uncertified vendors. Stakeholders must monitor regulatory divergence across national boundaries, as compliance fragmentation will determine which technology architectures achieve scalable deployment across the region's heterogeneous grid environments.
Market Dynamics
Cloud-native security architecture is fragmenting legacy on-premises deployments across Latin American utilities, forcing vendors to rearchitect delivery models around subscription-based platforms rather than perpetual hardware sales.
Growth Catalysts
- ANEEL Mandates:Brazil's national electric energy regulator requires encryption and intrusion detection upgrades across critical substations, compelling utilities to accelerate procurement cycles for certified security systems.
- AMI Deployments:Advanced metering infrastructure rollouts in Mexico's Comisión Federal de Electricidad service territory generate endpoint security demand that scales with meter density.
- Tropical Climate Engineering:Edge-computing security stacks purpose-built for humidity and temperature extremes unlock deployment in previously inaccessible Amazon basin and Caribbean coastal zones.
Market Restraints
- Import Dependency:Specialized cryptographic hardware concentrates in East Asian fabrication facilities, exposing Latin American utilities to extended lead times and currency volatility.
- Certification Fragmentation:Divergent national cybersecurity frameworks across Brazil, Mexico, Argentina and Chile force vendors to maintain parallel compliance tracks, inflating development overhead.
- Legacy Protocol Inertia:Extensive installed base of DNP3 and Modbus systems without native encryption creates technical debt that slows full-stack security modernization.
Strategic Opportunities
- Colombia's Grid Modernization:Underpenetrated Andean markets present first-mover advantages as the national grid operator initiates smart meter pilots without entrenched incumbent relationships.
- Hybrid Deployment Models:Convergence of on-premises SCADA with cloud-based analytics allows utilities to phase capital expenditure while capturing operational flexibility benefits.
- SEC Framework Alignment:Chile's Superintendencia de Electricidad y Combustibles is developing cybersecurity standards harmonized with IEC 62351, creating regulatory tailwind for pre-certified vendors.
Industry Challenges
- Cybersecurity Talent Scarcity:Industrial control system security expertise remains concentrated in São Paulo and Mexico City, leaving regional utilities dependent on remote support contracts.
- Integration Complexity:Multi-vendor substation environments require protocol gateway development that extends deployment timelines and strains project management capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Smart Grid Security Market |
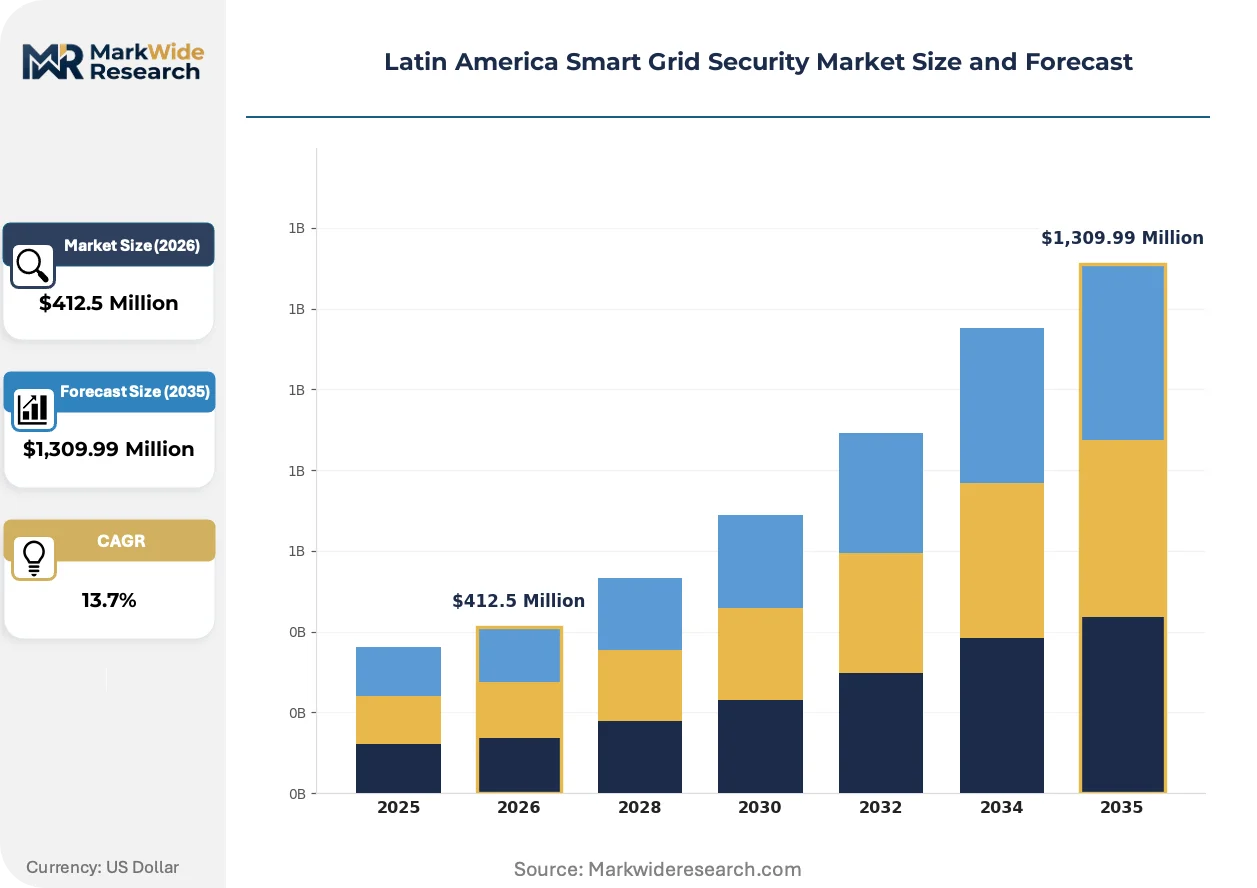
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,309.99 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Encryption, Authentication, Intrusion Detection, Firewall End User: Utilities, Energy Providers, Government Agencies, Industrial Users Component: Hardware, Software, Services, Network Infrastructure Deployment: On-Premises, Cloud, Hybrid, Edge |
| Companies Covered | Siemens AG, Schneider Electric SE, ABB Ltd, General Electric Company, Hitachi Energy, WEG S.A., Enel Group, Honeywell International Inc., Itron Inc., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Smart Grid Security Market Strategic Shifts & Innovations
Security delivery models are pivoting from capital-intensive hardware installations toward software-defined architectures that decouple functionality from physical infrastructure location.
Zero-trust network segmentation is hybridizing operational technology environments across Brazilian utility corridors. This architecture enforces continuous verification for every device and user session accessing substation control systems. State-owned distributors in São Paulo and Minas Gerais are piloting microsegmentation at transmission-distribution interfaces. The technology is hybridizing procurement patterns by enabling utilities to purchase security-as-a-service rather than owning full stack infrastructure.
Brazil's ANEEL Resolution 1000 establishes mandatory cybersecurity certification for critical infrastructure operators, with compliance deadlines phased through 2027. The regulation mandates third-party penetration testing and incident response planning that exceeds previous voluntary standards. Southeastern utility clusters are responding by consolidating vendor relationships around integrated platform providers capable of end-to-end certification support.
Subscription-based security monitoring is displacing perpetual licensing across fragmented municipal and cooperative utilities. These smaller operators lack capital budgets for upfront security infrastructure but require continuous threat intelligence feeds. The shift is most visible in Brazil's interior states where regional electricity cooperatives dominate distribution and where managed security service providers are establishing localized operations centers.
Latin America Smart Grid Security Market Segmentation
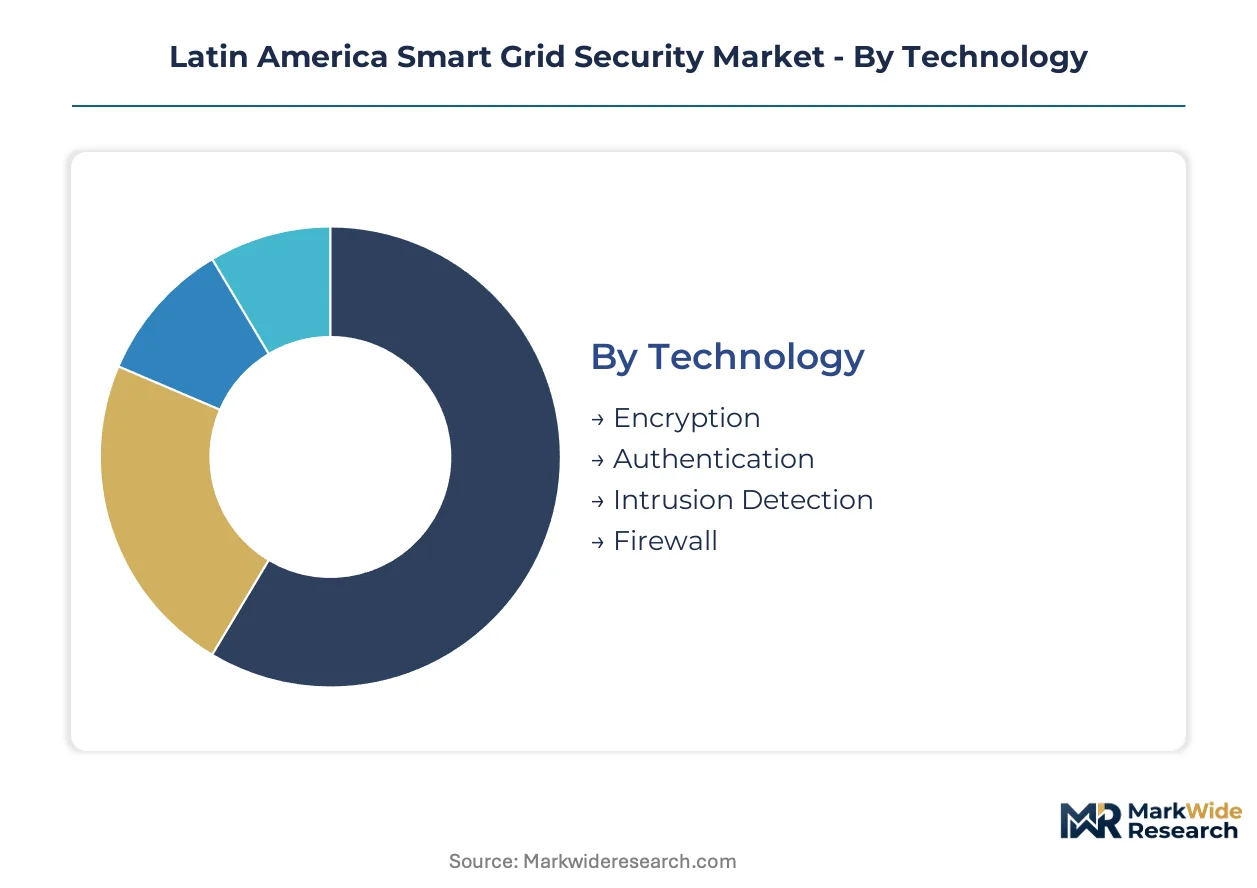
Smart grid security procurement in Latin America fragments across technology maturity, operational requirements, and infrastructure legacy. Understanding these segment boundaries clarifies why encryption and intrusion detection dominate current spending while cloud deployment models capture expanding share.
Technology:
Mature cryptographic protocols anchor established utility budgets, while emerging AI-driven detection layers reshape procurement priorities.
- Encryption:Advanced cryptographic modules protect data transmission across IEC 61850 and DNP3 protocols. Brazilian utilities in the southeastern corridor prioritize AES-256 implementations for critical substation links under ANEEL compliance deadlines.
- Intrusion Detection:Network behavior analysis systems monitor SCADA traffic for anomalous patterns. Mexico's Comisión Federal de Electricidad deploys these at AMI aggregation points where endpoint density creates attack surface expansion.
- Authentication:Multi-factor identity verification for field technicians and remote operators.
- Firewall:Perimeter defense systems segmenting operational technology from enterprise IT networks.
Encryption handles the majority of throughput; intrusion detection is expanding most quickly as utilities confront advanced persistent threat campaigns.
End User:
Customer type determines procurement scale, with state-backed distributors commanding multi-year deployment schedules against fragmented cooperative purchasing patterns.
- Utilities:State-owned and municipal distribution companies operate the region's largest security modernization programs. These entities consolidate vendor relationships around integrated platform providers capable of end-to-end certification support across Brazil's southeastern clusters.
- Energy Providers:Independent power producers and transmission operators with specialized generation assets. Chilean generators along the SIC and SING grids invest in substation hardening as SEC cybersecurity frameworks mature.
- Government Agencies:National regulators and critical infrastructure protection bodies mandating compliance standards.
- Industrial Users:Mining and manufacturing facilities with captive generation requiring grid interconnection security.
Utilities command the dominant procurement volume; energy providers are gaining share fastest as generation privatization accelerates security investment.
Component:
Margin concentration shifts from hardware ownership toward recurring software and service revenue streams.
- Hardware:Specialized security appliances including hardware security modules and ruggedized edge devices. Import dependency on East Asian fabrication creates procurement vulnerability for Brazilian utilities managing currency volatility.
- Software:License and subscription platforms for threat intelligence, policy management, and analytics. Regional electricity cooperatives in Brazil's interior states favor SaaS delivery to bypass capital budget constraints.
- Services:Managed security operations, penetration testing, and incident response retainers.
- Network Infrastructure:Secure communication backbones and protocol gateway installations.
Software is climbing the fastest on revenue share; hardware remains the foundation for initial deployment certification.
Deployment:
Infrastructure location choices balance latency requirements against operational flexibility and capital efficiency.
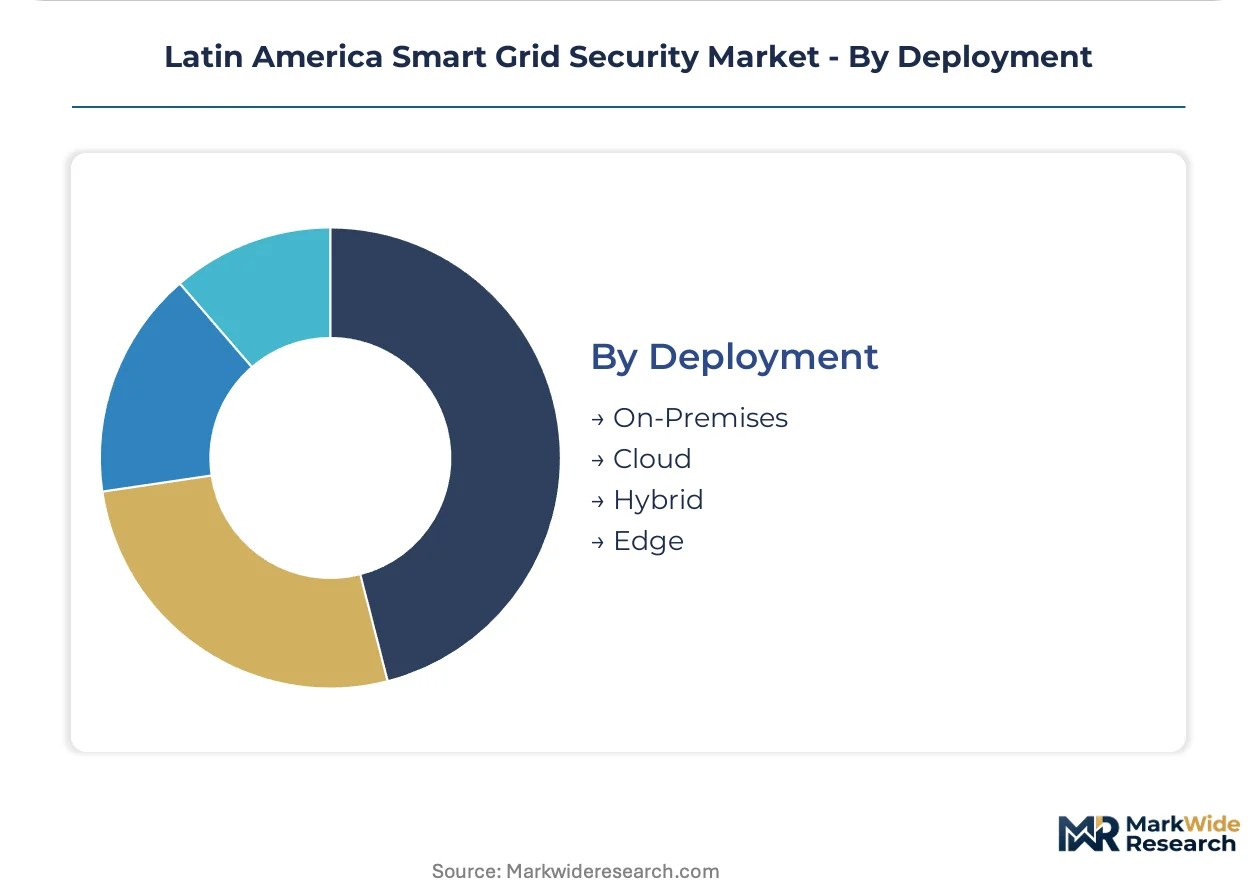
- On-Premises:Dedicated security infrastructure within utility control centers and substations. Legacy SCADA integration requirements keep this model dominant for real-time protection systems demanding sub-100 millisecond response.
- Cloud:Centralized security analytics and threat intelligence platforms hosted off-site. Mexican utilities pilot these for non-critical AMI data processing where latency tolerance permits remote computation.
- Hybrid:Split architectures preserving on-premises control while leveraging cloud analytics.
- Edge:Distributed processing at substation and meter levels for tropical climate zones.
On-premises retains the largest installed base; edge deployment shows the steepest expansion trajectory as Amazon basin and Caribbean coastal projects multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports smart grid security expertise and hardware into the Andean corridor, while Mexican system integrators supply Central American utilities with AMI security packages. This trade-flow pattern concentrates procurement budgets in southeastern Brazil and central Mexico, with secondary demand emerging from Chilean and Colombian grid modernization programs.
Brazil
ANEEL mandates drive encryption upgrades across state-owned distributors in São Paulo and Minas Gerais. The national electric energy regulator's Resolution 1000 mandates third-party penetration testing and incident response planning through 2027. The southeastern utility corridor consolidates vendor relationships around integrated platform providers capable of end-to-end certification support.
Mexico
Comisión Federal de Electricidad's AMI deployment generates endpoint security demand scaling with meter density in central and northern service territories. The national cybersecurity strategy shapes procurement standards for critical infrastructure operators. Mexico City Metro hosts regional operations centers for managed security service providers targeting cooperative utilities.
Chile
Superintendencia de Electricidad y Combustibles develops cybersecurity standards harmonized with IEC 62351, creating regulatory tailwind for pre-certified vendors. The SIC and SING grids attract substation hardening investment from privatized generators. Santiago anchors technical expertise clusters serving transmission-distribution interface projects.
Colombia
Underpenetrated Andean markets present first-mover advantages as the national grid operator initiates smart meter pilots without entrenched incumbent relationships. The country's mining sector drives captive generation security requirements for grid interconnection. Bogotá-based engineering firms broker technology partnerships between international vendors and regional electricity cooperatives.
Argentina
ENRE develops parallel cybersecurity frameworks tightening market access for uncertified vendors in Buenos Aires and surrounding provinces. Macroeconomic volatility compresses procurement timelines for capital-intensive hardware deployments. The federal capital retains concentration of industrial control system security expertise serving regional utilities.
Latin America Smart Grid Security Market Key Industry Players
Channel-controlling players compete with product-specialist players for procurement relationships with state-owned utilities and regional cooperatives. The market structure tilts toward integrated platform providers capable of spanning hardware certification, software delivery, and managed services under single contracting relationships. Three archetypes dominate: multinational industrial conglomerates with deep SCADA integration capabilities, regional specialists with tropical climate engineering expertise, and domestic manufacturers leveraging procurement channel control in home markets. Competitive moves concentrate on vendor consolidation around certification-capable platforms and geographic expansion into underpenetrated Andean markets.
Within the multinational tier, Siemens AG and Schneider Electric SE exemplify divergent technical positioning—Siemens anchoring large-scale contracts through SCADA integration depth, Schneider competing through edge-computing security stacks purpose-built for tropical climate resilience. WEG S.A. occupies the domestic manufacturer archetype, extending control over utility procurement channels in Brazil through locally manufactured hardware. These three companies represent the competitive vectors shaping regional procurement patterns: integration depth, environmental engineering specialization, and domestic channel control.
| Leading Market Players |
|---|
| Siemens AG |
| Schneider Electric SE |
| ABB Ltd |
| General Electric Company |
| Hitachi Energy |
| WEG S.A. |
| Enel Group |
| Honeywell International Inc. |
| Itron Inc. |
| Others |
Cost & Logistics Intelligence
East Asian cryptographic hardware fabrication concentrates supply-side leverage for encryption modules and hardware security modules, anchoring margin pools in subscription-based security software and managed services downstream. Brazilian utilities absorb currency volatility through phased procurement, while Mexican cooperatives bypass capital intensity via SaaS delivery models.
Pricing Analysis
Current-generation AES-256 encryption platforms command premium positioning against legacy DNP3 retrofit solutions and emerging quantum-resistant protocols still in pilot phase. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales service bundling. Pricing pressure stems from subscription displacement of perpetual licensing as regional cooperatives prioritize operational expenditure flexibility. Municipal utilities in Brazil's interior states exhibit highest price sensitivity; state-owned distributors in São Paulo and Minas Gerais tolerate premium positioning for integrated certification support.
Supply Chain Analysis
Contract manufacturing for specialized security appliances concentrates at Foxconn, Jabil, and Flex facilities across Taiwan, China, and Malaysia. Raw material dependencies span silicon wafers, rare earth magnets for ruggedized enclosures, and lithium-ion cells for edge device power backup. Single-source vulnerability in advanced cryptographic chip fabrication exposes Latin American utilities to extended lead times. Distribution runs through Siemens, Schneider Electric, and WEG S.A. channel networks with localized certification support capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as IEC 61850 interoperability standards enable multi-vendor substitution, fragmenting incumbent integration advantages. The ecosystem shift toward cloud-native security delivery rewards vendors with recurring revenue infrastructure over hardware-centric legacy players.
For Market Incumbents: Insulate certification relationships by embedding penetration testing and incident response capabilities directly into platform offerings. Threat substitution from edge-native specialists like Schneider Electric demands deeper SCADA integration investment. Channel control through localized operations centers in Mexico City and São Paulo remains the critical defensive lever against SaaS-native entrants. For New Entrants and Emerging Players: Colombia's underpenetrated Andean markets represent the most penetrable entry point for first-mover positioning without entrenched incumbent relationships. Brazil's regional electricity cooperatives in interior states offer white-space demand for managed security services with minimal capital budget requirements. Go-to-market execution should anchor on subscription pricing with embedded certification compliance to bypass lengthy procurement cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native security delivery as software margins displace hardware ownership economics. Long-term viability favors acquisition targets with established managed services infrastructure and recurring revenue concentration exceeding project-based deployment dependence. The signal to watch is ANEEL certification pipeline velocity as indicator of platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates vendor relationships around end-to-end IEC 61850 certification support for Brazilian utilities. |
| Geographic Expansion | Captures first-mover positioning in Colombia's smart meter pilots before incumbent channel lock-in. |
| Acquisition of Specialist Firm | Absorbs tropical climate engineering capabilities for Amazon basin and Caribbean coastal deployments. |
| Strategic Partnership | Aligns with Chile's SEC framework harmonization to accelerate pre-certified vendor status. |
| Product Launch | Introduces zero-trust microsegmentation for transmission-distribution interfaces in São Paulo corridor. |
Research Approach
A standing panel of utility cybersecurity officers, SCADA integration engineers, ANEEL compliance auditors, and managed security service directors provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation through ANEEL regulatory filings, Comisión Federal de Electricidad procurement disclosures, SEC cybersecurity risk disclosures, and IEC standards documentation. Bottom-up demand modeling triangulated against top-down market sizing across encryption, intrusion detection, and cloud deployment segments.
Scenario-bracketing framed analytical outputs across the projection horizon, with CAGRs derived from segmented adoption curves and infrastructure investment trajectories. Modeled dimensions span technology generation, deployment architecture, utility ownership type, and national regulatory framework cluster. Forecast inputs incorporated AMI rollout schedules, ANEEL Resolution 1000 compliance deadlines, and currency volatility assumptions for Brazilian real-denominated procurement.
Practitioners should monitor regulatory divergence across Brazil, Mexico, Argentina, and Chile for early signals of certification fragmentation or harmonization. Forecasts reflect assumptions about sustained encryption upgrade mandates and cloud migration willingness among cooperative utilities. Quarterly review of ANEEL enforcement patterns and SEC framework development velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Smart Water Grid Market
Smart Grid
Smart Grid Home Area Network (HAN) Market
Smart Grid
Asia-Pacific Demand Response Management Systems Market
Smart Grid
Asia-Pacific Smart Grid Network Market
Smart Grid
Europe Microgrid Market
Smart Grid
Smart Demand Response Market
Smart Grid
Saudi Arabia Smart Grid Network Market
Smart Grid
Europe Smart Grid Network Market
Smart Grid
Smart Grid Network Market
Smart Grid
North America Automated Demand Response Management System Market
Smart Grid
Middle-East Smart Grid Network Market
Smart Grid
Europe Smart Grid Security Market
Smart Grid
AC Grid Connected Microgrid Market
Smart Grid
South and Central America Smart Grid Market
Smart Grid
South Africa Smart Grid Network Market
Smart Grid
Smart Energy Switch Market