
 Saudi Arabia Smart Grid Market | 2026-2036
Saudi Arabia Smart Grid Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Smart Grid Market Insights
Industrial users are rotating toward active demand response participation as Saudi Electricity Company modernizes tariff structures. ABB Ltd leverages its substation automation portfolio to anchor large-scale utility deployments across the Kingdom. Schneider Electric differentiates through integrated cybersecurity and control solutions that protect critical infrastructure endpoints. Siemens AG dominates high-voltage grid digitization with hardware-software bundles tailored to desert climate extremes.
A smart grid denotes an electricity network incorporating digital communication, automated control systems, and sensor arrays to monitor power flows from generation through consumption in real time. These systems typically operate at 60 Hz with sub-second telemetry refresh rates, enabling fault isolation and self-healing capabilities that minimize outage duration. Advanced Metering Infrastructure leads technology adoption as utilities replace electromechanical meters with two-way communicating units capable of time-of-use pricing. Renewable Integration applications are expanding fastest as the Kingdom scales solar and wind capacity requiring grid-balancing services. On the solution side, Data Analytics commands emerging margin pools by converting petabytes of sensor streams into predictive maintenance schedules and load forecasts.
The Electricity and Cogeneration Regulatory Authority sets technical standards for grid interconnection and consumer data protection, while the National Cybersecurity Authority mandates encryption protocols for critical energy infrastructure. SFDA compliance requirements extend to hardware components with embedded software, creating a dual-track approval process for foreign equipment suppliers. Stakeholders must weigh localization commitments against technology transfer terms as procurement rules tighten.
Market Dynamics
Utilities across the Kingdom are consolidating procurement around integrated hardware-software platforms as Saudi Vision 2030 mandates accelerate grid digitization timelines. The Electricity and Cogeneration Regulatory Authority is tightening interconnection standards for distributed solar assets, forcing distribution network operators to prioritize automation investments that enable bidirectional power flows.
Growth Catalysts
- Advanced Metering Infrastructure:Distribution companies are replacing electromechanical meters with two-way communicating units capable of time-of-use pricing and remote disconnect functionality.
- Saudi Vision 2030:The national transformation program mandates renewable integration targets that require grid-balancing services and real-time telemetry infrastructure.
- Riyadh load centers:Industrial clustering around generation assets in the capital and Eastern Province concentrates demand for substation automation and predictive maintenance platforms.
Market Restraints
- Localization requirements:Procurement rules mandate domestic content thresholds that extend equipment delivery timelines for foreign suppliers lacking Saudi manufacturing partnerships.
- Semiconductor supply concentration:Power electronics and sensor components face input bottlenecks from concentrated East Asian foundry capacity.
- Cybersecurity certification:National Cybersecurity Authority encryption protocols for critical infrastructure create dual-track approval processes that delay deployment schedules.
Strategic Opportunities
- Eastern Province industrial zones:Petrochemical and desalination facilities present concentrated demand for microgrid controllers and islanding capabilities.
- Data Analytics convergence:Machine learning platforms processing sensor streams into predictive maintenance schedules command emerging margin pools beyond hardware sales.
- SFDA hardware compliance:Embedded software components in grid equipment trigger medical-device-grade approval pathways that create certification moats for prepared suppliers.
Industry Challenges
- SCADA-legacy integration:Greenfield digital platforms must interface with electromechanical protection systems installed during 1980s infrastructure buildouts.
- Specialized technician scarcity:Substation automation deployment outpaces vocational training pipeline output for relay configuration and fiber optic commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Smart Grid Market |
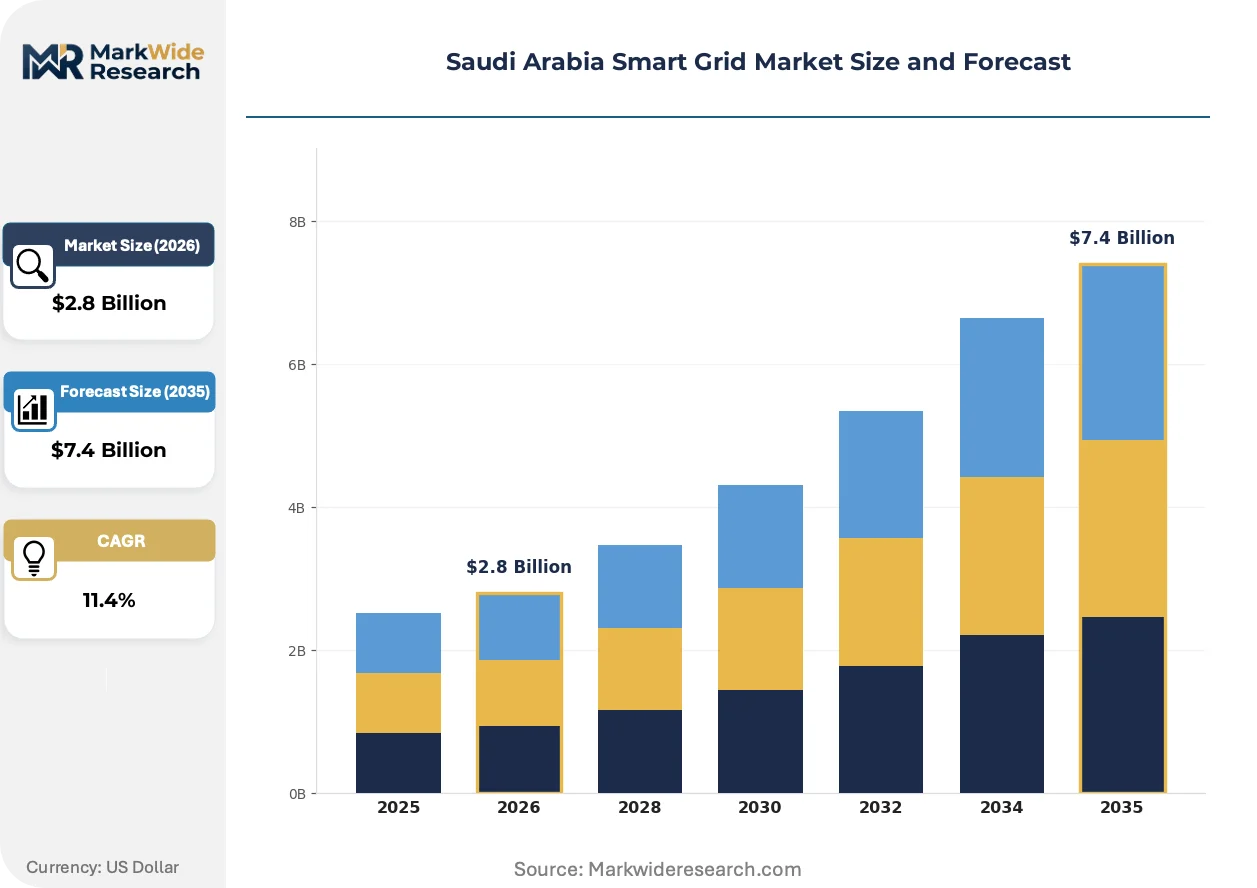
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Advanced Metering Infrastructure, Distribution Management System, Demand Response, SCADA Application: Energy Management, Renewable Integration, Grid Automation, Asset Management End User: Utilities, Industrial Users, Commercial Sector, Residential Consumers Solution: Monitoring Solutions, Control Solutions, Data Analytics, Cybersecurity |
| Companies Covered | Saudi Electricity Company, General Electric Company, ABB Ltd, Honeywell International Inc, Schneider Electric, Siemens AG, ACWA Power, CG Power and Industrial Solutions Ltd, Siemens Energy AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Smart Grid Market Trends and Innovations
Grid-edge intelligence is migrating from centralized control rooms to distributed sensor arrays as utilities prioritize millisecond fault isolation. The convergence of renewable intermittency and industrial load volatility is compressing telemetry refresh rate requirements across the Kingdom's transmission hierarchy.
Intelligent electronic relays are miniaturizing protection and control functions into single-housing units that replace traditional panel-mounted assemblies. Saudi Electricity Company is piloting these compact platforms at 132 kV substations in Riyadh. The footprint reduction is enabling retrofit installations within existing civil structures without switchyard expansion, compressing project timelines for urban density constraints.
Saudi Vision 2030 implementation frameworks are mandating renewable integration quotas that reshape procurement specifications for grid-stabilizing assets. The Electricity and Cogeneration Regulatory Authority now requires synchronous condenser capability or equivalent grid-forming inverters for utility-scale solar connections above 50 MW. Developer submissions for the National Renewable Energy Program are prioritizing vendors with demonstrated desert-climate inverter performance.
Industrial offtakers are unbundling after-sales service contracts from capital equipment purchases to secure multi-vendor maintenance flexibility. Large petrochemical complexes in Jubail are negotiating performance-based service agreements with independent commissioning specialists rather than OEM-locked long-term contracts. This procurement fragmentation is most visible in the Eastern Province where industrial load density supports third-party technician specialization.
Saudi Arabia Smart Grid Market Segmentation
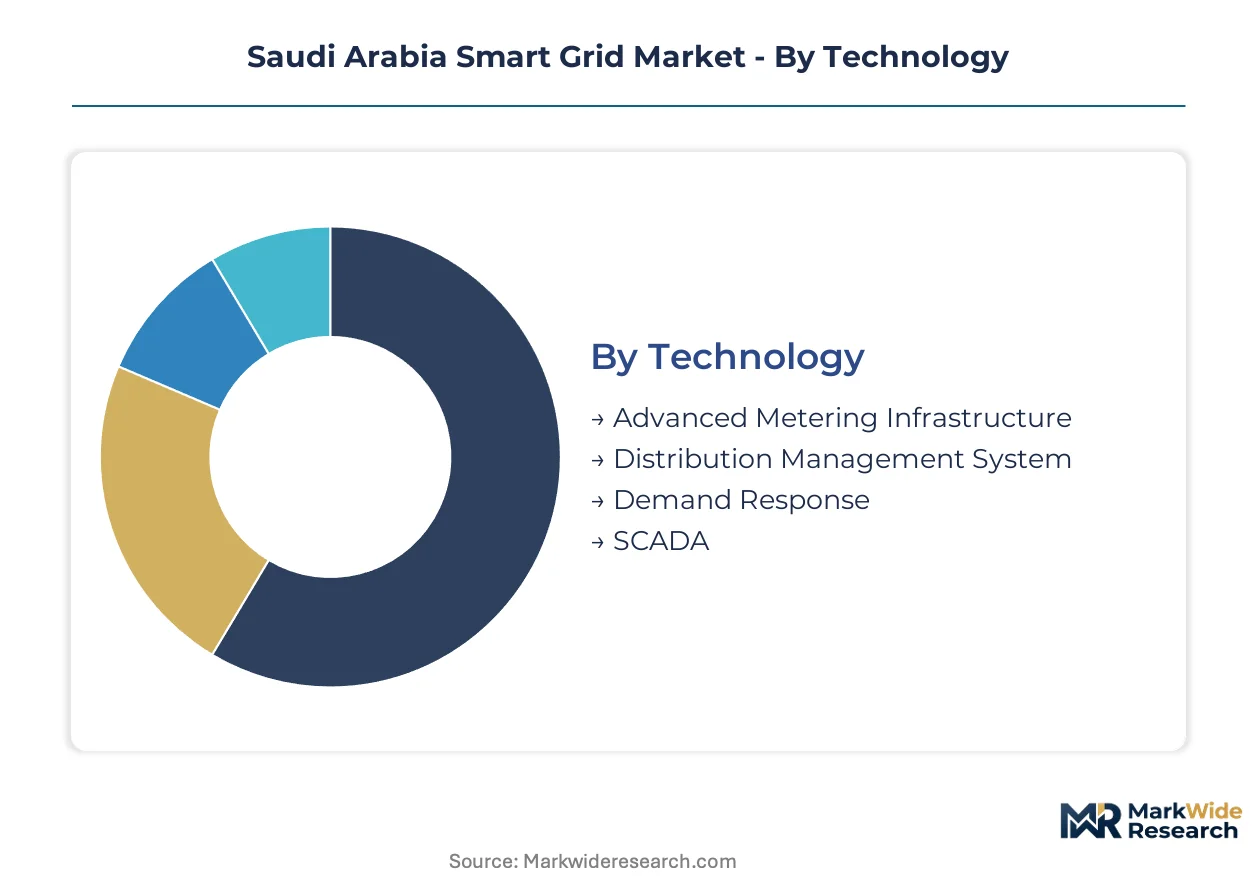
Saudi Arabia's smart grid market segments reflect distinct procurement channels and technical requirements shaped by Vision 2030 mandates. Each dimension captures different value capture points across hardware, software, and service layers.
Technology:
Channel mix varies sharply by technology maturity, with AMI flowing through distribution company tenders while SCADA upgrades route through transmission operator capital programs.
- Advanced Metering Infrastructure:Two-way communicating meter systems with remote disconnect and time-of-use pricing capabilities. Demand concentrates in Riyadh and Eastern Province distribution networks where Saudi Electricity Company is replacing electromechanical units under accelerated procurement schedules.
- Distribution Management System:Real-time outage management and feeder automation platforms integrating SCADA, GIS, and customer information systems. Industrial load centers in Jubail and Yanbu are driving adoption as petrochemical facilities require voltage stability guarantees.
- Demand Response:Load curtailment and shifting systems enabling industrial participation in grid balancing services.
- SCADA:Supervisory control and data acquisition systems for transmission and generation monitoring.
AMI dominates installed base. Distribution Management System is where expansion concentrates.
Application:
Margin structures diverge by application, with Grid Automation commanding premium pricing for desert-hardened equipment while Energy Management competes on software licensing models.
- Energy Management:Consumption optimization platforms for commercial and industrial facilities integrating building automation with utility pricing signals.
- Renewable Integration:Grid-forming inverters, synchronous condensers, and energy management systems for solar and wind connection compliance. The National Renewable Energy Program is scaling fastest here as developers seek ECRA interconnection approval for utility-scale projects above 50 MW.
- Grid Automation:Fault detection, isolation, and restoration systems with self-healing capabilities. Riyadh's 132 kV substation retrofit program anchors demand for intelligent electronic relays that minimize civil works.
- Asset Management:Predictive maintenance platforms converting sensor data into equipment replacement schedules.
Grid Automation captures the highest project values. Renewable Integration is climbing the fastest as solar capacity targets tighten.
End User:
Procurement concentration shapes vendor strategy, with Utilities consolidating around integrated platforms while Industrial Users fragment across multi-vendor service contracts.
- Utilities:Saudi Electricity Company and distribution company operators procuring transmission and distribution automation at scale.
- Industrial Users:Petrochemical complexes, desalination plants, and mining operations requiring microgrid controllers and islanding capabilities. Jubail industrial city anchors demand as facilities negotiate performance-based maintenance agreements independent of OEM lock-in.
- Commercial Sector:Retail, hospitality, and office buildings adopting demand response and energy management systems.
- Residential Consumers:Smart meter endpoints and home energy management interfaces.
Utilities control capital deployment timelines. Industrial Users are where third-party service specialization is emerging fastest.
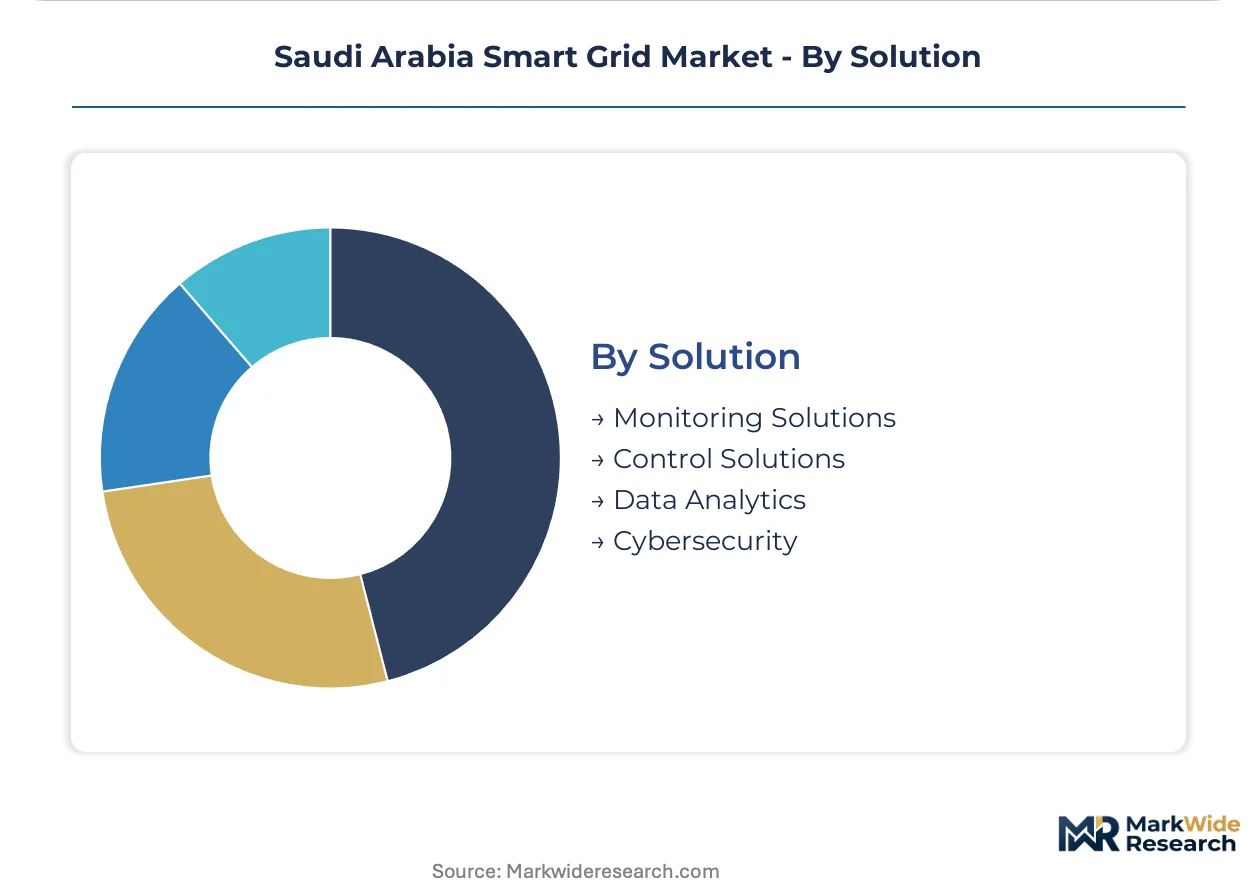
Solution:
Revenue mix shifts from hardware toward recurring software and services, with Data Analytics subscriptions displacing one-time control system sales in vendor portfolios.
- Monitoring Solutions:Sensor networks, phasor measurement units, and environmental monitoring for equipment condition assessment.
- Control Solutions:Substation automation, feeder switches, and voltage regulation systems with embedded protection logic.
- Data Analytics:Machine learning platforms processing petabytes of sensor streams into predictive maintenance schedules and load forecasts. Saudi Electricity Company's central control room upgrades are driving adoption as telemetry refresh rates compress to sub-second intervals.
- Cybersecurity:Encryption, intrusion detection, and secure remote access complying with National Cybersecurity Authority mandates for critical infrastructure protection.
Control Solutions anchor current procurement volumes. Data Analytics is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Cooperation Council Interconnection Authority's 1,200 km high-voltage backbone anchors the Kingdom's regional grid integration strategy, enabling power exchanges with neighboring utilities during peak demand periods.
Riyadh
Saudi Electricity Company operates the Kingdom's densest 132 kV substation network here, driving demand for intelligent electronic relay retrofits that minimize civil works. The Electricity and Cogeneration Regulatory Authority mandates real-time telemetry compliance for all new connections above 50 MW. King Abdullah Financial District and industrial zones south of the capital concentrate procurement for substation automation platforms.
Eastern Province
Jubail and Yanbu industrial cities host petrochemical complexes requiring microgrid controllers with islanding capabilities for process continuity. The National Cybersecurity Authority enforces encryption protocols for critical infrastructure endpoints across these facilities. Desalination plants cluster along the Arabian Gulf coastline, creating concentrated demand for predictive maintenance platforms.
Western Region
Jeddah and Makkah distribution networks face pilgrimage-driven seasonal load volatility that accelerates Advanced Metering Infrastructure deployment. Saudi Vision 2030 tourism targets are expanding commercial building automation procurement. The Red Sea coastal corridor is emerging as a testbed for grid-edge intelligence platforms.
NEOM Northwest
The giga-project's 100% renewable electricity mandate is driving procurement of grid-forming inverters and synchronous condensers at utility scale. The National Renewable Energy Program designates this zone for technology demonstration ahead of nationwide rollout. NEOM's integrated energy system is pioneering machine learning-based load forecasting for entirely new demand profiles.
Saudi Arabia Smart Grid Market Competitive Landscape
Listed leaders compete with private specialists across hardware-software integration depth, creating a tiered structure where scale advantages clash with customization agility. European industrial conglomerates anchor the premium tier through bundled control-cybersecurity offerings. Strategic archetypes include full-stack platform providers, component specialists with certification moats, and regional system integrators with localization partnerships. Competitive moves center on joint ventures with Saudi manufacturing partners and technology licensing agreements that satisfy domestic content thresholds.
Within the European-headquartered tier, ABB Ltd, Schneider Electric, and Siemens AG exemplify divergent positioning strategies. ABB Ltd anchors its presence through substation automation portfolios. Schneider Electric occupies a position emphasizing integrated cybersecurity architectures. Siemens AG represents the hardware-software bundle approach tailored to desert climate specifications. These three structures illustrate how foreign suppliers navigate the Kingdom's dual-track approval processes while competing for Saudi Electricity Company tenders.
| Leading Market Players |
|---|
| Saudi Electricity Company |
| General Electric Company |
| ABB Ltd |
| Honeywell International Inc |
| Schneider Electric |
| Siemens AG |
| ACWA Power |
| CG Power and Industrial Solutions Ltd |
| Siemens Energy AG |
| Others |
Pricing and Supply Chain Analysis
Foundry-scale economies in East Asian semiconductor manufacturing compress sensor and power electronics costs while concentrating supply risk. Saudi procurement rules mandating domestic content thresholds force foreign suppliers to absorb localization premiums that reshape price floors for substation automation platforms.
Pricing Analysis
Volume-discount tiering structures separate Saudi Electricity Company bulk tenders from fragmented industrial user procurements. Three-tier pricing stratification across premium desert-hardened equipment, standard grid automation, and economy meter hardware reflects certification grade and after-sales bundling intensity. Cost compression in the economy tier intensifies as Chinese manufacturers enter AMI supply, while premium tier buyers show low price sensitivity for grid-forming inverter warranties.
Supply Chain Analysis
China, Taiwan, and South Korea anchor wafer fabrication for power electronics and sensor components feeding Saudi grid deployments. Semiconductor foundry output, rare earth magnet supply, and copper conductor stock feed into intelligent electronic relay production. Single-source vulnerability concentrates in advanced node chip fabrication. Distribution runs through Riyadh-based system integrators with ECRA certification partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is compressing vendor margins as Saudi Electricity Company unbundles hardware from software subscriptions. Interoperability mandates from the Electricity and Cogeneration Regulatory Authority are forcing multi-vendor integration investments.
For Market Incumbents: Shield installed base revenue through captive service contracts that preempt third-party commissioning specialists. Deepen backward integration into Saudi manufacturing joint ventures to satisfy localization thresholds. Certification moats around SFDA hardware compliance provide defensive leverage against emerging Asian suppliers.
For New Entrants and Emerging Players: Differentiate on cybersecurity-native architectures that preempt National Cybersecurity Authority retrofit mandates. Target Eastern Province industrial microgrid controllers where petrochemical facilities unbundle from OEM-locked maintenance. Lead with performance-based service agreements rather than capital equipment positioning.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors data analytics platforms with recurring revenue models over hardware-dependent vendors. Acquisition targets should demonstrate machine learning deployment in Saudi Electricity Company control rooms. The signal to watch is telemetry refresh rate compression requirements accelerating software procurement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Localization | Satisfies Saudi Vision 2030 domestic content thresholds for substation automation tenders. |
| Cybersecurity Certification Investment | Creates approval moats under National Cybersecurity Authority encryption protocol mandates. |
| Data Analytics Platform Launch | Captures recurring revenue as Saudi Electricity Company upgrades central control rooms. |
| Desert Climate Hardening R&D | Differentiates hardware-software bundles for 50°C+ operational specifications. |
| Third-Party Service Partnership | Aligns with Jubail industrial zone procurement fragmentation away from OEM lock-in. |
Research Methodology
The analysis maps Advanced Metering Infrastructure, Distribution Management Systems, grid automation hardware, and data analytics platforms, each validated through utility planning officers, EPC contractors, grid operators, and IPP project developers. Primary interview intelligence triangulates against ECRA regulatory filings, Saudi Electricity Company procurement disclosures, GCCIA interconnection data, and National Renewable Energy Program development databases. Bottom-up project pipeline aggregation cross-checks against top-down macroeconomic assumptions.
Consistency checks validate volume and value outputs against hyperscaler capex patterns, regional grid investment benchmarks, and comparable smart grid deployment trajectories. Segmentation models incorporate technology maturity, application criticality, end-user procurement concentration, and solution layer revenue mix across the projection horizon. CAGRs derive from equipment replacement cycles, renewable integration mandates, and telemetry infrastructure refresh rates.
The analysis sits within stated boundaries; outcomes outside sustained Saudi Vision 2030 funding commitment or semiconductor supply normalization would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline adherence and localization partnership formation. Recalibration cycles align with material shifts in ECRA interconnection standards and National Cybersecurity Authority protocol updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
United Kingdom Smart Grid Market
Smart Grid
China Smart Power Distribution Systems Market
Smart Grid
Global Smart Grid Networking Market
Smart Grid
Global Microgrid As a Service Market
Smart Grid
Smart Grid Market
Smart Grid
Smart Grid Home Area Network (HAN) Market
Smart Grid
Smart Microgrid Controller Market
Smart Grid
Smart Grid Communications Market
Smart Grid
North America Automated Demand Response Management System Market
Smart Grid
South Korea Smart Grid Network Market
Smart Grid
South Africa Smart Grid Market
Smart Grid
Latin America Smart Grid Security Market
Smart Grid
United States Smart Grid Security Market
Smart Grid
Demand Response Market
Smart Grid
Europe Smart Grid Network Market
Smart Grid
Smart Energy Switch Market