
 Smart Microgrid Controller Market | 2026-2036
Smart Microgrid Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Microgrid Controller Market Outlook
Project finance for microgrid-as-a-service deployments is tilting competitive dynamics toward vendors with balance-sheet capacity to retain operational assets. General Electric Company leverages its turbine-to-controller integration to anchor utility-scale installations. Siemens sustains technology leadership through its digital grid software stack. Schneider Electric competes by extending its EcoStruxure platform across commercial and industrial microgrids.
A smart microgrid controller is a hardware-software system that orchestrates distributed energy resources through real-time communication protocols such as IEC 61850 and DNP3, maintaining frequency and voltage stability independently from the main grid. Networked controllers dominate current installations while distributed energy resource management systems represent the fastest-expanding technology segment as solar-plus-storage deployments multiply. On-premise installations still occupy the majority share in defense and critical infrastructure settings, though cloud-based and hybrid models are gaining traction among commercial building operators seeking remote diagnostics.
The US Federal Energy Regulatory Commission and state-level public utility commissions shape interconnection standards and compensation frameworks that directly determine microgrid controller deployment economics. Germany's Bundesnetzagentur enforces grid codes requiring distributed generators to provide frequency response, mandating controller capabilities that vendors must certify. Stakeholders should monitor how evolving cybersecurity mandates from NERC CIP and equivalent European network codes redefine product qualification thresholds.
Market Dynamics
Project finance structures for microgrid-as-a-service deployments are concentrating competitive advantage among vendors with balance-sheet capacity to retain operational assets, shifting procurement risk from utilities to equipment suppliers.
Growth Catalysts
- US Inflation Reduction Act investment tax credits:Distributed energy projects now capture accelerated depreciation benefits that improve microgrid controller deployment economics for commercial and industrial buyers.
- Military base electrification mandates:Defense installations in California and Texas are procuring autonomous grid management systems to achieve energy resilience targets independent from utility infrastructure.
- IEC 61850 protocol standardization:Unified communication frameworks reduce integration friction between distributed energy resources and controller hardware, compressing commissioning timelines for multi-vendor installations.
Market Restraints
- Semiconductor supply concentration:Controller manufacturing depends on power electronics fabricated in concentrated East Asian foundry capacity, exposing lead times to geopolitical disruption.
- NERC CIP cybersecurity certification costs:Critical infrastructure deployments require expensive third-party validation of controller firmware and communication stacks, elevating upfront capital requirements.
- Legacy SCADA substitution inertia:Existing utility control room investments in DNP3-based systems create technical and organizational resistance to protocol migration.
Strategic Opportunities
- Cloud-native controller architectures:Hybrid deployment models combining edge computing with remote diagnostics are penetrating commercial building portfolios where on-premise capital is constrained.
- Solar-plus-storage DERMS convergence:Distributed energy resource management systems integrating photovoltaic and battery dispatch represent the fastest-expanding technology segment as behind-the-meter deployments multiply.
- German Bundesnetzagentur frequency response mandates:Grid codes requiring distributed generators to provide ancillary services create certified product demand that vendors can capture through pre-qualification.
Industry Challenges
- IEC 61850 engineering talent scarcity:Specialized protocol configuration expertise sits with a limited pool of integration specialists, constraining deployment velocity for complex multi-node microgrids.
- Multi-protocol interoperability testing:Controllers must simultaneously support DNP3, Modbus, and IEC 61850 in heterogeneous legacy environments, extending commissioning cycles and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Microgrid Controller Market |
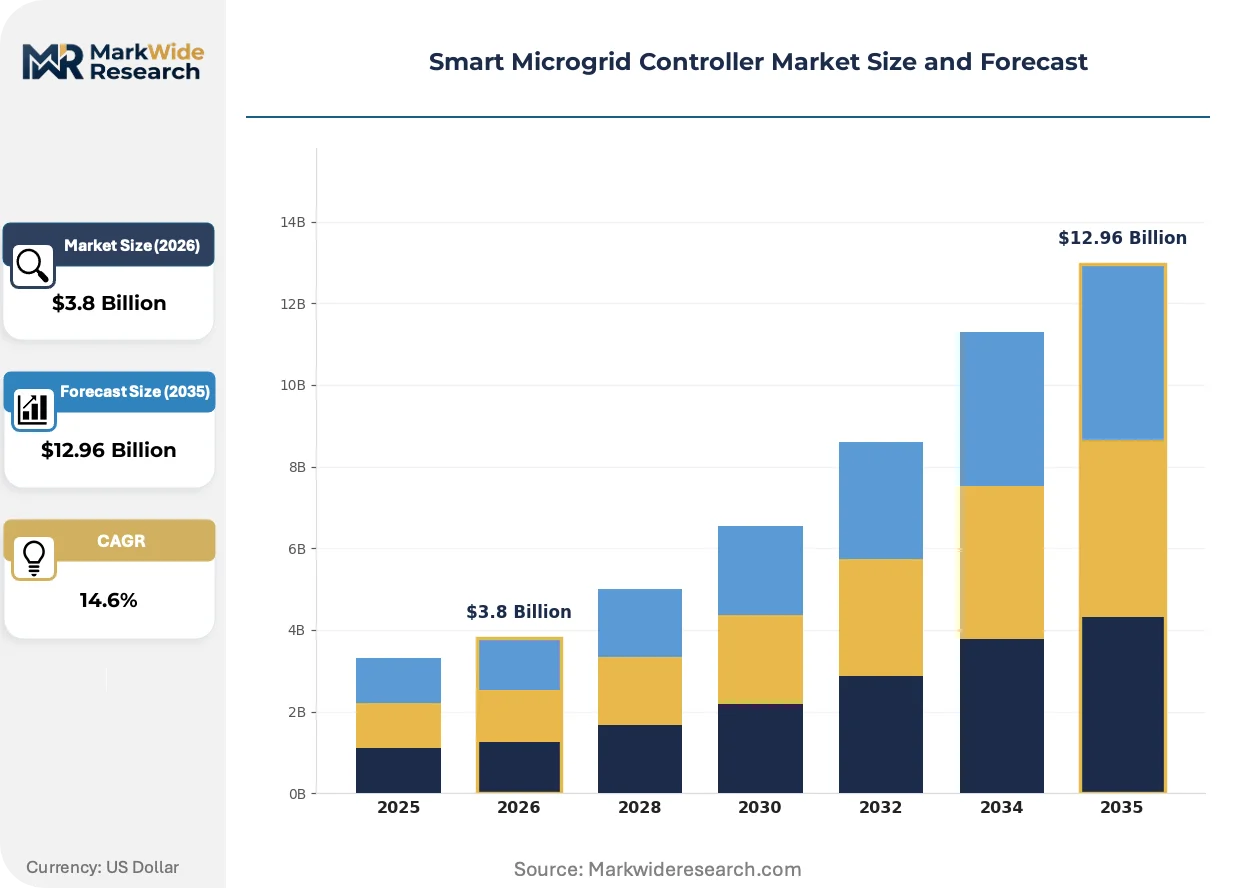
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Networked Controllers, Distributed Energy Resource Management Systems, Energy Management Systems, Advanced Metering Infrastructure Application: Renewable Integration, Demand Response, Voltage Control, Grid Resilience End User: Utilities, Industrial Facilities, Commercial Buildings, Research Institutions Installation: On-premise, Cloud-based, Hybrid Models, Retrofitting |
| Companies Covered | General Electric Company, Eaton Corporation, Schweitzer Engineering Laboratories, Emerson Automation Solutions, S&C Electric Company, Schneider Electric, ABB, Encorp, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Microgrid Controller Market Strategic Shifts
Edge-native artificial intelligence is collapsing the latency constraints that previously centralized microgrid optimization in remote data centers, enabling sub-cycle frequency response that synchronous generators cannot match.
Software-defined controllers with embedded machine learning inference engines are collapsing the functional boundary between hardware protection relays and optimization algorithms. Military microgrid operators in Texas and California are deploying these systems for autonomous islanding decisions. The compression of control-loop latency is collapsing the technical justification for centralized supervisory systems in sub-10MW installations.
Germany's Bundesnetzagentur has enacted grid codes requiring distributed generators above 100kW to provide frequency-watt response, mandating controller capabilities that vendors must certify through standardized type testing. This regulatory architecture is forcing hardware redesigns to accommodate bidirectional communication with distribution system operators. European commercial and industrial microgrid deployments are responding by pre-qualifying controllers for ancillary service participation.
Energy-as-a-service contracting models are transferring operational risk from facility owners to vendors who retain controller assets and performance obligations. Data center operators in Northern Virginia and pharmaceutical manufacturers in New Jersey are adopting these structures to bypass capital approval cycles. The shift is most visible in critical infrastructure verticals where uptime guarantees outweigh ownership preferences.
Smart Microgrid Controller Market Segmentation
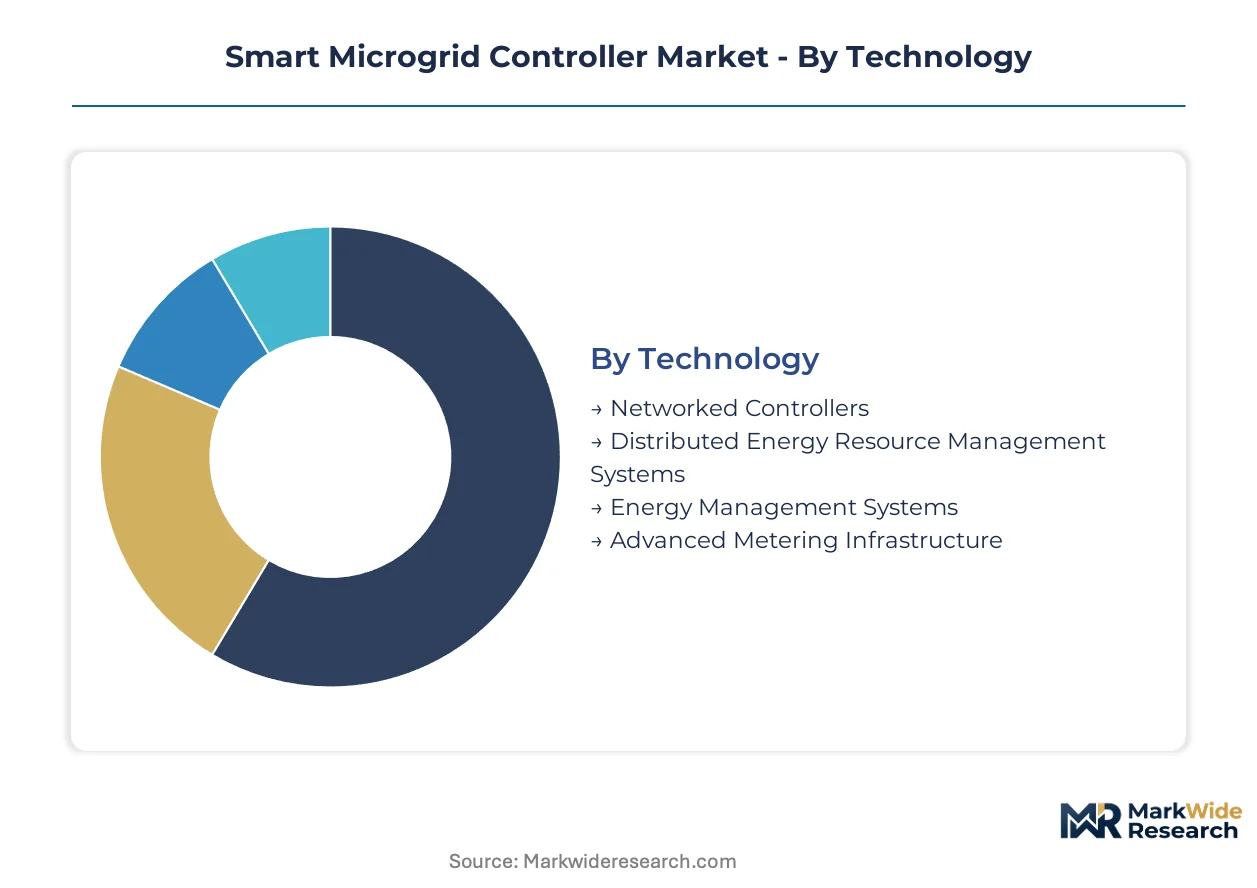
Controller deployment patterns diverge sharply across technology architectures and operational settings. Procurement specifications for military installations in Texas differ fundamentally from commercial building portfolios in California, creating distinct service intensity requirements across each segment category.
Technology:
After-sales service intensity escalates with software complexity and protocol interoperability requirements.
- Networked Controllers:Hardware-software systems coordinating multiple distributed nodes through IEC 61850 and DNP3 protocols. Defense installations in California and Texas anchor procurement volume, driven by mandates for autonomous islanding capability independent from utility infrastructure.
- Distributed Energy Resource Management Systems:Software platforms optimizing photovoltaic and battery dispatch through machine learning inference. Solar-plus-storage deployments across commercial building portfolios in Germany are climbing the fastest as behind-the-meter installations multiply.
- Energy Management Systems:Legacy supervisory platforms with embedded optimization algorithms for load scheduling.
- Advanced Metering Infrastructure:Communication-enabled measurement devices supporting real-time pricing signals and demand response activation.
Networked controllers hold the largest share; momentum sits with distributed energy resource management systems.
Application:
Functional requirements map directly to grid modernization investment cycles and regulatory compensation frameworks.
- Renewable Integration:Controller functions managing photovoltaic and wind intermittency through predictive dispatch and storage arbitrage. German Bundesnetzagentur frequency-watt mandates are concentrating certification demand among vendors pre-qualifying for ancillary service participation.
- Demand Response:Automated load curtailment protocols triggered by price signals or grid emergencies. Commercial building operators in Texas leverage these capabilities to capture demand charge reductions and wholesale market revenues.
- Voltage Control:Reactive power management maintaining distribution network stability.
- Grid Resilience:Autonomous islanding and black-start functions for critical infrastructure continuity.
Renewable integration commands dominant deployment share; steepest expansion trajectory belongs to demand response as retail tariff structures evolve.
End User:
Capital availability and risk tolerance segment procurement models across ownership structures.
- Utilities:Transmission and distribution operators deploying controllers for feeder automation and distributed generation hosting capacity. FERC interconnection standards and state public utility commission compensation frameworks directly shape deployment economics.
- Industrial Facilities:Manufacturing and processing plants requiring power quality assurance and uptime guarantees. Pharmaceutical manufacturers in New Jersey are adopting energy-as-a-service structures to bypass capital approval cycles while retaining operational control.
- Commercial Buildings:Office and retail portfolios seeking remote diagnostics and performance-based contracting.
- Research Institutions:Universities and national laboratories testing advanced control algorithms and interoperability protocols.
Utilities retain the largest installed base; commercial buildings are gaining share fastest through microgrid-as-a-service adoption.
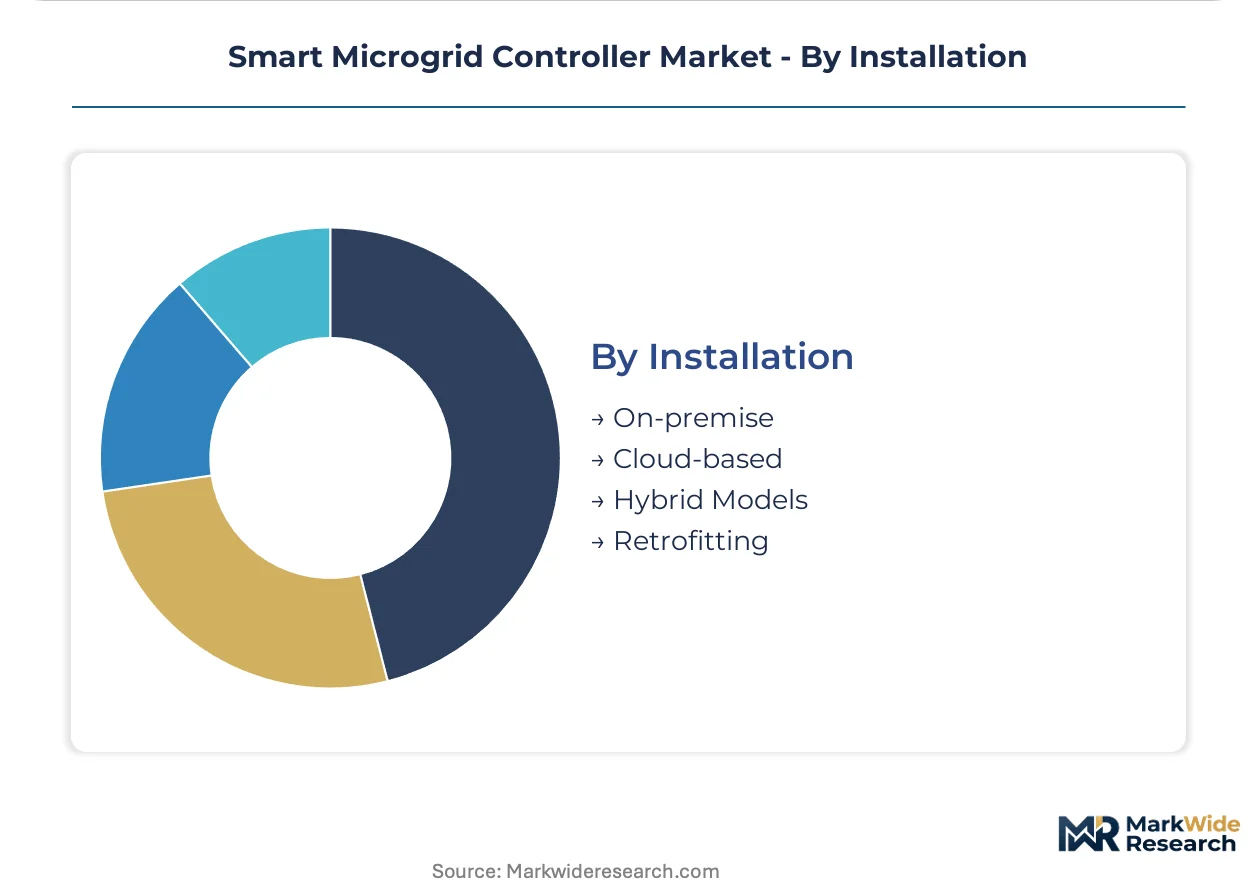
Installation:
Deployment architecture determines cybersecurity exposure and operational flexibility trade-offs.
- On-premise:Local controller hardware with physical air-gapping from external networks. Military bases and critical infrastructure settings in California mandate this architecture to satisfy NERC CIP certification requirements and minimize attack surface.
- Cloud-based:Remote optimization platforms with edge-to-cloud data pipelines. Northern Virginia data center operators are expanding fastest here, prioritizing remote diagnostics and predictive maintenance over local capital deployment.
- Hybrid Models:Edge computing for real-time control with cloud analytics for fleet optimization.
- Retrofitting:Controller upgrades to legacy SCADA and protection relay installations.
On-premise installations dominate current revenue; hybrid models are expanding most quickly as commercial operators balance latency requirements against capital constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Controller hardware flows from German engineering centers and US defense corridors toward Asia-Pacific integration hubs. Import dependency for power electronics concentrates procurement risk in East Asian foundry capacity. Regulatory divergence between FERC interconnection standards and Bundesnetzagentur grid codes fragments certification requirements across major demand centers.
United States
Military base electrification mandates in California and Texas are accelerating autonomous grid management procurement. FERC Order 2222 and state public utility commission compensation frameworks directly shape deployment economics for distributed energy projects. Northern Virginia data center operators are adopting hybrid cloud-native architectures to bypass capital approval cycles while retaining uptime guarantees.
Germany
Industrial microgrid deployments are responding to frequency-watt response mandates for distributed generators above 100kW. Bundesnetzagentur grid codes require bidirectional communication with distribution system operators, forcing hardware redesigns for ancillary service participation. Manufacturing clusters in Bavaria and Baden-Württemberg are pre-qualifying controllers for grid stability services.
China
Dual carbon policy targets are concentrating state-backed investment in distributed energy resource integration. MIIT standards for smart grid equipment interoperability compress commissioning timelines for multi-vendor installations. Yangtze River Delta industrial zones are deploying networked controllers for factory microgrids serving export manufacturing.
India
CEA grid connectivity regulations and state-level renewable purchase obligations are expanding controller deployment in commercial and industrial segments. PLI scheme incentives for solar manufacturing are multiplying behind-the-meter storage-plus-solar installations requiring DERMS platforms. Gujarat and Maharashtra industrial corridors anchor current procurement volume.
Japan
METI resiliency programs for critical infrastructure are mandating autonomous islanding capability in earthquake-prone regions. JIS standards for distributed energy interoperation create certification barriers that favor established vendor relationships. Kanto and Kansai metropolitan areas are retrofitting commercial building microgrids with edge-native control systems.
Smart Microgrid Controller Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying protection relays and communication modules. The vendor base concentrates among electrical equipment conglomerates with captive software stacks and dedicated power systems specialists with protocol expertise. Three archetypes dominate: turbine-to-controller integrated suppliers, digital grid software platforms, and DERMS-native optimization specialists. Competitive dynamics favor M&A activity targeting machine learning inference capabilities and strategic partnerships securing semiconductor supply continuity.
Among turbine-integrated suppliers, General Electric Company and Siemens occupy positions exemplifying hardware-software bundling strategies. Schneider Electric represents the platform archetype extending building automation expertise into microgrid orchestration. These three anchors illustrate how balance-sheet capacity to retain operational assets under microgrid-as-a-service structures is concentrating procurement risk transfer from utilities to equipment vendors.
| Leading Market Players |
|---|
| General Electric Company |
| Eaton Corporation |
| Schweitzer Engineering Laboratories |
| Emerson Automation Solutions |
| S&C Electric Company |
| Schneider Electric |
| ABB |
| Encorp |
| Siemens |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific container freight corridors from Shanghai to Long Beach transmit semiconductor cost volatility directly into controller hardware pricing, concentrating margin pressure on vendors without captive power electronics fabrication while enabling tiered pricing differentiation between IEC 61850-certified and uncertified product lines.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification grade under NERC CIP and volume scale represent the primary price differentiation drivers. Cost compression in the economy tier is intensifying because semiconductor foundry capacity constraints elevate bill-of-materials exposure. Commercial building operators exhibit the highest price sensitivity due to constrained capital approval cycles, while military procurement shows the lowest sensitivity given resilience mandates.
Supply Chain Analysis
Export controls on advanced power semiconductors limit flows from Taiwan and South Korea, forcing controller manufacturers toward alternative sourcing. Silicon carbide wafers, ARM-based microcontrollers, and isolated gate drivers constitute critical input dependencies. Single-source vulnerability concentrates in East Asian foundry capacity for wide-bandgap devices. Distribution runs through authorized industrial distributors serving EPC contractors and direct OEM supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software maintenance and firmware update subscriptions expand faster than hardware shipments, converting one-time controller sales into recurring revenue streams that improve lifetime customer value and reduce procurement cyclicality.
For Market Incumbents: Build switching-cost moats through deep protocol integration. Deepen backward integration into power semiconductor sourcing to mitigate foundry concentration risk. Invest in IEC 61850 certification pipelines to defend against DERMS-native specialists encroaching on utility-scale installations. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point given limited incumbent service infrastructure and accelerating solar-plus-storage deployment. Cloud-native controller architectures with remote diagnostics capabilities offer the strongest go-to-market angle against legacy on-premise vendors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors machine learning inference engine specialists over hardware-agnostic software platforms. The five-to-ten year viability window rewards vendors with demonstrated Bundesnetzagentur certification and military program wins. Acquisition targets should demonstrate pre-qualified ancillary service participation in European grid codes. The signal to watch is FERC Order 2222 implementation velocity across state public utility commissions.| Strategic Initiative | Industry Significance |
|---|---|
| Machine Learning Inference Acquisition | Compresses control-loop latency below synchronous generator response thresholds for sub-10MW installations. |
| IEC 61850 Certification Pipeline Investment | Unlocks Bundesnetzagentur-mandated frequency-watt response participation in German industrial clusters. |
| Semiconductor Supply Partnership | Secures wide-bandgap device allocation from Taiwan and South Korea foundries amid export control constraints. |
| Microgrid-as-a-Service Platform Launch | Transfers procurement risk from Northern Virginia data center operators to vendor balance sheets. |
| Cloud-Native Controller Architecture | Penetrates California commercial building portfolios where on-premise capital deployment faces constraints. |
Study Parameters
The analysis maps networked controller hardware, distributed energy resource management systems, energy management systems, and advanced metering infrastructure segments, each validated through utility planning officers, microgrid EPC contractors, industrial facility energy managers, and semiconductor procurement specialists. Primary interview findings triangulate against FERC interconnection filings, EIA distributed generation databases, IEC standardization committee records, and Bundesnetzagentur grid code documentation. Bottom-up installation forecasts reconcile with top-down market sizing across technology architectures.
Forecast assumptions hold regulatory compensation frameworks and semiconductor supply availability constant while varying distributed energy penetration rates and military electrification spending across the projection horizon. The analytical framework models technology type, application function, end-user vertical, and deployment architecture segmentation dimensions. CAGRs derive from installation volume trajectories and average selling price evolution informed by project finance structure shifts toward operational asset retention.
Practitioners should monitor NERC CIP cybersecurity mandate expansion and East Asian foundry utilization rates for early signals of forecast deviation. Material shifts in Inflation Reduction Act credit eligibility or Bundesnetzagentur grid code stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Demand Response Market
Smart Grid
Middle-East Smart Grid Network Market
Smart Grid
Global Smart Grid Networking Market
Smart Grid
Smart Microgrid Market
Smart Grid
Smart Grid Communications Market
Smart Grid
South Africa Smart Grid Market
Smart Grid
Latin America Smart Grid Security Market
Smart Grid
Smart Water Grid Market
Smart Grid
Smart Grid Market
Smart Grid
UK Smart Grid Network Market
Smart Grid
Global Microgrid As a Service Market
Smart Grid
AC Grid Connected Microgrid Market
Smart Grid
Europe Smart Grid Security Market
Smart Grid
North America Microgrid Market
Smart Grid
Saudi Arabia Smart Grid Market
Smart Grid
Microgrid Controller Market