
 China Smart Grid Network Market | 2026-2036
China Smart Grid Network Market Size, Share, and Industry Trends Forecast 2026-2036
China Smart Grid Network Market Outlook
Silicon carbide power semiconductors is restructuring inverter economics across China's smart grid value chain. Huawei Technologies Co. Ltd leverages its 5G private-network portfolio to dominate utility communication backbones. State Grid Corporation of China anchors national ultra-high voltage rollout through captive semiconductor sourcing. ABB Ltd competes on digital substation automation with European-origin protection relay architectures.
China Smart Grid Network denotes an integrated electricity infrastructure combining two-way digital communication, automated sensing, and distributed control across generation, transmission, and distribution layers, operating at 50 Hz with voltage classes from 0.4 kV to 1100 kV UHV. Its primary purpose enables real-time load balancing, renewable integration, and outage self-healing for the world's largest power system. Smart Meters and Communication Network segments lead current procurement volumes as utilities replace electromechanical billing devices with cellular-connected AMI endpoints. Demand Response and Grid Security applications exhibit the fastest structural expansion as provincial grid operators procure software platforms for peak shaving and cyber-physical threat detection.
MIIT mandates GB standards compliance for all grid-connected communication equipment, while SAMR enforces metering accuracy certifications under national metrology regulations. MEE's dual carbon goals tighten emissions benchmarks for grid infrastructure procurement, redirecting utility capex toward digital efficiency investments. Stakeholders must monitor how NMPA-equivalent equipment approval timelines and evolving GB cybersecurity standards reshape vendor qualification barriers for foreign technology suppliers.
Market Dynamics
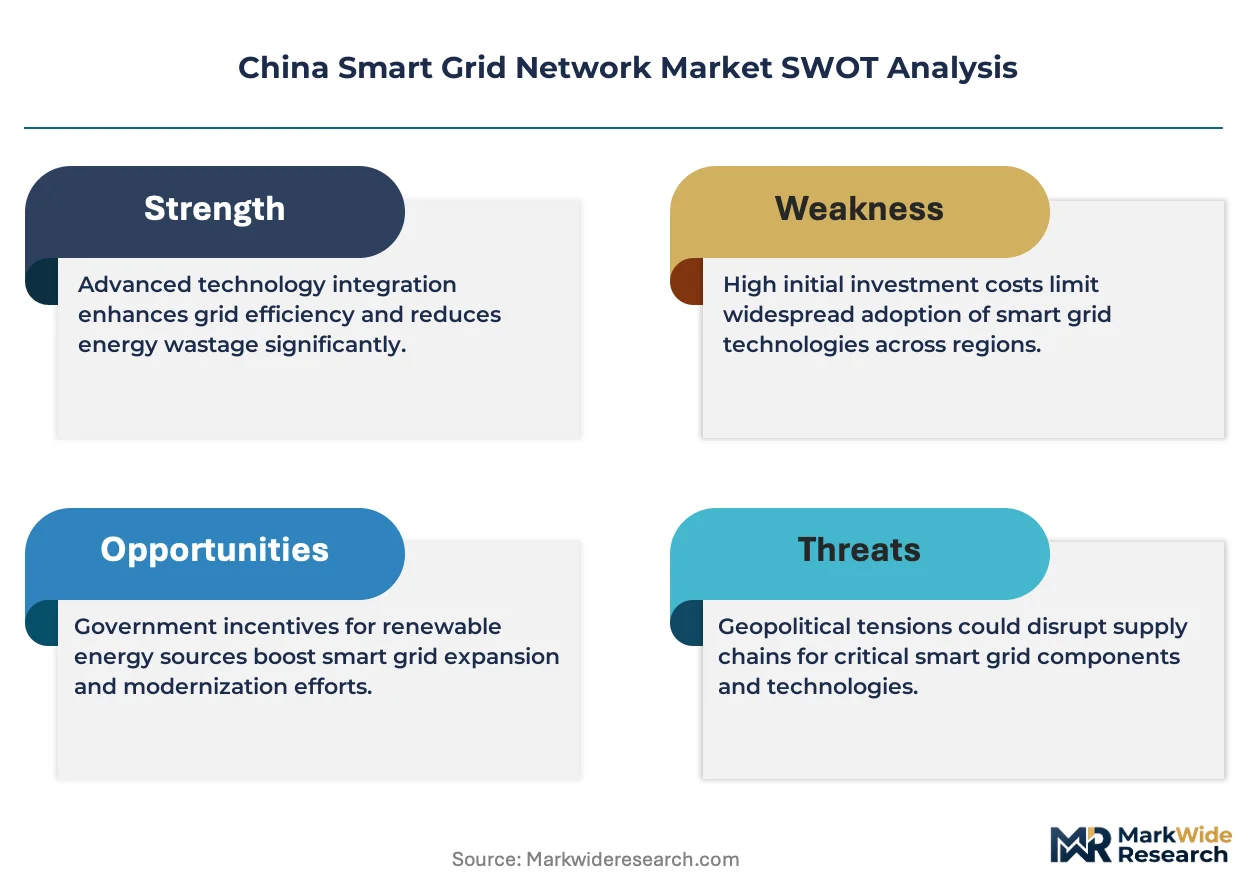
Silicon carbide power semiconductors are compressing inverter costs across China's grid infrastructure, while MIIT's GB standards compliance mandates reshape vendor qualification barriers for foreign technology suppliers entering the market.
Growth Catalysts
- MEE Dual Carbon Goals:Provincial grid operators face tightening emissions benchmarks that redirect capital expenditure toward digital protection systems and automated metering infrastructure.
- Jiangsu-Zhejiang AMI Deployment:Utilities in the Yangtze River Delta cluster are replacing electromechanical billing devices with cellular-connected endpoints at procurement volumes exceeding other provinces.
- UHV Transmission Expansion:State Grid Corporation's western corridor buildout creates sustained demand for ultra-high voltage switchgear and digital substation automation platforms.
Market Restraints
- Silicon Carbide Supply Concentration:Domestic production of wide-bandgap substrates remains concentrated among a limited set of foundries, exposing inverter manufacturers to input cost volatility.
- SAMR Metrology Certification:National metering accuracy regulations impose extended approval timelines that delay foreign smart meter market entry by quarters.
- Legacy Electromechanical Installed Base:Existing relay protection systems in older substations create technical debt that slows digital upgrade cycles despite policy pressure.
Strategic Opportunities
- Sichuan-Guizhou Renewable Integration:Hydropower-rich southwestern provinces present underpenetrated demand for grid-forming inverters and synchronous condensers.
- 5G Private Network Convergence:Utility communication backbones are adopting dedicated cellular slices that merge with existing fiber-optic trunk lines for mission-critical latency.
- Demand Response Software Procurement:Provincial dispatch centers are procuring peak-shaving platforms that aggregate distributed energy resources behind the meter.
Industry Challenges
- Cyber-Physical Security Skill Gap:Grid operators struggle to staff teams with combined expertise in IEC 62351 protocols and operational technology hardening.
- Interoperability Friction:Proprietary communication stacks from dominant equipment vendors complicate multi-supplier substation integration projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Smart Grid Network Market |
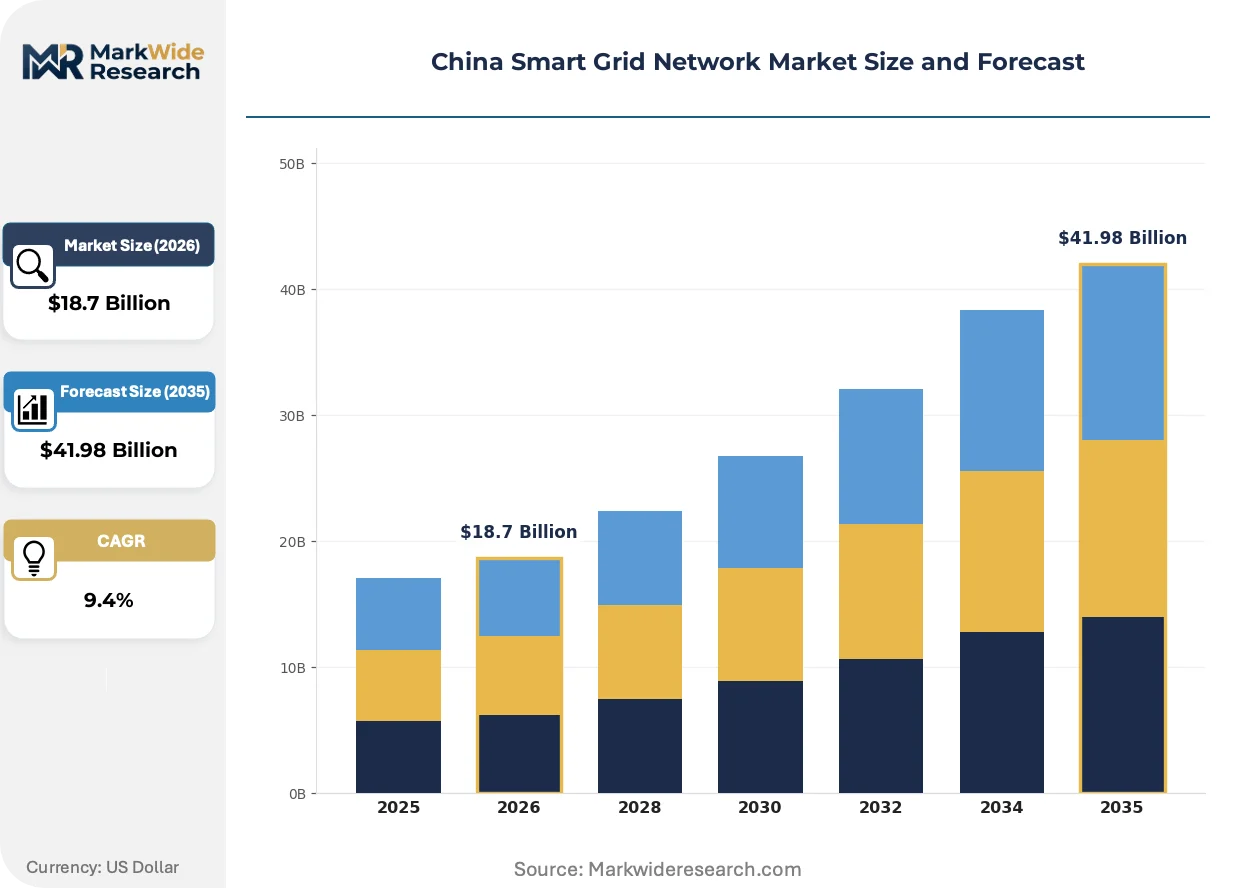
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Smart Meters, Advanced Sensors, Distribution Management System, Communication Network Application: Energy Management, Demand Response, Asset Management, Grid Security End User: Utilities, Industrial, Commercial, Residential Solution: Automation Solutions, Monitoring Solutions, Control Solutions, Maintenance Solutions |
| Companies Covered | Huawei Technologies Co. Ltd, ZTE Corporation, State Grid Corporation of China, Landis+Gyr Group AG, China Southern Power Grid, Siemens AG, General Electric Company, Shenzhen Clou Electronics Co, ABB Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Smart Grid Network Market Strategic Shifts
Digital protection relays and wide-bandgap power electronics are converging to redefine grid asset economics, while software-defined substations displace hardwired control architectures across China's transmission hierarchy.
Silicon carbide MOSFETs are rewriting inverter economics throughout the smart grid value chain. Traction inverter manufacturers are migrating designs from silicon IGBTs to SiC modules for 20-30% efficiency gains. This semiconductor transition is compressing cooling system costs and enabling higher switching frequencies that reduce passive component size in grid-tied power converters.
MIIT's GB/T 36572 cybersecurity standards for power systems are mandating encrypted communication protocols across all new grid-connected equipment. Foreign suppliers must demonstrate compliance with domestic certification laboratories before provincial procurement windows open. Digital substation automation vendors are restructuring product roadmaps to embed hardware security modules that satisfy these evolving baseline requirements.
Utility procurement of grid infrastructure is consolidating toward framework agreements with state-owned equipment integrators. Provincial grid companies are abandoning transactional spot purchasing for multi-year supply partnerships that bundle hardware, software, and maintenance. This buying-pattern shift is most visible in Jiangsu and Zhejiang, where State Grid subsidiaries now negotiate comprehensive digital substation packages rather than discrete component tenders.
China Smart Grid Network Market Segmentation
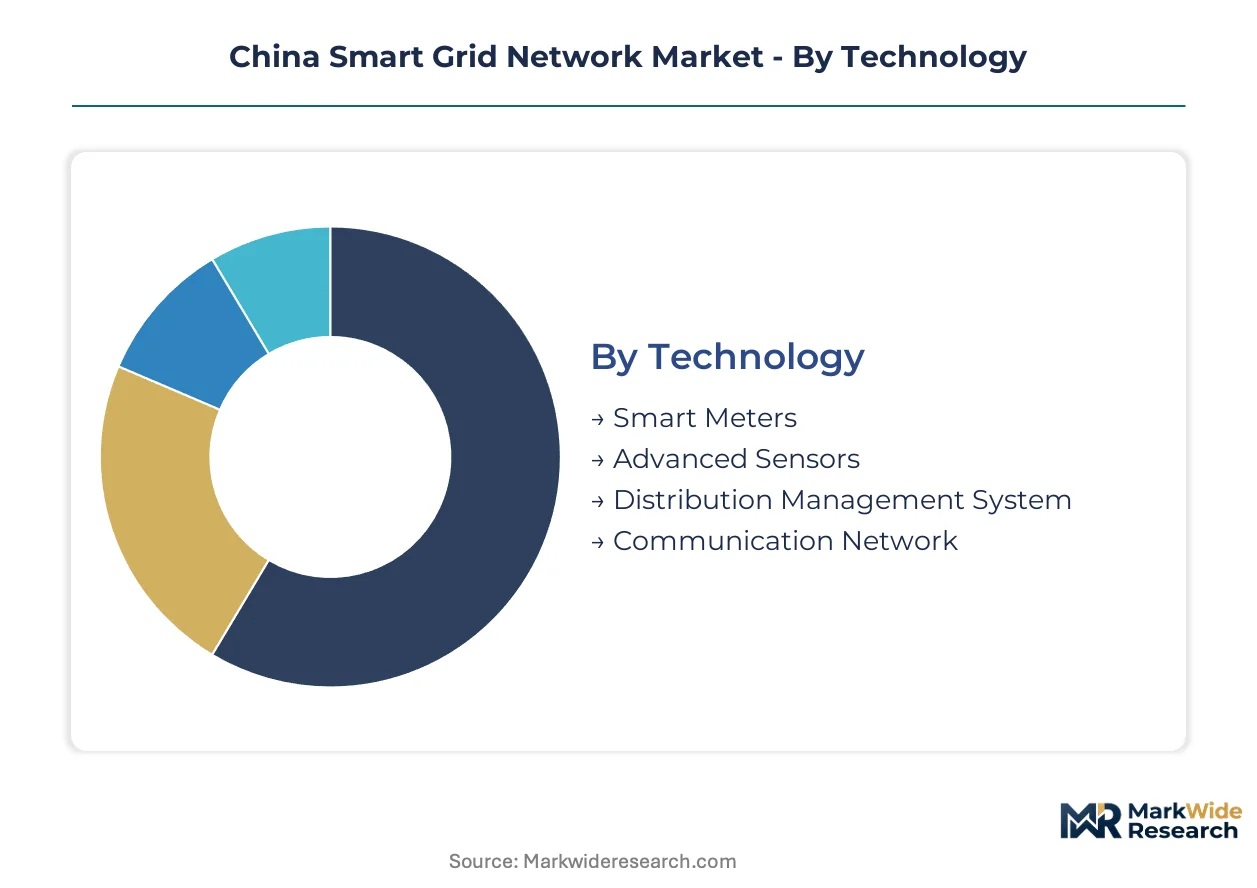
Smart grid procurement patterns in China diverge sharply across technology tiers and end-user categories. State Grid Corporation's framework agreements bundle hardware, software, and maintenance into multi-year packages that reshape how vendors must position across each segment axis.
Technology:
Supply of critical components clusters around domestic semiconductor foundries and state-owned equipment integrators, compressing margins for foreign suppliers lacking captive sourcing.
- Smart Meters:Cellular-connected AMI endpoints with integrated metrology and load profiling capabilities. Jiangsu and Zhejiang utilities deploy these at scale under SAMR accuracy certifications, with procurement volumes exceeding other provinces due to Yangtze River Delta urban density.
- Communication Network:5G private network slices and fiber-optic trunk lines delivering mission-critical latency for grid operations. MIIT's GB/T 36572 cybersecurity standards mandate encrypted protocols, forcing foreign vendors through extended domestic laboratory certification.
- Advanced Sensors:Phasor measurement units and digital instrument transformers enabling real-time grid state awareness. Deployment concentrates in UHV corridors where State Grid prioritizes synchronous wide-area monitoring.
- Distribution Management System:Software platforms for outage management and voltage optimization. Provincial dispatch centers in Sichuan and Guizhou adopt these for hydropower-rich network balancing.
Today's leader: Smart Meters. Tomorrow's challenger: Communication Network.
Application:
Utility software procurement is climbing the fastest for platforms that aggregate distributed resources and automate peak shaving.
- Demand Response:Peak-shaving platforms aggregating behind-the-meter distributed energy resources. Provincial grid operators procure these to meet MEE dual carbon emissions benchmarks through automated load curtailment.
- Grid Security:Cyber-physical threat detection systems combining IEC 62351 protocols with operational technology hardening. Grid operators struggle to staff combined expertise teams, creating vendor opportunity for managed security services.
- Energy Management:Real-time generation dispatch and renewable forecasting tools. Western provinces deploy these for ultra-high voltage corridor balancing.
- Asset Management:Predictive maintenance platforms for transformer and switchgear fleets. State Grid subsidiaries negotiate these as bundled maintenance add-ons to hardware framework agreements.
Demand Response captures current procurement momentum. Grid Security represents the steepest expansion trajectory as GB cybersecurity standards tighten.
End User:
Customer concentration varies by segment, with utilities dominating capital-intensive infrastructure and commercial users driving behind-the-meter software adoption.
- Utilities:Provincial grid companies and State Grid subsidiaries executing national ultra-high voltage rollout and AMI replacement programs. These entities control procurement through multi-year framework agreements that bundle hardware, software, and maintenance.
- Industrial:Energy-intensive manufacturers procuring demand response participation and power quality management. Yangtze River Delta factories represent concentrated demand for peak-shaving aggregation.
- Commercial:Office complexes and retail chains adopting building energy management systems. These users prioritize software platforms with minimal capital infrastructure requirements.
- Residential:Household consumers receiving smart meters through utility-mandated deployment. End-user choice remains limited to rate plan selection rather than equipment procurement.
Utilities anchor procurement volume. Industrial users gain share fastest as behind-the-meter aggregation platforms expand.
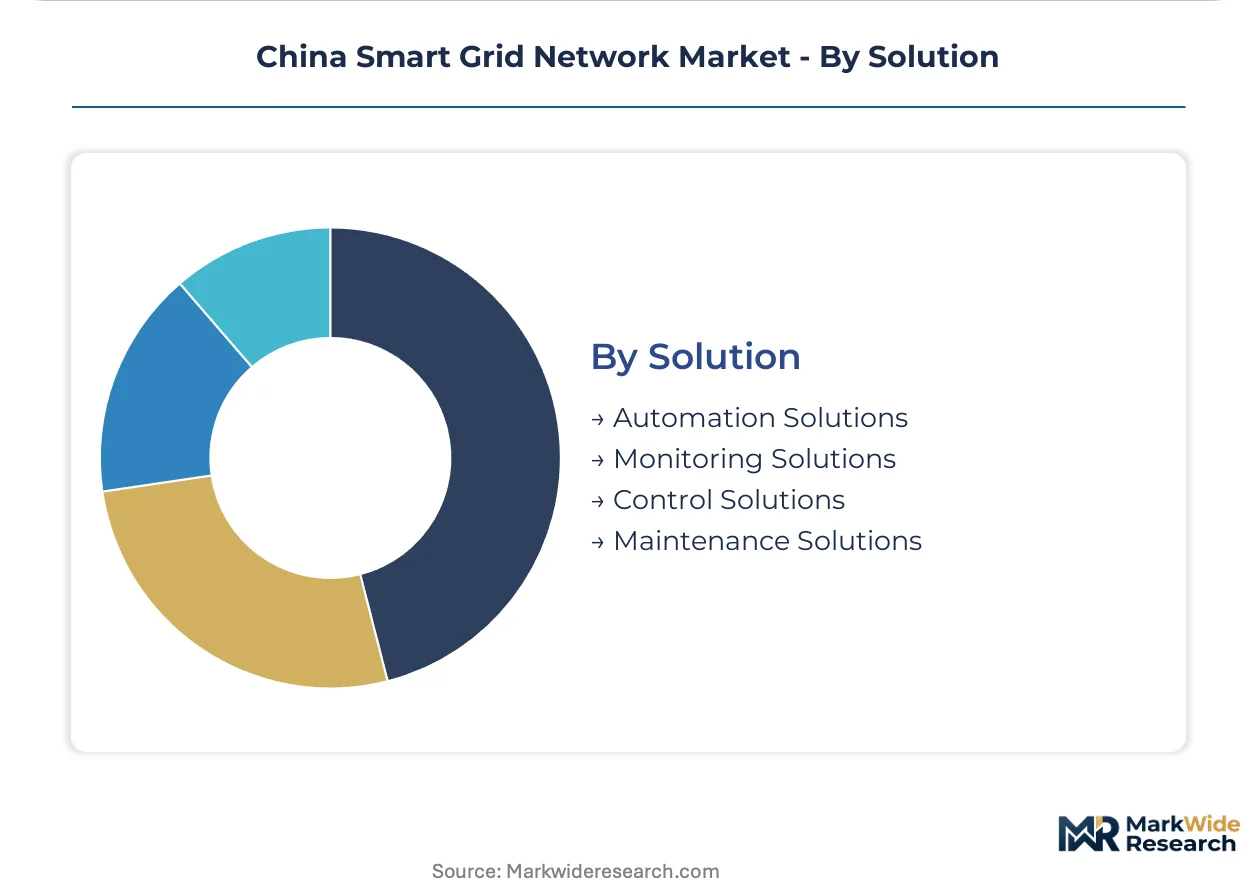
Solution:
Vendor margins compress where solutions commoditize into bundled maintenance add-ons, while differentiation persists in integrated automation platforms.
- Automation Solutions:Digital substation control systems replacing hardwired relay logic. State Grid's western corridor buildout sustains demand for these platforms with integrated protection and control.
- Monitoring Solutions:Wide-area situational awareness platforms combining sensor feeds and analytics. These solutions expand most quickly in provinces with high renewable penetration requiring real-time visibility.
- Control Solutions:Grid-forming inverter and synchronous condenser systems for renewable integration. Sichuan and Guizhou present underpenetrated demand for these assets.
- Maintenance Solutions:Predictive analytics and field service management bundled into hardware supply agreements. These commoditize fastest as state-owned integrators absorb them into comprehensive procurement packages.
Automation Solutions dominate current revenue. Monitoring Solutions are gaining share fastest as renewable integration pressures visibility requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors China's smart grid deployment intensity, with provincial utilities executing the nation's most concentrated AMI replacement programs and digital substation automation rollouts.
Jiangsu
Provincial grid operators in Jiangsu deploy cellular-connected AMI endpoints at volumes exceeding other provinces, driven by urban density across the Nanjing-Suzhou corridor. SAMR enforces metering accuracy certifications that shape vendor qualification timelines. State Grid subsidiaries in Wuxi and Changzhou negotiate multi-year framework agreements bundling hardware, software, and predictive maintenance.
Zhejiang
Hangzhou and Ningbo utilities accelerate digital protection system procurement to meet MEE dual carbon emissions benchmarks for grid infrastructure. MIIT mandates GB/T 36572 cybersecurity compliance for all new communication equipment entering service. The province's industrial load concentration creates sustained demand for demand response platforms that aggregate behind-the-meter resources.
Sichuan
Hydropower-rich networks in Sichuan present underpenetrated demand for grid-forming inverters and synchronous condensers stabilizing renewable output. Provincial dispatch centers procure real-time generation forecasting tools under western corridor expansion mandates. Chengdu-based system integrators bundle automation solutions for ultra-high voltage substation projects.
Guizhou
Grid operators in Guizhou adopt distribution management systems for network balancing across mountainous terrain with dispersed generation assets. MEE emissions benchmarks redirect capital expenditure toward digital efficiency investments. Guiyang clusters emerging as a procurement hub for wide-area monitoring platforms combining phasor measurement units with analytics.
Shandong
Industrial load centers in Jinan and Qingdao drive power quality management procurement from energy-intensive manufacturers participating in demand response programs. State Grid's eastern corridor buildout sustains demand for digital substation automation with integrated protection and control. Provincial framework agreements consolidate toward state-owned equipment integrators offering bundled maintenance packages.
China Smart Grid Network Market Competitive Environment
Global majors compete with regional champions across technology licensing and framework agreement access, creating a tiered structure where scale advantages concentrate procurement leverage. The vendor base separates into three strategic archetypes: state-owned equipment integrators with captive semiconductor sourcing, multinational automation specialists competing on digital substation architectures, and domestic communication equipment vendors leveraging 5G private network portfolios. Competitive moves center on multi-year supply partnerships replacing transactional tenders, and backward integration into wide-bandgap substrate production to secure inverter component supply.
Among state-owned champions, State Grid Corporation of China anchors national ultra-high voltage rollout through captive equipment sourcing and framework agreement dominance. Huawei Technologies Co. Ltd occupies a position exemplifying the communication infrastructure archetype, leveraging 5G private-network portfolios for utility backbones. ABB Ltd represents the multinational specialist tier, competing on European-origin protection relay architectures for digital substation automation projects.
| Leading Market Players |
|---|
| Huawei Technologies Co. Ltd |
| ZTE Corporation |
| State Grid Corporation of China |
| Landis+Gyr Group AG |
| China Southern Power Grid |
| Siemens AG |
| General Electric Company |
| Shenzhen Clou Electronics Co |
| ABB Ltd |
| Others |
Value Chain & Pricing Dynamics
State Grid Corporation's framework agreement dominance concentrates procurement leverage among a handful of state-owned equipment integrators, compressing vendor margins into multi-year bundled contracts that merge hardware, software, and maintenance pricing.
Pricing Analysis
Silicon carbide substrate costs pass through directly to inverter and digital protection relay pricing, with domestic foundry concentration amplifying input volatility for foreign suppliers lacking captive sourcing. Pricing stratifies across GB/T 36572 cybersecurity certification tiers, MIIT compliance grade, and volume scale under provincial framework agreements. Cost compression in standard-tier smart meters is intensifying because state-owned integrators absorb maintenance into bundled procurement packages. Industrial users in the Yangtze River Delta exhibit highest price sensitivity due to behind-the-meter aggregation platform commoditization, while UHV corridor projects show lowest sensitivity given national strategic priority.
Supply Chain Analysis
Regional distribution centers in Chengdu, Wuxi, and Hangzhou anchor hub-and-spoke patterns for digital substation components, with final-mile deployment feeding western corridor construction sites and Yangtze River Delta AMI replacement programs. Manufacturing concentrates in China, South Korea, and Taiwan for wide-bandgap semiconductors, fiber-optic transmission gear, and cellular communication modules. The supply chain draws from silicon carbide substrates, rare-earth magnetic materials, and high-purity copper for transformer windings. Single-source vulnerability in domestic SiC foundry capacity exposes inverter manufacturers to allocation risk. Distribution runs through state-owned equipment integrators that consolidate procurement across provincial grid subsidiaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where MEE dual carbon goals redirect utility capex toward premium digital protection systems and encrypted communication infrastructure that commands specification premiums over legacy electromechanical alternatives.
For Market Incumbents: Deepen backward integration into wide-bandgap substrate production to secure inverter component supply against domestic foundry allocation risk. Fortify framework agreement positioning with State Grid subsidiaries through bundled predictive maintenance offerings that raise switching costs for provincial procurement officers facing SAMR certification renewal cycles. For New Entrants and Emerging Players: The mid-tier price gap between Huawei-dominated 5G private network premiums and basic fiber-optic trunk solutions presents white-space opportunity for specialized communication vendors. Target Sichuan and Guizhou grid operators with grid-forming inverter solutions for hydropower-rich networks, positioning through Chengdu-based system integrators with existing UHV project relationships. For Investors and Strategic Acquirers: State-owned equipment integrators are the most active acquirer in this space, consolidating digital substation automation capabilities through asset purchases. Long-term viability hinges on exposure to western corridor UHV expansion and AMI replacement cycles rather than spot project exposure. Monitor MIIT GB cybersecurity standard evolution as inflection indicator for foreign technology supplier qualification windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrates | Captive sourcing insulates inverter margins from domestic foundry concentration risk. |
| GB/T 36572 Certification Investment | Hardware security module embedding unlocks provincial procurement windows under MIIT mandates. |
| Framework Agreement Restructuring | Multi-year bundled contracts with State Grid subsidiaries displace transactional spot purchasing. |
| 5G Private Network Convergence | Dedicated cellular slices merge with fiber-optic trunk lines for mission-critical latency requirements. |
| Sichuan-Guizhou Market Entry | Hydropower-rich southwestern provinces present underpenetrated demand for grid-forming assets. |
Study Parameters
Multiple input streams — utility planning officers, digital substation procurement leads, power semiconductor supply specialists, and grid cybersecurity consultants — were reconciled against State Grid framework agreement disclosures, MIIT GB standard publications, SAMR metrology certification records, and provincial grid company capex plans. Bottom-up segment sizing triangulated with top-down national smart grid investment trajectories anchored in MEE dual carbon policy documentation.
Historical deployment patterns for AMI endpoints, UHV corridor commissioning schedules, and digital protection relay replacement cycles were cross-referenced against expert panel assessments of procurement velocity across the projection horizon. Segmentation modeling incorporated technology tier, application function, end-user category, and solution type dimensions. CAGRs were derived from elasticity-adjusted demand curves for silicon carbide power electronics and software-defined substation automation platforms.
Caveats apply where MIIT cybersecurity standard evolution, SAMR certification timeline shifts, or State Grid procurement centralization could materially shift the outlook. Forecasts reflect documented assumptions regarding western corridor buildout pace and dual carbon policy enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
South Africa Smart Grid Market
Smart Grid
Power Grid Market
Smart Grid
Latin America Smart Grid Security Market
Smart Grid
Microgrid Market
Smart Grid
Automated Demand Response Management Systems Market
Smart Grid
United Arab Emirates Smart Grid Market
Smart Grid
South Korea Smart Grid Network Market
Smart Grid
North America Smart Grid Market
Smart Grid
Demand Response Market
Smart Grid
South and Central America Smart Grid Market
Smart Grid
GCC Smart Grid Security Market
Smart Grid
Europe Smart Grid Network Market
Smart Grid
Asia-Pacific Demand Response Management Systems Market
Smart Grid
Smart Water Grid Market
Smart Grid
Smart Grid Sensors Market
Smart Grid
Renewable Energy Integration with Smart Grid Market