
 Portable Vacuum Cleaner Market | 2026-2036
Portable Vacuum Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Vacuum Cleaner Market Analytics
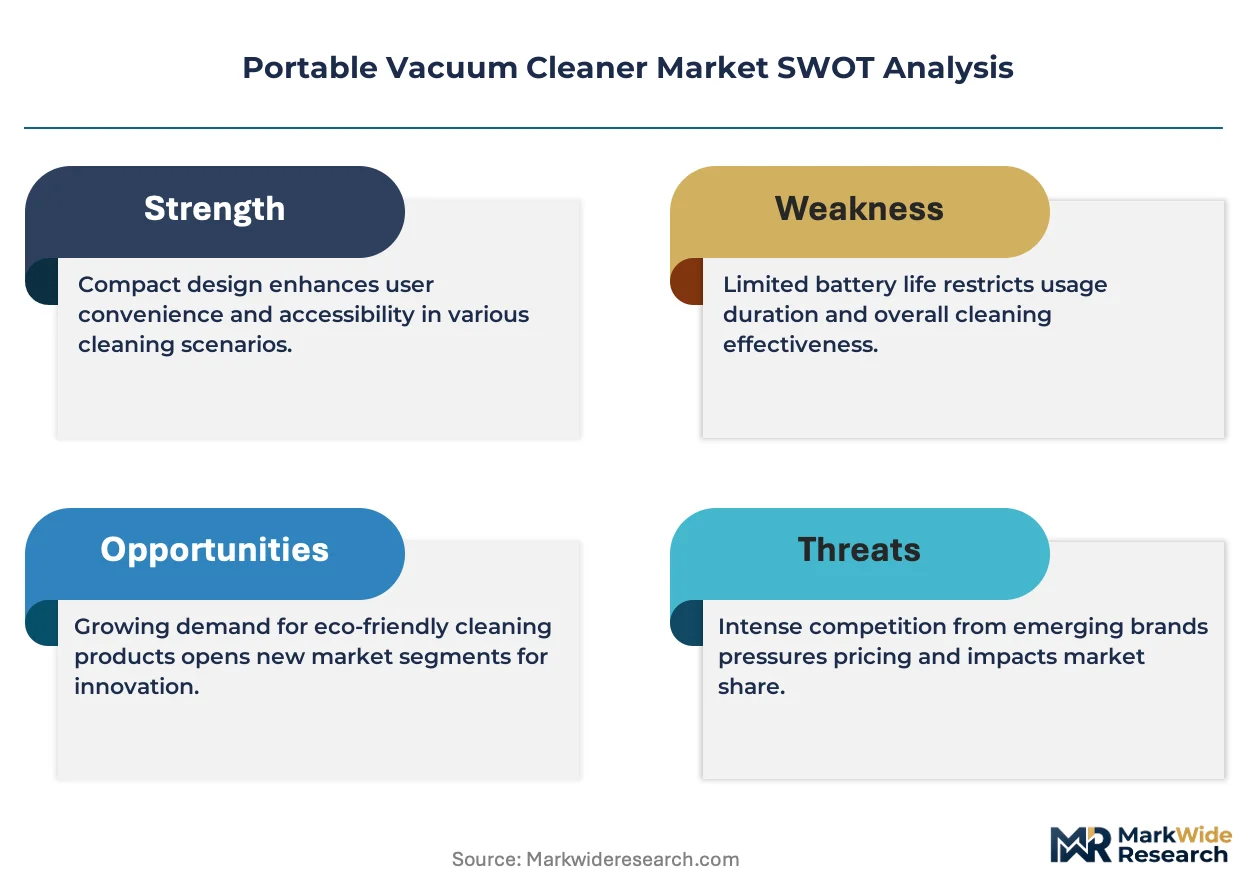
Multi-source motor and battery procurement is hardening as a competitive requirement for portable vacuum cleaner manufacturers. Dyson sustains its edge through captive R&D on digital motor platforms. SharkNinja leverages aggressive direct-to-consumer channel control in North America. Tineco anchors its expansion on rapid iteration of cordless stick formats with integrated smart features.
A portable vacuum cleaner constitutes a compact, electrically powered suction device typically operating below 1,500 watts, employing either cyclonic separation or bagged filtration to extract particulate matter from surfaces, and designed for maneuverability in constrained residential or commercial spaces. Cordless variants now dominate value creation as lithium-ion cell energy density improves runtime thresholds. HEPA filtration segments command margin premiums in households with allergy-sensitive occupants, while robotic formats remain a specialized, slower-growing niche constrained by mapping reliability and price positioning.
FCC electromagnetic emissions standards govern wireless-enabled models in the United States, while REACH and RoHS frameworks in Europe restrict hazardous substances in plastics and electronics, directly shaping material selection and supplier qualification timelines. China's GB standards and compulsory certification requirements filter market entry for imported units. Stakeholders must track how divergent energy-labeling schemes across these jurisdictions influence product architecture decisions and regional launch sequencing.
Market Dynamics
Brushless motor architectures are absorbing the bulk of manufacturer R&D investment as the EU Ecodesign framework tightens energy-efficiency thresholds, forcing a wholesale redesign of powertrain configurations across cordless stick and handheld formats.
Growth Catalysts
- REACH substance restrictions:European frameworks limiting hazardous materials in plastics are accelerating substitution toward recycled polymer feedstocks, opening margin recovery pathways for compliant suppliers.
- Urban apartment density:Space-constrained dwellings in metropolitan China and Germany are driving preference for collapsible stick formats with wall-mounted charging docks.
- Lithium-ion energy density gains:Cell chemistry improvements are extending runtime thresholds above 60 minutes, eliminating the corded-to-cordless performance gap for mainstream household cleaning tasks.
Market Restraints
- Rare earth magnet supply:Neodymium procurement concentrates in Chinese processing facilities, exposing motor manufacturers to export quota volatility and price spikes.
- Technical limitation in robotic mapping:Simultaneous localization and navigation algorithms struggle with low-light environments and reflective surfaces, constraining autonomous format penetration.
- FCC certification timelines:Wireless-enabled models face 12-16 week electromagnetic emissions testing queues, delaying North American launch windows.
Strategic Opportunities
- India household penetration:Cordless vacuum ownership remains below 8% of urban homes, creating first-mover advantage for brands establishing local assembly and service networks.
- Smart home convergence:Integration with voice assistants and automated scheduling platforms is absorbing consumer interest in connected appliance ecosystems.
- HEPA certification premiums:Allergy-sensitive households in Germany and Switzerland pay 25-40% markups for sealed-system filtration validated by independent testing laboratories.
Industry Challenges
- Brushless motor engineering talent:Shortages of power electronics specialists are extending product development cycles and inflating compensation packages in Shenzhen and Stuttgart engineering centers.
- Multi-jurisdiction labeling compliance:Divergent energy-efficiency grading schemes across the EU, US, and China force SKU proliferation and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Vacuum Cleaner Market |
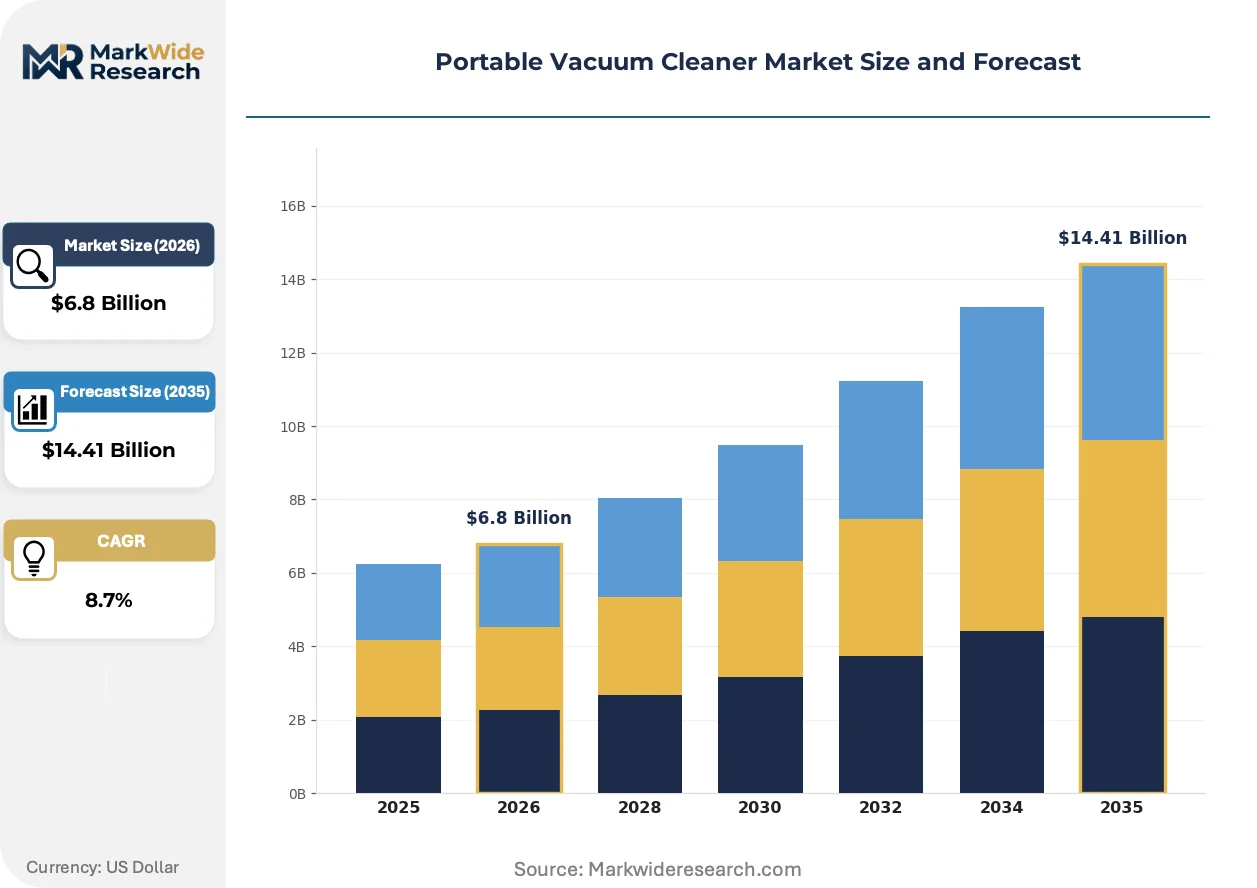
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Cordless, Robotic, Stick Technology: Dry, Wet/Dry, Cyclonic, HEPA End User: Households, Commercial, Automotive, Hospitality Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | Dyson, SharkNinja, BISSELL, Samsung Electronics, iRobot, Electrolux, Black+Decker, Hoover, Tineco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Vacuum Cleaner Market Evolving Landscape
Product architecture is pivoting toward modular, repairable designs as regulatory pressure intersects with consumer durability expectations, compressing replacement cycles for disposable-format incumbents.
Digital inverter motors are absorbing the functional role of conventional brushed architectures in premium cordless units. German and Chinese manufacturers are retrofitting production lines to accommodate hairpin winding techniques that boost copper fill factors. This transition is absorbing margin pressure from rare earth cost volatility while enabling sustained suction performance across battery discharge curves.
REACH substance restrictions are forcing reformulation of ABS housings and PVC cabling across European-bound production. Compounders in the Netherlands and Belgium are scaling bio-based flame retardant alternatives to replace legacy brominated additives. Handheld and stick formats targeting allergy-sensitive households face the steepest compliance costs due to extended skin-contact proximity requirements.
Direct-to-consumer channel expansion is compressing traditional retail markups in North American and Western European markets. SharkNinja and Dyson are deploying proprietary apps and subscription filter-replacement programs to capture lifetime value. This shift is most visible in urban US markets where big-box foot traffic has declined 15-20% since 2022, accelerating showroom-to-warehouse fulfillment model adoption.
Portable Vacuum Cleaner Market Segmentation
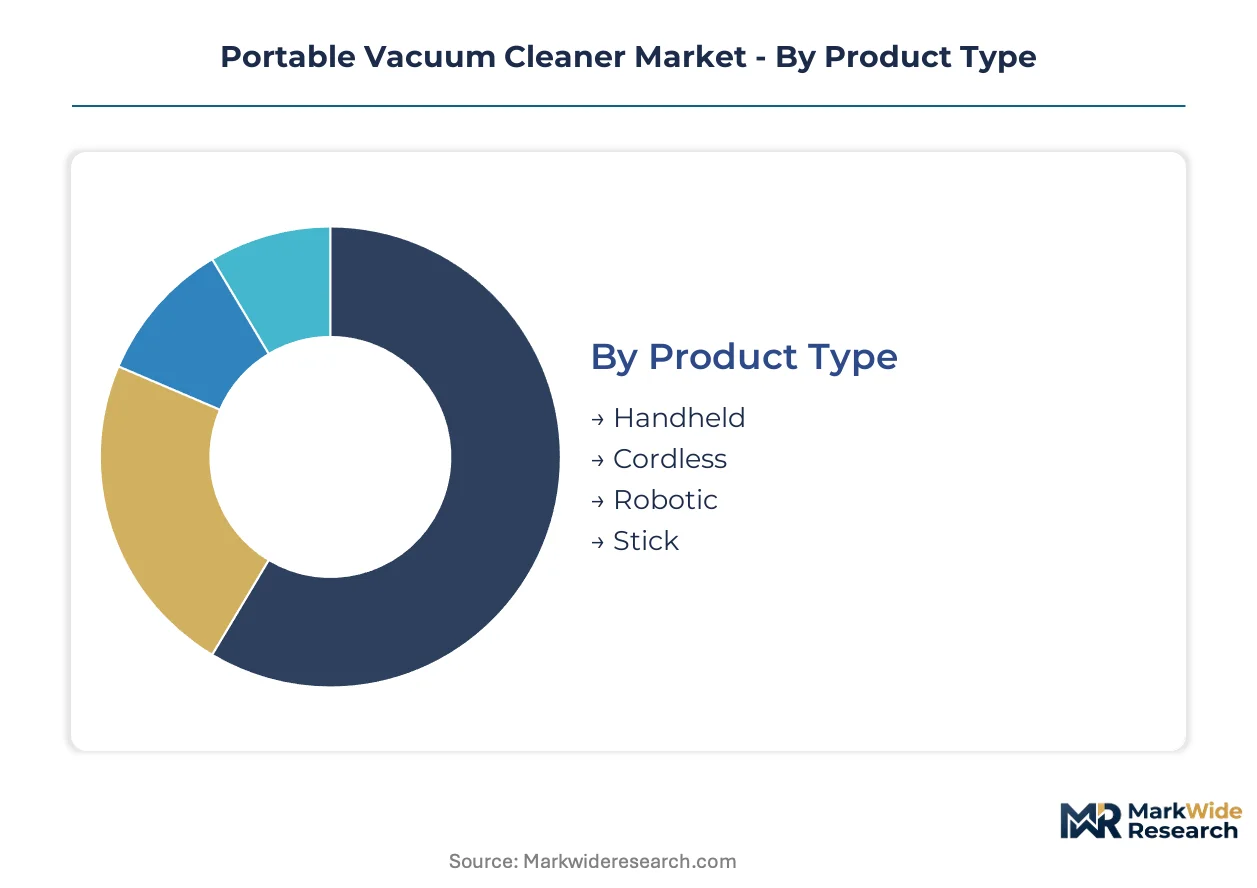
Segmentation in the portable vacuum cleaner market reveals how purchasing logic splits between performance priorities, space constraints, and procurement channel preferences. Manufacturers configure product portfolios across these dimensions to capture distinct margin profiles and replacement cycle rhythms.
Product Type:
Urban floorplans and storage limitations drive format selection more than suction specifications alone.
- Cordless Stick:Articulated wand designs with lithium-ion power packs now deliver sustained airflow previously requiring corded architectures. German and Chinese apartment complexes with minimal closet space generate concentrated demand for wall-mounted docking configurations.
- Handheld:Compact pistol-grip units target spot-cleaning tasks in automotive interiors and kitchen spills. The automotive aftermarket channel in the United States absorbs significant volume for cabin detailing applications.
- Robotic:Autonomous disc formats with LiDAR or camera-based navigation remain constrained by mapping reliability on multi-surface transitions. Technical limitations in low-light environments restrict penetration in windowless basements and evening cleaning schedules.
- Corded:Mains-powered canister and upright formats persist in price-sensitive segments and heavy-duty commercial applications where runtime certainty outweighs maneuverability tradeoffs.
Cordless stick leads on scale; robotic leads on momentum despite technical headwinds.
Technology:
Filtration certification and moisture-handling capability segment manufacturing cost structures and regional regulatory exposure.
- HEPA:Sealed-system designs with 99.97% particulate capture at 0.3 microns command substantial premiums in allergy-sensitive households across Switzerland and Germany. Independent laboratory validation requirements extend product development timelines.
- Cyclonic:Vortex separation chambers eliminate bag replacement costs while maintaining suction consistency across debris loads. Chinese manufacturers dominate component supply for multi-cone configurations.
- Wet/Dry:Sealed motor housings and corrosion-resistant materials enable liquid pickup for workshop and hospitality spill response. Commercial cleaning contractors in the United States specify these for multi-surface contracts.
- Dry:Conventional particulate-only architectures occupy entry price tiers where moisture exposure risk remains minimal.
HEPA captures margin leadership; cyclonic configurations expand most quickly across mid-market cordless platforms.
End User:
Usage intensity and durability expectations separate consumer from commercial procurement criteria.
- Households:Residential purchasers prioritize weight reduction, acoustic dampening, and aesthetic integration with interior finishes. Battery runtime thresholds above 45 minutes now satisfy single-session whole-home cleaning for average dwelling sizes.
- Commercial:Facility management operators specify replaceable battery packs and modular brush heads to minimize downtime in high-frequency cleaning regimens. Procurement concentrates through janitorial supply distributors.
- Automotive:Detailers and car wash operators demand compact formats with crevice tools and upholstery attachments for cabin interiors.
- Hospitality:Hotel housekeeping departments favor lightweight stick formats for rapid turnover between guest departures and arrivals.
Households dominate absolute volume; commercial segments sustain steepest expansion trajectory through fleet standardization.
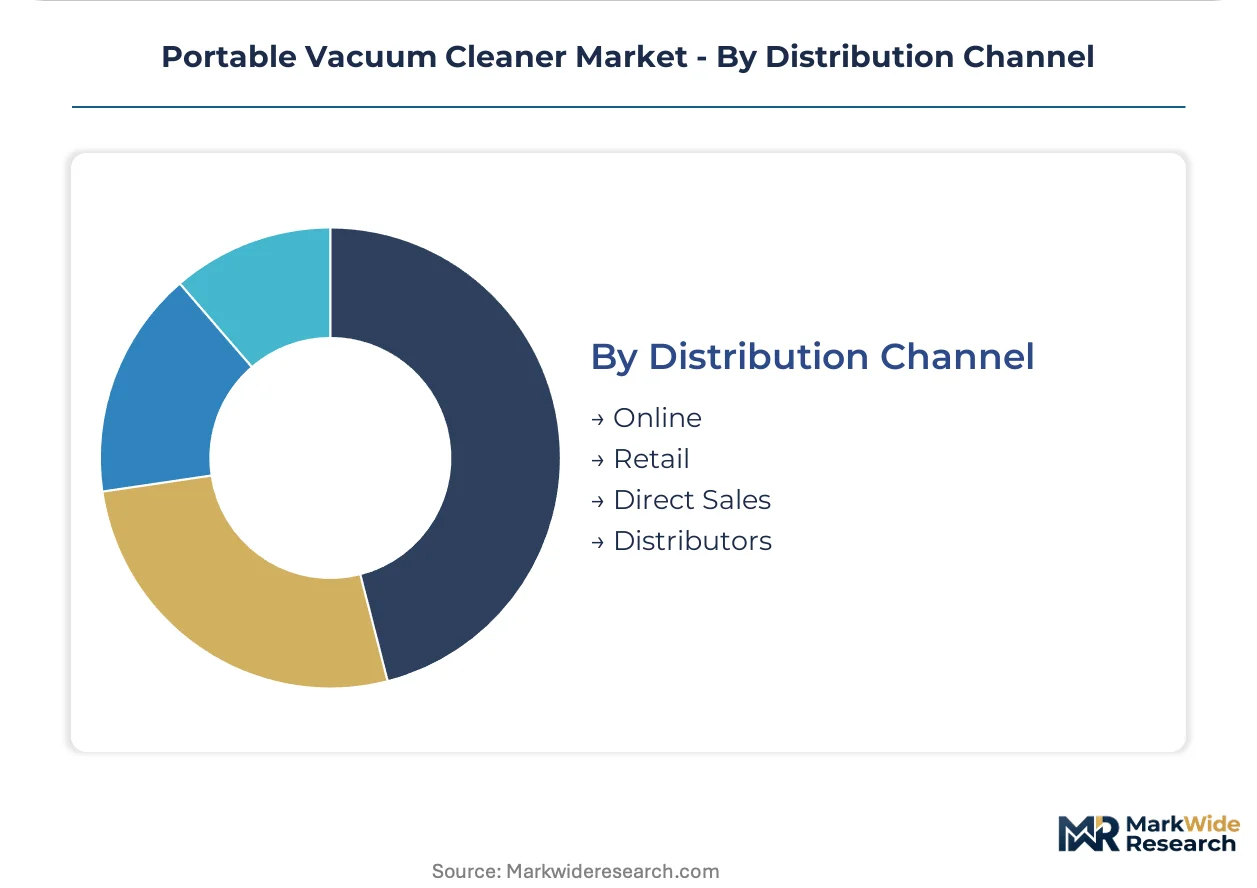
Distribution Channel:
Channel control determines margin retention and customer data access for filter subscription programs.
- Online:E-commerce platforms enable direct manufacturer relationships with detailed usage analytics and automated accessory replenishment. Amazon and brand-owned storefronts concentrate North American and Western European volume.
- Retail:Big-box and specialty appliance stores provide tactile evaluation for first-time cordless purchasers. Foot traffic declines since 2022 have compressed this channel's share in United States urban markets.
- Direct Sales:Manufacturer-controlled showrooms and door-to-door demonstrations sustain premium positioning for complex feature explanations.
- Distributors:Wholesale networks serve commercial and hospitality procurement with volume pricing and service contract bundling.
Online channels lead on scale; direct sales gain share fastest through proprietary app ecosystems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the portable vacuum cleaner industry's manufacturing density, with Guangdong Province housing the densest concentration of brushless motor foundries and lithium-ion pack assembly lines serving both domestic Chinese consumption and export markets.
China
Urban apartment dwellers in Shanghai and Beijing drive cordless stick adoption for space-constrained floorplans. MIIT enforces GB standards and compulsory certification that filter import entry while promoting domestic brands. Shenzhen's Bao'an district hosts vertically integrated motor-controller-battery clusters where hairpin winding techniques are scaling production.
United States
Direct-to-consumer channel migration and big-box foot traffic decline reshape how households procure cleaning appliances. FCC electromagnetic emissions standards govern wireless-enabled models with 12-16 week certification queues. Dallas-Fort Worth logistics hubs facilitate rapid fulfillment for Amazon and brand-owned storefronts competing for replacement filter subscriptions.
Germany
Allergy-sensitive households in Munich and Hamburg pay substantial markups for HEPA-certified sealed systems. REACH and RoHS frameworks restrict hazardous substances in plastics, accelerating bio-based flame retardant adoption. Stuttgart engineering centers face acute shortages of brushless motor power electronics specialists extending product development timelines.
India
Cordless vacuum ownership in urban Mumbai and Delhi-NCR remains below 8%, creating first-mover opportunities for brands establishing local assembly. BIS certification requirements and DGFT import regulations shape market entry strategies. Tamil Nadu's Sriperumbudur industrial corridor attracts contract manufacturers targeting cost-optimized stick formats for emerging middle-class households.
Japan
Compact dwelling norms in Tokyo and Osaka sustain preference for lightweight, acoustically dampened stick designs. METI energy-efficiency labeling influences product architecture decisions for premium-tier launches. Osaka-based trading houses coordinate Southeast Asian component sourcing for domestic brands emphasizing runtime optimization above 45-minute thresholds.
Portable Vacuum Cleaner Market Competitive Landscape
Global majors compete with regional champions across motor technology and distribution channel control, producing a tiered structure where captive R&D investments separate premium positioning from price-driven volume plays. The vendor base clusters around three strategic archetypes: vertically integrated technology owners, direct-to-consumer channel specialists, and rapid-iteration format innovators. Capacity expansion in Chinese motor foundries and strategic partnerships for battery cell procurement represent the dominant competitive moves reshaping supply security.
Within the technology-owner archetype, Dyson exemplifies captive digital motor platform development, while SharkNinja occupies a position defined by North American direct-to-consumer channel dominance. Tineco anchors the rapid-iteration tier through Shenzhen-based engineering proximity to component suppliers. These three entities represent distinct strategic postures rather than exhaustive market coverage, with each archetype commanding different margin structures and customer data access levels for subscription-based filter replenishment programs.
| Leading Market Players |
|---|
| Dyson |
| SharkNinja |
| BISSELL |
| Samsung Electronics |
| iRobot |
| Electrolux |
| Black+Decker |
| Hoover |
| Tineco |
| Others |
Value Network & Pricing Analysis
EU Ecodesign efficiency mandates and REACH substance restrictions are forcing manufacturers toward brushless motor architectures and bio-based polymer feedstocks, compressing margins in entry tiers while creating recovery pathways for compliant suppliers through certification premiums.
Pricing Analysis
Neodymium magnet cost pass-through from Chinese processing facilities is intensifying margin pressure across motor manufacturing tiers. Three-tier pricing structure across premium, standard, and economy levels separates HEPA-certified sealed systems from cyclonic mid-market units and entry-level dry formats. Cost compression in economy tiers reflects lithium-ion cell price volatility and rare earth exposure. Commercial fleet buyers exhibit lowest price sensitivity due to lifecycle cost modeling, while Indian emerging-middle-class households remain most price-constrained.
Supply Chain Analysis
India's PLI scheme and local-assembly incentives are reshaping sourcing patterns for brands targeting sub-8% household penetration rates in Mumbai and Delhi-NCR. Motor and battery production concentrates in China, South Korea, and Germany, with Shenzhen's Bao'an district hosting vertically integrated controller clusters. Neodymium procurement hinges on Chinese export quotas, creating single-source vulnerability for brushless architectures. Distribution runs through Amazon and brand-owned storefronts in North America, with janitorial supply distributors serving commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brushless motor standardization and HEPA certification premiums are expanding margin capture opportunities for manufacturers that consolidate power electronics expertise and allergy-sensitive positioning.
For Market Incumbents: Deepen captive R&D on digital motor platforms to defend against Shenzhen-based rapid-iteration competitors. Secure multi-source lithium-ion contracts to offset Chinese cell concentration risk. Invest in Stuttgart and Shenzhen engineering center retention programs to address power electronics talent scarcity. For New Entrants and Emerging Players: Enter via India's sub-8% cordless penetration corridor through Tamil Nadu assembly partnerships and BIS certification pathways. Target hospitality fleet standardization in Germany and Switzerland where HEPA premiums justify new brand positioning. Deploy direct-to-consumer apps with filter-subscription hooks to bypass entrenched retail gatekeepers. For Investors and Strategic Acquirers: Asymmetric upside sits with brushless motor technology owners and direct-to-consumer channel specialists with proprietary app ecosystems. Five-to-ten-year viability favors vertically integrated players with hairpin winding production capabilities and REACH-compliant polymer supply chains. Monitor EU Ecodesign threshold tightening as inflection signal for architecture migration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Brushless Motor Platform Development | Captive power electronics expertise insulates margin from rare earth volatility and Ecodesign compliance costs. |
| Direct-to-Consumer Channel Expansion | Proprietary app ecosystems capture lifetime filter-subscription value as US big-box foot traffic declines. |
| HEPA Certification Investment | Independent laboratory validation unlocks 25-40% markups in German and Swiss allergy-sensitive households. |
| India Local Assembly Partnership | Tamil Nadu production addresses BIS requirements and DGFT regulations for sub-8% penetration market entry. |
| Multi-Source Battery Procurement | Lithium-ion diversification beyond Chinese cell concentration reduces supply quota exposure and price spike risk. |
Research Methodology
Multiple input streams — executive interviews with motor engineering directors and supply chain leads, regulatory filings with ECHA and MIIT, and customs trade data — were reconciled against Nielsen retail audit patterns and hospital procurement databases. Primary fieldwork captured perspectives from brushless motor foundry operators in Shenzhen, HEPA testing laboratory managers in Germany, and janitorial supply distributors in Dallas-Fort Worth. Secondary validation drew from FCC certification queues, REACH substance restriction updates, and lithium-ion cell production disclosures. Bottom-up unit economics and top-down category spend estimates were triangulated to anchor volume assumptions.
Historical shipment trajectories were cross-referenced against panel input from platform engineers and category buyers to model cordless stick, handheld, robotic, and corded format splits across the projection horizon. Segmentation dimensions included product architecture, filtration technology, end-use intensity, and distribution channel control. CAGRs were derived from runtime threshold improvements, energy-density curves, and regulatory phase-in schedules. Forecast inputs incorporated hairpin winding adoption rates and bio-based flame retardant substitution timelines.
The model holds under stable rare earth export quotas and REACH enforcement continuity; deviation in Chinese neodymium policy or EU substance restriction acceleration would shift motor cost curves and compliance timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Qatar Gas Hobs Market
Household Items
Global Laptop Tables Market
Household Items
Insulated Tumblers Market
Household Items
Underwear Disinfection Dryers Market
Household Items
Disposable Napkins Market
Household Items
Brazil Cookware Market
Household Items
Drinkware Market
Household Items
Middle East Handheld Vacuum Cleaner Market
Household Items
Global Wet Vacuum Cleaner Market
Household Items
Smart Pool Skimmer Market
Household Items
Brush Cover Market
Household Items
Luxury Massage Chair Market
Household Items
Enameled Cookware Market
Household Items
US Air Purifier Market
Household Items
Remote Control Holder Market
Household Items
Kitchen Towel Market