
 US Handheld Vacuum Cleaners Market | 2026-2036
US Handheld Vacuum Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
US Handheld Vacuum Cleaners Market Insights
Pet-owning households is recalibrating demand profiles across the US handheld vacuum landscape, with fur-specific suction configurations now commanding premium positioning. Dyson leverages cyclonic separation patents to dominate high-end retail channels. SharkNinja sustains aggressive direct-to-consumer pricing that compresses margin structures for legacy brands. Bissell anchors its presence through specialized pet-hair product lines and deep big-box retail penetration.
US handheld vacuum cleaners are portable suction devices typically operating below 500 watts, employing lithium-ion battery packs or AC adapters to extract debris from confined surfaces, furniture, and vehicle interiors. Cordless configurations now lead unit shipments as lithium-ion energy density improvements extend runtime beyond twenty minutes per charge. Cyclonic technology captures the fastest-growing segment as consumers abandon bagged systems for zero-maintenance dust separation. Wet-dry applications concentrate margin pools in commercial and automotive channels where spill recovery commands price premiums over standard dry-only units.
FCC electromagnetic emissions standards constrain motor controller designs, while EPA ENERGY STAR thresholds filter low-efficiency models from federally procured inventories. OSHA indoor air quality guidelines in commercial settings are expanding HEPA filtration requirements beyond healthcare into hospitality and office deployments. Stakeholders must monitor evolving Department of Transportation interpretations regarding lithium-ion battery transport rules that could reshape warranty logistics and direct-ship fulfillment economics.
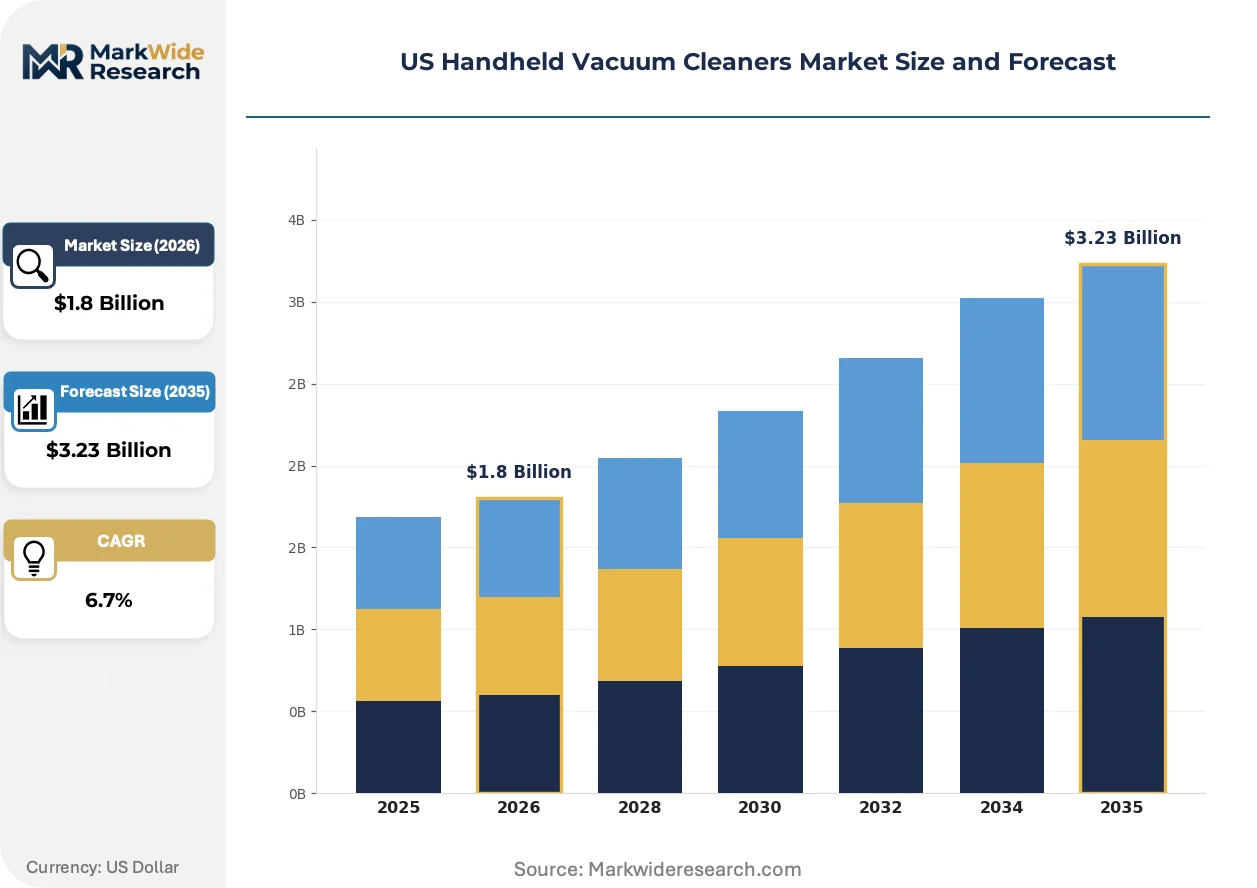
Market Dynamics
EPA ENERGY STAR certification thresholds are compressing low-efficiency motor designs out of federally procured inventories while lithium-ion energy density improvements extend cordless runtime beyond twenty minutes per charge.
Growth Catalysts
- Urban Apartment Density:Single-person households in California and Texas metro corridors are concentrating demand for compact cleaning tools that store in tight residential footprints.
- OSHA Indoor Air Quality Guidelines:Commercial hospitality and office deployments are expanding HEPA filtration requirements beyond traditional healthcare settings.
- Cyclonic Separation:Zero-maintenance dust separation technology is automating consumer abandonment of bagged collection systems.
Market Restraints
- Lithium-Ion Battery Supply Concentration:Asian cell manufacturers dominate cathode active material supply, creating input cost volatility for cordless unit producers.
- FCC Electromagnetic Emissions Standards:Motor controller designs face constrained design freedom from radio-frequency interference limits.
- AC-Powered Substitution:Corded configurations retain cost advantages in commercial cleaning fleets where runtime demands exceed battery economics.
Strategic Opportunities
- Wet-Dry Automotive Applications:Spill recovery functionality commands price premiums in vehicle interior detailing channels underserved by dry-only units.
- Direct-to-Consumer Fulfillment:Warranty logistics economics are being reshaped by evolving Department of Transportation lithium-ion battery transport interpretations.
- Pet-Hair Specialization:Fur-specific suction configurations address underpenetrated premium positioning among companion animal households.
Industry Challenges
- Certification Timeline Compression:EPA ENERGY STAR validation cycles delay product launches while competitors accelerate iterative motor releases.
- Supply Chain Reconfiguration:DOT battery shipping rule changes force warranty logistics restructuring and direct-ship fulfillment model overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Handheld Vacuum Cleaners Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corded, Cordless, Battery-Powered, Rechargeable Technology: Filtration, Cyclonic, Bagless, Wet/Dry Application: Home, Automotive, Commercial, Industrial End User: Residential, Contract Cleaners, Office, Hospitality |
| Companies Covered | Dyson, SharkNinja, Bissell, Black+Decker, Hoover, Samsung, Eureka, Tineco, iRobot Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Handheld Vacuum Cleaners Market Trends and Innovations
Cyclonic separation architecture, regulatory filtration mandates, and channel disintermediation are restructuring how handheld vacuum capabilities reach end-users.
Brushless DC motor controllers paired with high-density lithium-ion cells are automating runtime extension beyond legacy nickel-cadmium performance ceilings. Residential buyers in urban apartment configurations are adopting cordless configurations at accelerated replacement cycles. The technology is automating margin compression for AC-dependent legacy product lines while enabling premium positioning for battery-integrated designs.
EPA ENERGY STAR certification requirements are filtering sub-threshold motor efficiencies from federal procurement eligibility. Manufacturers must redesign winding configurations and magnetic materials to meet standby power limits. Commercial channel distributors in government supply contracts are most affected, pivoting inventory toward certified SKUs and discontinuing legacy motor platforms.
Single-person household formation is shortening replacement cycles and fragmenting purchase authority away from centralized retail. Big-box penetration is yielding share to direct-to-consumer platforms and specialized pet-care retail. California and Texas urban corridors exhibit the most visible channel rotation, with apartment-dwelling buyers prioritizing compact form factors over traditional retail service bundles.
US Handheld Vacuum Cleaners Market Segmentation
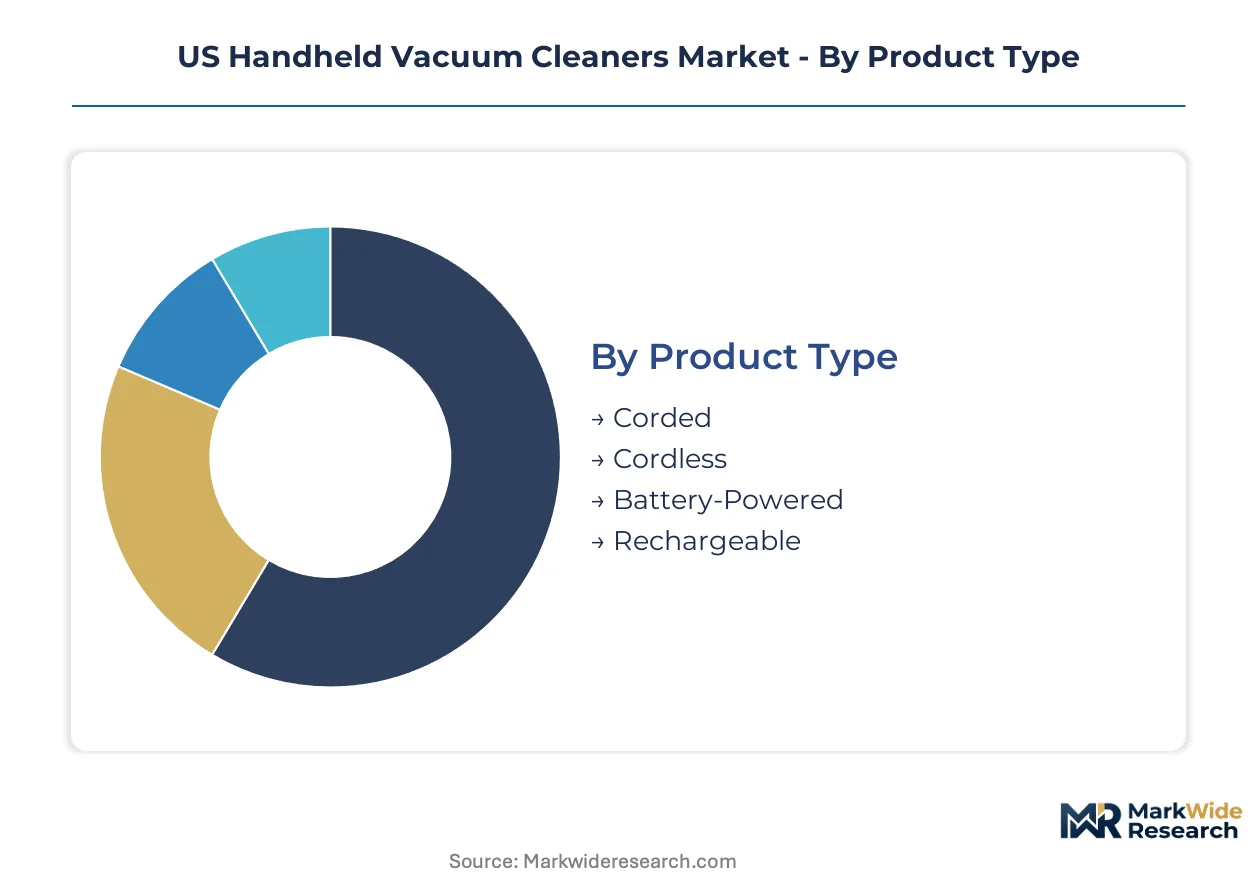
Segmentation in the US handheld vacuum market reveals how power source preferences, filtration architectures, and end-use environments create divergent margin profiles and replacement cadences. Understanding these partitions exposes where manufacturers can command premium positioning versus where price competition dominates.
Product Type:
Upgrade cycles accelerate where cordless runtime finally matches corded suction performance, compressing replacement windows for legacy AC-dependent units.
- Corded:AC-powered motors deliver sustained suction without battery degradation concerns. Demand persists among contract cleaners in Texas commercial corridors where runtime demands exceed current lithium-ion economics.
- Cordless:Lithium-ion configurations now dominate residential unit shipments as energy density improvements push runtime past twenty minutes. California apartment dwellers prioritize compact storage and maneuverability over tethered power.
- Battery-Powered:Removable cell designs enable field replacement and extend total product lifespan. Hospitality fleets value swap-and-go logistics over integrated battery disposal.
- Rechargeable:Integrated charging docks position these units as semi-permanent fixtures in urban kitchens. Single-person households favor grab-and-go convenience over full-size alternatives.
Volume placements concentrate in Cordless; the faster expansion belongs to Rechargeable.
Technology:
Cost tiers separate zero-maintenance cyclonic systems from consumable-dependent alternatives, with filtration mandates adding regulatory premiums to certified configurations.
- Filtration:HEPA-certified configurations capture allergen-sensitive residential buyers and OSHA-compliant commercial deployments. EPA indoor air quality guidelines expand mandatory filtration beyond healthcare into hospitality channels.
- Cyclonic:Centrifugal separation eliminates bag replacement costs and maintenance intervals. The architecture commands retail price premiums as consumers abandon recurring consumable purchases.
- Bagless:Transparent dust chambers provide visual feedback that triggers emptying behavior. Value-positioned SKUs target price-sensitive first-time buyers in Texas metro markets.
- Wet/Dry:Dual-functionality addresses spill recovery in automotive detailing and commercial food service. Margins concentrate where liquid handling justifies specialized motor sealing and corrosion-resistant materials.
Volume placements concentrate in Cyclonic; the steepest expansion trajectory belongs to Wet/Dry.
Application:
Customer type fragmentation separates impulse-driven residential purchases from specification-heavy commercial procurement with divergent warranty and service expectations.
- Home:Residential buyers prioritize compact form factors and storage efficiency. Urban apartment configurations in California drive demand for wall-mounted docking systems.
- Automotive:Crevices, upholstery, and trunk configurations require specialized attachments and flexible hoses. Detailing shops command price premiums for wet-dry spill recovery capabilities.
- Commercial:Contract cleaners demand runtime reliability and rapid battery swap protocols. OSHA guidelines in office and hospitality settings mandate HEPA filtration compliance.
- Industrial:Heavy-debris environments require reinforced housings and thermal protection. Limited volume concentrates in manufacturing facilities and warehouse maintenance fleets.
Volume placements concentrate in Home; the fastest share gain belongs to Commercial.
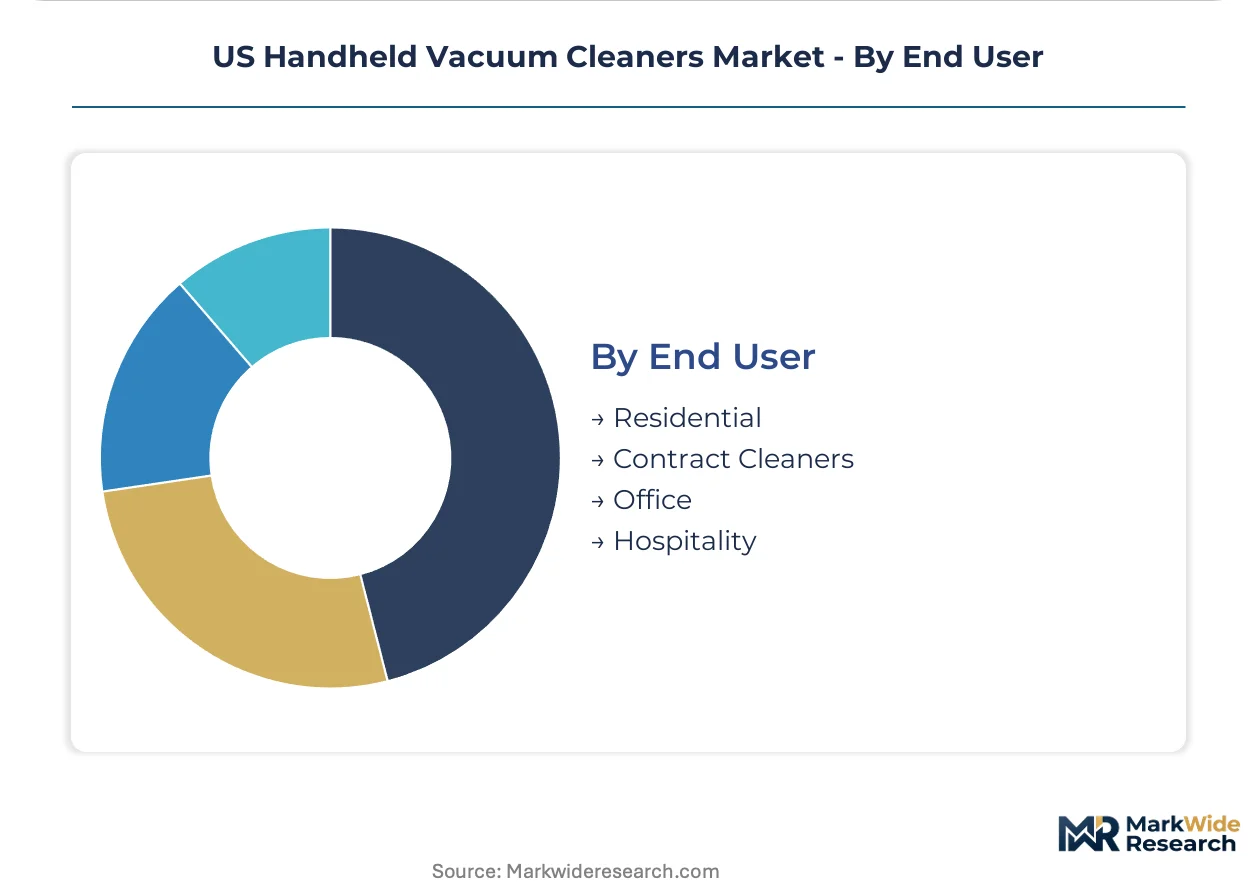
End User:
Margin concentration follows procurement authority fragmentation, with centralized fleet purchasing behaving differently than distributed household decision-making.
- Residential:Individual purchasers respond to direct-to-consumer pricing and pet-hair marketing. Replacement cycles shorten as cordless performance improves and brand loyalty weakens.
- Contract Cleaners:Fleet operators prioritize total cost of ownership and interchangeable battery platforms. Procurement concentrates through specialized distribution rather than retail channels.
- Office:Facility managers balance upfront cost against ENERGY STAR compliance for federal lease requirements. EPA certification thresholds filter low-efficiency models from eligible inventories.
- Hospitality:Housekeeping departments demand rapid room-turnaround capability and discrete operation. HEPA mandates from OSHA indoor air quality guidelines expand addressable market for certified units.
Volume placements concentrate in Residential; the climbing margin pool belongs to Hospitality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in Texas and California metro corridors are concentrating demand for compact cleaning tools as single-person household formation accelerates in dense urban cores.
California
Apartment dwellers in Los Angeles and San Francisco prioritize cordless configurations with wall-mounted docking systems. EPA ENERGY STAR certification thresholds filter low-efficiency models from state procurement contracts. San Diego's hospitality corridor drives HEPA-compliant commercial deployments under OSHA indoor air quality guidelines.
Texas
Dallas-Fort Worth and Houston contract cleaners demand runtime reliability exceeding current lithium-ion economics for fleet operations. FCC electromagnetic emissions standards constrain motor controller designs for regional manufacturers. Austin's tech corridor concentrates direct-to-consumer brand penetration among younger residential buyers.
New York Metro
Space-constrained Manhattan and Brooklyn residents favor rechargeable units as semi-permanent kitchen fixtures. Department of Transportation interpretations on lithium-ion battery transport reshape warranty logistics for Northeast distributors. Long Island's automotive detailing shops command wet-dry spill recovery premiums.
Florida
Orlando and Miami hospitality housekeeping departments prioritize rapid room-turnaround capability with discrete operation. OSHA guidelines expand HEPA filtration mandates into hotel and resort deployments. Tampa's retirement communities drive allergen-sensitive residential purchases.
Illinois
Chicago commercial office facility managers balance upfront cost against federal lease ENERGY STAR compliance requirements. EPA certification thresholds filter inventory eligibility for government supply contracts. Rockford's distribution hubs concentrate warranty logistics restructuring under evolving DOT battery shipping rules.
US Handheld Vacuum Cleaners Market Competitive Landscape
Top-tier vendors anchor premium positioning through cyclonic separation patents, while mid-tier competitors compress margins through aggressive direct-to-consumer pricing and specialized pet-hair configurations. The vendor base stratifies across three archetypes: technology licensors commanding retail price premiums, direct-to-consumer disruptors bypassing traditional distribution, and legacy manufacturers defending share through big-box retail penetration. Dominant competitive moves include portfolio diversification into wet-dry automotive applications and strategic partnerships reshaping lithium-ion battery supply security.
Among premium-tier technology specialists, Dyson occupies a position exemplifying cyclonic separation dominance, while SharkNinja represents the direct-to-consumer pricing compression archetype. Bissell anchors the pet-hair specialization vector within legacy retail channels. These three companies collectively illustrate how patent-protected engineering, channel disintermediation, and vertical category focus create divergent margin structures across the competitive landscape.
| Leading Market Players |
|---|
| Dyson |
| SharkNinja |
| Bissell |
| Black+Decker |
| Hoover |
| Samsung |
| Eureka |
| Tineco |
| iRobot Corporation |
| Others |
Pricing and Supply Chain Analysis
Brushless DC motor engineering talent concentrates in Shenzhen and Dongguan manufacturing corridors, where labor-cost differentials between coastal China and inland assembly zones directly determine pricing-tier spreads across premium cyclonic units versus entry-level bagless alternatives.
Pricing Analysis
Short lead-time premiums command twenty-to-thirty percent markups over spot inventory liquidated through direct-to-consumer channels. Three-tier pricing structure across premium, standard, and economy levels separates Dyson-patented cyclonic systems from SharkNinja's mid-market cordless configurations and Black+Decker's entry-level AC-powered units. Cost compression in the economy tier is intensifying because lithium-ion cell spot pricing volatility erodes integrated battery margins. Contract cleaners in Texas commercial fleets exhibit lowest price sensitivity due to total-cost-of-ownership procurement frameworks, while California apartment-dwelling first-time buyers drive volume through promotional elasticity.
Supply Chain Analysis
Ocean freight rate volatility from Shanghai and Ningbo ports to Long Beach reshapes landed cost calculations for cordless unit distributors. Cathode active material supply concentrates in China, South Korea, and Japan, while motor winding assemblies draw from Mexico maquiladora corridors and Vietnamese electronics parks. Single-source vulnerability sits with cylindrical 18650 cell formats from tier-one suppliers. Distribution runs through big-box retail consolidation in California and Texas, supplemented by direct-to-consumer fulfillment from regional 3PL nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive lithium-ion cell production and proprietary motor controller firmware determine margin capture. Players are pursuing backward integration into battery pack assembly to decouple from Asian cathode material pricing.
For Market Incumbents: Anchor cyclonic separation patent portfolios through incremental HEPA filtration certifications that satisfy OSHA hospitality mandates. Consolidate channel control by acquiring specialized pet-care retail distribution in California and Texas corridors. Direct-to-consumer pricing compression from SharkNinja represents the primary margin threat; defend through exclusive big-box promotional calendars and trade-in program financing. For New Entrants and Emerging Players: Solid-state battery chemistry roadmaps offer technology-first wedge positioning against incumbent lithium-ion runtime limitations. White-space concentrates in wet-dry automotive detailing channels where spill recovery functionality commands unserved price premiums. Target hospitality procurement managers in Florida and Illinois seeking rapid room-turnaround capability with discrete operation profiles. Go-to-market leverage sits with Amazon-native brand building and TikTok-native pet-hair demonstration content. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mid-tier specialists given ENERGY STAR certification acceleration as catalyst. Long-term viability frames around five-to-ten year lithium-ion chemistry transitions and regulatory filtration mandate expansion. Acquisition target archetype: cordless-focused brands with established direct-to-consumer fulfillment infrastructure and pending HEPA compliance pipelines. Signal to watch: Department of Transportation battery shipping rule interpretations that reshape warranty logistics economics and direct-ship fulfillment model viability.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Launch | SharkNinja's Amazon-native positioning compresses legacy retail margin structures for established brands. |
| Backward Integration into Battery Assembly | Captive lithium-ion pack production insulates margin volatility from Asian cathode material spot pricing. |
| HEPA Certification Investment | EPA ENERGY STAR thresholds filter non-compliant motor designs from federal and state procurement eligibility. |
| Premium Tier Introduction | Dyson's cyclonic patent portfolio commands retail price premiums through technology differentiation. |
| Distribution Channel Expansion | Specialized pet-care retail penetration anchors Bissell's fur-specific suction configuration market share. |
Research Methodology
Trade publications, customs import records, and EPA ENERGY STAR certification databases formed the secondary backbone, supplemented by primary interviews with cordless product engineering directors, big-box category buyers, contract cleaning fleet procurement managers, and lithium-ion battery supply specialists. Bottom-up unit shipment estimates triangulated against top-down retail dollar velocity through Nielsen and Circana point-of-sale tracking.
Bottom-up modeling segmented volume and value across power source configurations, filtration architectures, and end-use environments, then reconciled against top-down macroeconomic consumption indicators. CAGRs derived from regression analysis of replacement cycle compression, urban household formation rates, and regulatory certification timeline impacts. Industry-specific forecast inputs incorporated lithium-ion energy density improvement curves and OSHA indoor air quality guideline expansion trajectories.
Several conditions sit outside the modeled scope, including unannounced solid-state battery commercialization timelines and potential FCC electromagnetic emissions standard revisions. Forecasts reflect documented assumptions regarding DOT battery transport rule stability and Asian cathode material supply concentration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Electric Soap Dispenser Market
Household Items
Pet Fur Remover Market
Household Items
Window Rain Guards Market
Household Items
Brazil Cookware Market
Household Items
Robotic Vacuum Cleaner Market
Household Items
Cookware Market
Household Items
Global Disposable Toilet Seat Covers Market
Household Items
Indoor Humidifier Market
Household Items
Portable Humidifiers Market
Household Items
Stainless Steel Water Bottles Market
Household Items
Stainless Steel Vacuum Flask Market
Household Items
Knife Set Market
Household Items
Smart Pool Skimmer Market
Household Items
Steam Cleaners Market
Household Items
Air Freshener Market
Household Items
Electric Clothes Drying Hanger Market