
 Dryer Sheets Market | 2026-2036
Dryer Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Dryer Sheets Market Analysis
Multi-sourcing of nonwoven substrates and fragrance encapsulation chemistries is realigning how dryer sheet manufacturers secure supply. Henkel AG & Co. KGaA leverages its European chemical supply chain to sustain cost-competitive production of fabric softener formulations. Church & Dwight Co., Inc. anchors its position through specialization in baking-soda-based deodorizing variants that differentiate from conventional silicone-heavy offerings.
Dryer sheets are thin, nonwoven fabric substrates impregnated with cationic surfactants, fatty acid salts, and fragrance carriers that deposit softening agents onto textiles during the tumble-drying cycle, typically operating effectively at temperatures between 50°C and 70°C. The natural material segment is gaining structural momentum as biodegradable substrates displace petroleum-based polyester nonwovens in premium retail channels. Traditional scented products still dominate volume across mass-market household customer types, though margin pools are shifting toward chemical-free formulations sold through specialty grocers and direct-to-consumer platforms.
EPA oversight of volatile organic compound emissions and ECHA enforcement of REACH chemical registration requirements are tightening permissible fragrance loads and surfactant chemistries in major Western markets. BIS standards in India and GB standards in China add further compliance layers for brands seeking manufacturing or import access across multiple jurisdictions. Stakeholders must monitor evolving biodegradability certifications and regional chemical restriction lists to anticipate reformulation costs and retail delisting risks.
Market Dynamics
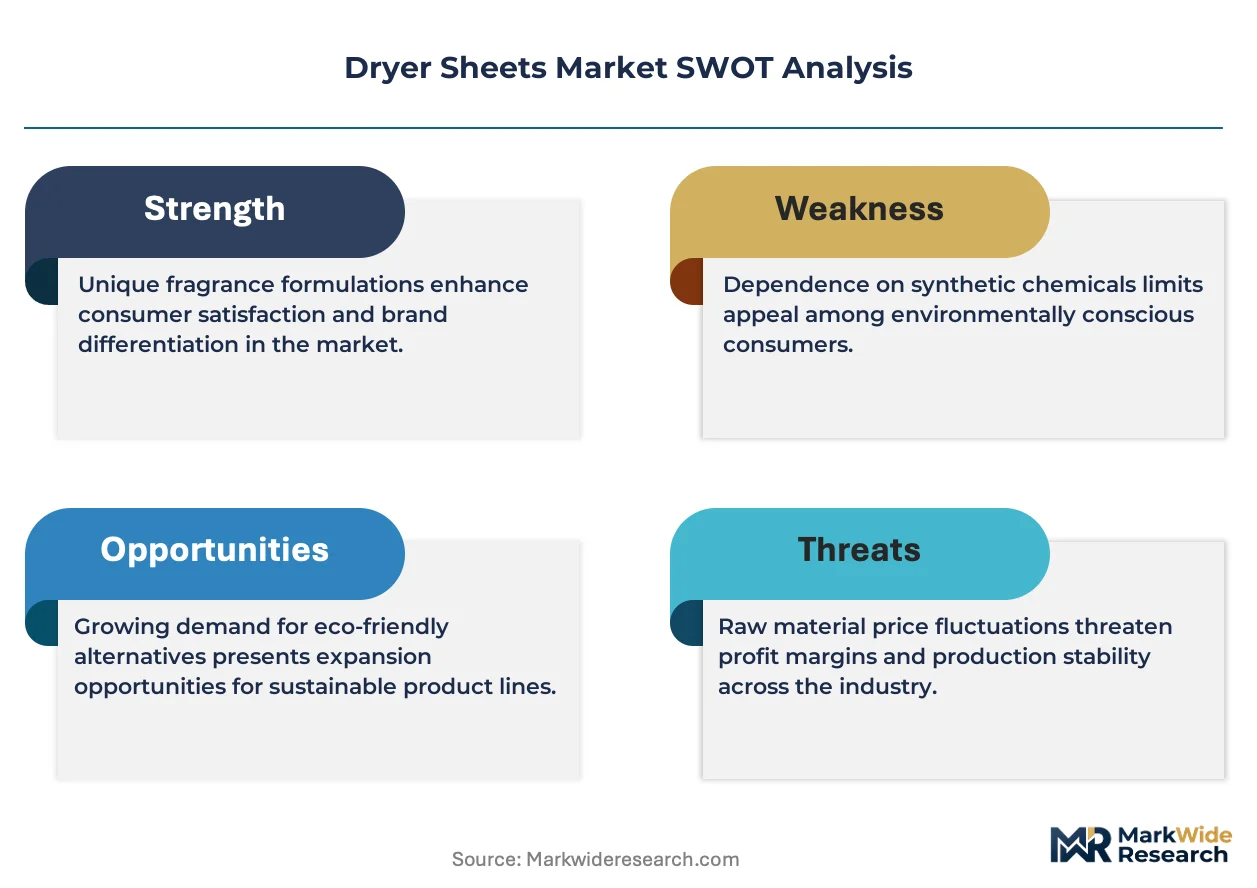
Biodegradable substrate adoption is forcing wholesale reformulation across dryer sheet manufacturing, as petroleum-based polyester nonwovens face retail delisting pressure from major grocers and hospitality procurement mandates.
Growth Catalysts
- REACH chemical registration:ECHA enforcement of fragrance load limits is accelerating investment in encapsulated scent technologies that comply while preserving performance.
- Hospitality commercial laundry:Hotel chains and linen services are expanding fabric conditioning protocols to extend textile replacement cycles and reduce operational costs.
- Cellulose fiber substrates:Wood-pulp-derived nonwovens are achieving cost parity with synthetic alternatives, enabling mass-market biodegradable variants.
Market Restraints
- Quaternary ammonium compound costs:Cationic surfactant feedstock volatility, tied to palm oil and petrochemical derivatives, compresses margin stability for formulators.
- Fragrance encapsulation concentration:Three European chemical suppliers control proprietary microencapsulation chemistries, creating supply vulnerability.
- Heat-activated release limitations:Current technologies require sustained 50°C-70°C dryer cycles, leaving cold-air and low-temperature applications unserved.
Strategic Opportunities
- Indian urban households:Washing machine penetration in tier-2 and tier-3 cities remains below saturation, creating first-mover positioning for dryer sheet brands.
- Subscription direct-to-consumer:Refillable dispenser systems and scheduled delivery models bypass retail slotting fees while capturing recurring revenue.
- EU Green Deal procurement criteria:Public-sector and institutional purchasing mandates for biodegradable products open tender opportunities excluded from conventional players.
Industry Challenges
- Biodegradability certification timelines:OECD 301B and ASTM D5338 testing protocols require 28-day minimum validation cycles, delaying product launches.
- Fragrance chemist scarcity:Formulation expertise combining encapsulation science with natural extract stability commands premium compensation and extended recruitment horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dryer Sheets Market |
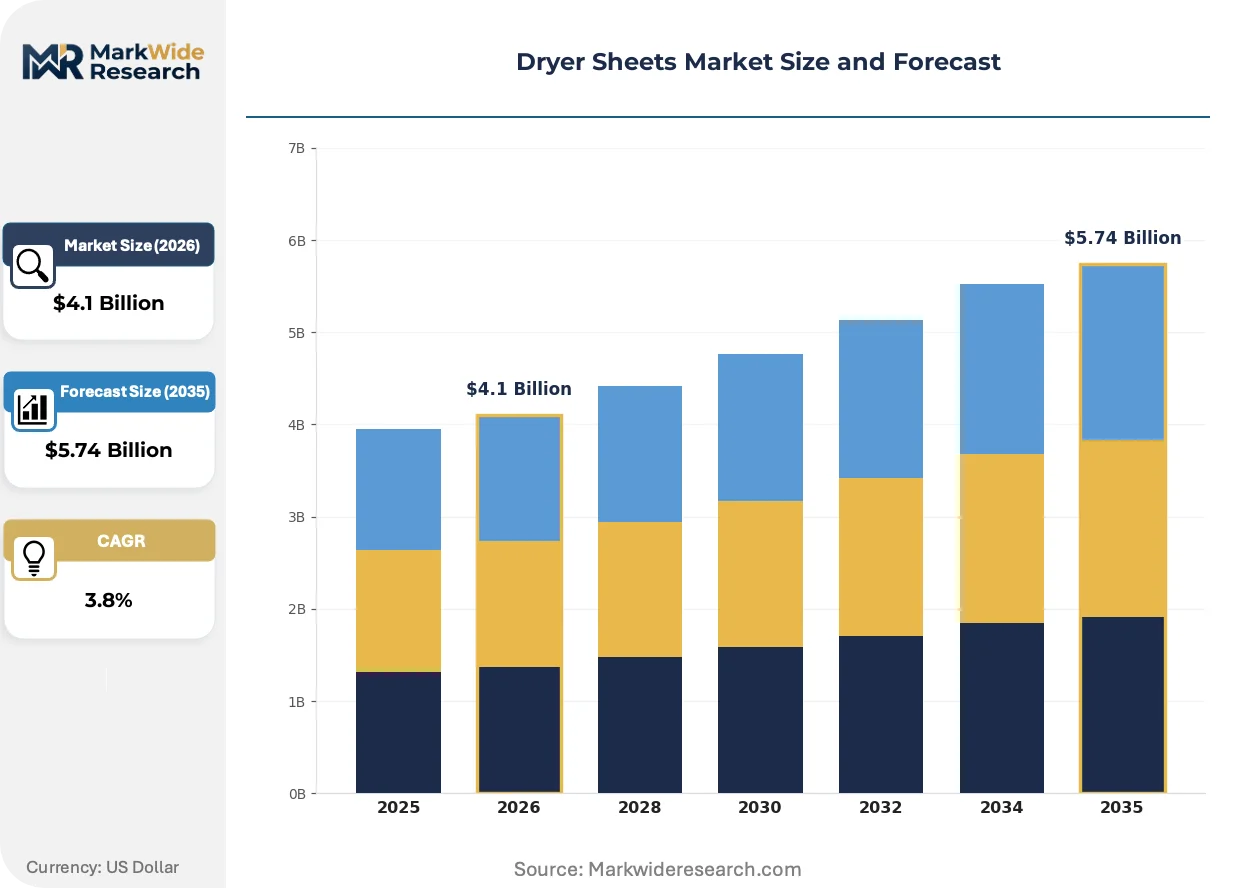
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $5.74 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Natural, Scented, Unscented Form: Single-sheet, Bulk-pack, Refillable, Dryer Ball Material: Fabric Softener, Biodegradable, Chemical-free, Synthetic Customer Type: Households, Commercial, Hospitality, Retail |
| Companies Covered | Henkel AG & Co. KGaA, Church & Dwight Co., Inc., The Procter & Gamble Company, Colgate-Palmolive Company, Reckitt Benckiser Group plc, S.C. Johnson & Son Inc., The Clorox Company, Seventh Generation, Inc., Unilever PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dryer Sheets Market Emerging Trajectories
Plant-derived softening actives and water-soluble substrates are converging to redefine product architecture, while regulatory chemical restrictions and hospitality procurement standards reshape competitive requirements.
Cellulose-based nonwoven substrates impregnated with plant-derived quaternary compounds are rewriting how softening agents deposit onto textiles during tumble cycles. Boutique hotel chains and eco-certified lodging operators are adopting these variants at accelerated procurement cycles. The technology is rewriting margin structures by enabling premium pricing while reducing petroleum-derived input exposure.
EPA volatile organic compound emission limits for consumer products are tightening permissible fragrance concentrations in dryer sheet formulations. Manufacturers must reformulate with lower-volatility carriers or invest in sealed-delivery packaging systems. Mass-market scented variants sold through big-box retailers face the steepest compliance costs and shelf-space renegotiation.
Specialty grocers and zero-waste retail concepts are displacing conventional supermarket channels for natural-positioned dryer sheet brands. Direct-to-consumer subscription models with refillable aluminum dispensers capture recurring revenue from urban millennials and environmentally certified households. Germany and Scandinavia exhibit the most pronounced channel migration, where packaging waste regulations and deposit-return systems accelerate adoption of concentrated or sheet-free alternatives.
Dryer Sheets Market Segmentation
Dryer sheet segmentation reveals divergent compliance burdens across product architectures, with natural and biodegradable variants navigating REACH chemical registration and EPA volatile organic compound limits while conventional formulations face fewer reformulation mandates. Material composition and customer channel selection determine which certification timelines and testing protocols manufacturers must absorb.
Product Type:
Traditional and scented variants require fragrance load documentation under ECHA REACH enforcement, while natural and unscented segments navigate biodegradable substrate certification through OECD 301B protocols.
- Traditional:Petroleum-based polyester substrates impregnated with quaternary ammonium surfactants dominate mass-market retail placement. United States big-box channels sustain volume concentration despite margin compression from feedstock volatility tied to palm oil derivatives.
- Natural:Plant-derived softening actives on cellulose-based nonwovens command premium positioning through specialty grocers and direct-to-consumer platforms. EU Green Deal procurement criteria in Germany and Scandinavia accelerate hospitality sector adoption for eco-certified lodging operators.
- Scented:Fragrance encapsulation chemistries face tightening EPA emission limits requiring lower-volatility carriers or sealed-delivery packaging investments.
- Unscented:Formulations bypass fragrance regulatory complexity, appealing to chemically sensitive households and healthcare textile services with minimal reformulation overhead.
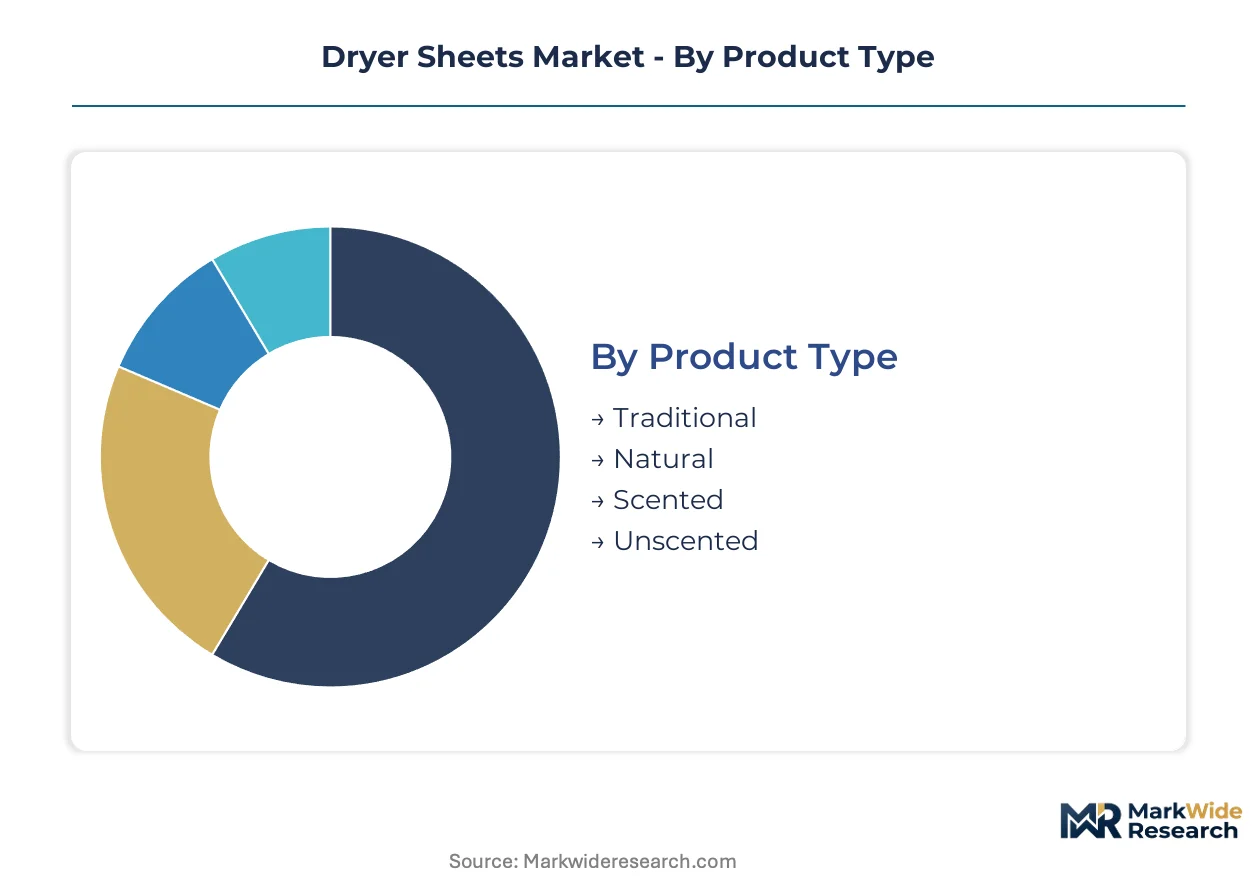
Traditional sits at the top of the volume ranking, with Natural climbing the fastest.
Form:
Packaging architecture determines distribution economics, with bulk-pack and single-sheet variants optimized for retail slotting fees while refillable systems capture lifetime value through recurring revenue models.
- Single-sheet:Individual sachet packaging maximizes retail shelf flexibility and trial conversion for new fragrance introductions. United States supermarket chains favor this format for promotional velocity and inventory turnover metrics.
- Bulk-pack:Multi-hundred count boxes reduce per-unit packaging costs and serve commercial laundry services with predictable throughput requirements. Hospitality procurement mandates in the United States favor this format for operational standardization across property portfolios.
- Refillable:Aluminum dispenser systems with concentrated sheet refills align with zero-waste retail concepts and subscription direct-to-consumer models capturing urban millennial households.
- Dryer Ball:Reusable solid alternatives eliminate substrate consumption entirely, appealing to package-free retail channels and deposit-return system environments in Germany.
Bulk-pack generates the steadiest revenue base, with Refillable gaining share fastest through channel migration toward subscription platforms.
Material:
Substrate chemistry dictates biodegradability certification requirements, with cellulose-derived and chemical-free segments absorbing 28-day minimum OECD 301B validation cycles while synthetic alternatives face retail delisting pressure.
- Biodegradable:Wood-pulp-derived nonwovens achieve cost parity with polyester alternatives, enabling mass-market penetration. REACH compliance documentation and ASTM D5338 testing protocols add launch timeline overhead.
- Fabric Softener:Conventional cationic surfactant formulations on synthetic substrates retain manufacturing scale advantages and established supply chains.
- Chemical-free:Baking-soda-based deodorizing actives differentiate from silicone-heavy offerings, commanding specialty placement through health-focused retail channels.
- Synthetic:Petroleum-based polyester nonwovens face procurement exclusion from major grocers and hospitality sustainability mandates, compressing addressable market scope.
Fabric Softener maintains volume leadership, with Biodegradable expanding most quickly as cellulose fiber costs converge with synthetic alternatives.
Customer Type:
Channel selection determines pricing power and certification burden intensity, with hospitality and commercial segments demanding batch documentation while household retail absorbs compliance costs through brand premiums.
- Households:Mass-market and premium scented variants serve washing machine owners across United States suburban and urban markets. Natural-positioned brands capture margin through specialty grocer placement and direct-to-consumer subscription models.
- Commercial:Industrial-scale laundry services prioritize bulk-pack formats with predictable softening performance metrics and textile replacement cycle extension.
- Hospitality:Hotel chains and linen services adopt fabric conditioning protocols to reduce operational costs, with eco-certified properties mandating biodegradable substrate procurement.
- Retail:Private-label and branded product assortment decisions by mass-market and specialty channels determine segment visibility and trial access.
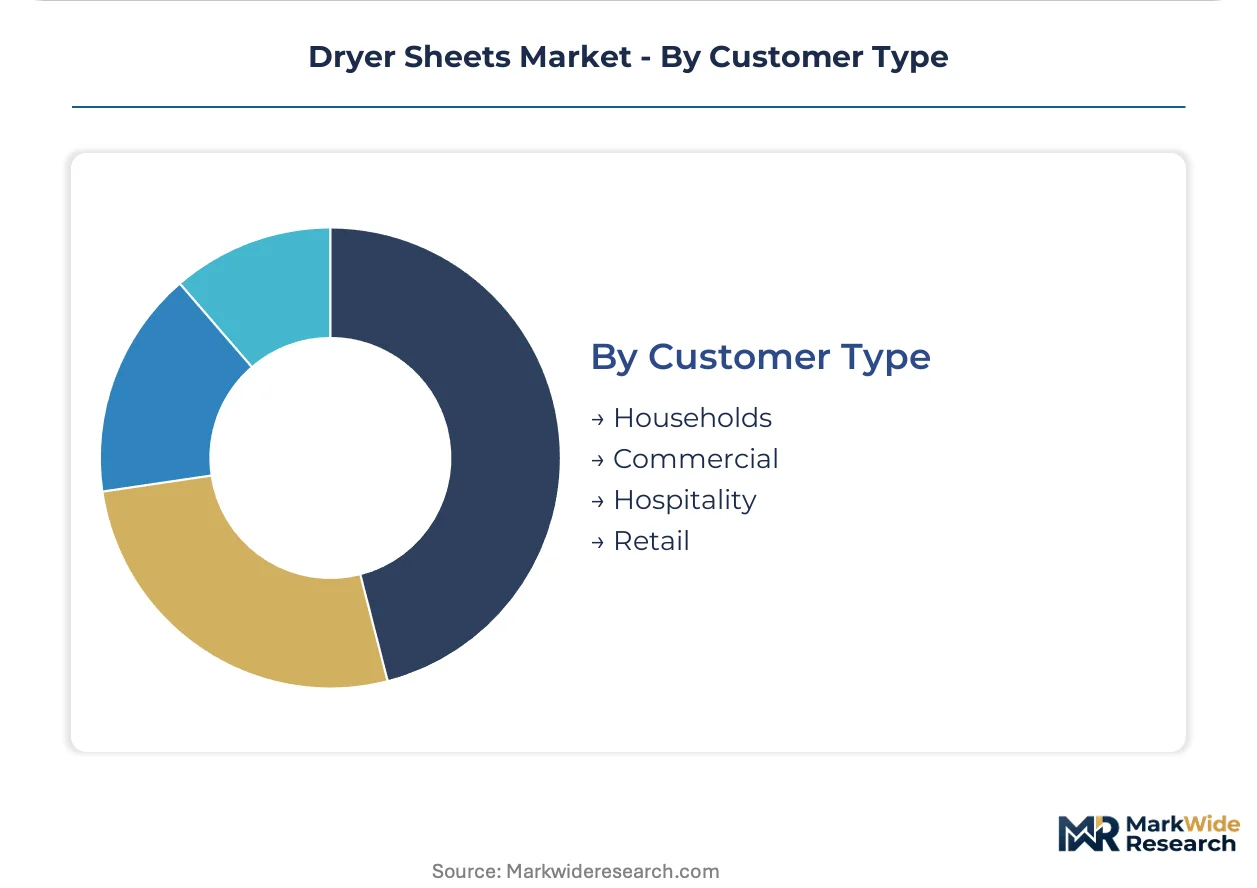
Households anchor volume concentration, with Hospitality showing the steepest expansion trajectory through commercial laundry service outsourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing migration follows divergent chemical registration costs, with producers relocating formulation activities to jurisdictions offering streamlined compliance pathways or feedstock proximity. This arbitrage dynamic concentrates supply chain investments in specific national clusters while reshaping export competitiveness.
United States
EPA volatile organic compound emission limits drive reformulation investments among domestic producers serving big-box retail channels. The Inflation Reduction Act's clean manufacturing incentives accelerate biodegradable substrate pilot programs in Ohio and North Carolina chemical corridors. Chicago-based commercial laundry services expand fabric conditioning protocols across Midwest hospitality networks.
Germany
ECHA REACH enforcement of fragrance load limits positions German chemical suppliers as encapsulation technology gatekeepers. EU Green Deal procurement criteria mandate biodegradable variants for federal and municipal institutional purchasing. Bavarian industrial clusters host concentrated pilot production of cellulose-derived nonwoven substrates.
China
GB standards compliance requirements shape export-oriented manufacturing for Western market access. Dual carbon goals accelerate domestic substitution of petroleum-based polyester nonwovens in Yangtze River Delta production zones. Shanghai-based converters develop cost-competitive wood-pulp substrate alternatives for Southeast Asian export markets.
India
BIS standards enforcement creates compliance barriers for imported finished goods while protecting domestic formulation investments. Washing machine penetration gaps in tier-2 and tier-3 cities present first-mover positioning opportunities for dryer sheet brands. Gujarat chemical corridors concentrate cationic surfactant feedstock production for regional fabric softener supply.
Brazil
ANVISA cosmetic and household product registration timelines delay imported natural-variant launches in Latin America's largest consumer market. São Paulo metropolitan retail channels sustain volume concentration for mass-market scented formulations. Southeast Brazilian industrial zones develop regional biodegradable substrate capabilities to serve Mercosur trade bloc requirements.
Dryer Sheets Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty positioning through natural formulations and direct-to-consumer channels. The market exhibits consolidated leadership among multinational consumer goods conglomerates with diversified household product portfolios, while mid-tier specialists concentrate on single-category depth. Three archetypes dominate: vertically integrated chemical conglomerates controlling surfactant supply, brand houses leveraging retail slotting relationships, and mission-driven naturals specialists capturing premium margins through certification differentiation. Competitive moves center on substrate material transitions and subscription platform investments.
Among European chemical conglomerates, Henkel AG & Co. KGaA anchors the integrated-formulator archetype through captive surfactant supply chains. Church & Dwight Co., Inc. exemplifies the specialty-deodorizing position with baking-soda-based differentiation from silicone-heavy conventional offerings. The Procter & Gamble Company represents scale-driven brand architecture, leveraging retail relationship density across mass-market channels. These three occupy distinct competitive vectors without direct overlap in core positioning.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Church & Dwight Co., Inc. |
| The Procter & Gamble Company |
| Colgate-Palmolive Company |
| Reckitt Benckiser Group plc |
| S.C. Johnson & Son Inc. |
| The Clorox Company |
| Seventh Generation, Inc. |
| Unilever PLC |
| Others |
Supply Flow & Price Mechanics
Palm oil derivative price volatility cascades through cationic surfactant feedstock markets into three-tier pricing structures across premium natural, standard biodegradable, and economy synthetic tiers. Buyers in United States mass-market channels absorb compressed margins while hospitality procurement mandates force premium tier migration.
Pricing Analysis
Input-cost pass-through from quaternary ammonium compound volatility stratifies pricing across certification-grade tiers. Premium natural variants command placement premiums through specialty grocers while standard biodegradable segments face cost compression from cellulose fiber substrate scaling. Economy synthetic tiers encounter price erosion as retail delisting pressure concentrates volume in compliant alternatives. Mass-market households exhibit highest price sensitivity; eco-certified hospitality buyers accept premium positioning for procurement mandate compliance.
Supply Chain Analysis
Direct-to-retail channels handle United States big-box velocity while commercial laundry services source through distributor consolidation points. Germany, China, and India concentrate nonwoven substrate manufacturing with feedstock proximity advantages. Wood-pulp cellulose, petrochemical-derived polyester, and palm oil-based cationic surfactants anchor material dependencies. Single-source vulnerability concentrates in European fragrance encapsulation chemistries controlled by three proprietary suppliers. Distribution runs through retail slotting fee negotiations and subscription platform direct fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between REACH compliance costs in Germany and streamlined BIS pathway investments in India, where formulation licensing timelines favor domestic production anchoring.
For Market Incumbents: Extend cellulose substrate capacity in Bavarian industrial clusters to capture EU Green Deal procurement volumes before biodegradable mandates harden. Deepen captive surfactant supply through palm oil derivative hedging instruments. Consolidation of fragrance encapsulation partnerships with German chemical suppliers defends against supply interruption from proprietary technology gatekeepers. For New Entrants and Emerging Players: Cold-air laundry applications in Japanese and South Korean urban households remain unserved by heat-activated release technologies. Tier-2 Indian cities present washing machine penetration gaps without established dryer sheet habits. Direct-to-consumer subscription models with aluminum dispenser systems bypass retail slotting barriers while capturing recurring revenue from millennial households. For Investors and Strategic Acquirers: Consolidation pressure builds where biodegradable certification overhead exceeds standalone R&D capacity for mid-tier regional formulators. Long-term viability favors vertically integrated players with captive cellulose fiber supply and encapsulation technology licensing. Watch for hospitality procurement mandate acceleration in Germany and Scandinavia as inflection signal for premium tier demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Substrate Scale-Up | Cellulose fiber cost parity with polyester enables mass-market natural variant penetration. |
| Fragrance Encapsulation Partnership | European chemical supplier alliances secure REACH-compliant scent technology access. |
| Direct-to-Consumer Platform Launch | Subscription aluminum dispenser systems capture urban millennial recurring revenue pools. |
| Commercial Laundry Service Expansion | Hospitality procurement mandates in United States Midwest extend textile replacement cycles. |
| Backward Integration into Surfactant Supply | Palm oil derivative hedging stabilizes margin exposure for cationic formulation production. |
Methodological Framework
Multiple input streams — primary interviews with brand managers and category buyers at mass-market retailers, technical R&D directors at nonwoven converters, and procurement leads at commercial laundry services — were reconciled against secondary validation from customs records, Nielsen retail audit data, and SEC 10-K filings of diversified household product conglomerates. Bottom-up volume modeling across substrate material tiers and customer channels triangulated with top-down market sizing from trade association disclosures.
Historical shipment data cross-referenced against panel input from supply chain participants informed analytical framework construction across the projection horizon. Segmentation dimensions modeled include product architecture, material composition, packaging format, and regional regulatory cluster. CAGRs derived from elasticity-adjusted volume trajectories incorporate washing machine penetration curves and hospitality outsourcing intensity as industry-specific forecast inputs.
Underlying measurement precision varies by segment; traditional synthetic variants carry tighter precision than emerging biodegradable categories due to established trade data coverage. Forecasts reflect assumptions about cellulose fiber cost convergence timelines and REACH enforcement stringency trajectories. Periodic stress-testing of base assumptions is recommended against regulatory acceleration or feedstock price dislocation scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Silicone Soap Mold Market
Household Items
North America Ceramic Barbeque Grill Market
Household Items
Global Ceramic Tableware Market
Household Items
Manual Bottle Opener Market
Household Items
Mosquito Lamps Market
Household Items
Hand Dryer Market
Household Items
Portable Showers Market
Household Items
Japan Cookware Market
Household Items
Europe & UK Nonstick Cookware Market
Household Items
Stick Vacuum Cleaner Market
Household Items
Dry and Wet Wipes Market
Household Items
North America Tankless Water Heater Market
Household Items
Leaf Blower Market
Household Items
Book Light Market
Household Items
Commercial Locker Market
Household Items
Laundry Dryer Sheets and Bars Market