
 Basin, Bowl, and Cup Market | 2026-2036
Basin, Bowl, and Cup Market Size, Share, and Industry Trends Forecast 2026-2036
Basin, Bowl, and Cup Market Intelligence
Southeast Asian thermoforming clusters are pivoting toward biodegradable sheet capacity to serve European export contracts. Dart Container Corporation leverages its captive resin sourcing and North American plant network to sustain price stability across foodservice accounts. Berry Global anchors its position through multi-layer barrier technology for hot-fill cups used in quick-service restaurants.
Basins, bowls, and cups comprise rigid hollowware vessels engineered to specific volumetric tolerances, wall thicknesses, and thermal shock resistance thresholds for containment, mixing, or serving applications. Ceramic serving bowls fired at temperatures exceeding 1200°C dominate premium residential tableware due to durability and aesthetic finish, while injection-molded polypropylene drinking cups command commercial catering volumes through unit-cost efficiency and stackability logistics. Stainless steel mixing bowls retain industrial kitchen preference where thermal conductivity and dent resistance justify higher per-unit spend against disposable alternatives.
The FDA's food-contact substance notification process and the EU's REACH Annex XVII restricted substance list govern material migration limits for plastic vessels entering consumer channels. China's SAMR enforces GB 4806 series standards on polymeric materials, creating divergent testing burdens for exporters serving multiple jurisdictions. Stakeholders must monitor evolving extended producer responsibility frameworks in Europe and North America to anticipate redesign obligations and recyclability mandates before compliance deadlines crystallize.
Market Dynamics
Hospital procurement departments are consolidating purchasing power into single-use medical vessel contracts, forcing manufacturers to retool for sterile packaging workflows and validated production environments.
Growth Catalysts
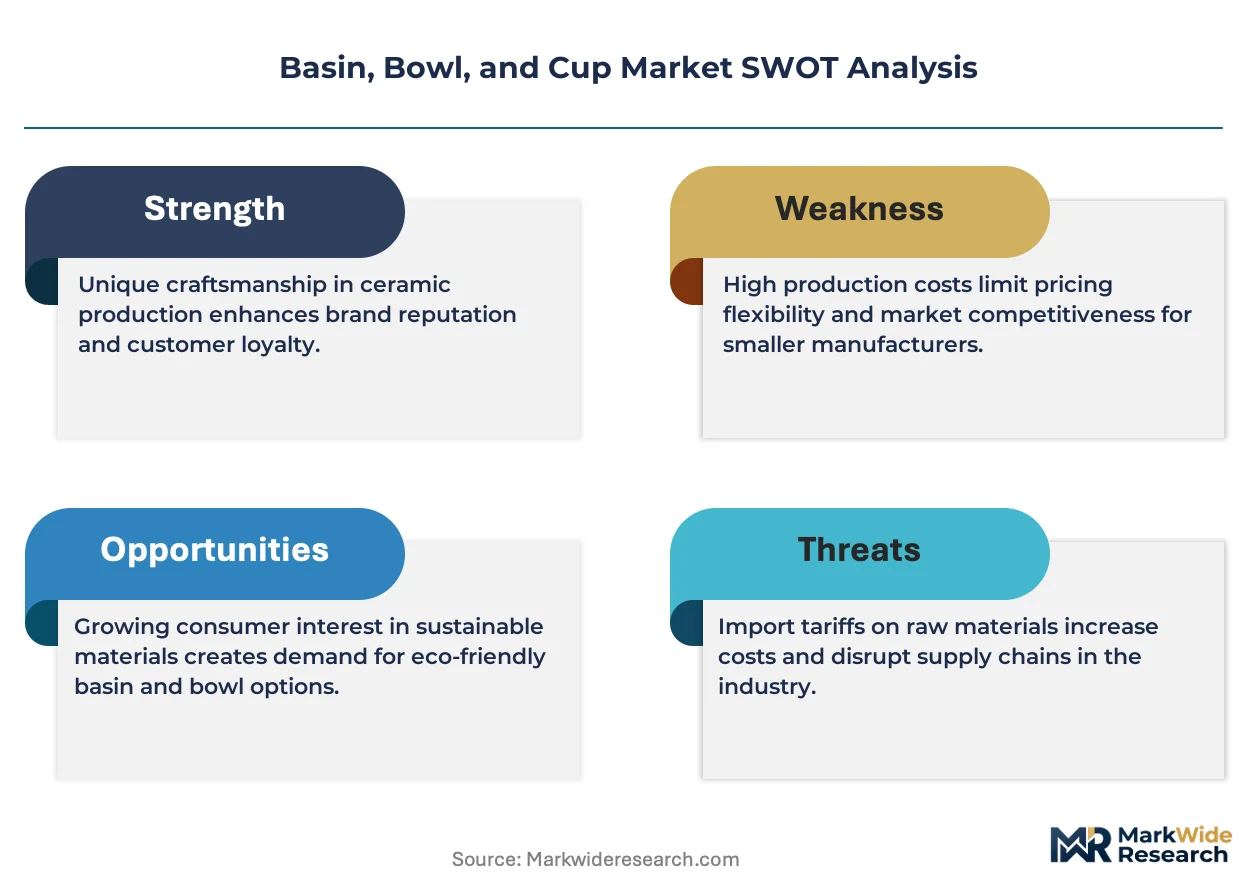
- GB 4806 Compliance Mandates:China's SAMR enforcement of food-contact polymer standards is accelerating domestic testing laboratory capacity expansion and certified resin formulation development.
- Institutional Catering Scale:India's mid-day meal programs and corporate cafeteria networks are standardizing on injection-molded polypropylene bowls for portion control and dishwasher durability.
- Thermoforming Biodegradation:Southeast Asian sheet extruders are converting starch-blend and PLA lines to capture EU Green Deal-aligned export procurement.
Market Restraints
- Propylene Feedstock Volatility:Crude-linked polypropylene pricing swings compress margin predictability for high-volume cup molders serving quick-service restaurant chains.
- REACH Annex XVII Migration Testing:ECHA's restricted substance list creates multi-jurisdiction compliance stacking for exporters serving both European and Chinese channels simultaneously.
- Ceramic Kiln Energy Intensity:Natural gas-fired sintering above 1200°C exposes premium tableware producers to carbon border adjustment exposure under EU CBAM phased implementation.
Strategic Opportunities
- Extended Producer Responsibility Tailwinds:EU Packaging and Packaging Waste Regulation mandates are creating design-for-recycling service contracts with brand owners seeking compliance pathway certainty.
- Barrier Technology Convergence:Multi-layer EVOH and tie-layer coextrusion is opening hot-fill cup applications previously reserved for glass and metal in ready-meal distribution.
- Direct-to-Institution E-Procurement:Hospital group purchasing organizations and university dining consortia are bypassing traditional distribution tiers for factory-direct container sourcing.
Industry Challenges
- Migration Testing Talent Scarcity:Analytical chemists capable of running FDA food-contact substance notifications and EU overall migration studies command premium compensation in contract laboratory markets.
- Hot-Runner Retrofit Capex Burden:Converting cold-runner injection systems for thin-wall cup production requires mold base replacement and auxiliary drying equipment investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Basin, Bowl, and Cup Market |
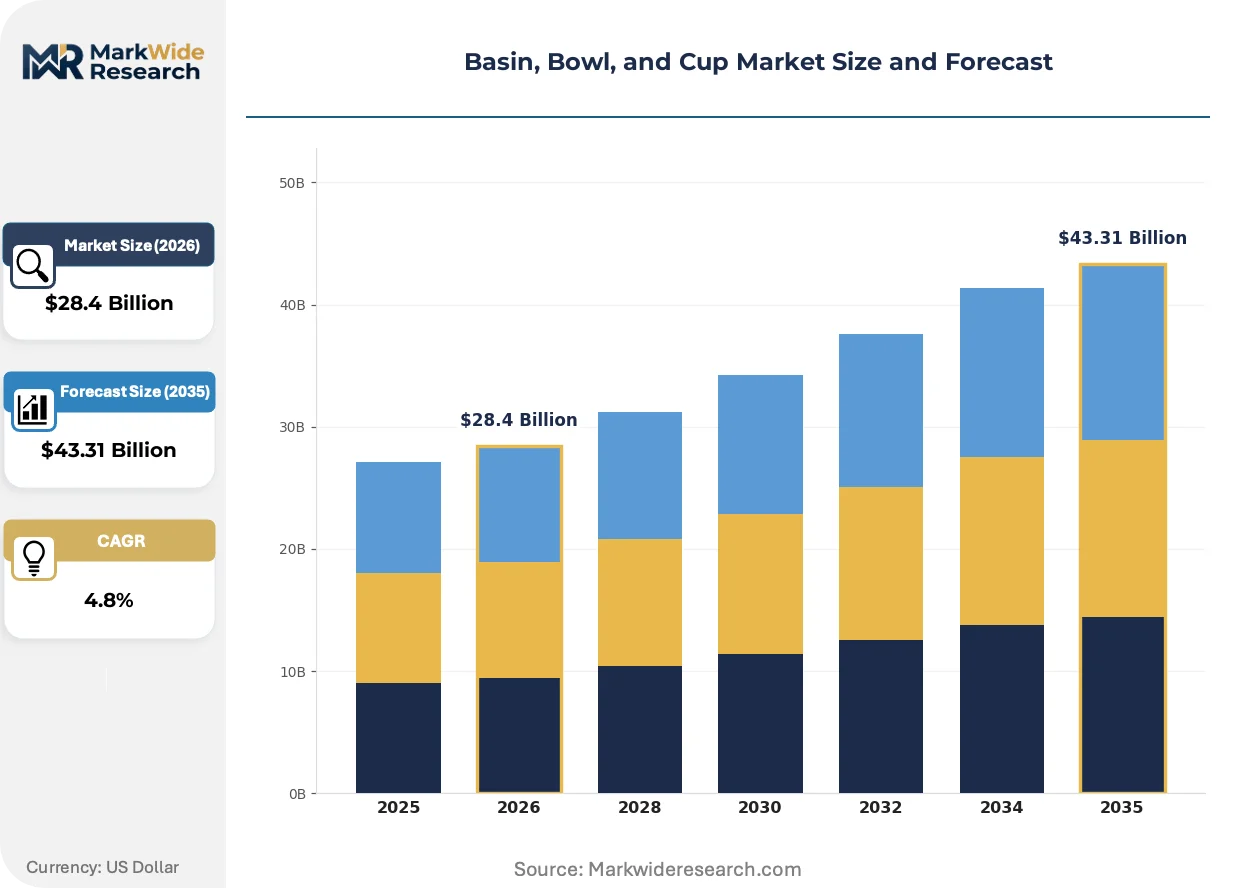
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $43.31 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serving Bowl, Mixing Bowl, Wash Basin, Drinking Cup Material: Ceramic, Glass, Stainless Steel, Plastic Manufacturing Stage: Molded, Handcrafted, Pressed, Injection Molded Usage Type: Residential, Commercial, Industrial, Catering |
| Companies Covered | Dart Container Corporation, Bioleader, Medtronic, Packware China, GreenChoice Packaging, Cardinal Health, Berry Global, Narang Medical Limited, The Vollrath Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Basin, Bowl, and Cup Market Strategic Shifts & Innovations
Material substitution pressures and regulatory compliance automation are compressing product development cycles while expanding the addressable application set for polymer vessels.
Polylactic acid and polyhydroxyalkanoate sheet formulations are rewriting the cost-performance tradeoff for cold-fill disposable cups. Quick-service restaurant chains in Northern Europe are piloting these materials for beverage lids and portion cups ahead of single-use plastic bans. The technology is compressing the viable window for conventional PS and PP in temperature-sensitive applications.
REACH Annex XVII restrictions on phthalates and bisphenol analogs are forcing reformulation of polycarbonate and PVC-based vessels across EU member states. Compounders are accelerating bio-based plasticizer validation to maintain clarity and impact resistance in transparent drinking cups. The regulatory pressure is concentrating compliance investment among exporters with existing European distribution infrastructure.
Consolidated procurement by hospital materials management departments is displacing fragmented purchasing through medical supply distributors. Group purchasing organizations are mandating lot-level traceability and sterile barrier validation for single-use basins and emesis containers. The behavioral shift is most visible in US health systems pursuing Joint Commission accreditation with standardized supply formularies.
Basin, Bowl, and Cup Market Segmentation
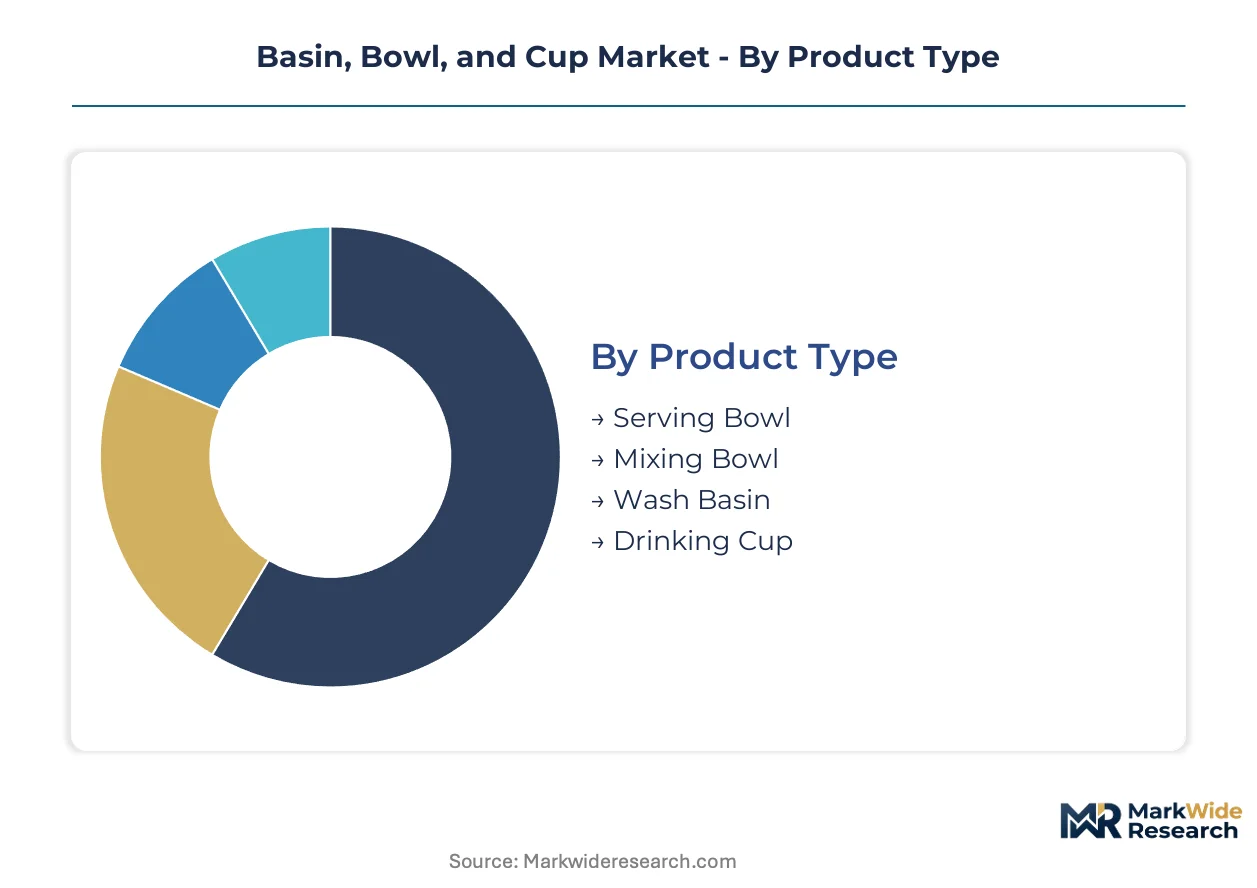
Segmentation in this market separates capital-heavy ceramic kiln operations from lean thermoforming workflows, with material choice and manufacturing method determining margin structures and regulatory exposure. Understanding these divides reveals why certain vessel categories attract consolidated investment while others fragment across regional specialists.
Product Type:
Serving bowls demand the heaviest upfront investment due to decorative glazing infrastructure and brand-building marketing spend, while drinking cups run on standardized mold platforms with rapid tooling amortization.
- Serving Bowl:Fired ceramic or tempered glass constructions with aesthetic surface finishes command premium residential tableware positioning. Hospitality procurement in India's institutional catering sector is standardizing portion-controlled serving bowls for mid-day meal distribution programs.
- Mixing Bowl:Stainless steel variants with graduated volumetric markings and non-slip silicone bases dominate commercial bakery and food processing applications. EU REACH compliance costs for metal finishing chemistries are pushing smaller fabricators toward contract manufacturing arrangements with certified foundries.
- Wash Basin:Medical-grade polypropylene basins for hospital sterile processing require validated cleanroom production environments.
- Drinking Cup:Thin-wall injection-molded designs prioritize stack density for quick-service restaurant logistics.
Serving bowls absorb the bulk of installed capacity; drinking cups are expanding most quickly.
Material:
Cost tier stratification separates commodity resin formulations from certified food-contact substrates, with ceramic occupying the highest price band and plastic spanning the widest volume range.
- Ceramic:Alumina-silicate bodies fired above 1200°C achieve vitrification for thermal shock resistance and surface impermeability. EU carbon border adjustment mechanisms threaten natural gas-intensive kiln operations in Southeast Asian export clusters.
- Glass:Borosilicate and soda-lime compositions serve temperature-stable beverage service and laboratory applications. China's GB 4806 glass migration testing protocols are diverting export volumes toward domestic certification laboratories.
- Stainless Steel:18/8 chromium-nickel grades provide dent resistance and thermal conductivity for industrial kitchen environments.
- Plastic:Polypropylene homopolymer and copolymer grades dominate through unit-cost efficiency and dishwasher durability.
Plastic commands the widest production base; ceramic maintains the steepest expansion trajectory in premium residential channels.
Manufacturing Stage:
Volume concentration clusters around automated molding platforms, while handcrafted output serves niche artisanal positioning with limited scalability.
- Molded:Compression and transfer molding of thermoset composites yields durable institutional serveware with thick-wall impact resistance. Hospital group purchasing organizations are consolidating specifications around molded basins for standardized sterile processing workflows.
- Handcrafted:Wheel-thrown and slip-cast ceramic techniques preserve regional aesthetic traditions for luxury hospitality and gift markets. Japanese Mino-yaki and Arita porcelain clusters sustain export premiums through craft-designation branding.
- Pressed:Automated hydraulic pressing of ceramic powder achieves dimensional consistency for stackable dinnerware at mid-market price points.
- Injection Molded:High-cavitation tooling with hot-runner systems produces thin-wall cups at cycle times under four seconds.
Injection molded output scales fastest; handcrafted segments defend margin through scarcity positioning.
Usage Type:
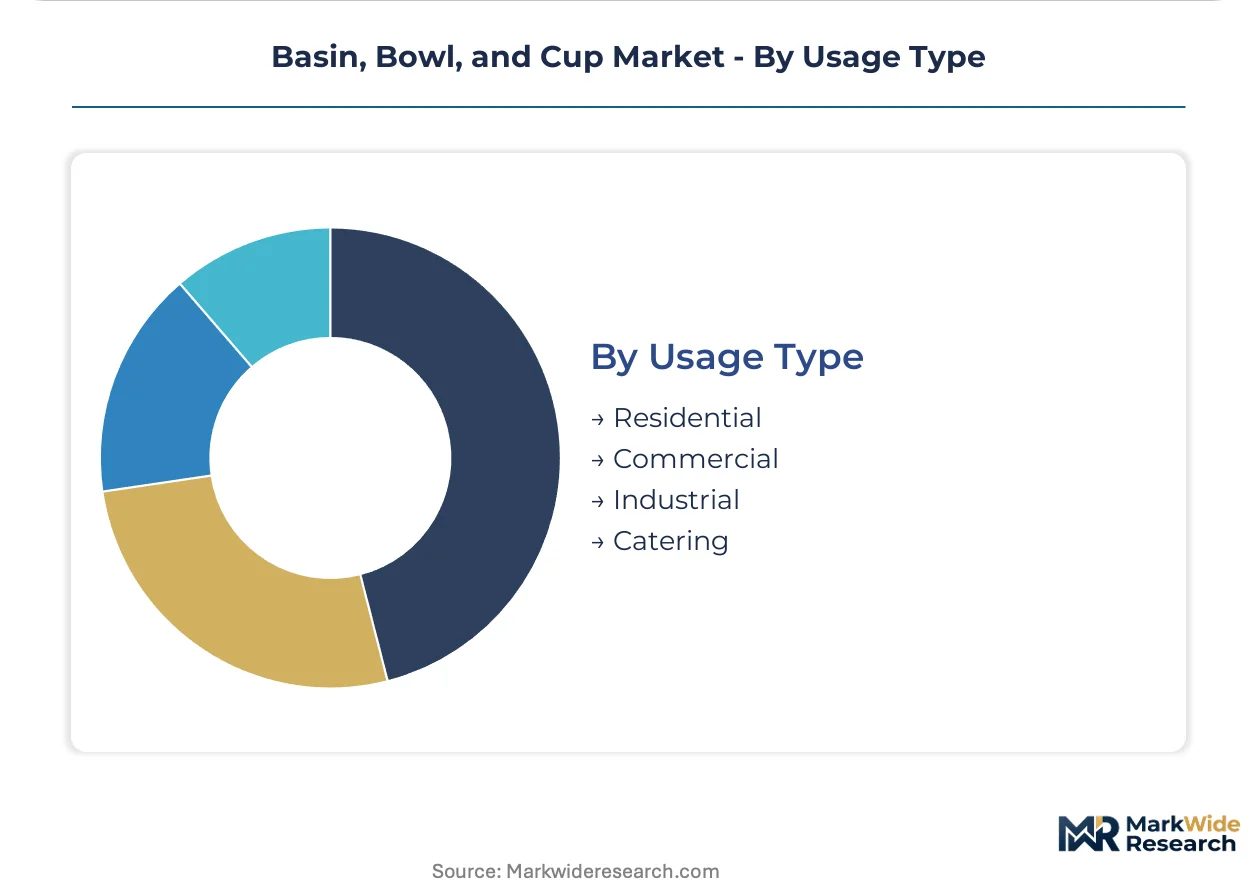
Customer type divergence separates fragmented residential purchasing from consolidated institutional procurement with divergent specification and compliance requirements.
- Residential:Aesthetic-driven selection prioritizes design coherence across dinnerware sets and countertop storage solutions. US and European consumers are migrating toward open-stock purchasing patterns that reduce commitment to complete place settings.
- Commercial:Quick-service restaurants and cafeteria operators prioritize stackability, dishwasher durability, and unit-cost efficiency in high-turnover environments. India's corporate food service networks are standardizing polypropylene bowl specifications across mid-day meal and canteen operations.
- Industrial:Food processing and pharmaceutical manufacturing require vessels with validated material traceability and cleanability documentation.
- Catering:Event rental and disposable single-use applications demand lightweight logistics and post-event disposal efficiency.
Commercial usage anchors production volume; industrial applications are climbing the fastest on compliance-driven specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polypropylene feedstock availability along the US Gulf Coast anchors North American thermoforming capacity. European ceramic clusters face carbon border adjustment exposure from natural gas-intensive kiln operations. Asian manufacturing concentrates in coastal export zones serving institutional foodservice procurement.
United States
Hospital group purchasing organizations consolidate single-use medical vessel contracts into multi-year agreements. FDA food-contact substance notifications govern polypropylene formulations for quick-service restaurant chains. Michigan-based thermoformers serve Great Lakes distribution networks with captive resin sourcing from regional petrochemical complexes.
Germany
REACH Annex XVII migration testing requirements filter export-capable compounders from commodity suppliers. ECHA restricted substance list updates drive reformulation of transparent drinking cup resins. Bavarian precision mold fabricators supply hot-runner systems to thin-wall injection operations across Central Europe.
China
GB 4806 series standards enforcement accelerates certified laboratory capacity expansion in Yangtze River Delta testing hubs. SAMR food-contact polymer compliance creates divergent export burdens for dual-market manufacturers. Zhejiang thermoforming clusters pivot toward PLA sheet capacity to capture EU Green Deal-aligned procurement.
India
Mid-day meal program standardization drives polypropylene bowl specifications across state procurement frameworks. FSSAI food-contact compliance timelines compress product development cycles for domestic molders. Gujarat injection molding corridors supply institutional catering networks with dishwasher-durable portion control vessels.
Vietnam
EU export contract migration accelerates starch-blend sheet extrusion line conversions in Ho Chi Minh City industrial zones. Biodegradable thermoforming capacity expansion targets European single-use plastic ban deadlines. Binh Duong province hosts emerging biopolymer compounders serving contract manufacturing demand.
Basin, Bowl, and Cup Market Key Industry Players
Global majors compete with regional champions across material technology and sterile packaging certification dimensions. Market structure tiered between resin-integrated volume producers, medical-validated specialists, and biodegradable material innovators. Archetypes include captive feedstock operators, hospital supply incumbents, and sustainability-focused compounders. Dominant competitive moves center on multi-layer barrier technology licensing and sterile production environment certification.
Among US-based operators, Dart Container Corporation exemplifies scale-driven resin integration, while Berry Global occupies a position in multi-layer coextrusion technology. Cardinal Health represents the medical-validated archetype with hospital procurement channel access. Vietnamese sustainability-focused compounders include Bioleader, which anchors biodegradable material development for European export compliance.
| Leading Market Players |
|---|
| Dart Container Corporation |
| Bioleader |
| Medtronic |
| Packware China |
| GreenChoice Packaging |
| Cardinal Health |
| Berry Global |
| Narang Medical Limited |
| The Vollrath Company |
| Others |
Cost & Logistics Intelligence
Hot-runner thin-wall injection molding adoption simultaneously compresses unit economics for high-volume cup producers and concentrates production among capital-equipped molders capable of sub-four-second cycle times. This technology transition rewards scale operators with captive resin sourcing while marginalizing cold-runner legacy facilities unable to amortize retrofit investments against polypropylene price volatility.
Pricing Analysis
Warranty and sterile validation bundling separates medical-grade basin suppliers from unbundled commodity cup vendors serving quick-service restaurant chains. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA food-contact certification tier and lot-level traceability documentation. Pricing pressure stems from propylene feedstock volatility linked to crude benchmarks, squeezing margin predictability for non-integrated molders. Quick-service restaurant procurement teams exhibit highest price sensitivity through consolidated annual contracts, while hospital group purchasing organizations absorb premium pricing for validated sterile barrier packaging.
Supply Chain Analysis
Workforce availability constraints in Zhejiang thermoforming corridors and Ho Chi Minh City extrusion zones are accelerating automation investment and biopolymer line conversion. Supply concentrates in China, Vietnam, and India, with raw material dependencies on polypropylene homopolymer, PLA resin, and starch-blend compounds. Single-source vulnerability runs through Gulf Coast propylene production exposed to hurricane disruption. Distribution feeds from factory-direct e-procurement platforms serving hospital group purchasing organizations and university dining consortia, bypassing traditional medical supply distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Basin, Bowl, and Cup Market sits in a material-substitution phase where polylactic acid and polyhydroxyalkanoate formulations displace conventional polypropylene in temperature-sensitive applications. This technology transition rewards compounders with validated bio-based plasticizer chemistry and EU Green Deal-aligned certification pathways.
For Market Incumbents: Cement sterile packaging dominance through Joint Commission-accredited production environment investment and lot-level traceability systems. Backward integration into captive resin compounding insulates margin from propylene feedstock volatility while blocking emerging biopolymer compounders from hospital procurement channels.
For New Entrants and Emerging Players: Capture biodegradable sheet capacity demand from European export contracts ahead of single-use plastic ban deadlines. India's institutional catering sector offers the most penetrable white space through FSSAI-compliant polypropylene bowl specifications for mid-day meal programs. Partner with Gujarat injection molding corridors for contract manufacturing scale without greenfield facility investment.
For Investors and Strategic Acquirers: Exit pathways concentrate in medical-validated specialists with hospital group purchasing organization contracts and sterile barrier validation infrastructure. Long-term viability favors compounders with multi-jurisdiction compliance infrastructure spanning FDA, REACH, and GB 4806 standards. Watch EU Packaging and Packaging Waste Regulation implementation timelines as inflection indicator for design-for-recycling service contract demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Material Transition | PLA and PHA sheet capacity captures EU Green Deal-aligned procurement from quick-service restaurant chains. |
| Sterile Barrier Validation Investment | Joint Commission-accredited cleanroom production opens multi-year hospital group purchasing organization contracts. |
| Multi-Layer Barrier Technology Licensing | EVOH and tie-layer coextrusion enables hot-fill cup applications previously reserved for glass and metal vessels. |
| Backward Integration into Resin Compounding | In-house polypropylene formulation development insulates margin from crude-linked feedstock volatility. |
| Direct-to-Institution E-Procurement Platform | Factory-direct sourcing bypasses distribution tiers for university dining consortia and hospital materials management. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving thermoforming plant managers, hospital procurement directors, foodservice category buyers, polymer compounder R&D leads, and sterile packaging validation specialists. FDA food-contact substance notifications, ECHA REACH Annex XVII updates, SAMR GB 4806 enforcement records, and FSSAI compliance timelines supplied regulatory boundary conditions. Bottom-up vessel production estimates triangulated against top-down institutional catering spend data.
Data-stream reconciliation across manufacturing capacity surveys, resin price indices, and export certification databases shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, material substrate, manufacturing method, and usage category, with regional regulatory cluster as an additional cross-cutting variable. CAGRs derived from trend extrapolation of hospital procurement consolidation rates and biodegradable material adoption curves in Northern European quick-service channels.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU carbon border adjustment implementation pace and polypropylene feedstock price volatility. Forecasts reflect documented assumptions regarding institutional catering standardization timelines and biopolymer cost-performance convergence. Material deviation in EU Packaging and Packaging Waste Regulation enforcement or Gulf Coast propylene supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Global Paper Towels Market
Household Items
Shower Caddies Market
Household Items
Electric Brooms Market
Household Items
Asia-Pacific Digital Showers Market
Household Items
Middle East and Africa Robotic Vacuum Cleaner Market
Household Items
Cutlery Market
Household Items
Crash Mat Market
Household Items
Copper Water Bottle Market
Household Items
US Air Fresheners Market
Household Items
Pet Stain Remover and Odour Control Market
Household Items
Tablet Tissue Paper Market
Household Items
Portable Humidifiers Market
Household Items
Sanitary Napkin Vending Machine Market
Household Items
Saudi Arabia Cookware Market
Household Items
Mexico Cookware Market
Household Items
Manual Bottle Opener Market