
 Garbage Disposals Market | 2026-2036
Garbage Disposals Market Size, Share, and Industry Trends Forecast 2026-2036
Garbage Disposals Market Analysis
The capital-intensity gap between mass-market assemblers and precision-machining specialists is collapsing as stainless steel grinding chamber standards tighten across residential and commercial lines. Emerson Electric Co. leverages captive motor production and in-house foundry capacity to sustain margin structures that import-reliant competitors cannot match. Fortune Brands Home & Security Inc. anchors its position through Moen Incorporated's channel control over big-box retail and plumbing wholesale networks, while Whirlpool Corporation competes on brand recognition and appliance ecosystem bundling.
Garbage disposals are electrically powered food waste processing units installed beneath kitchen sinks, utilizing high-torque induction motors to pulverize organic refuse into particles small enough for municipal wastewater systems. Stainless steel grinding components rated at 3/4 HP and above dominate the replacement segment due to corrosion resistance and extended service life. Continuous feed units lead volume shipments in North American residential applications, while batch feed systems command premium positioning in European markets where safety interlocks face stricter regulatory scrutiny. Commercial-grade installations under salvage and foodservice accounts represent the fastest-expanding margin pool, driven by landfill diversion mandates and operational cost reduction priorities.
The EPA administers WaterSense efficiency guidelines that constrain flow-rate specifications for new installations, while NSF International certification governs microbial safety and grind fineness thresholds for commercial foodservice deployments. State-level organic waste bans in California, Massachusetts, and Vermont directly stimulate replacement cycles by prohibiting landfill disposal of food scraps and mandating alternative processing infrastructure. Stakeholders must monitor municipal wastewater treatment capacity investments and building code harmonization efforts across jurisdictions to anticipate retrofit opportunity windows and product specification shifts.
Market Dynamics
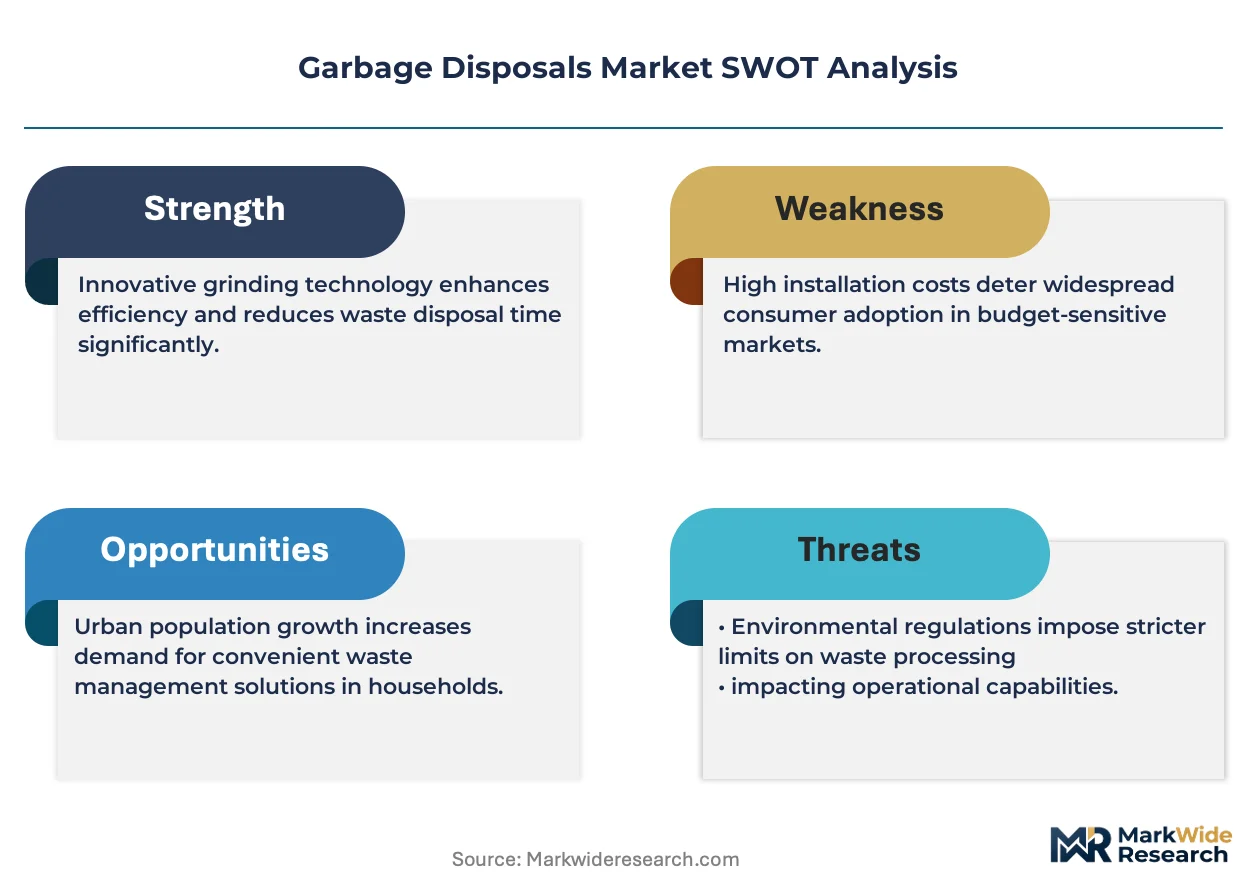
State-level organic waste bans in California, Massachusetts, and Vermont are forcing accelerated replacement cycles across the installed base, while EPA WaterSense flow-rate constraints simultaneously reshape product specifications and manufacturing cost structures.
Growth Catalysts
- Organic waste diversion mandates:California SB 1383 and comparable statutes in Massachusetts and Vermont prohibit landfill disposal of food scraps, compelling residential and commercial property owners to install grinding infrastructure.
- Sun Belt housing construction:Metropolitan areas across Texas, Florida, Arizona, and Georgia sustain elevated kitchen remodeling and new single-family home completions that embed disposals as standard equipment.
- Stainless steel grinding chamber migration:Corrosion-resistant 3/4 HP and above configurations are displacing galvanized steel in replacement demand due to extended service life and reduced callback rates for installers.
Market Restraints
- Copper and electrical steel input volatility:High-torque induction motor production faces raw material cost swings that compress assembler margins when long-term contracts with big-box retailers lock in pricing.
- Municipal wastewater capacity constraints:Aging treatment infrastructure in Northeastern and Midwestern cities creates installation permitting friction and localized moratoriums on new disposal connections.
- Composting and anaerobic digestion substitution:Centralized organic waste processing facilities in Vermont and Massachusetts municipalities reduce household-level grinding economics for some homeowner segments.
Strategic Opportunities
- Commercial foodservice underpenetration:Restaurants, hotels, and institutional kitchens in secondary US metropolitan areas lack disposal installation rates comparable to coastal urban centers.
- NSF International certification expansion:Microbial safety and grind fineness standards for commercial deployments create premium positioning for manufacturers achieving foodservice-specific validation.
- Smart home ecosystem integration:Connectivity modules enabling usage monitoring and predictive maintenance alerts are converging with residential kitchen appliance networks.
Industry Challenges
- Precision machining skill scarcity:Stainless steel grinding component fabrication requires tolerances that exceed capabilities of general metalworking labor pools in domestic manufacturing regions.
- Multi-jurisdiction code harmonization:Plumbing and electrical inspectors in different states apply inconsistent interpretations of grounding, dishwasher connection, and air-gap requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Garbage Disposals Market |
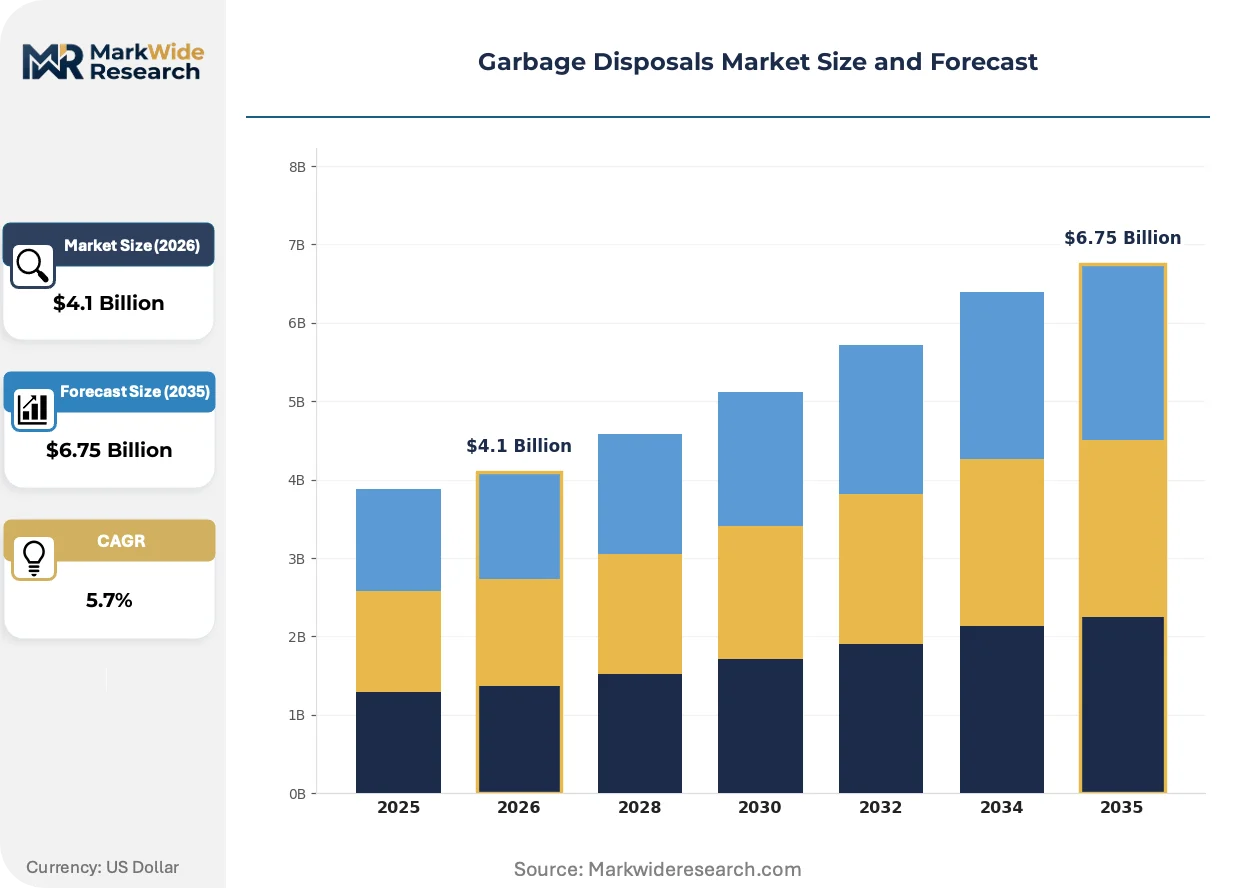
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.75 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Feed, Batch Feed, Commercial, Household Installation Type: Under-Sink, Standalone, Wall-Mounted, Portable Power Rating: 1/3 HP, 1/2 HP, 3/4 HP, 1 HP Material: Stainless Steel, Plastic, Cast Iron, Composite |
| Companies Covered | Emerson Electric Co., Fortune Brands Home & Security Inc., Whirlpool Corporation, Illinois Tool Works Inc., Joneca Corporation, Salvajor, Electrolux AB, Moen Incorporated, Waste King, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Garbage Disposals Market Emerging Trajectories
Product architecture is bifurcating between connected residential units and heavy-duty commercial systems, while regulatory pressure on water efficiency and waste diversion compresses development timelines.
Batch feed safety interlock technology is fragmenting the residential product architecture landscape. Multi-family housing developers and aging-in-place renovation contractors specify these systems at accelerating rates. The resulting specification divergence is fragmenting R&D budgets away from continuous feed optimization toward dual-platform engineering.
EPA WaterSense efficiency guidelines constrain flow-rate specifications for new installations below 2.0 gallons per minute. Manufacturers must redesign impeller geometry and motor torque curves to maintain grind performance under reduced water volumes. Commercial foodservice deployments face the steepest redesign costs due to high-throughput operational requirements.
Installer and contractor purchasing is consolidating around integrated kitchen appliance packages rather than standalone disposal procurement. Big-box retail and plumbing wholesale networks are responding with bundled pricing structures that tie disposals to faucet and sink combinations. This consolidation is most visible in Sun Belt metropolitan areas where new construction volume supports package economics.
Garbage Disposals Market Segmentation
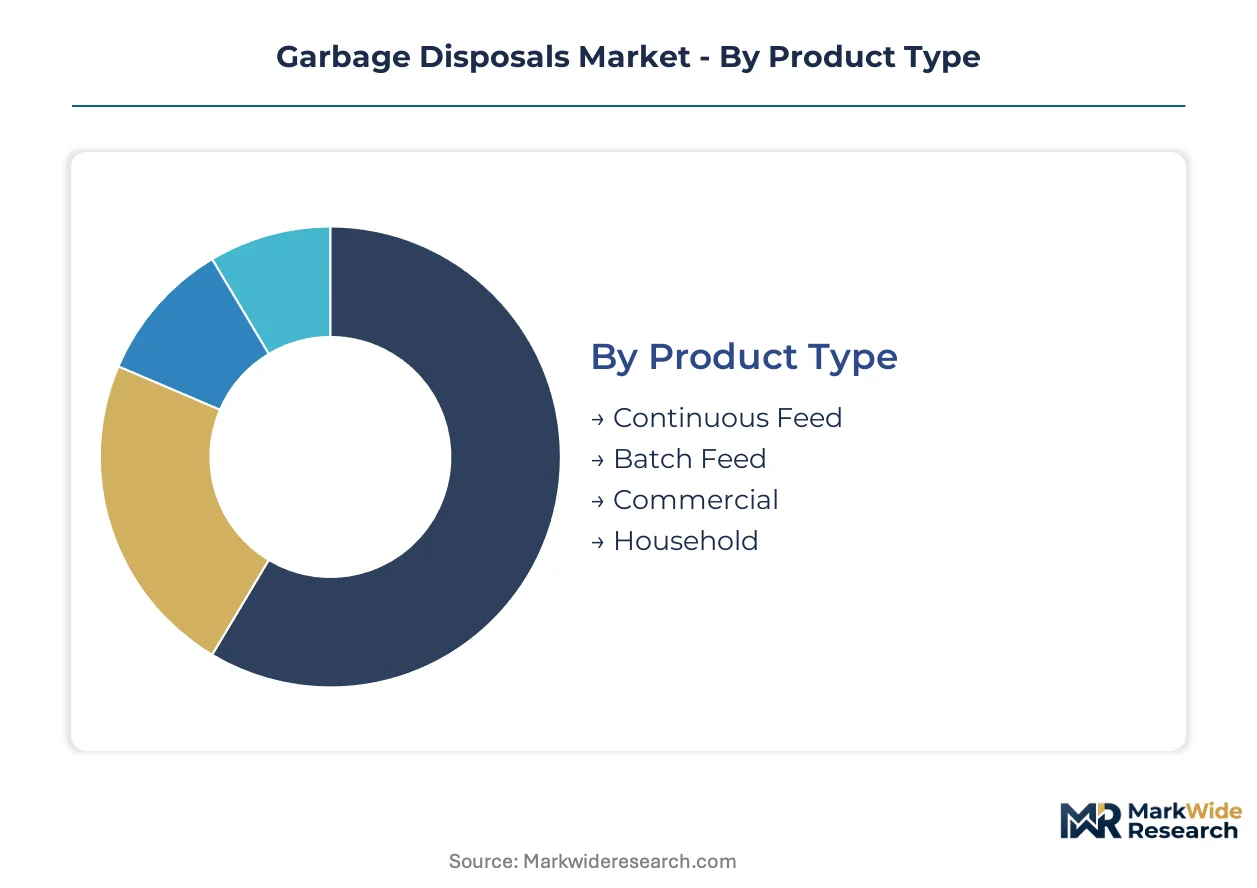
Segmentation in garbage disposals reveals how channel economics and specification requirements diverge between replacement-driven residential demand and mandate-stimulated commercial installations. Product architecture and material choices map directly to installer purchasing patterns and regulatory compliance thresholds.
Product Type:
Channel concentration varies sharply across product architectures, with continuous feed units dominating big-box retail and plumbing wholesale while batch feed systems flow through specialty distributors serving multi-family and aging-in-place contractors.
- Continuous Feed:Open-chamber designs with wall-switch activation dominate North American residential replacement. Sun Belt metropolitan areas sustain volume through new construction packages that embed these units as standard equipment.
- Batch Feed:Safety-interlocked systems requiring stopper engagement command premium positioning in European markets and multi-family housing developments where liability exposure drives specification. Massachusetts and Vermont organic waste mandates accelerate adoption in retrofit applications where child-safety concerns intersect with diversion requirements.
- Commercial:High-torque units with extended grinding chambers serve foodservice accounts under landfill diversion mandates.
- Household:Standard-duty configurations target single-family replacement cycles with corrosion-resistant grinding components.
By volume, Continuous Feed leads. By growth pace, Batch Feed is ahead.
Installation Type:
Cost tier stratification separates professional-installation categories from accessible retrofit options, with under-sink configurations anchoring premium pricing and portable units capturing price-sensitive replacement demand.
- Under-Sink:Permanent mounting beneath kitchen drains represents the dominant professional installation category. EPA WaterSense flow-rate constraints force redesign of drain connections and dishwasher integration hardware.
- Standalone:Freestanding units with independent plumbing connections serve commercial foodservice and institutional kitchens where centralized waste processing infrastructure is unavailable.
- Wall-Mounted:Space-constrained installations in urban multi-family housing and commercial galley kitchens utilize vertical mounting configurations with remote activation.
- Portable:Temporary-connection units target rental property retrofits and seasonal foodservice operations with lower capital commitment requirements.
Under-Sink configurations command the highest average selling prices. Portable units are climbing the fastest as rental housing turnover accelerates replacement frequency.
Power Rating:
Application intensity determines motor specification, with food waste volume and fibrous material content dictating torque requirements across residential and commercial use cases.
- 1/3 HP:Entry-level induction motors serve light-duty residential applications with limited organic waste generation. These units concentrate in apartment replacement cycles and budget-conscious renovation projects.
- 1/2 HP:Mid-range configurations balance cost and performance for standard single-family kitchens. California SB 1383 compliance retrofits favor this tier for residential properties with moderate disposal frequency.
- 3/4 HP:High-torque stainless steel grinding systems dominate replacement demand where service life and corrosion resistance justify premium positioning. Extended warranties and reduced installer callback rates drive specification in professional channels.
- 1 HP:Heavy-duty commercial-grade motors process high-volume foodservice waste streams under continuous operational loads.
3/4 HP units lead replacement revenue. 1 HP configurations are expanding most quickly as commercial foodservice landfill diversion mandates tighten.
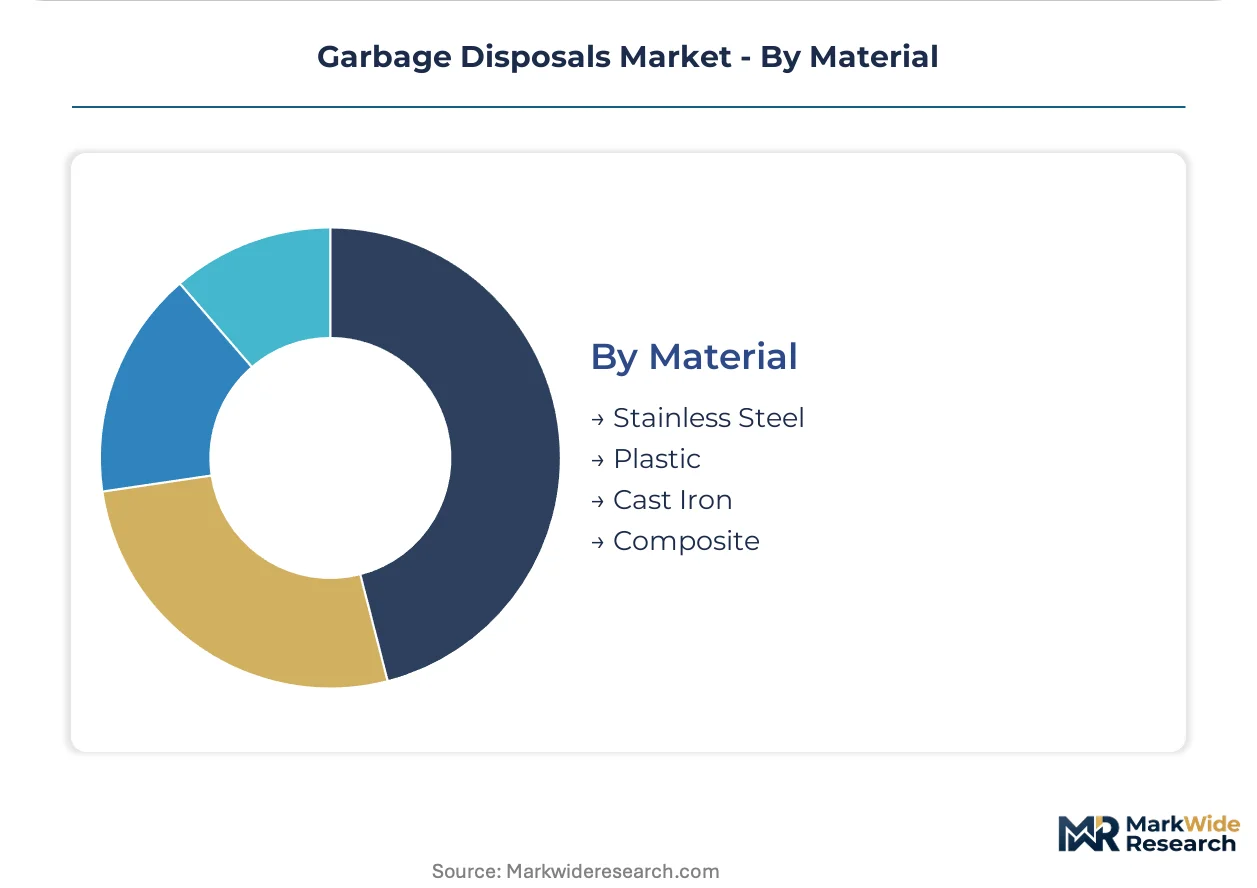
Material:
Supply concentration in precision-machining regions shapes material cost structures, with stainless steel fabrication requiring specialized foundry and grinding capabilities that constrain vendor participation.
- Stainless Steel:Corrosion-resistant grinding chambers and impellers rated for 3/4 HP and above displace galvanized alternatives in quality-focused replacement demand. Precision machining tolerances for these components exceed capabilities of general metalworking suppliers.
- Plastic:Polymer housings and non-grinding components reduce unit weight and material cost in entry-tier residential products. Big-box retail pricing pressure sustains volume despite durability limitations.
- Cast Iron:Traditional grinding chamber material persists in commercial heavy-duty applications where mass dampens vibration under continuous operation.
- Composite:Reinforced polymer-metal hybrid constructions target mid-tier positioning with weight reduction and corrosion resistance trade-offs.
Stainless Steel commands the premium tier. Composite materials are gaining share fastest as manufacturers seek weight and cost optimization without sacrificing grind performance ratings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in garbage disposals tilt toward import dependence in most markets, with domestic manufacturing concentrated where precision-machining infrastructure and captive motor production coexist. Regional demand patterns diverge sharply based on housing construction velocity, organic waste regulation timing, and wastewater treatment capacity.
United States
Sun Belt metropolitan areas across Texas, Florida, and Arizona sustain replacement cycles through elevated single-family construction and kitchen renovation spending. EPA WaterSense flow-rate guidelines constrain new product specifications below 2.0 gallons per minute. California's SB 1383 organic waste mandate accelerates retrofit installations in Los Angeles and San Francisco metropolitan corridors where landfill diversion targets are binding.
Germany
Batch feed safety systems command premium positioning in residential applications where liability exposure drives specification toward interlocked designs. REACH chemical compliance and CE marking requirements govern stainless steel grinding component imports. The Ruhr industrial region hosts precision-machining suppliers serving commercial foodservice accounts under EU Green Deal circular economy targets.
China
Domestic demand concentrates in coastal tier-one cities where kitchen appliance upgrade cycles accelerate disposal adoption. GB standards and MIIT energy efficiency regulations shape motor specification for both domestic sale and export manufacturing. The Yangtze River Delta cluster around Shanghai anchors assembly operations serving North American private-label contracts.
Japan
Compact batch feed units dominate residential installations where space constraints and safety interlock preferences intersect. METI efficiency guidelines and JIS standards constrain water consumption ratings for new construction integration. The Kansai region around Osaka maintains specialized foundry capacity for corrosion-resistant grinding chamber components.
United Kingdom
Retrofit demand concentrates in London and Southeast England where aging housing stock undergoes kitchen modernization. Building regulations and water company bylaws create installation permitting friction in areas with combined sewer overflow risks. Midlands manufacturing retains limited assembly presence focused on commercial foodservice exports.
Garbage Disposals Market Vendor Landscape
Concentration sits with vertically integrated electrical component manufacturers and captive-brand plumbing specialists who control foundry capacity and distribution simultaneously. Three structural tiers define participation: mass-market assemblers reliant on imported motors and grinding components; precision-machining specialists with in-house stainless steel fabrication; and diversified appliance conglomerates bundling disposals within broader kitchen ecosystem offerings. Competitive maneuvering centers on backward integration into motor production and exclusive channel arrangements with big-box retail and plumbing wholesale networks.
Among North American electrical equipment conglomerates, Emerson Electric Co. exemplifies the integrated archetype through captive motor manufacturing and foundry ownership. Fortune Brands Home & Security Inc. anchors the plumbing-specialist position via Moen Incorporated's channel control over professional installer networks. Whirlpool Corporation represents the diversified appliance bundling approach, leveraging brand recognition and cross-product ecosystem lock-in. These three patterns illustrate how margin sustainability correlates with upstream control over critical components and downstream access to specification-setting channels.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Fortune Brands Home & Security Inc. |
| Whirlpool Corporation |
| Illinois Tool Works Inc. |
| Joneca Corporation |
| Salvajor |
| Electrolux AB |
| Moen Incorporated |
| Waste King |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at captive motor foundries in Wisconsin and Ohio sets price floors that import-reliant assemblers cannot match, concentrating margin power among manufacturers with backward integration into high-torque induction motor production. This scale asymmetry compresses pricing flexibility for competitors sourcing electrical steel and copper windings through spot-market exposure.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the residential replacement segment. Three-tier pricing structure across premium, standard, and economy levels segments by stainless steel grinding chamber grade and NSF International certification tier. Cost compression in entry-tier galvanized steel configurations is intensifying because big-box retail pricing locks compress assembler margins against copper volatility. Rental property managers and seasonal foodservice operators exhibit highest price sensitivity, while commercial foodservice accounts under landfill diversion mandates show lowest sensitivity due to operational cost reduction priorities.
Supply Chain Analysis
Inventory buffers for precision-machined stainless steel grinding components stretch lead times when Ruhr Valley and Yangtze River Delta foundries operate at capacity. Supply concentrates in China, Germany, and Japan for corrosion-resistant grinding chamber fabrication. Raw material flows draw from electrical steel mills in South Korea, copper cathode from Chilean smelters, and polymer housings from petrochemical complexes along the US Gulf Coast. Single-source vulnerability in high-grade stainless steel precision machining creates exposure when EPA WaterSense redesign cycles spike component demand. Distribution runs through plumbing wholesale networks and big-box retail channels serving professional installer and DIY replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The garbage disposals market functions as a defensive-moat story where regulatory entrenchment around EPA WaterSense certification and state-level organic waste mandates creates high switching costs for institutional buyers.
For Market Incumbents: Shield market position by deepening backward integration into captive motor production and stainless steel foundry capacity. Secure exclusive channel arrangements with big-box retailers facing inventory consolidation pressure. Counter emerging threat from composting infrastructure substitution in Vermont and Massachusetts municipalities by accelerating NSF International certification for commercial foodservice accounts.
For New Entrants and Emerging Players: NSF International certification fast-track offers entry pathway into commercial foodservice underpenetration in secondary Sun Belt metropolitan areas. Target Texas and Florida restaurant supply chains where disposal installation rates lag coastal urban centers. Pursue white-label manufacturing contracts for private-label brands seeking stainless steel grinding chamber sourcing outside established supplier relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision-machining specialists with in-house foundry capacity and established plumbing wholesale distribution. Five-to-ten year viability favors acquisition targets with EPA WaterSense-compliant product pipelines and multi-state contractor relationships. Monitor municipal wastewater treatment capacity investment announcements as inflection indicator for retrofit opportunity windows in Northeastern and Midwestern cities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Production | Captive electrical steel sourcing insulates margin structures from copper price volatility. |
| NSF International Certification Expansion | Foodservice-specific validation unlocks premium positioning in commercial landfill diversion mandates. |
| Smart Home Ecosystem Integration | Connectivity modules converge with residential kitchen appliance networks for predictive maintenance revenue. |
| Batch Feed Safety Interlock Development | Multi-family housing specifications in Massachusetts and Vermont accelerate adoption of interlocked designs. |
| Commercial Foodservice Channel Penetration | Secondary metropolitan areas in Texas and Florida lack disposal installation rates comparable to coastal centers. |
Methodological Framework
The analysis maps continuous feed, batch feed, and commercial-grade product architectures, each validated through plumbing contractor interviews, wholesale distributor purchasing managers, and municipal wastewater treatment officials. Primary fieldwork combined with secondary validation from EPA WaterSense technical documentation, state environmental agency SB 1383 implementation reports, and SEC 10-K filings from electrical equipment manufacturers. Bottom-up shipment volume modeling triangulated against top-down housing construction and kitchen renovation spending estimates.
Consistency checks validated volume and value outputs against external benchmarks including municipal wastewater connection permits and big-box retail SKU velocity data. Segmentation modeling spanned product type, power rating, material grade, installation configuration, and regional regulatory cluster across the projection horizon. CAGRs derived from fitted growth curves incorporating housing starts, organic waste mandate phase-in schedules, and stainless steel input cost trajectories. Industry-specific inputs included EPA WaterSense flow-rate constraint compliance costs and precision-machining labor pool availability by manufacturing region.
The analysis sits within stated boundaries; outcomes outside assumed housing construction velocity and regulatory enforcement intensity would require recalibration. Forecasts reflect documented assumptions around copper price stability and municipal wastewater capacity expansion timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Range Hood Cleaning Service Market
Household Items
Global Sports Bottle Market
Household Items
Wipes Market
Household Items
Asia Pacific Residential Vacuum Cleaners Market
Household Items
Shower Caddies Market
Household Items
Drinkware Market
Household Items
Global Aluminum Cookware Market
Household Items
UK Digital Showers Market
Household Items
Window Rain Guards Market
Household Items
Smart Bathroom Products Market
Household Items
Europe Electric Cordless Lawn and Garden Tools Market
Household Items
Air Mattress Market
Household Items
Ironing Boards Market
Household Items
Underwear Disinfection Dryers Market
Household Items
Dishwasher Tablets Market
Household Items
Home Use Air Purifiers Market