
 Smart Refrigerator Market | 2026-2036
Smart Refrigerator Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Refrigerator Market Intelligence
Embedded systems engineering talent scarcity is reorganizing how manufacturers allocate R&D budgets across connected appliance programs. Samsung Electronics leverages its semiconductor subsidiary to sustain in-house production of proprietary refrigeration control modules. LG Electronics anchors its competitive stance through deep manufacturing scale in Korean and Mexican production facilities. Haier Group dominates the Chinese domestic channel through direct-to-consumer platform integration and localized IoT service layers.
A smart refrigerator integrates compressor-based cooling with networked sensors, microprocessors, and cloud connectivity to enable remote temperature management, inventory tracking, and predictive maintenance protocols. The appliance typically operates between 0°C and 4°C in fresh compartments while transmitting operational data via Wi-Fi or Bluetooth protocols to manufacturer servers and consumer mobile applications. French Door configurations command premium positioning due to larger interior volumes and dual-zone climate management capabilities that support specialized food preservation. Wi-Fi Enabled technology leads connectivity adoption as it supports over-the-air firmware updates and third-party smart home platform integration. Commercial Food Service applications are expanding fastest among non-residential segments as restaurant chains deploy connected cold storage for compliance documentation and spoilage reduction.
The EPA Energy Star program and EU Green Deal F-Gas Regulation constrain refrigerant selection and minimum efficiency thresholds for products sold in North America and European markets. China's GB standards and NMPA-equivalent quality certifications govern electromagnetic compatibility and food-contact material safety for domestic and export-bound units. Stakeholders must monitor evolving interoperability mandates from the EU AI Act and fragmented smart home protocol standards before committing to proprietary ecosystem investments.
Market Dynamics
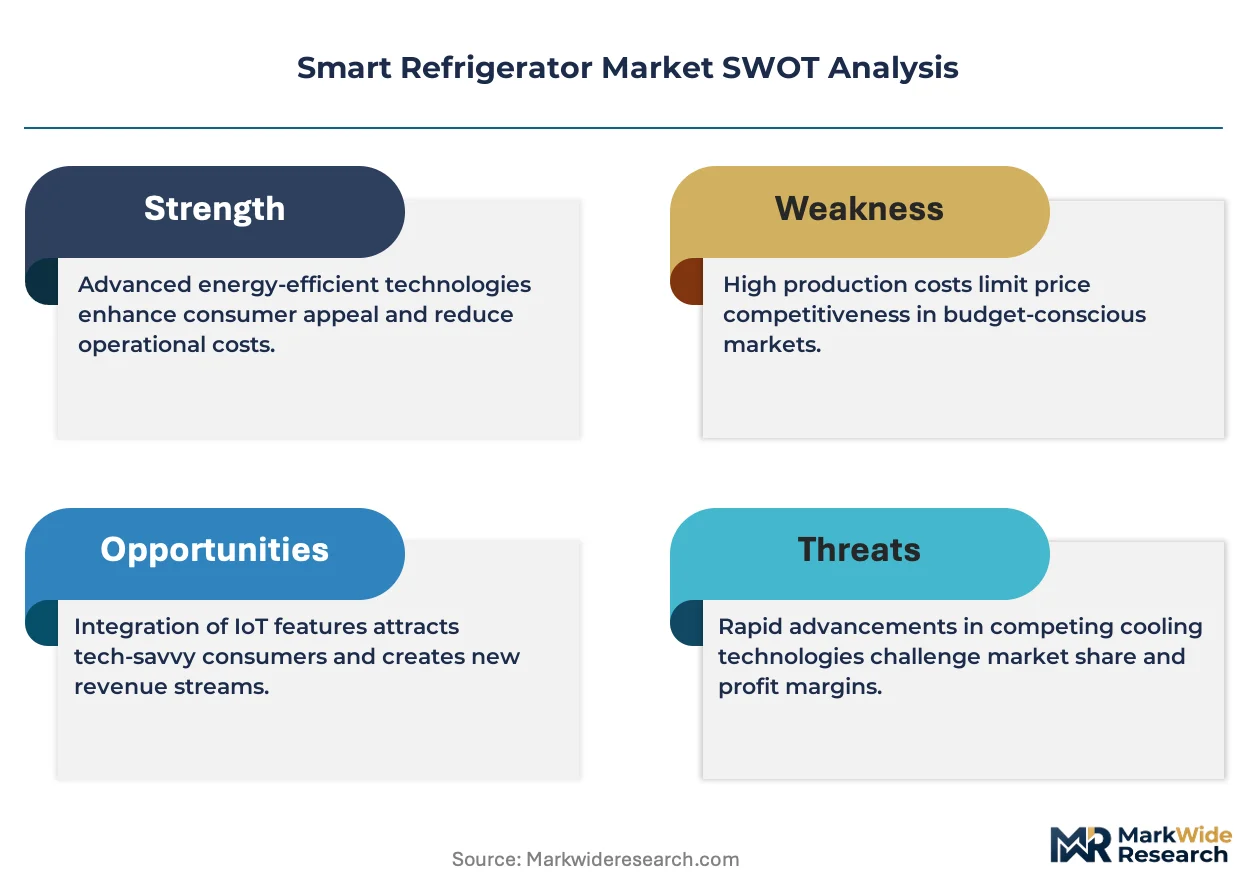
Embedded systems engineering scarcity is forcing appliance manufacturers to consolidate R&D budgets around proprietary semiconductor capabilities rather than distributed supplier networks.
Growth Catalysts
- EPA Energy Star mandates:North American efficiency thresholds accelerate replacement cycles for pre-2020 refrigeration units in residential installations.
- Commercial Food Service digitization:Restaurant chains deploy connected cold storage for automated spoilage logging and health inspection documentation.
- French Door configuration preference:Dual-zone climate management attracts premium residential buyers seeking specialized preservation for organic produce and wine collections.
Market Restraints
- Refrigerant input volatility:F-Gas Regulation phase-down schedules in Europe constrain hydrofluorocarbon supply chains and inflate compressor manufacturing costs.
- Semiconductor foundry concentration:Taiwan and South Korea dominate microcontroller wafer production, exposing appliance makers to single-source disruption risk.
- Protocol fragmentation:Competing smart home standards (Matter, Zigbee, proprietary clouds) force redundant hardware integration and inflate bill-of-materials complexity.
Strategic Opportunities
- India residential electrification:Rural grid expansion and appliance financing schemes open first-time buyer segments for entry-level connected refrigeration.
- Predictive maintenance convergence:Machine learning on compressor vibration and thermal cycle data enables subscription service revenue from commercial fleet operators.
- EU AI Act compliance tooling:Automated transparency documentation for food safety algorithms creates vendor lock-in potential for cloud platform providers.
Industry Challenges
- Firmware engineering scarcity:Real-time operating system expertise for refrigeration control loops commands premium salaries and extends product development timelines.
- Multi-certification sequencing:Simultaneous EPA Energy Star, EU F-Gas, and China GB electromagnetic compatibility testing creates launch date coordination complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Refrigerator Market |
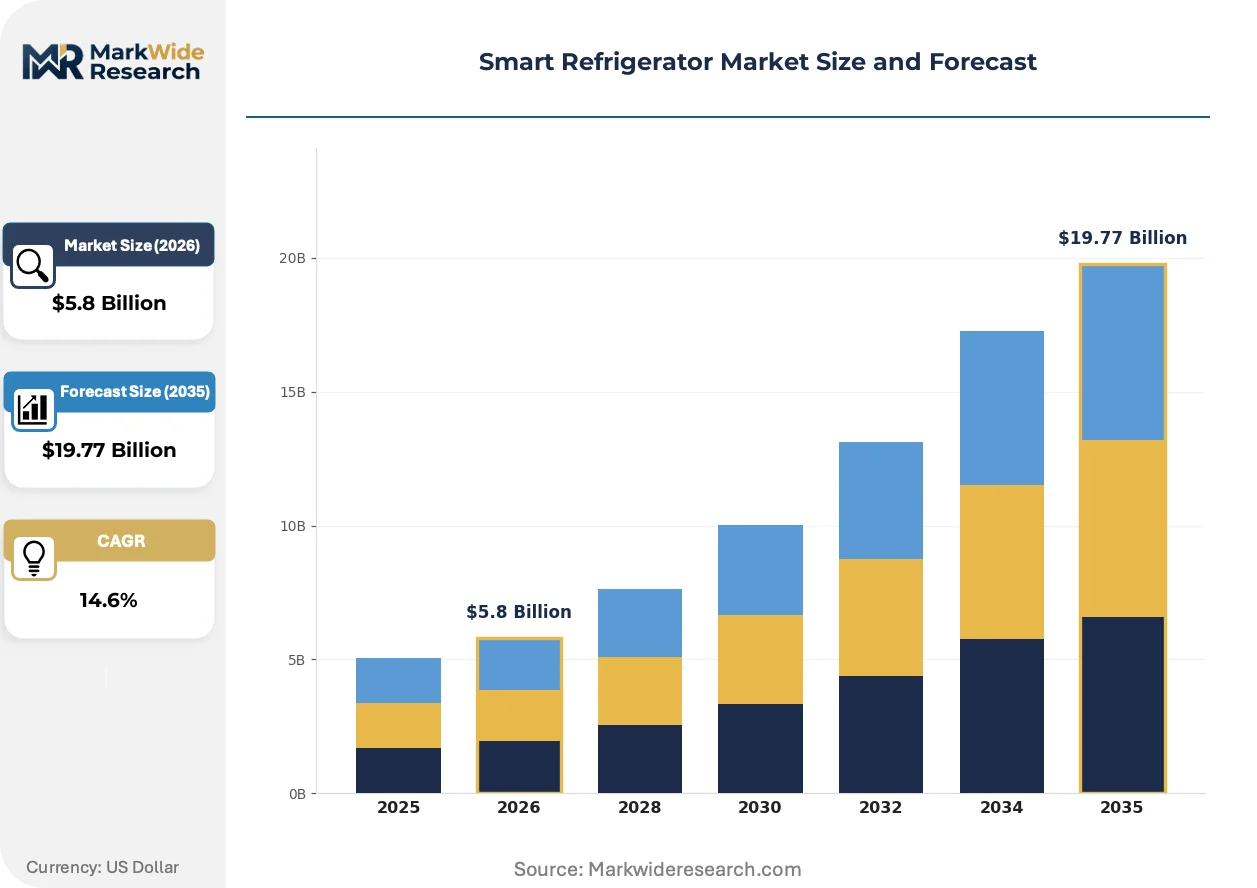
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $19.77 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Door, Double Door, Side-by-Side, French Door, Compact Technology: Wi-Fi Enabled, Bluetooth Enabled, Touchscreen Interface, Voice Recognition, Temperature Control Sensors Application: Residential Kitchens, Commercial Food Service, Hospitality, Office Pantries, Institutional Cafeterias End User: Homeowners, Food Service Operators, Hotel Chains, Corporate Offices, Educational Institutions |
| Companies Covered | Haier Group, Robert Bosch GmbH, Samsung Electronics, AB Electrolux, Siemens, LG Electronics, Panasonic Corporation, Midea Group, Whirlpool Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Refrigerator Market Strategic Shifts & Innovations
Smart refrigerator architecture is bifurcating between vertically integrated proprietary stacks and modular open-ecosystem designs, with regulatory pressure on refrigerants and data governance accelerating both paths simultaneously.
Edge-based computer vision for inventory recognition is fragmenting competitive positioning in the premium segment. Cameras mounted on door interiors identify produce types and expiration dates without cloud transmission. High-end residential buyers in Germany and the United States prioritize this local-processing architecture for privacy compliance. The technology is fragmenting vendor strategies between those investing in proprietary recognition models and those licensing third-party food databases.
F-Gas Regulation phase-down schedules are compressing refrigerant choice sets for European-bound products. Manufacturers must redesign compressor systems around hydrofluoroolefin blends or natural refrigerants like isobutane. This regulatory compression most acutely affects mid-tier product lines where engineering amortization across lower volumes strains margin structures. French Door configurations with larger refrigerant charges face disproportionate compliance cost pressure.
Channel consolidation among big-box retailers is concentrating buyer power in North American distribution. Best Buy and Lowe's now demand exclusive SKU configurations and dedicated firmware support teams as condition for floor placement. This buyer concentration most visibly reshapes go-to-market economics for Korean and Chinese manufacturers seeking scale in the United States. Direct-to-consumer platform investments by Haier and emerging D2C entrants represent the primary counterstrategy.
Smart Refrigerator Market Segmentation
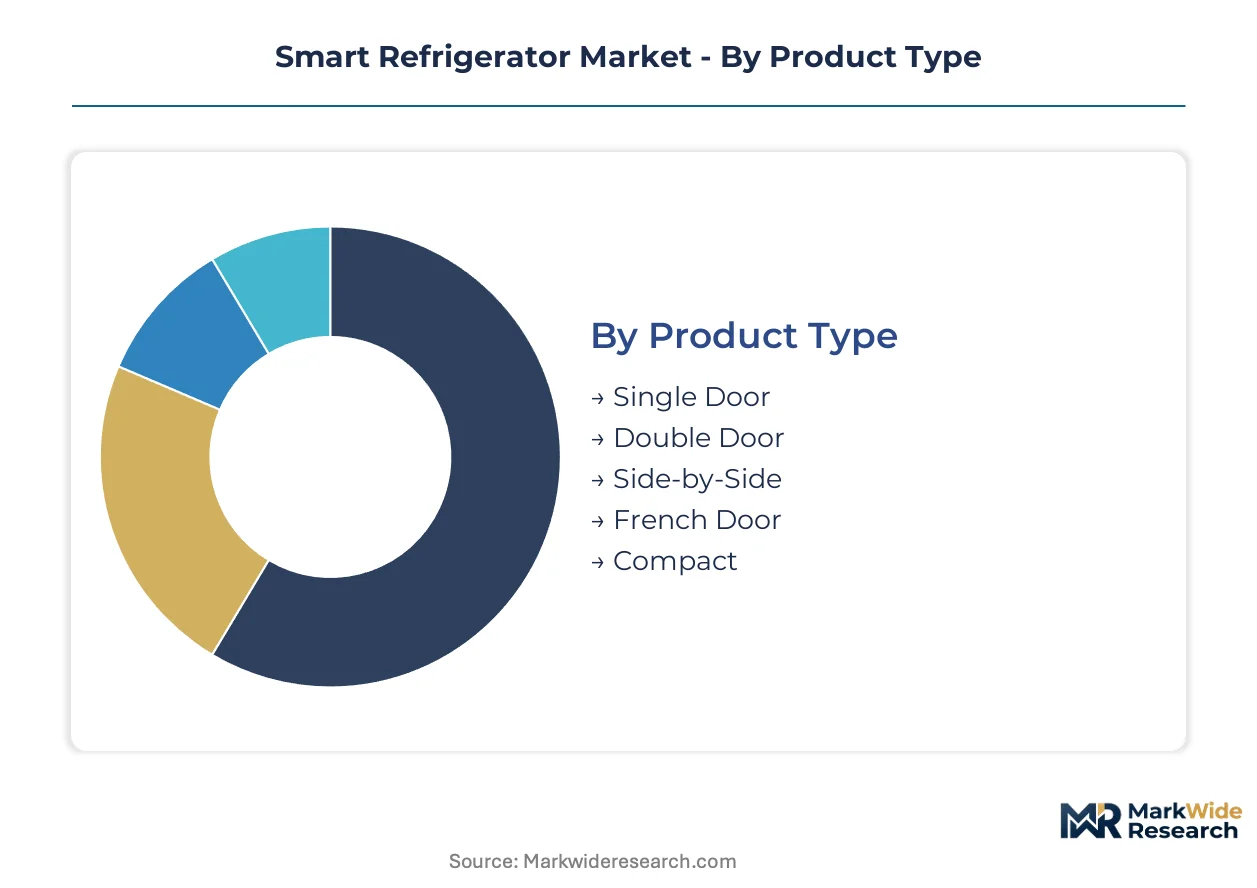
Smart refrigerator segmentation reveals divergent engineering priorities across residential and commercial use cases. Product architecture, connectivity protocols, and buyer procurement patterns vary substantially by end-use environment.
Product Type:
French Door and Side-by-Side configurations dominate export shipments to North American and European markets, while Single Door and Compact units serve price-sensitive domestic channels in emerging economies.
- French Door:Dual-zone climate management supports specialized preservation zones for organic produce and wine collections. Demand concentrates in the United States and Germany where premium residential buyers prioritize interior volume and aesthetic integration with open-plan kitchens.
- Side-by-Side:Vertical freezer-refrigerator split enables narrow footprint installation in urban apartments. Adoption clusters in Chinese metropolitan markets and South Korean high-density residential developments where floor space constraints override capacity preferences.
- Double Door:Traditional top-freezer design retains cost competitiveness for first-time appliance buyers.
- Single Door:Compact footprint suits studio apartments and secondary refrigeration needs.
- Compact:Portable scale targets dormitory, recreational vehicle, and home office applications.
French Door holds the largest share; momentum sits with Compact configurations as remote work patterns expand secondary refrigeration demand.
Technology:
Connectivity protocol selection determines hardware cost tiers and recurring cloud service revenue potential for manufacturers.
- Wi-Fi Enabled:Supports over-the-air firmware updates and third-party smart home platform integration through Matter and proprietary cloud protocols. Food Service Operators in the United States deploy this architecture for centralized fleet monitoring across restaurant locations.
- Voice Recognition:Hands-free inventory logging and temperature adjustment appeals to accessibility-focused buyers and professional kitchen environments. Integration with Amazon Alexa and Google Assistant ecosystems drives specification in premium residential retrofits.
- Touchscreen Interface:Embedded display enables meal planning applications and digital content consumption.
- Bluetooth Enabled:Short-range pairing suits proximity-based mobile app control without cloud dependency.
- Temperature Control Sensors:Precision thermistor arrays enable predictive maintenance algorithms.
Wi-Fi Enabled commands the installed base; Voice Recognition is climbing the fastest as hospitality and food service sectors prioritize operational efficiency.
Application:
Commercial deployments generate higher per-unit software subscription attach rates than residential installations.
- Commercial Food Service:Connected cold storage automates spoilage logging and health inspection documentation for restaurant chains. Deployment concentrates in the United States where FDA Food Code compliance documentation requirements drive digitization investment.
- Residential Kitchens:Homeowners seek appliance ecosystem integration with existing smart home infrastructure. Demand localizes in Germany and China where utility-sponsored efficiency programs subsidize connected appliance upgrades.
- Hospitality:Hotel chains deploy minibars and suite refrigeration with centralized monitoring.
- Office Pantries:Corporate wellness programs drive specification of visibility-enabled units for employee amenity spaces.
- Institutional Cafeterias:School and healthcare food service operators prioritize temperature compliance tracking.
Residential Kitchens retain volume leadership; Commercial Food Service shows the steepest expansion trajectory as regulatory documentation requirements tighten.
End User:
Procurement authority and financing mechanisms vary sharply between consumer-directed and enterprise purchasing contexts.
- Food Service Operators:Independent restaurants and regional chains prioritize total cost of ownership calculations including energy efficiency and maintenance predictability. Financing through equipment leasing specialists dominates in the United States.
- Homeowners:Replacement cycles accelerate where EPA Energy Star rebates and utility demand-response programs reduce effective purchase price. German homeowners show elevated willingness-to-pay for edge-computing privacy features.
- Hotel Chains:Brand-standard procurement centralizes specification decisions at corporate headquarters.
- Corporate Offices:Facilities management departments evaluate lifecycle cost against employee satisfaction metrics.
- Educational Institutions:Public procurement regulations constrain vendor selection and extend sales cycles.
Homeowners represent the largest addressable base; Food Service Operators are gaining share fastest through fleet digitization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smart refrigerator deployment varies sharply by geography, with residential buyers in wealthy markets prioritizing ecosystem integration while commercial operators in emerging economies focus on compliance documentation and fleet monitoring capabilities.
United States
French Door configurations dominate residential kitchens as homeowners seek dual-zone preservation for organic produce and wine collections. EPA Energy Star rebates accelerate replacement cycles for pre-2020 units in suburban installations. Best Buy and Lowe's concentrate buyer power through exclusive SKU demands, reshaping go-to-market economics for Korean and Chinese manufacturers.
China
Side-by-Side units cluster in metropolitan markets where floor space constraints override capacity preferences. GB standards and NMPA-equivalent certifications govern electromagnetic compatibility and food-contact material safety for domestic and export-bound production. Haier Group anchors domestic channel dominance through direct-to-consumer platform integration and localized IoT service layers in Qingdao and beyond.
Germany
Edge-computing privacy features command elevated willingness-to-pay among residential buyers concerned with local data processing. EU Green Deal F-Gas Regulation constrains refrigerant selection and minimum efficiency thresholds for European-bound products. Berlin and Munich metropolitan areas drive premium uptake through utility-sponsored efficiency programs subsidizing connected appliance upgrades.
South Korea
High-density residential developments favor vertical freezer-refrigerator splits enabling narrow footprint installation. MFDS-equivalent quality frameworks intersect with domestic manufacturing scale advantages. LG Electronics anchors competitive positioning through deep production facilities in Korean and Mexican locations serving export markets.
India
Rural grid expansion and appliance financing schemes open first-time buyer segments for entry-level connected refrigeration. BIS certification requirements and CEA electrical safety mandates shape product specifications for domestic market entry. Maharashtra and Gujarat industrial corridors attract component assembly investments targeting price-sensitive urban middle-class demand.
Smart Refrigerator Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with consolidation pressures intensifying around semiconductor capabilities and proprietary control module production. The vendor base separates into three strategic archetypes: vertically integrated electronics conglomerates with captive semiconductor supply, appliance specialists leveraging manufacturing scale across multiple production geographies, and platform-native players building direct-to-consumer channel infrastructure. Dominant competitive moves include backward integration into microcontroller design and geographic diversification of final assembly to mitigate tariff and logistics exposure.
Within the integrated electronics tier, Samsung Electronics and LG Electronics exemplify scale-driven positioning through captive semiconductor subsidiaries and continental production footprints. Haier Group occupies a distinct archetype as a platform-native operator leveraging direct-to-consumer infrastructure and localized service layer investments. These three anchors illustrate divergent strategic pathways: proprietary silicon control versus manufacturing scale optimization versus channel disintermediation.
| Leading Market Players |
|---|
| Haier Group |
| Robert Bosch GmbH |
| Samsung Electronics |
| AB Electrolux |
| Siemens |
| LG Electronics |
| Panasonic Corporation |
| Midea Group |
| Whirlpool Corporation |
| Others |
Cost & Logistics Intelligence
Compressor foundry utilization rates in Taiwan and South Korea dictate microcontroller availability and establish price floors for connected refrigeration modules across all tier positions.
Pricing Analysis
Long-term offtake contracts dominate procurement between appliance OEMs and Taiwanese semiconductor foundries, insulating premium tier pricing from spot-market volatility while exposing mid-tier manufacturers to component cost fluctuations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with EPA Energy Star and EU F-Gas compliance commanding measurable premiums. Cost compression in mid-tier lines is intensifying because refrigerant redesign amortization spreads across lower unit volumes. Food Service Operators demonstrate the highest price sensitivity due to fleet-scale procurement, whereas German residential buyers accept elevated price points for edge-computing privacy features.
Supply Chain Analysis
Inventory lead times for refrigeration-grade microcontrollers have extended substantially, forcing manufacturers to hold larger safety stocks and compress working capital cycles. Taiwan, South Korea, and China anchor wafer fabrication and final assembly capacity, with Mexican facilities serving North American tariff mitigation. Supply chains draw from hydrofluorocarbon compounds, copper winding stock, and high-grade steel sheet as critical inputs. Single-source vulnerability concentrates in Taiwanese foundry capacity for control module production. Distribution runs through big-box retail concentration in the United States and direct-to-consumer platforms in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart refrigerator architecture is undergoing high-growth disruption as edge-based computer vision and F-Gas refrigerant mandates simultaneously reshape engineering investment priorities.
For Market Incumbents: Fortify proprietary semiconductor capabilities through backward integration into microcontroller design, countering foundry concentration risk that threatens production continuity. Deepen manufacturing scale in Mexican and Vietnamese assembly locations to mitigate tariff exposure from United States trade policy shifts. Prioritize EPA Energy Star certification investments to accelerate replacement cycle capture in suburban residential installations.
For New Entrants and Emerging Players: Anchor in India's rural electrification corridor where appliance financing schemes and first-time buyer segments remain underpenetrated by established Korean and Chinese brands. Target compact secondary refrigeration for remote work home office applications, a segment expanding faster than traditional residential replacement cycles. Deploy direct-to-consumer platform infrastructure with localized IoT service layers, replicating Haier's domestic channel architecture.
For Investors and Strategic Acquirers: Platform-native specialists with captive direct-to-consumer infrastructure and edge-computing software stacks represent the highest-conviction acquisition archetype for medium-term consolidation. Long-term viability hinges on regulatory compliance tooling capabilities as EU AI Act documentation mandates create vendor lock-in potential. Monitor F-Gas Regulation phase-down acceleration as the primary inflection signal for refrigerant technology winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Semiconductor Development | Captive control module production insulates Samsung and LG from foundry disruption risk. |
| Direct-to-Consumer Platform Launch | Haier's Qingdao-based D2C infrastructure demonstrates channel disintermediation viability. |
| Edge-Computing Privacy Architecture | German residential buyers prioritize local inventory processing over cloud transmission. |
| Predictive Maintenance Service Layer | Machine learning on compressor vibration data enables subscription revenue from restaurant fleets. |
| Natural Refrigerant System Redesign | Isobutane and hydrofluoroolefin transitions address EU F-Gas Regulation compliance thresholds. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EPA Energy Star certification databases, EU F-Gas regulatory filings, and customs trade records for refrigeration component flows. Appliance engineering directors, semiconductor procurement leads at OEMs, and food service fleet operators provided structured input across Korean, Chinese, German, and United States markets. Bottom-up unit shipment estimates triangulate against top-down value aggregation from manufacturer revenue disclosures.
Segmentation dimensions modeled include product configuration, connectivity protocol, end-use application, and buyer procurement authority across the projection horizon. CAGRs derive from regression analysis of historical replacement cycles, efficiency mandate adoption curves, and smart home infrastructure penetration rates. Refrigerant technology transition timelines and edge-computing hardware cost curves inform scenario-weighted outputs.
Material uncertainties — refrigerant phase-down acceleration, semiconductor foundry allocation shocks, and smart home protocol standardization outcomes — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and consumer willingness-to-pay for connected features. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Large Cooking Appliance Market
Appliances
APAC White Goods Market
Appliances
Global Electric Water Heaters Market
Appliances
Fully Automatic Dishwasher Market
Appliances
Small Electric Kettles Market
Appliances
Household Beauty Appliances Market
Appliances
Saudi Arabia Gas Hobs Market
Appliances
Digital Showers Market
Appliances
Europe Tumble Dryers Market
Appliances
Water Heater Market
Appliances
Clothing Iron Market
Appliances
Electric Dryers Market
Appliances
Electric Rice Cooker Market
Appliances
Asia-Pacific Washing Machine Market
Appliances
Smart Connected Washing Machine Market
Appliances
Kuwait Dishwasher Market