
 Hydralight Lanterns Market | 2026-2036
Hydralight Lanterns Market Size, Share, and Industry Trends Forecast 2026-2036
Hydralight Lanterns Market Analytics
Solid-state magnesium-air fuel cell technology is reconfiguring the power architecture of portable illumination devices, replacing conventional battery chemistries with water-activated electrochemical reactions that eliminate charging infrastructure dependency. Hydra Light International Limited leverages proprietary salt-water activation patents to dominate emergency preparedness channels across Australia and North America. Energizer Holdings sustains broad retail penetration through established alkaline and lithium-ion product ecosystems that compete directly with emerging hydralight formats. Streamlight specializes in tactical and first-responder applications, anchoring professional-grade demand through ANSI/NEMA FL-1 certified output specifications.
Hydralight lanterns are portable illumination devices that generate electrochemical energy through the reaction of magnesium alloy electrodes with saline or freshwater solutions, producing hydrogen gas that drives fuel cells to power LED arrays with outputs typically ranging from 25 to 300 lumens. Their primary commercial purpose centers on off-grid emergency lighting, disaster relief operations, and recreational outdoor activities where grid electricity or battery resupply proves unavailable or unreliable. Rechargeable lanterns and solar lanterns currently occupy the largest addressable segments, though hybrid systems integrating magnesium-air cells with photovoltaic trickle charging represent the fastest-expanding technology category as users seek redundant power pathways. Emergency services and residential use constitute the most concentrated end-user margin pools, with specialty stores and direct sales channels capturing premium pricing through technical consultation and institutional procurement relationships.
The EU Ecodesign Directive and REACH regulations constrain material compositions and energy efficiency claims for portable lighting sold within European markets, while the U.S. EPA and FERC influence federal procurement standards for disaster-response equipment through environmental preference programs. The EU Battery Regulation is accelerating design requirements for replaceable components and recycled content thresholds that will reshape product architecture decisions across export-oriented manufacturers. Stakeholders must monitor how evolving sodium-chloride fuel cell classifications under transport safety frameworks affect cross-border logistics and retail distribution economics.
Market Dynamics
Magnesium-air fuel cell technology is compressing the total cost of ownership for off-grid illumination by eliminating battery replacement cycles and charging infrastructure dependency across emergency services and outdoor recreation verticals.
Growth Catalysts
- Federal disaster preparedness programs:Municipal procurement of salt-water activated lighting accelerates across United States emergency management agencies seeking grid-independent illumination assets.
- EU Ecodesign Directive:Tightening energy efficiency standards for portable lighting products create regulatory pull toward electrochemical alternatives that exceed minimum lumen-per-watt thresholds.
- Magnesium alloy electrode advances:Improved corrosion resistance and activation speed extend operational lifespan in saline environments, expanding marine and coastal application viability.
Market Restraints
- Input cost volatility:Magnesium ingot prices fluctuate with Chinese smelter output and energy input costs, compressing margin stability for fuel cell manufacturers.
- Technical limitation:Hydrogen gas venting requirements constrain sealed enclosure designs, limiting underwater submersion ratings compared to solid-state battery alternatives.
- Substitution threat:Lithium-iron-phosphate battery packs with integrated solar charging compete directly on total cost of ownership for multi-day outdoor use cases.
Strategic Opportunities
- Rural utility cooperatives:United States member-owned electric distribution systems seek backup lighting for storm response without fuel logistics dependencies.
- Hybrid photovoltaic integration:Convergence of magnesium-air cells with trickle-charge solar panels creates redundant power pathways for extended off-grid deployment.
- Direct institutional procurement:Bypassing retail distribution through federal GSA schedules and municipal cooperative purchasing agreements captures premium pricing with technical consultation.
Industry Challenges
- Transport safety classification:Sodium-chloride fuel cell shipments face evolving hazardous materials designations that complicate cross-border logistics and warehouse storage economics.
- ANSI/NEMA FL-1 certification timelines:Third-party testing for lumen output, runtime, and water resistance ratings extends product launch cycles by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydralight Lanterns Market |
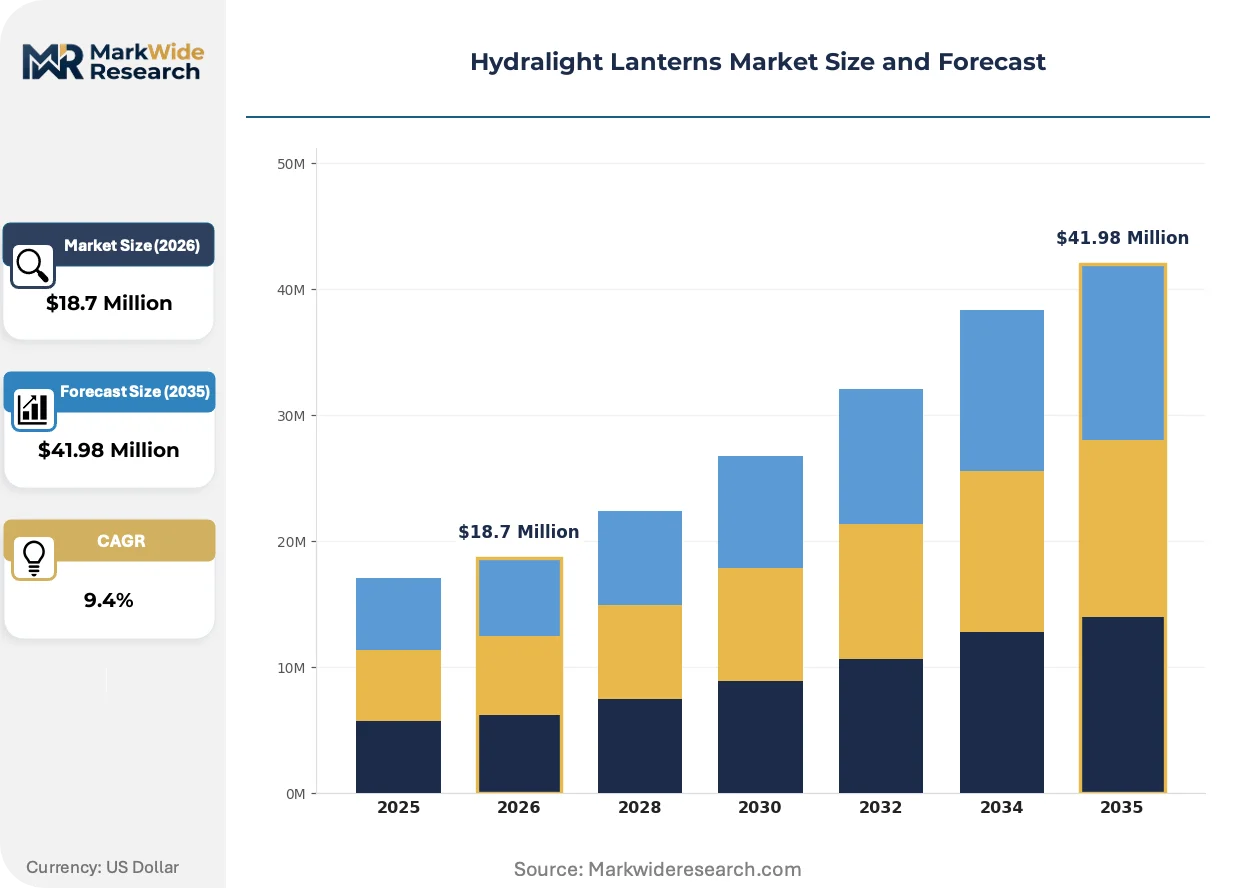
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $41.98 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rechargeable Lanterns, Solar Lanterns, LED Lanterns, Traditional Lanterns End User: Campsites, Emergency Services, Residential Use, Outdoor Events Technology: Solar Technology, Battery Technology, Fuel Technology, Hybrid Systems Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Hydra Light International Limited, Energizer Holdings, Maglite, Streamlight, Princeton Tec, Fenix Lighting, Nitecore, Goal Zero, Black Diamond Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydralight Lanterns Market Evolving Landscape
Solid-state electrochemistry and regulatory pressure on battery supply chains are converging to reposition water-activated illumination from niche emergency backup toward mainstream off-grid infrastructure.
Magnesium-air fuel cell architecture is rendering obsolete the dependency on lithium-ion supply chains for portable emergency lighting. Federal disaster response agencies in the United States are standardizing salt-water activated inventory at scale. This technology compression eliminates charging infrastructure requirements while sidestepping critical mineral sourcing constraints.
REACH regulations and the EU Battery Regulation are mandating replaceable component design and recycled content thresholds for portable lighting sold in European markets. Manufacturers must reconfigure product architecture to accommodate serviceable fuel cartridges and document material provenance. Export-oriented suppliers face compliance cost escalation that favors larger production volumes.
Buyer preference is rotating toward redundant power pathway systems that combine multiple generation methods. Specialty outdoor retailers report accelerating interest in hybrid lanterns integrating magnesium-air cells with photovoltaic trickle charging. This pattern concentrates in United States recreational markets where extended backcountry trips demand failure-resistant illumination.
Hydralight Lanterns Market Segmentation
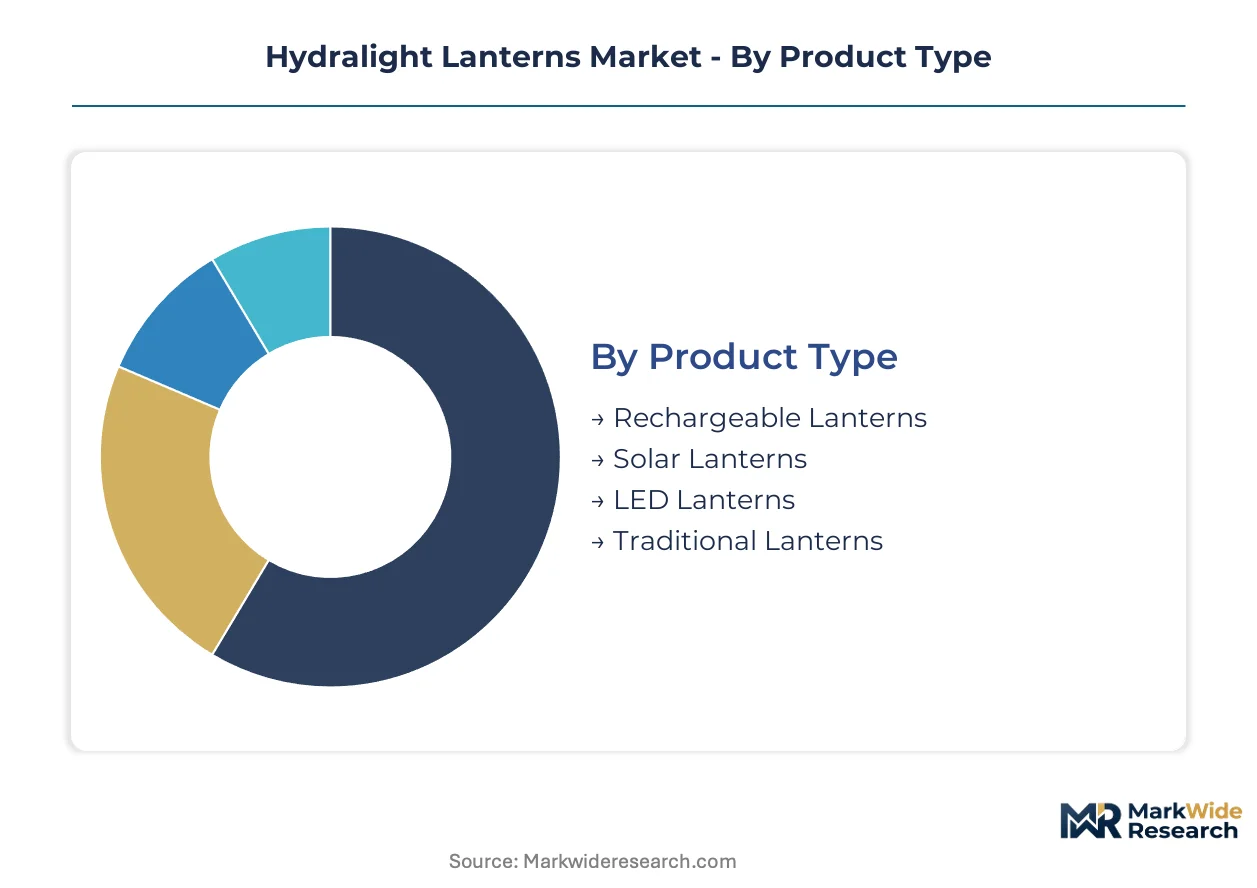
Segmentation in hydralight lanterns reveals how electrochemical activation technology intersects with distinct procurement channels and use-case durability requirements. Each category exposes different margin structures and technical consultation intensities that shape go-to-market economics.
Product Type:
After-sales service intensity varies sharply across product architectures, with fuel-cell-based systems demanding cartridge replacement programs while solid-state alternatives minimize ongoing touchpoints.
- Rechargeable Lanterns:Lithium-ion and nickel-metal hydride cell configurations dominate residential preparedness kits through established retail ecosystems. Demand concentrates in United States suburban households seeking FEMA-recommended emergency supplies with familiar plug-in recharging protocols.
- Solar Lanterns:Photovoltaic-integrated enclosures with integrated battery storage serve rural African and South Asian off-grid communities where distributed generation outpaces grid extension. Photovoltaic module efficiency gains and falling polysilicon costs compress unit economics for development-finance procurement programs.
- LED Lanterns:Solid-state illumination arrays with alkaline or lithium primary batteries anchor mass-market retail penetration through hardware and sporting goods channels.
- Traditional Lanterns:Kerosene and propane combustion formats persist in price-sensitive segments and legacy institutional inventories despite emissions and fuel logistics constraints.
By volume, LED Lanterns leads. By growth pace, Solar Lanterns is ahead.
End User:
Application context dictates performance certification requirements and purchasing authority structures, with institutional buyers commanding technical specification influence that residential consumers cannot replicate.
- Emergency Services:Fire departments, search-and-rescue units, and disaster response agencies specify ANSI/NEMA FL-1 certified output, runtime, and water resistance ratings. United States federal procurement through GSA schedules and state cooperative purchasing agreements concentrates demand for salt-water activated formats that eliminate fuel logistics in inundated environments.
- Campsites:Recreational outdoor enthusiasts prioritize weight minimization and multi-day runtime for backcountry expeditions where battery resupply proves impractical. Demand clusters in United States national park gateway communities and Canadian wilderness access points.
- Residential Use:Homeowners stock grid-independent lighting for hurricane, wildfire, and winter storm contingencies, with purchase decisions driven by retail availability and FEMA guideline familiarity.
- Outdoor Events:Festival operators and temporary infrastructure providers rent or purchase high-output units for perimeter lighting and egress path marking where grid connection costs exceed temporary power budgets.
By volume, Residential Use leads. By growth pace, Emergency Services is expanding most quickly.
Technology:
Technology selection determines supply chain exposure to critical mineral markets and regulatory compliance complexity across transport safety and end-of-life disposal frameworks.
- Hybrid Systems:Convergent architectures combining magnesium-air fuel cells with photovoltaic trickle charging create redundant power pathways for extended off-grid deployment. United States specialty outdoor retailers report accelerating interest as backcountry users seek failure-resistant illumination across multi-week expeditions.
- Fuel Technology:Magnesium-air electrochemical cells utilizing saline or freshwater activation eliminate charging infrastructure dependency and lithium supply chain exposure. Marine and coastal applications expand as corrosion-resistant electrode formulations improve activation speed in high-salinity environments.
- Solar Technology:Standalone photovoltaic conversion with integrated storage serves equatorial off-grid markets where insolation patterns support predictable daily cycling.
- Battery Technology:Conventional alkaline and lithium-ion chemistries retain cost advantages in high-frequency use cases with reliable grid access for recharging.
By volume, Battery Technology leads. By growth pace, Hybrid Systems is gaining share fastest.
Distribution Channel:
Channel structure shapes pricing power and technical consultation depth, with direct institutional relationships capturing premium positioning that mass retail cannot replicate.
- Direct Sales:Manufacturer-to-institutional procurement bypasses distributor margins for federal agencies, municipal emergency management departments, and rural utility cooperatives seeking technical specification consultation and volume pricing. United States GSA schedules and cooperative purchasing agreements concentrate high-value transactions in this channel.
- Specialty Stores:Outdoor recreation and emergency preparedness retailers provide hands-on product demonstration and staff expertise that converts consideration into purchase for technical buyers.
- Online Retail:E-commerce platforms aggregate comparison shopping and user review influence for price-sensitive residential purchasers.
- Wholesale Distributors:Inventory aggregation and logistics services support retail channel replenishment with limited end-user technical engagement.
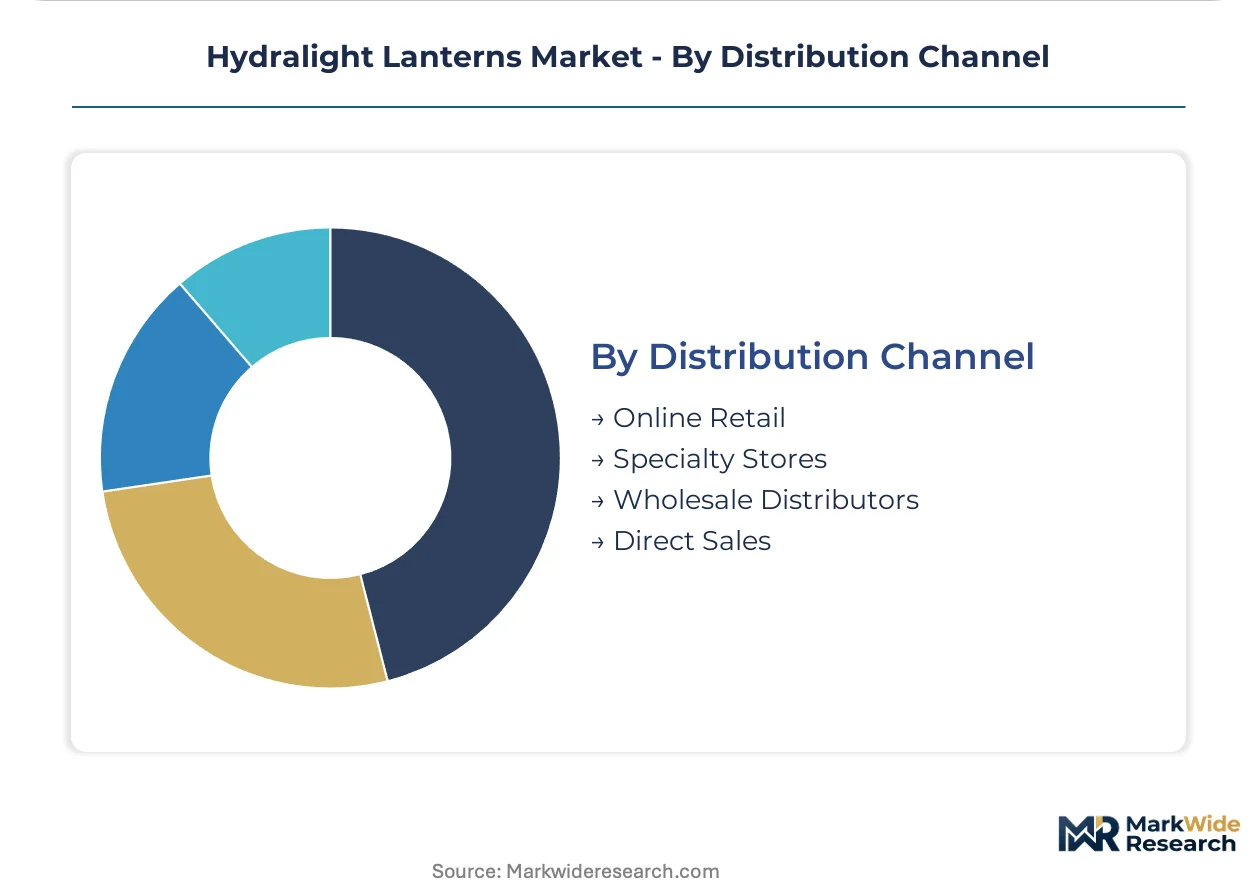
By volume, Online Retail leads. By growth pace, Direct Sales is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Emergency management agencies and rural utility cooperatives concentrate procurement authority across developed markets, with regulatory pressure on battery supply chains accelerating geographic diversification of magnesium-air fuel cell deployment.
United States
Federal disaster preparedness programs and FEMA-recommended emergency supply guidelines drive institutional procurement of salt-water activated lighting. The EPA and FERC influence environmental preference standards for federal procurement of disaster-response equipment. Rural electric cooperatives in the Mountain West and Southeast stock grid-independent backup illumination for storm response without fuel logistics dependencies.
Germany
REACH regulations and the EU Ecodesign Directive mandate replaceable component design and energy efficiency thresholds for portable lighting products. The ECHA enforces chemical composition standards that constrain material selections for electrochemical cells. Industrial clusters in Bavaria and Baden-Württemberg host precision manufacturing capabilities for corrosion-resistant magnesium alloy electrode formulations.
Australia
Bushfire preparedness programs and remote community infrastructure needs expand demand for water-activated illumination in off-grid environments. The country's national energy regulator influences standards for distributed emergency power systems. Queensland and Western Australia concentrate marine and coastal applications where high-salinity activation environments test electrode corrosion resistance.
Japan
METI promotes disaster resilience technologies through public-private partnerships for earthquake and tsunami response capabilities. JIS standards govern performance certification requirements for portable emergency lighting equipment. The Kansai region around Osaka maintains precision metalworking expertise for fuel cell component fabrication.
Canada
Arctic community infrastructure and remote resource extraction operations require illumination independent of battery resupply logistics. Health Canada and Environment and Climate Change Canada regulate transport safety classifications for sodium-chloride fuel cell shipments. Alberta and the Prairie Provinces concentrate rural utility cooperative procurement for winter storm contingency planning.
Hydralight Lanterns Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments where federal GSA schedules and municipal cooperative purchasing agreements concentrate high-value transactions. The vendor base spans diversified battery manufacturers, tactical lighting specialists, and emergent fuel-cell technology developers. Three archetypes dominate: established consumer electronics brands with retail distribution depth, professional-grade lighting specialists with ANSI/NEMA FL-1 certification capabilities, and magnesium-air technology developers with proprietary salt-water activation patents. Competitive moves center on strategic partnerships with institutional procurement channels and portfolio diversification into hybrid photovoltaic-magnesium-air architectures.
Within the technology-specialist tier, Hydra Light International Limited exemplifies proprietary fuel-cell positioning through salt-water activation patents. Among diversified lighting manufacturers, Energizer Holdings and Streamlight occupy positions spanning consumer retail and professional-grade channels respectively. These three anchors represent distinct competitive vectors: pure-technology licensing, mass-market brand leverage, and tactical certification expertise.
| Leading Market Players |
|---|
| Hydra Light International Limited |
| Energizer Holdings |
| Maglite |
| Streamlight |
| Princeton Tec |
| Fenix Lighting |
| Nitecore |
| Goal Zero |
| Black Diamond Equipment |
| Others |
Value Network & Pricing Analysis
Chinese magnesium smelter concentration anchors upstream cost volatility, transmitting directly to fuel cell manufacturers who must absorb ingot price swings or push through downstream. Margin pools concentrate with institutional procurement channels that lock in volume commitments through GSA schedules and municipal cooperative purchasing agreements.
Pricing Analysis
Cost-plus contracts with magnesium ingot indexation dominate long-term supply agreements between electrode fabricators and fuel cell assemblers. ANSI/NEMA FL-1 certification tier and after-sales cartridge replacement bundling drive price differentiation across emergency services, residential, and recreational segments. Pricing pressure stems from lithium-iron-phosphate battery pack substitution in multi-day outdoor use cases. Residential purchasers exhibit highest price sensitivity through retail comparison shopping, while federal emergency management agencies accept premium positioning for grid-independence guarantees.
Supply Chain Analysis
Export control regimes on magnesium alloy electrode formulations constrain technology transfer to non-allied manufacturing jurisdictions. Supply concentrates in China for magnesium ingot primary production, Taiwan for precision electrode machining, and Japan for corrosion-resistant alloy formulations. Raw material dependencies span magnesium ingots, saline activation packets, and LED array modules. Single-source vulnerability runs through Chinese smelter output disruptions. Distribution runs through direct institutional procurement for high-value transactions, specialty outdoor retailers for technical consultation, and e-commerce platforms for residential price discovery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through federal GSA schedule consolidation and municipal cooperative purchasing aggregation, fragmenting vendor pricing leverage across institutional procurement channels.
For Market Incumbents: Build certification moats around ANSI/NEMA FL-1 testing infrastructure investments that extend product launch timelines for challengers. Deepen backward integration into magnesium alloy electrode production to offset Chinese ingot price volatility. Anchor channel control through exclusive GSA schedule relationships that preempt municipal procurement aggregation. For New Entrants and Emerging Players: Establish a beachhead in rural utility cooperative procurement segments where technical consultation requirements favor smaller-scale relationship selling. Target marine and coastal applications where corrosion-resistant electrode formulations remain underdeveloped. Pursue direct institutional sales channels bypassing retail margin extraction. For Investors and Strategic Acquirers: Capital is best deployed toward hybrid technology developers combining magnesium-air cells with photovoltaic trickle charging, as redundant power pathway demand accelerates across United States backcountry recreation markets. Long-term viability hinges on transport safety classification resolution for sodium-chloride fuel cell shipments. Watch for EPA environmental preference program revisions as inflection indicator for federal procurement volume shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Photovoltaic Integration | Combines magnesium-air cells with solar trickle charging for redundant off-grid power pathways. |
| ANSI/NEMA FL-1 Certification Investment | Third-party testing infrastructure creates six-to-nine month launch barriers for unproven competitors. |
| Direct Institutional Procurement Channel | Bypasses retail margin extraction through federal GSA schedules and municipal cooperative purchasing. |
| Corrosion-Resistant Electrode R&D | Extends marine and coastal application viability through improved activation speed in high-salinity environments. |
| Cartridge Replacement Service Programs | Captures recurring revenue streams from fuel cell-based systems through ongoing after-sales touchpoints. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with emergency management procurement officers, outdoor recreation retail buyers, magnesium alloy electrode fabricators, and fuel cell system engineers. Secondary validation drew from FEMA procurement databases, EPA environmental preference program filings, United States Customs magnesium ingot trade records, and ANSI/NEMA FL-1 certification registries. Bottom-up unit economics triangulated against top-down addressable market sizing across product type, end user, technology, and distribution channel dimensions.
Calibration anchored volume and value outputs to observed institutional procurement transaction values and retail point-of-sale patterns across the projection horizon. Segmentation modeling incorporated product architecture, activation technology, buyer procurement authority, and channel structure variables. CAGRs derived from historical magnesium-air fuel cell adoption curves and lithium-ion substitution elasticity estimates. Forecast inputs included federal disaster preparedness budget appropriations and EU Ecodesign Directive compliance cost escalations.
Macroeconomic conditions sit as an overlay; deviation in magnesium ingot commodity prices or Chinese energy input costs would shift the trajectory. Forecasts reflect assumptions around transport safety classification stability and REACH regulation enforcement intensity. Material shifts in federal emergency management procurement standardization or EU Battery Regulation replaceable component mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Japan Digital Showers Market
Household Items
Memory Foam Market
Household Items
Toilet Rim Blocks Market
Household Items
Brazil Cookware Market
Household Items
Smart Spin Mop Market
Household Items
Toilet Brush Market
Household Items
Massage Pillow Market
Household Items
Replacement Sheets Market
Household Items
Ceramic Travel Mug Market
Household Items
Insulated Drinkware Market
Household Items
India POU Water Purifiers Market
Household Items
Drinkware Market
Household Items
Heated Towel Rail Market
Household Items
Cutlery Market
Household Items
North America Ceramic Barbeque Grill Market
Household Items
Japan Faucets Market