
 MENA POU Water Purifiers Market | 2026-2036
MENA POU Water Purifiers Market Size, Share, and Industry Trends Forecast 2026-2036
MENA POU Water Purifiers Market Foresight
A capital-intensity divergence between membrane fabrication capabilities and assembly-only operations is redrawing competitive tiers in the MENA POU water purifiers space. A.O. Smith Corporation leverages captive reverse-osmosis membrane production to command premium positioning in Saudi Arabia's project market. Kent RO Systems Ltd. anchors its Gulf presence through distributor-trained service networks that reduce replacement-cycle attrition.
Point-of-use water purifiers are self-contained filtration units installed at single water access points, typically incorporating sediment pre-filters, activated carbon stages, and UV or membrane-based final barriers to remove particulates, dissolved solids, and microbiological contaminants for direct consumption. Reverse osmosis systems dominate value capture in the MENA residential segment due to high feed-water salinity across Gulf Cooperation Council states. UV purifiers gain share in Lebanese and Jordanian markets where electricity reliability constraints favor low-wattage alternatives. The hospitality end-user channel now specifies nanofiltration-equipped units that preserve mineral content for premium food-service applications.
SASO's water efficiency standards, the UAE's Emirates Authority for Standardization and Metrology (ESMA) registration requirements, and Egypt's mandatory conformity assessments through the General Organization for Export and Import Control collectively raise compliance costs for non-certified suppliers. These frameworks shift procurement criteria from upfront price toward verified performance documentation and local service presence. Stakeholders must track which certification pathways Gulf regulators will mutually recognize versus maintain as country-specific gates.
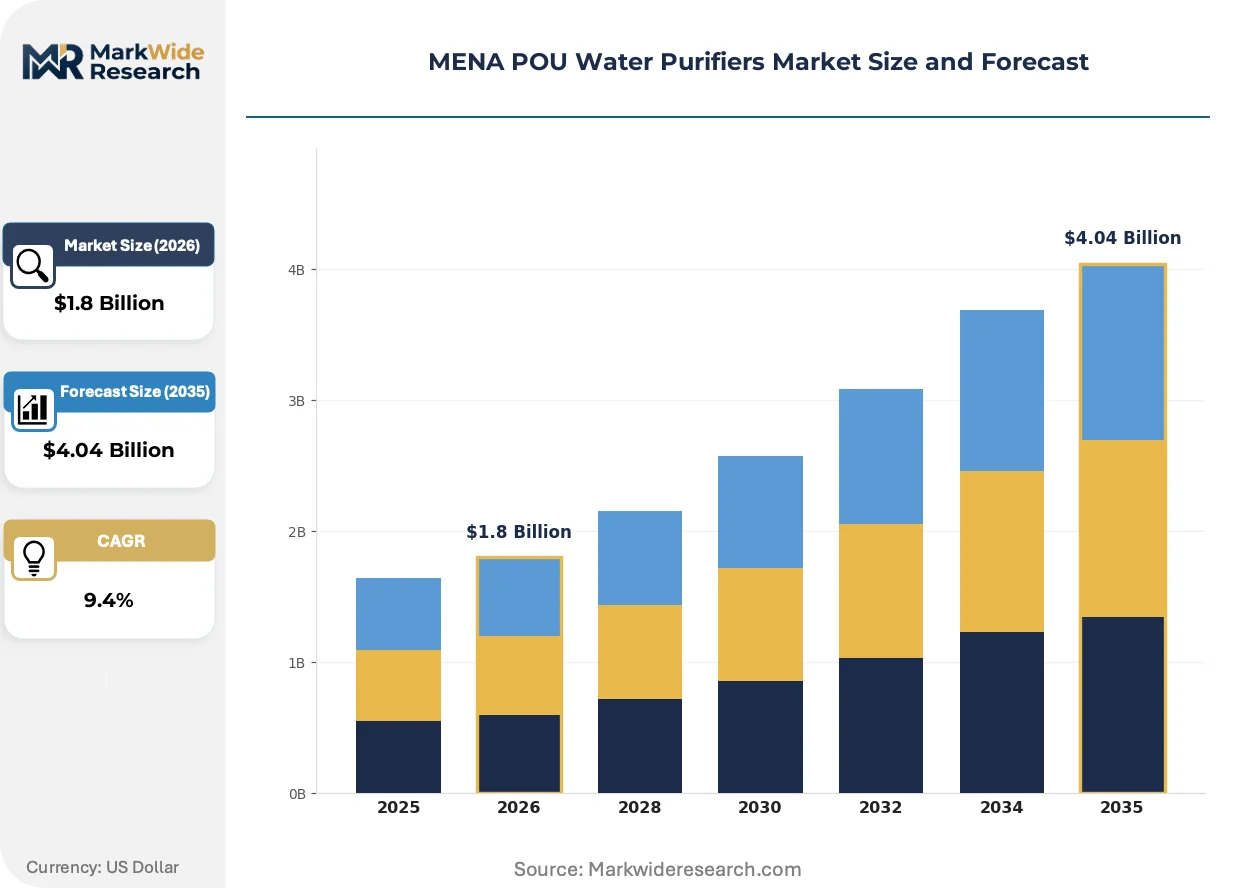
Market Dynamics
Membrane fabrication capabilities are redrawing competitive tiers across the MENA POU water purifiers market, separating captive producers from assembly-only operators and reshaping procurement criteria toward verified performance documentation.
Growth Catalysts
- SASO Water Efficiency Labeling:Saudi Arabia's tightening performance thresholds for imported units are accelerating replacement cycles among commercial end-users seeking compliant certification.
- Commercial Kitchen Channel:Food-service operators across Dubai now specify nanofiltration-equipped systems that preserve mineral content for premium culinary applications.
- Reverse Osmosis Membrane Advances:Feed-water salinity levels across Gulf Cooperation Council states are driving specification upgrades in residential installations.
Market Restraints
- Import Certification Costs:Egypt's mandatory conformity assessments through the General Organization for Export and Import Control create multi-month approval delays for non-certified suppliers.
- Electricity Reliability Constraints:Lebanese and Jordanian markets face operational limitations that restrict UV purifier deployment in off-grid residential clusters.
- Membrane Supply Concentration:Captive production capabilities among tier-one manufacturers limit sourcing flexibility for assembly-only market entrants.
Strategic Opportunities
- Service Network Gaps:Distributor-trained technical capacity remains underdeveloped across secondary Saudi cities, creating first-mover advantages for organized service providers.
- Hospitality Specification Uplift:Riyadh hotel operators are transitioning from bulk filtration to point-of-use guest-facing installations.
- Cross-Border Certification Recognition:Mutual recognition pathways between ESMA and SASO frameworks could reduce duplicate testing burdens for multi-market suppliers.
Industry Challenges
- Replacement Cycle Attrition:Filter cartridge renewal rates lag installation volumes where local service infrastructure remains sparse.
- Multi-Jurisdiction Compliance:Divergent testing protocols between UAE, Saudi Arabia, and Egypt force product line fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MENA POU Water Purifiers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UV Purifiers, Reverse Osmosis Systems, Activated Carbon Filters, Gravity Filters Technology: Microfiltration, Nanofiltration, Electrochemical, Ultraviolet End User: Residential, Commercial, Industrial, Hospitality Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | A.O. Smith Corporation, Brita GmbH, Kent RO Systems Ltd., LG Electronics, Coway Co. Ltd., Eureka Forbes Ltd., Pentair PLC, Best Water Technology Group, Culligan International Company, Others |
| Regions Covered | MENA: Saudi Arabia, UAE, Qatar, Kuwait, Egypt, Morocco, Algeria, Tunisia, Rest of MENA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MENA POU Water Purifiers Market Shifts & Advancements
Active filtration technologies are compressing form factors while regulatory convergence and buyer sophistication are rewriting procurement specifications across the MENA region.
Tankless reverse osmosis systems are eliminating storage reservoir requirements through direct-flow membrane configurations. Hospitality operators in Dubai are specifying these units for premium guest room installations. The technology is miniaturizing under-sink footprints from cabinet-scale to drawer-compatible dimensions.
ESMA registration requirements are mandating third-party performance verification for all imported water treatment devices. The UAE's Emirates Authority for Standardization and Metrology now requires documented contaminant reduction rates prior to market entry. Commercial distributors are consolidating supplier relationships around pre-certified product portfolios to reduce compliance timeline risk.
Buyer evaluation criteria are migrating from upfront capital cost toward total cost of ownership calculations spanning filter replacement intervals and energy consumption. Food-service procurement teams in Riyadh now require five-year operating cost projections alongside initial quotes. This specification discipline is compressing margins for low-service, low-availability suppliers across the Saudi project market.
MENA POU Water Purifiers Market Segmentation
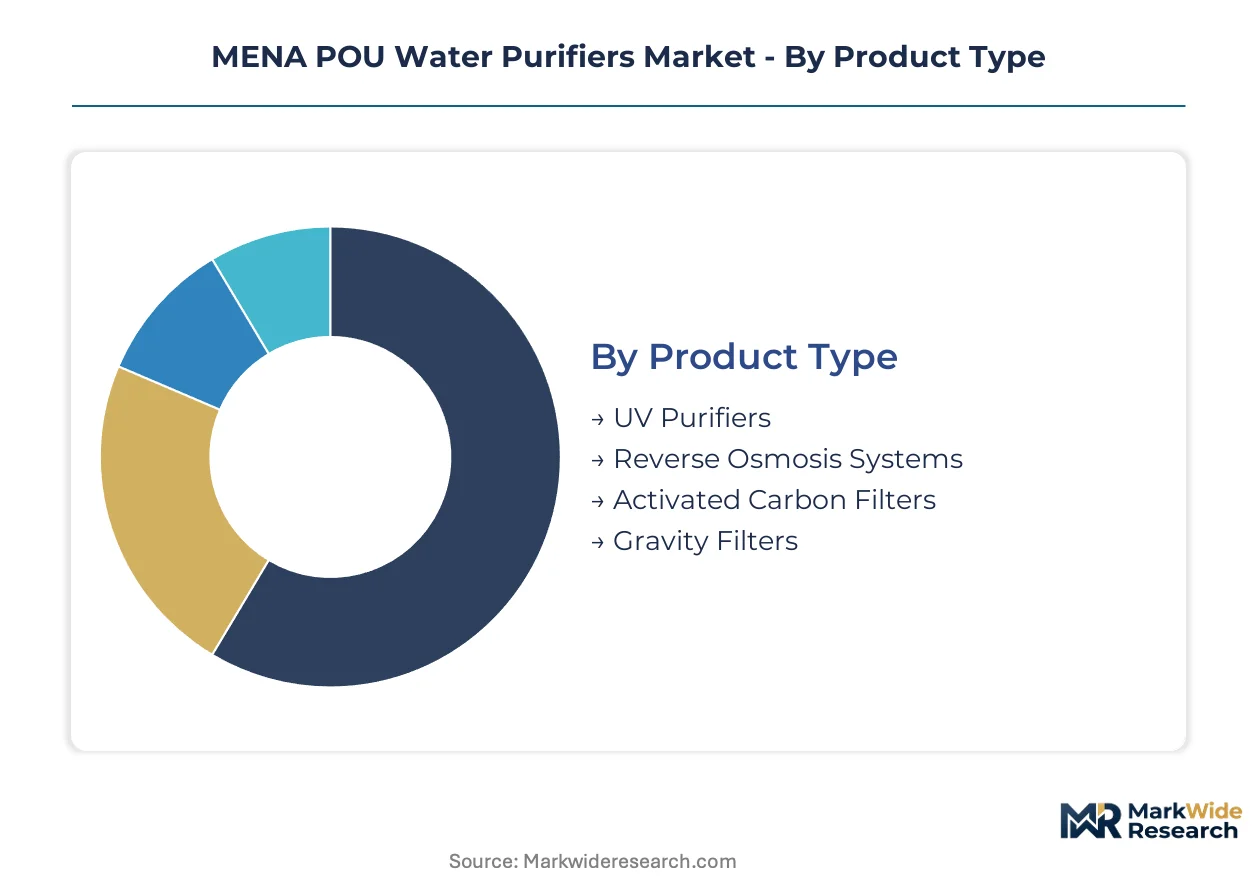
Point-of-use water purification technology fragments across multiple technical and commercial axes in MENA markets. Feed-water chemistry variations between Gulf Cooperation Council states and Levantine territories create divergent specification requirements. Procurement channels reflect distinct service intensity needs across hospitality, residential, and industrial end-users.
Product Type:
Margin pools concentrate in membrane-based systems where captive fabrication capabilities command pricing premiums against assembly-only competitors.
- Reverse Osmosis Systems:Multi-stage membrane configurations force water through semi-permeable barriers to reject dissolved solids exceeding 99 percent. Saudi Arabia's commercial kitchen operators specify these units for SASO-compliant installations in Riyadh food-service clusters. High feed-water salinity across Gulf Cooperation Council states sustains specification dominance despite elevated energy draw.
- UV Purifiers:Ultraviolet germicidal irradiation at 254 nanometers disrupts microbiological DNA without chemical additives. Lebanese residential markets favor these units where electricity reliability constraints limit power-intensive alternatives. Compact form factors suit Beirut apartment installations with space restrictions.
- Activated Carbon Filters:Adsorptive media remove chlorine, organic compounds, and taste-odor contaminants through porous carbon structures. These units serve as pre-treatment stages in Dubai hospitality pre-filtration trains.
- Gravity Filters:Unpowered ceramic or carbon block elements rely on hydrostatic pressure for contaminant reduction. Off-grid Jordanian rural clusters deploy these where electrical infrastructure remains intermittent.
The dominant share belongs to Reverse Osmosis Systems, while UV Purifiers are closing the gap fastest.
Technology:
Application-specific performance thresholds determine which filtration mechanisms capture volume in each MENA territory.
- Nanofiltration:Pore-size selectivity between reverse osmosis and ultrafiltration retains divalent ions while passing monovalent salts. Dubai hotel operators specify these membranes for guest-facing installations where mineral preservation enhances taste profiles. Premium food-service applications in UAE commercial kitchens drive specification uplift.
- Ultraviolet:Mercury-vapor or LED-based irradiation delivers log-reduction of pathogens without physical barrier replacement. Jordanian municipal water treatment facilities integrate UV polishing stages where chemical disinfection residuals are restricted.
- Microfiltration:Hollow-fiber or pleated polymer membranes exclude particulates and cysts above 0.1 micron. These systems protect downstream reverse osmosis membranes in Saudi industrial pre-treatment configurations.
- Electrochemical:Electrode-based ion separation removes dissolved metals and nitrates through redox reactions. Emerging deployments in Egyptian agricultural processing address heavy-metal contamination in Nile Delta irrigation sources.
Nanofiltration holds the revenue concentration, though Ultraviolet is gaining share fastest in electricity-constrained territories.
End User:
Service infrastructure availability shapes which customer categories sustain replacement revenue streams.
- Hospitality:Hotels, resorts, and food-service operators specify point-of-use systems for guest-facing water quality assurance. Riyadh luxury properties are transitioning from bulk filtration to in-room installations. Procurement teams require five-year operating cost projections alongside capital quotes.
- Commercial:Office buildings, retail spaces, and institutional facilities demand reliable potable water for occupant consumption. Dubai commercial kitchen operators specify nanofiltration-equipped units for premium culinary applications.
- Residential:Individual households select countertop, under-sink, or faucet-mounted units based on space constraints and water quality concerns. Saudi residential projects specify reverse osmosis systems for villa developments in Jeddah and Dammam corridors.
- Industrial:Manufacturing and processing facilities deploy point-of-use polishing for sensitive production processes. Egyptian pharmaceutical manufacturers pre-certify systems through GOEIC conformity assessments prior to installation.
Hospitality commands the margin premium, while Commercial is expanding most quickly through food-service channel specification.
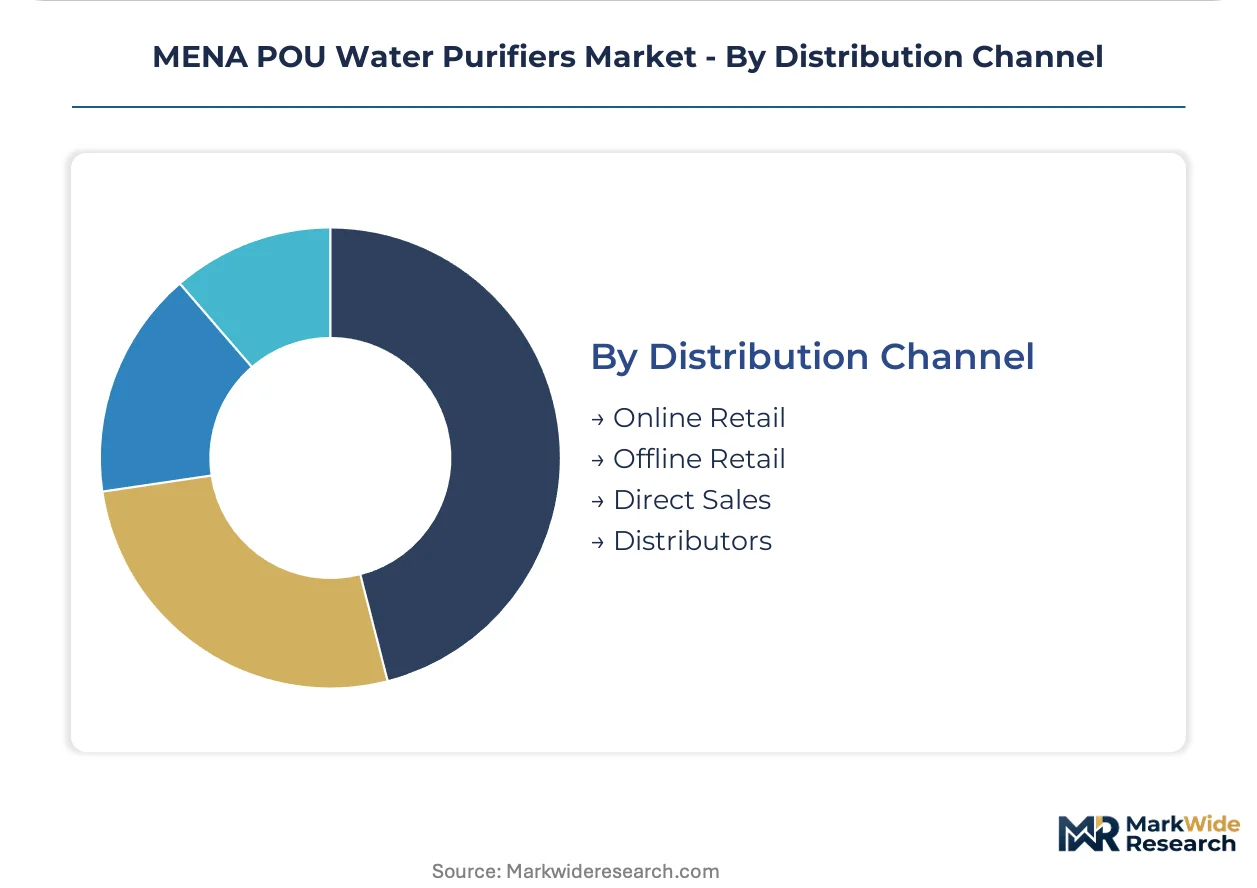
Distribution Channel:
Technical support proximity determines channel viability across MENA territories with divergent service infrastructure maturity.
- Distributors:Authorized regional networks provide installation, maintenance, and cartridge replacement logistics. Kent RO Systems anchors Gulf presence through distributor-trained service networks that reduce replacement-cycle attrition. Secondary Saudi cities present first-mover advantages for organized technical capacity.
- Direct Sales:Manufacturer-led project teams engage large hospitality and industrial accounts with customized specifications. A.O. Smith Corporation leverages captive membrane production to command premium positioning in Saudi project markets.
- Offline Retail:Bricks-and-mortar showrooms and specialty stores enable physical product evaluation. UAE consumer electronics chains stock ESMA-registered portfolios to reduce compliance timeline risk for buyers.
- Online Retail:E-commerce platforms and direct-to-consumer websites facilitate price comparison and convenience purchasing. Egyptian market entry delays through GOEIC assessments limit cross-border digital sales velocity.
Distributors retain the structural advantage, while Direct Sales is climbing the fastest through hospitality specification uplift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Saudi Arabia and the UAE exhibit low price elasticity for certified systems, while Egyptian and Jordanian markets demand value-engineered alternatives. This demand-elasticity contrast shapes regional competitive positioning and channel strategies.
United Arab Emirates
Hospitality operators in Dubai specify nanofiltration-equipped point-of-use systems for premium guest-facing installations. ESMA registration requirements mandate third-party performance verification for all imported water treatment devices. The commercial kitchen channel in Dubai drives specification uplift for mineral-preserving filtration in food-service applications.
Saudi Arabia
SASO water efficiency labeling rules are tightening performance thresholds for imported units, accelerating replacement cycles among commercial end-users. The national standards body enforces documented contaminant reduction rates prior to market entry. Riyadh hotel operators are transitioning from bulk filtration to in-room point-of-use installations.
Egypt
Residential demand concentrates in value-engineered reverse osmosis systems for Nile Delta villa developments. Mandatory conformity assessments through the General Organization for Export and Import Control create multi-month approval delays for non-certified suppliers. Cairo pharmaceutical manufacturers pre-certify systems through GOEIC assessments prior to installation.
Jordan
Electricity reliability constraints favor low-wattage UV purifiers in Beirut apartment installations with space restrictions. The national water utility promotes decentralized treatment where municipal infrastructure remains intermittent. Rural clusters in the north deploy gravity filters where electrical infrastructure is unavailable.
MENA POU Water Purifiers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the MENA POU water purifiers market. Captive membrane fabrication capabilities separate premium-positioned manufacturers from assembly-only operators. Two strategic archetypes dominate: vertically integrated membrane producers and distributor-trained service network operators. Competitive moves concentrate on certification pre-positioning for multi-jurisdiction compliance and service infrastructure buildout in secondary cities.
Among integrated membrane producers, A.O. Smith Corporation exemplifies the captive-fabrication archetype through its reverse-osmosis membrane production. Kent RO Systems Ltd. anchors the service-network tier through distributor-trained technical capacity. LG Electronics occupies a position bridging consumer electronics distribution with water treatment specialization. These three represent divergent strategic vectors: upstream control over critical components, downstream service density, and cross-category brand leverage.
| Leading Market Players |
|---|
| A.O. Smith Corporation |
| Brita GmbH |
| Kent RO Systems Ltd. |
| LG Electronics |
| Coway Co. Ltd. |
| Eureka Forbes Ltd. |
| Pentair PLC |
| Best Water Technology Group |
| Culligan International Company |
| Others |
Supply & Pricing Matrix
Tankless reverse-osmosis membrane modules displacing conventional storage-tank configurations are redrawing supply geography toward South Korean and Chinese component hubs while compressing landed-cost structures for Dubai hospitality procurement teams. This substitution dynamic simultaneously elevates after-sales service premiums and fragments sourcing concentration across multiple assembly corridors.
Pricing Analysis
Filter cartridge replacement contracts and annual maintenance subscriptions capture lifetime value exceeding original equipment margins by substantial multiples. Three-tier pricing structure across premium, standard, and economy levels separates ESMA-certified systems from SASO-registered units and uncertified gray-market alternatives. Pricing pressure stems from Egyptian GOEIC assessment delays extending working-capital cycles for importers. Food-service operators in Riyadh exhibit lowest price sensitivity while Jordanian residential clusters demand value-engineered gravity-filter alternatives.
Supply Chain Analysis
Port congestion at Jebel Ali and container availability constraints on Asia-Middle East trade lanes are extending lead times for membrane module deliveries into Saudi project markets. Supply concentrates in China for polyamide thin-film composite membranes, South Korea for pump and valve assemblies, and Taiwan for UV-C LED emitters. Raw material dependencies span high-purity aluminum oxide for ceramic filters, food-grade activated carbon from coconut shell sources, and specialized polymer resins for hollow-fiber housings. Single-source vulnerability concentrates in reverse-osmosis membrane chemistry where captive fabrication capabilities limit second-sourcing flexibility. Distribution runs through authorized distributor networks with certified installation capacity across Gulf Cooperation Council territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is materializing as hospitality procurement teams consolidate supplier relationships around pre-certified product portfolios that reduce multi-jurisdiction compliance timeline risk. Interoperability between ESMA and SASO testing protocols would collapse duplicate certification burdens and concentrate procurement spend on integrated service-platform providers.
For Market Incumbents: Shield installed-base revenue streams by embedding IoT-enabled filter-monitoring capabilities that preempt third-party service encroachment. Deepen backward integration into membrane fabrication to defend margin position against Chinese assembly-only entrants. Prioritize certification pre-positioning for Egyptian GOEIC conformity assessments ahead of competitor market-entry timelines.
For New Entrants and Emerging Players: Differentiate on service-network density rather than membrane specification parity. Target secondary Saudi cities where distributor-trained technical capacity remains underdeveloped. Penetrate through hospitality direct-sales channels requiring five-year operating-cost projections alongside capital quotes.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional distributors possessing ESMA-registered portfolios but limited membrane-fabrication capabilities. Five-to-ten-year viability hinges on backward-integration completion or exclusive supply agreements with captive producers. Monitor ESMA-SASO mutual-recognition negotiations as inflection indicator for multi-market scalability premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Positioning | GOEIC conformity assessments in Egypt compress first-mover advantage windows for compliant suppliers. |
| Service Network Expansion | Distributor-trained technical capacity in secondary Saudi cities reduces replacement-cycle attrition rates. |
| Backward Integration | In-house reverse-osmosis membrane production commands premium positioning in Riyadh project markets. |
| Platform Integration | IoT-enabled filter monitoring embeds recurring revenue streams within hospitality installed bases. |
| Geographic Expansion | Lebanese UV-purifier deployment addresses electricity-constrained residential clusters with low-wattage alternatives. |
Research Methodology
Cross-validation between regulatory filing analysis and distributor channel interviews anchors the qualitative findings across this study. Primary fieldwork engaged membrane-fabrication engineers, hospitality procurement directors, ESMA certification consultants, and aftermarket service technicians. Secondary sources encompassed SASO technical regulations, GOEIC conformity assessment protocols, customs trade databases, and SEC filings from listed water-treatment equipment manufacturers. Bottom-up demand modeling triangulated against top-down macroeconomic projections.
Sensitivity analysis tested forecast robustness across membrane-cost inflation scenarios and certification-timeline variations throughout the projection horizon. Segmentation dimensions modeled include product type, technology mechanism, end-user vertical, and distribution channel structure. CAGRs derived from regression-based trending of replacement-cycle velocities and specification-upgrade frequencies. Feed-water salinity indices and electricity-reliability metrics informed territory-level adoption curves.
Material uncertainties — regulatory reciprocity failures, membrane-supply disruptions, and hospitality-capacity expansion delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding certification-pathway stability and service-infrastructure buildout rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Middle East and Africa B2B Air Care Market
Household Items
Basin, Bowl, and Cup Market
Household Items
Coffin and Cremation Urn Market
Household Items
North America Glassware Market
Household Items
Asia-Pacific Digital Showers Market
Household Items
Asia-Pacific Hand Dryer Market
Household Items
Global Rimless Toilets Market
Household Items
Facial Tissue Market
Household Items
Floor-Standing Integrated Smart Toilet Market
Household Items
Smart Drying Racks Market
Household Items
Dry Vacuum Cleaner Market
Household Items
Sleeping Pods Market
Household Items
Global Tableware Market
Household Items
Global Electronic Bidet Seats Market
Household Items
Sleeping Pillow Market
Household Items
Smart Connected Water Purifier Market