
 Soap Tablet Market | 2026-2036
Soap Tablet Market Size, Share, and Industry Trends Forecast 2026-2036
Soap Tablet Market Analytics
Pharmaceutical-grade surfactant purity is unwinding cost structures across the soap tablet category as manufacturers reformulate around higher-active concentrates. Blueland leverages direct-to-consumer subscription mechanics to sustain repeat purchase rates in household segments. Reckitt Benckiser anchors shelf presence through mass retail drugstore partnerships in North America. Colgate-Palmolive competes on manufacturing scale, operating integrated personal care facilities that feed tablet production lines.
Soap tablets are compressed solid cleansing formulations containing 15-40% active surfactant, 20-50% filler binders such as starch or talc, and 5-15% humectants, produced through high-pressure rotary tableting or slugging processes designed for controlled dissolution upon water contact. Their primary commercial purpose is to deliver measured, portable hygiene without liquid carriers, reducing shipping weight and packaging waste relative to conventional bottled products. Organic and antibacterial product types split the margin pool, with organic variants commanding premium positioning in specialty channels while antibacterial formats dominate institutional procurement for hospitals and schools. Online distribution channels represent the fastest-growing access route, though supermarkets still handle the bulk volume for household end users seeking immediate replenishment.
FDA oversight of cosmetic labeling and antimicrobial claims shapes product positioning for US manufacturers, while the EU REACH framework governs surfactant chemical safety and restricts certain preservative systems in tablet formulations sold across Europe. ECHA substance evaluations periodically force reformulation cycles that raise compliance costs for exporters serving multiple jurisdictions. Stakeholders must monitor pending amendments to the EU Detergents Regulation and emerging state-level packaging laws in California and New York that could mandate refill-compatible formats.
Market Dynamics
The EU Single-Use Plastics Directive is compressing liquid soap volumes across hospitality procurement channels while elevating tablet formats to default status in European hotel amenity programs.
Growth Catalysts
- EU Single-Use Plastics Directive:Bans plastic toiletry containers in hospitality settings, directly mandating tablet adoption across German, French, and Italian hotel chains.
- Green hotel certification programs:Germany's mandatory waste-reducing guest amenity requirements are creating procurement pull through LEED-equivalent hospitality standards.
- Pharmaceutical-grade surfactant concentrates:Higher-active formulations are reducing tablet weight and shipping costs for cross-border e-commerce fulfillment.
Market Restraints
- Palm oil and coconut-derived surfactant volatility:Raw material price swings from Southeast Asian supply disruptions compress tablet manufacturer margins.
- Rotary tableting equipment concentration:German and Italian machinery suppliers control high-pressure tablet press availability, creating capex bottlenecks for new entrants.
- Humectant hygroscopicity limitations:Starch-based binders absorb atmospheric moisture, degrading shelf stability in tropical climates without moisture-barrier packaging.
Strategic Opportunities
- Antibacterial institutional procurement:Hospitals and schools in the United States are expanding tablet-based hygiene programs to reduce liquid soap spillage and inventory theft.
- Subscription direct-to-consumer channels:Refill-pouch tablet replenishment models are capturing household segments seeking plastic-free bathroom conversions.
- California and New York packaging laws:Pending state-level refill-compatible format mandates are creating regulatory tailwinds for tablet-first market entry.
Industry Challenges
- High-pressure tableting technician scarcity:Skilled operators for rotary press calibration and dissolution-rate optimization are concentrated among legacy pharmaceutical equipment specialists.
- FDA antimicrobial claim compliance timelines:Cosmetic-antibacterial boundary disputes delay product launches by 12-18 months for dual-positioned tablet formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soap Tablet Market |
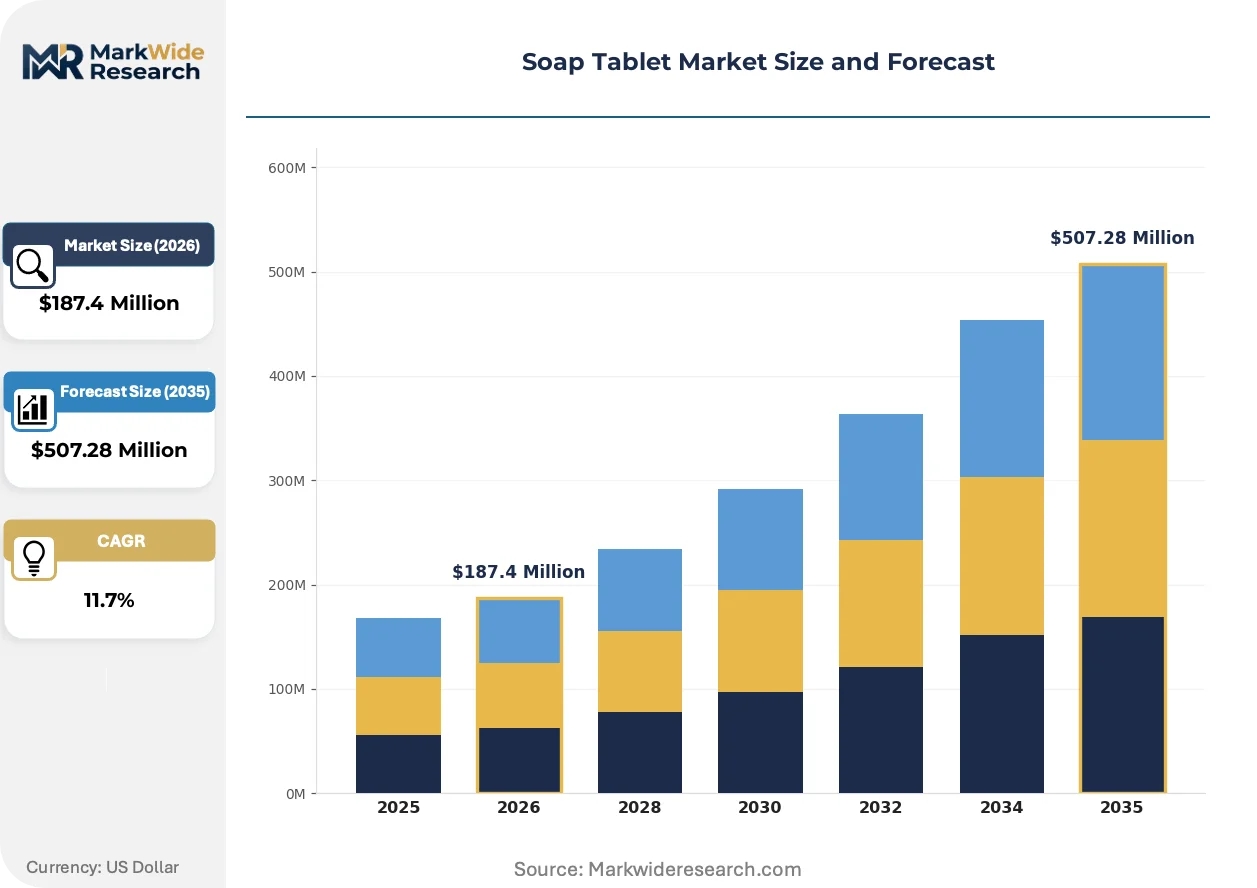
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Antibacterial, Moisturizing, Travel-sized End User: Households, Hotels, Hospitals, Schools Packaging Type: Biodegradable, Plastic, Cardboard, Bulk Distribution Channel: Online, Supermarkets, Drugstores, Specialty Stores |
| Companies Covered | Colgate-Palmolive, Blueland, Orial Imara, reuuse, Tirtyl Trading, Cleancult, Meliora Cleaning Products, Reckitt Benckiser, Nivea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soap Tablet Market Evolving Landscape
Tablet manufacturing is splitting between pharmaceutical-precision equipment and simplified food-grade presses as end-use requirements diverge across hospitality and household segments.
Cold-process surfactant concentration technology is bifurcating tablet production economics. High-active concentrate formulations enable smaller tablet dimensions for travel retail adoption. Luxury hotel chains are specifying 40% active-content tablets for single-use amenity applications. This concentration gradient is compressing commodity tablet margins while expanding premium positioning headroom.
REACH substance evaluations are forcing preservative system reformulations across European tablet exports. ECHA restrictions on isothiazolinone biocides are eliminating established antimicrobial tablet chemistries from cross-border commerce. German manufacturers are responding with phenoxyethanol-based alternatives certified for EU Detergents Regulation compliance.
Hotel procurement departments are consolidating supplier relationships around full-amenity tablet portfolios. Single-vendor contracts for soap, shampoo, and conditioner tablets are displacing fragmented liquid amenity purchasing. This concentration is most visible in Nordic hospitality chains pursuing zero-waste certification under national green building standards.
Soap Tablet Market Segmentation
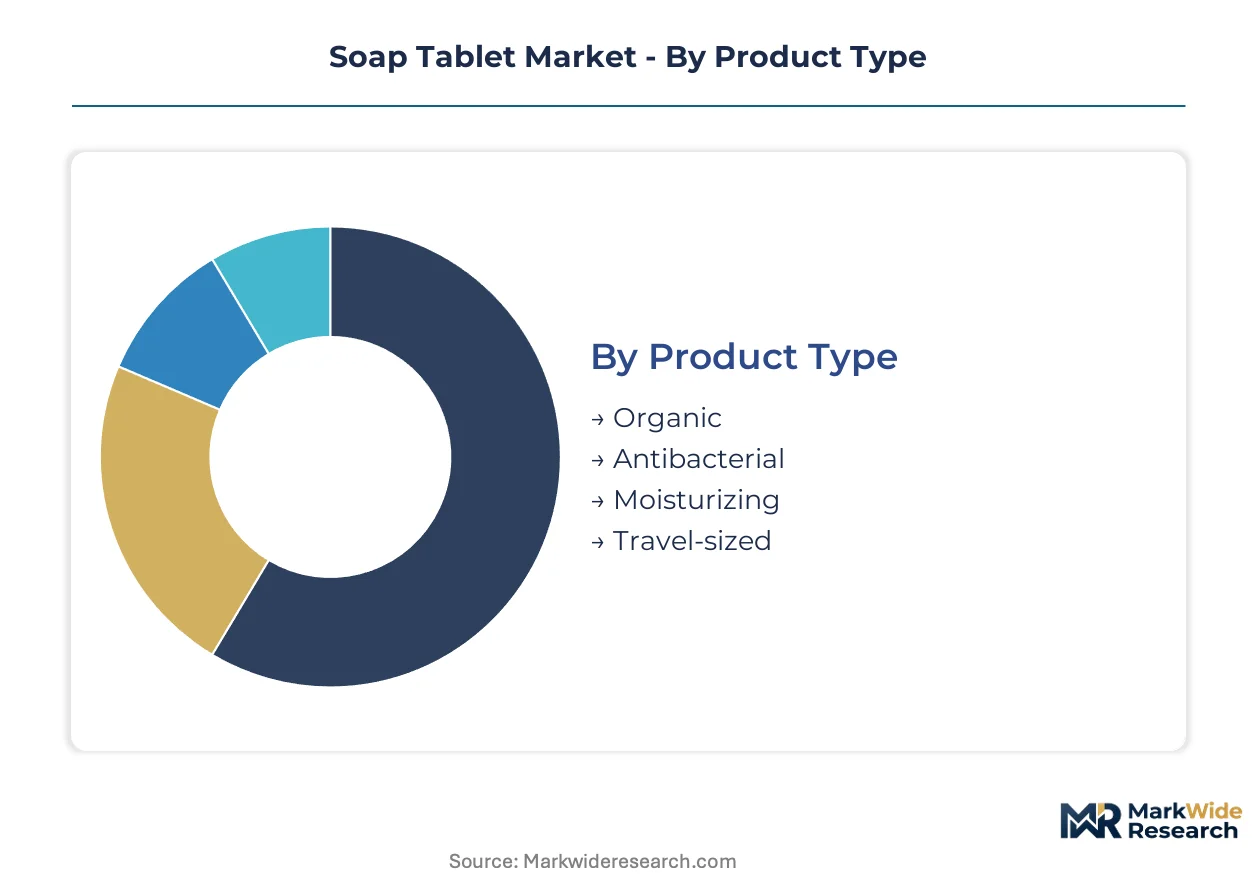
Soap tablet manufacturers navigate divergent margin pools across hospitality procurement and household retail channels. Channel-specific formulation requirements create segmentation fault lines between institutional bulk contracts and direct-to-consumer premium positioning.
Product Type:
Organic and antibacterial variants flow through divergent channel architectures, with organic commanding specialty retail premiums and antibacterial dominating institutional procurement through distributor networks.
- Organic:Formulations exclude synthetic surfactants and petrochemical preservatives, carrying third-party certifications that unlock placement in natural-product specialty stores and green hotel amenity programs. German hospitality chains pursuing zero-waste certification mandate organic tablet portfolios for guest room placement.
- Antibacterial:Incorporate phenoxyethanol or alternative biocide systems replacing restricted isothiazolinones under ECHA evaluations. Hospital procurement departments in the United States specify antibacterial tablets for patient hygiene stations to reduce liquid soap spillage and inventory shrinkage.
- Moisturizing:Blend humectant-rich binders targeting dry-skin household segments through drugstore and supermarket placement.
- Travel-sized:Compressed to sub-5 gram dimensions for airline amenity kits and boutique hotel single-use applications.
Antibacterial dominates installed base through institutional volume contracts. Organic is where expansion concentrates as green building certifications proliferate across European hospitality.
End User:
Customer-type segmentation maps directly to order-size economics and formulation specification intensity, with hospitals demanding antimicrobial compliance documentation that household channels rarely require.
- Households:Subscription replenishment models and supermarket impulse purchases drive volume, with consumers prioritizing scent profiles and plastic-free packaging credentials over surfactant concentration specifications.
- Hotels:Procurement departments consolidate around full-amenity tablet portfolios covering soap, shampoo, and conditioner, displacing fragmented liquid supplier relationships. Nordic chains pursuing national green building standards mandate tablet-only guest room configurations.
- Hospitals:Infection control protocols specify antibacterial tablets with documented kill-rate testing, creating documentation burdens that filter supplier pools to pharmaceutical-grade manufacturers.
- Schools:Budget-constrained institutional buyers favor bulk cardboard packaging over unitized formats, prioritizing cost-per-use metrics above environmental positioning.
Hotels anchor current procurement volume through chain-wide amenity standardization. Households are gaining share fastest as direct-to-consumer subscription mechanics scale.
Packaging Type:
Packaging segmentation reflects regulatory pressure gradients, with biodegradable formats capturing hospitality mandates while bulk packaging serves price-sensitive institutional segments.
- Biodegradable:Cellulose-derived films and molded fiber trays satisfy EU Single-Use Plastics Directive requirements for German and French hotel chains. These formats carry 15-25% packaging cost premiums that compress margins unless offset by volume commitments.
- Plastic:Shrink-wrapped polyethylene remains prevalent in tropical markets where moisture-barrier properties override sustainability positioning, though regulatory pressure is narrowing permissible applications.
- Cardboard:Recyclable paperboard cartons dominate supermarket and drugstore shelf placement for household segments.
- Bulk:Unpackaged tablets in corrugated master cases serve school district and hospital central supply operations.
Biodegradable formats dominate new hospitality procurement specifications. Bulk packaging retains institutional installed base through total-cost optimization.
Distribution Channel:
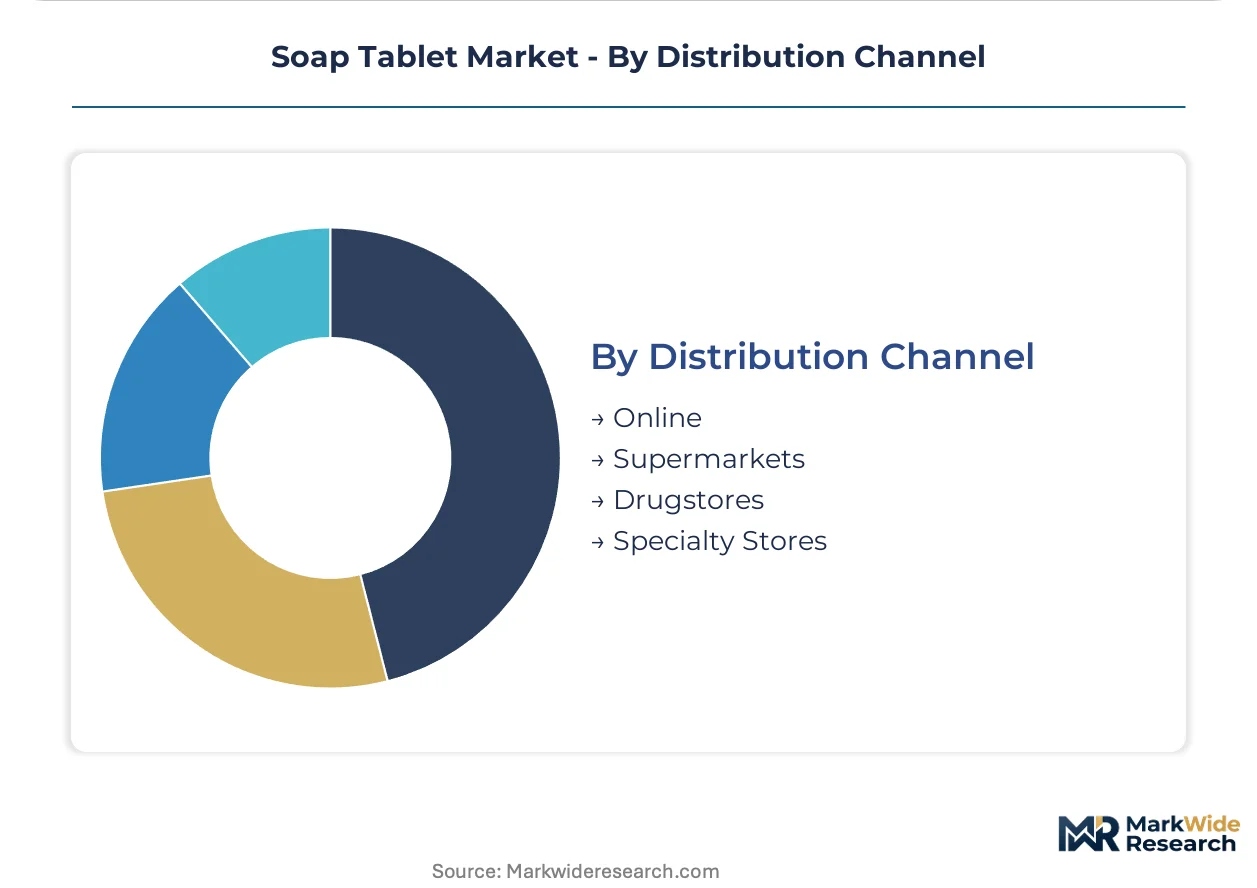
Channel segmentation stratifies by replenishment urgency and discovery mode, with online subscription models capturing planned conversions and supermarkets retaining emergency replenishment traffic.
- Online:Direct-to-consumer subscription mechanics with refill-pouch replenishment capture plastic-free bathroom conversion segments. Blueland and comparable operators anchor customer lifetime value through automated reorder algorithms.
- Supermarkets:Mass retail placement drives impulse trial and emergency replenishment for household segments prioritizing immediate availability over environmental credentials.
- Drugstores:Pharmacy chains stock moisturizing and antibacterial variants targeting health-conscious consumers and travel preparation purchases.
- Specialty Stores:Natural-product retailers and zero-waste shops carry organic-certified tablets with premium positioning supported by staff education and sampling programs.
Supermarkets retain the broadest household reach. Online channels are climbing the fastest as subscription mechanics reduce customer acquisition costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tablet press manufacturing clusters in Germany and Italy dominate equipment supply chains, while hospitality procurement mandates in Northern Europe accelerate format adoption. Regulatory pressure gradients vary sharply across jurisdictions, creating divergent market entry timelines.
Germany
Green hotel certification programs mandate waste-reducing guest amenities across Bavaria and North Rhine-Westphalia. The EU Single-Use Plastics Directive bans plastic toiletry containers in hospitality settings, elevating tablet formats to default status. Stuttgart-area machinery suppliers control high-pressure rotary press availability, constraining new entrant capacity expansion.
United States
Hospital procurement departments specify antibacterial tablets for patient hygiene stations to reduce liquid soap spillage and inventory shrinkage. FDA oversight of cosmetic labeling and antimicrobial claims shapes product positioning timelines. California and New York pending state-level packaging laws mandate refill-compatible formats, creating regulatory tailwinds for tablet-first market entry.
France
Paris-based hospitality chains consolidate supplier relationships around full-amenity tablet portfolios covering soap, shampoo, and conditioner. ECHA substance evaluations force preservative system reformulations across European tablet exports. Île-de-France procurement departments specify biodegradable cellulose-derived packaging formats satisfying EU directive requirements.
United Kingdom
London hotel groups pursue zero-waste certification under national green building standards, mandating tablet-only guest room configurations. The UK Environment Agency enforces packaging waste regulations that elevate refill-pouch subscription mechanics. Midlands-based contract manufacturers serve cross-border e-commerce fulfillment for household segments.
India
Budget-constrained school districts favor bulk cardboard packaging over unitized formats, prioritizing cost-per-use metrics. BIS standards govern surfactant chemical safety in domestic tablet formulations. Maharashtra and Gujarat industrial clusters concentrate starch-based binder production for regional tablet manufacturers serving tropical climate packaging requirements.
Soap Tablet Market Competitive Landscape
Concentration sits with multinational consumer goods conglomerates anchoring mass retail shelf presence through manufacturing scale and integrated personal care facilities. Mid-scale direct-to-consumer specialists capture subscription-driven household segments with plastic-free positioning. The competitive terrain splits between pharmaceutical-grade precision manufacturers and simplified food-grade press operators. Dominant moves include portfolio diversification into full-amenity tablet suites and geographic expansion through hospitality chain standardization contracts.
Among subscription-model specialists, Blueland exemplifies the direct-to-consumer archetype with automated reorder algorithms. Reckitt Benckiser occupies a position within the mass retail drugstore partnership tier. Colgate-Palmolive represents the manufacturing-scale conglomerate archetype with integrated production facilities feeding tablet lines. These three anchors illustrate the tripartite competitive structure spanning precision manufacturing, mass distribution, and digital-native subscription mechanics.
| Leading Market Players |
|---|
| Colgate-Palmolive |
| Blueland |
| Orial Imara |
| reuuse |
| Tirtyl Trading |
| Cleancult |
| Meliora Cleaning Products |
| Reckitt Benckiser |
| Nivea |
| Others |
Value Network & Pricing Analysis
Sixty-day raw material inventory cycles among German tablet press operators compress working capital flexibility while amplifying pricing leverage over downstream formulation houses. This lead-time concentration reinforces cost pass-through mechanics when palm oil and coconut-derived surfactants spike, and it concentrates procurement power among hospitality chains consolidating around full-amenity tablet portfolios.
Pricing Analysis
The EU Single-Use Plastics Directive dictates the pricing tier structure across European hospitality procurement, mandating biodegradable packaging formats that carry 15-25% cost premiums over conventional alternatives. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade precision manufacturers from food-grade press operators and commodity importers. Price differentiation centers on certification grade and volume scale, with organic-certified tablets commanding specialty retail premiums while antibacterial formats compete on contract-based long-term offtake to institutional buyers. Pricing pressure stems from raw material volatility in Southeast Asian surfactant supply chains, compressing margins for mid-scale operators lacking backward integration into active concentrate production. School districts exhibit highest price sensitivity, prioritizing cost-per-use metrics above environmental positioning, whereas luxury hotel chains demonstrate lowest sensitivity as green certification mandates override procurement cost concerns.
Supply Chain Analysis
Strategic stockpile preferences dominate among German and Italian machinery suppliers controlling high-pressure rotary press availability, while just-in-time inventory management prevails among downstream formulation houses serving volatile household retail demand. Geographic supply concentration centers on Germany and Italy for precision tableting equipment, India for starch-based binder production, and Southeast Asia for palm oil and coconut-derived surfactant feedstocks. Raw material dependencies draw from pharmaceutical-grade surfactant concentrates, starch or talc filler binders, and phenoxyethanol preservative systems replacing restricted isothiazolinones. Supply chain risk hinges on single-source vulnerability for high-pressure tableting technician expertise concentrated among legacy pharmaceutical equipment specialists. Distribution runs through direct-to-consumer subscription mechanics for household segments, consolidated full-amenity contracts for hospitality chains, and distributor networks for institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospitality procurement department consolidation around single-vendor tablet portfolios, fragmenting supplier negotiating leverage as Nordic chains and German hotel groups mandate zero-waste amenity configurations.
For Market Incumbents: Secure full-amenity tablet portfolio contracts with green-certified hotel chains before competitor capacity expansion in Stuttgart-area machinery clusters. Defend margin position through backward integration into pharmaceutical-grade surfactant concentrate production, reducing exposure to Southeast Asian raw material volatility. Channel control represents the critical lever, as supermarket and drugstore shelf presence sustains household segment visibility against direct-to-consumer subscription entrants. For New Entrants and Emerging Players: EU organic certification fast-tracks unlock placement in German hospitality chains pursuing mandatory waste-reducing guest amenity requirements. White-space targets include budget-constrained school districts in India favoring bulk cardboard packaging, and California households anticipating state-level refill-compatible format mandates. A direct-to-consumer launch with automated reorder algorithms captures plastic-free bathroom conversion segments before incumbent conglomerates replicate subscription mechanics. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational consumer goods conglomerates seeking to divest non-core personal care tablet operations amid portfolio rationalization. Long-term viability favors precision manufacturers with pharmaceutical-grade equipment access and established ECHA compliance documentation, over commodity operators exposed to REACH reformulation cycles. Monitor ECHA substance evaluation timelines as the inflection indicator; accelerated isothiazolinone restrictions would trigger consolidation among preservative-dependent formulation houses lacking phenoxyethanol alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Concentrates | Captures margin pool from pharmaceutical-grade active suppliers while insulating against Southeast Asian supply disruptions. |
| Full-Amenity Portfolio Consolidation | Positions single-vendor contractors to displace fragmented liquid amenity purchasing across Nordic hospitality chains. |
| Direct-to-Consumer Subscription Launch | Blueland-type automated reorder algorithms reduce customer acquisition costs in plastic-free household conversion segments. |
| ECHA-Compliant Preservative Reformulation | Phenoxyethanol certification maintains EU Detergents Regulation access as isothiazolinone restrictions eliminate incumbent chemistries. |
| Biodegradable Packaging Scale-Up | Cellulose-derived film capacity captures German and French hotel procurement mandates under EU Single-Use Plastics Directive. |
Research Methodology
A standing panel of hotel procurement directors, pharmaceutical manufacturing engineers, surfactant supply planners, and ECHA regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from EU Detergents Regulation amendment trackers, REACH substance evaluation databases, FDA cosmetic labeling guidance documents, and hospitality green certification program standards. Bottom-up tablet production capacity modeling triangulated against top-down hospitality amenity spend allocation estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type tier, end-user category, packaging format compliance grade, and distribution channel architecture. CAGRs were derived from installed base growth rates adjusted for regulatory mandate acceleration curves and e-commerce penetration trajectories. Industry-specific forecast inputs incorporated rotary tableting equipment lead times and surfactant concentrate purity upgrade cycles.
Decision-makers should treat outputs as directional under stable EU regulatory enforcement and intact Southeast Asian surfactant supply assumptions; material deviation would warrant model refresh. Specific risk factors include pending California and New York packaging law implementations, ECHA accelerated biocide restriction timelines, and tropical climate moisture-barrier packaging cost spikes. Revision becomes warranted when hospitality procurement consolidation velocity crosses thresholds that alter supplier negotiation leverage.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Leaf Blower Market
Household Items
Europe & UK Nonstick Cookware Market
Household Items
Hands-Free Faucet Market
Household Items
Heated Mattress Pads Market
Household Items
Drain Cleaners Market
Household Items
Electric Brooms Market
Household Items
Global Disposable Toilet Seat Covers Market
Household Items
Fan Market
Household Items
Enameled Cookware Market
Household Items
Germany Induction Hobs Market
Household Items
Latex Mattress Market
Household Items
Ceramic Travel Mug Market
Household Items
Turkey Cookware Market
Household Items
North America Ceramic Barbeque Grill Market
Household Items
Smart Shower Market
Household Items
Air Mattress Market