
 Robot Vacuum Cleaners Market | 2026-2036
Robot Vacuum Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
Robot Vacuum Cleaners Market Analytics
LiDAR sensors is rebalancing cost structures across the robot vacuum category as solid-state designs replace bulkier mechanical scanning units. iRobot Corporation leverages its established brand strength and extensive service network to sustain consumer loyalty in North America. Roborock Technology anchors its competitive stance through deep manufacturing integration in Shenzhen, while Ecovacs Robotics differentiates via its AI-driven obstacle-recognition platform and aggressive expansion into European retail channels.
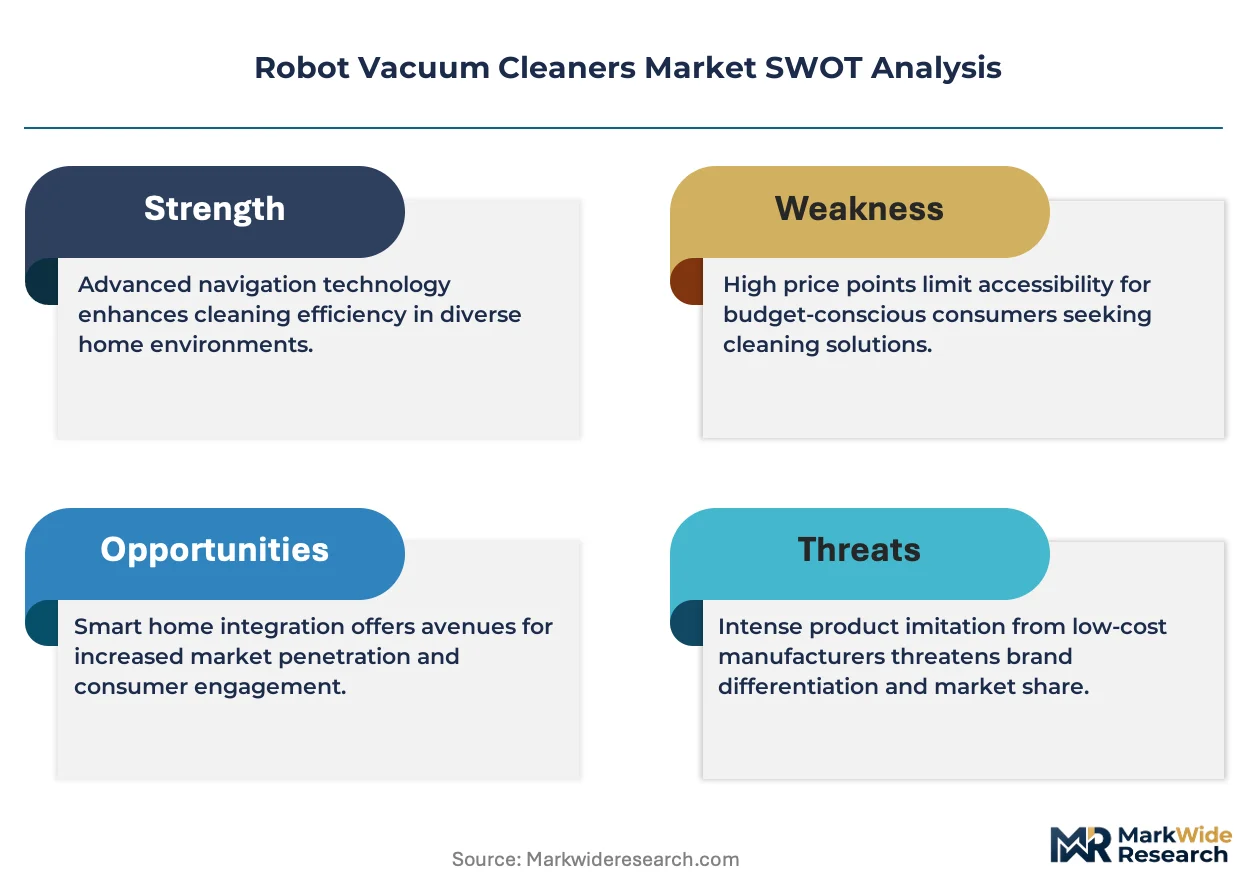
A robot vacuum cleaner constitutes an autonomous mobile robot equipped with suction mechanisms, debris collection chambers, navigation sensors, and rechargeable battery systems, designed to traverse floor surfaces without human intervention for routine cleaning operations. These devices typically incorporate HEPA filtration, cliff-detection sensors, and docking stations for automated recharging, serving residential and commercial environments where labor reduction and consistent sanitation schedules represent operational priorities. Lidar-based mapping systems command the premium technology tier due to superior spatial accuracy and multi-floor memory capabilities, while the residential end-user segment absorbs the dominant volume share as dual-income households prioritize time-saving domestic automation. The economy price tier remains structurally crowded with white-label alternatives, compressing margins for non-differentiated entrants.
FCC certification requirements govern wireless connectivity modules in US-bound units, while CE marking under the EU Machinery Directive and RoHS substance restrictions shape European market access and material composition standards. China's GB standards and MIIT radio-transmission regulations impose additional compliance layers for products manufactured and sold domestically. Stakeholders must weigh the capital intensity of LiDAR miniaturization against the margin erosion from economy-tier competition as they calibrate portfolio positioning across technology and price tiers.
Market Dynamics
LiDAR miniaturization is compressing premium-tier pricing while simultaneously elevating baseline performance expectations across all buyer segments, forcing incumbents to recalibrate R&D roadmaps and margin structures simultaneously.
Growth Catalysts
- Smart Home Integration Mandates:Residential developers in China now bundle robot vacuums with new construction under MIIT IoT interoperability standards, normalizing automated cleaning as standard household infrastructure.
- Dual-Income Household Density:Time-scarce professional couples in South Korea and Japan prioritize domestic labor substitution, creating sustained replacement-cycle demand for navigation-upgraded units.
- RoHS Material Compliance:European REACH substance restrictions accelerate lead-free solder and recyclable chassis adoption, indirectly improving product longevity and brand positioning.
Market Restraints
- Lithium-Ion Cell Volatility:Battery pack costs fluctuate with cobalt and nickel spot markets, squeezing assembly margins for mid-tier manufacturers lacking long-term supply agreements.
- Shenzhen Supply Concentration:Over 70% of LIDAR module fabrication clusters in Guangdong province expose brands to single-region disruption risks from power rationing or logistics congestion.
- Obstacle Recognition Limitations:Current AI vision systems misclassify low-contrast objects at sub-5% ambient light, constraining reliable operation in unlit commercial environments.
Strategic Opportunities
- India Urban Penetration:Tier-2 city apartment complexes remain undersupplied with automated cleaning, presenting first-mover advantage for brands adapting to BIS voltage and dust-load specifications.
- EU Green Deal Subsidies:Energy-efficient appliance rebates in Germany and France partially offset premium pricing for low-consumption brushless motor designs.
- Voice-Assistant Convergence:Integration with Alexa and Google Home ecosystems creates switching costs that lock households into compatible hardware families.
Industry Challenges
- FCC Certification Timelines:Wi-Fi 6E module approvals for US-bound units extend lead times by 8-14 weeks, compressing seasonal launch windows.
- Embedded Software Talent Scarcity:Simultaneous localization and mapping (SLAM) algorithm expertise concentrates among Shenzhen and Boston metro hiring pools, inflating compensation for experienced robotics engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robot Vacuum Cleaners Market |
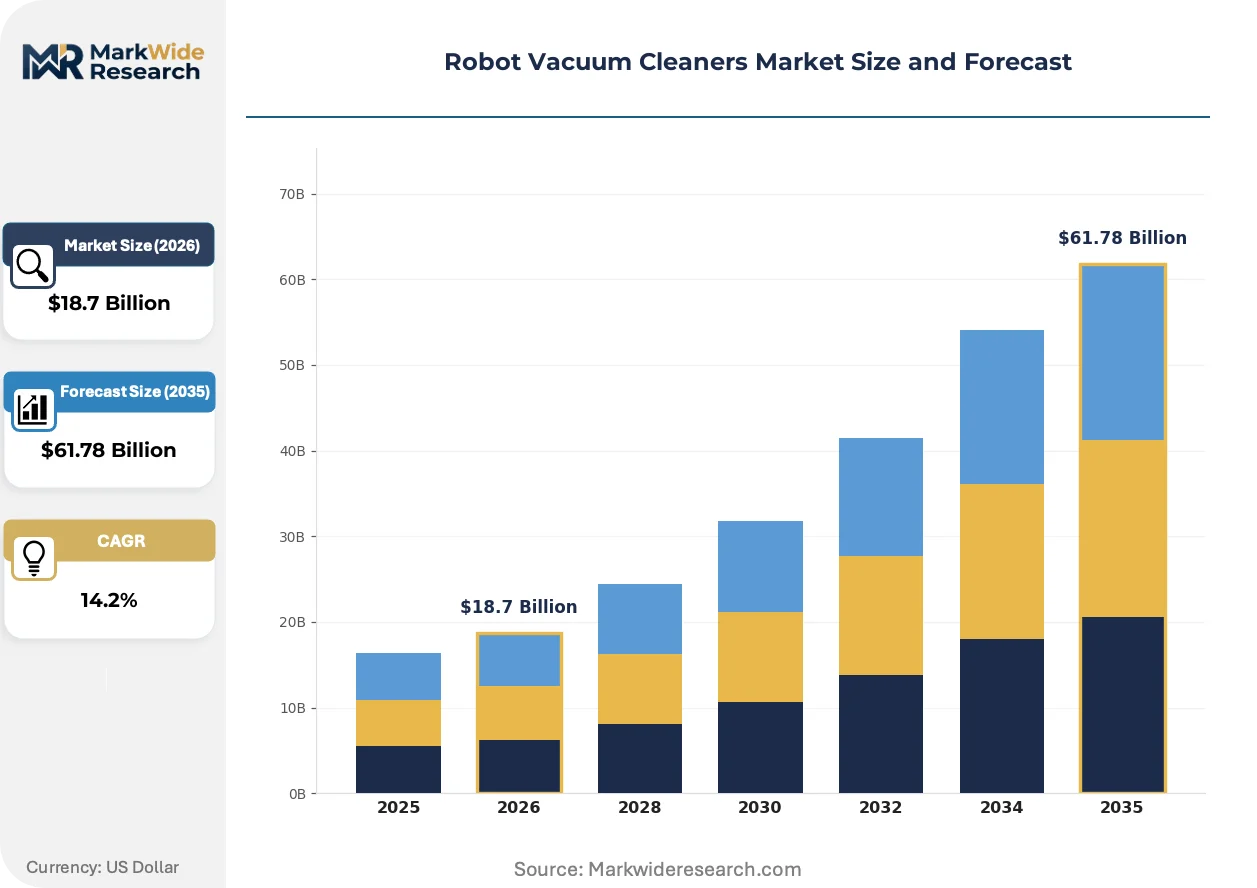
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart, Autonomous, Robotic, App-Controlled Technology: Lidar, Infrared, Ultrasonic, Gyro End User: Residential, Commercial, Industrial, Hospitality Price Tier: Economy, Mid-Range, Premium, Luxury |
| Companies Covered | iRobot Corporation, Ecovacs Robotics, Roborock Technology, SharkNinja, Dyson, Samsung Electronics, LG Electronics, Xiaomi Corporation, Neato Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robot Vacuum Cleaners Market Evolving Landscape
Navigation hardware and power electronics are undergoing simultaneous generational transitions that redefine competitive differentiation beyond suction specifications alone.
Solid-state LiDAR arrays are overtaking mechanical spinning units as the dominant spatial mapping technology in flagship product lines. Premium residential buyers now expect sub-2cm positional accuracy and multi-floor map retention as baseline features. This shift is compressing development timelines for camera-only navigation systems and elevating hardware BOM thresholds industry-wide.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are pressuring manufacturers to eliminate refrigerant-based cooling in high-power charging docks. Industrial designers must now accommodate passive thermal management or liquid-cooled alternatives without expanding footprint dimensions. German and French retail channels are prioritizing climate-neutral certification labels in their 2024-2025 assortment planning.
Direct-to-consumer subscription models for consumable replenishment are displacing traditional retail attachment sales in North American and Western European markets. Buyers increasingly prefer automated filter and brush shipments triggered by usage telemetry rather than manual reordering. This behavioral pivot concentrates lifetime value capture with brands possessing integrated cloud infrastructure and captive e-commerce fulfillment capabilities.
Robot Vacuum Cleaners Market Segmentation
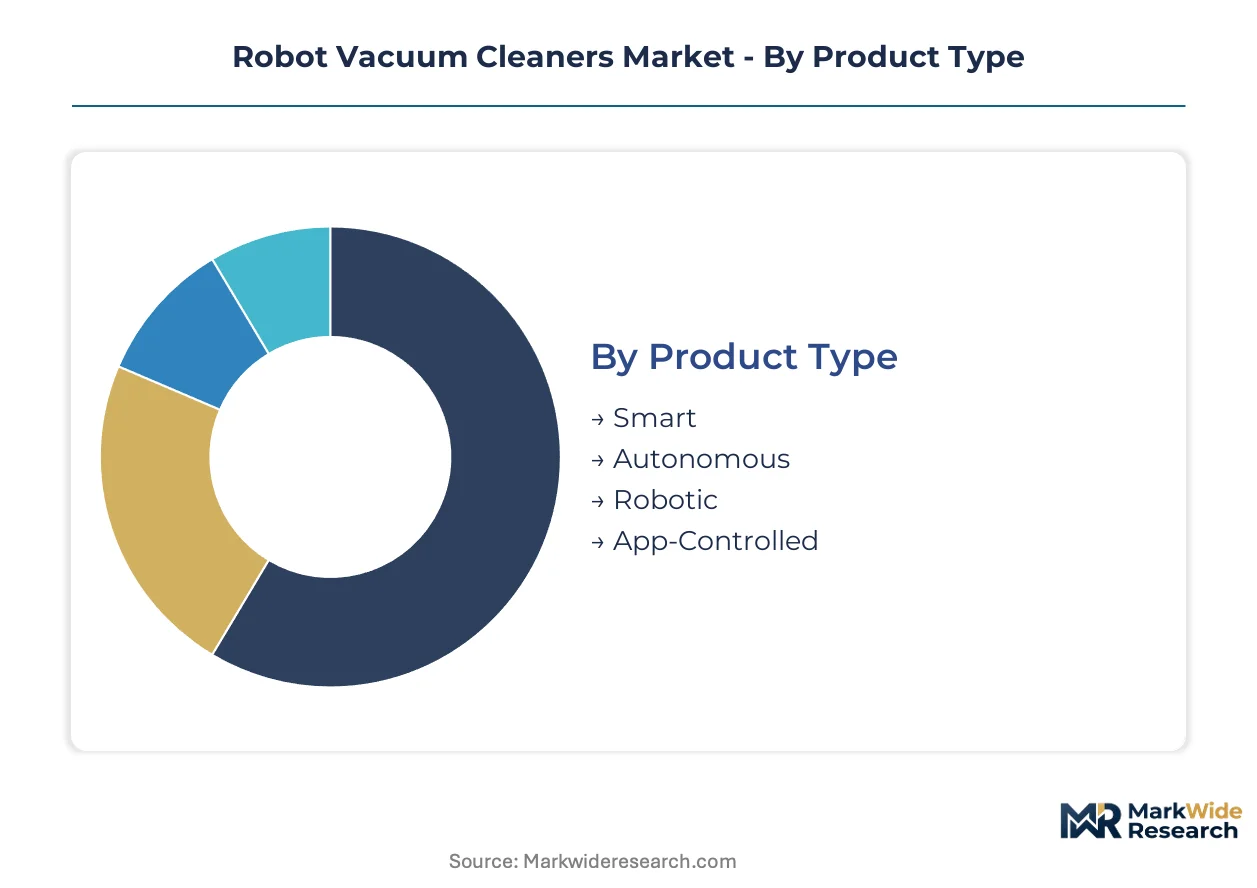
Robot vacuum segmentation reflects divergent technical requirements across buyer sophistication levels and operating environments. Manufacturers calibrate sensor arrays, battery capacities, and software stacks to match specific use-case intensity rather than pursuing universal designs.
Product Type:
Supply concentration for core navigation chipsets and motor assemblies favors integrated platform approaches over discrete component sourcing.
- Smart:Units incorporate Wi-Fi connectivity, mobile app interfaces, and cloud-based mapping storage. Demand concentrates in suburban North American households where Alexa and Google Home ecosystems dominate smart home penetration.
- Autonomous:Self-directed operation with minimal user intervention requires advanced SLAM algorithms and obstacle-recognition neural networks. German and French buyers prioritize these capabilities for multi-room cleaning schedules in dual-income professional households.
- Robotic:Hardware emphasizes mechanical durability and standardized replacement parts for commercial deployment cycles.
- App-Controlled:Interface-driven command structures appeal to tech-forward demographics in South Korea and Japan seeking granular cleaning zone customization.
Autonomous units absorb the bulk of installed capacity; Smart configurations are expanding most quickly through retail bundling with smart home ecosystems.
Technology:
Cost tier differentiation in navigation hardware now separates premium positioning from economy alternatives more sharply than suction power metrics.
- Lidar:Solid-state laser arrays deliver sub-2cm positional accuracy and multi-floor map retention. Shenzhen manufacturing clusters for these modules command 70% of global supply, creating sourcing leverage for vertically integrated brands.
- Infrared:Proximity-based detection systems dominate economy-tier production with simpler BOM requirements and faster FCC certification timelines.
- Ultrasonic:High-frequency sound mapping supplements camera systems in low-light commercial environments.
- Gyro:Inertial measurement units provide dead-reckoning backup for hybrid navigation architectures in mid-range product lines.
Lidar-equipped units absorb the bulk of installed capacity; solid-state variants are gaining share fastest as mechanical scanning designs phase out.
End User:
Application intensity drives divergence in battery specifications, chassis durability ratings, and service contract structures.
- Residential:Dual-income households in China and South Korea prioritize time-saving automation with quiet-operation modes for apartment living. MIIT IoT interoperability standards now normalize bundled installation in new Chinese construction.
- Commercial:Office cleaning contractors require extended runtime batteries and centralized fleet management dashboards for multi-unit deployment.
- Industrial:Heavy-debris environments demand reinforced suction pathways and HEPA filtration for particulate-heavy manufacturing floors.
- Hospitality:Hotel chains in Dubai and Singapore specify low-noise profiles and rapid recharge docks for between-guest turnaround schedules.
Residential deployments absorb the bulk of installed capacity; Commercial segment applications are climbing the fastest as facility management outsourcing accelerates.
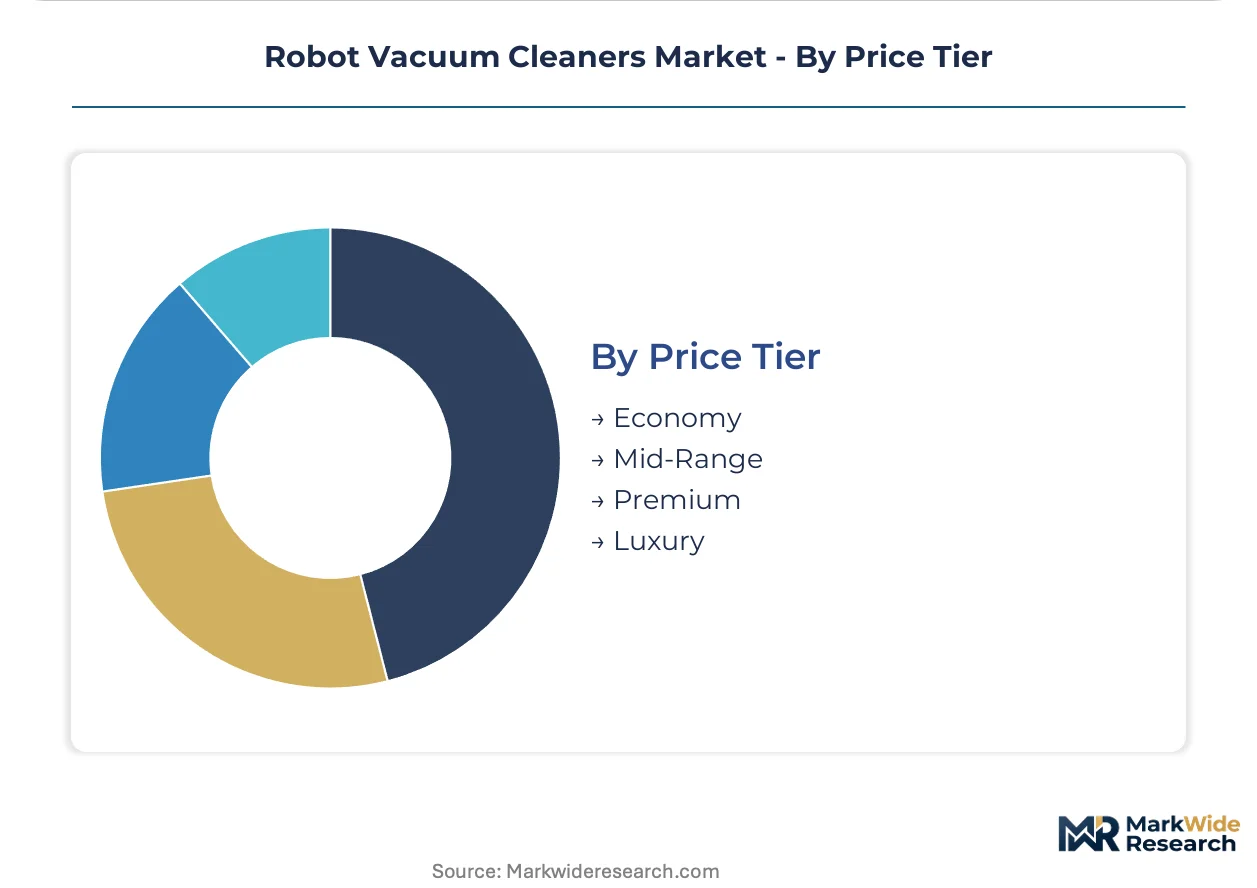
Price Tier:
Margin structures stratify sharply between captive component supply and outsourced assembly models.
- Economy:White-label alternatives from Shenzhen assemblers compress differentiation space for non-integrated entrants. Indian Tier-2 city distributors prioritize these units for first-time automation buyers under BIS voltage compliance requirements.
- Mid-Range:Hybrid navigation combining gyroscopic dead-reckoning with basic camera targeting captures replacement-cycle demand from infrared legacy owners.
- Premium:Solid-state LiDAR and AI obstacle recognition anchor positioning for brands with cloud infrastructure and consumable subscription capabilities.
- Luxury:Design-forward aesthetics and concierge service tiers target high-net-worth households in London, Tokyo, and Manhattan with bespoke finish options.
Economy units absorb the bulk of installed capacity; Premium tier positioning is expanding most quickly through subscription-model lifetime value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the dominant share of robot vacuum demand, with Shenzhen manufacturing clusters supplying over 70% of global LiDAR module volume. Dual-income households in South Korea and Japan sustain replacement-cycle intensity, while European buyers prioritize energy-efficient certification under EU Green Deal frameworks.
China
Residential developers bundle robot vacuums with new construction under MIIT IoT interoperability standards, normalizing automated cleaning as standard household infrastructure. GB standards and MIIT radio-transmission regulations impose compliance layers for domestically manufactured units. Shenzhen's Pearl River Delta anchors LiDAR fabrication, with solid-state array production scaling rapidly as mechanical scanning designs phase out.
United States
Suburban households with Alexa and Google Home ecosystems drive smart-configuration demand through retail bundling partnerships. FCC certification requirements govern wireless connectivity modules, extending lead times by 8-14 weeks for Wi-Fi 6E approvals. Boston metro hiring pools concentrate SLAM algorithm expertise, inflating compensation for experienced robotics engineers.
Germany
Dual-income professional households prioritize autonomous units with multi-room cleaning schedules and low-noise profiles. EU F-Gas Regulation restrictions eliminate refrigerant-based cooling in charging docks, forcing passive thermal management redesigns. German retail channels prioritize climate-neutral certification labels in 2024-2025 assortment planning.
South Korea
Time-scarce professional couples in Seoul Capital Area prioritize domestic labor substitution, creating sustained replacement-cycle demand. MFDS and national radio regulations shape product certification for domestic sale. Busan-Ulsan manufacturing corridors support component assembly for brands targeting premium-tier positioning with app-controlled zone customization.
India
Tier-2 city apartment complexes remain undersupplied with automated cleaning, presenting first-mover opportunity for BIS voltage-compliant designs. BIS certification requirements and dust-load specifications differentiate products for local operating conditions. Maharashtra and Karnataka distribution hubs prioritize economy-tier units for first-time automation buyers.
Robot Vacuum Cleaners Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium-tier positioning concentrating among integrated platform owners while economy-tier volume flows through Shenzhen assemblers. The vendor base organizes around three strategic archetypes: vertically integrated hardware-software platforms, component-specialist OEMs, and ecosystem-anchored consumer electronics giants. Capacity expansion and strategic partnerships dominate competitive moves, with brands securing captive LiDAR supply and cloud infrastructure partnerships.
Within the integrated platform tier, iRobot Corporation and Ecovacs Robotics exemplify archetypes combining brand strength with service network density. Roborock Technology occupies a position among Shenzhen-anchored manufacturers leveraging deep manufacturing integration. These three entities represent divergent approaches to navigating LiDAR miniaturization cost pressures and subscription-model lifetime value capture.
| Leading Market Players |
|---|
| iRobot Corporation |
| Ecovacs Robotics |
| Roborock Technology |
| SharkNinja |
| Dyson |
| Samsung Electronics |
| LG Electronics |
| Xiaomi Corporation |
| Neato Robotics |
| Others |
Value Network & Pricing Analysis
Premium residential households concentrated in North American suburbs and Chinese tier-1 cities anchor the dominant subscription-plus-hardware pricing model, with recurring consumable revenue streams offsetting compressed upfront margins on LiDAR-equipped units.
Pricing Analysis
Volume concentrates in economy-tier white-label units while margins concentrate in premium solid-state LiDAR configurations. Price differentiation rests on navigation chipset certification tiers and captive cloud infrastructure ownership. Pricing pressure stems from Shenzhen assembly cost compression and cobalt-nickel battery volatility. First-time automation buyers in Indian Tier-2 cities exhibit highest price sensitivity; luxury-tier households in Tokyo and Manhattan show lowest.
Supply Chain Analysis
Reverse-logistics flows for LiDAR module refurbishment and battery pack remanufacturing concentrate in Shenzhen and Dongguan facilities serving warranty-extension programs. Component sourcing draws from Chinese solid-state laser arrays, South Korean battery cells, and Japanese motor assemblies. Single-region vulnerability in Guangdong province exposes brands to power-rationing disruption. Distribution runs through direct-to-consumer channels in North America and electronics retail chains in Germany and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FCC certification timelines and EU F-Gas Regulation restrictions erect barrier-to-entry moats favoring incumbents with established regulatory affairs infrastructure and captive testing facilities.
For Market Incumbents: Deepen backward integration into solid-state LiDAR fabrication to defend against margin erosion from Shenzhen white-label competition. Prioritize MIIT IoT interoperability certification investment to secure Chinese new-construction bundling relationships. Channel control through direct-to-consumer subscription platforms represents the critical retention lever against ecosystem-anchored entrants. For New Entrants and Emerging Players: Capture undersupplied Tier-2 Indian apartment complexes through BIS voltage-compliant economy-tier designs with dust-load optimization for local operating conditions. Voice-assistant ecosystem partnerships with Alexa and Google Home create the most penetrable go-to-market angle for smart-configuration market entry. For Investors and Strategic Acquirers: The window for entry favors vertically integrated platform owners with captive LiDAR supply and cloud infrastructure over pure-brand assemblers. Long-term viability hinges on subscription-model lifetime value capture rather than transactional hardware margins. Monitor solid-state LiDAR cost curves and EU Green Deal subsidy program expansions as inflection indicators for premium-tier acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| LiDAR Supply Integration | Captive solid-state array production insulates margins from Shenzhen module price volatility. |
| Subscription Model Launch | Automated consumable replenishment locks households into recurring revenue streams. |
| EU F-Gas Compliance Redesign | Passive thermal management in charging docks unlocks German and French retail placement. |
| Voice-Assistant Platform Partnership | Alexa and Google Home integration creates switching costs that reduce churn. |
| India Tier-2 Distribution Buildout | BIS-certified economy-tier units address first-time automation demand in undersupplied cities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with robotics engineering directors, smart home platform integration leads, electronics retail category buyers, and aftermarket service heads combined with FCC equipment authorization databases, MIIT radio-transmission filings, EU CE marking registries, and Shenzhen customs export records. Bottom-up unit shipment modeling and top-down consumer expenditure triangulation validated segmentation outputs.
Granularity-level modeling deployed technology tiers, price-band configurations, end-use intensity profiles, and regional regulatory clusters as core dimensions across the projection horizon. CAGRs derived from fitted adoption curves and replacement-cycle frequency analysis. SLAM algorithm talent concentration indices and lithium-ion cell spot price trajectories informed cost-structure assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state LiDAR cost reduction velocity and EU Green Deal subsidy program durability. Forecasts reflect documented assumptions about smart home penetration rates and MIIT bundling mandate enforcement. Practitioners should monitor cobalt-nickel price volatility and FCC certification backlog durations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Dosage Spoon Market
Household Items
Robot Mops Market
Household Items
Smart Connected Water Purifier Market
Household Items
Asia-Pacific Air Purifier Market
Household Items
Aquarium Hydrometers Market
Household Items
Snow Blower Market
Household Items
Knife Set Market
Household Items
Smart Air Purifier Market
Household Items
Portable Air Humidifier and Dehumidifier Market
Household Items
Wax Removal Aids Market
Household Items
Asia-Pacific Digital Showers Market
Household Items
Drain Cleaners Market
Household Items
Steam Cleaners Market
Household Items
Robotic Pool Cleaner Market
Household Items
Dishwashing Products Market
Household Items
Electric Soap Dispenser Market