
 Air Purifier Market | 2026-2036
Air Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
Air Purifier Market Analysis
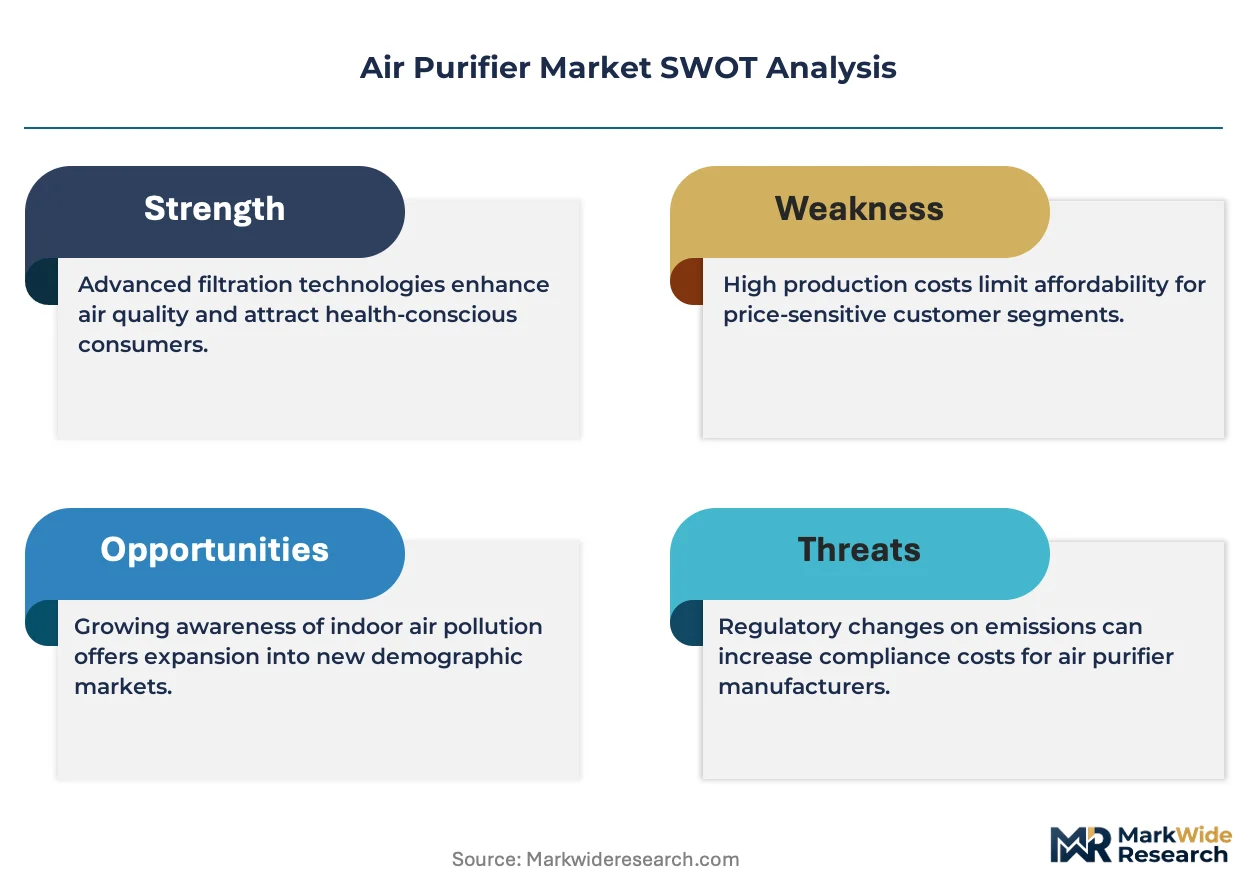
The air purifier category is shifting along a widening performance gap between medical-grade HEPA systems and basic ionizer models sold through mass retail. Daikin Industries leverages its HVAC integration expertise to bundle climate control with filtration in commercial builds. Coway Co. anchors its position through subscription-based filter replacement programs that lock in recurring revenue. IQAir North America differentiates via hyper-specialized cleanroom-grade units targeting hospitals and laboratories.
An air purifier is an electromechanical device designed to remove particulate matter, volatile organic compounds, and biological contaminants from indoor air through forced filtration, adsorption, or electrostatic precipitation, typically achieving specified clean air delivery rates measured in cubic meters per hour. Its primary commercial purpose is to maintain breathable air quality in enclosed environments where natural ventilation proves inadequate or external pollution levels exceed safe thresholds. HEPA filtration occupies the dominant revenue position due to proven efficacy against sub-micron particles, while activated carbon segments capture margin pools from VOC-sensitive industrial and medical buyers. Residential application volumes lead absolute unit sales, though medical end users command premium pricing through stringent certification requirements and institutional procurement protocols.
The US EPA Indoor airPLUS program and China's GB standards framework jointly shape product testing methodologies and filter efficiency benchmarks that manufacturers must satisfy for market access. India's BIS certification mandates and the EU Ecodesign Directive progressively tighten energy consumption limits and material disclosure rules for imported units. Stakeholders must monitor evolving particulate matter thresholds in emerging economy cities where regulatory enforcement is tightening faster than supply chain certification capacity can adapt.
Market Dynamics
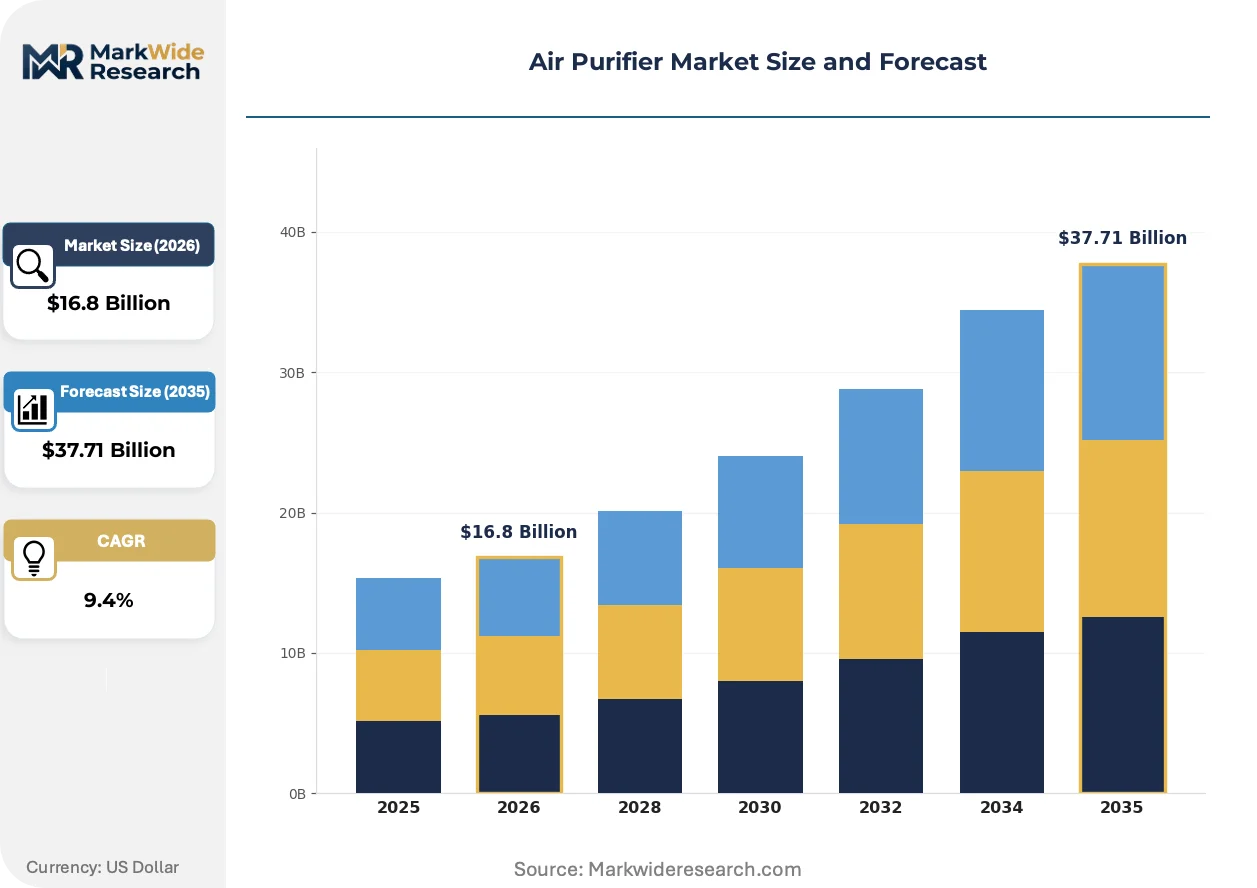
The air purifier market is bifurcating between medical-grade certification requirements and consumer-grade cost compression, with filter material supply concentration and HVAC integration complexity determining margin capture.
Growth Catalysts
- Healthcare ventilation mandates:Joint Commission standards in the United States are compelling hospital systems to upgrade to HEPA-certified units, institutionalizing replacement cycles.
- GB/T 18801 revisions:China's tightened CADR testing protocols are accelerating filter efficiency upgrades across domestic manufacturing bases.
- AQI-triggered procurement:India's northern urban corridors now automate bulk institutional purchases when particulate readings exceed threshold levels.
Market Restraints
- Filter media supply concentration:Microglass fiber and PTFE membrane production clusters in Germany and Japan create input bottlenecks during demand surges.
- Technical performance ceiling:HEPA filtration efficiency gains asymptote near 99.97% at 0.3 microns, compressing premium differentiation space.
- Regulatory fragmentation:Divergent certification timelines between EPA Indoor airPLUS, EU Ecodesign, and BIS delay unified product platform launches.
Strategic Opportunities
- VOC-sensitive industrial verticals:Semiconductor cleanrooms and pharmaceutical manufacturing in South Korea and Taiwan are specifying activated carbon-HEPA hybrid configurations.
- Filter-as-a-service models:Subscription-based replacement programs lock in recurring revenue streams from cost-sensitive residential buyers.
- HVAC convergence:Integration of air purification with climate control systems in commercial new-builds creates specification advantages for building automation vendors.
Industry Challenges
- Certification timeline compression:BIS and EPA parallel approval processes extend time-to-market by 8-14 months for multi-territory launches.
- Retrofit integration complexity:Legacy building infrastructure in European commercial stock lacks ductwork compatibility with centralized purification systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Purifier Market |
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $37.71 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA, Activated Carbon, Ionizers, UV Light Technology: Filtration, Photocatalytic, Electrostatic, Ozone Generation Application: Residential, Commercial, Industrial, Medical End User: Homeowners, Businesses, Hospitals, Schools |
| Companies Covered | Daikin Industries, Ltd., KONINKLIJKE PHILIPS N.V., Honeywell International, Inc., Coway Co., Ltd., Samsung Electronics Co., Ltd., IQAir North America, Inc., Panasonic Corporation, Sharp Corporation, LG Electronics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Purifier Market Emerging Trajectories
Filtration architecture is fragmenting into application-specific configurations, with modularity, regulatory stringency, and procurement centralization as the dominant vectors reshaping competitive position.
Photocatalytic oxidation technology is modularizing around titanium dioxide-coated substrates activated by UV-LED arrays. Hospital facilities in the United States are piloting these systems for biological decontamination in isolation wards. The technology is modularizing previously monolithic air handling units into stackable treatment stages that maintenance staff can swap without engineering support.
REACH substance restrictions and the EU F-Gas Regulation are eliminating hydrofluorocarbon-based refrigerants in climate-integrated purification systems. Manufacturers serving the European market are redesigning heat-recovery ventilation cores to comply with phasedown schedules. Medical device classification under the MDR is extending compliance documentation requirements for units deployed in surgical suites.
Buying committees in India's corporate real estate sector now require total cost of ownership modeling over five-year horizons. Equipment vendors are unbundling filter replacement logistics from hardware margins to win these tenders. This behavioral shift is most visible in Bengaluru and Hyderabad, where facility management outsourcing has concentrated specification authority with third-party operators.
Air Purifier Market Segmentation
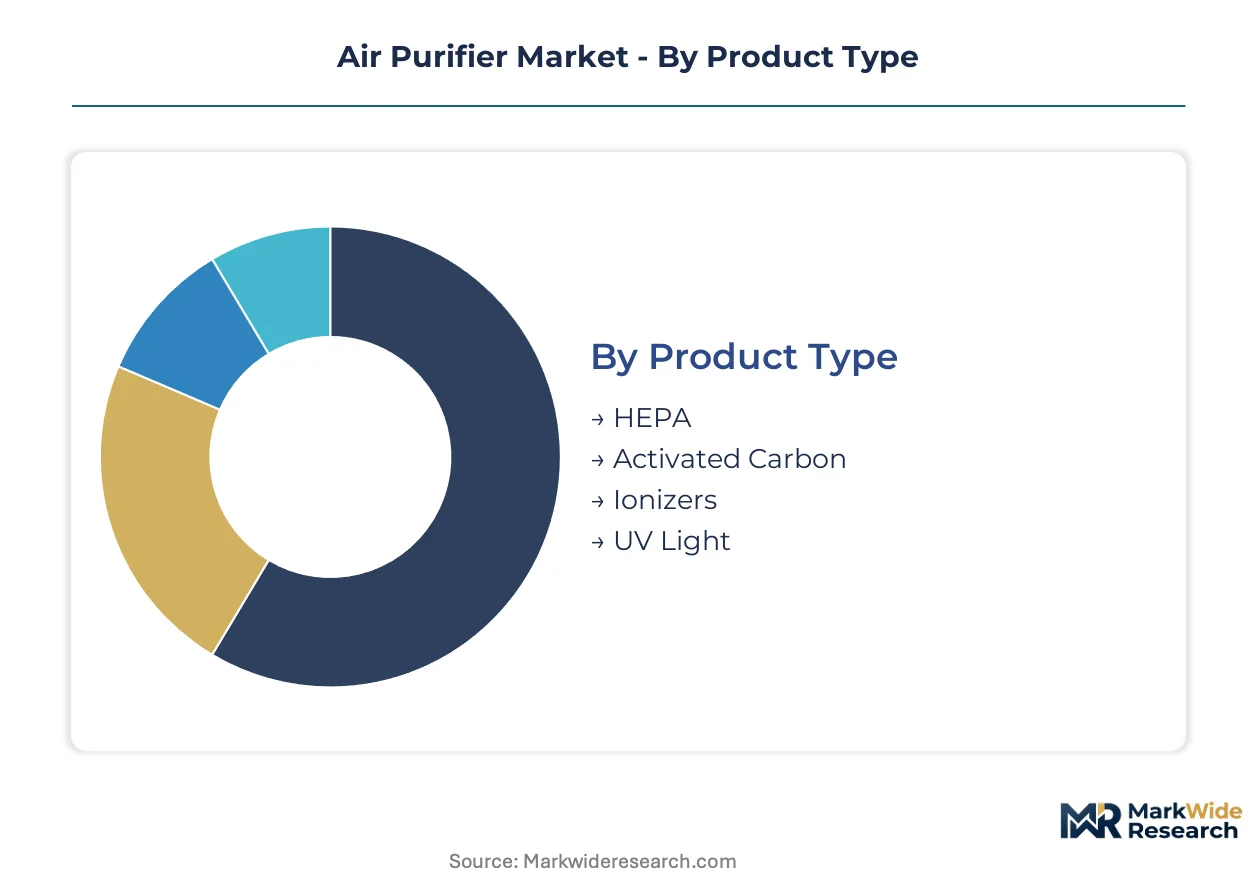
Air purifier purchasing decisions fragment across performance certification tiers, installation complexity, and operational cost structures. Manufacturers must align product architectures with distinct procurement protocols governing hospitals, commercial facilities, and residential channels.
Product Type:
Volume concentration favors entry-level units, while premium capture accrues to certified medical-grade systems with documented efficacy against sub-micron particles.
- HEPA:High-efficiency particulate air filters utilize dense microglass fiber matrices to intercept 99.97% of particles at 0.3 microns. Demand concentrates in United States hospital systems upgrading to Joint Commission-compliant ventilation infrastructure, with replacement cycles institutionalized through facility management contracts.
- Activated Carbon:Porous carbon substrates adsorb volatile organic compounds and gaseous contaminants through physisorption and chemisorption mechanisms. Procurement is accelerating in South Korean semiconductor cleanrooms and Taiwanese pharmaceutical manufacturing facilities where process contamination carries catastrophic yield costs.
- Ionizers:Electrostatic discharge systems charge airborne particles for collection on oppositely charged plates. Mass retail channels in China and India dominate volume distribution.
- UV Light:Ultraviolet-C germicidal irradiation disrupts pathogen DNA replication. United States isolation wards are piloting hybrid configurations for biological decontamination protocols.
Mature deployment sits with HEPA filtration. Newer deployment is concentrated in UV Light configurations for healthcare biological control.
Technology:
Cost-to-performance ratios determine adoption velocity, with established mechanical methods defending share against emerging photochemical approaches.
- Filtration:Physical barrier methods employing fibrous media or membrane structures to mechanically trap particulate matter. Residential replacement cycles in India's northern urban corridors automate when AQI readings exceed municipal thresholds.
- Photocatalytic:Titanium dioxide-coated substrates activated by UV-LED arrays generate reactive oxygen species for VOC oxidation. United States hospital facilities are modularizing previously monolithic air handling units into stackable treatment stages.
- Electrostatic:Corona discharge systems impart electrical charges for particle precipitation. Commercial building retrofits in Germany face ductwork compatibility constraints.
- Ozone Generation:High-voltage discharge produces triatomic oxygen for odor neutralization. Regulatory restrictions under EPA and state-level environmental agencies limit indoor deployment scope.
Established infrastructure favors Filtration. Photocatalytic configurations are gaining share fastest in medical-grade specifications.
Application:
Unit economics diverge sharply between price-sensitive residential volumes and specification-driven institutional premiums.
- Residential:Single-room and whole-home units targeting individual consumers through retail and direct-to-consumer channels. India's corporate real estate buying committees in Bengaluru and Hyderabad now require five-year total cost of ownership modeling, unbundling filter logistics from hardware margins.
- Commercial:Centralized and distributed systems for office buildings, retail environments, and hospitality venues. China's GB/T 18801 standard revisions are forcing filter efficiency upgrades across domestic manufacturing bases serving this segment.
- Industrial:Heavy-duty configurations for manufacturing environments with elevated particulate loading. Activated carbon-HEPA hybrid specifications dominate semiconductor and pharmaceutical verticals.
- Medical:Cleanroom-grade and surgical suite systems meeting stringent certification requirements. United States Joint Commission ventilation mandates are compelling hospital system upgrades with institutionalized replacement cycles.
Volume leadership sits with Residential. Specification premiums concentrate in Medical procurement protocols.
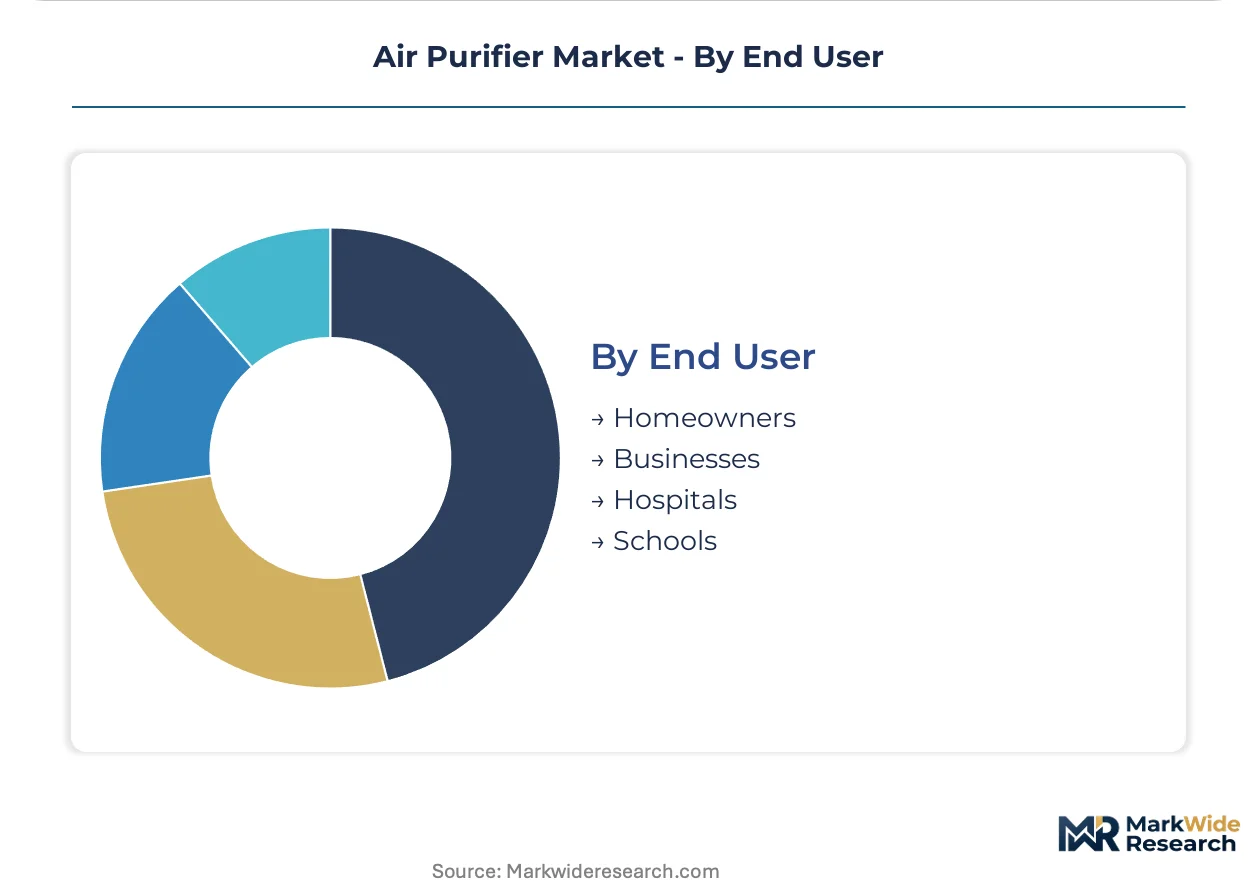
End User:
Procurement authority fragmentation shapes sales motion complexity, from individual purchase decisions to centralized facility management tenders.
- Homeowners:Individual consumers making discretionary purchases through retail, e-commerce, and direct channels. Subscription-based filter replacement programs are locking in recurring revenue streams from cost-sensitive buyers.
- Businesses:Corporate real estate and facility management operators specifying equipment for employee environments. India's facility management outsourcing concentration has shifted specification authority to third-party operators in Hyderabad and Bengaluru.
- Hospitals:Healthcare systems governed by ventilation mandates and patient safety protocols. EPA Indoor airPLUS and Joint Commission standards jointly shape product testing methodologies and filter efficiency benchmarks.
- Schools:Educational institutions balancing budget constraints with occupant density considerations. Bulk procurement automation triggers when regional air quality indices exceed threshold levels.
Institutional maturity sits with Hospitals. Procurement automation is expanding fastest among Schools responding to environmental health mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bengaluru and Hyderabad anchor procurement automation for India's corporate real estate sector, where facility management outsourcing concentrates specification authority with third-party operators demanding five-year total cost of ownership modeling.
United States
Hospital systems drive HEPA-certified unit demand through Joint Commission ventilation mandates that institutionalize replacement cycles. The EPA Indoor airPLUS program shapes product testing methodologies alongside state-level environmental agencies. Isolation wards in Boston and Houston pilot UV-LED hybrid configurations for biological decontamination protocols.
China
GB/T 18801 standard revisions tighten CADR testing protocols and force filter efficiency upgrades across domestic manufacturing bases. The Ministry of Ecology and Environment enforces dual carbon goals that reshape climate-integrated purification system designs. Yangtze River Delta production clusters adapt microglass fiber supply chains to meet stricter certification timelines.
India
AQI-triggered procurement automates bulk institutional purchases when particulate readings exceed threshold levels in northern urban corridors. BIS certification mandates progressively tighten energy consumption limits for imported units. Delhi-NCR facility operators unbundle filter replacement logistics from hardware margins to win corporate tenders.
Germany
REACH substance restrictions and the EU F-Gas Regulation eliminate hydrofluorocarbon-based refrigerants in climate-integrated systems. ECHA compliance documentation extends approval timelines for multi-territory launches. Bavarian heat-recovery ventilation manufacturers redesign cores to meet phasedown schedules.
South Korea
Semiconductor cleanrooms specify activated carbon-HEPA hybrid configurations where process contamination carries catastrophic yield costs. The Korean Agency for Technology and Standards enforces filter efficiency benchmarks for industrial deployments. Suwon and Pyeongtaek manufacturing clusters concentrate procurement authority with on-site facility engineering teams.
Air Purifier Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade stratification, with medical-grade HEPA specialists capturing institutional premiums while ionizer manufacturers compete on mass retail price points. The vendor base organizes around three strategic archetypes: HVAC-integrated climate control bundlers, subscription-based filter service operators, and cleanroom-grade hyper-specialists. Dominant competitive moves include strategic partnerships with building automation vendors and portfolio diversification into photocatalytic oxidation modules.
Within the HVAC-integrated tier, Daikin Industries exemplifies climate control bundling expertise, while Coway Co. occupies a position as a subscription-based filter replacement model operator. IQAir North America represents the cleanroom-grade hyper-specialist archetype targeting hospitals and laboratories. These three entities anchor distinct competitive vectors without overlapping positioning.
| Leading Market Players |
|---|
| Daikin Industries, Ltd. |
| KONINKLIJKE PHILIPS N.V. |
| Honeywell International, Inc. |
| Coway Co., Ltd. |
| Samsung Electronics Co., Ltd. |
| IQAir North America, Inc. |
| Panasonic Corporation |
| Sharp Corporation |
| LG Electronics, Inc. |
| Others |
Supply Flow & Price Mechanics
Hospital procurement committees in the United States anchor value-based pricing through Joint Commission-mandated replacement cycles that institutionalize premium capture for HEPA-certified systems. Cost compression in India's mass retail channels for ionizer units feeds back into supply chain choices favoring domestic assembly over imported filter media.
Pricing Analysis
Yield-guarantee contracts in South Korean semiconductor cleanrooms anchor value-based pricing, tying unit costs to documented contamination prevention outcomes. Three-tier pricing structure across medical-grade, commercial-certified, and residential-economy levels differentiates by filtration efficiency and certification burden. Cost compression in China's domestic manufacturing base intensifies as GB/T 18801 revisions force filter upgrades without corresponding price elasticity. Residential buyers in India exhibit highest price sensitivity, while United States hospital systems demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Specialized technician availability constrains production scaling in Germany's microglass fiber manufacturing clusters and Japan's PTFE membrane fabrication centers. Supply concentrates in these two countries for critical filter media, with secondary concentration in China's Yangtze River Delta for final assembly. Raw material dependencies span borosilicate glass microfibers, activated carbon substrates from coconut shell and bituminous coal sources, and UV-LED semiconductor components. Single-source vulnerability in German microglass fiber production creates structural risk during demand surges. Distribution runs through HVAC specification channels for commercial builds, direct-to-consumer e-commerce for residential units, and GPO contracts for hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Filter media supply concentration in Germany and Japan props pricing power for certified-grade systems, creating a supply-constrained market structure that favors incumbent margin defense.
For Market Incumbents: Anticipate photocatalytic oxidation modules displacing monolithic HEPA configurations in United States hospital isolation wards by accelerating R&D partnerships with UV-LED semiconductor suppliers. Defend position by deepening backward integration into activated carbon sourcing from Southeast Asian suppliers to offset REACH-driven input cost volatility. For New Entrants and Emerging Players: India's BIS certification tightening opens a window for domestic assembly operations that bypass import duty exposure on finished units. Target corporate real estate procurement automation in Bengaluru and Hyderabad through unbundled filter-logistics service models that separate hardware from recurring revenue streams. For Investors and Strategic Acquirers: The window for entry favors cleanroom-grade hyper-specialists with documented FDA and CE-MDR certification pathways already in progress. Monitor Joint Commission ventilation standard revision announcements as the inflection signal indicating accelerated replacement cycle timing for hospital system installed bases.| Strategic Initiative | Industry Significance |
|---|---|
| Filter-as-a-Service Subscription Launch | Locks recurring revenue from India's cost-sensitive residential buyers through automated replacement logistics. |
| HVAC Integration Partnership | Daikin Industries exemplifies climate control bundling that captures commercial new-build specification authority. |
| Photocatalytic Oxidation Module Development | United States hospital pilots validate titanium dioxide-UV-LED stacks for biological decontamination protocols. |
| Backward Integration into Carbon Sourcing | Mitigates REACH substance restriction exposure for European market access compliance. |
| GB/T 18801 Certification Pre-Positioning | Accelerates market access for China's tightened CADR testing protocols before enforcement deadlines. |
Methodological Framework
Independent corroboration across facility management directors, hospital biomedical engineers, and HVAC specification consultants underwrites the qualitative findings in this study. Primary interviews with GPO contracts managers and aftermarket service heads combined with secondary validation from EPA Indoor airPLUS documentation, China's GB standards filings, and BIS certification registries. Bottom-up triangulation across equipment shipment data and top-down reconciliation against regulatory mandate timelines anchored the market sizing.
Comparable-period anchoring to historical Joint Commission compliance cycles and AQI-triggered procurement automation patterns structured the projection horizon. Segmentation modeling spanned filtration technology, application tier, and certification grade alongside geographic regulatory cluster differentiation. CAGRs derived from installed base replacement velocity and new penetration coefficients calibrated against healthcare infrastructure spending patterns and semiconductor cleanroom construction pipelines.
The model assumes a particular technology adoption path; alternative pathways for photocatalytic oxidation would alter the outlook if UV-LED cost curves flatten faster than projected. Forecasts reflect assumptions about regulatory enforcement consistency and filter media supply elasticity. Material deviation in BIS certification timeline compression or REACH substance restriction expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Robot Vacuum Cleaners Market
Household Items
Sleeping Pods Market
Household Items
Hands-Free Faucet Market
Household Items
Global Electronic Bidet Seats Market
Household Items
Can Opener Market
Household Items
North America Ceramic Barbeque Grill Market
Household Items
Pet Fur Remover Market
Household Items
Portable Steam Cleaners Market
Household Items
Waterless Aroma Diffuser Market
Household Items
Neck Pillows Market
Household Items
Stainless Steel Thermos Cup Market
Household Items
Household Sewing Machines Market
Household Items
Global Tableware Market
Household Items
HEPA Vacuum Cleaners Market
Household Items
Shower Heads Market
Household Items
Enameled Cookware Market