
 Smart Flow Meter Market | 2026-2036
Smart Flow Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Flow Meter Market Analytics
The EU Green Deal is consolidating demand for intelligent flow measurement across European process industries. Emerson Electric leverages its automation portfolio to anchor digital flow solutions in chemical processing. Honeywell International competes through integrated building energy platforms that embed thermal and ultrasonic metering. Siemens AG extends its dominance via industrial IoT architectures that connect flow data to enterprise asset management.
A smart flow meter is an instrument that measures fluid velocity, volume, or mass flow rate using electromagnetic, ultrasonic, or thermal sensing principles, typically achieving accuracy within 0.5% to 2% of reading depending on technology and installation conditions. These devices transmit data through wireless or cloud-connected protocols to enable real-time monitoring, leak identification, and automated process optimization in industrial and utility settings. Ultrasonic and electromagnetic product types now capture the strongest margin pools as utilities phase out mechanical meters with moving parts. IoT and cloud-based technology segments are expanding fastest where edge computing reduces latency for critical leak detection and energy management applications.
The EPA enforces drinking water quality standards that mandate accurate consumption tracking and loss accounting, directly shaping municipal procurement specifications for advanced metering infrastructure. In Europe, the EU AI Act and F-Gas Regulation impose algorithmic transparency and refrigerant containment requirements that elevate demand for intelligent sensors in HVAC and process cooling systems. Stakeholders must weigh regulatory compliance timelines against sensor refresh cycles to align capital deployment with evolving certification thresholds.
Market Dynamics
The Smart Flow Meter Market is undergoing structural transformation as electromagnetic and ultrasonic sensing architectures displace mechanical meters with moving parts, compressing maintenance cycles while elevating accuracy thresholds for utility and industrial procurement.
Growth Catalysts
- EPA Lead and Copper Rule Revisions:Accelerated infrastructure replacement mandates in United States municipal water systems are forcing digitization of consumption tracking and loss accounting.
- EU Green Deal Consolidation:European process industries face binding carbon accounting requirements that demand intelligent thermal and mass flow measurement for energy optimization.
- Edge Computing Integration:IoT-enabled meters with localized data processing are reducing leak detection latency from hours to minutes in critical distribution networks.
Market Restraints
- Semiconductor Component Volatility:MEMS sensors and signal processing chips face supply concentration risks concentrated in East Asian foundry networks.
- Calibration Infrastructure Gaps:Developing markets lack traceable flow calibration facilities certified to ISO 17025 standards, limiting deployment accuracy guarantees.
- Mechanical Meter Residual Stock:Decades-long asset depreciation cycles in mature utilities delay refresh timelines despite superior total cost of ownership for electronic alternatives.
Strategic Opportunities
- HVAC Refrigerant Monitoring:EU F-Gas Regulation phase-down schedules create installed base expansion for thermal mass flow sensors in commercial building systems.
- Sub-Saharan Africa Utility Modernization:Green climate fund financing for non-revenue water reduction programs opens tender pipelines for prepaid smart metering architectures.
- Digital Twin Convergence:Integration of real-time flow data with enterprise asset management platforms enables predictive maintenance contracts that monetize sensor networks beyond hardware sales.
Industry Challenges
- Field Engineering Talent Scarcity:Installation and commissioning of electromagnetic meters in hazardous environments requires certified technicians with scarce cross-training in electrical safety and fluid mechanics.
- Multi-Protocol Integration Complexity:Legacy SCADA systems in industrial plants use proprietary communication stacks that demand costly middleware development for cloud-connected meter onboarding.
- Cybersecurity Certification Timelines:IEC 62443 compliance for industrial IoT devices extends product launch schedules by 12-18 months in regulated verticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Flow Meter Market |
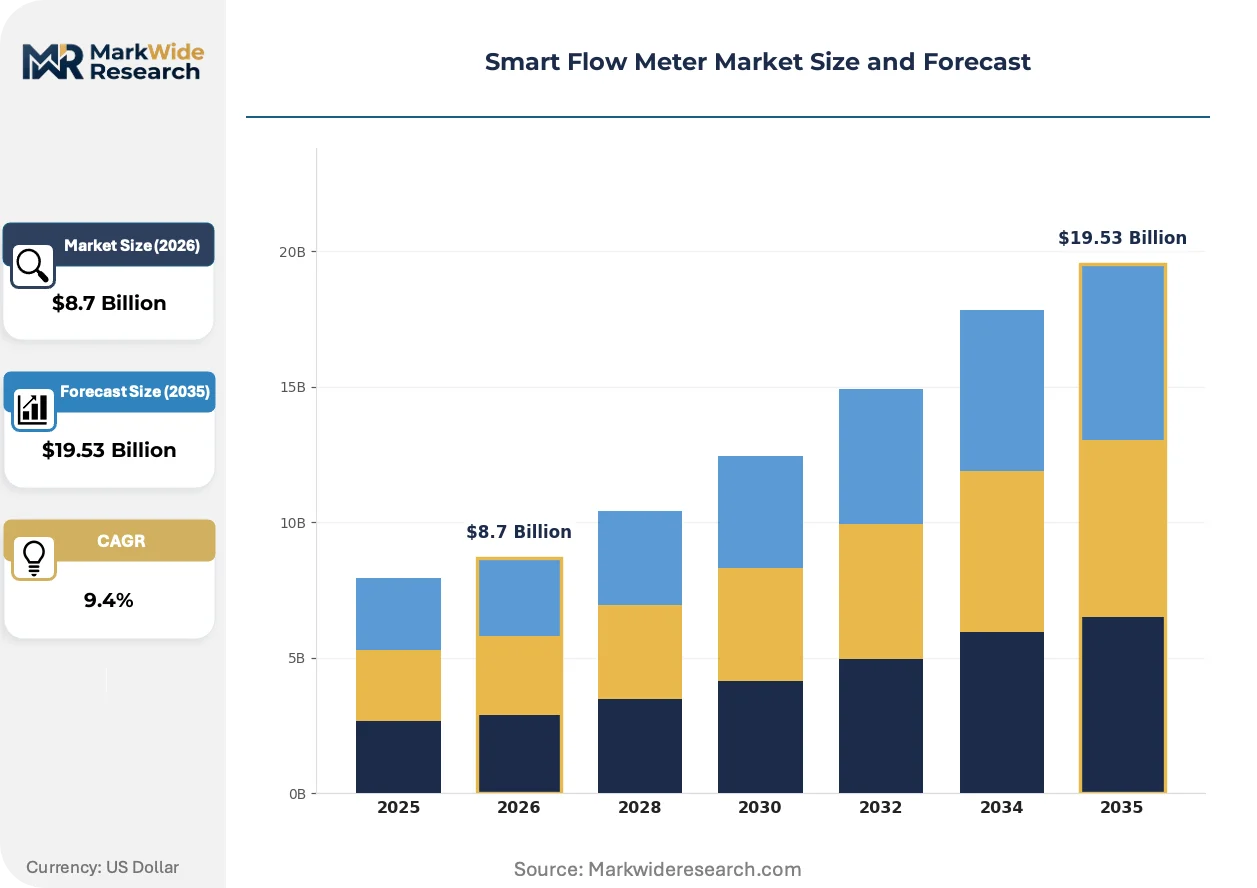
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnetic, Ultrasonic, Mechanical, Thermal Technology: IoT, Wireless, Smart Sensors, Cloud-Based End User: Water Utilities, Oil & Gas, Chemical Processing, HVAC Application: Flow Measurement, Leak Detection, Process Control, Energy Management |
| Companies Covered | Siemens AG, Honeywell International, Emerson Electric, Yokogawa Electric Corporation, Azbil Corporation, ABB Ltd., Sierra Instruments, Fuji Electric, Endress+Hauser AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Flow Meter Market Evolving Landscape
Ultrasonic time-of-flight sensing is absorbing market share as utilities prioritize non-intrusive measurement that eliminates pressure drop and corrosion vulnerability inherent in wetted mechanical designs.
Ultrasonic clamp-on transducers measure fluid velocity through pipe walls using acoustic pulse transit time differentials. Water utilities in Germany and the Netherlands are deploying these sensors at scale for district metering area segmentation. This architecture is absorbing applications previously served by inline electromagnetic meters, particularly in retrofit scenarios where pipeline shutdown is economically prohibitive.
The EU AI Act imposes algorithmic transparency requirements on automated decision systems that process sensor data for leak classification. Industrial operators must now document training data provenance and model performance metrics for flow-based anomaly detection. Chemical processing facilities in Belgium and France are responding by demanding meter suppliers provide edge AI chips with auditable inference logging.
Buying committees in North American municipal utilities are consolidating vendor relationships around integrated advanced metering infrastructure platforms that bundle meters, communication modules, and software analytics. Traditional equipment distributors are losing specification influence as procurement teams engage directly with automation OEMs for enterprise-wide standardization. This pattern is most pronounced in California and Texas, where water scarcity economics justify centralized capital planning for meter refresh programs.
Smart Flow Meter Market Segmentation
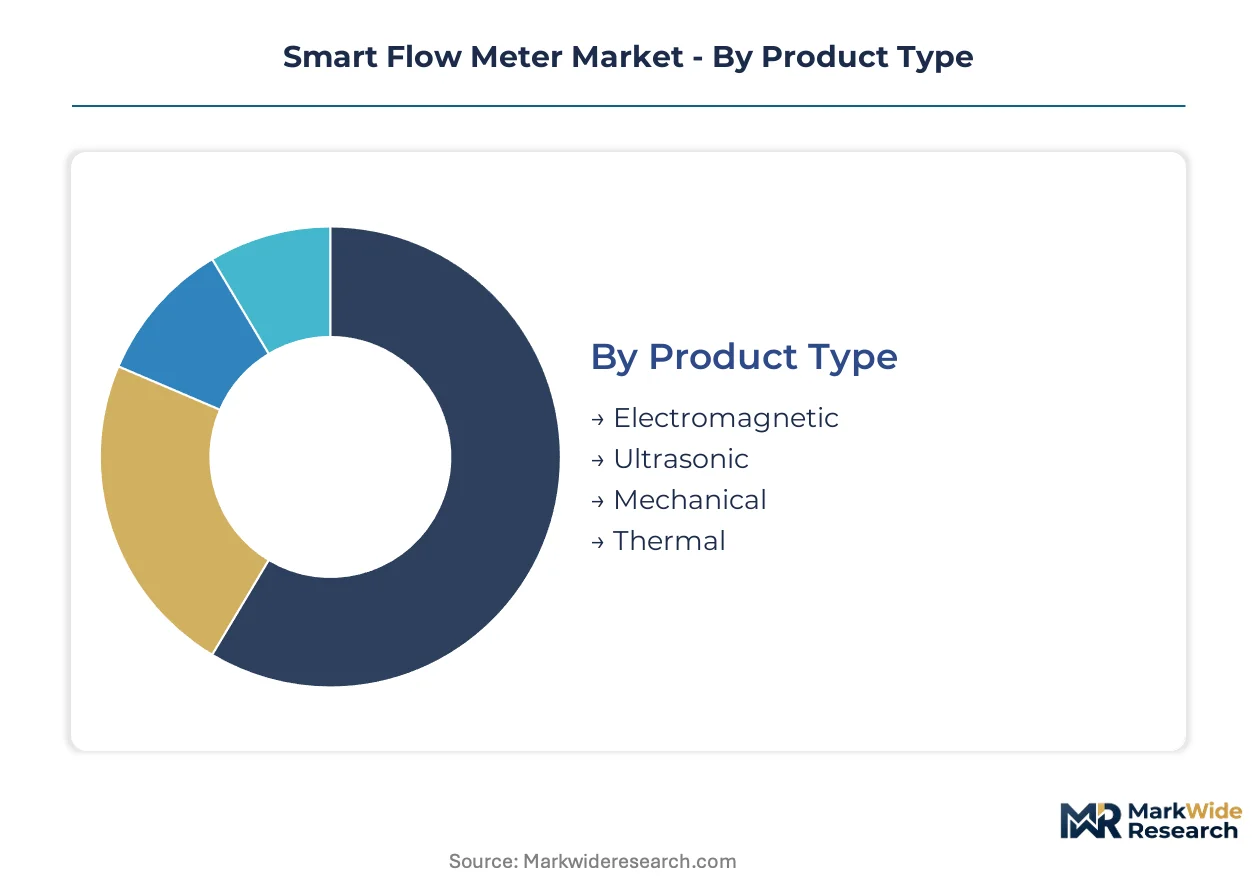
Smart flow meter procurement varies sharply by operational environment, from standardized utility bulk purchases to highly customized industrial installations requiring hazardous area certifications. Segmentation reveals where margin pools concentrate versus where volume scales, guiding capital allocation and product portfolio design.
Product Type:
Customization intensity spans from fully configurable electromagnetic systems with field-programmable measurement ranges to commodity mechanical meters with fixed specifications.
- Electromagnetic:Faraday's law-based sensors measure conductive fluid velocity through induced voltage across a magnetic field, achieving accuracy within 0.5% of reading. Water utilities in Germany and California specify these for large-diameter transmission mains where pressure drop minimization outweighs higher unit cost. EPA Lead and Copper Rule infrastructure replacement cycles are accelerating municipal procurement.
- Ultrasonic:Time-of-flight and Doppler principles enable non-intrusive measurement through clamp-on or inline transducers with no moving parts. District metering area segmentation in Dutch and Belgian utilities absorbs these sensors for retrofit scenarios where pipeline shutdown is economically prohibitive. EU Green Deal carbon accounting requirements elevate demand for thermal energy measurement in building systems.
- Mechanical:Turbine and positive displacement designs with rotating elements dominate legacy installed bases in mature North American utilities. Residual stock and depreciation cycles delay refresh timelines despite superior total cost of ownership for electronic alternatives.
- Thermal:Calorimetric and hot-wire anemometry principles measure mass flow of gases and clean liquids in HVAC and semiconductor process cooling. EU F-Gas Regulation refrigerant containment mandates are expanding specification opportunities.
Leading the category by volume: Mechanical. Growing fastest: Ultrasonic.
Technology:
Integration depth determines value capture, from standalone sensors to full-stack cloud platforms with embedded analytics.
- IoT:Networked meters with edge computing capabilities process data locally for real-time leak classification and anomaly detection. Water utilities in Texas and Arizona deploy these architectures to reduce non-revenue water losses through sub-minute response latency.
- Wireless:LoRaWAN, NB-IoT, and proprietary radio protocols eliminate trenching costs for retrofit deployments. Sub-Saharan African prepaid metering programs favor these technologies for rapid infrastructure rollout without fiber dependency.
- Smart Sensors:MEMS-based flow elements with integrated signal conditioning and self-diagnostics reduce field commissioning complexity. Chemical processing facilities in Belgium specify these for hazardous area installations where technician certification scarcity elevates installation cost.
- Cloud-Based:Centralized data aggregation platforms enable enterprise-wide consumption analytics and predictive maintenance contracts. North American municipal buying committees are consolidating vendor relationships around these integrated AMI platforms.
Deepest integration: Cloud-Based. Steepest expansion trajectory: IoT.
End User:
Procurement sophistication ranges from centralized utility tenders to fragmented industrial maintenance budgets.
- Water Utilities:Municipal and investor-owned operators account for the largest volume procurement, driven by non-revenue water reduction targets and regulatory compliance mandates. California and Texas water scarcity economics justify accelerated meter refresh programs.
- Oil & Gas:Upstream, midstream, and downstream operators require custody transfer accuracy and hazardous area certifications. North Sea and Permian Basin developments specify high-reliability electromagnetic meters for multiphase flow measurement.
- Chemical Processing:Batch and continuous manufacturers demand corrosion-resistant materials and SIL-rated safety integrity. EU AI Act algorithmic transparency requirements are reshaping sensor data processing specifications in Belgian and French facilities.
- HVAC:Commercial building operators and OEMs integrate thermal mass flow sensors for refrigerant monitoring and energy optimization. EU F-Gas Regulation phase-down schedules are expanding installed base replacement cycles.
Highest procurement concentration: Water Utilities. Fastest specification evolution: HVAC.
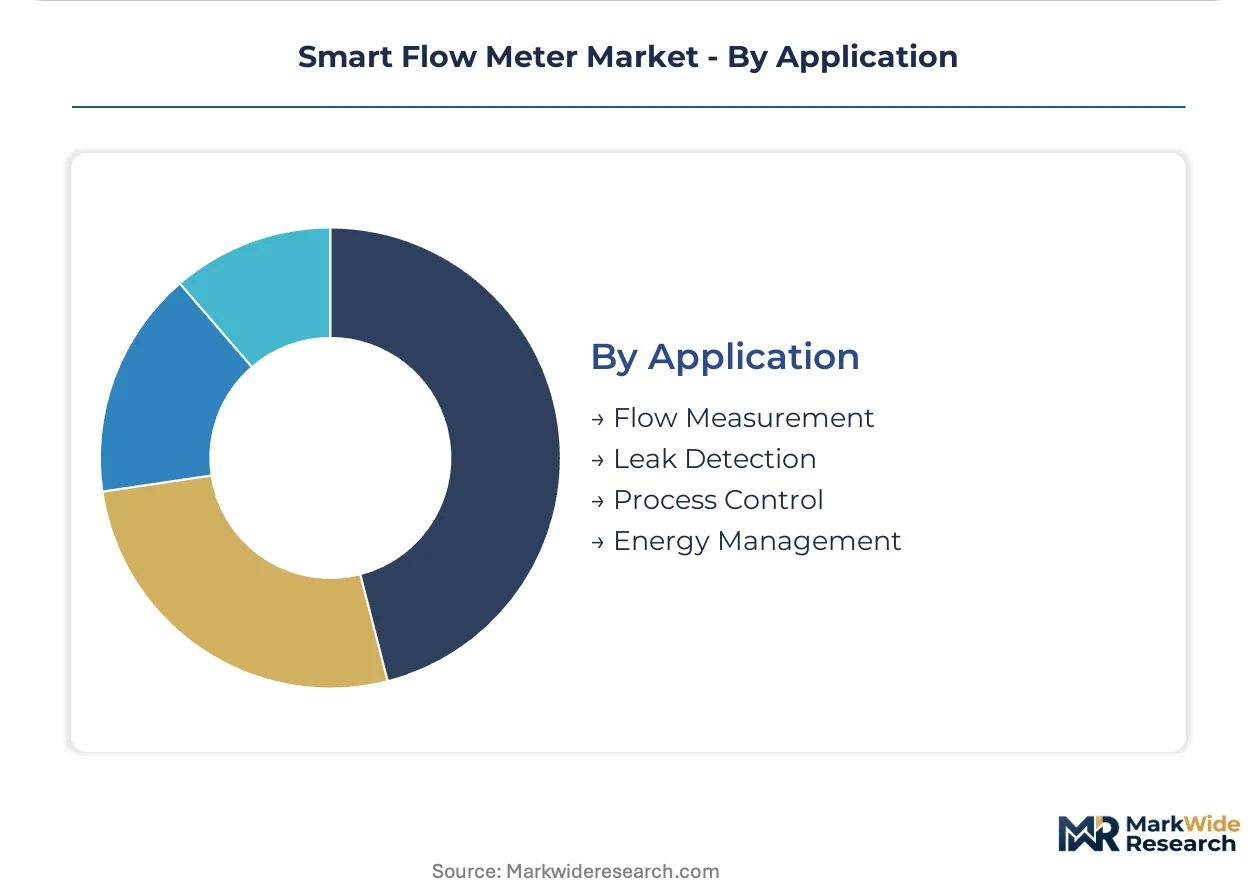
Application:
Value extraction varies from basic measurement commodities to predictive analytics services with recurring revenue potential.
- Flow Measurement:Fundamental velocity, volume, and mass quantification remains the core function across all end-use segments. Accuracy specifications tighten as carbon accounting and custody transfer requirements proliferate.
- Leak Detection:Pressure transient analysis and acoustic signature recognition enable pipeline integrity monitoring. German and Dutch district metering architectures achieve sub-hour localization precision through distributed sensor networks.
- Process Control:Closed-loop automation in chemical and food processing demands millisecond-level measurement latency. Edge AI inference on sensor-integrated chips is displacing centralized SCADA architectures.
- Energy Management:Thermal flow measurement for heating, cooling, and steam systems supports building efficiency optimization and carbon reporting. EU Green Deal binding targets are mandating sub-metering granularity in commercial real estate.
Deepest margin pool: Process Control. Widening specification fastest: Energy Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors North American demand for custody-transfer flow measurement in oil and gas midstream infrastructure, while Munich and Stuttgart drive European precision instrumentation for process industries. Regulatory mandates and utility modernization programs are concentrating procurement across specific national markets.
United States
California and Texas water utilities deploy advanced metering infrastructure to reduce non-revenue losses amid persistent drought economics. EPA Lead and Copper Rule revisions mandate infrastructure replacement cycles that accelerate municipal digitization. The Permian Basin absorbs high-reliability electromagnetic meters for multiphase flow measurement in upstream operations.
Germany
Dutch and Belgian district metering architectures influence German utility specifications for ultrasonic retrofit deployments. EU Green Deal carbon accounting requirements elevate demand for thermal energy measurement in building systems. The Ruhr industrial corridor specifies SIL-rated flow sensors for chemical processing safety integrity.
China
Yangtze River Delta municipalities phase out mechanical meters for electromagnetic alternatives in large-diameter transmission mains. National dual carbon goals mandate sub-metering granularity for industrial energy optimization. Shenzhen technology clusters develop edge AI chips for localized leak classification algorithms.
Japan
Kansai region semiconductor fabs demand thermal mass flow sensors for ultra-pure process cooling systems. METI efficiency standards drive HVAC refrigerant monitoring specifications in commercial building retrofits. Yokogawa's domestic manufacturing base anchors precision instrumentation exports across Asia-Pacific.
Netherlands
Dutch water utilities pioneered district metering area segmentation using clamp-on ultrasonic transducers. EU F-Gas Regulation phase-down schedules expand thermal flow sensor specifications for building energy management. Rotterdam port logistics clusters integrate flow data with enterprise asset management platforms.
Smart Flow Meter Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with automation portfolios. Siemens AG, Honeywell International, and Emerson Electric anchor the premium tier through integrated IoT architectures and building energy platforms. Mid-scale specialists compete on hazardous area certifications and SIL-rated safety integrity. Dominant competitive moves include strategic partnerships for cloud platform integration and geographic expansion through utility tender participation in Sub-Saharan Africa.
Among Germany-based precision instrumentation manufacturers, Endress+Hauser AG and Siemens AG exemplify the diversified conglomerate archetype with vertical integration into sensor manufacturing and enterprise software. Yokogawa Electric Corporation represents the Asia-Pacific specialist position with concentrated expertise in process automation. These three occupy positions where regulatory compliance capabilities and calibration infrastructure determine specification success in European and North American municipal tenders.
| Leading Market Players |
|---|
| Siemens AG |
| Honeywell International |
| Emerson Electric |
| Yokogawa Electric Corporation |
| Azbil Corporation |
| ABB Ltd. |
| Sierra Instruments |
| Fuji Electric |
| Endress+Hauser AG |
| Others |
Value Network & Pricing Analysis
Certified electromagnetic meter technicians in the Ruhr industrial corridor command wage premiums that compress margins on mid-tier instrumentation, widening spreads between SIL-rated premium systems and economy-grade mechanical alternatives. Labor scarcity in hazardous-area commissioning elevates total installed cost differentials beyond raw component gaps, forcing procurement committees toward bundled service contracts that obscure unit pricing transparency.
Pricing Analysis
Value-based pricing anchored to non-revenue water reduction outcomes dominates municipal utility procurement, with vendors contracting against guaranteed leak-detection performance rather than per-unit hardware fees. Price differentiation separates IEC 62443-certified industrial IoT architectures from basic wireless transmitters lacking edge-computing capabilities. Pricing pressure stems from semiconductor component volatility concentrated in East Asian foundry networks, compressing margins on MEMS-integrated smart sensors. Water utilities in Sub-Saharan Africa exhibit highest price sensitivity due to Green Climate Fund budget constraints, while Permian Basin oil and gas operators absorb premium custody-transfer specifications with minimal negotiation.
Supply Chain Analysis
Dual-sourcing requirements mandated by European chemical processors and North American municipal buying committees force qualification of secondary suppliers for magnetic flow tubes and ultrasonic transducer ceramics. Manufacturing concentrates in Germany, Japan, and China, with Siemens AG and Yokogawa Electric Corporation anchoring precision instrumentation capacity in Stuttgart and Kofu respectively. Raw material dependencies center on rare-earth magnets for electromagnetic sensors, piezoelectric ceramics for ultrasonic elements, and corrosion-resistant alloys for wetted components. Single-source vulnerability in MEMS sensor fabrication creates exposure to East Asian logistics chokepoints. Distribution runs through automation OEM direct channels and specialized industrial distributors serving hazardous-area certification markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart Flow Meter Market is consolidating around vertical-integration races, with automation conglomerates pursuing captive production of edge-AI chips and cloud analytics platforms to capture recurring revenue beyond hardware displacement cycles.
For Market Incumbents: Hedge against ultrasonic clamp-on displacement of inline electromagnetic architectures by acquiring thermal mass flow specialists serving EU F-Gas Regulation refrigerant monitoring mandates. Secure backward integration into MEMS sensor fabrication to insulate margin structures from East Asian foundry concentration risks. Prioritize IEC 62443 cybersecurity certification investment to extend product launch timelines that deter mid-scale competitors.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in cloud-based AMI platforms creates entry space for software-native vendors with predictive analytics capabilities. Target Sub-Saharan African prepaid metering programs where Green Climate Fund financing bypasses incumbent distributor relationships. Pursue partnership-based go-to-market angles with European HVAC OEMs facing EU Green Deal sub-metering granularity requirements.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale specialists possessing SIL-rated safety integrity certifications and established utility tender participation records given EPA Lead and Copper Rule acceleration timelines. Long-term viability favors targets with calibration infrastructure traceable to ISO 17025 standards across multiple regulatory jurisdictions. Watch district metering area segmentation adoption rates in Dutch and Belgian utilities as inflection indicators for ultrasonic retrofit demand scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Chip Development | Localized leak classification algorithms reduce latency for Texas and Arizona water utilities. |
| Cloud Platform Integration | Enterprise asset management convergence enables predictive maintenance contracts beyond hardware sales. |
| Calibration Infrastructure Expansion | ISO 17025-certified facilities unlock municipal tender participation in developing markets. |
| Cybersecurity Certification Investment | IEC 62443 compliance extends product launch schedules but locks out unqualified competitors. |
| Sub-Saharan Africa Tender Participation | Green Climate Fund financing for non-revenue water programs opens prepaid metering pipelines. |
Research Methodology
Document review covered EPA enforcement actions, EU Green Deal implementation guidance, and F-Gas Regulation phase-down schedules, complemented by interviews with water utility procurement directors, chemical processing plant engineers, and HVAC system integrators. Secondary validation drew from SEC 10-K filings of listed automation conglomerates, customs data on electromagnetic flow meter trade flows, and IEC certification registry databases. Bottom-up unit economics triangulated against top-down market sizing across product type, technology, and end-use segmentation dimensions.
Segment-level revenue estimates and volume projections across the analysis window reflect econometric modeling of regulatory compliance timelines, utility capital expenditure cycles, and industrial IoT adoption curves. The analytical framework incorporated technology substitution dynamics between electromagnetic, ultrasonic, and mechanical architectures alongside end-user procurement sophistication differentials. CAGRs were derived from regression analysis of historical deployment rates against mandated infrastructure replacement schedules and carbon accounting binding targets.
Inputs from EPA enforcement databases and EU certification registries were available through the study window; gaps in real-time utility procurement pipeline data introduce uncertainty bands around near-term volume estimates. Deviation in semiconductor supply chain normalization timelines or cybersecurity certification processing speeds would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Frictionless Remote Monitoring Devices Market
Sensors and Controls
Photonic Sensors and Detectors Market
Sensors and Controls
Actigraphy Sensors Market
Sensors and Controls
Pressure Transducer Market
Sensors and Controls
Asia Pacific Fingerprint Sensor Market
Sensors and Controls
Europe Pressure Transmitter Market
Sensors and Controls
MEMS Pressure Sensors Market
Sensors and Controls
Digital Flow Meter Market
Sensors and Controls
Global Proximity and Displacement Sensors Market
Sensors and Controls
Biopotential Sensor Market
Sensors and Controls
Digital Angle Gauge Market
Sensors and Controls
Yaw Rate Sensors Market
Sensors and Controls
Japan Sensor Market
Sensors and Controls
Speed Sensor Market
Sensors and Controls
Magnetoresistive Sensors Market
Sensors and Controls
Optical Chemical Sensor Market