
 Speed Sensor Market | 2026-2036
Speed Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Speed Sensor Market Analysis
ISO 26262 functional safety certification is reorganizing competitive access in automotive speed sensing, raising barriers for uncertified suppliers. Robert Bosch GmbH leverages captive semiconductor fabrication to control Hall Effect sensor quality from wafer to module. Infineon Technologies AG anchors its position through vertical integration into magnetic sensing ASICs. STMicroelectronics NV differentiates by specializing in automotive-grade MEMS speed modules with embedded diagnostic logic.
A speed sensor detects rotational or linear velocity by converting mechanical motion into electrical signals, typically outputting pulse trains or analog voltages with resolutions from 1 to 10,000 pulses per revolution depending on encoder geometry. These devices serve critical feedback loops in antilock braking, traction control, and industrial servo positioning where timing precision below one microsecond prevents mechanical failure. Hall Effect sensors occupy the dominant product tier due to their immunity to dust and oil contamination in powertrain environments. Digital technology segments are expanding fastest as automakers replace analog interfaces with SENT-protocol outputs for higher noise immunity and diagnostic depth. Wireless speed sensing remains nascent but attracts development capital for rotating machinery where slip rings degrade.
FDA scrutiny of sensor accuracy in medical centrifuges and the EPA's drive-by-wire emissions testing protocols both tighten calibration requirements across supplier bases. NHTSA mandates for electronic stability control sustain baseline automotive volume, while REACH restrictions on rare-earth magnet content force material substitutions in European-sourced magnetic sensors. Stakeholders must monitor how functional safety tiering and magnet supply chain restructuring reshape qualification costs and sourcing geography.
Market Dynamics
Automotive electrification is compressing design cycles for speed sensing modules, forcing suppliers to synchronize Hall Effect and MEMS roadmaps with electric powertrain thermal profiles and magnetic field tolerances.
Growth Catalysts
- EU Green Deal vehicle emissions standards:Tightening CO2 monitoring requirements mandate precision wheel-speed feedback for regenerative braking optimization, expanding sensor counts per electric vehicle platform.
- Industrial servo positioning:Machine tool OEMs in Germany and Japan deploy high-resolution encoders for sub-micron positioning accuracy in five-axis machining centers.
- SENT protocol adoption:Automakers replace analog voltage outputs with Single Edge Nibble Transmission digital interfaces, enabling diagnostic fault reporting without secondary wiring harnesses.
Market Restraints
- Rare-earth magnet supply concentration:REACH restrictions on neodymium and dysprosium sourcing force European magnetic sensor manufacturers toward ferrite alternatives with inferior temperature stability.
- ISO 26262 ASIL certification costs:Functional safety qualification for automotive speed modules requires 18-24 month validation cycles, freezing out mid-tier semiconductor suppliers without captive testing facilities.
- Optical encoder substitution:Industrial automation buyers in precision metrology applications migrate to photoelectric encoders where oil contamination risks are controlled, eroding Hall Effect penetration in cleanroom environments.
Strategic Opportunities
- Wireless speed sensing for rotating machinery:Slip ring elimination in wind turbine nacelles and steel rolling mills creates addressable white space for battery-free inductive power harvesting modules.
- India PLI scheme for automotive components:Tier-1 suppliers establishing Chennai and Pune manufacturing footprints qualify for production-linked incentives covering sensor module assembly.
- FDA medical centrifuge accuracy mandates:Blood processing equipment OEMs face upgraded calibration requirements, opening premium-priced high-reliability Hall Effect channels.
Industry Challenges
- Magnetic sensing ASIC design talent scarcity:Mixed-signal engineers capable of integrating Hall plates with temperature compensation algorithms command compensation premiums that strain R&D budgets.
- Legacy CAN bus integration complexity:Industrial retrofit projects require protocol translation gateways to marry SENT-output speed sensors with existing controller area network architectures, extending commissioning timelines.
- RoHS material requalification:Lead-free solder joint reliability testing for automotive underhood temperature cycling consumes validation resources without incremental performance gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Speed Sensor Market |
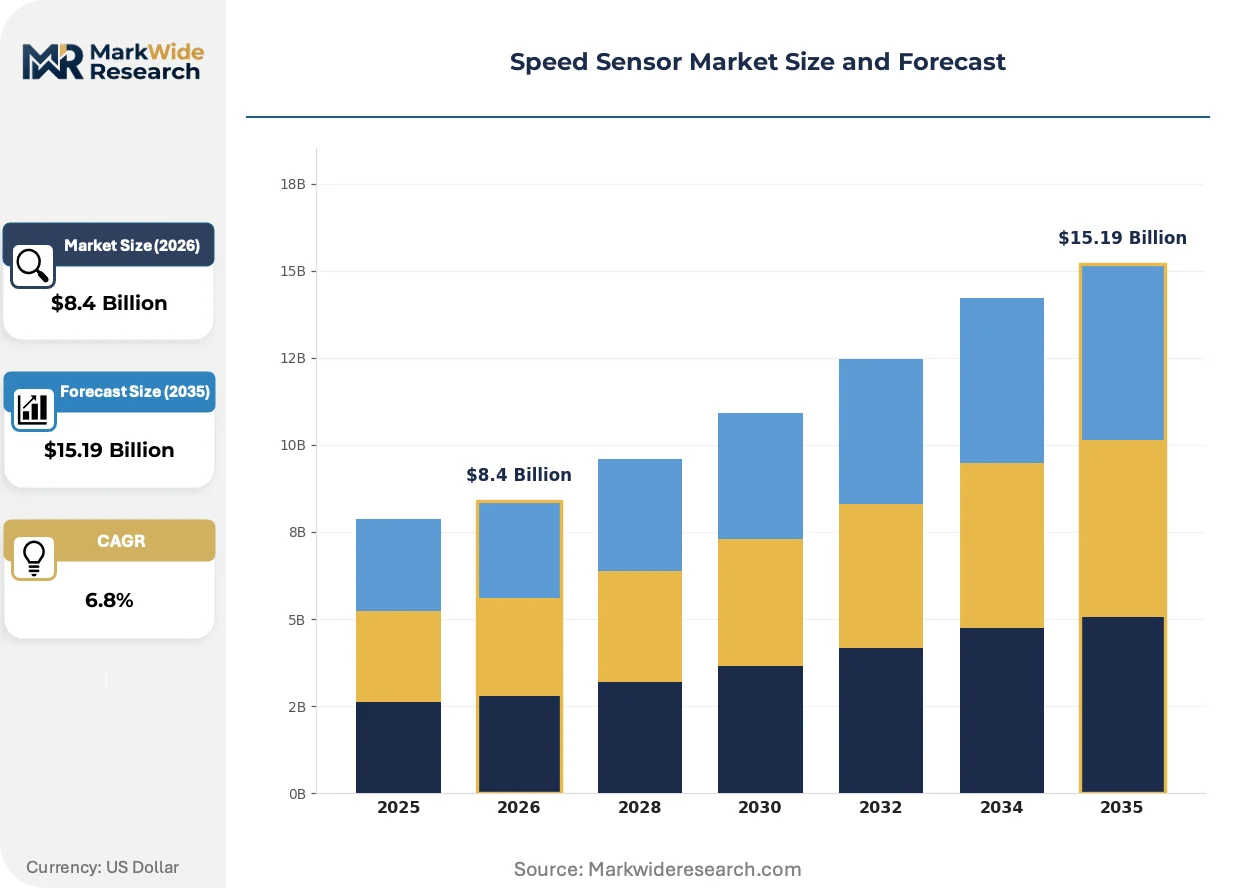
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic, Optical, Hall Effect, Capacitive End User: Automotive OEMs, Aerospace, Industrial Machinery, Consumer Electronics Technology: Analog, Digital, Wireless, Hybrid Application: Speed Measurement, Position Sensing, Motion Detection, Control Systems |
| Companies Covered | Honeywell International Inc., Infineon Technologies AG, Robert Bosch GmbH, HELLA GmbH & Co. KGaA, STMicroelectronics NV, Continental AG, DENSO CORPORATION, Allegro MicroSystems Inc., NXP Semiconductors NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Speed Sensor Market Emerging Trajectories
Speed sensing technology is fragmenting along automotive-industrial fault lines, with divergent performance specifications and interface standards creating parallel supply ecosystems rather than unified product platforms.
Hall Effect sensing is bifurcating into automotive-grade variants with embedded diagnostic logic and industrial-grade modules optimized for extended temperature ranges. Electric vehicle powertrain engineers demand ASIL-D capable devices with self-test routines, while steel mill automation buyers prioritize 150°C continuous operation over functional safety certification. This technological split is compressing supplier margins as dual qualification costs accumulate without volume consolidation.
REACH restrictions on rare-earth magnet content are forcing material substitutions across European-sourced magnetic sensors. ECHA substance of very high concern listings for neodymium compounds push manufacturers toward ferrite and alnico alternatives, degrading magnetic field sensitivity in compact packages. German automotive Tier-1 suppliers around Stuttgart are responding with larger sensor footprints that accommodate weaker magnetic materials without sacrificing air-gap tolerance.
Buyer concentration among automotive OEMs is consolidating procurement leverage for speed sensor contracts. Volkswagen, BMW, and Mercedes-Benz parent entities now mandate SENT protocol compliance and multi-source qualification as table stakes for platform awards, eroding supplier differentiation on technical specifications alone. This behavioral shift is most visible in Bavaria and Baden-Württemberg, where powertrain engineering teams synchronize sensor roadmaps across shared electric vehicle architectures.
Speed Sensor Market Segmentation
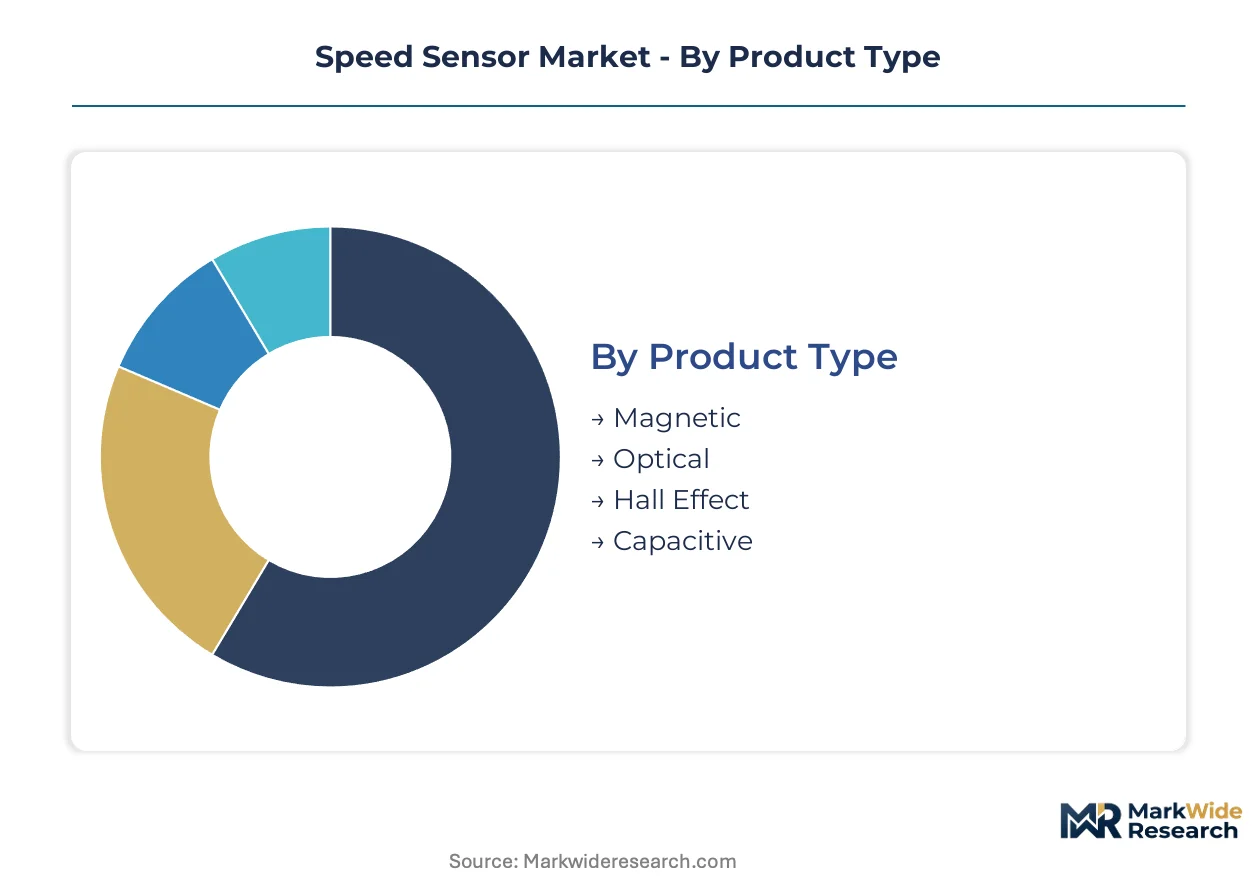
Speed sensor segmentation reveals divergent technical requirements across automotive, industrial, and aerospace verticals, with interface protocols and environmental tolerances driving product differentiation more than raw performance metrics. Each dimension carries distinct substitution pressures that reshape supplier positioning and R&D allocation.
Product Type:
Optical encoders exert the strongest substitution pressure on incumbent magnetic technologies in cleanroom industrial settings, while Hall Effect sensors defend their automotive dominance through contamination immunity.
- Hall Effect:These sensors exploit semiconductor Hall plates to detect magnetic field variations from rotating targets, delivering robust performance in oil-saturated powertrain environments. Automotive OEMs in Germany specify Hall Effect modules for wheel-speed monitoring in electric vehicle regenerative braking systems, driven by NHTSA electronic stability control mandates and EU Green Deal emissions verification requirements.
- Magnetic:Variable reluctance and magnetoresistive designs target heavy industrial rotating machinery with extended air-gap tolerance and passive operation without external power. Steel rolling mills in Japan and wind turbine nacelles in Denmark specify magnetic sensors for 150°C continuous operation where active electronics would degrade, constrained by REACH rare-earth magnet sourcing restrictions forcing ferrite substitution.
- Optical:Photoelectric encoders deliver sub-micron resolution for precision metrology and semiconductor manufacturing equipment.
- Capacitive:Non-contact proximity sensing suits medical centrifuge and laboratory automation applications requiring immunity to magnetic interference.
Hall Effect sensors anchor the volume base while optical encoders gain share at the steepest rate in precision industrial applications.
End User:
Customer concentration patterns split the market between consolidated automotive procurement and fragmented industrial specification.
- Automotive OEMs:Volkswagen, BMW, and Mercedes-Benz parent entities mandate SENT protocol compliance and multi-source qualification for platform awards, compressing supplier margins through technical commoditization. Tier-1 suppliers cluster around Stuttgart and Munich to synchronize sensor roadmaps with shared electric vehicle architectures.
- Industrial Machinery:Machine tool OEMs in Germany and Japan deploy high-resolution encoders for five-axis machining centers requiring sub-micron positioning accuracy. This segment demands extended temperature ratings over functional safety certification, creating parallel qualification tracks from automotive-grade production.
- Aerospace:Flight control surface position sensing requires DO-178C software assurance and extended environmental qualification cycles.
- Consumer Electronics:Smartphone camera optical image stabilization and gaming peripheral motion sensing drive high-volume, cost-optimized Hall Effect module demand.
Automotive OEMs dominate procurement volume while industrial machinery expands most quickly as reshoring initiatives accelerate capital equipment deployment.
Technology:
Interface migration from analog voltage outputs to digital protocols restructures competitive access across all end-use categories.
- Digital:Single Edge Nibble Transmission protocol outputs enable diagnostic fault reporting without secondary wiring harnesses, satisfying automotive OEM demands for reduced connector count and improved electromagnetic compatibility. Infineon Technologies and STMicroelectronics anchor digital sensor supply through captive ASIC fabrication.
- Analog:Legacy voltage and current loop outputs persist in industrial retrofit applications where controller area network gateway costs delay protocol migration. Steel mill automation buyers in Japan prioritize analog simplicity for 20-year equipment lifecycles.
- Wireless:Battery-free inductive power harvesting eliminates slip ring maintenance in rotating wind turbine nacelles and steel rolling mills.
- Hybrid:Combined analog-digital outputs bridge legacy system integration with future-proof diagnostic capability.
Analog technology retains the installed base while digital interfaces climb the fastest as automakers mandate SENT compliance for new platform awards.
Application:
Functional specialization fragments the market between rotational velocity measurement and linear position sensing with divergent accuracy requirements.
- Speed Measurement:Wheel-speed, crankshaft, and transmission input shaft monitoring for antilock braking and traction control demands timing precision below one microsecond. FDA scrutiny of centrifuge accuracy and EPA drive-by-wire emissions testing tighten calibration requirements across supplier bases.
- Control Systems:Closed-loop servo positioning in machine tools and robotics requires synchronized multi-axis feedback with nanosecond-level timestamp alignment. German automotive Tier-1 suppliers integrate control system sensors with electric powertrain thermal management modules.
- Position Sensing:Throttle plate, pedal, and valve lift measurement prioritize absolute accuracy over velocity resolution.
- Motion Detection:Vibration monitoring and predictive maintenance applications in industrial rotating machinery emphasize trend analysis over instantaneous precision.
Speed measurement anchors the volume base while control systems gain share at the steepest rate as electric vehicle powertrain complexity multiplies sensor counts per platform.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal vehicle emissions standards and India's PLI scheme for automotive components are redistributing speed sensor procurement across manufacturing clusters. Germany retains engineering density while Asian production incentives attract module assembly investment.
Germany
Automotive OEM procurement concentrates among Stuttgart and Munich engineering clusters sourcing ASIL-D certified Hall Effect modules for electric powertrain management. REACH restrictions on neodymium compounds force Tier-1 suppliers toward ferrite magnet alternatives with enlarged sensor footprints. KBA enforcement of EU Green Deal CO2 monitoring mandates precision wheel-speed feedback for regenerative braking calibration.
United States
NHTSA electronic stability control mandates sustain baseline automotive volume while FDA scrutiny of medical centrifuge accuracy opens premium Hall Effect channels. EPA drive-by-wire emissions testing protocols tighten calibration requirements for powertrain sensor suppliers. Detroit-area automotive engineering centers synchronize sensor roadmaps with shared electric vehicle platform architectures.
China
MIIT dual carbon goals accelerate electric vehicle platform deployment, multiplying sensor counts per powertrain. Domestic magnetic sensor manufacturers expand capacity for local OEM supply chains serving BYD and NIO production networks. Yangtze River Delta semiconductor fabrication clusters attract Hall Effect ASIC design investment.
Japan
METI industrial automation initiatives drive high-resolution encoder demand for five-axis machining centers requiring sub-micron positioning accuracy. Machine tool OEMs in Nagoya and Osaka prefectures prioritize 150°C continuous operation ratings over functional safety certification. JIS standards for rotating machinery sensors emphasize 20-year equipment lifecycle compatibility.
India
PLI scheme production-linked incentives cover sensor module assembly for Tier-1 suppliers establishing Chennai and Pune manufacturing footprints. Domestic automotive OEMs expand local sourcing requirements for antilock braking and traction control systems. CDSCO medical device regulations create parallel qualification tracks for centrifuge speed monitoring applications.
Speed Sensor Market Vendor Landscape
Listed leaders compete with private specialists across functional safety certification tiers, fragmenting competitive access by qualification depth rather than manufacturing scale alone. The vendor base separates into three strategic archetypes: diversified semiconductor conglomerates with captive fabrication, automotive-focused sensor specialists with OEM-integrated roadmaps, and industrial-grade module suppliers prioritizing temperature tolerance over ASIL ratings. M&A activity targets magnetic sensing ASIC design talent, while strategic partnerships bridge SENT protocol adoption gaps in legacy industrial retrofit markets.
Among German-based diversified technology groups, Robert Bosch GmbH and Continental AG occupy positions exemplifying vertical control from semiconductor wafer through module integration. Infineon Technologies AG anchors the magnetic sensing ASIC tier with in-house fabrication capabilities. STMicroelectronics NV represents the MEMS specialization vector with automotive-grade module differentiation.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Infineon Technologies AG |
| Robert Bosch GmbH |
| HELLA GmbH & Co. KGaA |
| STMicroelectronics NV |
| Continental AG |
| DENSO CORPORATION |
| Allegro MicroSystems Inc. |
| NXP Semiconductors NV |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four-month ISO 26262 validation cycles compress supplier pricing power while concentrating procurement leverage among Stuttgart and Munich engineering clusters capable of absorbing extended qualification timelines. This lead-time asymmetry rewards captive semiconductor fabrication with margin protection while squeezing mid-tier module assemblers competing for SENT-protocol platform awards.
Pricing Analysis
Certification level creates the primary spread between automotive-grade ASIL-D modules and industrial temperature-rated alternatives. Three-tier pricing structure across premium, standard, and economy levels segments by functional safety tier, with EU Green Deal emissions verification mandates supporting premium positioning for regenerative braking sensors. Cost compression in standard-grade Hall Effect channels intensifies because REACH ferrite substitution degrades magnetic sensitivity and enlarges package footprints. Automotive OEM procurement teams exhibit lowest price sensitivity due to platform-award consolidation, while industrial retrofit buyers prioritize analog simplicity over diagnostic depth.
Supply Chain Analysis
Neodymium and dysprosium concentrate in Chinese rare-earth processing facilities, exposing European magnetic sensor manufacturers to ECHA substance of very high concern listings. Hall plate semiconductor fabrication draws from Taiwan and South Korea wafer foundries, while ferrite magnet production rests on German and Japanese ceramic powder suppliers. Single-source vulnerability in rare-earth magnet sourcing forces material substitution toward alnico alternatives with inferior temperature coefficients. Distribution runs through automotive Tier-1 supplier clusters around Stuttgart and Munich for platform-synchronized delivery, with industrial channels feeding through Nagoya and Osaka machine tool OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SENT protocol standardization across Volkswagen, BMW, and Mercedes-Benz shared electric vehicle architectures creates platform-economics inflection, with interoperability mandates consolidating procurement leverage and compressing supplier differentiation on technical specifications alone.
For Market Incumbents: Secure captive Hall Effect ASIC fabrication capacity to defend margin position against fabless competitors facing 18-24 month ISO 26262 qualification barriers. Deepen backward integration into magnetic sensing semiconductor design talent pools, as mixed-signal engineer scarcity commands compensation premiums that strain R&D budgets at non-integrated suppliers. For New Entrants and Emerging Players: Anchor in wireless speed sensing for rotating machinery where slip ring elimination creates addressable white space in wind turbine nacelles and steel rolling mills. Target India's PLI scheme production-linked incentives for sensor module assembly in Chennai and Pune manufacturing footprints, leveraging domestic automotive OEM local sourcing expansion for antilock braking systems. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized magnetic sensing divisions lacking automotive functional safety certification. Long-term viability favors suppliers with dual qualification tracks spanning ASIL-D automotive and 150°C continuous industrial ratings. Watch FDA medical centrifuge accuracy mandate enforcement as inflection indicator for premium-priced high-reliability channel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| SENT Protocol Compliance Investment | Volkswagen, BMW, and Mercedes-Benz procurement teams mandate digital interface standardization for platform awards. |
| Backward Integration into ASIC Design | Captive semiconductor fabrication controls Hall plate quality from wafer through module integration. |
| Wireless Sensing Module Development | Battery-free inductive power harvesting eliminates slip ring maintenance in rotating wind turbine nacelles. |
| India Manufacturing Footprint Expansion | PLI scheme incentives cover sensor module assembly for Tier-1 suppliers in Chennai and Pune clusters. |
| Ferrite Magnet Material Requalification | REACH rare-earth restrictions force European suppliers toward enlarged sensor footprints with alternative magnetic materials. |
Methodological Framework
A standing panel of Tier-1 supplier procurement managers, OEM platform engineers, magnetic sensing ASIC designers, and industrial automation maintenance directors provided ongoing calibration across primary interview cycles. Secondary validation drew from KBA vehicle registration databases, ECHA substance restriction filings, NHTSA electronic stability control mandate documentation, and semiconductor trade flow records. Bottom-up sensor unit demand modeling triangulated against top-down automotive production forecasts across the analysis window.
Consistency checks validated volume and value outputs against IHS Markit vehicle production data, MIIT electric vehicle platform deployment disclosures, and METI industrial automation capital expenditure surveys. Segmentation modeling spanned product type, end user, technology interface, and application dimensions, with propulsion architecture and regional regulatory cluster treated as cross-cutting variables. CAGRs derived from log-linear trend fitting across the projection horizon, with electric vehicle sensor content per powertrain and REACH material substitution timelines as key forecast inputs.
Underlying assumptions cover SENT protocol adoption velocity, rare-earth magnet supply continuity, and ISO 26262 certification backlog clearance, with deviation risk concentrated in EU Green Deal enforcement timing and India PLI scheme incentive duration. Practitioners should keep alternative scenarios live as ECHA substance of very high concern listing expansion and MIIT dual carbon goal acceleration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Meteorological Devices Market
Sensors and Controls
Gyroscope Market
Sensors and Controls
US Acoustic Sensors Market
Sensors and Controls
Industrial Controllers Market
Sensors and Controls
Control Network Modules Market
Sensors and Controls
Connected Sensors Market
Sensors and Controls
Digital Automation Temperature Regulator Market
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
Russia Digital Thermometer Market
Sensors and Controls
Non-Dispersive Infrared Sensing Market
Sensors and Controls
Automotive Steering Sensors Market
Sensors and Controls
Germany Non-Contact Infrared Thermometer Market
Sensors and Controls
MEMS Accelerometer and Gyroscope Market
Sensors and Controls
Consumer Grade Electrochemical CO Sensor Market
Sensors and Controls
Magnetoresistive Sensors Market
Sensors and Controls
Micropump Market