
 Yaw Rate Sensors Market | 2026-2036
Yaw Rate Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Yaw Rate Sensors Market Analytics
Silicon MEMS is decoupling from legacy piezoelectric architectures in mid-range automotive stability modules, reducing unit costs while preserving angular velocity accuracy. Bosch Sensortec GmbH leverages captive MEMS foundry capacity to anchor supply for European OEM programs. STMicroelectronics NV competes through 3D-stacked gyroscope designs that extend temperature resilience into aerospace tiers. Continental AG dominates integrated sensor fusion modules where yaw rate feeds directly into brake-by-wire controllers.
A yaw rate sensor measures angular velocity around a vehicle's vertical axis, typically employing Coriolis-force detection in vibrating MEMS structures or Sagnac-phase interferometry in fiber-optic rings to resolve rotation rates below one degree per second. Automotive stability control represents the dominant application, where real-time yaw data triggers differential braking to prevent skids and rollovers. Microelectromechanical Systems occupy the largest value pool due to semiconductor-scale manufacturing, while Optical Sensors command premium positioning in aerospace systems where bias stability requirements exceed military-grade thresholds. Solid-State Sensors are gaining fastest in robotics navigation as warehouse automation platforms demand compact, drift-resistant inertial units.
NHTSA electronic stability control mandates and UN ECE R13-H braking performance standards shape product qualification timelines and test-protocol rigor for suppliers targeting transatlantic OEM contracts. The EU Green Deal's embedded carbon tracking requirements are beginning to penetrate automotive supplier audits, pressuring sensor manufacturers to document foundry energy intensity. Stakeholders must monitor how sensor fusion integration levels redefine tier-1 supplier value capture as OEMs internalize multi-axis inertial measurement units.
Market Dynamics
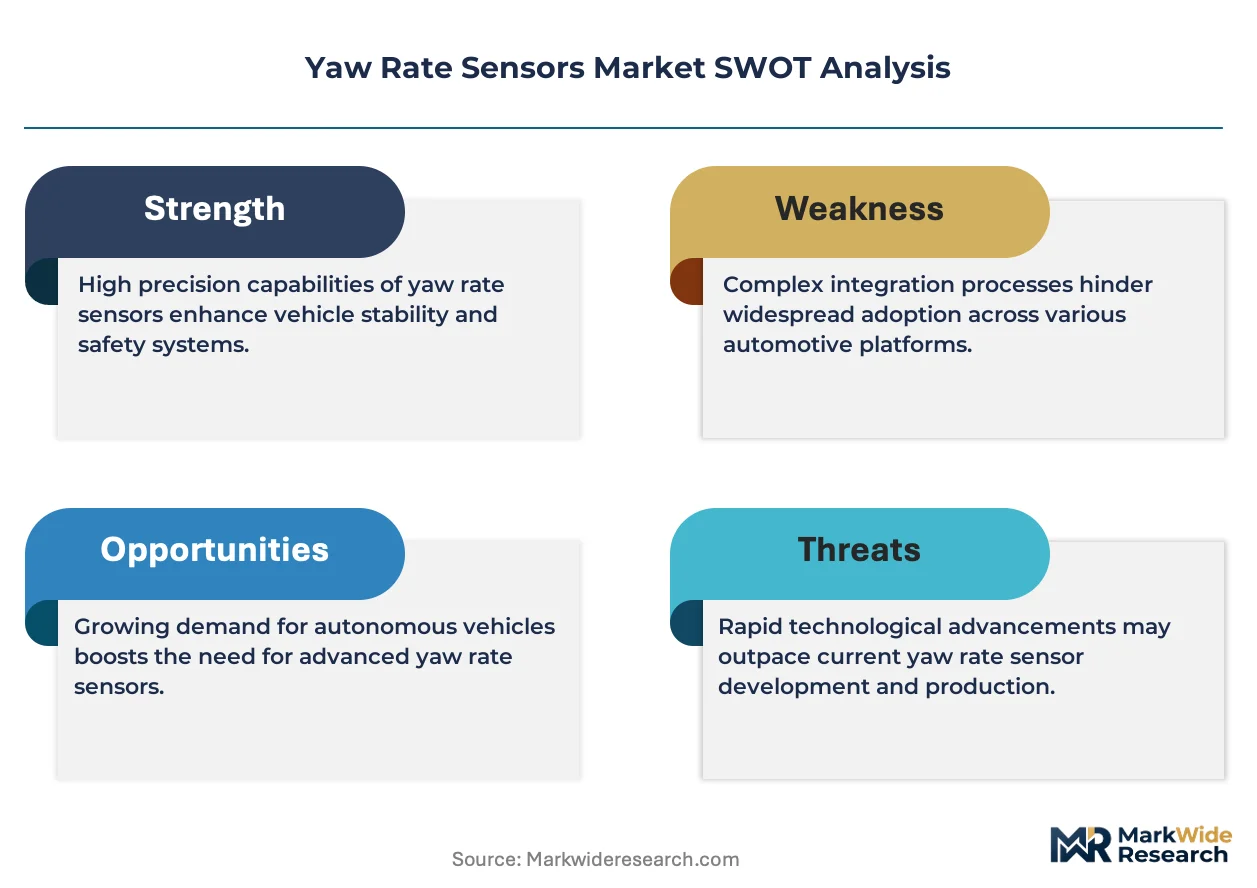
Automotive OEMs are consolidating yaw rate sensing into multi-axis inertial measurement units, compressing supplier margins while demanding higher functional safety certification under ISO 26262. This integration wave favors semiconductor foundries with captive MEMS capacity over discrete sensor specialists.
Growth Catalysts
- NHTSA ESC Mandates:US federal requirements for electronic stability control on light vehicles sustain baseline demand for yaw rate modules in passenger car platforms.
- Silicon MEMS Cost Curves:Semiconductor-scale manufacturing of vibrating structure gyroscopes reduces per-unit costs for mid-range automotive stability systems.
- German Tier-1 Clustering:Dense concentration of automotive sensor foundries around Stuttgart and Munich accelerates prototyping cycles for European OEM programs.
Market Restraints
- Raw Material Concentration:Specialty silicon-on-insulator wafers depend on a limited set of European and Japanese substrate suppliers, creating input cost volatility.
- Functional Safety Certification Burden:ISO 26262 ASIL-D qualification timelines extend 18-24 months, freezing out smaller module integrators from OEM direct contracts.
- Optical Gyroscope Substitution:Fiber-optic ring laser gyros retain aerospace and defense applications where MEMS bias stability falls short, capping addressable market expansion.
Strategic Opportunities
- Autonomous Mobile Robotics:Warehouse automation platforms in North America and Europe require compact, drift-resistant inertial units for navigation without GPS dependency.
- EU Green Deal Embedded Carbon Tracking:Supplier audit requirements for foundry energy intensity create first-mover advantage for MEMS manufacturers with documented renewable power sourcing.
- Sensor Fusion Module Integration:Brake-by-wire and steer-by-wire architectures enable tier-1 suppliers to capture value through combined yaw-rate/acceleration/steering-angle packages.
Industry Challenges
- MEMS Process Engineering Talent Scarcity:Specialized expertise in resonant structure design and wafer-level packaging concentrates at a handful of European and North American research institutions.
- Legacy Vehicle Integration Complexity:Retrofit of yaw rate data into older CAN bus architectures requires protocol translation layers that degrade signal latency.
- Cross-Border Certification Harmonization:Divergent test protocols between NHTSA FMVSS 126 and UN ECE R13-H force dual qualification runs for transatlantic suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yaw Rate Sensors Market |
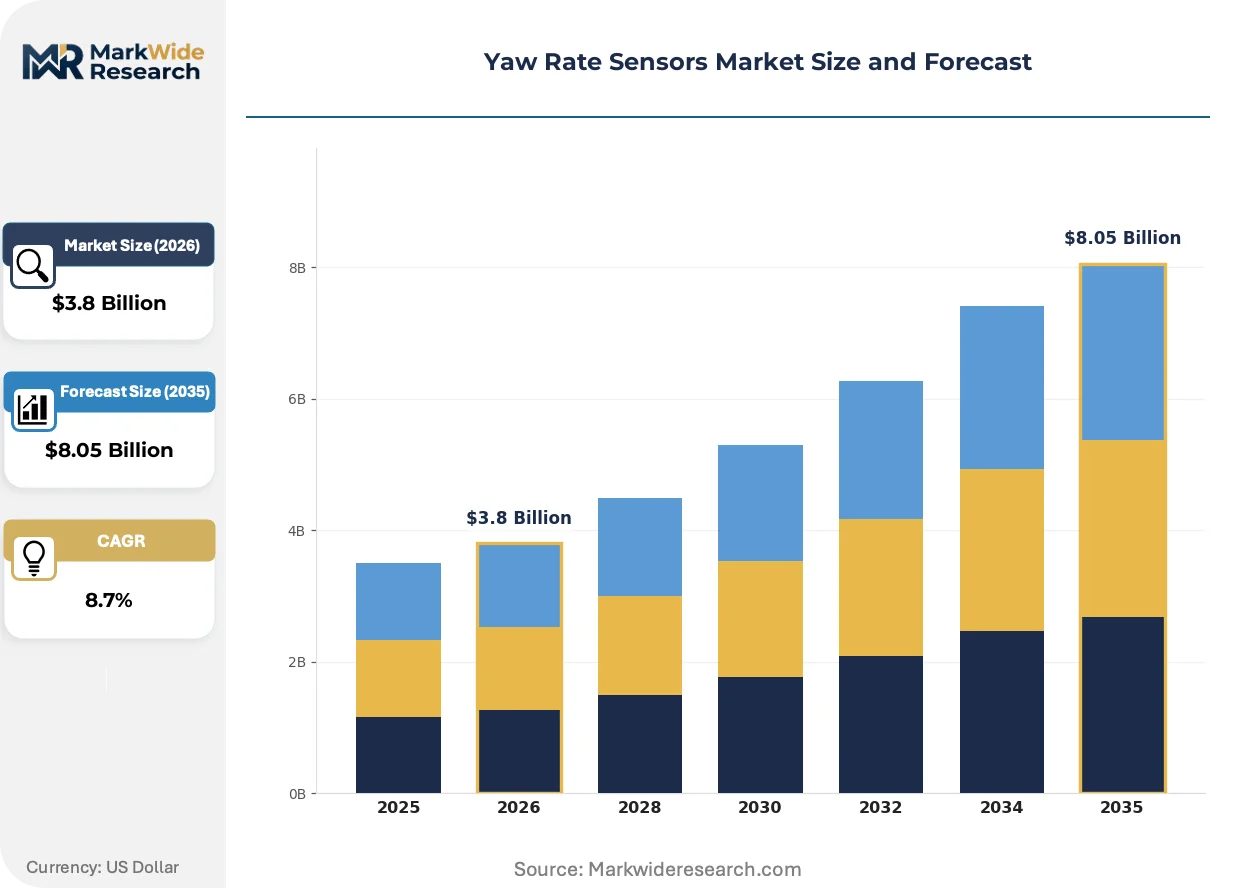
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Microelectromechanical Systems, Optical Sensors, Solid-State Sensors, Capacitive Sensors Application: Automotive Stability Control, Robotics Navigation, Aerospace Systems, Agricultural Machinery End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Research Institutions Integration Level: Standalone Sensors, Integrated Systems, Sensor Fusion, Embedded Solutions |
| Companies Covered | Bosch Sensortec GmbH, STMicroelectronics NV, Continental AG, Epson Europe Electronics GmbH, Baumer Group, ZF Friedrichshafen AG, DIS Sensors, Silicon Sensing Systems, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yaw Rate Sensors Market Evolving Landscape
Yaw rate sensing is migrating from discrete components toward embedded inertial cores within domain controllers. This architectural shift compresses the addressable market for standalone modules while elevating software compensation algorithms as competitive differentiators.
MEMS vibrating ring gyroscopes are converging with 3D-stacked accelerometer dice in single-package inertial measurement units. Automotive tier-1 suppliers are adopting these fused designs for electronic stability programs to reduce wiring harness complexity and ECU footprint. The structural consequence is converging with brake-by-wire system architectures that demand synchronized multi-axis motion data within sub-millisecond latency budgets.
UN ECE R13-H braking performance standards are tightening test-protocol rigor for yaw rate sensor accuracy under split-friction conditions. European OEMs must demonstrate that stability control modules maintain angular velocity resolution below 0.5 degrees per second across temperature extremes. Passenger car platforms targeting transatlantic export are responding by sourcing dual-redundant sensor channels from qualified tier-1 integrators.
Buyer concentration among top-ten automotive OEMs is compressing component sourcing cycles from annual to quarterly negotiations. Direct procurement teams at Volkswagen Group and Stellantis are unbundling sensor modules from historical brake system contracts, creating spot-market exposure for MEMS foundries. This disintermediation is most visible in Germany, where Bosch Sensortec and Continental AG now compete for discrete yaw rate die supply separate from fused system integration.
Yaw Rate Sensors Market Segmentation
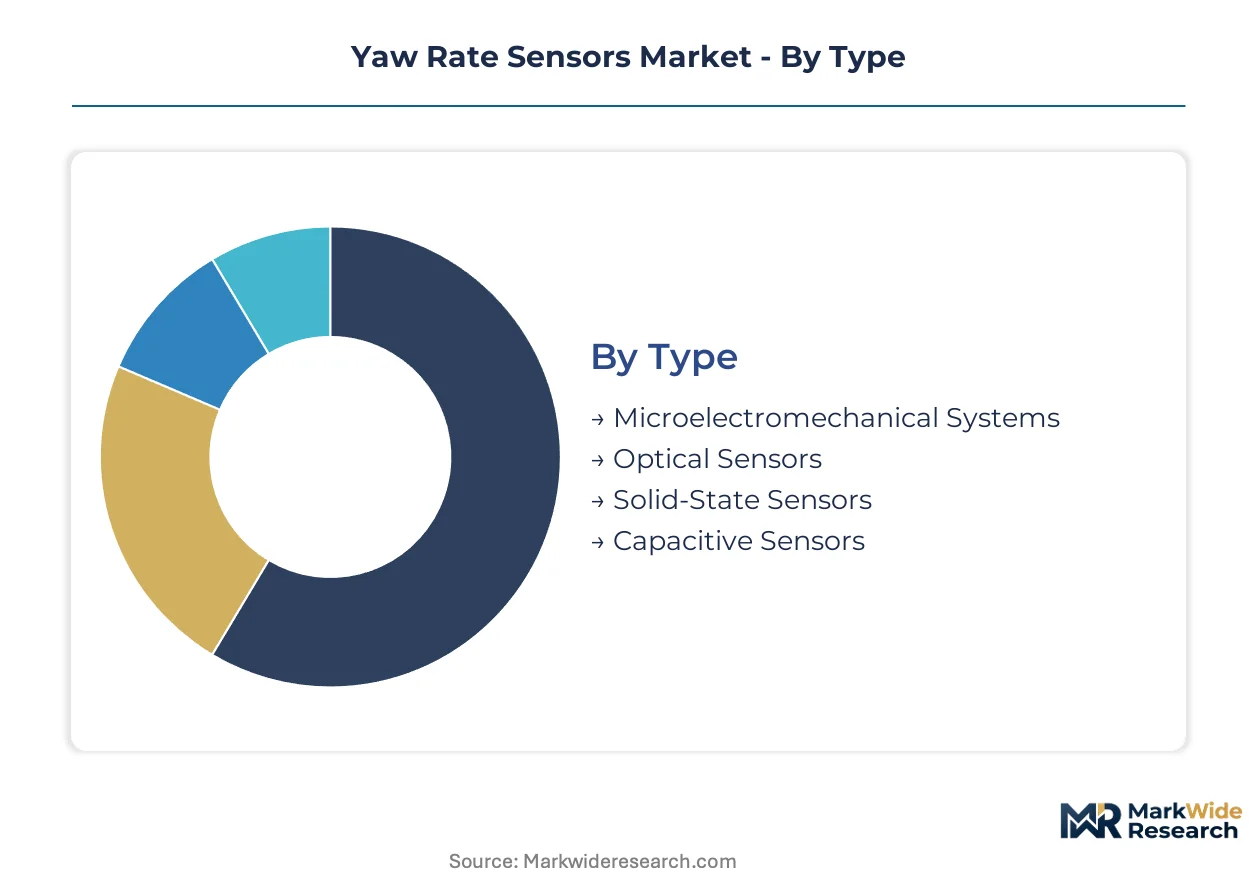
Yaw rate sensor procurement patterns diverge sharply across technology types and integration architectures. Tier-1 automotive suppliers prioritize MEMS cost curves against aerospace bias stability requirements, while robotics integrators trade absolute precision for compact form factors.
Type:
Customization intensity spans from commodity silicon MEMS to mission-specific optical gyros, with standardization deepest in automotive-grade vibrating structure designs.
- Microelectromechanical Systems:Vibrating ring or tuning-fork gyroscopes fabricated on silicon-on-insulator wafers exploit semiconductor-scale economics. Automotive OEMs in Germany source these in highest volumes for electronic stability programs where angular velocity resolution below one degree per second satisfies FMVSS 126 thresholds.
- Optical Sensors:Fiber-optic ring laser gyros and interferometric designs measure Sagnac-phase shifts with bias stability exceeding military-grade specifications. Aerospace systems in France and the United States demand these for navigation-grade inertial units where MEMS drift rates prove unacceptable.
- Solid-State Sensors:Piezoelectric and Coriolis-force devices without moving parts serve robotics navigation in warehouse automation platforms across North America.
- Capacitive Sensors:Electrostatic force-rebalance architectures populate low-cost agricultural machinery stability systems in Brazil and India.
Leading the category by volume: Microelectromechanical Systems. Expanding most quickly: Solid-State Sensors.
Application:
Application segmentation tracks functional safety certification tiers, with automotive stability control demanding ISO 26262 ASIL-D compliance against robotics navigation's looser reliability requirements.
- Automotive Stability Control:Electronic stability programs deploy yaw rate data for differential braking intervention during skid events. NHTSA mandates sustain baseline demand across passenger car platforms in the United States.
- Robotics Navigation:Autonomous mobile robots in warehouse automation require compact inertial units for dead-reckoning without GPS dependency.
- Aerospace Systems:Flight control and navigation platforms in commercial aviation and defense specify bias stability thresholds that only optical gyroscopes achieve.
- Agricultural Machinery:Tractor stability and implement guidance systems in precision farming adopt MEMS-based yaw sensing for rollover prevention.
Dominant revenue concentration: Automotive Stability Control. Steepest expansion trajectory: Robotics Navigation.
End User:
End user segmentation reflects procurement power asymmetries, with OEM direct sourcing compressing tier-1 margins while aftermarket providers capture retrofit premiums.
- OEMs:Volkswagen Group and Stellantis procurement teams now unbundle yaw rate modules from historical brake system contracts, creating quarterly negotiation cycles.
- Tier-1 Suppliers:Continental AG and Bosch Sensortec integrate discrete yaw rate die into fused sensor packages for brake-by-wire architectures.
- Aftermarket Providers:Retrofit specialists serve legacy vehicle fleets requiring CAN bus protocol translation layers.
- Research Institutions:European and North American universities advance resonant structure design for next-generation MEMS architectures.
Highest procurement volume: OEMs. Fastest-growing engagement: Research Institutions.
Integration Level:
Integration segmentation captures architectural migration from discrete components toward domain-consolidated inertial cores, with margin structures inverting accordingly.
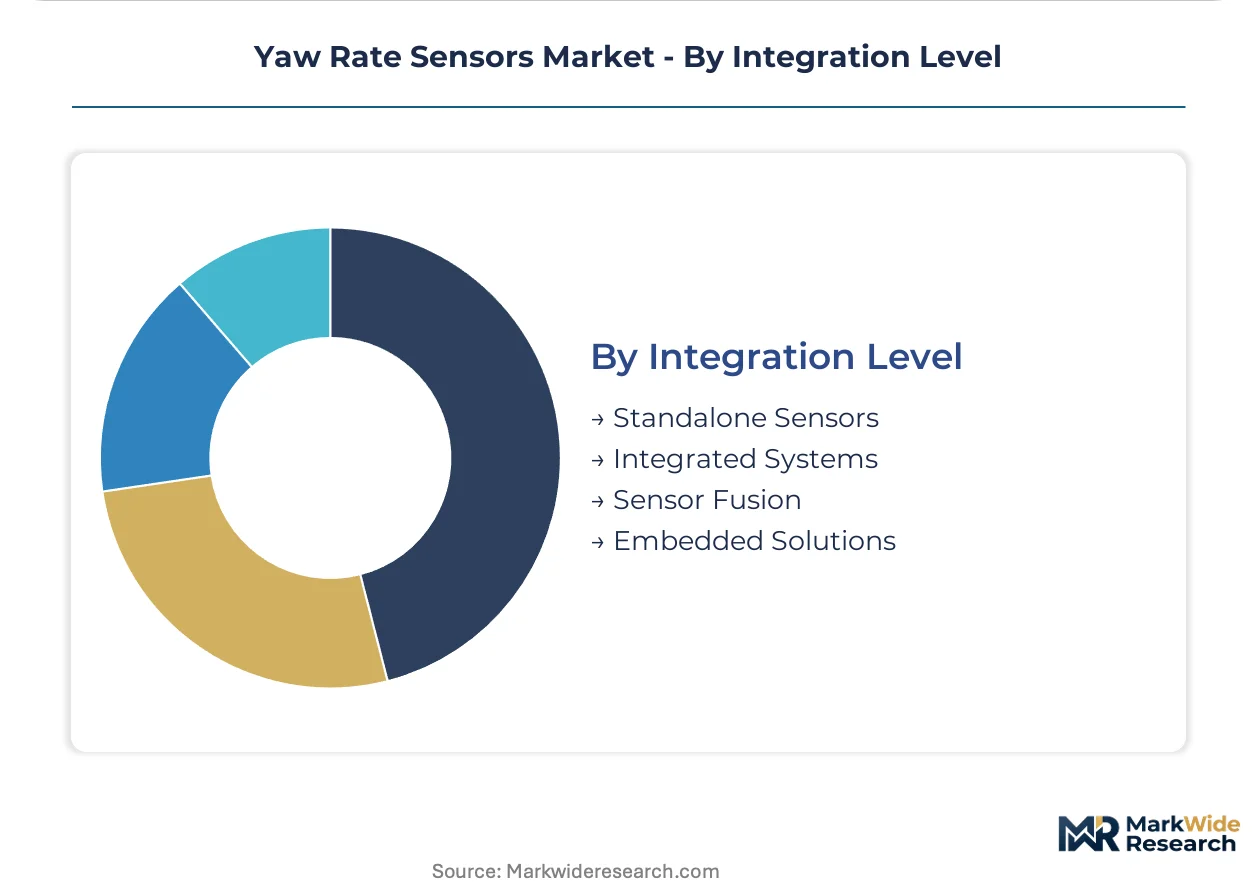
- Standalone Sensors:Discrete yaw rate modules persist in legacy platforms and cost-sensitive agricultural machinery where wiring harness complexity remains acceptable.
- Integrated Systems:Multi-axis inertial measurement units combine gyroscope and accelerometer dice in single packages, reducing ECU footprint for European OEM stability programs.
- Sensor Fusion:Brake-by-wire and steer-by-wire architectures synchronize yaw rate with steering angle and lateral acceleration data within sub-millisecond latency budgets.
- Embedded Solutions:Inertial cores migrate directly into domain controllers, compressing the addressable market for standalone modules while elevating software compensation algorithms.
Current volume leader: Integrated Systems. Gaining share fastest: Embedded Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement concentrates in Germany, where dense tier-1 supplier clustering around Stuttgart and Munich compresses prototyping cycles for electronic stability programs. Foundry capacity for silicon MEMS yaw rate sensors tracks this demand geography, with qualification protocols tightening under transatlantic regulatory divergence.
United States
NHTSA mandates on electronic stability control sustain baseline demand for yaw rate modules across passenger car platforms. FMVSS 126 performance standards enforce angular velocity resolution thresholds that OEMs must demonstrate during split-friction testing. Detroit-area automotive engineering centers coordinate tier-1 sourcing cycles that have shifted from annual to quarterly negotiations.
Germany
Volkswagen Group and Stellantis procurement teams unbundle yaw rate sensors from historical brake system contracts, creating spot-market exposure for MEMS foundries. EU Green Deal embedded carbon tracking requirements penetrate supplier audits, pressuring manufacturers to document foundry energy intensity. The Stuttgart-Munich corridor anchors captive MEMS capacity for European OEM stability programs.
Japan
Precision robotics navigation for warehouse automation platforms drives demand for compact, drift-resistant inertial units. METI industrial standards shape test-protocol rigor for automotive-grade sensor exports. Nagoya-area automotive suppliers integrate yaw rate data into brake-by-wire architectures with sub-millisecond latency requirements.
China
Domestic EV platforms accelerate procurement of multi-axis inertial measurement units for stability control systems. MIIT vehicle safety regulations tighten qualification timelines for sensor suppliers targeting local OEM contracts. Yangtze River Delta semiconductor foundries expand MEMS capacity to serve regional automotive clusters.
South Korea
Hyundai-Kia procurement programs source fused sensor packages combining yaw rate with steering-angle and acceleration data. MFDS automotive safety standards align with UN ECE frameworks for export-oriented production. Seoul Capital Area engineering centers coordinate tier-1 integration of inertial cores into domain controllers.
Yaw Rate Sensors Market Competitive Landscape
Capacity expansion dominates the current landscape as semiconductor foundries invest in captive MEMS fabrication lines to secure automotive OEM contracts. The vendor structure tiers between integrated tier-1 system suppliers and discrete sensor specialists, with margin compression accelerating consolidation. Three archetypes define positioning: captive foundry operators with backward integration into wafer processing, multi-axis fusion module integrators, and discrete component specialists serving cost-sensitive agricultural segments. M&A activity and strategic partnerships between brake system architects and MEMS fabricators represent the dominant competitive vectors reshaping supply relationships.
Among European-based integrated suppliers, Continental AG and Bosch Sensortec GmbH occupy positions anchored by proximity to German OEM engineering centers. STMicroelectronics NV exemplifies the foundry-operator archetype through 3D-stacked gyroscope designs that extend temperature resilience specifications. These three entities represent divergent strategic postures: system-level integration versus semiconductor-scale manufacturing specialization versus combined hardware-software fusion capabilities.
| Leading Market Players |
|---|
| Bosch Sensortec GmbH |
| STMicroelectronics NV |
| Continental AG |
| Epson Europe Electronics GmbH |
| Baumer Group |
| ZF Friedrichshafen AG |
| DIS Sensors |
| Silicon Sensing Systems |
| Denso Corporation |
| Others |
Value Network & Pricing Analysis
Captive MEMS foundry operations anchor supply positioning for tier-1 automotive suppliers while simultaneously preserving pricing power through ISO 26262 certification moats. This backward integration into wafer processing insulates Bosch Sensortec and STMicroelectronics from spot-market volatility in specialty silicon-on-insulator substrates, creating cost advantages that discrete sensor specialists cannot replicate under quarterly OEM procurement cycles.
Pricing Analysis
High-volume MEMS die shipments to German automotive OEMs compress margins at the commodity end, while aerospace-grade optical gyroscopes sustain premium positioning through bias stability specifications exceeding military thresholds. Price differentiation rests on functional safety certification tiers and captive foundry capacity, with ISO 26262 ASIL-D qualification creating entry barriers that protect incumbent pricing power. Cost compression in mid-range automotive stability modules intensifies as Volkswagen Group and Stellantis disaggregate sensor procurement from brake system contracts. Aftermarket retrofit providers exhibit highest price sensitivity due to CAN bus protocol translation complexity, whereas aerospace integrators demonstrate lowest sensitivity given mission-critical performance requirements.
Supply Chain Analysis
Regional distribution centers in Stuttgart and Munich operate as hub-and-spoke nodes for European OEM just-in-time programs, compressing logistics lead times for qualified tier-1 integrators. Manufacturing concentrates in Germany, Japan, and China, with Yangtze River Delta foundries expanding MEMS capacity to serve domestic EV platforms. Raw material flows draw from European and Japanese specialty silicon-on-insulator wafer suppliers, creating input concentration risk. Single-source vulnerability in substrate supply chains exposes tier-2 module integrators to cost volatility. Distribution runs through direct OEM procurement channels and tier-1 system supplier networks, with spot-market exposure growing as historical brake system bundling dissolves.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where NHTSA electronic stability control mandates and UN ECE R13-H braking standards erect regulatory moats that freeze out undercapitalized entrants lacking eighteen-to-twenty-four-month ISO 26262 qualification timelines.
For Market Incumbents: Lock in captive MEMS foundry capacity through equipment purchase agreements with European substrate suppliers to defend against specialty silicon-on-insulator input volatility. Deepen sensor fusion integration capabilities for brake-by-wire architectures before OEMs internalize multi-axis inertial measurement units, preserving value capture as standalone module markets contract.
For New Entrants and Emerging Players: Warehouse automation integrators represent the most penetrable channel partner type for compact solid-state yaw rate sensors, as robotics navigation demands drift-resistant inertial units without GPS dependency. Target North American and European warehouse automation platforms where functional safety requirements remain less stringent than automotive tiers, offering software compensation algorithms as differentiated service bundles alongside hardware supply.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by brake system architects seeking captive MEMS supply, with financial sponsors capturing value through roll-up of discrete sensor specialists facing margin compression. Long-term viability favors foundry operators with documented renewable power sourcing under EU Green Deal audit requirements. Watch for NHTSA mandate expansion into commercial vehicle segments as inflection signal for volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive MEMS Foundry Expansion | Secures silicon-on-insulator wafer supply for German OEM qualification programs under tightening ISO 26262 timelines. |
| Sensor Fusion Module Integration | Captures value through combined yaw-rate/acceleration packages for Continental AG brake-by-wire architectures. |
| EU Green Deal Compliance Documentation | Creates first-mover advantage in OEM supplier audits tracking embedded carbon in foundry energy intensity. |
| Robotics Navigation Partnership | Opens warehouse automation segment where solid-state sensors displace MEMS for compact drift-resistant inertial units. |
| Dual-Channel Redundancy Qualification | Meets UN ECE R13-H split-friction testing requirements for transatlantic passenger car export platforms. |
Research Methodology
Multi-period observation of MEMS foundry capacity utilization, OEM procurement cycle compression, and regulatory qualification timelines anchored the trend analysis, supplemented by interviews with tier-1 supplier procurement directors, automotive platform engineers, MEMS process engineering specialists, and aftermarket retrofit distributors. Secondary validation drew from NHTSA FMVSS 126 enforcement data, UN ECE R13-H braking standard documentation, SEC filings of semiconductor manufacturers, and vehicle production databases. Bottom-up sensor shipment estimates triangulated against top-down automotive stability control system penetration assumptions.
Segment-weighting across technology types, application tiers, and integration architectures structured the analytical framework across the analysis window. Modeled dimensions included sensor technology, automotive versus aerospace versus robotics end-use, standalone versus fused versus embedded integration levels, and regional production cluster sourcing patterns. CAGRs derived from fitted growth curves incorporating MEMS cost curve trajectories, NHTSA mandate expansion scenarios, and warehouse automation platform deployment rates.
Caveats apply where raw material concentration in European and Japanese silicon-on-insulator suppliers, regulatory divergence between NHTSA and UN ECE test protocols, or faster-than-anticipated OEM internalization of sensor fusion could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Voltage Sensor Market
Sensors and Controls
Global Tactile Sensor Market
Sensors and Controls
Global Digital Temperature and Humidity Sensor Market
Sensors and Controls
Global Ultra Low Power MEMS Sensors Market
Sensors and Controls
Acoustic Breathing Sensor Market
Sensors and Controls
Piezoelectric Polymers Market
Sensors and Controls
Europe Bulk Acoustic Wave Sensors Market
Sensors and Controls
MEMS Energy Harvesting Devices Market
Sensors and Controls
Thermal Flow Meter Market
Sensors and Controls
Capacitive Tactile Sensor Market
Sensors and Controls
Thermography Condition Monitoring Equipment Market
Sensors and Controls
TMAH Concentration Monitor Market
Sensors and Controls
Digital Array Microphone Market
Sensors and Controls
3D Profile Sensors Market
Sensors and Controls
Battery Monitor Market
Sensors and Controls
Temperature Monitoring System Market