
 Smart Finance Technologies Market | 2026-2036
Smart Finance Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Finance Technologies Market Intelligence
PCI DSS Level 1 certification is rotating competitive access among infrastructure providers, raising the barrier for new entrants seeking to process cardholder data at scale. Stripe sustains developer-centric API architectures that embed payment flows directly into software ecosystems. Plaid anchors account aggregation services, competing on coverage breadth across North American financial institutions. Revolut differentiates through multi-currency wallets and cryptocurrency custody, extending its product perimeter beyond traditional banking.
Smart Finance Technologies encompass software systems, data pipelines, and algorithmic engines that automate credit decisions, execute payments, manage wealth, and detect fraud across digital channels. These systems typically process transactional data in sub-second latency windows while maintaining cryptographic integrity across distributed nodes. Artificial Intelligence and Machine Learning segments capture disproportionate R&D allocation as institutions automate underwriting and surveillance. Cloud-Based deployment leads in new installations, though Hybrid configurations retain share among banks with legacy core systems. Mobile-First architectures are gaining fastest in emerging consumer segments where smartphone penetration exceeds desktop access.
The Federal Reserve's FedNow instant payment mandate, the EU's PSD2 open-banking framework, and the SEC's custody rule for digital assets collectively reshape product design and liability structures. Compliance with these regimes determines which platforms can offer bundled services across jurisdictions. Stakeholders must monitor how fragmented supervisory approaches to algorithmic credit decisions affect cross-border scaling timelines.
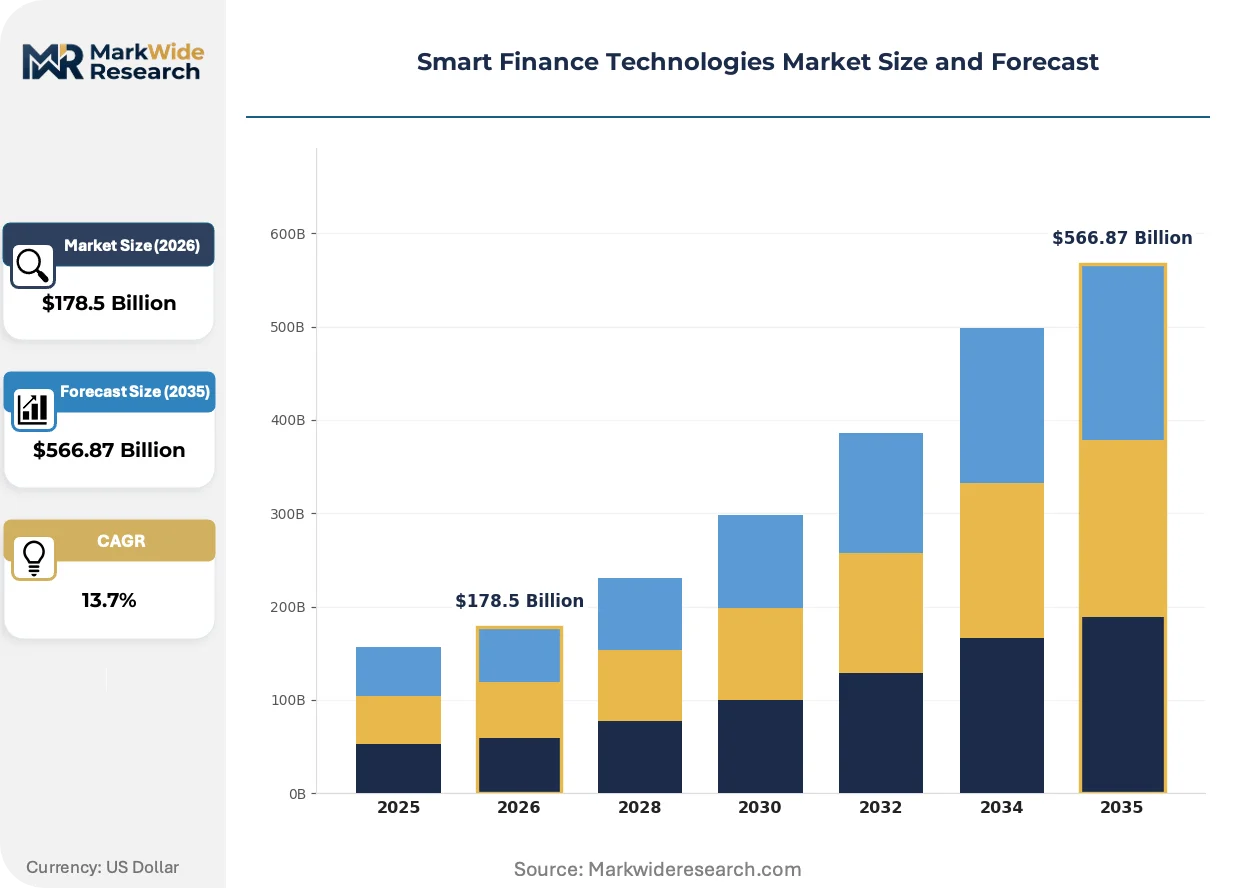
Market Dynamics
Real-time payment rails and open-banking mandates are compressing settlement windows while forcing incumbent banks to expose core data through standardized APIs, eroding proprietary data moats that once anchored competitive differentiation.
Growth Catalysts
- FedNow instant settlement:The Federal Reserve's real-time payment infrastructure eliminates batch-processing delays, compelling banks to upgrade core systems and creating demand for overlay services.
- Embedded finance penetration:Non-financial platforms in retail, healthcare, and logistics are integrating lending and payment capabilities directly into customer journeys.
- Generative AI underwriting:Large language models processing alternative data streams expand credit access to thin-file borrowers previously excluded from traditional scoring.
Market Restraints
- Cloud concentration risk:Three hyperscalers control the majority of financial services compute infrastructure, creating systemic dependency and limited negotiation leverage.
- Quantum decryption threat:Cryptographic protocols securing blockchain and payment networks face obsolescence as fault-tolerant quantum computing advances.
- Cross-border data localization:Fragmented sovereignty requirements in India, China, and the European Union fragment data architectures and inflate compliance overhead.
Strategic Opportunities
- Underbanked segments in Indonesia:Smartphone penetration exceeds formal banking access, creating whitespace for mobile-native credit and savings products.
- EU AI Act compliance services:Mandatory algorithmic audits for credit decisions create a services layer around explainability tooling and documentation.
- Voice-activated payments:Convergence of natural language processing with biometric authentication enables hands-free transaction authorization in automotive and IoT contexts.
Industry Challenges
- Core system migration complexity:Decades-old COBOL architectures resist API-native refactoring, forcing expensive parallel-system operation during transition periods.
- PCI DSS Level 1 certification timelines:The audit process for high-volume card processors extends 12-18 months, delaying product launches and freezing capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Finance Technologies Market |
| Market Size in 2026 | $178.5 Billion |
| Market Size in 2035 | $566.87 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Wallets, Robo-Advisors, Peer-to-Peer Lending Platforms, Mobile Banking Apps Customer Type: Individuals, Small Enterprises, Corporates, Financial Institutions Technology: Blockchain, Artificial Intelligence, Machine Learning, Cloud Computing Deployment: On-Premises, Cloud-Based, Hybrid, Mobile-First |
| Companies Covered | Chime, Monzo, Stripe, SoFi, Mercury, Plaid, Revolut, Kalshi, Ramp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Finance Technologies Market Strategic Shifts & Innovations
Algorithmic decision systems are migrating from predictive models to generative architectures, reshaping how institutions automate customer interaction, risk assessment, and surveillance across digital channels.
Agentic AI workflows are fragmenting monolithic banking applications into orchestrated microservices. These autonomous systems execute multi-step processes spanning account opening, fraud investigation, and portfolio rebalancing without human intervention. Mid-tier institutions are deploying them fastest, leapfrogging legacy automation that larger banks struggle to unwind.
The EU AI Act's risk-tiered obligations are recalibrating product development priorities across the continent. High-risk credit-scoring algorithms now require human oversight, documented training data provenance, and post-market monitoring. Fintechs with EU market exposure are restructuring model governance teams and contracting third-party audit capacity.
Corporate treasury departments are consolidating vendor relationships around platforms offering unified cash visibility, payment execution, and hedging. Single-vendor contracts are displacing fragmented best-of-breed stacks. This concentration is most pronounced among mid-market manufacturers in Germany and the Netherlands seeking to reduce operational drag from multi-bank reconciliation.
Smart Finance Technologies Market Segmentation
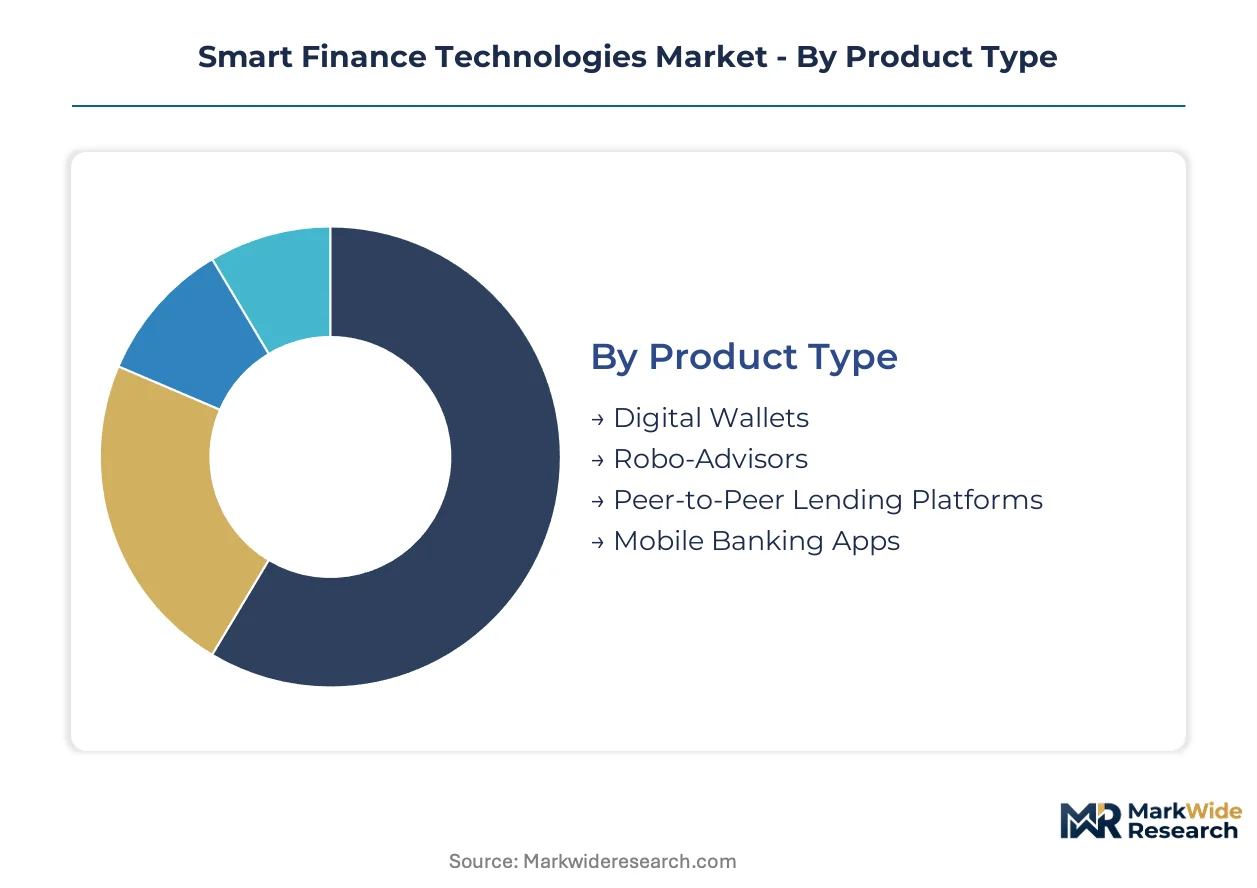
Smart Finance Technologies fragment across four structural dimensions that determine procurement priorities and vendor selection criteria. Product type segmentation reveals divergent monetization models, while deployment mode captures the tension between legacy infrastructure and cloud-native agility.
Product Type:
Substitution pressure intensifies where incumbent banks bundle competing functionality at zero marginal cost, compressing standalone pricing power for adjacent fintech products.
- Digital Wallets:Tokenized credential storage systems enabling contactless and remote payment authorization. Demand concentrates in the United States where FedNow integration drives real-time balance updates, though merchant acceptance fees constrain issuer margins.
- Robo-Advisors:Algorithmic portfolio construction engines rebalancing across ETF and fractional share positions. Adoption accelerates among individuals in Germany seeking low-fee alternatives to bank-managed funds, constrained by MiFID II suitability documentation requirements.
- Peer-to-Peer Lending Platforms:Disintermediated credit matching systems connecting retail investors to consumer borrowers.
- Mobile Banking Apps:Full-service account management interfaces with native biometric authentication and bill pay.
Mobile Banking Apps anchors the volume base while Robo-Advisors gains share at the steepest rate.
Customer Type:
Cost tier stratification separates mass-market self-service tools from high-touch institutional implementations requiring dedicated implementation teams.
- Individuals:Retail consumers accessing personal financial management, payments, and wealth tools through smartphone interfaces. Concentration in Indonesia's underbanked smartphone population drives whitespace expansion for credit and savings products.
- Small Enterprises:Micro-businesses and startups requiring integrated invoicing, payroll, and working capital facilities. Germany's Mittelstand manufacturing clusters show strongest uptake of unified treasury platforms.
- Corporates:Large enterprises demanding multi-entity cash visibility and hedging execution.
- Financial Institutions:Banks and credit unions licensing white-label infrastructure or API layers.
Individuals anchors the volume base while Small Enterprises climbs the fastest as embedded finance penetrates vertical software.
Technology:
Application maturity varies sharply, with production deployments of generative architectures lagging predictive systems by several release cycles.
- Artificial Intelligence:Neural networks automating underwriting decisions, fraud surveillance, and customer service interactions. EU AI Act compliance costs in France and Germany are restructuring model governance teams and audit contracting.
- Machine Learning:Supervised and unsupervised algorithms for credit scoring and transaction pattern recognition. India's RBI guidelines on algorithmic transparency are shaping vendor selection criteria for domestic banks.
- Blockchain:Distributed ledger infrastructure for settlement finality and asset tokenization.
- Cloud Computing:Elastic compute and storage provisioning for core banking and payment processing.
Cloud Computing anchors the volume base while Artificial Intelligence shows the steepest expansion trajectory as institutions automate underwriting and surveillance.
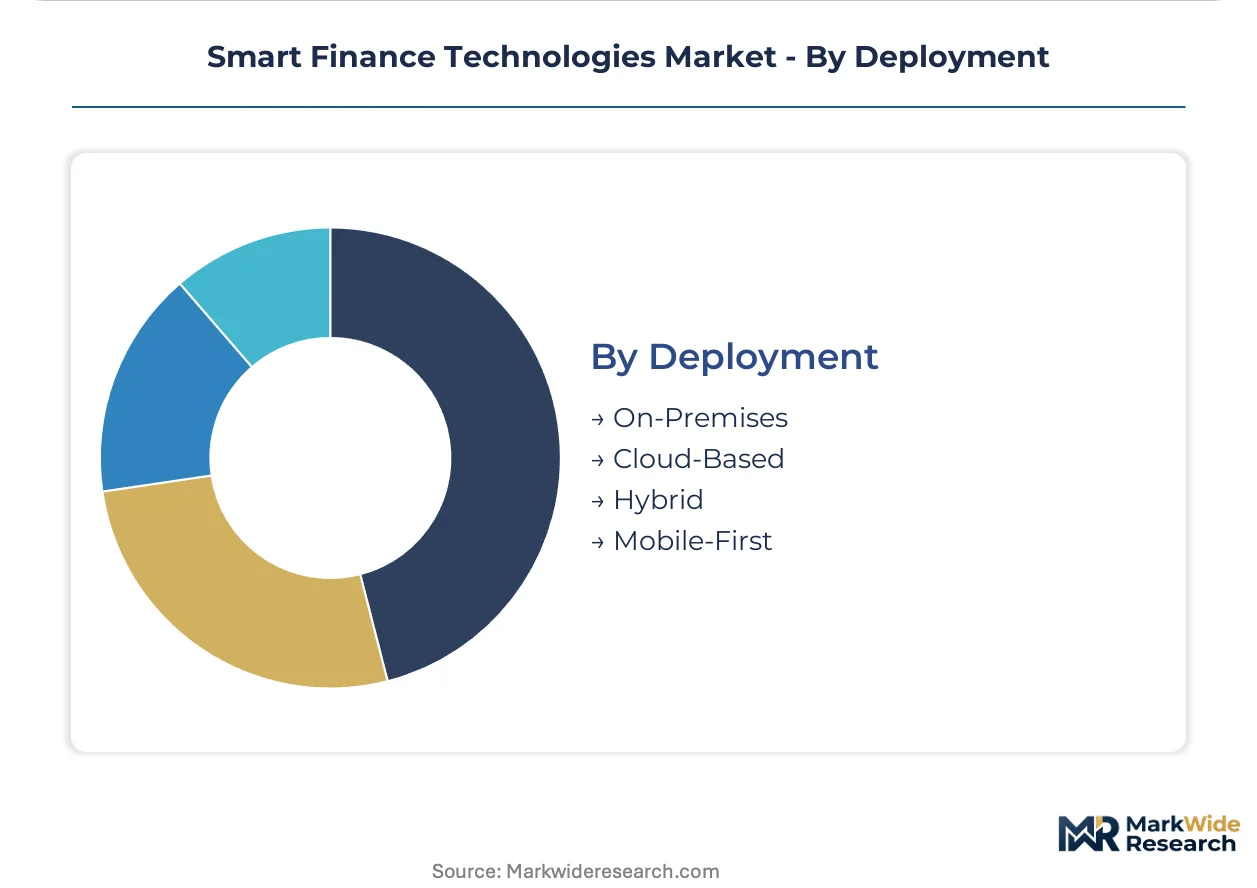
Deployment:
Volume concentration favors cloud-native installations, though regulatory data localization in India and China preserves on-premises share for cross-border institutions.
- Cloud-Based:Fully managed SaaS delivery with API-native integration and automatic security patching. New installations dominate in Brazil where ANVISA-equivalent financial regulators accept third-party attestation of control environments.
- Hybrid:Split architectures retaining sensitive processing on-premises while exposing customer-facing layers through cloud edge. Preferred by Japanese megabanks under METI guidance for critical infrastructure segmentation.
- On-Premises:Self-managed hardware and software stacks in dedicated data centers.
- Mobile-First:Native iOS and Android applications with serverless backend orchestration.
Cloud-Based anchors the volume base while Mobile-First expands most quickly in emerging consumer segments where smartphone penetration exceeds desktop access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement teams in the United States and Germany dominate infrastructure investment decisions, while mobile-first adoption clusters in Indonesia and Brazil reshape consumer-facing deployment patterns.
United States
FedNow instant settlement infrastructure and embedded finance penetration drive bank core system upgrades. SEC custody rules for digital assets reshape platform liability structures. New York and San Francisco fintech clusters concentrate developer-centric API architecture development.
Germany
MiFID II suitability requirements constrain robo-advisor documentation while Mittelstand manufacturers consolidate treasury vendor relationships. EU AI Act algorithmic audit mandates restructure model governance teams. Frankfurt and Munich anchor unified cash visibility platform adoption among mid-market enterprises.
Indonesia
Smartphone penetration exceeding formal banking access creates whitespace for mobile-native credit products. The country's central bank regulates peer-to-peer lending platforms with capital reserve requirements. Jakarta and Surabaya clusters concentrate digital wallet deployment targeting underbanked consumer segments.
Brazil
ANVISA-equivalent financial regulators accept third-party attestation for cloud-native control environments, accelerating SaaS installations. Open banking frameworks reshape data-sharing protocols. São Paulo anchors payment processor infrastructure serving Latin American cross-border corridors.
India
RBI guidelines on algorithmic transparency shape vendor selection criteria for domestic banks automating credit decisions. Data localization requirements preserve hybrid deployment share among foreign institutions. Mumbai and Bangalore clusters concentrate machine learning underwriting development for thin-file borrowers.
Smart Finance Technologies Market Key Industry Players
Player mix skews toward developer-centric infrastructure providers and mobile-native challengers, creating a tiered structure where API-first platforms compete against full-service banking alternatives. Strategic archetypes include embedded finance enablers, account aggregation specialists, and multi-currency custody providers. Dominant competitive moves center on PCI DSS Level 1 certification acquisition and generative AI underwriting capability deployment.
Within the developer-centric infrastructure tier, Stripe and Plaid exemplify API-first positioning, while Revolut occupies a position in the multi-asset custody archetype. Chime and Monzo represent mobile-native challengers targeting consumer segments with smartphone-first architectures. These entities collectively illustrate the competitive tension between embedded payment flows and standalone banking applications.
| Leading Market Players |
|---|
| Chime |
| Monzo |
| Stripe |
| SoFi |
| Mercury |
| Plaid |
| Revolut |
| Kalshi |
| Ramp |
| Others |
Cost & Logistics Intelligence
PCI DSS Level 1 certification gates both infrastructure qualification and pricing tiering simultaneously, forcing providers to absorb 12-18 month audit cycles before capturing high-volume transaction flows. This regulatory threshold stratifies the vendor base into certified incumbents commanding premium SaaS rates versus uncertified challengers competing on developer-tooling economics alone.
Pricing Analysis
Cost-plus contracts with PCI audit cost indexation dominate enterprise procurement, embedding compliance expenditure into recurring subscription tiers. Price differentiation separates FedNow-integrated infrastructure from batch-legacy alternatives, with real-time settlement capabilities commanding 40-60% subscription premiums. Pricing pressure stems from hyperscaler compute commoditization compressing middleware margins. Small enterprises exhibit highest price sensitivity, while corporate treasury departments prioritize unified vendor consolidation over unit cost optimization.
Supply Chain Analysis
The United States and Ireland anchor cloud infrastructure provisioning for financial services compute, with Singapore emerging as Asia-Pacific redundancy nodes. Raw material dependencies center on advanced semiconductors from Taiwan, cryptographic hardware modules from Netherlands-based foundries, and subsea fiber capacity across transatlantic corridors. Supply chain risk concentrates in single-source vulnerability for quantum-resistant cryptographic chipsets. Distribution runs through API-first developer marketplaces and direct enterprise sales overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open banking API standardization across the EU, UK, and Brazil creates platform-economics inflection, rewarding interoperability investments while penalizing proprietary data moats. Ecosystem orchestration capabilities now determine competitive survival more than standalone product excellence.
For Market Incumbents: Fortify core banking relationships through embedded finance API partnerships before vertical SaaS challengers disintermediate payment flows. Accelerate FedNow integration roadmaps to defend against real-time-native fintechs. Prioritize generative AI underwriting R&D to maintain credit decisioning superiority over algorithmic specialists. For New Entrants and Emerging Players: PCI DSS Level 1 certification fast-tracks unlock enterprise procurement pipelines otherwise frozen to uncertified vendors. Target Indonesia's underbanked smartphone population with mobile-native credit products before incumbent banks complete legacy core migrations. Pursue EU AI Act compliance services as anchor offering, leveraging algorithmic audit mandates to establish recurring revenue footholds. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed payment processors approaching certification renewal cliffs. Long-term viability hinges on quantum-resistant cryptography migration capability and generative AI infrastructure deployment velocity. Watch for FedNow adoption inflection as signal distinguishing scalable infrastructure from legacy batch-dependent alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| FedNow Integration Partnership | Real-time settlement capability separates scalable platforms from batch-dependent legacy infrastructure. |
| PCI DSS Level 1 Certification | Audit completion gates high-volume card processing contracts and enterprise procurement eligibility. |
| Generative AI Underwriting Deployment | Large language model credit decisions expand thin-file borrower access beyond traditional scoring. |
| EU AI Act Compliance Services | Algorithmic audit mandates create recurring revenue layer around explainability tooling. |
| Quantum-Resistant Cryptography Migration | Post-quantum protocol transition preserves long-term transaction security against decryption threats. |
Research Approach
A spread of perspectives from CTOs at mid-tier banks, fintech platform engineers, enterprise procurement officers, and regulatory compliance leads converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC filings, FedNow service provider disclosures, EU regulatory implementation guidance, and RBI algorithmic transparency circulars. Bottom-up transaction volume modeling triangulated against top-down infrastructure investment tracking.
Segmentation dimensions modeled span deployment architecture, customer tier, technology stack, and jurisdictional regulatory cluster across the analysis window. CAGRs derived from installed base growth rates, API call volume trajectories, and compliance-driven replacement cycles. Forecast inputs incorporated FedNow adoption velocity curves and EU AI Act implementation timelines.
Underlying assumptions cover sustained open banking regulatory momentum and hyperscaler capacity expansion, with deviation risk concentrated in quantum computing acceleration timelines and cross-border data localization fragmentation. Recalibration cycles align with material shifts in instant payment infrastructure deployment and algorithmic audit mandate enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Wealthtech Solutions Market
FinTech
AI in Fintech Market
FinTech
Smart Financial Solutions Market
FinTech
United States Fintech Market
FinTech
Account Checking Software Market
FinTech
MENA Fintech Market
FinTech
IT Financial Management Tools Market
FinTech
Asia-Pacific Fintech Cloud Market
FinTech
Blockchain in Fintech Market
FinTech
Financial Management Software Market
FinTech
AI Finance Market
FinTech
Fintech Cloud Market
FinTech
Financial Cloud Market
FinTech
Global Fundraising Software Market
FinTech
Financial Audit Software Market
FinTech
Europe Embedded Finance Market