
 Global Bitcoin and Cryptocurrency Wallets Market | 2026-2036
Global Bitcoin and Cryptocurrency Wallets Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bitcoin and Cryptocurrency Wallets Market Foresight
Multi-source security procurement is broadening across the wallet ecosystem as institutional custodians diversify beyond single-vendor dependencies. Ledger SAS anchors its position through proprietary secure element chip architecture. Coinbase Global, Inc. competes by integrating custody with exchange liquidity. Trezor differentiates through open-source firmware transparency and community-verified security audits.
A cryptocurrency wallet constitutes a cryptographic key management system that stores private keys enabling blockchain transaction signing, typically employing elliptic curve cryptography with 256-bit entropy for Bitcoin addresses. Its commercial purpose centers on enabling digital asset custody, transfer authorization, and portfolio management for both individual and institutional holders. Hardware wallets command premium positioning due to air-gapped cold storage architectures, while mobile wallets capture volume through embedded exchange integrations and biometric authentication pipelines. Institutional trader segments concentrate margin pools in multi-signature custody arrangements requiring HSM-backed key sharding.
Europe's MiCA framework mandates reserve transparency and operational resilience standards for wallet providers serving EU residents. Japan's FSA enforces strict segregation of exchange and custody functions, compelling providers to obtain specialized registration. The SEC in the United States continues evaluating whether wallet-integrated staking services constitute securities offerings. Stakeholders must monitor how jurisdictional licensing fragmentation affects cross-border product deployment and compliance cost allocation.
Market Dynamics
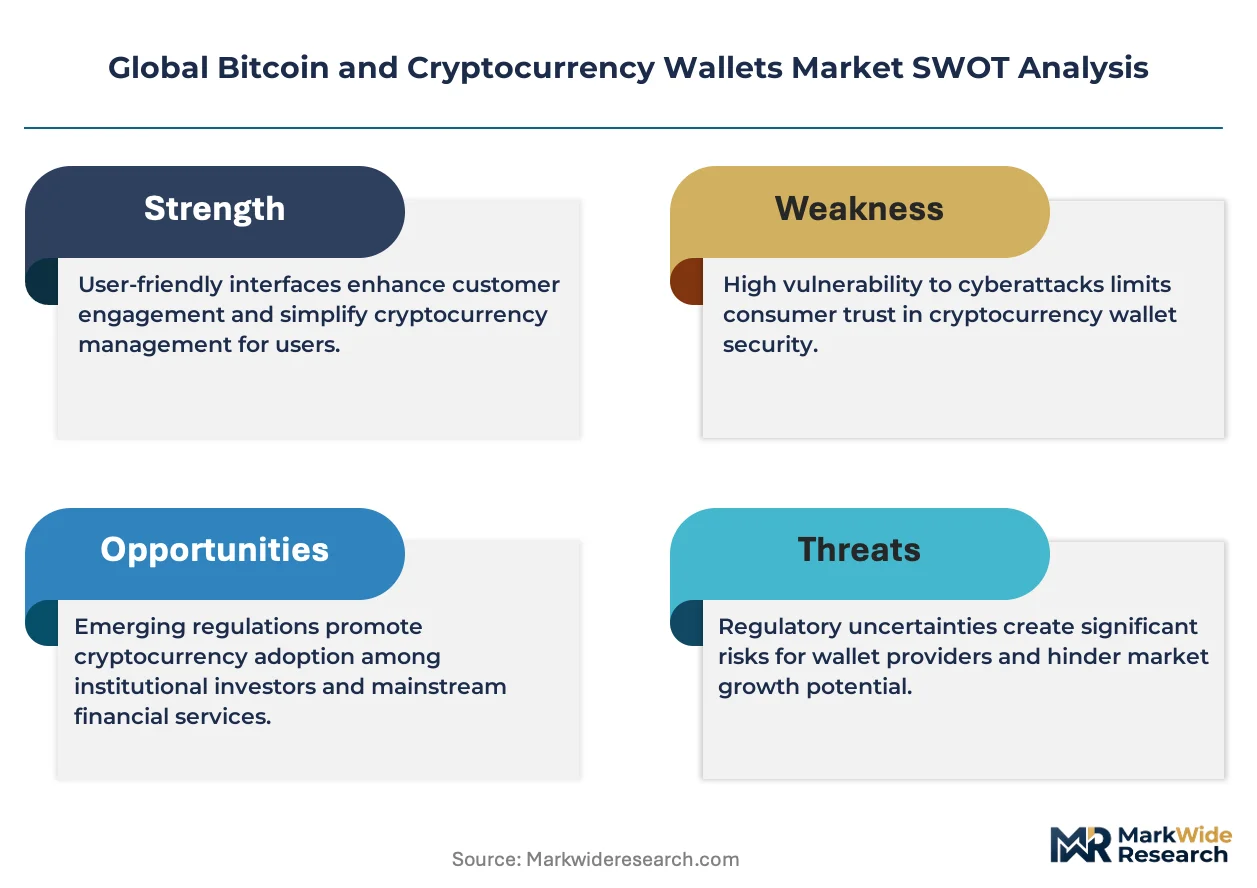
Institutional custody requirements are fragmenting wallet architectures as MiCA, Japan's FSA guidelines, and US SEC evaluations force providers into jurisdiction-specific compliance stacks rather than unified global platforms.
Growth Catalysts
- MiCA Reserve Transparency Mandates:European wallet providers must maintain auditable cold storage reserves, accelerating hardware wallet procurement by institutional custodians seeking compliant infrastructure.
- Japan METI Cold Storage Standards:Institutional-grade hardware wallets gain mandatory certification pathways, creating regulated demand channels for air-gapped key management systems.
- Biometric Authentication Pipelines:Mobile wallet developers integrate fingerprint and facial recognition layers, expanding retail accessibility in underbanked Southeast Asian markets.
Market Restraints
- Secure Element Chip Concentration:Proprietary semiconductor fabrication for hardware wallet security modules concentrates among limited foundry capacity in East Asian supply chains.
- Elliptic Curve Cryptography Standardization Lags:Cross-chain signature compatibility remains technically constrained by competing curve implementations across Bitcoin, Ethereum, and alternative layer-1 protocols.
- SEC Staking Service Evaluation:Ongoing securities classification uncertainty surrounding wallet-integrated yield features freezes product roadmap decisions for US-facing providers.
Strategic Opportunities
- Multi-Signature HSM-Backed Custody:Institutional traders require hardware security module key sharding, opening specialized infrastructure services for exchange-adjacent wallet operators.
- Southeast Asia Retail Penetration:Software wallet adoption accelerates among unbanked populations in Indonesia, Vietnam, and the Philippines following regional fintech licensing liberalization.
- Open-Source Firmware Verification:Community-audited security architectures attract privacy-conscious holders seeking transparent key generation protocols outside proprietary black-box systems.
Industry Challenges
- Cross-Border Licensing Fragmentation:Wallet providers face divergent registration requirements across EU member states, Japanese FSA categories, and US state-level money transmitter frameworks.
- Quantum-Resistant Cryptography Migration:Engineering teams must retrofit elliptic curve foundations with post-quantum signature schemes without compromising backward compatibility or user experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bitcoin and Cryptocurrency Wallets Market |
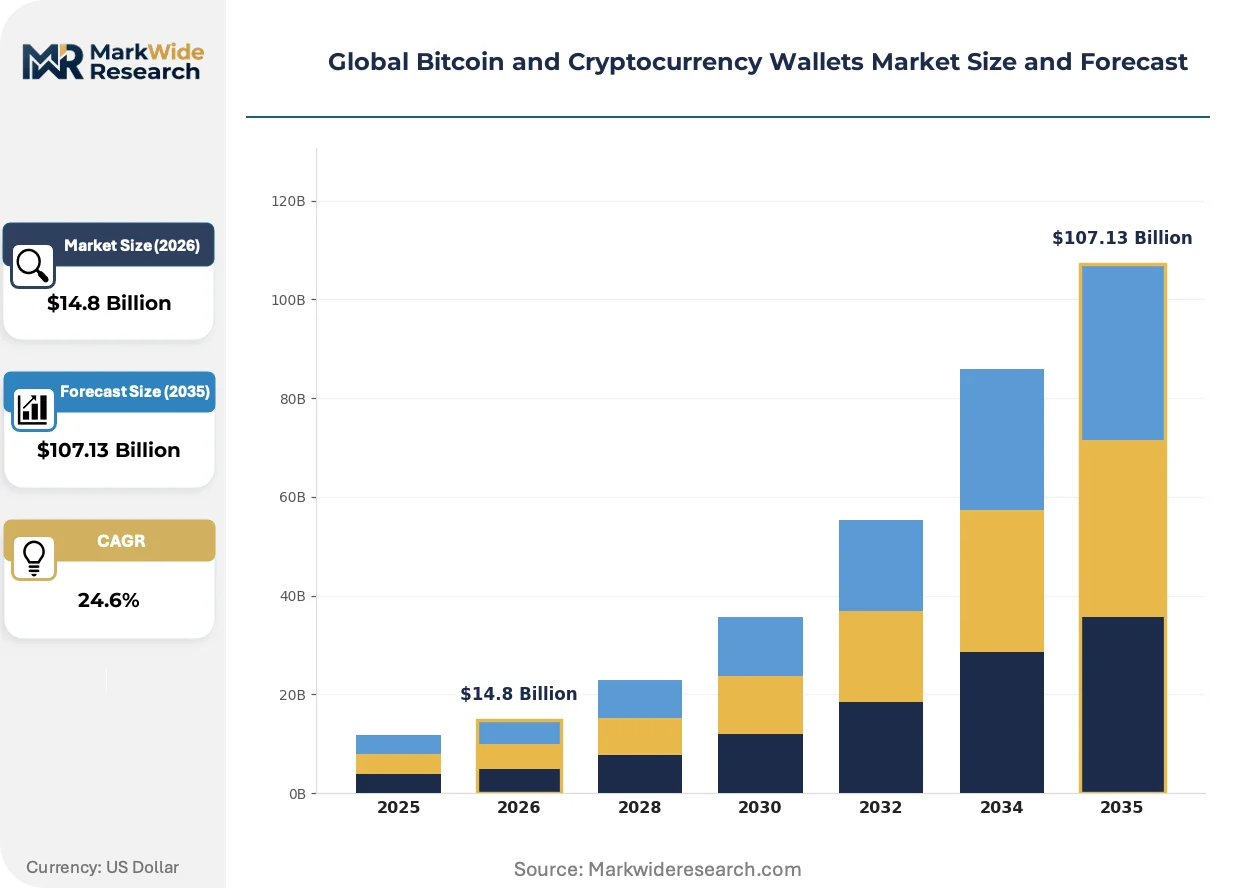
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $107.13 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Wallet Type: Hardware, Software, Web, Mobile Cryptocurrency Supported: Bitcoin, Ethereum, Ripple, Litecoin, Cardano User Category: Retail Investors, Institutional Traders, Miners, Developers, Payment Processors Security Feature: Multi-Signature, Two-Factor Authentication, Biometric Access, Cold Storage, Encryption |
| Companies Covered | Binance, Coinbase Global, Inc., Ledger SAS, Trezor, BitGo, BitPay, Exodus Movement, Inc., Zengo Ltd., Blockchain.com, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bitcoin and Cryptocurrency Wallets Market Shifts & Advancements
Self-custody tooling is bifurcating between institutional-grade multi-signature infrastructure and streamlined mobile interfaces, with regulatory compliance emerging as the primary architectural constraint rather than technical capability.
Social recovery mechanisms using Shamir secret sharing are decentralizing key backup responsibility across trusted contacts rather than centralized seed phrase storage. Retail adopters in emerging markets favor this model over hardware wallet ownership due to cost barriers. The architecture compresses single points of failure while introducing new trust assumptions around recovery participant selection.
Europe's MiCA framework mandates operational resilience testing and incident reporting protocols for wallet providers serving EU residents. Custody services must segregate client assets and maintain transparent reserve documentation. Hardware wallet manufacturers with EU manufacturing footprints adapt certification processes faster than importers relying on third-country production.
Institutional procurement of wallet infrastructure now separates custody from exchange execution, with prime brokerage models unbundling these functions. Multi-signature arrangements requiring geographically distributed key holders displace single-vendor dependencies among hedge funds and asset managers. This pattern concentrates most visibly in Japanese institutional markets where FSA segregation rules predate comparable US or European enforcement intensity.
Global Bitcoin and Cryptocurrency Wallets Market Segmentation
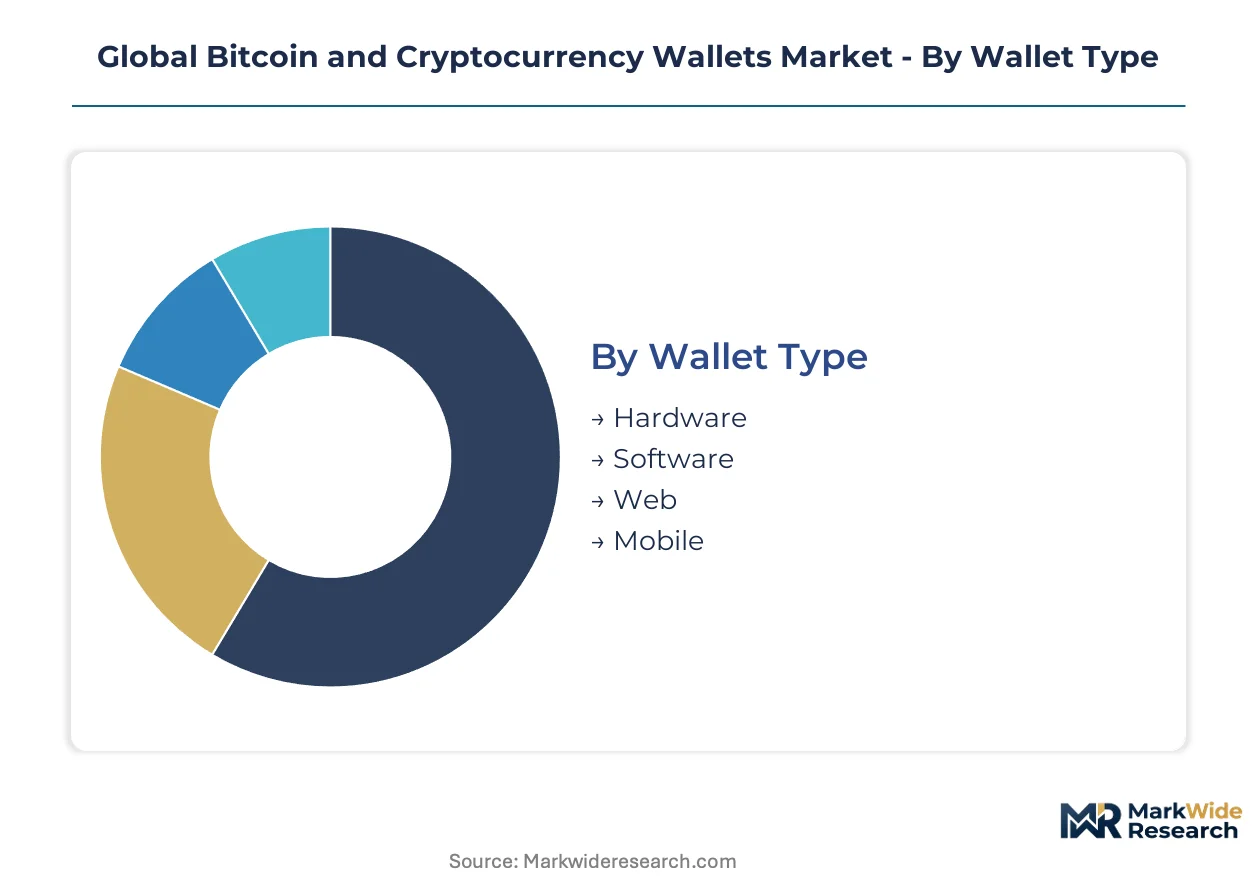
Wallet segmentation determines which compliance frameworks apply to specific product architectures. Hardware and institutional-facing solutions carry heavier certification burdens than retail software alternatives. Understanding these boundaries clarifies where development resources concentrate and which regulatory pathways gate market entry.
Wallet Type:
Hardware wallets require CE marking under EU electronics directives plus METI certification for Japanese institutional sales, while software variants face lighter registration under money transmitter frameworks.
- Hardware:Air-gapped devices with secure element chips isolate private keys from network-connected systems. Japanese institutional custodians procure these under METI cold storage standards, with demand concentrating in Tokyo's asset management district.
- Software:Desktop applications manage keys through encrypted local storage without dedicated hardware. Southeast Asian retail investors in Indonesia and Vietnam adopt these for cost accessibility amid fintech licensing liberalization.
- Web:Browser-accessible interfaces store encrypted keys on provider servers. These face heightened scrutiny under MiCA operational resilience mandates for EU-resident services.
- Mobile:Smartphone applications integrate biometric authentication pipelines with embedded exchange connectivity. These capture volume in underbanked Philippine and Indonesian markets where smartphone penetration exceeds traditional banking access.
Mobile wallets sit at the top of the volume ranking, with hardware climbing the fastest on institutional procurement.
Cryptocurrency Supported:
Asset coverage shapes wallet architecture complexity, with multi-chain implementations demanding broader cryptographic libraries than Bitcoin-native designs.
- Bitcoin:The foundational cryptocurrency employs elliptic curve secp256k1 signatures with 256-bit entropy. Hardware manufacturers optimize secure element firmware specifically for Bitcoin's UTXO model, creating performance advantages in institutional cold storage deployments.
- Ethereum:Account-based architecture with smart contract interaction requirements demands more complex transaction parsing. Wallet developers in Singapore and Switzerland prioritize Ethereum compatibility for DeFi-integrated custody solutions.
- Ripple:Consensus ledger with distinct node validation requirements necessitates separate key derivation paths. Institutional payment corridors in Southeast Asian banking networks drive specialized wallet implementations.
- Litecoin:Scrypt-based mining derivative shares Bitcoin's UTXO structure with faster block confirmation. Retail-focused software wallets include Litecoin for portfolio diversification without significant engineering overhead.
- Cardano:Proof-of-stake consensus with native staking functionality creates regulatory ambiguity under SEC evaluation of yield-bearing wallet features. Product teams defer full Cardano integration pending US securities classification clarity.
Bitcoin retains the deepest installed base, though Ethereum expands most quickly on DeFi custody demand.
User Category:
Customer type determines security architecture investment, with institutional segments requiring HSM-backed infrastructure that retail users rarely access.
- Retail Investors:Individual holders prioritize accessibility over advanced security, driving mobile wallet adoption with biometric convenience layers. Southeast Asian markets show particular concentration as first-time crypto participants seek low-friction onboarding.
- Institutional Traders:Hedge funds and asset managers mandate multi-signature arrangements with geographically distributed key holders. Japanese FSA segregation rules force these entities toward specialized custody providers separate from exchange execution platforms.
- Miners:Block reward recipients require wallet solutions handling high-frequency small-value transactions with minimal fee overhead. Cold storage integration matters less than rapid liquidity conversion for operational expense coverage.
- Developers:Technical users demand testnet compatibility and raw transaction construction capabilities. Open-source firmware transparency attracts this segment toward community-audited security architectures.
- Payment Processors:Merchant-facing services require instant confirmation pipelines with fiat settlement integration. MiCA reserve transparency mandates impose additional compliance layers on EU-serving payment infrastructure.
Retail investors dominate transaction volume, while institutional traders gain share fastest on prime brokerage unbundling.
Security Feature:
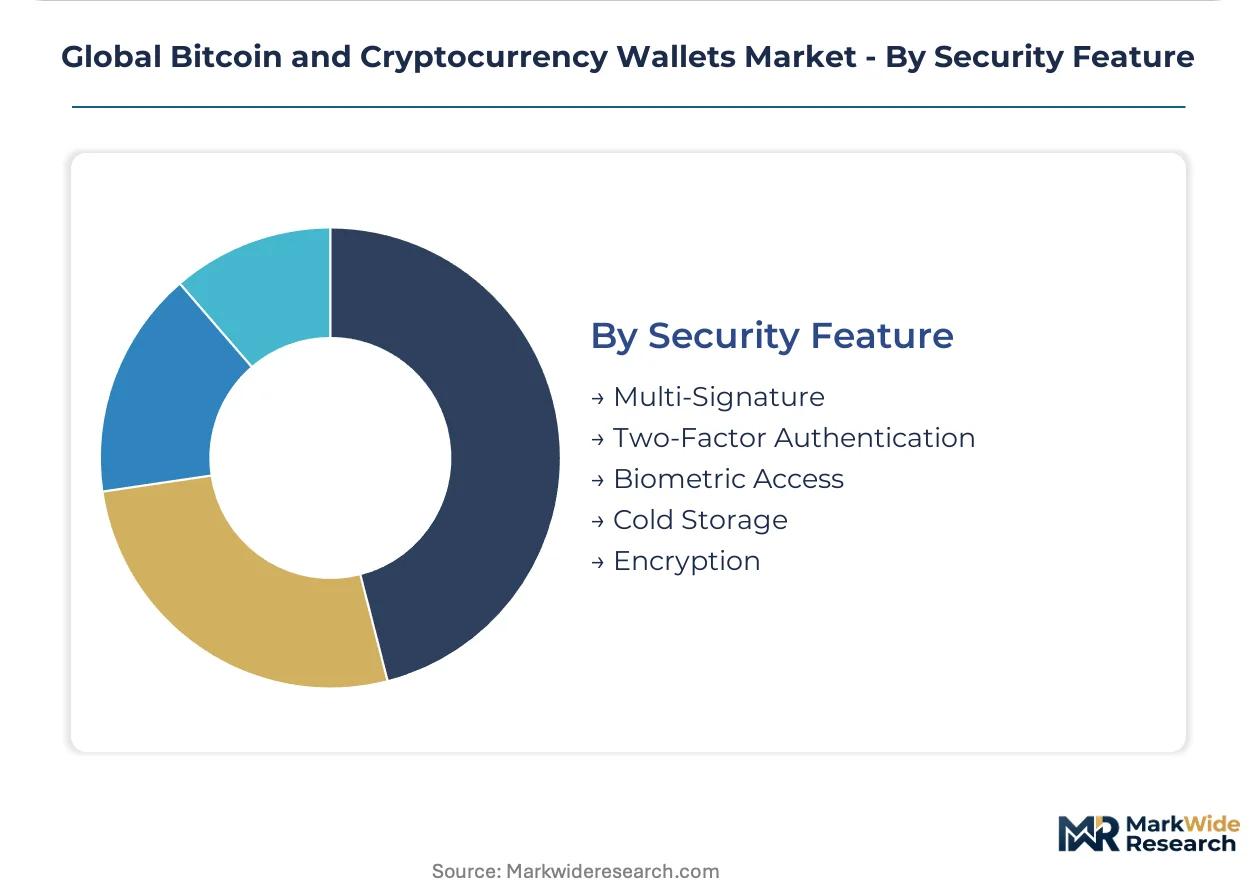
Protection mechanisms stratify across cost tiers, with biometric and cold storage commanding premium positioning against basic encryption.
- Multi-Signature:Threshold signature schemes requiring M-of-N key holder consensus distribute compromise risk. Institutional custody in Japan and Singapore mandates these arrangements for large-value holdings.
- Two-Factor Authentication:Time-based one-time passwords or hardware token verification add secondary verification layers. Mobile wallet developers integrate these as baseline requirements under European operational resilience guidelines.
- Biometric Access:Fingerprint and facial recognition pipelines embed hardware-backed authentication without password memorization. These features penetrate fastest in Indonesian and Vietnamese retail markets with high smartphone-native user bases.
- Cold Storage:Air-gapped key generation and transaction signing eliminate network attack vectors. METI certification pathways in Japan create regulated demand channels for institutional-grade cold storage hardware.
- Encryption:AES-256 or comparable cipher protection for data at rest and in transit forms the foundational security layer. All wallet categories implement encryption, with differentiation emerging in key derivation and storage architectures.
Encryption sits at the top of the volume ranking, with biometric access climbing the fastest on retail mobile adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo's asset management district anchors institutional hardware wallet procurement under METI cold storage standards. Regulatory divergence across major economies fragments product architectures into jurisdiction-specific compliance stacks rather than unified global platforms.
United States
SEC staking service evaluations freeze product roadmaps for yield-integrated wallets. State-level money transmitter frameworks layer atop federal uncertainty, compelling providers into multi-jurisdictional licensing. New York's BitLicense regime filters market entry for custody-focused entrants.
Japan
FSA segregation rules force institutional traders toward specialized custody providers separate from exchange execution. METI certification pathways create regulated demand channels for air-gapped key management systems. Osaka's fintech corridor concentrates hardware wallet distribution for asset managers.
Germany
MiCA operational resilience mandates accelerate hardware procurement by institutional custodians seeking compliant cold storage infrastructure. BaFin licensing requirements impose reserve transparency obligations on wallet providers serving EU residents. Frankfurt's banking cluster drives multi-signature HSM-backed custody adoption.
Singapore
Payment Services Act frameworks license wallet operators alongside digital asset exchanges, creating integrated regulatory pathways. MAS guidelines on consumer protection shape retail product feature sets. The city's wealth management hub concentrates prime brokerage unbundling of custody from execution.
Indonesia
Fintech licensing liberalization accelerates software wallet adoption among unbanked populations with smartphone penetration exceeding traditional banking access. BI regulations on digital asset trading establish baseline consumer safeguards. Jakarta's startup ecosystem drives mobile-first biometric authentication deployment.
Global Bitcoin and Cryptocurrency Wallets Market Competitive Landscape
Global majors compete with regional champions across custody architecture and compliance integration. The vendor base stratifies into three tiers: hardware-anchored secure element specialists, exchange-integrated custody platforms, and open-source firmware transparency advocates. Consolidation pressure concentrates among institutional-facing providers as prime brokerage models unbundle custody from execution. Strategic moves center on multi-signature HSM infrastructure partnerships and jurisdiction-specific licensing acquisitions.
Within the hardware-anchored tier, Ledger SAS exemplifies secure element chip architecture specialization. Coinbase Global, Inc. occupies a position bridging exchange liquidity with custody integration. Trezor represents the open-source firmware transparency archetype, attracting privacy-conscious holders through community-verified security protocols.
| Leading Market Players |
|---|
| Binance |
| Coinbase Global, Inc. |
| Ledger SAS |
| Trezor |
| BitGo |
| BitPay |
| Exodus Movement, Inc. |
| Zengo Ltd. |
| Blockchain.com |
| Others |
Supply & Pricing Matrix
Secure element chip fabrication costs in Taiwan and South Korea flow through hardware wallet pricing tiers, with premium METI-certified devices absorbing foundry premiums while economy software wallets bypass semiconductor procurement entirely through cloud-hosted key architectures.
Pricing Analysis
Input-cost pass-through from secure element chip shortages concentrates in hardware wallet premiums, particularly for devices seeking Japanese METI cold storage certification. Three-tier pricing structure across certified institutional, retail hardware, and software-only levels separates buyers by compliance burden rather than feature count alone. Pricing pressure stems from Southeast Asian software wallet competition where biometric authentication pipelines cost less to deploy than secure element procurement. Retail investors in Indonesia and Vietnam exhibit highest price sensitivity, while Japanese institutional custodians accept premium positioning for regulatory compliance assurance.
Supply Chain Analysis
Secure element chip supply rests on Taiwanese and South Korean foundry capacity, with assembly concentration in Shenzhen and Dongguan manufacturing clusters. Cryptographic processor components and air-gapped housing materials feed from Japanese and German precision component suppliers. Single-source vulnerability concentrates in East Asian semiconductor fabrication, where foundry allocation prioritizes automotive and smartphone contracts over niche cryptocurrency security modules. Distribution runs through authorized reseller networks for hardware wallets, while software wallets deploy through app store ecosystems and direct-to-consumer download channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between European MiCA compliance costs and Southeast Asian fintech licensing liberalization creates margin expansion opportunities for wallet providers structuring dual-entity operating models across regulatory jurisdictions.
For Market Incumbents: Deepen secure element chip supply agreements with Taiwanese foundries to lock capacity ahead of automotive sector competition. Invest in multi-jurisdictional licensing infrastructure to defend against exchange-integrated custody platforms unbundling prime brokerage functions. METI certification maintenance costs in Japan represent the critical margin pressure point requiring operational streamlining.
For New Entrants and Emerging Players: Shamir secret sharing social recovery technology offers a wedge into Philippine and Indonesian retail markets where hardware wallet cost barriers exclude first-time adopters. Target unbanked smartphone-native populations with biometric-authenticated software wallets distributed through telco partnership channels. White-space concentration sits in open-source firmware verification services for privacy-conscious developers seeking alternatives to proprietary secure element architectures.
For Investors and Strategic Acquirers: Consolidation pressure builds where multi-signature HSM infrastructure providers lack standalone distribution reach. Long-term viability favors custody-specialist firms with jurisdictional licensing depth over exchange-adjacent wallet operators facing SEC staking service classification uncertainty. Acquisition target archetype: institutional-facing custody platforms with Japanese FSA registration and EU operational resilience compliance already secured. Watch SEC securities classification rulings on yield-integrated wallet features as the inflection indicator for US market access viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdictional Licensing Acquisition | MiCA, FSA, and state-level money transmitter registrations compress competitor entry timelines. |
| Secure Element Chip Supply Agreement | Taiwanese foundry capacity commitments insulate against automotive sector allocation competition. |
| Open-Source Firmware Verification Program | Community-audited security protocols attract developer segments outside proprietary black-box systems. |
| Biometric Authentication Pipeline Integration | Fingerprint and facial recognition layers penetrate Indonesian and Vietnamese retail markets fastest. |
| Social Recovery Mechanism Deployment | Shamir secret sharing compresses single points of failure for cost-excluded hardware wallet alternatives. |
Research Methodology
Multiple input streams — primary interviews with wallet platform CTOs, institutional custody directors, and regulatory compliance leads; secondary validation through SEC filings, MiCA implementation guidance, and FSA registration databases; plus customs data on secure element chip trade flows — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned hardware wallet manufacturers in France and Czech Republic, software developers in Singapore and Switzerland, and institutional custodians in Tokyo's asset management district. Secondary sources included BaFin licensing records, METI certification registries, and BI fintech licensing announcements.
Data-stream reconciliation across wallet type, cryptocurrency supported, user category, security feature, and regional regulatory framework dimensions shaped the analytical framework over the projection horizon. CAGRs derived from installed base growth rates, institutional procurement cycle analysis, and retail adoption curve modeling across biometric authentication penetration and social recovery mechanism deployment. Forecast inputs incorporated MiCA implementation timelines, FSA segregation enforcement intensity, and SEC staking service evaluation trajectories.
The model holds under stable regulatory classification environments; deviation in SEC securities rulings, EU operational resilience enforcement calibration, or Japanese METI certification pathway modifications would shift institutional procurement timing assumptions. A small set of named triggers — SEC staking classification, MiCA reserve transparency audit protocols, and Taiwanese foundry capacity allocation shifts — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
NFT Art Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Exchange Platform Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Hardware Wallet Market
Digital Assets and Cryptocurrency Finance
Blockchain Distributed Ledger Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Exchanges Market
Digital Assets and Cryptocurrency Finance
Global Hardware Wallets Market
Digital Assets and Cryptocurrency Finance
Music NFT Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency and Blockchain Market
Digital Assets and Cryptocurrency Finance
Germany Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Smart Contracts Platforms Market
Digital Assets and Cryptocurrency Finance
Bitcoin Exchange Market
Digital Assets and Cryptocurrency Finance
Crypto Art Market
Digital Assets and Cryptocurrency Finance
Bitcoin Market
Digital Assets and Cryptocurrency Finance
Digital Asset Trading Platform Market
Digital Assets and Cryptocurrency Finance
United States Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Platform Market