
 Global Fundraising Software Market | 2026-2036
Global Fundraising Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fundraising Software Market Foresight
API-first architecture is pivoting away from legacy monolithic codebases toward modular microservices that reduce implementation costs for mid-sized nonprofits. Blackbaud leverages its entrenched data ecosystem to sustain renewal rates across faith-based and arts institutions. Salesforce.org competes through native CRM integration that eliminates donor data silos for large enterprises. Qgiv differentiates via embedded payment processing that shortens campaign launch cycles for small and medium organizations.
Fundraising software comprises cloud-deployed applications that automate donor acquisition, gift processing, campaign analytics, and compliance reporting through RESTful APIs and encrypted transaction pipelines. The primary commercial purpose is to replace spreadsheet-based donor tracking with centralized databases that segment constituents by giving history, engagement score, and channel preference. Cloud-based deployment leads solution type adoption because subscription economics eliminate capital expenditure barriers for volunteer-staffed charities. Peer-to-peer fundraising represents the fastest-expanding solution category as social proof mechanics amplify individual donor reach through personal network effects. Donor management retains the deepest margin pool because recurring subscription revenue locks in multi-year contracts with enterprise-scale nonprofits.
FDA oversight of healthcare-adjacent patient fundraising platforms, GDPR data residency mandates from European regulators, and SEC disclosure requirements for political campaign finance software collectively elevate compliance engineering costs for cross-border vendors. The EU AI Act's risk classification system is forcing sentiment-analysis features in donor scoring algorithms toward explainability standards that demand audit trails. Stakeholders must monitor whether emerging central bank digital currency frameworks in pilot economies reshape payment rail dependencies for recurring gift processing.
Market Dynamics
API-first microservices architecture is fragmenting vendor lock-in by enabling mid-sized nonprofits to assemble best-of-breed donor management stacks without monolithic platform commitments.
Growth Catalysts
- EU AI Act risk classification:Mandatory explainability standards for algorithmic donor scoring are accelerating vendor investment in auditable sentiment-analysis pipelines.
- Peer-to-peer social mechanics:Network-effect amplification through personal fundraising pages is expanding individual donor reach beyond traditional campaign boundaries.
- Cloud subscription economics:Elimination of upfront capital expenditure barriers is unlocking adoption among volunteer-staffed charitable organizations previously constrained by IT budgets.
Market Restraints
- Cross-border compliance engineering:Simultaneous adherence to GDPR data residency, FDA healthcare-adjacent oversight, and SEC political disclosure mandates inflates development overhead for multi-jurisdiction vendors.
- Payment rail concentration:Dependency on legacy card networks and emerging central bank digital currency pilot frameworks creates uncertainty in recurring gift processing infrastructure.
- Enterprise contract lock-in:Multi-year subscription agreements with large nonprofits reduce competitive switching and compress margin recovery timelines for challenger platforms.
Strategic Opportunities
- Embedded payment processing convergence:Native transaction pipeline integration is compressing campaign launch cycles for small and medium organizations.
- Australia digital infrastructure deepening:Government investment in charitable giving rails is creating favorable conditions for cloud-native platform expansion.
- Central bank digital currency pilots:Experimental government-issued payment frameworks in select economies may reshape recurring donation settlement architectures.
Industry Challenges
- Algorithmic audit trail engineering:EU AI Act compliance demands retrofitted explainability infrastructure for existing donor scoring models.
- Legacy system API integration:Decades-old donor databases in established institutions resist seamless data migration to modular microservices stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fundraising Software Market |
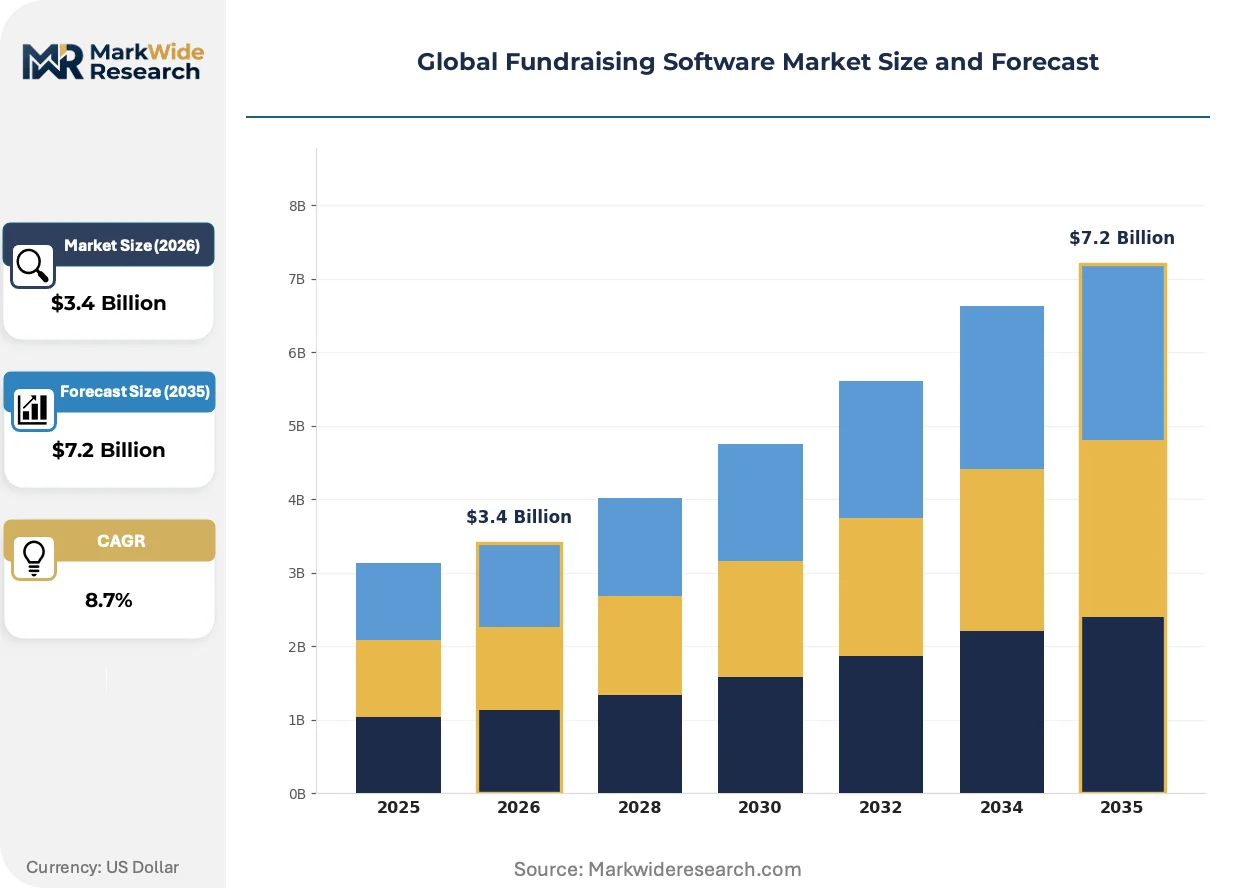
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $7.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Solution Type: Donor Management, Event Management, Peer-to-Peer Fundraising, Crowdfunding, Grant Management Application: Nonprofit Organizations, Educational Institutions, Religious Organizations, Political Campaigns, Arts & Culture Customer Type: Small & Medium Enterprises, Large Enterprises, Government Agencies, Foundations |
| Companies Covered | Blackbaud, DonorPerfect, Bloomerang, Neon One, Salsa Labs, Qgiv, Classy, Salesforce.org, Kindful, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fundraising Software Market Shifts & Advancements
Three interconnected shifts are restructuring how fundraising software delivers value: automation of donor engagement workflows, regulatory pressure on algorithmic transparency, and compression of campaign deployment timelines through embedded financial infrastructure.
Machine learning-powered donor propensity scoring is automating gift officer prioritization by ranking constituents according to predicted giving likelihood. Faith-based institutions and university advancement offices are deploying these tools at accelerating velocity. The technology is automating segmentation workflows that previously required manual spreadsheet analysis, compressing campaign planning cycles from weeks to days.
The EU AI Act's risk-based classification system is mandating explainability documentation for high-risk algorithmic applications including donor sentiment analysis. Vendors must now maintain audit trails demonstrating how scoring models weight engagement signals. European nonprofits and cross-border platforms serving EU data subjects face the steepest compliance retrofit requirements.
Self-service campaign configuration portals are displacing vendor-managed implementation for mid-market organizations. Small and medium charities now expect drag-and-drop page builders and autonomous payment gateway activation. Germany and Australia exhibit the sharpest adoption curves as digital-native fundraising teams mature within these markets.
Global Fundraising Software Market Segmentation
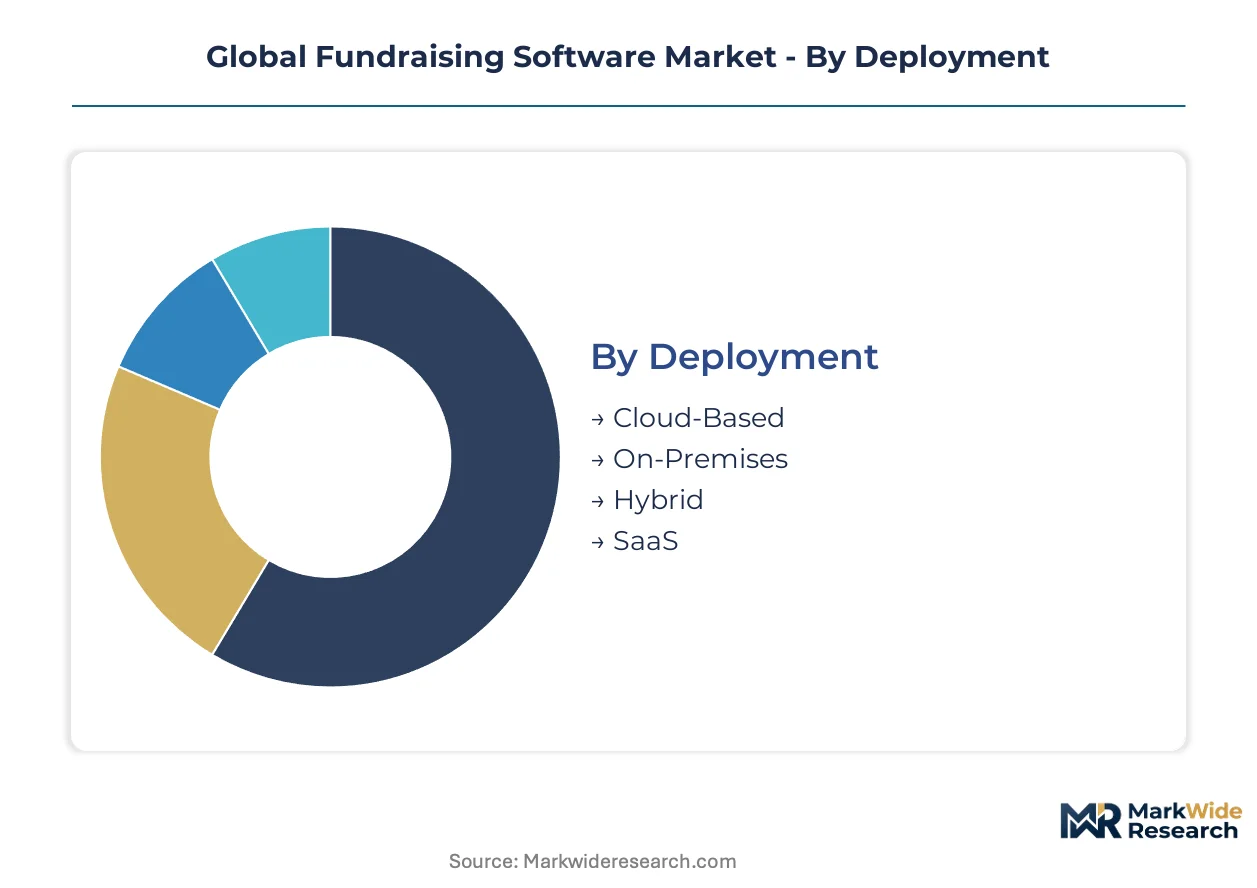
Fundraising software segmentation reveals how deployment economics, solution architecture, and customer scale reshape procurement patterns across charitable and institutional buyers. Understanding these dimensions exposes where vendor R&D investments concentrate and which user profiles drive margin expansion.
Deployment:
Replacement cycles in fundraising infrastructure accelerate as volunteer-staffed charities retire legacy server installations for subscription-based alternatives.
- Cloud-Based:Multi-tenant architectures with automatic security patching eliminate capital expenditure barriers for resource-constrained nonprofits. Demand concentrates among faith-based institutions in the United States and Germany seeking remote access for distributed volunteer teams without IT staffing.
- SaaS:Pre-configured donor management workflows with tiered subscription pricing compress implementation timelines from months to weeks. Australian charitable organizations exhibit the sharpest adoption velocity as government digital infrastructure investments mature.
- On-Premises:Single-tenant installations retained by large universities and hospital foundations with dedicated compliance officers and legacy data residency requirements.
- Hybrid:Split architectures pairing cloud campaign tools with on-premise donor databases for European nonprofits navigating GDPR data sovereignty mandates.
Cloud-Based sits at the top of the volume ranking, with SaaS climbing the fastest.
Solution Type:
Application maturity varies sharply across solution categories, with established donor databases commanding premium pricing against emerging social fundraising formats.
- Donor Management:Centralized constituent databases segmenting giving history, engagement scores, and channel preferences through machine learning-powered propensity scoring. Large enterprises in the United States lock in multi-year contracts, generating the deepest recurring revenue pools for established vendors.
- Peer-to-Peer Fundraising:Personal campaign pages leveraging network effects to amplify individual donor reach beyond traditional organizational boundaries. Social proof mechanics are expanding fastest among educational institutions and health charities in Australia and Germany.
- Event Management:Registration, ticketing, and on-site donation processing for galas, runs, and benefit auctions retained by arts and culture institutions.
- Crowdfunding:Project-specific fundraising with all-or-nothing funding thresholds attracting startup nonprofits and emergency relief campaigns.
- Grant Management:Compliance reporting and funder relationship tracking for foundations and research institutions navigating complex reporting requirements.
Donor Management captures the largest revenue share, while Peer-to-Peer Fundraising exhibits the steepest expansion trajectory.
Application:
End-use concentration determines feature prioritization, with nonprofit-specific compliance requirements diverging from political campaign disclosure mandates.
- Nonprofit Organizations:General-purpose donor acquisition, gift processing, and stewardship automation for charitable entities across mission areas. Cloud-native platforms in the United States and Germany dominate procurement as these markets deepen digital giving infrastructure.
- Educational Institutions:Alumni engagement and advancement office workflows with complex pledge tracking and reunion campaign orchestration. University systems concentrate demand in Australia and the United States where endowment fundraising scales justify enterprise platform investments.
- Religious Organizations:Tithing automation and congregant stewardship tools with specific requirements for recurring gift processing and pastoral access controls.
- Political Campaigns:Contribution tracking with real-time disclosure reporting to satisfy FEC and state-level transparency mandates.
- Arts & Culture:Membership management and performance-based fundraising for museums, theaters, and orchestras with donor recognition tiering.
Nonprofit Organizations anchor procurement volume, with Educational Institutions gaining share fastest among end-use categories.
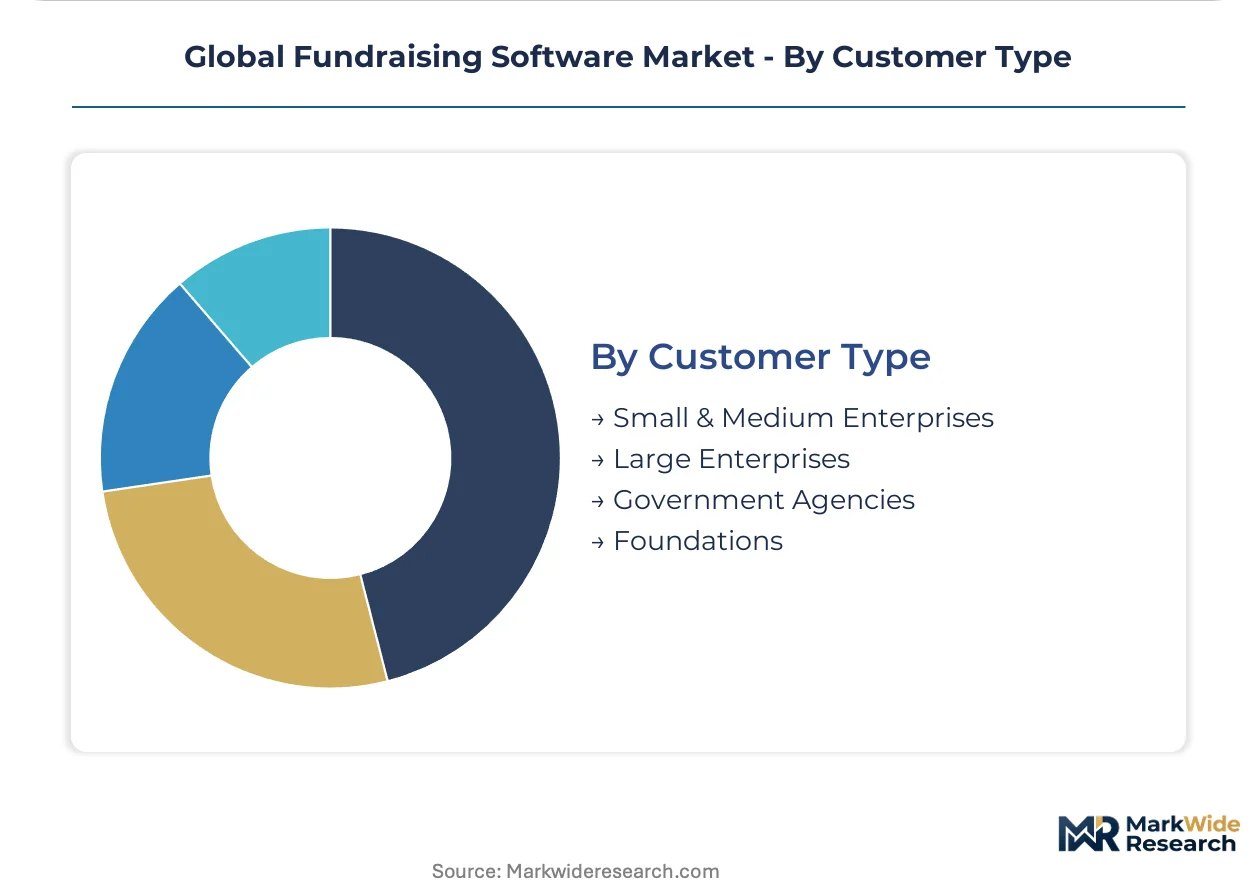
Customer Type:
Scale-based segmentation separates self-service configurations for budget-constrained buyers from enterprise implementations requiring dedicated account management.
- Large Enterprises:Multi-departmental deployments with custom API integrations, dedicated success managers, and advanced analytics dashboards. Major nonprofit federations and university systems in the United States and Germany sustain the highest contract values and longest renewal terms.
- Small & Medium Enterprises:Volunteer-staffed charities and community foundations requiring drag-and-drop campaign builders and autonomous payment activation. Australia exhibits concentrated demand as digital-native fundraising teams mature within this market segment.
- Government Agencies:Public benefit corporations and state arts councils with specific procurement and transparency requirements.
- Foundations:Grant-making institutions with specialized due diligence workflows and multi-year payout tracking needs.
Large Enterprises command the premium tier by contract value, with Small & Medium Enterprises expanding most quickly as subscription economics democratize access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The San Francisco Bay Area anchors software innovation for charitable giving infrastructure, with venture-backed platforms originating here diffusing subscription-based donor management tools worldwide. Cloud-native architectures from this cluster now serve faith-based institutions and university advancement offices across multiple continents.
United States
Enterprise-scale nonprofits and university systems drive concentrated demand for multi-tenant donor management platforms with machine learning-powered propensity scoring. SEC disclosure requirements for political campaign finance software elevate compliance engineering costs for cross-border vendors serving this market. The Boston-Cambridge corridor hosts dense clusters of advancement offices at research universities deploying sophisticated alumni engagement workflows.
Germany
Faith-based institutions and medium-sized charitable organizations seek GDPR-compliant cloud solutions with data residency guarantees. The EU AI Act's risk classification system mandates explainability documentation for algorithmic donor scoring features deployed here. Berlin and Munich concentrate procurement activity as digital-native fundraising teams mature within established nonprofit federations.
Australia
Government investment in charitable giving digital infrastructure accelerates adoption of SaaS donor management among volunteer-staffed community foundations. The TGA regulates healthcare-adjacent patient fundraising platforms with oversight requirements that shape vendor development priorities. Sydney and Melbourne host expanding technology clusters where peer-to-peer fundraising platforms achieve rapid deployment velocity.
United Kingdom
Arts and culture institutions with membership management needs sustain demand for integrated campaign analytics and donor recognition tiering. GDPR compliance requirements intersect with Charity Commission transparency mandates to create layered regulatory complexity for platform providers. London's nonprofit technology sector concentrates procurement decision-making for major international development organizations.
Canada
Health charities and hospital foundations retain hybrid deployment preferences pairing cloud campaign tools with on-premise donor databases. Health Canada oversight of patient-facing fundraising platforms elevates compliance documentation requirements for vendors operating in this jurisdiction. Toronto and Vancouver anchor procurement activity for bilingual fundraising infrastructure serving English and French-speaking constituencies.
Global Fundraising Software Market Competitive Landscape
Global majors compete with regional champions across deployment architecture and compliance specialization, producing a tiered structure where entrenched data ecosystems sustain renewal rates against modular challengers. Consolidation pressures concentrate around enterprise-scale contracts with multi-year subscription terms, while fragmentation persists in the mid-market where API-first microservices enable best-of-breed stack assembly. Three archetypes dominate: legacy platform incumbents with deep institutional data lock-in, cloud-native specialists with embedded payment processing, and CRM-extended entrants leveraging native integration advantages. Competitive moves center on strategic partnerships for compliance localization and portfolio diversification into adjacent grant management workflows.
Within the legacy platform tier, Blackbaud anchors entrenched positions across faith-based and arts institutions through decades of accumulated donor data assets. Salesforce.org occupies the CRM-extended archetype, exemplifying how native integration eliminates data silos for large enterprise deployments. Qgiv represents the cloud-native specialist position, with embedded payment processing capabilities that compress campaign launch timelines for resource-constrained organizations. These three companies collectively illustrate the competitive vectors reshaping procurement patterns across customer scale segments.
| Leading Market Players |
|---|
| Blackbaud |
| DonorPerfect |
| Bloomerang |
| Neon One |
| Salsa Labs |
| Qgiv |
| Classy |
| Salesforce.org |
| Kindful |
| Others |
Supply & Pricing Matrix
EU AI Act explainability mandates gate both qualified supply and premium-tier pricing access, as vendors investing in auditable algorithmic infrastructure capture enterprise contracts while compliance laggards face margin compression in mid-market segments. The intersection of regulatory certification costs and cloud infrastructure economics concentrates pricing power among established platforms with pre-built audit trails.
Pricing Analysis
Input-cost pass-through from compliance engineering and cloud infrastructure investments sustains subscription pricing elevation for GDPR-certified and AI Act-compliant platforms. Three-tier pricing structure across premium, standard, and economy levels segments by audit depth, API customization scope, and embedded payment processing capabilities. Pricing pressure stems from challenger platforms compressing implementation timelines through modular microservices. Volunteer-staffed small and medium enterprises exhibit highest price sensitivity, while large nonprofit federations with dedicated compliance officers absorb premium tiers.
Supply Chain Analysis
Dual-sourcing requirements for payment processors and cloud infrastructure providers mandate multi-supplier qualification among risk-averse enterprise buyers. Supply concentration centers on the United States for hyperscaler cloud infrastructure, Ireland and Germany for GDPR-compliant data residency, and Australia for government-backed charitable giving rails. Raw material dependencies include encrypted transaction pipelines, RESTful API frameworks, and machine learning inference infrastructure. Single-source vulnerability concentrates in legacy card network dependencies for recurring gift settlement. Distribution runs through direct vendor sales teams for enterprise accounts and self-service portals for mid-market adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as procurement shifts toward premium specifications for algorithmic auditability and cross-border compliance certification.
For Market Incumbents: Acquire specialized compliance engineering teams to retrofit explainability infrastructure for existing donor scoring models. Consolidate data migration capabilities to defend against modular challengers dismantling monolithic lock-in. The threat of API-first microservices fragmenting enterprise contracts demands vertical integration into adjacent grant management workflows. For New Entrants and Emerging Players: Volunteer-staffed community foundations in Australia represent the most penetrable buyer archetype, given government digital infrastructure investments and maturing SaaS procurement literacy. White-space targets include embedded central bank digital currency pilot integration and self-service campaign configuration for faith-based institutions. Go-to-market through channel partnerships with existing payment processors accelerates trust acquisition. For Investors and Strategic Acquirers: Roll-up economics work for regional cloud-native specialists because GDPR localization requirements create natural market fragmentation that rewards compliance-certified portfolios. Long-term viability hinges on recurring revenue durability from multi-year enterprise subscriptions. Acquisition targets should demonstrate pre-built EU AI Act audit trails. The signal to watch is central bank digital currency framework maturation in pilot economies reshaping payment rail dependencies.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native CRM connectivity eliminates donor data silos for large university advancement offices. |
| Compliance Certification Investment | EU AI Act audit trail infrastructure unlocks enterprise procurement in Germany and France. |
| Embedded Payment Processing | Autonomous transaction pipelines compress campaign launch cycles for mid-market charities. |
| Acquisition of Specialist Firm | Grant management workflow capabilities diversify revenue beyond donor acquisition tools. |
| Geographic Expansion | Australia government digital infrastructure investments create favorable cloud-native entry conditions. |
Research Methodology
Multiple input streams — executive interviews with fundraising software CTOs, procurement discussions with nonprofit IT directors, and validation sessions with payment gateway integration specialists — were reconciled against secondary sources including SEC filings from publicly traded vendors, GDPR enforcement documentation from European data protection authorities, and central bank digital currency pilot disclosures. Bottom-up triangulation across deployment model adoption curves and top-down validation through cloud infrastructure spend patterns anchored volume estimates.
Data-stream reconciliation across deployment architecture, solution type, customer scale, and regional regulatory cluster dimensions structured the analytical framework. CAGRs were derived from segment-level subscription renewal rates and new customer acquisition velocity. Forecast inputs incorporated EU AI Act implementation timelines and government digital infrastructure investment commitments in target markets.
Underlying measurement precision varies by segment; cloud-based deployment and large enterprise customer types carry tighter precision than emerging peer-to-peer categories. Forecasts reflect assumptions around regulatory enforcement consistency and payment rail stability. Deviation in central bank digital currency pilot acceleration or GDPR penalty escalation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Asia-Pacific Financial Analytics Market
FinTech
Smart Finance Connectivity Market
FinTech
Embedded Finance Market
FinTech
Smart Lending Platform Market
FinTech
Fintech Lending Market
FinTech
North America Fintech Cloud Market
FinTech
AI-Powered Wealth Management Solution Market
FinTech
Financial Forecasting Software Market
FinTech
Robo Advisory Market
FinTech
Transaction Monitoring Software Market
FinTech
Smart Financial Solutions Market
FinTech
Supply Chain Finance Market
FinTech
Europe Fintech Cloud Market
FinTech
Intelligent Cash Deposit Machine Market
FinTech
North America AI in Fintech Market
FinTech
Europe AI in Fintech Market