
 Blockchain in Fintech Market | 2026-2036
Blockchain in Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
Blockchain in Fintech Market Analysis
North American cloud infrastructure providers is pivoting toward regulated financial workloads. IBM sustains mainframe-grade security architectures for central bank digital currency pilots across multiple jurisdictions. Amazon Web Services dominates compliant node hosting through its dedicated financial services cloud regions. Microsoft leverages enterprise middleware to bridge legacy core banking systems with Ethereum-compatible ledgers.
Blockchain in Fintech denotes cryptographically linked distributed ledgers that achieve consensus through proof-of-stake or Byzantine fault-tolerant mechanisms, primarily engineered to eliminate intermediary reconciliation delays in value transfer. Payment Processing applications currently anchor transaction volume due to real-time gross settlement demands, while Asset Tokenization represents the fastest-expanding margin pool as institutional issuers fractionalize real estate and private credit instruments. Public Blockchain protocols compete with Consortium Blockchain configurations for institutional trust, though hybrid architectures increasingly occupy the compliance-sensitive middle ground where KYC obligations intersect with transparency mandates.
The SEC, EU's MiCA framework, and Singapore's MAS collectively shape market access through divergent custody, reserve, and disclosure requirements that fragment deployment strategies across jurisdictions. HIPAA-informed data privacy standards and ISO 27001 certifications further constrain how Development Services firms architect on-chain identity layers for Insurance Companies and Regulatory Bodies. Stakeholders must monitor whether jurisdictional regulatory arbitrage or technical interoperability standards will determine which ledger ecosystems capture institutional liquidity flows.
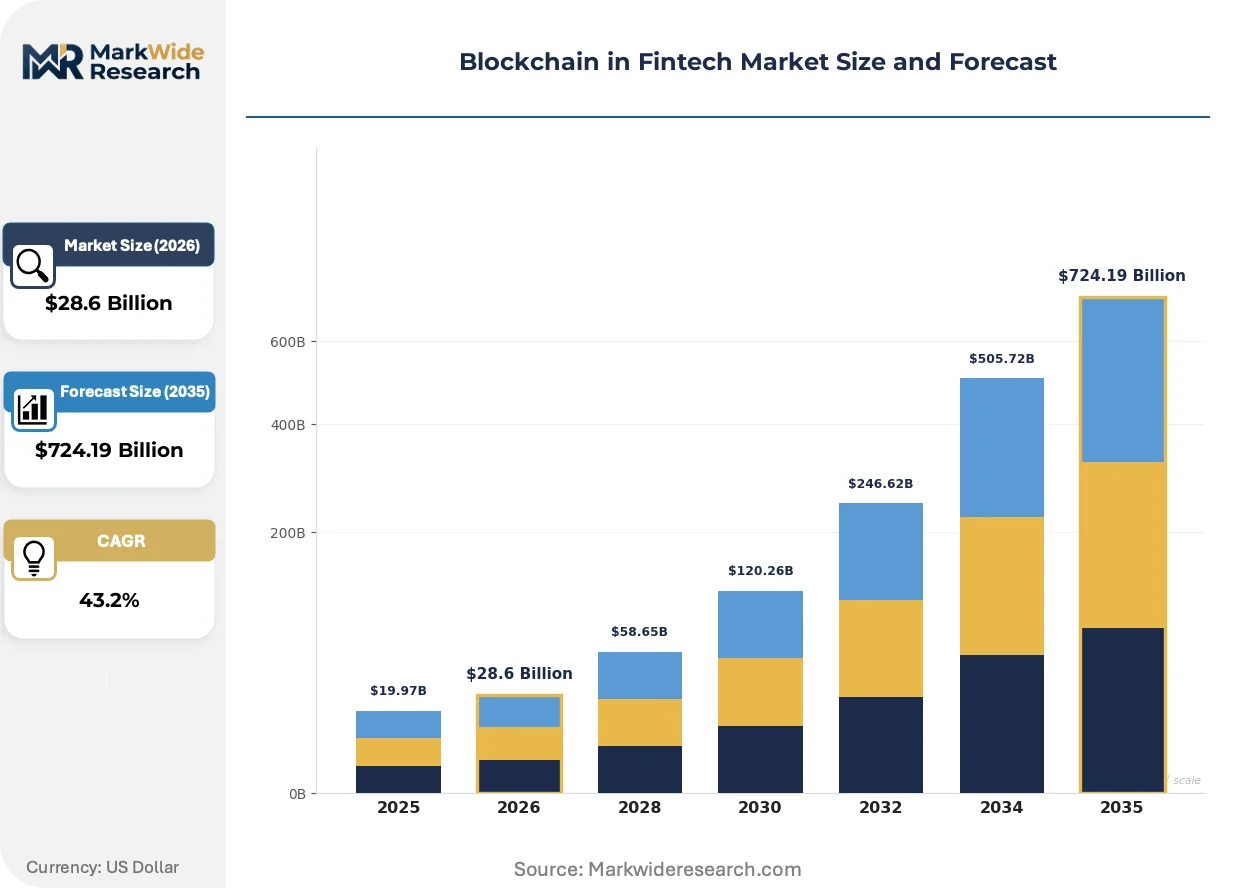
Market Dynamics
Cross-border payment corridors anchored by RippleNet and SWIFT gpi integration are pulling banking institutions toward distributed ledger infrastructure, forcing compliance architecture upgrades across European neobanks under the EU's Markets in Crypto-Assets regulation.
Growth Catalysts
- MiCA Framework Implementation:The EU's Markets in Crypto-Assets regulation mandates standardized reserve and disclosure requirements, accelerating institutional adoption of compliant custody solutions across European neobanks.
- Project Guardian Tokenization:Singapore's Monetary Authority is tokenizing foreign exchange and bond markets at institutional scale, creating template architectures for wholesale CBDC deployment.
- Real-Time Gross Settlement Demand:Payment processing applications require Byzantine fault-tolerant consensus mechanisms to eliminate intermediary reconciliation delays in high-velocity clearing.
Market Restraints
- Energy Input Volatility:Proof-of-stake validation networks face electricity cost pressures in jurisdictions with carbon-adjusted pricing, compressing node operator margins.
- Supply Concentration Risk:Specialized hardware wallet manufacturing clusters in East Asian foundries create single-point-of-failure vulnerabilities for institutional key management systems.
- Interoperability Limitations:Fragmented consensus protocols between public Ethereum-compatible ledgers and permissioned Hyperledger Fabric deployments force expensive middleware development.
Strategic Opportunities
- Underpenetrated Indian Market:The Reserve Bank of India's digital rupee pilot creates first-mover positioning for compliant node hosting infrastructure in Mumbai and Bangalore financial districts.
- Insurance Claims Automation:Parametric smart contracts linked to verified oracle data streams enable automated payout execution for catastrophe bonds and crop insurance products.
- ISO 27001 Certification Pathway:Information security management certification for on-chain identity layers opens regulated procurement channels with HIPAA-bound healthcare payers.
Industry Challenges
- Cryptographic Talent Scarcity:Zero-knowledge proof engineering and formal verification skills command premium compensation, constraining development velocity for privacy-preserving transaction architectures.
- Legacy Core Banking Integration:COBOL-based mainframe systems require expensive API abstraction layers to interface with Ethereum-compatible smart contract environments.
- Cross-Border Regulatory Arbitrage:Divergent SEC custody requirements versus Singapore MAS reserve mandates fragment liquidity pools and complicate multi-jurisdictional product design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blockchain in Fintech Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $724.19 Billion |
| CAGR (2026 – 2036) | 43.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Smart Contracts, Payment Processing, Identity Verification, Asset Tokenization Technology: Public Blockchain, Private Blockchain, Consortium Blockchain, Hybrid Blockchain Service Type: Consulting Services, Development Services, Integration Services, Maintenance Services End User: Banking Institutions, Investment Firms, Insurance Companies, Regulatory Bodies |
| Companies Covered | IBM, Microsoft, Coinbase, Ripple, Oracle, Amazon Web Services, Digital Asset Holdings, Chainalysis, Avalanche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blockchain in Fintech Market Emerging Trajectories
Institutional blockchain deployment is pivoting from experimental pilots to production-grade infrastructure, with hybrid architectures occupying the compliance-sensitive middle ground where KYC obligations intersect with transparency mandates.
Zero-knowledge rollup technology is rewriting settlement economics for high-frequency trading venues. Institutional exchanges in Singapore and Switzerland are adopting zk-SNARK-based validity proofs to compress transaction batch verification costs. This compression is enabling real-time gross settlement at throughput levels previously requiring centralized clearinghouses.
The EU's Markets in Crypto-Assets regulation is forcing standardized reserve attestations for stablecoin issuers. European neobanks must upgrade custody infrastructure to meet qualified wallet provider status, diverting engineering resources from product differentiation. Asset tokenization platforms targeting German real estate markets are responding by segregating MiCA-compliant issuance vehicles from offshore-domiciled structures.
Corporate treasury departments are unbundling cryptocurrency custody from prime brokerage relationships. Large manufacturing conglomerates in Japan and South Korea are issuing direct RFPs to qualified custodians, bypassing traditional banking intermediaries. This disintermediation is most visible in Seoul's Gangnam financial district, where chaebol-affiliated venture arms are building captive validation node operations.
Blockchain in Fintech Market Segmentation
Segmentation in blockchain fintech reveals how capital deployment, regulatory exposure, and technical architecture choices fragment the addressable opportunity. Each dimension carries distinct margin profiles and compliance burdens that reshape vendor positioning.
Application:
Capital intensity varies sharply across use cases, with infrastructure-heavy segments demanding multi-year deployment cycles while lightweight applications achieve faster monetization.
- Payment Processing:Byzantine fault-tolerant consensus mechanisms power real-time gross settlement networks. Singapore's MAS Project Guardian and RippleNet corridors are concentrating demand for cross-border clearing infrastructure that eliminates correspondent banking delays.
- Asset Tokenization:Fractionalization engines for real estate and private credit instruments require sophisticated legal structuring alongside smart contract development. German real estate markets and Singapore bond tokenization pilots are absorbing the bulk of institutional engineering resources.
- Smart Contracts:Self-executing agreement protocols automate escrow, derivatives settlement, and trade finance execution.
- Identity Verification:Decentralized credential systems enable KYC portability across banking relationships without central data repositories.
Payment Processing absorbs the bulk of installed capacity; Asset Tokenization is expanding most quickly.
Technology:
Architecture selection determines regulatory exposure and interoperability costs, with hybrid configurations emerging as the dominant compromise between transparency mandates and privacy requirements.
- Consortium Blockchain:Permissioned networks governed by banking coalitions balance auditability with transaction confidentiality. SWIFT gpi integration and R3 Corda deployments across European trade finance consortia are driving enterprise adoption where competitive secrecy matters.
- Hybrid Blockchain:Dual-layer structures anchor sensitive operations on private ledgers while anchoring integrity proofs to public chains. IBM's central bank digital currency pilots and Singapore's institutional tokenization frameworks are validating this architecture for compliance-sensitive deployments.
- Public Blockchain:Open, permissionless networks with native cryptocurrency settlement and censorship-resistant transaction ordering.
- Private Blockchain:Single-entity controlled ledgers optimized for internal reconciliation and supply chain visibility.
Consortium Blockchain carries the heaviest engineering investment burden; Hybrid Blockchain is climbing the fastest as regulators demand audit trails without full transparency.
Service Type:
Professional services revenue correlates with implementation complexity, with integration work commanding premium rates where legacy core banking systems require abstraction layers.
- Development Services:Smart contract engineering and zero-knowledge proof implementation demand scarce cryptographic talent. European neobanks upgrading for MiCA compliance and Singaporean institutions building tokenization infrastructure are competing for the same limited engineering pools.
- Integration Services:Middleware construction bridging COBOL mainframes to Ethereum-compatible environments absorbs the largest project budgets. Japanese and South Korean chaebol treasury departments are issuing direct RFPs for captive node operations that bypass traditional banking intermediaries.
- Consulting Services:Regulatory navigation and tokenomics design for compliant issuance structures.
- Maintenance Services:Continuous node operation, security patching, and consensus protocol upgrades.
Integration Services captures the greatest share of professional services revenue; Development Services faces the steepest talent constraints and rate inflation.
End User:
Procurement authority and technical sophistication diverge across buyer categories, with regulatory bodies increasingly mandating standards that reshape vendor roadmaps.
- Banking Institutions:Correspondent banks and neobanks are the primary deployers of distributed ledger infrastructure for cross-border payments and trade finance. EU MiCA implementation is forcing custody architecture upgrades that divert engineering budgets from product differentiation.
- Insurance Companies:Parametric smart contract deployment for catastrophe bonds and crop insurance requires verified oracle data streams. HIPAA-informed data privacy standards constrain how Development Services firms architect on-chain identity layers for healthcare payers.
- Investment Firms:Asset managers and hedge funds tokenizing fund interests and streamlining settlement workflows.
- Regulatory Bodies:Central banks and securities commissions establishing technical standards for CBDC pilots and stablecoin oversight.
Banking Institutions account for the dominant share of current deployment spending; Insurance Companies are gaining share fastest as parametric contract architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Project Guardian tokenization pilots and the EU's MiCA implementation are anchoring distributed ledger infrastructure deployment across major financial centers. Regulatory clarity in these jurisdictions is pulling institutional capital toward compliant custody and settlement architectures.
United States
SEC custody mandates and state-level money transmitter licenses are shaping how banking institutions deploy cross-border payment infrastructure. New York's BitLicense framework and Wyoming's blockchain banking charters create divergent compliance pathways. Manhattan's financial district hosts the densest concentration of enterprise blockchain engineering talent, with major cloud providers operating dedicated financial services regions.
Singapore
MAS Project Guardian is tokenizing foreign exchange and bond markets at institutional scale, creating template architectures for wholesale CBDC deployment. The regulator's technology risk management guidelines enforce strict operational resilience standards for node operators. The Marina Bay financial district has emerged as the primary hub for Asian institutional tokenization pilots, with multiple banking consortia establishing captive development centers.
Germany
MiCA implementation is forcing custody architecture upgrades across European neobanks, diverting engineering resources from product differentiation. BaFin's crypto custody licensing regime creates high barriers to qualified wallet provider status. Frankfurt's banking cluster and Berlin's fintech ecosystem are absorbing the bulk of continental compliance engineering demand for tokenized securities issuance.
Switzerland
FINMA's distributed ledger technology guidelines provide granular clarity on token classification and anti-money laundering obligations. The country's banking secrecy tradition intersects with transparency mandates in hybrid ledger deployments. Zurich and Zug's Crypto Valley host concentrated specialist engineering pools for institutional tokenization and custody infrastructure.
India
RBI's digital rupee pilot creates first-mover positioning for compliant node hosting infrastructure in Mumbai and Bangalore financial districts. The central bank's phased CBDC rollout is testing wholesale settlement use cases before retail deployment. Bangalore's technology corridor and Mumbai's banking headquarters are competing for captive validation node operations from domestic banking consortia.
Blockchain in Fintech Market Vendor Landscape
Global majors compete with regional champions across cloud infrastructure, enterprise middleware, and specialized cryptographic services. The vendor base clusters around three tiers: hyperscale cloud providers with financial services compliance certifications, enterprise software incumbents with legacy banking integration capabilities, and niche specialists in zero-knowledge proof engineering or on-chain analytics. Dominant competitive moves include vertical integration into custody hardware manufacturing and strategic partnerships with central bank digital currency pilot programs.
Among enterprise software incumbents, IBM and Microsoft exemplify the middleware bridging archetype, occupying positions between legacy core banking systems and Ethereum-compatible environments. Amazon Web Services anchors the compliant cloud hosting tier, with dedicated financial services regions enabling regulated node operations. Within the specialized infrastructure segment, Ripple represents the cross-border payment corridor specialization, while Chainalysis occupies a position in the on-chain analytics and compliance tooling tier.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| Coinbase |
| Ripple |
| Oracle |
| Amazon Web Services |
| Digital Asset Holdings |
| Chainalysis |
| Avalanche |
| Others |
Supply Flow & Price Mechanics
Ethereum gas fee volatility serves as the primary cost benchmark cascading through blockchain fintech infrastructure tiers, compressing margins for node operators in carbon-adjusted jurisdictions while elevating premium pricing for compliant custody solutions in Singapore and Germany.
Pricing Analysis
Warranty and service bundling separates enterprise-grade node hosting from bare-metal infrastructure rentals, with IBM and Amazon Web Services wrapping compliance certifications into multi-year contracts while smaller providers unbundle security patching. Pricing stratifies across premium, standard, and economy tiers based on ISO 27001 certification status and geographic proximity to financial district latency requirements. Cost compression in the standard tier is intensifying because European neobanks are diverting engineering budgets toward MiCA compliance upgrades. Banking institutions show the least price sensitivity due to regulatory mandate pressures, while emerging market fintechs exhibit acute cost consciousness.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale demand from Japanese and South Korean chaebol treasury departments, while systems integrators serve mid-tier European neobanks upgrading for MiCA compliance. Hardware wallet manufacturing concentrates in Taiwan and South Korea, with cryptographic chip fabrication anchored in United States foundries. The supply chain draws from specialized semiconductor components, HSM modules, and certified data center real estate. Single-source vulnerability in East Asian foundries threatens institutional key management system availability. Distribution runs through cloud provider marketplaces and direct procurement teams at major banking consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is mounting as MiCA implementation costs force subscale European neobanks toward acquisition or partnership, eliminating vendors lacking qualified wallet provider status.
For Market Incumbents: Extend middleware capabilities to absorb COBOL mainframe integration complexity that smaller competitors cannot resource, defending against hyperscaler encroachment into regulated financial workloads. Deepen captive validation node operations in Singapore's Marina Bay district to anchor Project Guardian infrastructure relationships. Prioritize backward integration into HSM manufacturing to secure hardware wallet supply chains against East Asian foundry concentration risk. For New Entrants and Emerging Players: API-first distribution partnerships with Indian banking consortia offer the most penetrable entry vector, bypassing entrenched vendor relationships in saturated European and North American markets. Target parametric smart contract development for insurance companies as the fastest-adopting segment with unmet demand for verified oracle integration. Pursue ISO 27001 certification early to unlock procurement channels with HIPAA-bound healthcare payers. For Investors and Strategic Acquirers: Distressed-cycle entries favor zero-knowledge proof engineering specialists in Switzerland and Germany facing talent cost inflation but holding irreplaceable cryptographic expertise. Long-term viability hinges on positioning within central bank digital currency pilot ecosystems rather than speculative token infrastructure. Watch Singapore MAS wholesale CBDC deployment timelines as the critical inflection signal for institutional liquidity migration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Middleware bridging COBOL mainframes to Ethereum environments absorbs largest project budgets at European banks. |
| Strategic Partnership | Central bank digital currency pilot participation anchors long-term vendor positioning across multiple jurisdictions. |
| Acquisition of Specialist Firm | Zero-knowledge proof engineering talent scarcity commands premium valuations for cryptographic capability access. |
| Geographic Expansion | Compliant node hosting in Mumbai and Bangalore captures RBI digital rupee pilot infrastructure demand. |
| Product Launch | Parametric smart contract platforms for catastrophe bonds unlock insurance company procurement budgets. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with blockchain infrastructure executives, neobank CTOs, central bank digital currency program directors, and insurance company innovation leads. SEC disclosure documents, EU MiCA implementation guidance, Singapore MAS technology risk management circulars, and RBI pilot program announcements provided regulatory validation. Customs records on cryptographic hardware imports and hyperscaler capital expenditure disclosures supplied supply chain calibration. Bottom-up project pipeline enumeration and top-down addressable market sizing underwent iterative reconciliation.
Data-stream reconciliation across payment processing transaction volumes, asset tokenization issuance pipelines, and smart contract deployment metrics informed the analytical framework across the analysis window. Segmentation modeling incorporated application type, technology architecture, service delivery mode, and end-user procurement authority. CAGRs derived from installed base growth curves and replacement cycle analysis, with cross-validation against central bank pilot timeline acceleration and regulatory compliance deadline clustering.
The model holds under stable regulatory implementation schedules; deviation in MiCA enforcement timing or SEC custody rule revision would shift deployment velocity assumptions. Forecasts reflect documented base-case assumptions regarding proof-of-stake network adoption and institutional tokenization regulatory clarity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Singapore AI in Fintech Market
FinTech
Saudi Arabia Fintech Market
FinTech
Netherlands AI in Fintech Market
FinTech
Wealthtech Solutions Market
FinTech
Account Checking Software Market
FinTech
Robo Advisory Market
FinTech
Spend Management Platform Market
FinTech
North America Fintech Market
FinTech
Europe Fintech Cloud Market
FinTech
Supply Chain Finance Market
FinTech
Canada AI in Fintech Market
FinTech
AI-Powered Wealth Management Solution Market
FinTech
Global Fintech Market
FinTech
Fintech Technologies Market
FinTech
UAE Fintech Market
FinTech
Singapore Fintech Market