
 Smart Bands Payments Market | 2026-2036
Smart Bands Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Bands Payments Market Analysis
Subscription-based payment token management is realigning how wearable OEMs monetize hardware deployments. Apple Inc. leverages its closed-loop Apple Pay infrastructure to sustain recurring transaction fee economics across its device base. Samsung Electronics Co., Ltd. anchors its position through Samsung Knox security layers that differentiate enterprise-grade payment bands from consumer alternatives.
Smart bands payments denote wrist-worn devices incorporating secure elements, near-field communication antennas, and tokenized credential storage to execute contactless financial transactions at point-of-sale terminals. These devices typically operate at 13.56 MHz for NFC protocols and embed EMV-compliant chips to substitute physical card credentials during authentication. Fitness bands dominate unit volume due to lower price points and minimal user interface requirements, while smartwatches capture disproportionate margin pools through premium positioning and multi-function utility. NFC technology leads transaction throughput for in-store proximity payments, though QR code integration gains traction in markets where merchant terminal penetration remains uneven.
The Federal Reserve's Regulation E and the Consumer Financial Protection Bureau's oversight of electronic fund transfers govern liability frameworks for wearable-initiated transactions in the United States, while the European Banking Authority's strong customer authentication requirements under PSD2 mandate multi-factor verification for band-based payments exceeding contactless thresholds. China's NMPA and SAMR jointly supervise biometric data collection from payment wearables, constraining how fingerprint or pulse-signature authentication layers integrate with financial apps. Stakeholders must monitor divergence between regional tokenization standards as fragmentation in certification requirements threatens cross-border wearable payment interoperability.
Market Dynamics
Tokenization standardization is compressing the competitive window for wearable payment hardware, as EMVCo specifications force OEMs to redesign secure element architectures before legacy implementations lose certification validity.
Growth Catalysts
- PSD2 Strong Customer Authentication:European Banking Authority mandates for biometric multi-factor verification are accelerating deployment of pulse-signature and fingerprint sensors in payment bands across EU member states.
- Transit Authority Modernization:Municipal transport systems in Seoul and London have adopted NFC wristband fare collection, creating installed base effects that spill into retail payment adoption.
- Secure Element Miniaturization:Advances in embedded chip packaging are enabling payment credential storage within fitness-optimized form factors previously constrained by physical antenna and processor requirements.
Market Restraints
- Silicon Supply Concentration:Secure element fabrication depends on a limited number of certified foundries, creating vulnerability to capacity constraints in East Asian semiconductor manufacturing clusters.
- EMVCo Certification Timeline:Tokenization compliance testing cycles extend 14-18 months, freezing product release schedules and compressing revenue recognition windows for new hardware generations.
- Smartphone Payment Substitution:Handset-based contactless wallets retain merchant terminal compatibility advantages and consumer familiarity, limiting wrist-worn device differentiation in mature payment markets.
Strategic Opportunities
- India UPI Wearable Integration:National Payments Corporation of India's open API framework for wearable form factors creates entry pathways for bands linking directly to bank account rails without card network intermediation.
- Healthcare-Payment Convergence:Biometric vital sign authentication from pulse-signature sensors enables dual-use devices that satisfy both health monitoring and payment verification requirements in single hardware units.
- Enterprise Access-Payment Bundling:Corporate campus credential systems in Japan and South Korea are merging building access, transit, and point-of-sale functions into single wearable tokens, expanding average revenue per deployed unit.
Industry Challenges
- Biometric Data Governance:China's NMPA and SAMR jointly supervise fingerprint and pulse-signature collection from payment wearables, creating compliance complexity for firmware architectures that must isolate health data from financial credential storage.
- Cross-Border Token Fragmentation:Divergent regional certification requirements between EMVCo, China's UnionPay, and India's RuPay specifications threaten interoperability for travelers and multinational corporate deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Bands Payments Market |
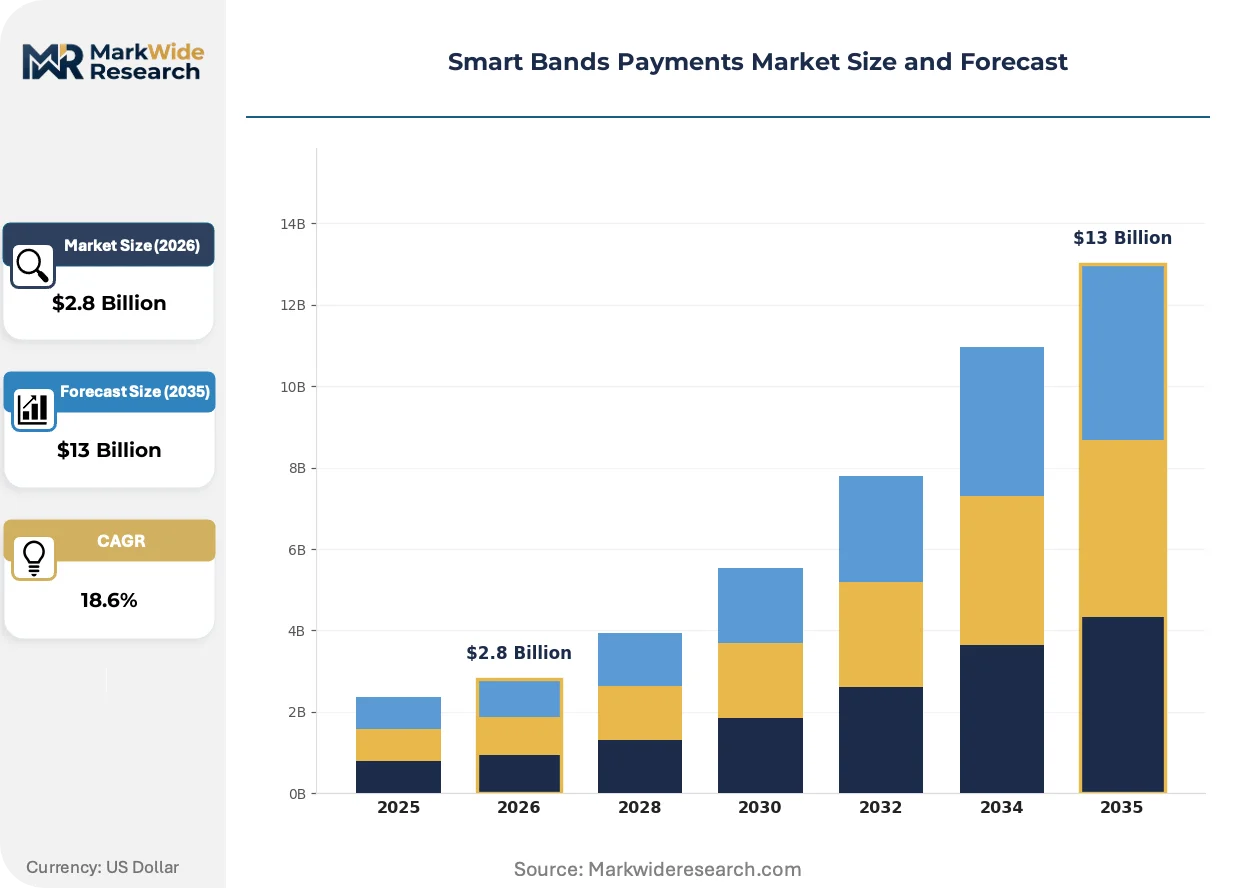
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fitness Bands, Smartwatches, Medical Bands, Fashion Bands Technology: NFC, Bluetooth, QR Code, Biometrics End User: Consumers, Enterprises, Healthcare Providers, Retailers Use Case: Personal Payments, Access Control, Health Tracking, Loyalty Programs |
| Companies Covered | Apple Inc., Samsung Electronics Co., Ltd., Fitbit Inc., Google LLC, Visa Inc., Mastercard, PayPal Holdings Inc., Barclays PLC, Xiaomi Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Bands Payments Market Emerging Trajectories
Hardware-software decoupling is redefining how payment credentials migrate across wearable devices, as cloud-based token provisioning reduces dependence on factory-embedded secure elements.
On-device machine learning for behavioral biometrics is automating continuous authentication during payment sessions. Transit authorities in London have piloted gait-pattern verification that eliminates explicit user action at fare gates. This compression of friction is automating throughput optimization in high-volume public transport corridors where transaction speed determines system capacity.
Europe's GDPR and the EU AI Act are imposing algorithmic transparency requirements on biometric authentication systems embedded in payment wearables. Device manufacturers must now document decision logic for pulse-signature matching algorithms and enable user-accessible explanation interfaces. Premium smartwatch segments are responding by segregating biometric processing to dedicated edge compute modules that enable audit trail isolation.
Subscription-based token lifecycle management is displacing perpetual hardware licensing in enterprise wearable deployments. Corporate purchasers in South Korea now procure payment bands through managed service contracts that include credential refresh, compliance updates, and device refresh cycles. This shift concentrates procurement authority with facilities management functions rather than traditional IT hardware acquisition channels.
Smart Bands Payments Market Segmentation
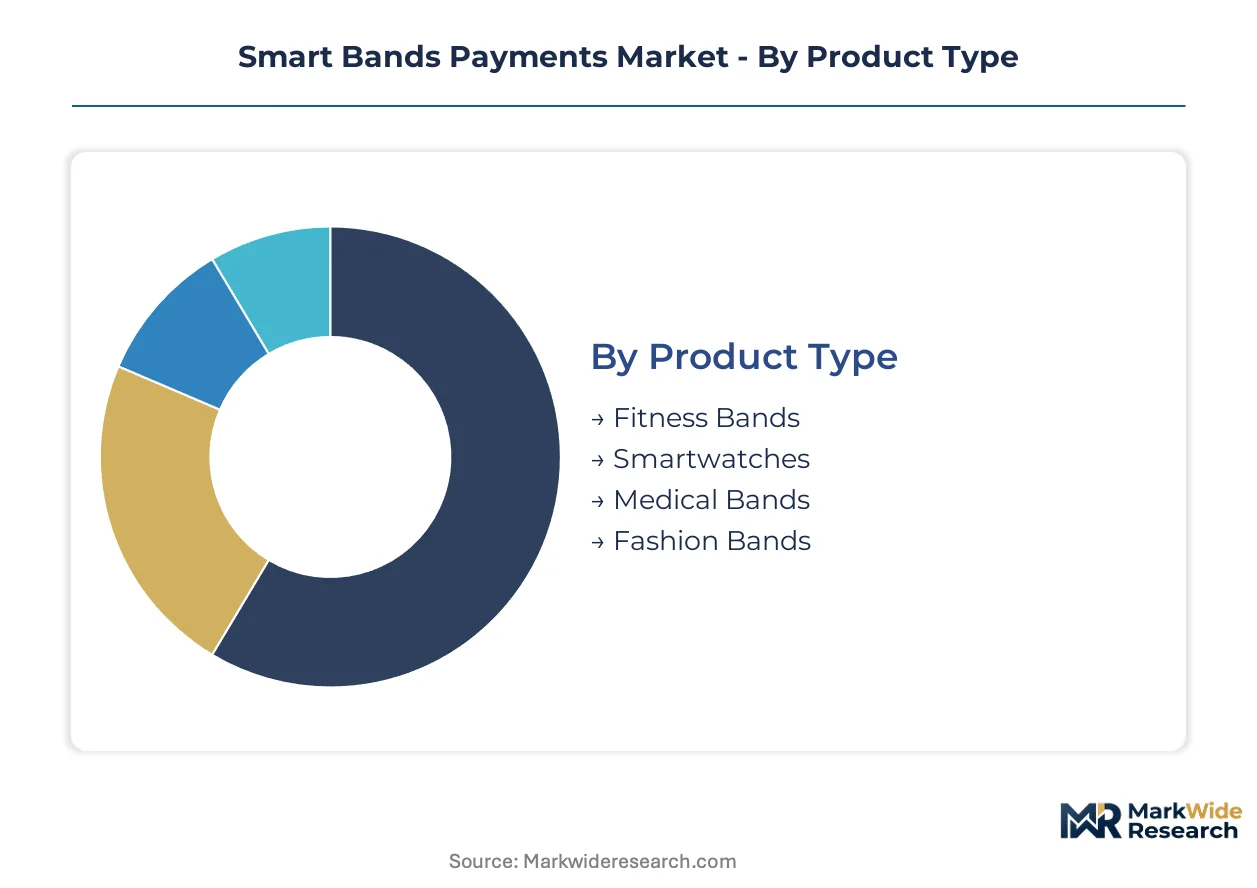
Segmentation in smart bands payments reveals how hardware form factors, authentication protocols, and deployment contexts determine capital allocation and margin capture. Product type and technology choices drive secure element architecture decisions, while end-user and use-case configurations shape recurring revenue models.
Product Type:
Capital intensity varies sharply across form factors, with medical-grade secure elements and FDA-equivalent certifications demanding the highest upfront investment.
- Fitness Bands:These devices embed stripped-down NFC antennas and minimal secure element storage, prioritizing battery longevity over transaction complexity. Demand concentrates in China, where Xiaomi and Huawei have built domestic payment ecosystems around sub-premium wearable devices. The segment's low unit economics depend on high-volume manufacturing clusters in Shenzhen and Dongguan.
- Smartwatches:Multi-function devices integrate EMV-compliant chips, biometric sensors, and cellular connectivity modules that triple bill-of-materials costs against fitness alternatives. Enterprise procurement in South Korea and Japan favors these units for campus access-payment bundling. Premium positioning sustains recurring token management fees.
- Medical Bands:Pulse-signature authentication and vital sign monitoring require isolated edge compute modules for GDPR and EU AI Act compliance. These devices serve healthcare providers seeking dual-use payment verification and patient monitoring.
- Fashion Bands:Minimalist designs sacrifice antenna performance for aesthetics, targeting loyalty program integration rather than full payment credential storage. European luxury houses have piloted limited editions with tokenized gift card functionality.
Fitness bands absorb the bulk of installed capacity; medical bands are expanding most quickly on healthcare-payment convergence.
Technology:
Authentication protocol selection determines terminal compatibility, certification burden, and geographic addressability.
- NFC:Operating at 13.56 MHz with EMVCo-compliant tokenization, this protocol dominates in-store proximity payments. Transit authorities in Seoul and London have standardized on NFC wristbands for fare collection, creating installed base spillover into retail adoption. The technology requires 14-18 month certification cycles that freeze product release schedules.
- Bluetooth:Low-energy protocols enable longer-range authentication for access control and vehicle entry, though merchant terminal penetration remains limited. Enterprise campus deployments in Japan leverage Bluetooth for building access-payment convergence.
- QR Code:Camera-dependent authentication gains traction in India where UPI wearable integration bypasses card network infrastructure. National Payments Corporation of India's open API framework enables direct bank account linkage.
- Biometrics:Pulse-signature and fingerprint sensors satisfy PSD2 strong customer authentication mandates across EU member states. China's NMPA and SAMR jointly supervise biometric data collection, constraining firmware architectures.
NFC captures the dominant transaction volume; biometrics is climbing the fastest on regulatory authentication requirements.
End User:
Procurement authority shifts from IT hardware channels to facilities management as subscription-based token lifecycle management displaces perpetual licensing.
- Consumers:Individual purchasers prioritize form factor comfort and smartphone ecosystem compatibility. Fitness bands dominate unit volume due to lower price points and minimal interface requirements.
- Enterprises:Corporate campus credential systems in Japan and South Korea merge building access, transit, and point-of-sale functions into single wearable tokens. Managed service contracts now include credential refresh and compliance updates.
- Healthcare Providers:Hospitals and clinics demand biometric vital sign authentication for both payment verification and patient monitoring. Dual-use devices reduce hardware proliferation.
- Retailers:Merchant-deployed bands for staff payments and loyalty program administration require centralized token provisioning and rapid credential rotation capabilities.
Consumers account for the greatest unit deployment; enterprises show the steepest expansion trajectory on subscription contract adoption.
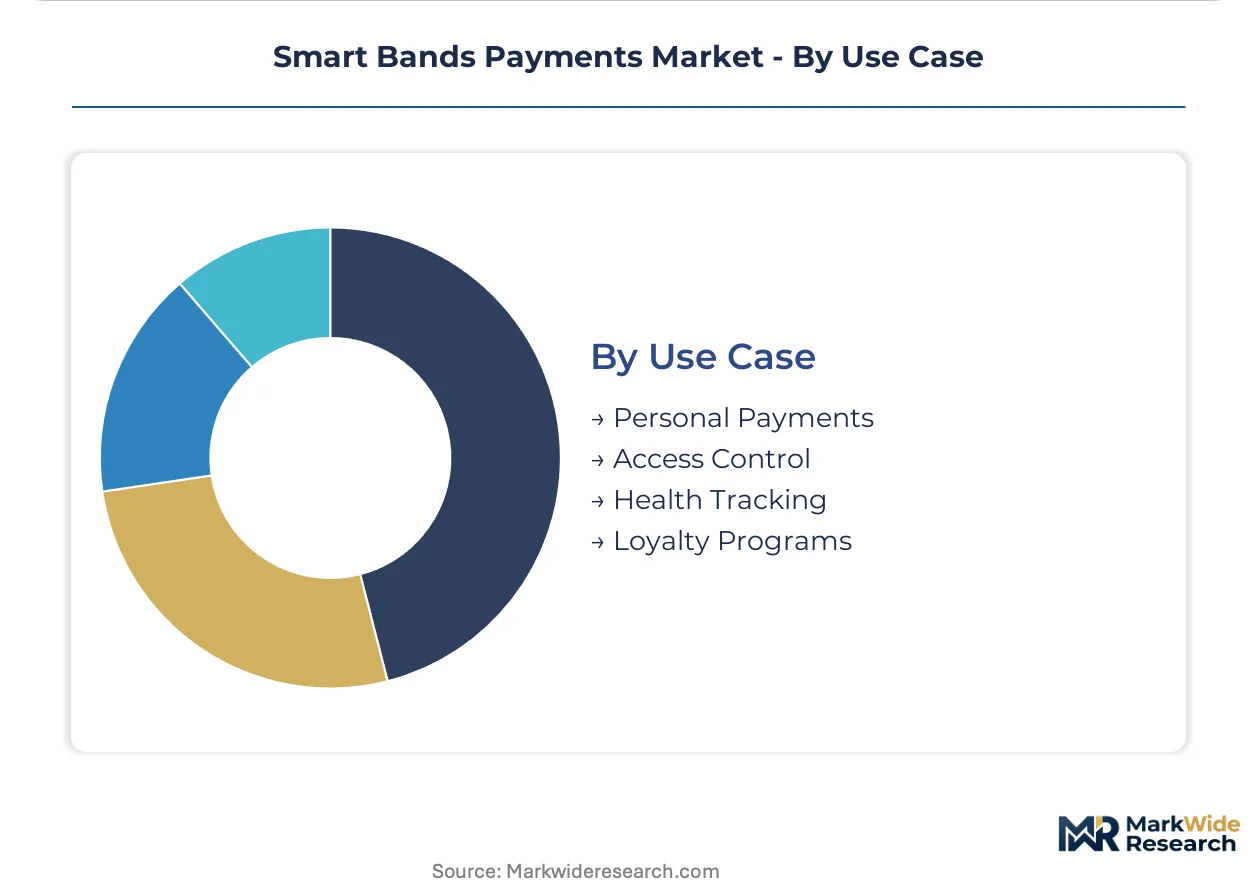
Use Case:
Application context determines friction tolerance, authentication frequency, and integration depth with existing infrastructure.
- Personal Payments:Point-of-sale contactless transactions require sub-500 millisecond authentication speed. London's transit authority piloted gait-pattern verification to eliminate explicit user action at fare gates.
- Access Control:Building entry and vehicle access prioritize longer-range detection over transaction speed. Bluetooth protocols dominate this application.
- Health Tracking:Vital sign monitoring generates biometric data that must remain isolated from financial credential storage per China's NMPA requirements. Pulse-signature authentication enables payment verification without additional sensors.
- Loyalty Programs:Reduced security requirements allow fashion bands with minimal secure element storage. Tokenized gift card functionality suffices for closed-loop merchant ecosystems.
Personal payments command the largest transaction volume; health tracking is gaining share fastest on healthcare-payment convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics manufacturing corridor anchors global smart band production, with Dongguan and Guangzhou satellite clusters feeding component supply chains for payment-enabled wearables.
China
Domestic payment ecosystems from Xiaomi and Huawei concentrate demand in the Yangtze River Delta and Pearl River Delta manufacturing belts. SAMR and NMPA jointly supervise biometric data collection from payment wearables, constraining firmware architectures that must isolate health data from financial credentials. Shenzhen's secure element packaging facilities enable high-volume production of fitness-optimized payment bands.
United States
Enterprise campus deployments and healthcare-payment convergence drive adoption in California's technology corridor and Texas medical centers. The Consumer Financial Protection Bureau oversees electronic fund transfer liability under Regulation E, while FDA-equivalent pathways govern medical-grade biometric authentication devices. Greater Boston hosts pilot programs for pulse-signature verification in hospital payment systems.
South Korea
Corporate campus credential systems in Seoul merge building access, transit, and point-of-sale functions into single wearable tokens. The Financial Services Commission enforces strong customer authentication requirements that accelerate biometric sensor deployment. Busan-Ulsan manufacturing clusters produce enterprise-grade secure elements for regional export.
United Kingdom
Transport for London's NFC wristband fare collection creates installed base effects that spill into retail payment adoption across Greater London. The Financial Conduct Authority implements PSD2 strong customer authentication mandates that drive multi-factor verification in payment bands. Cambridge hosts edge compute module development for GDPR-compliant biometric processing.
India
National Payments Corporation of India's open API framework enables direct bank account linkage for wearable form factors bypassing card network intermediation. RBI oversight governs UPI-based wearable transaction limits and liability frameworks. Bangalore's fintech development clusters prototype QR code authentication for markets with uneven merchant terminal penetration.
Smart Bands Payments Market Vendor Landscape
Capital-heavy semiconductor foundries compete with asset-light wearable designers for control of secure element architecture. The market structure concentrates around three tiers: integrated technology conglomerates with closed-loop payment infrastructure, component specialists supplying NFC antennas and biometric sensors, and regional OEMs leveraging domestic certification pathways. Strategic moves center on EMVCo certification pre-emption and healthcare-payment convergence partnerships that expand addressable use cases beyond retail transactions.
Within the integrated technology tier, Apple Inc. and Samsung Electronics Co., Ltd. exemplify divergent approaches to wearable payment monetization. Apple leverages closed-loop infrastructure to sustain recurring transaction fee economics, while Samsung anchors positioning through security layer differentiation. Xiaomi Corporation occupies a distinct geography-first position, building domestic payment ecosystems around sub-premium wearable devices in Chinese manufacturing clusters.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Fitbit Inc. |
| Google LLC |
| Visa Inc. |
| Mastercard |
| PayPal Holdings Inc. |
| Barclays PLC |
| Xiaomi Corporation |
| Others |
Supply Flow & Price Mechanics
Enterprise procurement managers in South Korea and Japan anchor contract negotiations for campus access-payment bundles, forcing OEMs toward subscription-based token lifecycle models that trade upfront hardware margins for recurring service revenue streams.
Pricing Analysis
Value-based pricing anchored to transaction throughput and uptime guarantees dominates enterprise wearable deployments, with subscription contracts bundling credential refresh, compliance updates, and device refresh cycles. Price differentiation separates EMVCo-certified medical-grade bands with isolated edge compute modules from fitness-optimized alternatives with stripped-down secure elements. Cost compression in the fitness band tier intensifies because Shenzhen manufacturing clusters enable high-volume production at minimal bill-of-materials overhead. Healthcare providers show the least price sensitivity due to dual-use payment-verification and patient-monitoring requirements, while individual consumers in China drive the most aggressive price negotiations for sub-premium wearable devices.
Supply Chain Analysis
Reverse-logistics flows for tokenized credential migration and secure element refurbishment create secondary value recovery channels as cloud-based provisioning reduces dependence on factory-embedded chips. Secure element fabrication concentrates in Taiwan, South Korea, and certified East Asian foundries, with antenna and biometric sensor assembly feeding from Dongguan and Guangzhou satellite clusters. Raw material dependencies span NFC ferrite substrates, EMV-compliant microcontroller units, and pulse-signature sensor arrays. Single-source vulnerability in certified semiconductor foundry capacity threatens production continuity when demand spikes coincide with transit authority modernization programs. Distribution runs through enterprise facilities management channels rather than traditional IT hardware procurement pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based token provisioning is displacing factory-embedded secure elements as the dominant credential architecture, compressing the competitive window for hardware-centric business models across wearable payment ecosystems.
For Market Incumbents: Anchor market position through EMVCo certification pre-emption and healthcare-payment convergence partnerships that expand addressable use cases beyond retail transactions. Samsung Knox security layers and Apple Pay closed-loop infrastructure exemplify defensive moats against emerging entrants leveraging India's UPI open API framework. Vertical integration into secure element packaging capabilities in Shenzhen manufacturing corridors protects margin structures from component cost volatility. For New Entrants and Emerging Players: India's National Payments Corporation open API framework for wearable form factors offers the most penetrable entry pathway, enabling direct bank account linkage without card network intermediation. QR code authentication for markets with uneven merchant terminal penetration, particularly in Bangalore's fintech development clusters, provides a second white-space target. A direct-to-bank go-to-market angle bypasses incumbent payment network gatekeepers entirely. For Investors and Strategic Acquirers: The window for entry favors component specialists with biometric sensor and NFC antenna capabilities that can pivot toward healthcare-payment convergence applications. Long-term viability hinges on regulatory certification assets rather than pure hardware volume scale. Watch for divergence between EMVCo, UnionPay, and RuPay tokenization standards as the critical inflection indicator threatening cross-border wearable payment interoperability.| Strategic Initiative | Industry Significance |
|---|---|
| EMVCo Certification Pre-emption | Accelerates product release schedules before legacy implementations lose validity under evolving tokenization standards. |
| Healthcare-Payment Convergence Partnership | Enables dual-use devices satisfying both pulse-signature authentication and patient monitoring requirements in hospital systems. |
| India UPI Wearable Integration | Bypasses card network intermediation through direct bank account rails under RBI oversight frameworks. |
| Enterprise Access-Payment Bundling | Merges building access, transit, and point-of-sale functions into single wearable tokens for corporate campus deployments. |
| Cloud-Based Token Provisioning | Reduces hardware dependence and enables credential migration across devices without factory-embedded secure elements. |
Methodological Framework
Independent corroboration across wearable OEM product managers, transit authority procurement officers, and secure element foundry engineers underwrites the qualitative findings in this study. Primary interviews with EMVCo certification specialists, hospital biomedical engineers, and enterprise facilities management directors combined with secondary validation from SEC filings of payment network operators, EMVCo specification documents, and National Payments Corporation of India API disclosures. Bottom-up triangulation across device shipment estimates and top-down reconciliation against transaction volume data ensure analytical consistency.
Comparable-period anchoring to historical certification cycle timelines and transit authority deployment schedules structured the forecast window across the projection horizon. Segmentation dimensions modeled include product type tier, authentication protocol, end-user procurement authority, and geographic regulatory cluster. CAGRs derived from installed base accumulation curves and replacement cycle dynamics incorporate healthcare-payment convergence adoption rates and subscription contract penetration trajectories as industry-specific forecast inputs.
Revisions become necessary when EMVCo specification updates accelerate certification obsolescence, when biometric data governance frameworks tighten in China's NMPA and SAMR jurisdictions, or when secure element foundry capacity constraints materialize. Practitioners should monitor cross-border token fragmentation between regional certification standards and enterprise procurement channel shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
North America Payment Analytics Software Market
Payments
China Prepaid Cards Market
Payments
Gift Card and Incentive Card Market
Payments
Master Recharge API Market
Payments
Belgium POS Terminals Market
Payments
Freight Audit and Payment Service Market
Payments
Contactless Payment Ring Market
Payments
Asia-Pacific Payment Gateway Market
Payments
Blockchain Payments Software Market
Payments
France Buy Now Pay Later Services Market
Payments
Taiwan Mobile Payments Market
Payments
South Korea Digital Payments Market
Payments
Global Payment Processor Market
Payments
Bus Card Reader Market
Payments
Australia Mobile Payment Market
Payments
Contactless Payment Terminals Market