
 Digital Livestock Farming Market | 2026-2036
Digital Livestock Farming Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Livestock Farming Market Insights
Buyer concentration among commercial dairy cooperatives is restructuring procurement patterns across the Digital Livestock Farming Market. DeLaval International leverages its installed base of milking systems to cross-sell connected herd management platforms. GEA Farm Technologies anchors its competitive position through backward integration into sensor hardware and automated feeding controls. Allflex Livestock Intelligence differentiates via specialized animal identification and traceability systems that integrate with broader farm software ecosystems.
Digital livestock farming encompasses the deployment of networked sensors, automated control systems, and data analytics platforms to monitor animal health, optimize feeding regimens, and manage reproduction cycles across cattle, swine, and poultry operations. Core functional parameters include real-time rumination monitoring through accelerometer collars, automated milk yield measurement with conductivity-based mastitis detection, and cloud-based feed ration optimization algorithms that adjust dry matter intake based on lactation stage. Farm management software and livestock tracking solutions capture the dominant share of current value as legacy record-keeping systems convert to cloud platforms, while artificial intelligence and data analytics represent the fastest-expanding technology layers as predictive models for disease onset and fertility windows mature from pilot to production scale.
The EU Green Deal and F-Gas Regulation shape equipment standards for climate-controlled livestock housing across European markets, while the USDA and FDA influence animal health data protocols and antibiotic traceability requirements in the United States. REACH and CE marking directives govern sensor material safety and electromagnetic compatibility for devices deployed in agricultural environments. Stakeholders must monitor evolving carbon accounting methodologies and animal welfare certification standards as these frameworks increasingly determine market access and premium pricing eligibility for protein outputs.
Market Dynamics
The EU Green Deal's carbon accounting mandates are restructuring capital allocation across livestock operations, forcing producers to prioritize emissions-tracking infrastructure alongside traditional productivity metrics. This regulatory pressure is compressing technology procurement cycles and favoring vendors with integrated sensor-to-software platforms.
Growth Catalysts
- EU Green Deal compliance deadlines:National carbon accounting mandates in the Netherlands, Denmark, and Germany are accelerating investment in methane-monitoring sensors and automated feed optimization systems that reduce enteric emissions.
- Precision dairy infrastructure:Commercial cooperatives in northern Europe are deploying networked accelerometer collars for real-time rumination tracking, creating pull-through demand for cloud-based herd management platforms.
- F-Gas Regulation equipment standards:Climate-controlled housing requirements under EU F-Gas rules are driving replacement cycles for ventilation and cooling systems with connected monitoring capabilities.
Market Restraints
- Sensor hardware supply concentration:Electromagnetic compatibility-certified accelerometer and conductivity sensor production concentrates among specialized German and Dutch component suppliers, creating input bottlenecks.
- REACH material compliance costs:Sensor housings and battery enclosures must satisfy ECHA substance restrictions, adding certification overhead that disadvantages smaller equipment vendors.
- Legacy system integration friction:Proprietary data formats from incumbent milking equipment block seamless connectivity with third-party analytics platforms, slowing platform consolidation.
Strategic Opportunities
- Swine and poultry digitization gaps:Cattle operations capture disproportionate technology investment, leaving automated feeding and health monitoring penetration below 15% in intensive pork and broiler facilities.
- AI-driven fertility prediction:Machine learning models analyzing pedometer and temperature data are expanding into commercial deployment, enabling service-based pricing for reproduction management.
- Carbon credit verification infrastructure:Methane quantification sensors that generate auditable emissions data are positioning livestock operations for participation in compliance and voluntary carbon markets.
Industry Challenges
- Veterinary data science talent scarcity:Interpretation of sensor-derived health indicators requires combined livestock medicine and analytics expertise that training pipelines have not scaled to match deployment growth.
- CE marking timeline compression:Electromagnetic compatibility and safety certification for new sensor form factors faces backlog at notified bodies, delaying product launches by 8-14 months.
- Interoperability standard fragmentation:Competing data exchange protocols between farm management software platforms force producers into single-vendor lock-in or expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Livestock Farming Market |
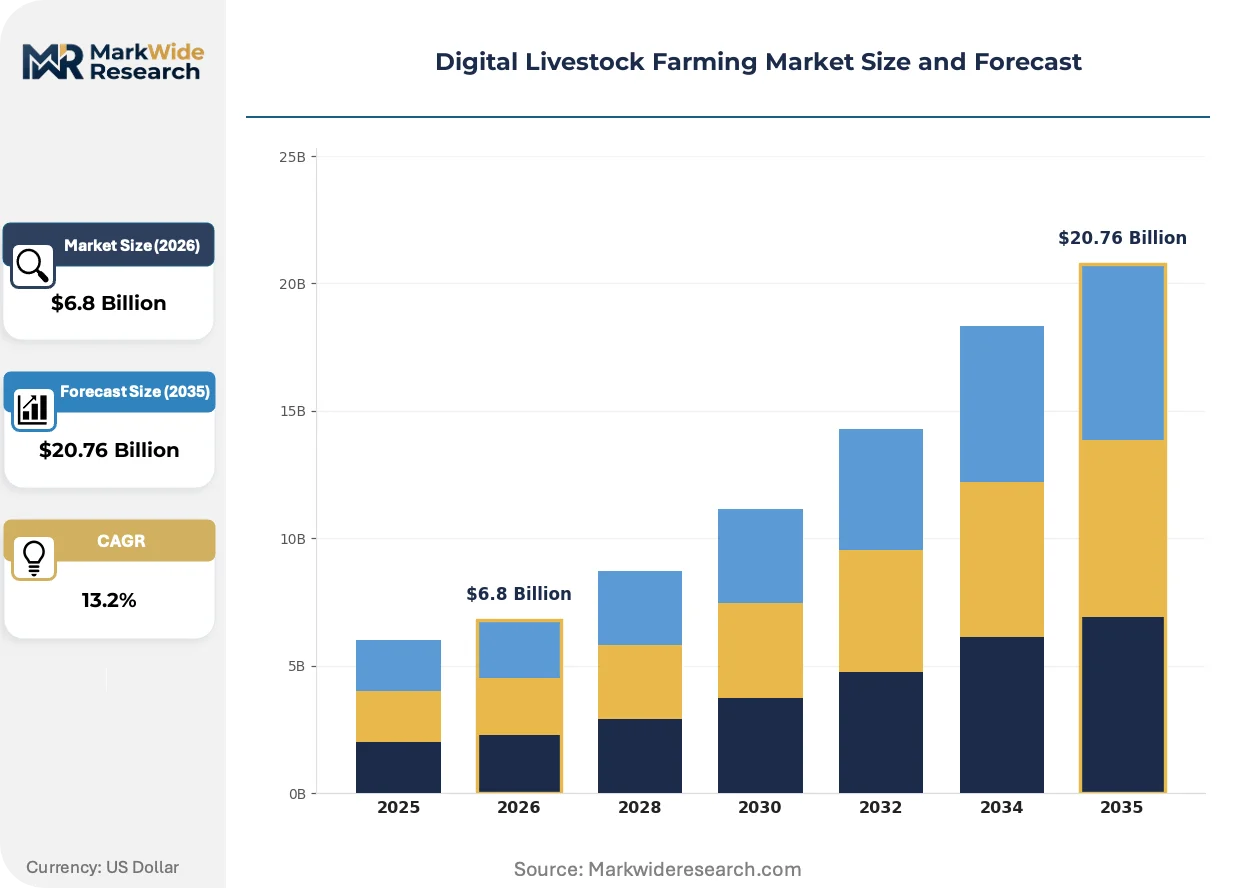
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $20.76 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
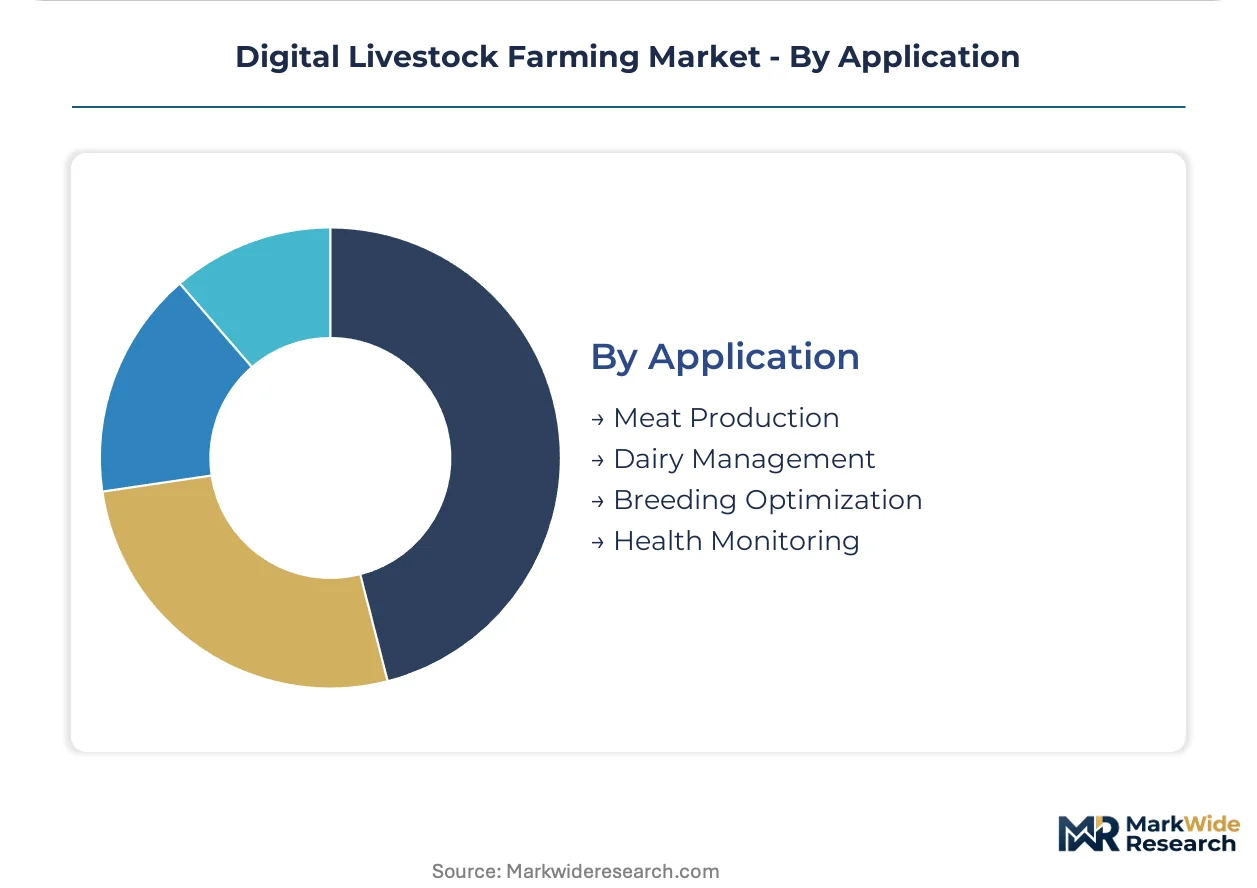
| Segmentation | Product Type: Farm Management Software, Livestock Tracking Solutions, Disease Management Systems, Feeding Automation Tools Technology: IoT Devices, Cloud Computing, Artificial Intelligence, Data Analytics End User: Commercial Farms, Smallholder Farmers, Agricultural Cooperatives, Research Institutions Application: Meat Production, Dairy Management, Breeding Optimization, Health Monitoring |
| Companies Covered | GEA Farm Technologies, DeLaval International, Lely International, Allflex Livestock Intelligence, SCR Dairy, Nedap, Afimilk, AgriWebb, Hexagon AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Livestock Farming Market Trends and Innovations
Sensor fusion architectures and edge computing are collapsing the latency between data capture and actionable insight, enabling real-time intervention in feeding and health management that batch-processed systems cannot match.
Computer vision systems for automated body condition scoring and lameness detection are expanding into commercial dairy operations, with large-scale cooperatives in Denmark and the Netherlands piloting camera-based monitoring in tie-stall and free-stall barns. These installations reduce labor hours for visual inspection while generating continuous datasets that train predictive models for metabolic disorder onset, compressing the window between symptom emergence and veterinary intervention.
REACH and F-Gas Regulation amendments are tightening material and refrigerant specifications for climate-controlled livestock housing equipment, with ECHA substance restriction proposals targeting persistent organic pollutants in sensor coatings. Equipment manufacturers are reformulating housing materials and accelerating heat pump adoption to maintain CE marking eligibility, with the Netherlands and Germany showing fastest compliance retrofit activity due to national building code alignment with EU directives.
Cooperative procurement consortia are consolidating technology purchasing across member farms, displacing individual farm-level vendor negotiations with centralized platform selection and volume-based service agreements. This concentration is visible in Dutch dairy cooperatives, where collective bargaining for sensor hardware and cloud subscriptions has reduced per-cow technology costs and locked in multi-year vendor relationships that resist competitive displacement.
Digital Livestock Farming Market Segmentation
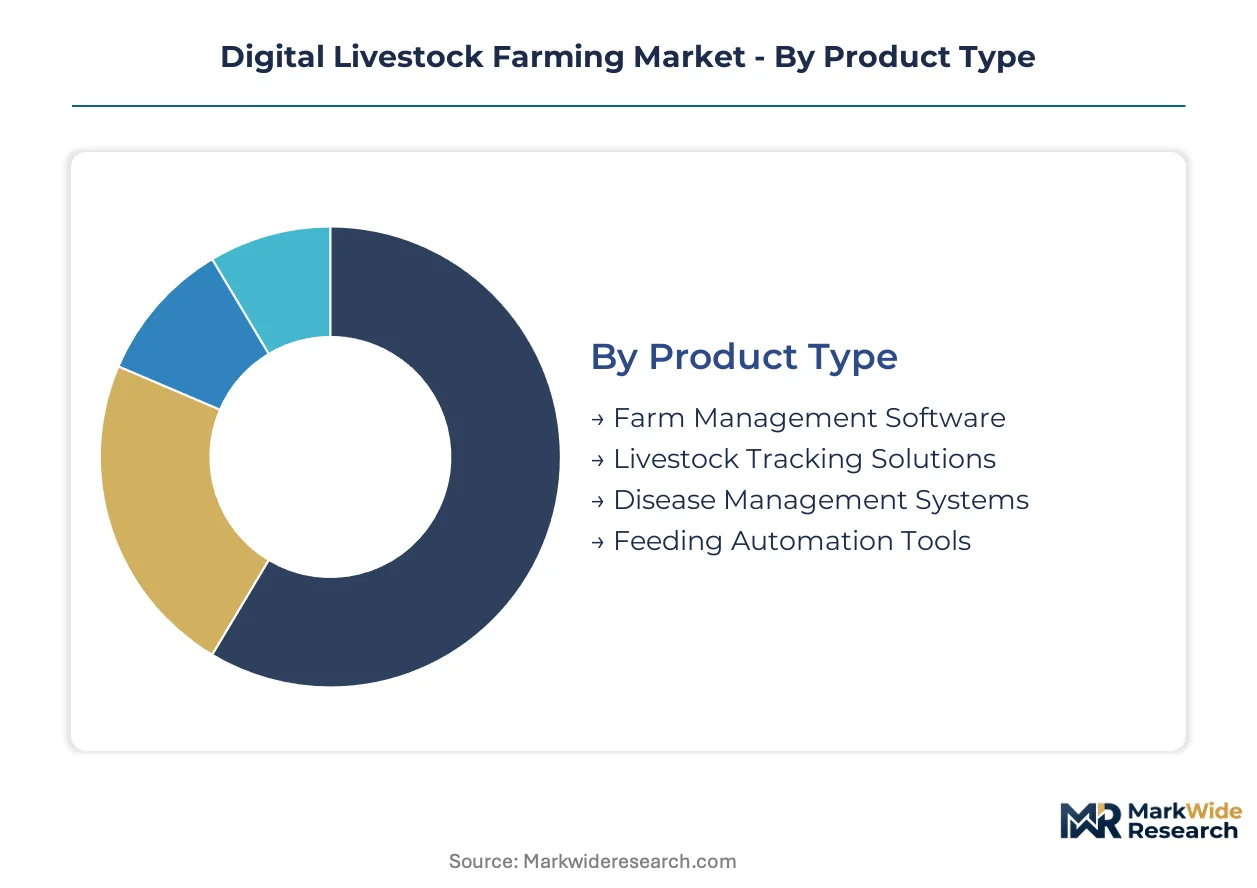
Technology procurement patterns in digital livestock farming diverge sharply by operational scale and regulatory exposure. Buyers select platforms based on integration complexity with legacy milking infrastructure, carbon accounting compliance requirements, and cooperative procurement structures.
Product Type:
Investment thresholds separate buyers seeking modular point solutions from those demanding integrated sensor-to-software platforms.
- Farm Management Software:Cloud-based platforms consolidating herd records, reproduction calendars, and financial tracking into unified dashboards. Demand concentrates among Dutch and Danish dairy cooperatives where EU Green Deal carbon reporting mandates require centralized data aggregation for scope 3 emissions verification.
- Livestock Tracking Solutions:RFID ear tags, accelerometer collars, and GPS-enabled monitoring devices capturing real-time location and behavioral metrics. German commercial farms are deploying these systems to satisfy EFSA traceability requirements while optimizing grazing rotation patterns on fragmented pasture holdings.
- Disease Management Systems:Sensor networks detecting mastitis through milk conductivity analysis and rumination pattern anomalies.
- Feeding Automation Tools:Programmable dispensers and ration optimization algorithms adjusting dry matter intake by lactation stage.
Volume sits with Farm Management Software; growth tilts toward Livestock Tracking Solutions.
Technology:
Deployment maturity varies dramatically across the technology stack, with hardware layers facing certification bottlenecks that software layers bypass.
- IoT Devices:Electromagnetic compatibility-certified sensors for temperature, pH, and activity monitoring requiring REACH-compliant housings and CE marking validation. Netherlands-based component suppliers dominate accelerometer production, creating input concentration that extends procurement timelines for non-integrated vendors.
- Cloud Computing:Distributed data infrastructure enabling multi-farm aggregation and cooperative-level analytics without on-premise server investment. Danish agricultural cooperatives leverage these platforms to centralize carbon accounting across member farms, reducing per-farm compliance costs through shared subscription models.
- Artificial Intelligence:Machine learning models predicting fertility windows and metabolic disorder onset from sensor-derived behavioral patterns.
- Data Analytics:Visualization tools and predictive dashboards translating raw sensor feeds into actionable husbandry interventions.
Cloud Computing captures the largest installed base; Artificial Intelligence is climbing the fastest as predictive models mature from pilot to production scale.
End User:
Procurement authority and capital access determine platform sophistication, with cooperatives extracting volume discounts unavailable to individual operators.
- Commercial Farms:Large-scale operations with dedicated technology staff and direct vendor relationships. German dairy enterprises are retrofitting existing milking parlors with sensor networks to meet F-Gas Regulation ventilation standards while capturing methane emissions data for carbon credit eligibility.
- Agricultural Cooperatives:Member-owned consortia centralizing technology selection and negotiating multi-year service agreements. Dutch dairy cooperatives have pioneered collective procurement models that reduce per-cow platform costs and lock in vendor relationships resistant to competitive displacement.
- Smallholder Farmers:Individual operators with limited capital and technical expertise, typically served through subsidized extension programs.
- Research Institutions:Universities and government laboratories validating sensor accuracy and developing predictive algorithms.
Commercial Farms dominate current procurement volume; Agricultural Cooperatives are gaining share fastest as collective bargaining structures proliferate across northern Europe.
Application:
Return-on-investment timelines vary by application, with health monitoring delivering measurable productivity gains that justify upfront sensor deployment costs.
- Dairy Management:Integrated platforms combining milk yield monitoring, mastitis detection, and reproductive cycle tracking. Netherlands operations lead deployment density, driven by cooperative financing structures and national carbon accounting frameworks that reward emissions-reducing feed optimization.
- Health Monitoring:Continuous physiological surveillance through rumination sensors, temperature probes, and computer vision lameness detection. Danish commercial herds are piloting camera-based body condition scoring to compress veterinary intervention windows for metabolic disorders.
- Meat Production:Growth optimization and feed conversion tracking in cattle, swine, and poultry operations.
- Breeding Optimization:Genetic selection support through fertility prediction and pedigree management systems.
Dairy Management retains the deepest technology penetration; Health Monitoring is expanding most quickly as computer vision and edge computing enable real-time intervention capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer foundries in the Netherlands supply the accelerometer substrates that underpin sensor hardware across northern European dairy operations. The EU Green Deal's carbon accounting framework is redrawing procurement geography, concentrating technology deployment in jurisdictions with cooperative financing structures and national emissions verification systems.
Netherlands
Dutch dairy cooperatives command the densest sensor deployment per capita, driven by FrieslandCampina's collective procurement consortia. The EU Green Deal's scope 3 reporting requirements force member farms to adopt methane-monitoring infrastructure for carbon credit eligibility. Eindhoven's precision agriculture cluster houses Nedap and accelerometer component suppliers serving cross-border German and Belgian operations.
Germany
German commercial dairies retrofit existing parlors with networked ventilation controls to satisfy F-Gas Regulation equipment standards. The country's national carbon accounting mandate, operational since 2024, requires documented feed optimization protocols for operations exceeding 500 head. Bavaria's Allgäu region hosts concentrated pilot programs for camera-based lameness detection in tie-stall configurations.
Denmark
Danish agricultural cooperatives leverage cloud computing platforms to centralize emissions data across member farms, reducing per-farm compliance costs through shared subscription models. Arla Foods' procurement consortium negotiates multi-year sensor hardware agreements that lock in vendor relationships. The central Jutland corridor exhibits highest penetration of computer vision body condition scoring systems.
United States
US large-scale dairy operations deploy sensor networks under USDA conservation program incentives that subsidize precision feeding infrastructure. FDA antibiotic traceability requirements drive adoption of RFID-linked health record systems in vertically integrated supply chains. California's Central Valley and Wisconsin's Fox River Valley concentrate deployment of automated milking system retrofits.
Australia
Australian grazing operations adopt GPS-enabled livestock tracking to optimize rotation patterns across fragmented pastoral holdings. The country's national livestock identification system mandates electronic tagging, creating baseline infrastructure for behavioral monitoring expansion. Victoria's Gippsland region leads commercial deployment of cloud-based herd management platforms among export-oriented dairy cooperatives.
Digital Livestock Farming Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-driven fertility prediction and carbon credit verification services as differentiation vectors. The vendor base stratifies across three tiers: integrated milking equipment manufacturers with captive sensor platforms, specialized livestock intelligence firms with traceability expertise, and software-native entrants lacking hardware production capabilities. Dominant competitive moves include backward integration into electromagnetic compatibility-certified component production and multi-year service agreements negotiated through cooperative procurement consortia.
Within the integrated equipment tier, DeLaval International and GEA Farm Technologies exemplify vendors leveraging installed milking system bases to cross-sell connected herd management platforms. Allflex Livestock Intelligence occupies a distinct position as a specialized animal identification and traceability provider that integrates with broader farm software ecosystems rather than competing for platform dominance. These three entities represent the primary competitive archetypes: equipment-anchored integrators, component-specialized independents, and software-centric challengers.
| Leading Market Players |
|---|
| GEA Farm Technologies |
| DeLaval International |
| Lely International |
| Allflex Livestock Intelligence |
| SCR Dairy |
| Nedap |
| Afimilk |
| AgriWebb |
| Hexagon AB |
| Others |
Pricing and Supply Chain Analysis
Veterinary data science talent scarcity in the Netherlands and Denmark widens pricing spreads between premium integrated platforms and modular point solutions, as labor-cost differentials for combined livestock medicine and analytics expertise compress margins at the economy tier while reinforcing vendor lock-in at the premium tier.
Pricing Analysis
Volume concentrates in standardized SaaS subscriptions for farm management software while margins concentrate in AI-driven fertility prediction services with outcome-based pricing. Price differentiation rests on CE marking certification status and cooperative procurement scale, with Dutch and Danish agricultural consortia extracting volume discounts unavailable to individual operators. Cost compression in sensor hardware is intensifying because REACH material compliance overhead disadvantages smaller equipment vendors. Smallholder farmers served through subsidized extension programs exhibit highest price sensitivity; commercial dairy cooperatives with dedicated technology staff show lowest sensitivity due to multi-year service agreement structures.
Supply Chain Analysis
Regional distribution centers in Eindhoven and Bavaria operate hub-and-spoke patterns serving cross-border German, Dutch, and Belgian operations. Electromagnetic compatibility-certified accelerometer production concentrates in the Netherlands and Germany, with silicon wafer substrates drawing from specialized foundries. Single-source vulnerability runs through Dutch component suppliers dominating collar-based sensor assemblies. Distribution feeds from cooperative procurement consortia negotiating centralized platform selection and volume-based service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors with integrated sensor-to-software platforms, as EU Green Deal carbon accounting mandates force smaller point-solution providers into acquisition or exit.
For Market Incumbents: Acquire electromagnetic compatibility-certified component production capabilities to secure accelerometer supply and compress CE marking timelines. Anchor backward integration into sensor hardware manufacturing to defend against software-native entrants lacking production capabilities. Prioritize multi-year service agreements with cooperative procurement consortia to lock in vendor relationships resistant to competitive displacement. For New Entrants and Emerging Players: Cloud-based channel partnerships with existing farm management software ecosystems offer the lowest-friction entry path. Target swine and poultry digitization gaps where automated feeding and health monitoring penetration remains below intensive cattle operations. Pursue AI-driven carbon credit verification services as a service-based pricing wedge distinct from capital-intensive hardware competition. For Investors and Strategic Acquirers: Re-rating potential sits with specialized livestock intelligence firms possessing traceability expertise given accelerating FDA antibiotic traceability requirements and EFSA compliance mandates. Long-term viability favors vendors with captive sensor production and established cooperative relationships over software-only challengers. Watch CE marking timeline compression at notified bodies as an inflection indicator for hardware launch velocity and working capital efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Hardware | Captive supply of REACH-compliant accelerometer housings reduces ECHA certification bottlenecks for Dutch and German vendors. |
| Cooperative Procurement Consortium Partnership | Multi-year platform agreements with FrieslandCampina and Arla Foods lock in volume commitments resistant to competitive displacement. |
| AI-Driven Fertility Prediction Service Launch | Machine learning models analyzing pedometer data enable outcome-based pricing distinct from capital-intensive hardware sales. |
| Carbon Credit Verification Infrastructure Buildout | Methane quantification sensors generating auditable emissions data position livestock operations for compliance and voluntary carbon markets. |
| Computer Vision Lameness Detection Pilot | Camera-based body condition scoring in Danish tie-stall configurations compresses veterinary intervention windows for metabolic disorders. |
Research Methodology
Multi-period observation of sensor deployment density, cooperative procurement contract structures, and CE marking timeline trends anchored the trend analysis, supplemented by interviews with dairy cooperative technology officers, livestock sensor hardware procurement leads, farm management software integration specialists, and ECHA regulatory compliance consultants. Secondary validation drew from EU Green Deal implementation progress reports, ECHA substance restriction proposals, FDA antibiotic traceability guidance documents, and agricultural cooperative financial disclosures. Bottom-up farm-level technology spend estimates triangulated against top-down vendor revenue aggregation across the analysis window.
Segment-weighting approaches modeled technology layer adoption curves, operational scale procurement authority, and regulatory exposure tiers without assuming uniform penetration rates. The analytical framework applied differential CAGRs across farm management software, livestock tracking solutions, and artificial intelligence layers based on cloud infrastructure maturity and predictive model commercialization timelines. Forecast inputs incorporated EU F-Gas Regulation equipment replacement cycles and national carbon accounting mandate compliance deadlines as demand-pull variables.
The model holds under continued EU Green Deal implementation and stable REACH enforcement intensity; deviation in ECHA substance restriction scope or notified body certification capacity would shift hardware launch timelines and vendor competitive positioning. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Animal Identification Market
Livestock Management
South America Swine Feed Market
Livestock Management
Colombia Animal Feed Market
Livestock Management
Africa Alfalfa Hay Market
Livestock Management
Cattle Feeder Market
Livestock Management
Dairy Herd Management Market
Livestock Management
Morocco Poultry Market
Livestock Management
South America Ruminant Feed Market
Livestock Management
Pig Feed Market
Livestock Management
Europe Feed Binders Market
Livestock Management
Wagyu Beef Market
Livestock Management
Layer Breeding System Market
Livestock Management
Cattle Squeeze Market
Livestock Management
China Swine Feed Market
Livestock Management
Europe Swine Feed Market
Livestock Management
North America Feed Binders Market