
 Sports Events Market | 2026-2036
Sports Events Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Events Market Analysis
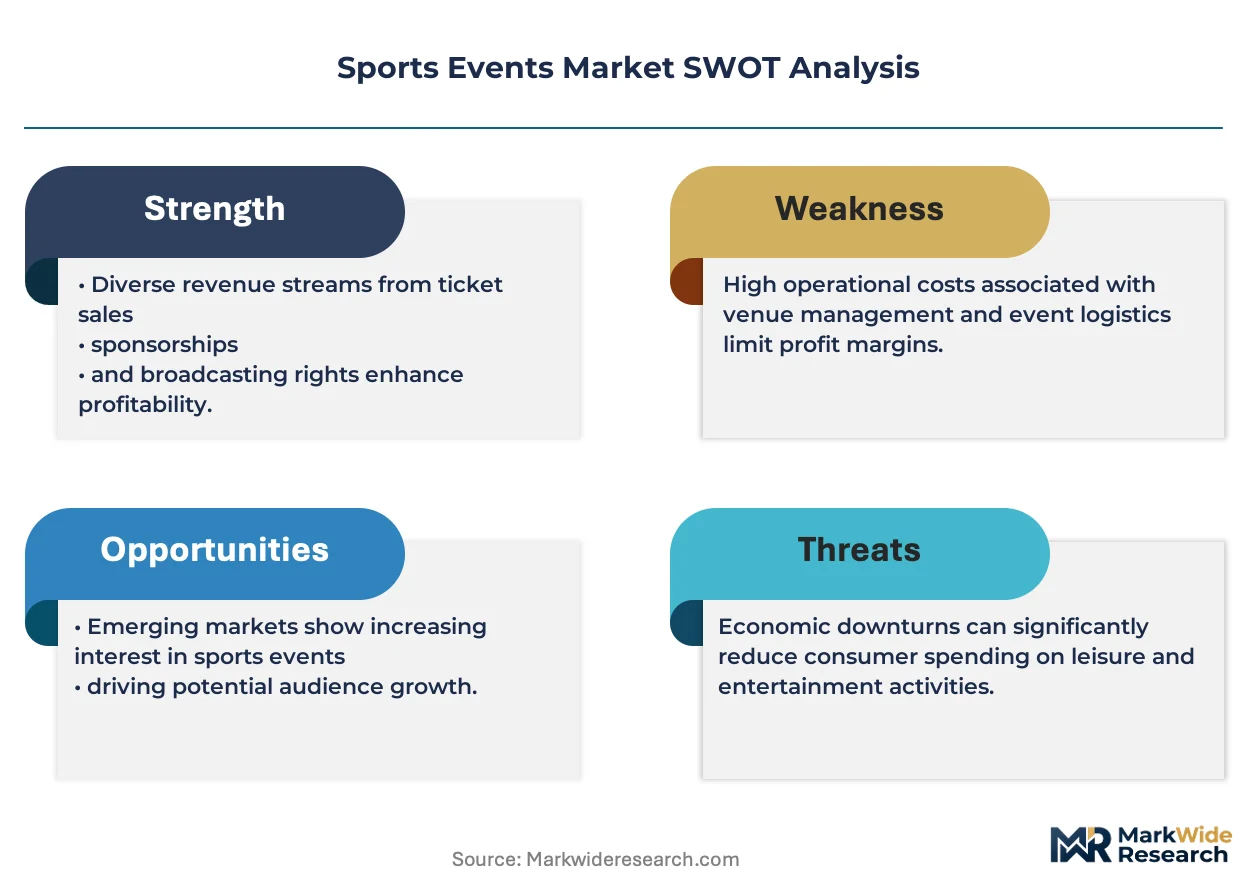
Corporate hospitality buyer concentration is hardening as multinational firms consolidate annual event spending with fewer preferred venue partners. Live Nation Entertainment leverages its vertically integrated venue-ticketing-promotion stack to capture premium corporate accounts. Anschutz Entertainment Group sustains geographic dominance through its controlled arena network across North American and European metropolitan cores. The Madison Square Garden Company differentiates via exclusive media rights and proprietary venue technology platforms.
Sports events encompass organized competitive athletic competitions and associated live entertainment experiences delivered through purpose-built or adapted venues, requiring integrated crowd management systems, broadcast infrastructure, and real-time digital engagement platforms. These events generate commercial value through direct audience participation, media distribution, and ancillary consumption in hospitality and merchandise. Football matches and marathons occupy the largest revenue pools, while basketball tournaments register faster audience growth among younger demographics. VIP ticketing segments capture disproportionate margin contribution, though general admission volume underwrites stadium utilization economics.
FCC regulations govern broadcast rights allocation and anti-siphoning rules for televised sports in the United States, while OSHA standards enforce crowd safety protocols and emergency egress requirements at large-capacity venues. EPA guidelines influence stadium construction permits and environmental impact assessments for new developments. Stakeholders must monitor evolving data privacy frameworks governing biometric fan identification and mobile payment ecosystems.
Market Dynamics
Biometric stadium access systems are compressing entry times while generating behavioral data streams that reshape sponsorship valuation models across professional sports venues.
Growth Catalysts
- Corporate Experiential Spending:Multinational firms consolidate annual hospitality budgets with fewer venue partners, concentrating procurement power and extending contract durations.
- FCC Anti-Siphoning Framework:Broadcast rights allocation rules preserve free-to-air access for marquee events, sustaining mass audience bases that underpin advertising rates.
- Mobile Payment Infrastructure:Stadium ecosystems integrate contactless commerce platforms, reducing friction at concession points and capturing incremental per-capita spend.
Market Restraints
- Construction Cost Escalation:Steel and concrete input volatility elevates capital requirements for new venue developments, compressing developer returns.
- EPA Permitting Timelines:Environmental impact assessments for large-capacity stadiums extend approval cycles, delaying revenue commencement.
- Broadcast Fragmentation:Streaming subscription fatigue among younger demographics threatens aggregate viewership concentration that legacy media bundles provided.
Strategic Opportunities
- India Sports Infrastructure:Underdeveloped purpose-built venues for cricket and emerging football leagues present greenfield development potential.
- Biometric-Facial Recognition Convergence:Integrated identity verification enables personalized fan experiences and dynamic pricing execution.
- OSHA Safety Mandates:Crowd management compliance requirements create service contract demand for specialized technology vendors.
Industry Challenges
- Legacy System Integration:Older venues face technical debt burdens when retrofitting IoT sensor networks and real-time data platforms.
- Skilled Crowd Safety Personnel:Certified emergency management specialists command premium wages, elevating operational fixed costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Events Market |
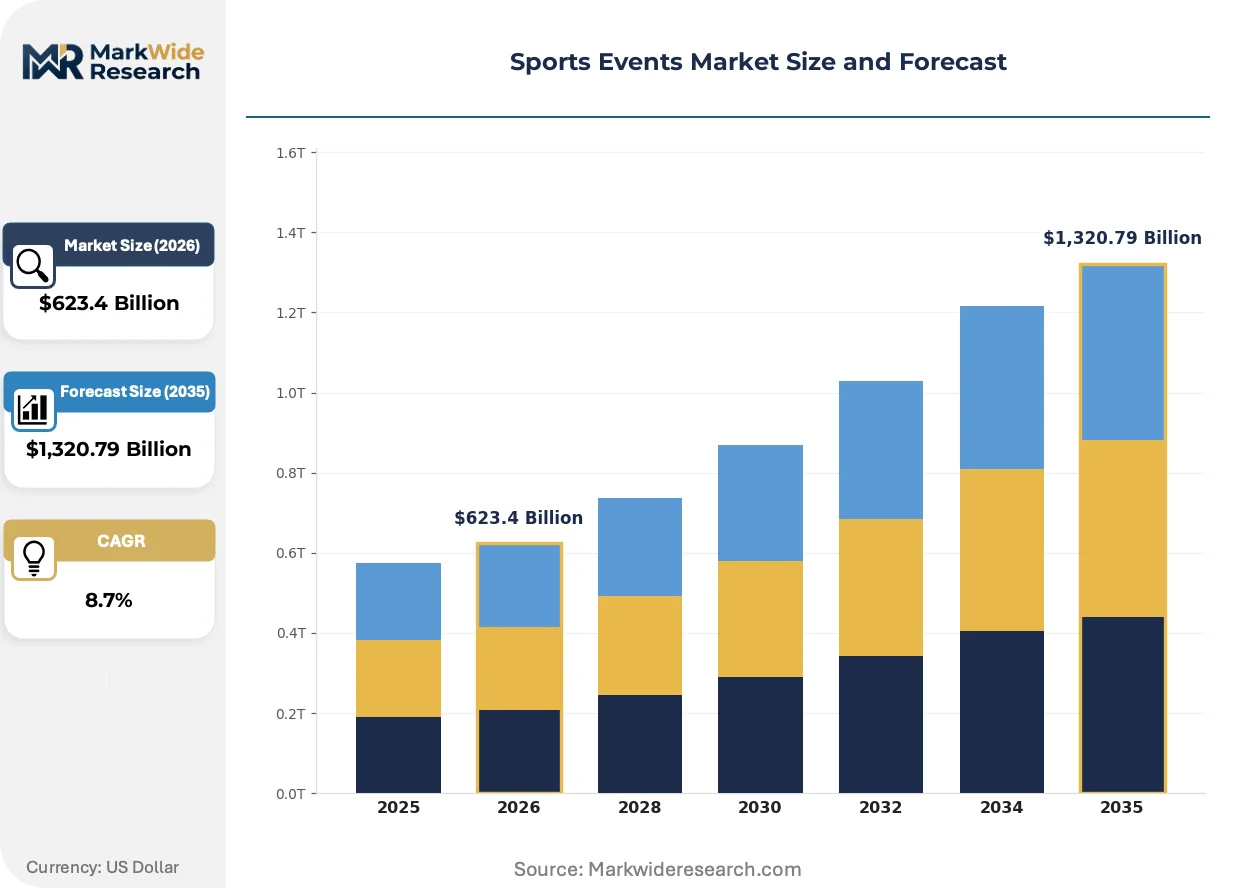
| Market Size in 2026 | $623.4 Billion |
| Market Size in 2035 | $1,320.79 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Event Type: Marathons, Football Matches, Basketball Tournaments, Tennis Championships Ticket Category: VIP, General Admission, Early Bird, Student Discounts Audience Demographic: Families, Millennials, Corporate Groups, Sports Enthusiasts Revenue Stream: Ticket Sales, Merchandise, Sponsorship, Broadcasting Rights |
| Companies Covered | Live Nation Entertainment Inc., Anschutz Entertainment Group, The Madison Square Garden Company, Comcast Spectacor, Ticketmaster, StubHub, SeatGeek, International Management Group, Sportfive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Events Market Emerging Trajectories
Digital infrastructure investments are reconfiguring how venues monetize attendance, shifting revenue capture from static ticket sales to dynamic, behavior-triggered transactions throughout the event experience.
Facial recognition access control is rewriting stadium entry protocols by eliminating physical credential exchange. Premium seating holders at NBA and NFL venues adopt these systems fastest, cutting ingress times by half. The technology is compressing sponsorship activation windows into personalized, real-time engagement moments.
GDPR and emerging state-level biometric privacy statutes in the United States impose consent and data retention obligations on fan identification systems. Venue operators must architect separate data governance frameworks for European and American attendees. Football clubs with transatlantic exhibition schedules face the steepest compliance complexity.
Corporate hospitality buyers now demand outcome-guaranteed packages rather than per-seat inventory commitments. Sports properties respond with revenue-sharing structures tied to measurable client engagement metrics. This recalibration concentrates most visibly in the United States, where Fortune 500 procurement departments apply stringent ROI thresholds to experiential spending.
Sports Events Market Segmentation
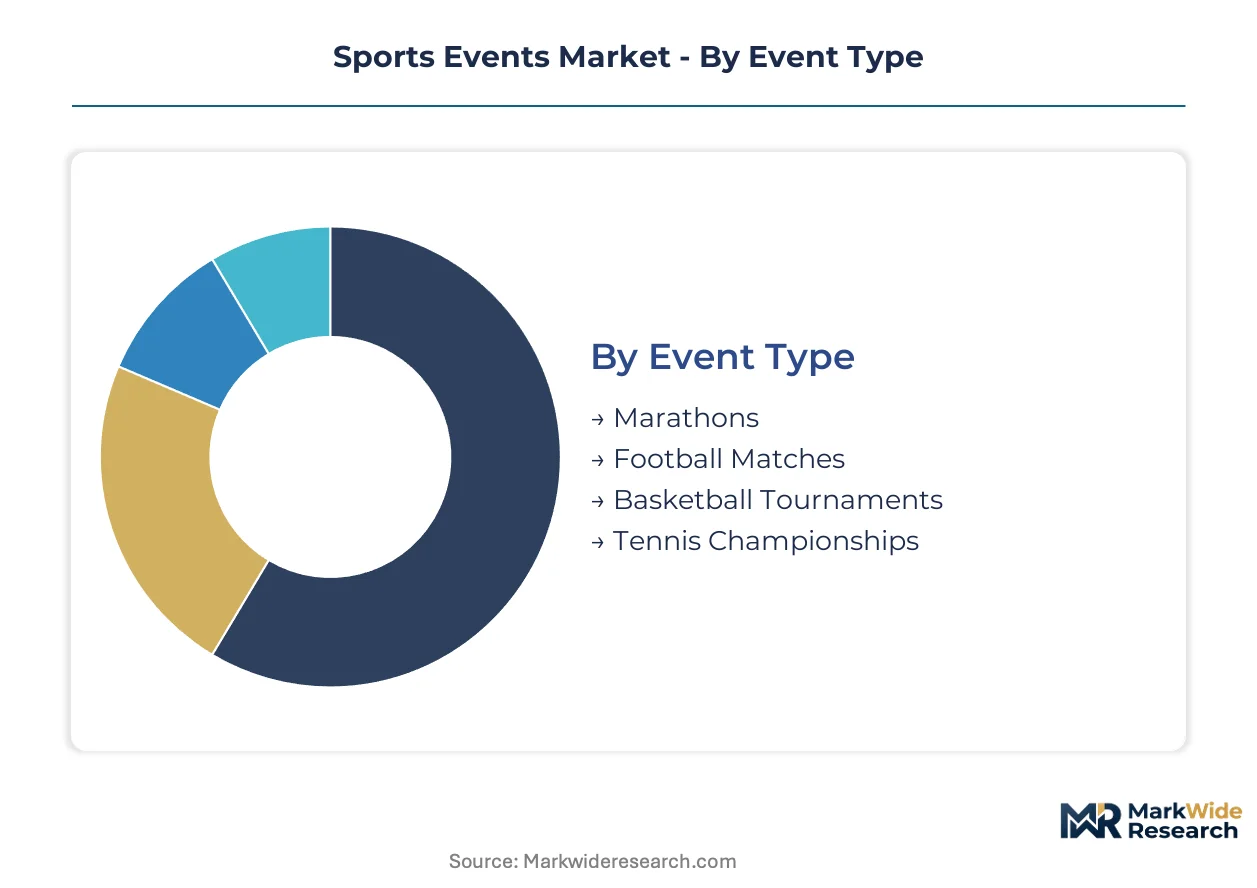
Sports events monetization varies dramatically across audience composition and commercial structure. Segmentation reveals how venue operators and rights holders allocate capital between mass-market volume plays and premium experience extraction.
Event Type:
Customization spans intimate boutique competitions to standardized mega-events with fixed broadcast windows and rigid infrastructure requirements.
- Football Matches:Professional league fixtures and international tournaments command the largest venue capacities and longest advance booking cycles. European club competitions and North American franchise systems anchor stadium financing models through guaranteed season-ticket bases and multi-year media contracts.
- Marathons:Mass-participation road races combine elite athlete fields with recreational runner entry fees, creating dual revenue architecture. City governments in Boston, London, and Tokyo leverage these events for destination tourism positioning and municipal brand elevation.
- Basketball Tournaments:Single-elimination college and professional formats concentrate viewership into compressed windows. Arena configurations prioritize court-side proximity and club seating density over raw capacity.
- Tennis Championships:Grand Slam and ATP/WTA tour events operate on fortnight schedules with variable daily attendance pricing. Grass, clay, and hard court surfaces dictate venue specialization and limit multi-sport reuse.
Leading the category by volume: Football Matches. Growing fastest: Basketball Tournaments.
Ticket Category:
Margin concentration follows a steep tiered structure where a small share of inventory generates disproportionate profit contribution.
- VIP:Hospitality suites, all-inclusive clubs, and premium seating pods integrate food service, parking, and exclusive access into bundled pricing. Corporate procurement departments negotiate multi-year blocks for client entertainment and employee retention programming.
- General Admission:Standard seating sections provide the attendance foundation that validates stadium operating economics and satisfies broadcast visual density requirements. Dynamic pricing algorithms adjust these tickets based on opponent quality, weather, and team performance trajectory.
- Early Bird:Advance purchase discounts lock in cash flow and reduce no-show rates through sunk-cost commitment. Season-ticket holders and fan club members receive priority windows before public release.
- Student Discounts:Price-sensitive young adult segments receive targeted promotions to build lifetime fan affinity and populate lower-demand sections. Verification partnerships with university enrollment systems reduce arbitrage and scalping.
Highest margin capture: VIP. Steepest volume contribution: General Admission.
Audience Demographic:
Behavioral segmentation separates occasional attendees seeking social occasion from high-frequency participants motivated by tribal identification.
- Corporate Groups:B2B hospitality buyers demand outcome-guaranteed packages with measurable client engagement metrics rather than per-seat inventory. Procurement consolidation favors venues with integrated meeting facilities and transportation logistics.
- Sports Enthusiasts:Core fan bases exhibit price inelasticity for premium matchups and playoff contention, sustaining season-ticket renewal rates. These segments over-index on merchandise consumption and digital subscription adoption.
- Families:Multi-generational attendance drives demand for safe viewing environments, convenient parking, and child-friendly concession options. Weekend matinee scheduling and promotional giveaways target this segment.
- Millennials:Digital-native attendees prioritize mobile-first ticketing, cashless venues, and shareable in-stadium moments over traditional loyalty programs. Social media integration and augmented reality activations capture this cohort.
Deepest per-capita spend: Corporate Groups. Fastest digital adoption: Millennials.
Revenue Stream:
Cash flow timing and predictability diverge sharply between upfront ticket commitments and contingent performance-based income.
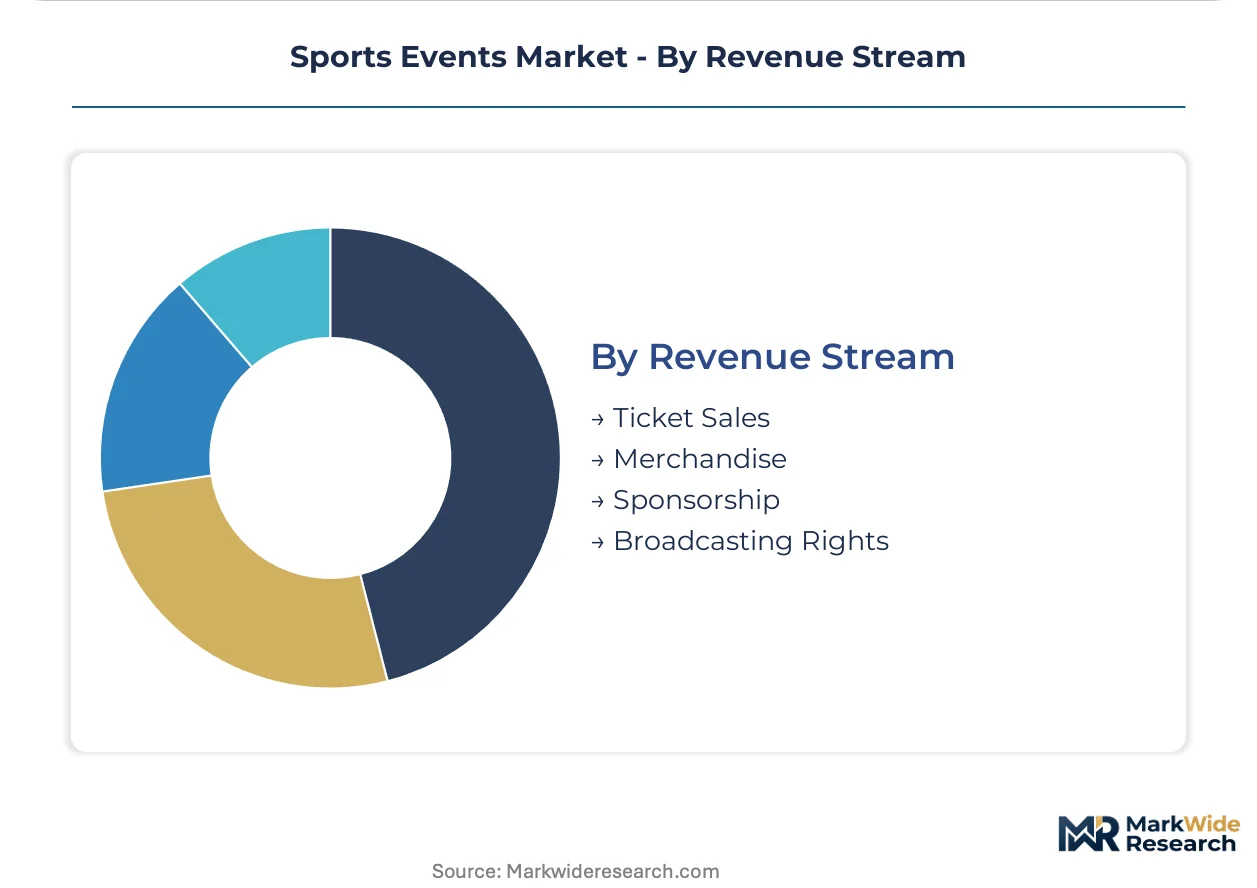
- Broadcasting Rights:Multi-year league and event media contracts provide the revenue foundation that underwrites player salaries and facility debt service. FCC anti-siphoning rules in the United States preserve free-to-air access for marquee events.
- Sponsorship:Brand partnerships span venue naming rights, jersey patches, and in-game activation integrations. Biometric access systems generate behavioral data that reshape sponsorship valuation models.
- Ticket Sales:Direct attendance revenue remains vulnerable to competitive performance and external disruption. Mobile payment infrastructure reduces friction at purchase points and enables dynamic pricing execution.
- Merchandise:Licensed apparel and collectibles extend monetization beyond event windows through e-commerce and retail partnerships. Limited-edition drops and player-specific products drive scarcity premiums.
Most predictable cash flow: Broadcasting Rights. Highest margin expansion: Sponsorship.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate hospitality buyers concentrate procurement power with United States-based venue operators, while emerging football markets in Asia and the Middle East attract greenfield stadium investment. Regulatory frameworks governing broadcast rights and biometric data collection vary sharply across jurisdictions, shaping where technology vendors prioritize deployment.
United States
Franchise league structures and privately financed stadium developments anchor investment flows, with NFL and NBA venues driving premium seating innovation. FCC anti-siphoning rules preserve free-to-air access for marquee events, sustaining mass audience bases that underpin advertising rates. Los Angeles and Las Vegas host the most aggressive venue construction pipelines, with SoFi Stadium and Allegiant Stadium exemplifying integrated entertainment district models.
United Kingdom
Premier League football clubs and Wimbledon-style heritage tournaments sustain dual revenue architecture from broadcast and hospitality streams. GDPR imposes strict consent and data retention obligations on biometric fan identification systems deployed at Wembley and Tottenham Hotspur Stadium. London concentrates venue technology vendors and corporate hospitality agencies serving European multinational accounts.
Germany
Bundesliga clubs operate under 50+1 ownership rules that limit private capital concentration, producing distinctive stadium financing models. REACH and RoHS regulations influence construction materials specifications for venue retrofits and new builds. Munich and Dortmund anchor industrial clusters supplying crowd management technology and LED display systems to stadium operators across Europe.
China
Government-backed sports infrastructure investment supports football league expansion and multi-purpose arena development in tier-one cities. MIIT standards govern broadcast transmission equipment and digital ticketing platform interoperability. Shanghai and Beijing metropolitan authorities prioritize venue clusters that integrate with commercial retail and transit hubs.
India
Cricket stadium modernization and emerging Indian Super League football venues present greenfield development opportunities for integrated technology systems. BIS certification requirements apply to imported crowd safety equipment and structural materials. Mumbai and Ahmedabad host the largest venue construction projects, with Narendra Modi Stadium setting capacity benchmarks for cricket-specific facilities.
Sports Events Market Vendor Landscape
United States producers anchor the premium venue-ticketing-promotion tier; European specialists hold differentiated positions in football-centric hospitality and media rights. Market structure consolidates around vertically integrated platform operators capable of delivering end-to-end event experiences, while regional venue managers compete on location-specific exclusivity. Three archetypes dominate: integrated entertainment conglomerates controlling arena networks, pure-play ticketing technology vendors, and specialized sports marketing agencies. Competitive intensity manifests through exclusive venue partnerships and biometric platform licensing rather than price-based rivalry.
Within the integrated entertainment tier, Live Nation Entertainment Inc. and Anschutz Entertainment Group exemplify geographic scale advantages through controlled venue networks across North American and European metropolitan cores. The Madison Square Garden Company occupies a distinctive position combining proprietary arena assets with media rights and technology platform development. These operators represent how venue ownership, ticketing infrastructure, and promotion capabilities converge to capture corporate hospitality procurement consolidation.
| Leading Market Players |
|---|
| Live Nation Entertainment Inc. |
| Anschutz Entertainment Group |
| The Madison Square Garden Company |
| Comcast Spectacor |
| Ticketmaster |
| StubHub |
| SeatGeek |
| International Management Group |
| Sportfive |
| Others |
Supply Flow & Price Mechanics
VIP-corporate versus general-admission bifurcation creates divergent margin architectures across venue tiers, with premium hospitality bundling commanding sustained pricing power while mass-market ticketing faces dynamic compression from algorithmic yield management. This divergence manifests in supply chain configurations where biometric infrastructure and integrated payment platforms concentrate procurement with technology vendors serving tier-one stadium operators, while legacy venues absorb retrofit costs that erode operating leverage.
Pricing Analysis
Volume-versus-margin splits separate corporate hospitality procurement from general-admission yield management across venue portfolios. Three-tier pricing structure across premium, standard, and economy levels captures differential willingness-to-pay through bundled amenities, dynamic seat-location premiums, and advance-purchase discounts. Price differentiation rests on opponent quality metrics and real-time demand signals rather than static season schedules. Cost compression in general-admission tiers is intensifying because streaming alternatives reduce attendance inelasticity for routine matchups. Corporate buyers exhibit lowest price sensitivity due to client-entertainment budget insulation, while student segments and occasional attendees drive highest elasticity.
Supply Chain Analysis
BIS certification requirements for crowd safety equipment and MIIT standards for digital ticketing platforms are reshaping sourcing patterns toward domestic-content compliance in India and China. Geographic supply concentration centers on Germany for LED display systems and crowd management technology, China for integrated biometric hardware and mobile payment infrastructure, and the United States for venue management software and broadcast equipment. Raw material dependencies include high-grade steel for stadium structural components, rare-earth elements for LED manufacturing, and semiconductor chips for access control systems. Single-source vulnerability runs through specialized biometric sensor suppliers concentrated in East Asian manufacturing clusters. Distribution runs through direct venue operator contracts and league-level technology partnerships rather than open-market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sports events infrastructure is transitioning from static ticketing toward biometric-integrated, behavior-triggered monetization platforms that displace legacy credential-based access systems. This technology replacement cycle concentrates investment decisions around data architecture and real-time personalization capabilities.
For Market Incumbents: Hedge against biometric platform commoditization by deepening exclusive venue partnerships and captive data analytics capabilities. Live Nation Entertainment and Anschutz Entertainment Group demonstrate how controlled arena networks create switching costs that protect corporate hospitality relationships from pure-play technology vendors. FCC regulatory shifts on data privacy and emerging state-level biometric statutes in the United States threaten centralized fan identification architectures, elevating compliance infrastructure as a defensive priority.
For New Entrants and Emerging Players: Enter via underdeveloped cricket and football infrastructure in India, where greenfield stadium construction lacks integrated technology systems and established vendor relationships. The Indian Super League and venue modernization programs present the most penetrable geography for biometric access and mobile payment platform providers. A go-to-market angle anchored in BIS certification assistance and domestic-content compliance reduces procurement friction with public-sector stadium developers.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated venue-technology operators given corporate hospitality procurement consolidation and the shift toward outcome-guaranteed experiential packages. Long-term viability over a multi-year horizon favors platforms combining physical venue assets with proprietary data infrastructure and media rights. Acquisition target archetypes include specialized crowd management technology vendors with OSHA compliance expertise and biometric platform developers with GDPR-architected systems. The signal to watch as inflection indicator is league-level mandates for cashless venue operations and facial recognition access standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Platform Integration | Facial recognition access at SoFi Stadium and Tottenham Hotspur Stadium halves ingress times and enables real-time sponsorship activation. |
| Corporate Hospitality Consolidation | Fortune 500 procurement departments concentrate annual event spending with fewer venue partners possessing integrated meeting facilities. |
| Greenfield Stadium Development | Narendra Modi Stadium in Ahmedabad and emerging Indian Super League venues create demand for purpose-built technology systems. |
| Data Governance Architecture | GDPR and emerging US state biometric statutes require separate compliance frameworks for transatlantic exhibition schedules. |
| Mobile Payment Infrastructure | Contactless commerce platforms at NFL and NBA venues reduce concession friction and capture incremental per-capita spend. |
Methodological Framework
Document review covered SEC filings from Live Nation Entertainment and Madison Square Garden Sports, FCC regulatory dockets on broadcast rights allocation, EPA environmental impact assessments for stadium developments, and league financial disclosures, complemented by interviews with venue operations executives, corporate hospitality procurement managers, sports marketing agency principals, and biometric technology vendors. Secondary validation drew from OSHA crowd safety compliance records, BIS certification databases for Indian stadium equipment, and MIIT standards documentation for Chinese digital infrastructure. Bottom-up venue capacity and attendance modeling triangulated against top-down league revenue aggregates.
Cross-referencing historical franchise valuation trends against panel input from stadium financing specialists and broadcast rights consultants anchored the projection framework across the analysis window. Segmentation dimensions modeled include event type, ticket category, audience demographic, and revenue stream, with additional granularity on biometric technology deployment status and corporate hospitality contract duration. CAGRs were derived from convergence of demand-side attendance projections and supply-side venue construction pipelines. Industry-specific forecast inputs incorporated FCC anti-siphoning rule stability assumptions and EPA permitting timeline distributions for large-capacity developments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory acceleration on biometric data privacy or sustained steel and concrete cost volatility extending stadium financing timelines. Forecasts reflect assumptions on corporate experiential spending durability and streaming subscription fatigue patterns among younger demographics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Ultra Mobile Devices (UMD) Market
Others
South Korea Smart Home Market
Others
Construction Fabrics Market
Others
China Online Gambling Market
Others
China Cloud Gaming Technology Market
Others
United States Air Furnaces Market
Others
Dried Fruit Extracts Market
Others
Global Aircraft Lighting Systems Market
Others
DIY Smart Home Market
Others
Content Experience Platforms Market
Others
Europe Air Separation Unit Market
Others
Middle East and Africa Home Care Packaging Market
Others
Wearable AI Market
Others
Global Car Wax Market
Others
Global OTA Testing Market
Others
Flexographic Printing Plate Market