
 Channel-In-A-Box (Ciab) Market | 2026-2036
Channel-In-A-Box (Ciab) Market Size, Share, and Industry Trends Forecast 2026-2036
Channel-In-A-Box (Ciab) Market Outlook
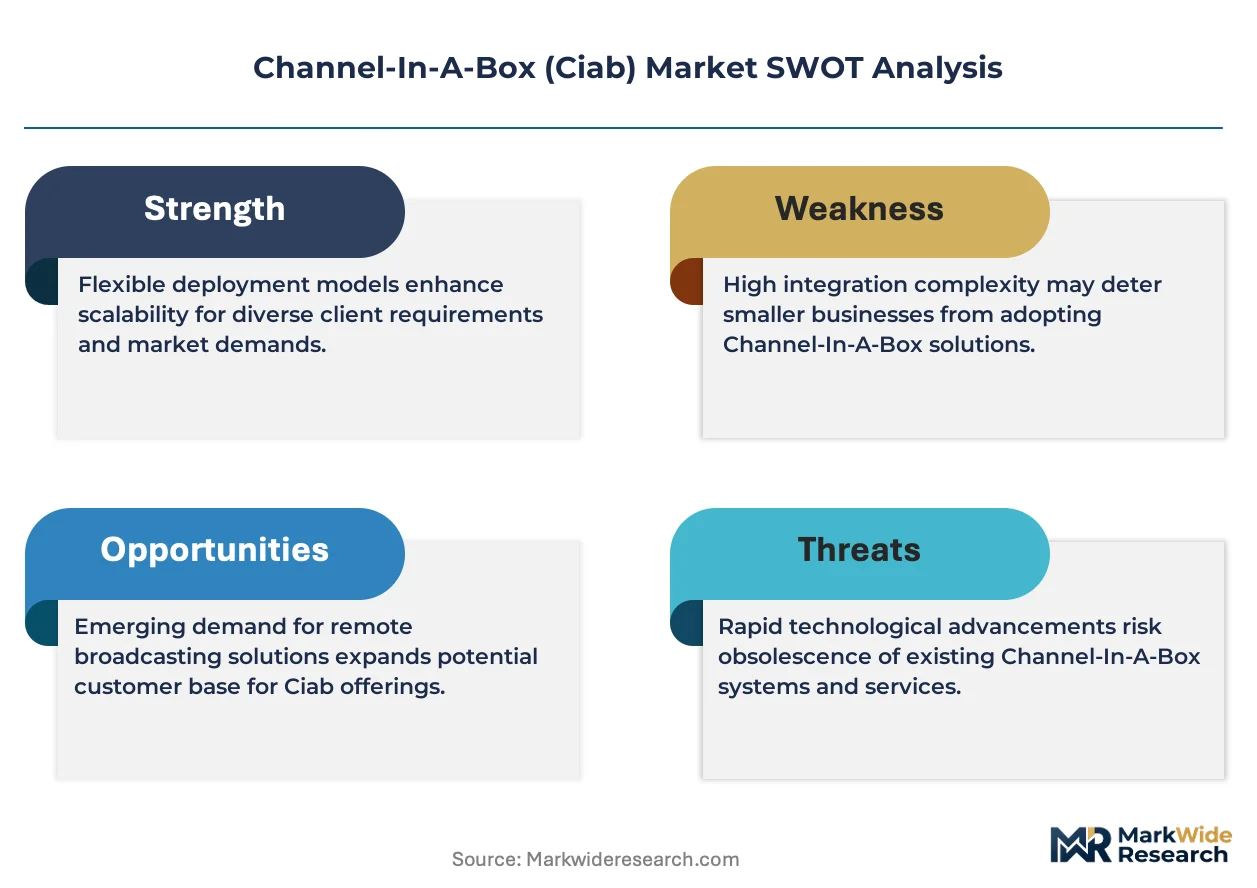
Subscription-based SaaS licensing and operational leasing for broadcast infrastructure is reconfiguring capital deployment across the Ciab competitive landscape. Evertz Microsystems Ltd. leverages its hardware heritage to anchor premium integrated system deployments. Harmonic Inc. differentiates through cloud-native stream processing architectures. PlayBox Neo competes on modular software pricing that lowers entry barriers for mid-tier broadcasters.
Channel-In-A-Box denotes a consolidated broadcast playout system integrating graphics, automation, ingest, and master control within a single software-defined or hardware appliance platform, typically supporting SDI and IP inputs with frame-accurate switching. Its primary purpose is to replace discrete broadcast chains with unified, redundant, and remotely operable playout engines for television channels and streaming services. Software solutions now command the fastest expansion as broadcasters decouple playout from proprietary hardware, while integrated systems retain margin concentration among tier-one networks demanding broadcast-grade reliability. Cloud-based technology is displacing on-premise dominance in new deployments, though hybrid architectures persist where latency constraints govern live programming.
The FCC mandates ATSC 3.0 transition timelines that compel infrastructure refresh cycles across U.S. broadcasters. EMA and CE marking requirements in Europe enforce electromagnetic compatibility and safety standards that shape product certification roadmaps for Ciab vendors. ISO 27001 and SOC 2 frameworks increasingly gate procurement decisions as OTT providers and telecom operators impose information security preconditions on playout suppliers. Stakeholders must weigh sovereign data residency rules against cloud economics when architecting multi-territory channel delivery.
Market Dynamics
Cloud migration is compressing capital cycles across broadcast infrastructure as OTT operators abandon fixed-asset playout models for elastic consumption. This shift is restructuring vendor economics and customer lock-in mechanisms simultaneously.
Growth Catalysts
- ATSC 3.0 mandates:The FCC's broadcast modernization timelines in the United States are forcing infrastructure refresh cycles among terrestrial networks. This regulatory pressure accelerates replacement of legacy master control systems.
- OTT expansion:Streaming-first operators are adopting software-defined playout to launch channels without dedicated broadcast facilities. Their demand for rapid channel provisioning outpaces traditional broadcaster upgrade cycles.
- IP transport maturation:SMPTE ST 2110 and NMOS specifications have stabilized, reducing integration risk for all-IP facilities. Broadcast engineers now specify IP-native Ciab systems for greenfield builds.
Market Restraints
- GPU supply concentration:Cloud rendering and AI workloads have tightened availability of broadcast-grade graphics accelerators. Vendors face allocation constraints from TSMC-dependent foundry capacity.
- Latency physics:Live sports and election coverage impose sub-frame synchronization requirements that resist full cloud migration. Hybrid architectures persist where frame-accurate switching governs programming.
- Skill scarcity:Broadcast engineering expertise concentrates among aging professionals with SDI-era training. Universities have de-prioritized RF and baseband curriculum for software engineering tracks.
Strategic Opportunities
- India digitization:TRAI's phase-out of analog terrestrial transmission creates replacement demand across regional broadcasters. Mid-tier stations seek modular Ciab configurations to avoid capital-intensive facility builds.
- Edge playout:Content delivery networks are deploying localized playout nodes for personalized ad insertion and blackout management. This architecture converges Ciab functions with CDN infrastructure.
- AI-assisted automation:Machine learning models for content classification and dynamic scheduling are integrating with playout engines. Early deployments reduce manual playlist management for multi-channel operations.
Industry Challenges
- ISO 27001 certification timelines:OTT platforms and telecom operators now gate vendor selection on information security attestations. Smaller Ciab suppliers lack resources to complete SOC 2 audits within procurement windows.
- Interoperability debt:Decades of proprietary automation protocols resist standardization. Migration projects require costly middleware layers to bridge legacy device control with modern REST APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Channel-In-A-Box (Ciab) Market |
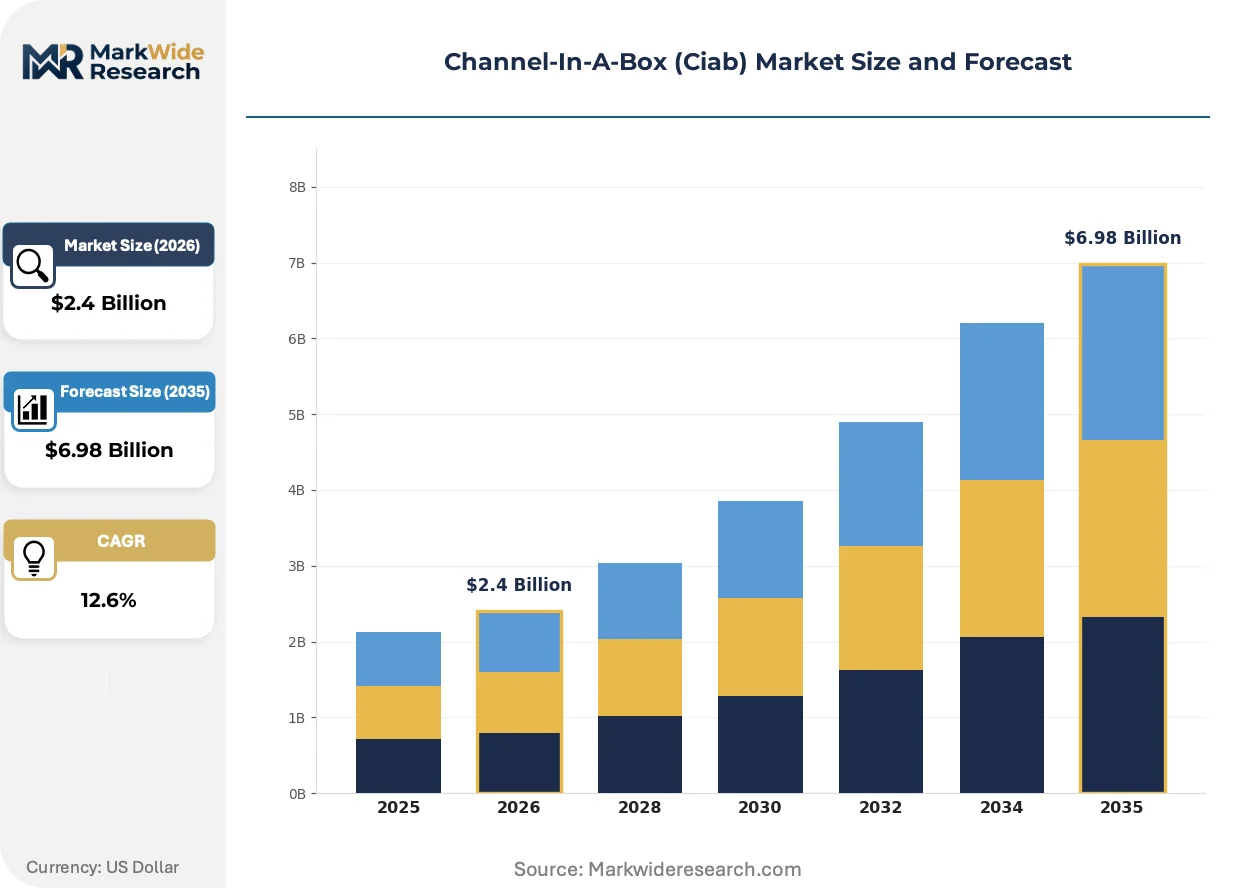
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.98 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Integrated Systems, Virtual Solutions Client Type: Broadcasters, OTT Providers, Digital Content Creators, Telecom Operators Technology: Cloud-Based, On-Premise, Hybrid, Stream Processing Distribution Channel: Direct Sales, Resellers, Online Platforms, Partner Networks |
| Companies Covered | Evertz Microsystems Ltd., Imagine Communications, PlayBox Neo, Harmonic Inc., Pebble Beach Systems Ltd., Grass Valley, Bitcentral Inc., Aveco, Cinegy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Channel-In-A-Box (Ciab) Market Strategic Shifts
Broadcast technology is bifurcating between cloud-native elasticity and on-premise determinism, with hybrid architectures emerging as the dominant design pattern. This tension is reshaping vendor roadmaps and customer deployment strategies.
Software-defined playout is hybridizing broadcast operations by unifying graphics, automation, and master control within containerized workflows. Tier-one networks are piloting these configurations for disaster recovery and overflow capacity. The technology is compressing the distinction between primary and backup facilities while enabling geographic distribution of operations staff.
The FCC's ATSC 3.0 transition mandates are forcing transmitter site upgrades that cascade into master control refresh decisions. Broadcasters must synchronize infrastructure investments across the RF chain and baseband plant. United States station groups are consolidating vendor relationships to manage certification complexity across the integrated broadcast chain.
Subscription licensing is displacing perpetual purchase models among mid-market broadcasters and streaming startups. Buyers prefer operational expenditure alignment with channel revenue rather than capital deployment against uncertain viewership. This pattern is most visible in Germany's regional broadcaster landscape and among FAST channel operators building virtual channel portfolios.
Channel-In-A-Box (Ciab) Market Segmentation
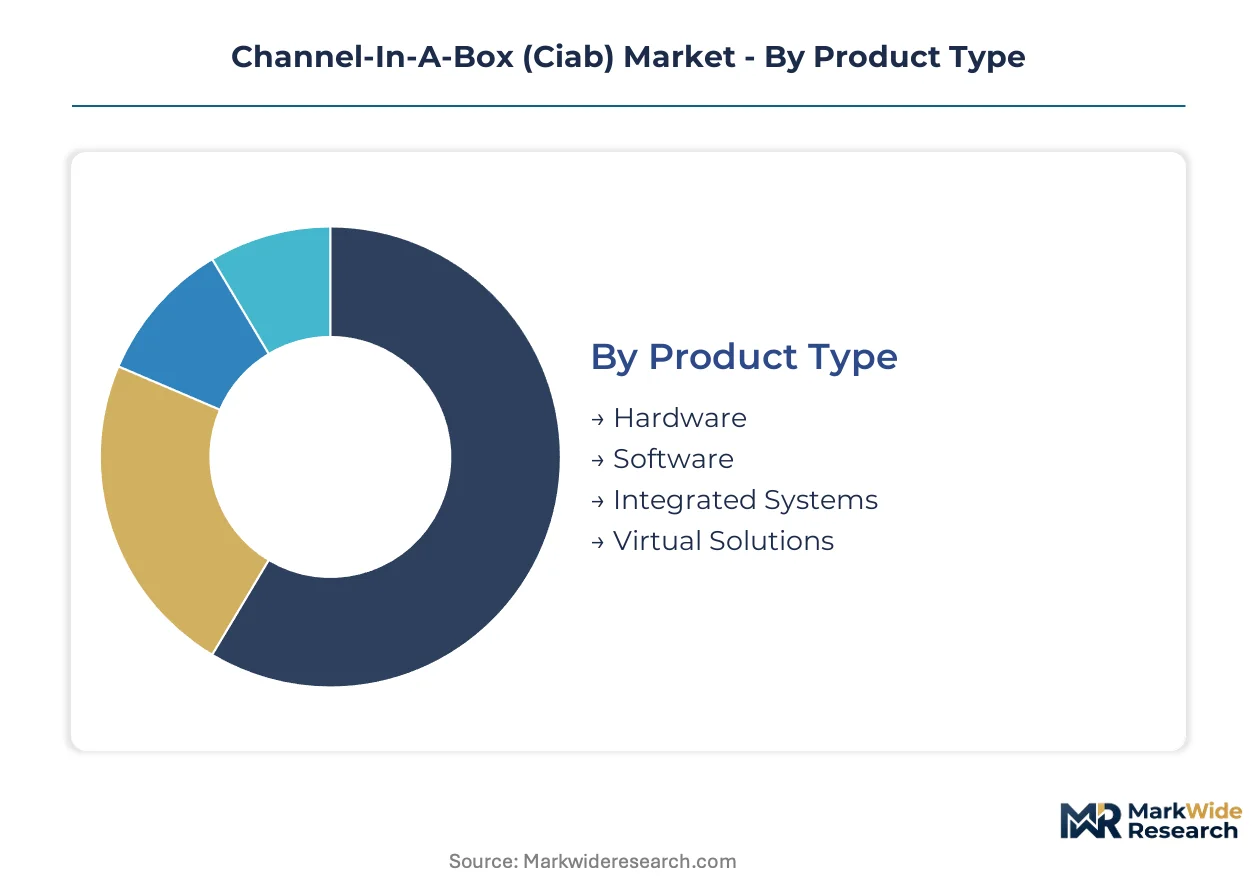
Channel-In-A-Box procurement patterns diverge sharply across deployment models and buyer sophistication. Segmentation reveals where capital cycles compress versus where operational expenditure models dominate vendor economics.
Product Type:
Hardware refreshes stretch across seven-to-ten year cycles while software licenses turn over in annual or quarterly subscriptions.
- Hardware:Purpose-built appliances with SDI/IP hybrid interfaces and redundant power supplies anchor master control rooms at major network affiliates. Demand concentrates among U.S. station groups executing FCC-mandated ATSC 3.0 transmitter site upgrades where deterministic latency governs live programming.
- Software:Containerized playout engines deploy on commercial-off-the-shelf servers or cloud instances, decoupling channel operations from proprietary silicon. FAST channel operators and streaming startups in Germany's regional broadcaster landscape favor this model for rapid channel provisioning without facility investment.
- Integrated Systems:Pre-configured bundles combining compute, storage, and graphics acceleration for turnkey deployment.
- Virtual Solutions:Fully abstracted playout functions running as microservices without local hardware presence.
Hardware anchors the volume base while software gains share at the steepest rate.
Client Type:
Capital availability and technical staffing depth separate buyers who own infrastructure from those who rent operational capacity.
- Broadcasters:Terrestrial networks with transmitter assets and FCC licensing obligations maintain on-premise primary facilities while piloting cloud disaster recovery. U.S. station groups consolidate vendor relationships to manage certification complexity across the integrated broadcast chain.
- OTT Providers:Streaming-first operators launch channels without dedicated broadcast facilities, consuming software-defined playout as elastic infrastructure. Their procurement cycles align with content slate expansion rather than regulatory deadlines.
- Digital Content Creators:Influencer-led media brands and niche programming houses seeking professional-grade playout without broadcast engineering departments.
- Telecom Operators:Mobile and fixed-line carriers bundling linear channels with broadband subscriptions, imposing ISO 27001 security preconditions on vendor selection.
Broadcasters contribute the largest absolute revenue while OTT providers expand most quickly.
Technology:
Latency tolerance and content genre determine whether buyers accept cloud economics or insist on physical proximity to transmission infrastructure.
- Cloud-Based:Fully off-premise playout with geographic distribution of operations staff, enabled by SMPTE ST 2110 and NMOS specification maturation. Tier-one networks pilot these configurations for overflow capacity and disaster recovery.
- On-Premise:Local hardware deployment maintaining frame-accurate switching for live sports and election coverage where sub-frame synchronization resists full cloud migration.
- Hybrid:Split architectures with primary on-premise and cloud backup, or cloud primary with edge nodes for localized ad insertion.
- Stream Processing:Real-time encoding, packaging, and encryption functions integrated with playout automation.
On-premise retains margin concentration while cloud deployments climb the fastest.
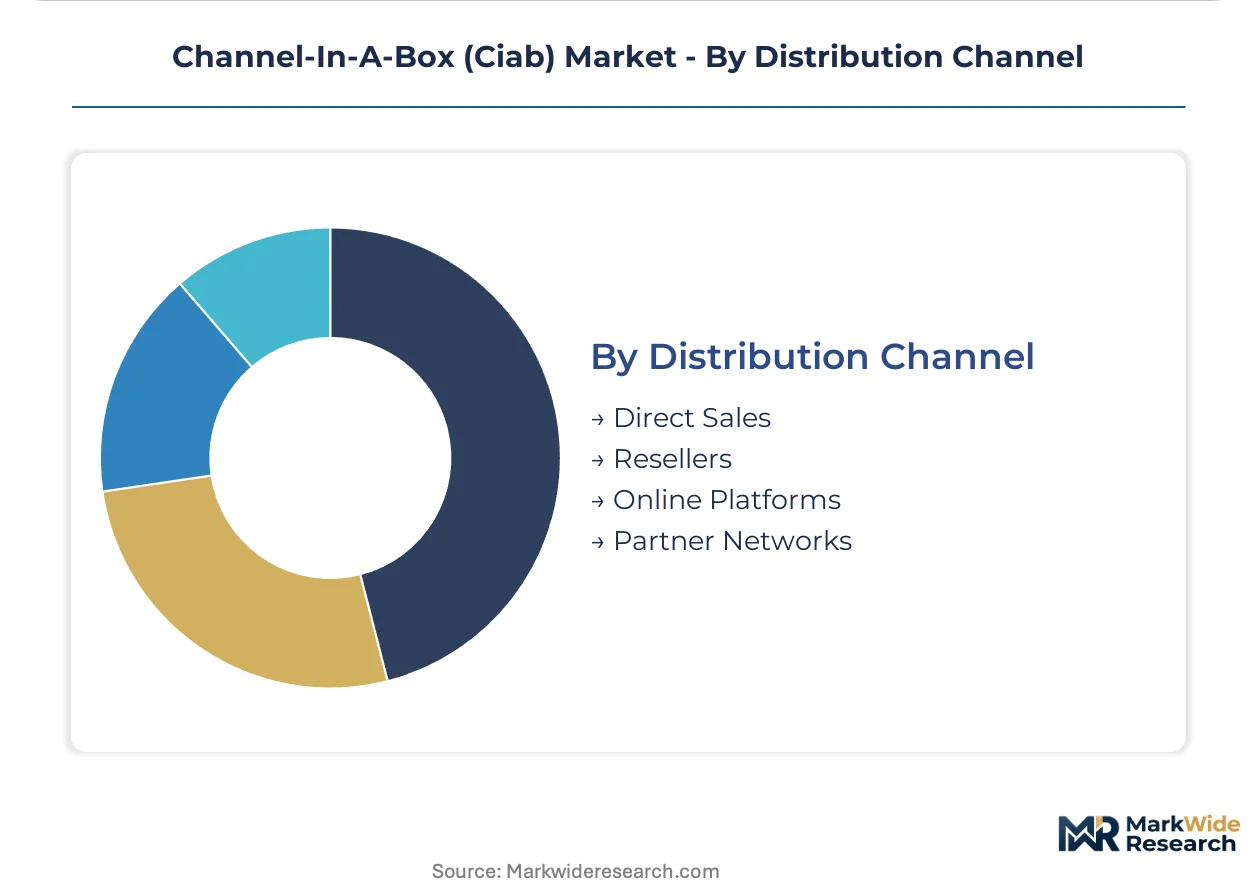
Distribution Channel:
Deal complexity and buyer technical sophistication shape whether vendors sell direct or through intermediaries.
- Direct Sales:Vendor field organizations engage tier-one networks and station groups requiring custom integration, certification support, and long-term service relationships.
- Resellers:Regional systems integrators and broadcast equipment dealers serve mid-market buyers needing local installation and maintenance without direct vendor engagement.
- Online Platforms:Self-service procurement portals for software licenses and virtual solution subscriptions, targeting streaming startups and digital content creators.
- Partner Networks:Strategic alliances with CDN operators and cloud hyperscalers bundling Ciab functions with content delivery infrastructure.
Direct sales capture the highest transaction values while online platforms expand access fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in broadcast infrastructure tilt toward technology-importing markets, with manufacturing concentration in North America and Western Europe supplying deployment demand across Asia-Pacific and Latin America. Trade flows track regulatory modernization cycles, as countries with active digitization mandates absorb premium Ciab systems while emerging markets prioritize cost-optimized configurations.
United States
FCC-mandated ATSC 3.0 transmitter upgrades are cascading into master control refresh decisions across station groups. The regulatory timeline compresses procurement windows for terrestrial networks. Dallas-Fort Worth and Atlanta clusters concentrate deployment activity as major broadcasters synchronize infrastructure investments across RF chains.
Germany
Regional broadcaster consolidation is accelerating software-defined playout adoption to avoid capital-intensive facility builds. EMA electromagnetic compatibility requirements shape vendor certification roadmaps for European market entry. Munich and Cologne anchor systems integration expertise serving Central European upgrade cycles.
China
State media digitization programs and provincial broadcaster consolidation are driving demand for integrated playout appliances. MIIT standards for ultra-high-definition transmission mandate infrastructure refresh across terrestrial networks. Beijing and Shanghai clusters concentrate domestic vendor development and deployment capacity.
India
TRAI's analog terrestrial phase-out is creating replacement demand across regional broadcasters seeking modular configurations. BIS certification requirements for broadcast equipment filter supplier participation in government tenders. Mumbai and Bengaluru concentrate deployment activity as private networks expand regional channel portfolios.
Brazil
ASO digital switchover completion is sustaining infrastructure investment among terrestrial networks upgrading to ISDB-Tb standards. ANVISA-equivalent broadcast equipment regulations enforce electromagnetic compatibility compliance for imported systems. São Paulo anchors Latin American systems integration capacity serving Portuguese-language markets.
Channel-In-A-Box (Ciab) Market Competitive Environment
On the supply side, the industry is bifurcating between hardware-anchored incumbents and cloud-native challengers, with mid-tier modular specialists occupying a contested middle ground. Tier-one networks consolidate vendor relationships to manage certification complexity, while streaming operators fragment procurement across best-of-breed software components. Strategic archetypes include integrated system architects, subscription-software pure-plays, and hybrid hardware-software bundlers. Competitive moves center on cloud partnership formations and security certification acceleration.
Within the integrated system tier, Evertz Microsystems Ltd. and Harmonic Inc. exemplify divergent architectural philosophies—hardware heritage versus cloud-native stream processing. PlayBox Neo occupies a position representing modular software pricing strategies that compress entry barriers for mid-market buyers. These three anchors illustrate how vendor economics restructure around capital deployment preferences: perpetual purchase alignment for terrestrial networks, operational expenditure models for streaming operators, and hybrid configurations for transitional broadcasters.
| Leading Market Players |
|---|
| Evertz Microsystems Ltd. |
| Imagine Communications |
| PlayBox Neo |
| Harmonic Inc. |
| Pebble Beach Systems Ltd. |
| Grass Valley |
| Bitcentral Inc. |
| Aveco |
| Cinegy |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific container freight corridors from Shenzhen to Los Angeles govern landed cost dynamics for broadcast hardware components, compressing margin buffers for vendors sourcing GPU accelerators and SDI interface silicon while amplifying price differentiation between appliance-based and software-defined deployment tiers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Tier-one networks absorb premium hardware appliance pricing tied to ATSC 3.0 certification tiers and redundant power specifications, while mid-market German regional broadcasters and FAST channel operators gravitate toward subscription SaaS tiers that eliminate capital deployment. Price differentiation hinges on ISO 27001 attestation status and after-sales service bundling. Cost compression in the mid-tier software segment is intensifying as containerized playout vendors compete for streaming startup accounts with quarterly billing cycles and rapid provisioning guarantees.
Supply Chain Analysis
Extended payment terms from TSMC-dependent foundry partners now stretch to ninety days for broadcast-grade graphics accelerators, tightening working capital requirements for Ciab hardware vendors. Manufacturing concentrates in Taiwan for GPU silicon, Malaysia for PCB assembly, and Germany for precision mechanical enclosures. Raw material dependencies include TSMC-fabricated semiconductors, copper-clad laminates, and redundant power supply units. Single-source vulnerability around TSMC's advanced node allocation creates supply chain risk. Distribution runs through direct vendor field organizations for tier-one networks and regional systems integrators for mid-market buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Channel-In-A-Box procurement is evolving into a service-attach opportunity as subscription-based operational support and remote monitoring contracts expand faster than perpetual hardware purchases. Recurring revenue from cloud-native disaster recovery and overflow capacity provisioning now outpaces upfront appliance sales among transitional broadcasters.
For Market Incumbents: Entrench broadcast-grade reliability credentials through accelerated SOC 2 Type II certification completion and ATSC 3.0 compliance verification. Lock in U.S. station group consolidation opportunities by offering integrated RF chain certification management. Counter cloud-native challengers by embedding edge playout nodes within CDN partnership architectures, converting hardware heritage into hybrid deployment control points. For New Entrants and Emerging Players: Pursue white-space opportunities in India's regional broadcaster digitization wave, where TRAI-mandated analog phase-out creates modular software demand without incumbent vendor relationships. Target FAST channel operators building virtual portfolios in Germany's fragmented regional landscape. Lead with ISO 27001 pre-certification and API-first automation protocols to bypass legacy interoperability debt. For Investors and Strategic Acquirers: Cloud-native automation specialists with proven NMOS integration and containerized disaster recovery deployments represent the most compelling acquisition archetype. Long-term viability rests on recurring revenue ratio expansion and multi-territory channel delivery capabilities. Watch for inflection when tier-one networks shift primary playout from on-premise to cloud-native configurations, signaling hardware-anchored incumbent displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Partnership Formation | Hyperscaler alliances enable elastic playout capacity for OTT operators without facility investment. |
| Security Certification Acceleration | SOC 2 and ISO 27001 completion gates procurement decisions from telecom operators and streaming platforms. |
| Edge Playout Node Deployment | CDN-integrated localization supports personalized ad insertion and blackout management for sports rights holders. |
| AI-Assisted Automation Integration | Machine learning content classification reduces manual playlist management for multi-channel operations. |
| Hybrid Architecture Standardization | Split cloud-primary and on-premise backup configurations address latency constraints in live sports coverage. |
Study Parameters
A standing panel of broadcast engineering directors, OTT platform operations leads, and regional systems integrators provided ongoing calibration across primary interview cycles. Secondary validation drew from FCC equipment authorization databases, EMA electromagnetic compatibility filings, and TRAI digitization mandate notifications. Bottom-up channel count and deployment model enumeration triangulated against top-down vendor revenue segmentation across hardware, software, and integrated system tiers.
Scenario-bracketing framed analytical outputs across the projection horizon, testing sensitivity to ATSC 3.0 compliance timeline shifts and OTT subscriber growth trajectories. Segmentation dimensions modeled include deployment architecture, buyer capital availability, content genre latency requirements, and regional regulatory modernization status. CAGRs derived from installed base turnover analysis and greenfield channel provisioning rates, with specific inputs from SMPTE ST 2110 adoption curves and GPU foundry allocation constraints.
Sensitivities concentrate around FCC mandate enforcement consistency, TSMC advanced node capacity allocation, and sovereign data residency rule expansion. Forecasts reflect documented assumptions on cloud migration velocity and hybrid architecture persistence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Powder Coating Equipment Market
Others
Griffin Beaker Market
Others
Receiving Scales Market
Others
China Cloud Gaming Technology Market
Others
Technical Films Market
Others
Digital LUX Meter Market
Others
Blockchain in BFSI Market
Others
Communication Base Station Body Market
Others
Global Smart Devices Market
Others
Air Separation Plant Market
Others
Asia-Pacific Road Safety Market
Others
AC Switchgear Market
Others
Global Phablets and Superphones Market
Others
North America IT Device Market
Others
Hybrid Switchgear Market
Others
Global Surface Analysis Market