
 Billet Market | 2026-2036
Billet Market Size, Share, and Industry Trends Forecast 2026-2036
Billet Market Analysis
EU Carbon Border Adjustment Mechanism is restructuring the cost-of-entry calculus for billet exporters serving European downstream markets. ArcelorMittal leverages its integrated European flat-and-long product network to preempt carbon-adjusted supply positions. POSCO anchors its competitiveness through captive green hydrogen pilot programs tied to Korean decarbonization targets. Tata Steel differentiates via India-focused long-product capacity that serves domestic rebar and wire-rod demand.
A billet is a semi-finished metal casting with a square or round cross-section, typically measuring 100-200 mm per side, produced through continuous casting or ingot breakdown for subsequent rolling, extrusion, or forging into finished long products. Steel billets constitute the dominant material type by tonnage, serving as the essential feedstock for construction rebar, automotive shafts, and marine fasteners. Extrusion-based production methods command premium positioning in aluminum billet supply chains where aerospace and automotive end users require tight dimensional tolerances and homogenized microstructures. Construction end-user demand anchors volume throughput, while aerospace-grade material commands the deepest margin pools.
EPA emissions guidelines in the US, REACH substance restrictions in Europe, and China's MEE carbon intensity benchmarks collectively shape billet producer compliance investments and market access conditions. These frameworks elevate operational costs for carbon-intensive electric arc furnace and blast furnace routes while advantaging producers with scrap-based or hydrogen-reduction capabilities. Stakeholders must monitor regulatory timeline acceleration in major demand centers to align capital deployment with shifting compliance thresholds.
Market Dynamics
Carbon-adjusted cost structures are fragmenting the competitive map for billet producers, with EU CBAM compliance costs now separating integrated hydrogen-ready mills from carbon-intensive export-dependent suppliers.
Growth Catalysts
- India's infrastructure buildout:Government-funded rail and highway projects are absorbing record volumes of long-product feedstock, concentrating procurement with domestic mills possessing captive billet capacity.
- REACH substance restrictions:European downstream users are tightening material traceability requirements, pulling premium-grade billet toward certified low-carbon supply chains.
- Continuous casting advancement:Near-net-shape casting technologies are compressing yield losses and enabling tighter dimensional tolerances for automotive shaft applications.
Market Restraints
- Scrap price volatility:Electric arc furnace operators face margin compression when ferrous scrap inventories tighten in Turkish and Southeast Asian collection markets.
- China's capacity consolidation:MEE carbon intensity benchmarks are forcing regional mill closures, concentrating supply risk with surviving state-backed producers.
- Aluminum billet substitution:Lightweighting mandates in automotive are displacing steel billet in select chassis and structural applications.
Strategic Opportunities
- Vietnam's underpenetrated downstream:Foreign direct investment in rebar and wire-rod rolling capacity is outpacing domestic billet supply, creating import-dependent demand pockets.
- Green hydrogen reduction pilots:Korean decarbonization targets are funding captive hydrogen-DRI demonstration plants that will reshape feedstock specifications.
- Direct mill-to-fabricator channels:Large construction consortia are bypassing traditional traders to secure volume commitments with billet producers.
Industry Challenges
- Metallurgical technician scarcity:Continuous casting optimization and microstructure control require specialized expertise that aging workforces in European and Japanese mills cannot replenish.
- Dual certification timelines:Aerospace-grade aluminum billet producers face extended qualification periods with Boeing and Airbus supply chains that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Billet Market |
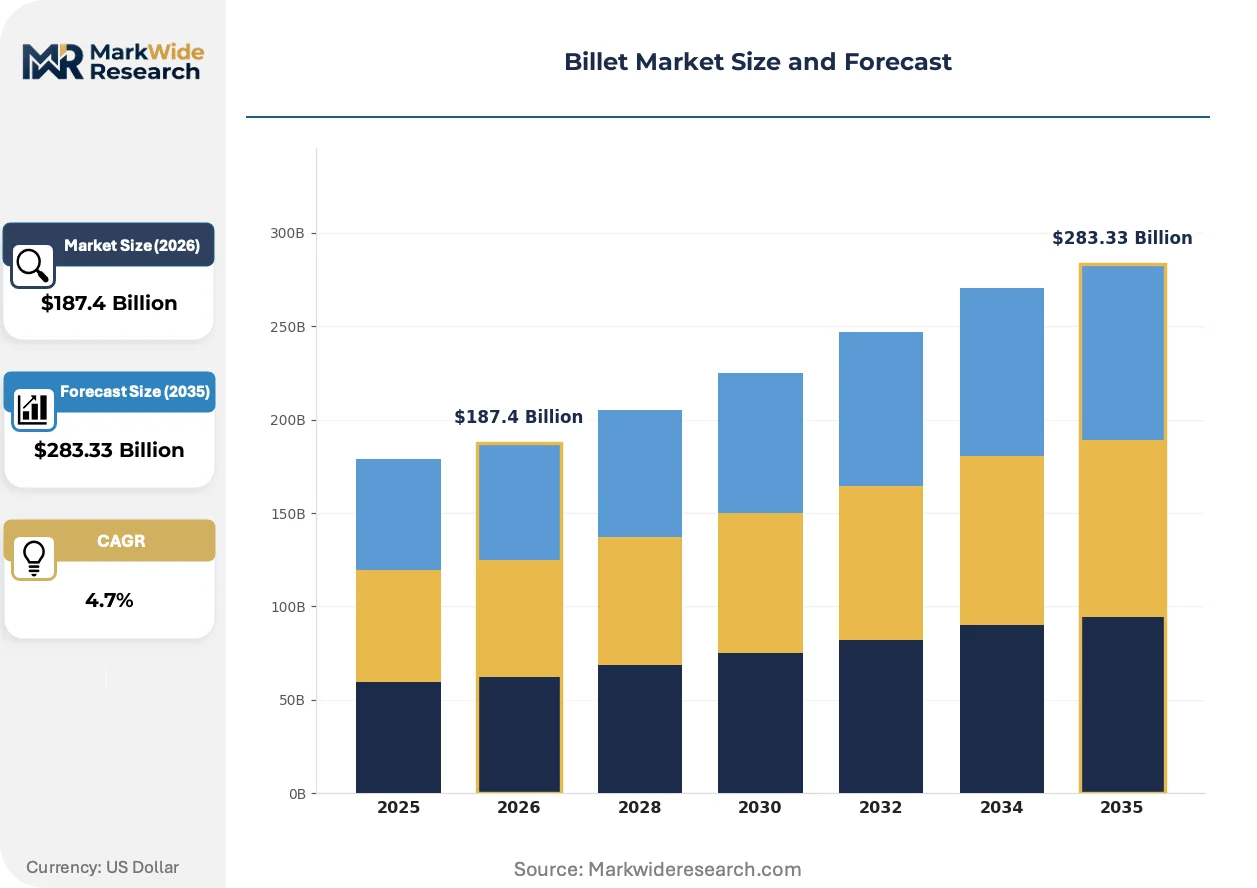
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $283.33 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Steel, Aluminum, Brass, Copper Production Method: Extrusion, Casting, Forging, Rolling End User: Aerospace, Automotive, Construction, Marine Size: Small, Medium, Large, Custom |
| Companies Covered | POSCO, JFE Steel Corporation, ArcelorMittal, Gerdau S.A., Hyundai Steel, China Baowu Steel Group, Tata Steel, Thyssenkrupp AG, Nippon Steel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Billet Market Emerging Trajectories
Process intensification and regulatory measurement are compressing the gap between primary production and end-use certification, forcing billet suppliers to embed compliance data directly into material documentation.
Digital twin modeling of continuous casting parameters is unifying real-time thermal mapping with predictive microstructure simulation. Automotive tier-one suppliers are adopting these verified billet specifications to reduce incoming inspection overhead. The technology is unifying quality assurance costs across geographically dispersed forging operations.
EU Carbon Border Adjustment Mechanism is restructuring import duty calculations for non-EU billet suppliers. Downstream rebar and wire-rod producers are now sourcing based on embedded emissions documentation rather than delivered price alone. Turkish and Indian exporters are accelerating third-party carbon auditing to preserve European market access.
Consortium-based procurement is consolidating construction sector purchasing power into multi-year offtake agreements. Large infrastructure developers are replacing spot market purchases with volume commitments tied to project finance milestones. This pattern is most visible in Indian rail and highway projects where state-backed contractors secure feedstock ahead of construction seasonality.
Billet Market Segmentation
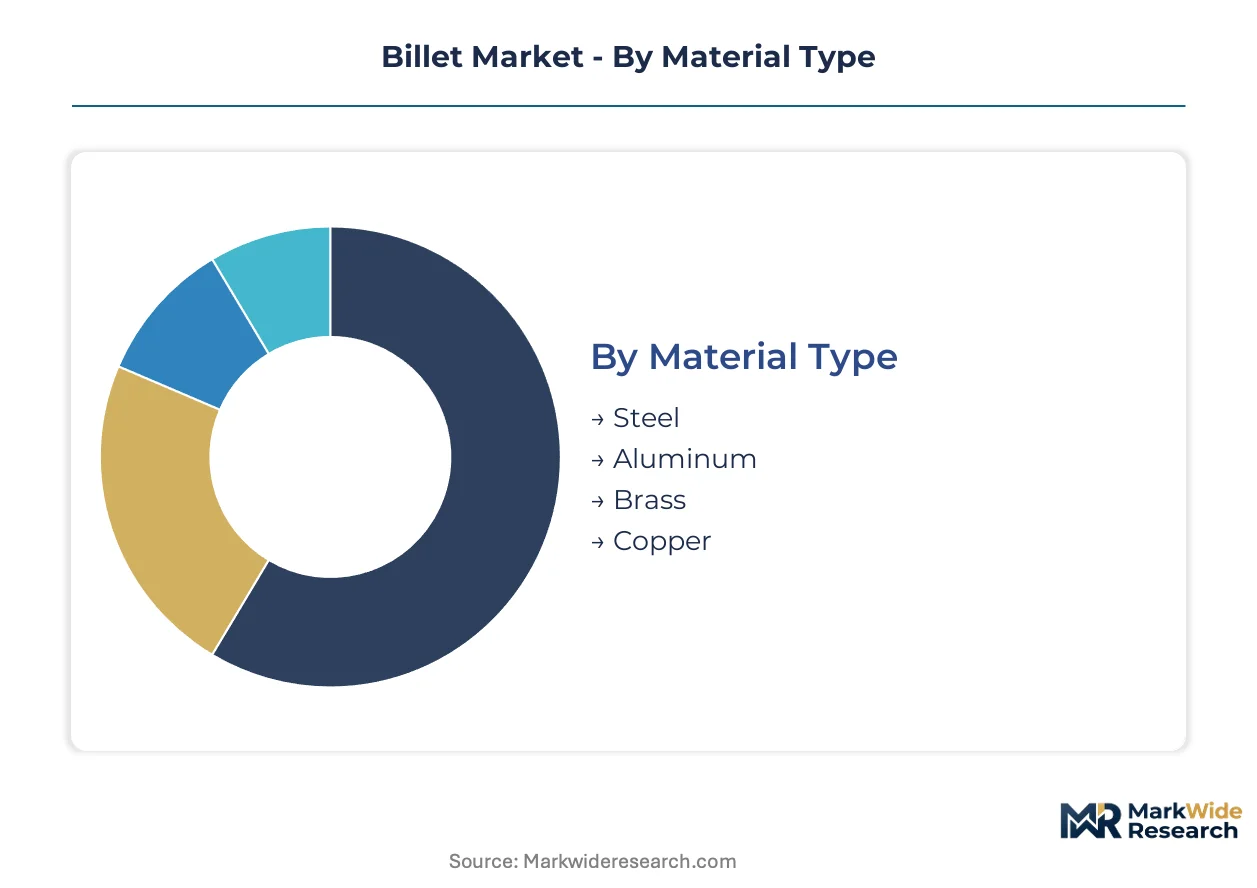
Billet segmentation determines feedstock procurement strategies across construction, automotive, and aerospace supply chains. Material composition and production method dictate downstream processing economics and regulatory compliance pathways. End-user specifications and dimensional requirements shape mill capacity allocation and geographic sourcing decisions.
Material Type:
Steel billets operate as standalone commodity feedstock for high-volume construction applications, while aluminum and copper variants embed into precision-engineered systems demanding alloy-specific performance.
- Steel:Carbon and alloy steel billets serve as the dominant feedstock for rebar, wire rod, and structural long products. Construction procurement in India absorbs record volumes as government-funded rail and highway projects accelerate, with domestic mills consolidating supply positions under China's GB standard-driven capacity rationalization.
- Aluminum:Extrusion-grade aluminum billets require tight dimensional tolerances and homogenized microstructures for aerospace and automotive lightweighting applications. Boeing and Airbus supply chains impose extended qualification timelines that delay revenue recognition for certified producers.
- Brass:Copper-zinc alloy billets target plumbing fixtures and electrical connectors where machinability and corrosion resistance intersect.
- Copper:Pure copper billets feed electrical wire drawing and industrial heat exchanger fabrication.
Volume placements concentrate in Steel; the faster expansion belongs to Aluminum.
Production Method:
Cost tier separation distinguishes capital-intensive continuous casting from batch-oriented forging routes, with margin structures varying by energy input and yield efficiency.
- Extrusion:Direct and indirect extrusion methods command premium positioning in aluminum billet supply chains where aerospace end users require verified microstructure documentation. Digital twin modeling of thermal parameters is compressing yield losses and unifying quality assurance across dispersed forging operations.
- Casting:Continuous casting dominates steel billet production through near-net-shape technologies that enable tighter dimensional tolerances for automotive shaft applications. EPA emissions guidelines and China's MEE carbon intensity benchmarks elevate operational costs for carbon-intensive electric arc furnace routes.
- Forging:Ingot breakdown forging serves specialized alloy grades requiring directional grain structure control.
- Rolling:Breakdown rolling of cast ingots produces standard structural steel billets for construction rebar feedstock.
Casting captures the highest throughput volumes; extrusion maintains the steepest margin premiums.
End User:
Application criticality segments procurement behavior, with construction demanding scale and aerospace insisting on traceable certification documentation.
- Construction:Structural steel billet procurement anchors market volume as infrastructure budgets expand across emerging economies. EU CBAM compliance costs are restructuring import duty calculations, pulling procurement toward certified low-carbon supply chains with embedded emissions documentation.
- Automotive:Drive shaft and chassis applications require verified billet specifications that tier-one suppliers adopt to reduce incoming inspection overhead. Lightweighting mandates are displacing steel billet with aluminum in select chassis applications.
- Aerospace:Titanium and high-strength aluminum billets face dual certification timelines with Boeing and Airbus that extend qualification periods.
- Marine:Corrosion-resistant alloy billets serve propeller shafts and fastener applications in saltwater environments.
Construction commands absolute volume leadership; aerospace-grade material accesses the deepest margin pools.
Size:
Customer type differentiation separates standard mill production from custom specification orders, with inventory risk and lead time economics diverging sharply.
- Medium:100-200 mm cross-section billets constitute the standard specification for continuous casting output serving construction rebar and wire rod mills. Consortium-based procurement in Indian infrastructure projects is consolidating purchasing power into multi-year offtake agreements for this specification band.
- Small:Precision-dimensioned small billets feed automotive fastener and specialty shaft applications with tight tolerance requirements.
- Large:Heavy-section billets target forging presses producing marine propellers and industrial crankshafts.
- Custom:Non-standard dimensions serve direct mill-to-fabricator channels where large construction consortia bypass traditional traders.
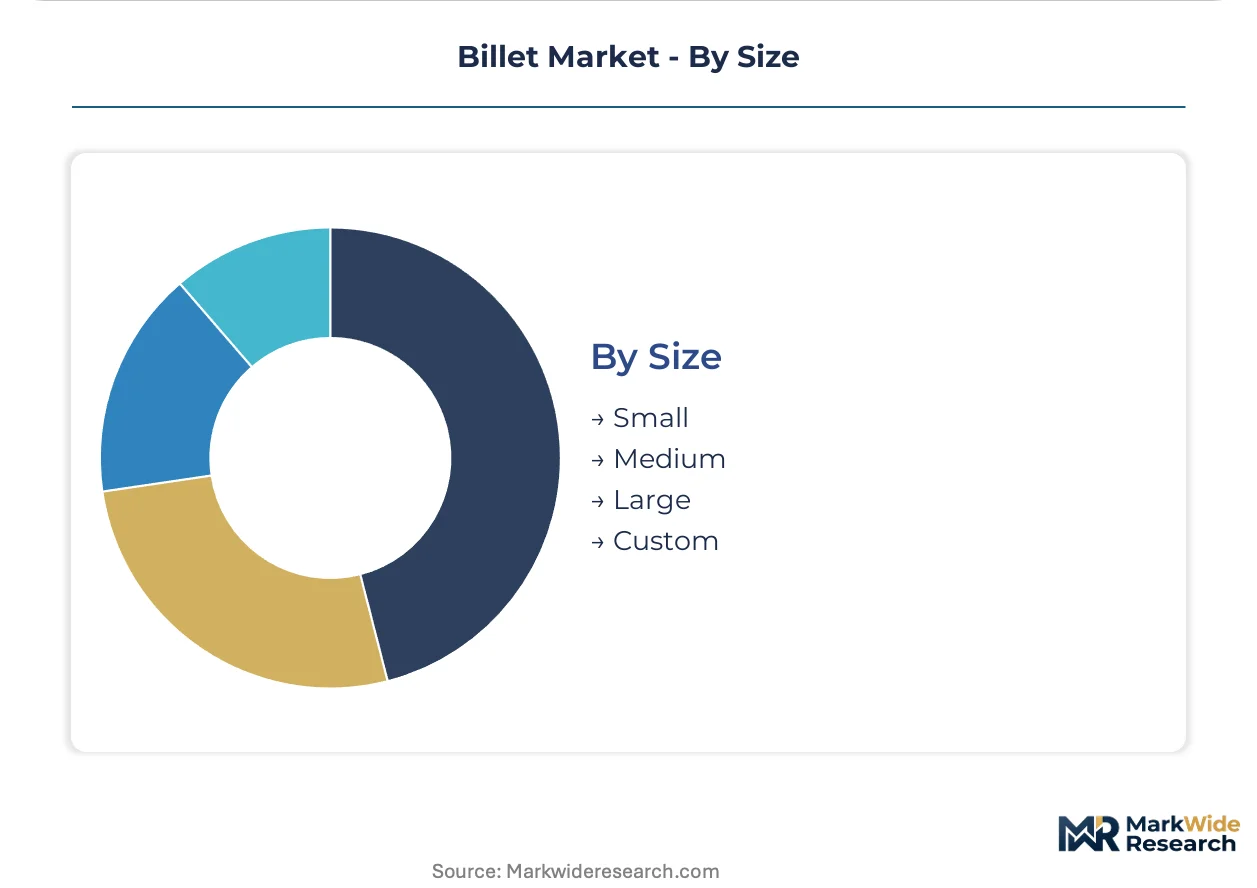
Medium specifications dominate rolling mill intake; custom dimensions are gaining share fastest in project-financed infrastructure procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Dedicated Freight Corridor and industrial corridor tax incentives are concentrating billet demand around government-funded infrastructure nodes. Special economic zones in Gujarat and Maharashtra offer duty exemptions that attract rolling mill investments. These zones reshape procurement geography for long-product feedstock.
India
Rail and highway projects absorb record structural steel billet volumes under the National Infrastructure Pipeline. The Ministry of Steel's PLI scheme incentivizes domestic long-product capacity expansion. Rolling mills cluster in Raipur and Jharsuguda where captive billet supply secures government contract eligibility.
China
GB standard updates force carbon-intensive mill consolidation, concentrating supply with state-backed producers. The MEE carbon intensity benchmarks eliminate smaller regional operators. Output concentrates in Hebei and Jiangsu where surviving mills integrate hydrogen-DRI pilot programs.
United States
Infrastructure Investment and Jobs Act disbursements accelerate rebar demand from bridge and highway contractors. EPA emissions guidelines elevate compliance costs for electric arc furnace routes. Mills in Indiana and Ohio deploy scrap optimization to defend margin positions under tightening environmental enforcement.
Germany
Automotive shaft specifications pull premium-grade billet toward verified low-carbon supply chains. REACH substance restrictions mandate material traceability documentation that favors integrated producers. The Ruhr industrial cluster hosts hydrogen-reduction demonstration plants tied to EU Green Deal funding.
South Korea
Shipbuilding and automotive procurement anchors demand for high-strength long products. Korean decarbonization targets fund captive green hydrogen pilot programs at integrated mills. POSCO's Pohang complex anchors domestic supply while targeting carbon-adjusted export positions.
Billet Market Vendor Landscape
Indian producers anchor one tier serving domestic infrastructure procurement; East Asian specialists hold premium positions in automotive and aerospace-grade material. The vendor base separates into integrated hydrogen-ready mills, scrap-dependent electric arc furnace operators, and aluminum extrusion-grade specialists. Strategic moves concentrate on M&A-driven capacity consolidation and direct mill-to-fabricator offtake agreements that bypass traditional trading channels.
Within the integrated steel tier, ArcelorMittal, POSCO, and Tata Steel exemplify divergent geographic anchoring strategies. ArcelorMittal occupies a position across European flat-and-long product networks. POSCO sits within Korean decarbonization pilot programs targeting hydrogen-reduction capabilities. Tata Steel anchors India-focused long-product capacity serving domestic rebar and wire-rod demand under government-funded project procurement.
| Leading Market Players |
|---|
| POSCO |
| JFE Steel Corporation |
| ArcelorMittal |
| Gerdau S.A. |
| Hyundai Steel |
| China Baowu Steel Group |
| Tata Steel |
| Thyssenkrupp AG |
| Nippon Steel Corporation |
| Others |
Supply Flow & Price Mechanics
Captive billet capacity at integrated Indian mills anchors supply positions and pricing power for government-funded infrastructure procurement, while outsourced scrap-dependent operators in Turkey face margin compression from ferrous scrap volatility. This integration choice separates carbon-adjusted premium positions from spot-market commodity exposure.
Pricing Analysis
Lead-time premiums for certified low-carbon billet command substantial markups over spot inventory as EU CBAM compliance documentation becomes a procurement gate. Contract-based long-term offtake agreements dominate Indian infrastructure procurement, while spot-market transactions concentrate in Turkish export channels facing carbon-adjusted duty exposure. Price differentiation separates aerospace-grade aluminum billet with Boeing-Airbus dual certification from standard construction rebar feedstock. Margins are tightening in carbon-intensive electric arc furnace routes as EPA emissions guidelines elevate compliance costs, with construction consortia showing highest price sensitivity and aerospace tier-one suppliers least sensitive to delivered cost.
Supply Chain Analysis
Extended qualification timelines with Boeing and Airbus certification gates restrict aerospace-grade aluminum billet supply to a qualified producer tier, filtering downstream distribution. Geographic supply concentrates in China, India, and South Korea where integrated mills control long-product feedstock output. Raw material dependencies center on ferrous scrap inventories, iron ore pellets, and green hydrogen pilot volumes for DRI reduction routes. Single-source vulnerability runs through surviving state-backed Chinese producers under MEE carbon intensity consolidation. Distribution runs through direct mill-to-fabricator channels consolidating in Indian rail and highway projects, bypassing traditional trader intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The billet market operates as a cost-of-compliance story where EU Carbon Border Adjustment Mechanism duties create a barrier-to-entry moat for producers with verified embedded emissions documentation, locking out carbon-intensive export-dependent suppliers from European downstream rebar and wire-rod markets.
For Market Incumbents: Extend captive green hydrogen pilot programs to preempt Korean and EU decarbonization compliance thresholds, securing carbon-adjusted export positions before regulatory timelines accelerate. Defend domestic infrastructure procurement share in India through backward integration into ore and scrap collection networks, countering emerging electric arc furnace entrants from Southeast Asia. Prioritize certification investment for REACH substance traceability documentation to maintain European automotive shaft supply positions against integrated hydrogen-ready competitors. For New Entrants and Emerging Players: The premium-to-economy price gap in carbon-certified billet offers white-space entry for scrap-based electric arc furnace operators with third-party emissions auditing capability. Target Vietnam's underpenetrated rebar and wire-rod rolling capacity where foreign direct investment outpaces domestic billet supply, creating import-dependent demand pockets. Pursue direct mill-to-fabricator channel partnerships with state-backed Indian construction consortia, bypassing trader markups through volume commitments tied to project finance milestones. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated hydrogen-ready mill acquisitions by carbon-intensive regional players seeking compliance positioning. Long-term viability over the next decade hinges on regulatory alignment with EU and Korean decarbonization trajectories, favoring targets with captive DRI demonstration plants or scrap optimization infrastructure. Watch for inflection signals in EU CBAM timeline acceleration or Chinese MEE benchmark tightening that would compress valuations for carbon-intensive export-dependent assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Collection | Secures ferrous scrap supply for electric arc furnace routes amid Turkish and Southeast Asian inventory tightening. |
| Green Hydrogen DRI Pilot Expansion | Aligns with Korean decarbonization targets and EU CBAM compliance thresholds for carbon-adjusted export positioning. |
| Direct Mill-to-Fabricator Channel Development | Bypasses trader intermediation for Indian rail and highway project procurement under National Infrastructure Pipeline disbursements. |
| Dual Certification Investment for Aerospace | Accelerates Boeing-Airbus qualification timelines to capture premium-margin aluminum billet supply positions. |
| Continuous Casting Digital Twin Deployment | Compresses yield losses and unifies quality assurance across dispersed automotive shaft forging operations. |
Methodological Framework
Trade statistics from customs authorities, national steel association production databases, and regulatory filing repositories formed the secondary backbone, cross-referenced with primary interviews involving continuous casting plant managers, rebar mill procurement leads, construction consortium supply chain directors, and automotive tier-one supplier quality engineers. Bottom-up volume estimates from mill capacity utilization rates triangulated against top-down infrastructure budget disbursement data to anchor demand-side calibration.
Historical trendline analysis of billet-to-rebar margin spreads and carbon intensity benchmark adoption curves informed the projection framework across the analysis window. Segmentation modeling incorporated material type, production method, end-user application criticality, and dimensional specification bands. CAGRs derived from regression-weighted infrastructure investment trajectories and regulatory compliance cost curves, with specific inputs from EU CBAM duty phase-in schedules and Indian PLI scheme capacity addition timelines.
Inputs from continuous casting operators and construction procurement databases were available through the study window; gaps in real-time ferrous scrap inventory data and unannounced hydrogen-DRI pilot commissioning introduce uncertainty bands around electric arc furnace cost projections. Forecasts reflect assumptions on regulatory timeline adherence and infrastructure budget execution rates. A model refresh is warranted upon material change in EU CBAM carbon border duty implementation pace or Chinese MEE capacity consolidation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Mobile Retina Services Market
Others
Diamond Mining Market
Others
India Data Center Physical Security Market
Others
Global Contactless Biometrics Technology Market
Others
Industrial Air Purifiers Market
Others
Industrial Wearable Devices Market
Others
Cloud DVR Market
Others
Cellular-Connected Laptops Market
Others
Global Extruded Plastics Market
Others
Global Smart Home Installation Service Market
Others
Smart Home Service Market
Others
Europe Polycarbonate Sheets Market
Others
Cashew Kernel Market
Others
Digital Thermal Plates Market
Others
Inorganic Tin Chemicals Market
Others
Global Essential Oils and Plant Extracts for Livestock Market