
 Viral Vector Contract Development and Manufacturing Organization (CDMO) Market | 2026-2036
Viral Vector Contract Development and Manufacturing Organization (CDMO) Market Size, Share, and Industry Trends Forecast 2026-2036
Viral Vector Contract Development and Manufacturing Organization (CDMO) Market Insights
Buyer concentration among large biopharmaceutical sponsors is recalibrating capacity allocation across the viral vector CDMO landscape. Lonza leverages its global manufacturing footprint to secure multi-year supply agreements with gene therapy developers. Catalent differentiates through integrated plasmid-to-viral-vector platforms that compress development timelines. Thermo Fisher Scientific extends its position via end-to-end cell and gene therapy services spanning clinical through commercial stages.
Viral vector contract development and manufacturing organizations specialize in the production of replication-deficient viral particles—typically adeno-associated virus, lentivirus, or adenovirus—delivering genetic payloads with titers exceeding 10^10 vector genomes per milliliter for therapeutic applications. The AAV vector segment dominates current revenue as the primary delivery vehicle for in vivo gene therapies targeting rare monogenic disorders. Lentiviral vector demand is expanding fastest in ex vivo cell therapy applications, particularly CAR-T and gene-edited stem cell programs where stable transduction remains critical.
FDA's CMC guidance for gene therapy and EMA's ATMP framework impose stringent potency, purity, and reproducibility standards that filter out underqualified CDMO competitors. The EU AI Act and evolving GMP Annex 1 requirements for sterile manufacturing add compliance layers for European-serving facilities. Stakeholders must monitor regulatory divergence between FDA and EMA regarding replication-competent virus testing and biosafety containment levels as programs advance toward commercial scale.
Market Dynamics
Gene therapy pipeline maturation is compressing development timelines and forcing CDMOs to absorb upfront capacity risk through dedicated suite investments and multi-year exclusivity agreements with sponsors.
Growth Catalysts
- FDA CMC Guidance for Gene Therapy:The FDA's Chemistry, Manufacturing, and Controls guidance mandates standardized potency assays and viral clearance validation, filtering out underqualified manufacturers and consolidating demand among credentialed CDMOs.
- Ex vivo Cell Therapy Expansion:CAR-T and gene-edited stem cell programs require lentiviral vector production at clinical and commercial scales, pulling manufacturing capacity toward stable transduction platforms.
- United States Clinical Trial Concentration:The majority of late-stage gene therapy trials operate under FDA oversight, anchoring sponsor demand and CDMO facility investments in Massachusetts, North Carolina, and California clusters.
Market Restraints
- Plasmid DNA Supply Bottleneck:GMP-grade plasmid production concentrates among a limited supplier base, creating input cost volatility and qualification delays for viral vector manufacturers.
- Replication-Competent Virus Testing Burden:FDA and EMA divergence on biosafety containment levels and detection assay standards adds regulatory friction and facility redesign costs for dual-territory programs.
- Allogeneic Cell Therapy Substitution:Off-the-shelf cell therapies reduce per-patient viral vector consumption compared to autologous processes, threatening long-term demand intensity for certain vector types.
Strategic Opportunities
- India Biomanufacturing Incentives:The country's Production Linked Incentive scheme for pharmaceuticals offers capital subsidies and tax benefits for greenfield viral vector facilities serving export markets.
- Continuous Bioprocessing Convergence:Perfusion-based cell culture systems integrated with inline analytics enable real-time titer monitoring and reduced facility footprint for high-density vector production.
- Japan Regenerative Medicine Framework:PMDA's streamlined review pathway for designated regenerative medical products accelerates commercial timelines for CDMOs with Japanese regulatory expertise.
Industry Challenges
- Gene Therapy Process Analytical Technology Expertise Gap:CDMOs struggle to recruit and retain scientists capable of developing and validating complex potency assays for novel vector serotypes.
- Multi-Product Suite Changeover Complexity:Viral vector facilities require extensive cleaning validation and environmental monitoring between campaigns, compressing effective utilization rates and extending lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Viral Vector Contract Development and Manufacturing Organization (CDMO) Market |
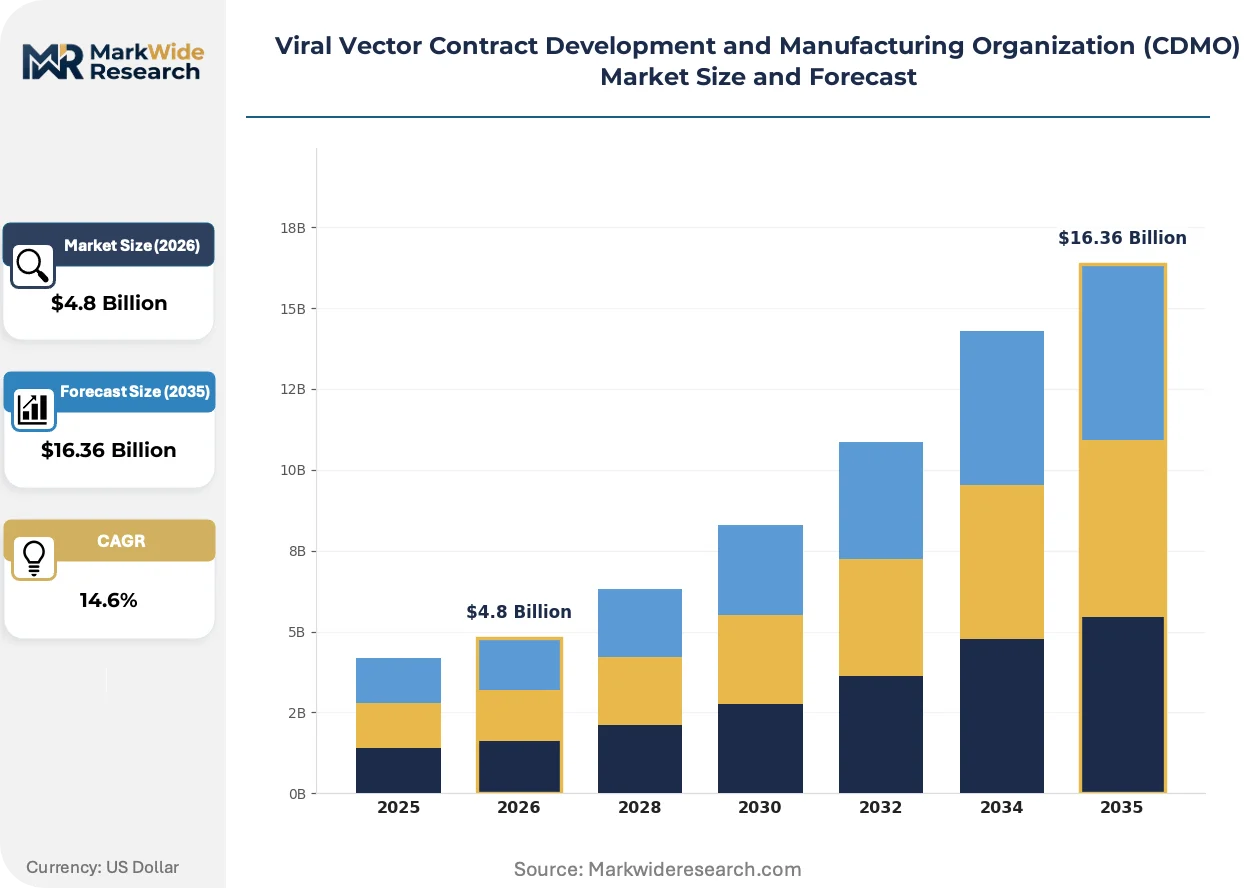
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adenoviral Vectors, Lentiviral Vectors, AAV Vectors, Others End User: Biopharmaceutical Companies, Research Institutes, Academic Institutions, Hospitals Technology: Transfection, Stable Cell Line Development, Viral Packaging, Others Application: Gene Therapy, Vaccines Development, Cell Therapy, Regenerative Medicine |
| Companies Covered | Thermo Fisher Scientific, Lonza, Catalent, Charles River Laboratories, AGC Biologics, Oxford Biomedica, FUJIFILM Diosynth Biotechnologies, Creative Biogene, REGENXBIO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Viral Vector Contract Development and Manufacturing Organization (CDMO) Market Trends and Innovations
Platform standardization and modular facility design are reshaping how CDMOs balance customization demands against economies of scale in viral vector production.
Stable producer cell lines are converging with suspension culture platforms to eliminate transient transfection bottlenecks. Gene therapy developers with late-stage assets are adopting these systems to secure supply continuity and reduce batch-to-batch variability. The technology is converging with single-use bioreactor infrastructure, enabling faster facility reconfiguration and lower capital barriers for capacity expansion.
EMA's ATMP framework revision tightens traceability requirements for starting materials and viral seed stocks across the European supply chain. Manufacturers must implement enhanced electronic batch records and genealogy tracking systems to maintain market access. The regulation most heavily affects CDMOs serving multiple EU member states with divergent national competent authority interpretations.
Sponsor technical teams now embed directly within CDMO quality units during process transfer, replacing arm's-length vendor management with co-development partnerships. This integration compresses tech transfer timelines and reduces deviation rates during scale-up. The pattern is most visible among United States-based biopharmaceuticals with expedited FDA designations requiring compressed CMC development.
Viral Vector Contract Development and Manufacturing Organization (CDMO) Market Segmentation
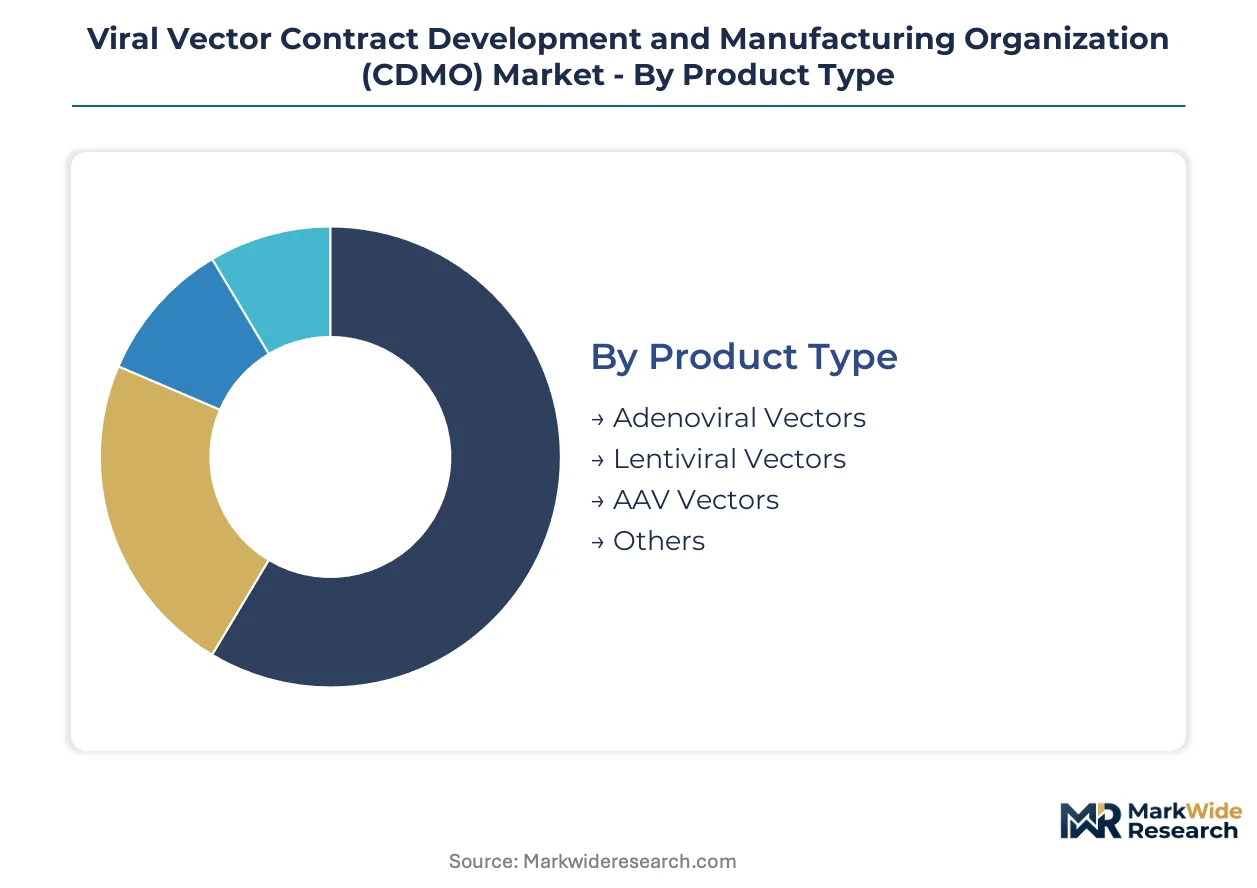
Viral vector CDMOs must balance platform standardization against bespoke process development across vector types, end-user requirements, and therapeutic modalities. Segmentation reveals where manufacturing complexity concentrates and which technology choices determine facility investment priorities.
Product Type:
Standardization potential varies sharply across vector architectures, with some platforms enabling plug-and-play manufacturing while others demand bespoke upstream and downstream development.
- AAV Vectors:These single-stranded DNA parvoviruses dominate in vivo gene therapy manufacturing, with serotype selection driving capsid engineering complexity. Demand concentrates among Massachusetts and California sponsors developing treatments for rare monogenic disorders, where FDA breakthrough therapy designations compress CMC timelines and require dedicated manufacturing slots.
- Lentiviral Vectors:RNA retroviruses with stable integration profiles anchor ex vivo cell therapy production, particularly CAR-T programs requiring high-titer transduction. North Carolina and Maryland biopharmaceutical clusters pull capacity toward lentiviral suites as allogeneic cell therapy pipelines mature.
- Adenoviral Vectors:Double-stranded DNA viruses with high immunogenicity serve vaccine and oncolytic applications where transient expression suffices.
- Others:Gammaretroviral and baculoviral systems occupy niche indications with specialized tropism or packaging requirements.
Most installed capacity flows through AAV Vectors. Expansion is steepest in Lentiviral Vectors.
End User:
Contracting patterns diverge between capital-rich sponsors seeking multi-year exclusivity and resource-constrained buyers prioritizing flexible access.
- Biopharmaceutical Companies:These sponsors command dedicated suite investments through long-term supply agreements spanning clinical phases to commercial launch. Late-stage gene therapy developers in the United States negotiate capacity reservations years ahead of BLA submission, absorbing upfront risk in exchange for manufacturing priority.
- Research Institutes:Academic medical centers with GMP-adjacent facilities purchase small-batch vector production for investigator-initiated trials. Funding volatility from NIH grant cycles creates demand lumpiness that CDMOs address through shared-suite scheduling models.
- Academic Institutions:University-based gene therapy programs typically lack internal GMP infrastructure, outsourcing early-phase vector generation for preclinical and Phase I studies.
- Hospitals:Health systems with embedded cell therapy programs procure patient-specific vectors for point-of-care autologous treatments.
Biopharmaceutical Companies absorb the majority of premium capacity. Academic Institutions are expanding fastest as university spinouts proliferate.
Technology:
Manufacturing methodology selection determines capital intensity, batch consistency, and regulatory pathway complexity for vector production.
- Transfection:Transient plasmid co-transfection of adherent or suspension cells remains the dominant production mode, enabling rapid serotype switching without cell line engineering. Massachusetts and California CDMOs maintain extensive transfection capacity to serve early-phase programs requiring platform flexibility over titer optimization.
- Stable Cell Line Development:Producer cell lines with integrated vector components eliminate plasmid supply dependencies and reduce batch-to-batch variability. Gene therapy sponsors with commercial-stage assets are adopting these systems to secure supply continuity and meet FDA potency consistency expectations.
- Viral Packaging:Helper-dependent amplification systems concentrate among specialized providers with advanced biosafety containment infrastructure.
- Others:Baculovirus-insect cell and cell-free synthetic approaches serve niche high-dose applications.
Transfection commands the largest installed base. Stable Cell Line Development is gaining share fastest as commercial programs advance.
Application:
Therapeutic modality dictates vector payload design, dosing regimen, and regulatory scrutiny intensity.
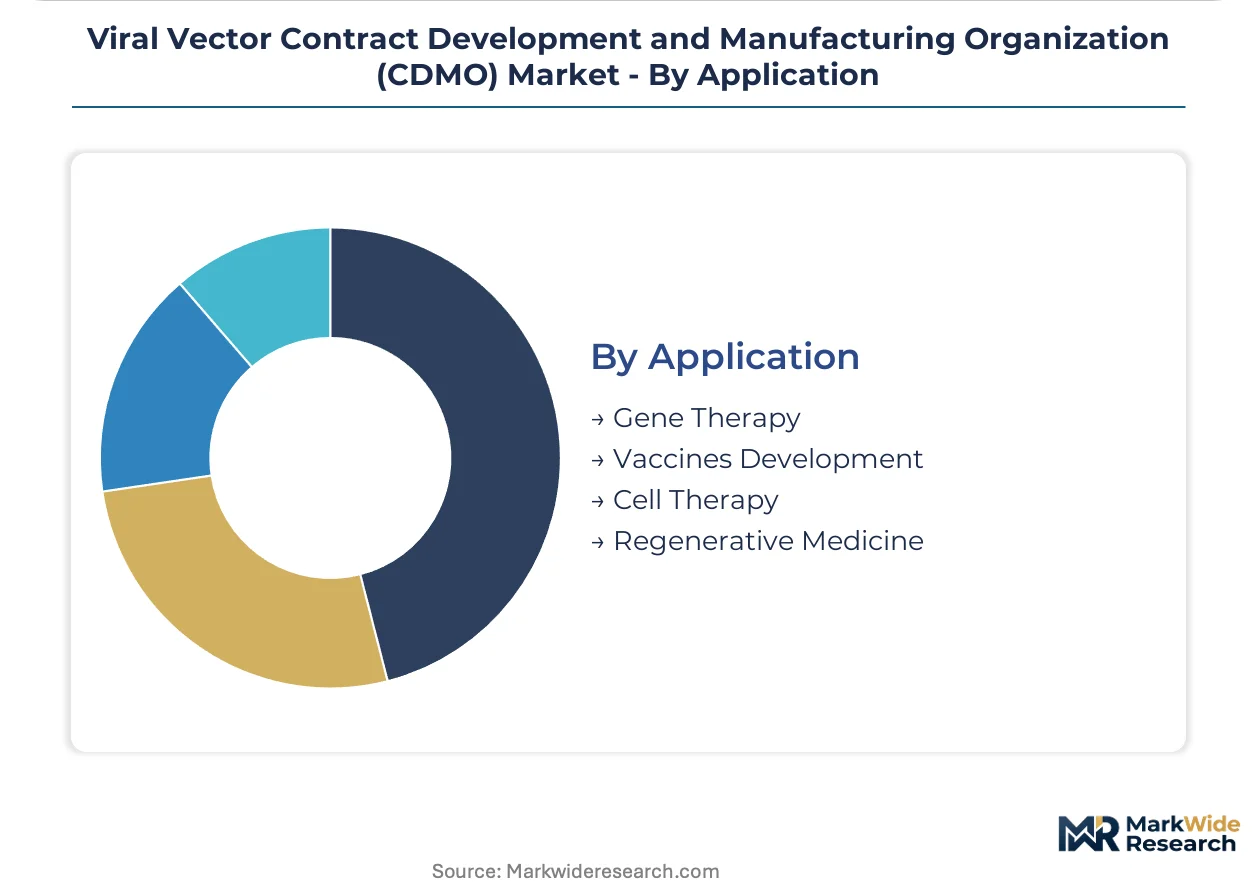
- Gene Therapy:In vivo genetic modification for monogenic diseases requires high-purity, high-potency vectors with stringent empty capsid removal. FDA CMC guidance on potency assay validation and replication-competent virus testing concentrates CDMO qualification efforts on gene therapy manufacturing.
- Cell Therapy:Ex vivo genetic modification platforms—CAR-T, TCR-T, and gene-edited stem cells—depend on lentiviral or gammaretroviral transduction. The application pulls manufacturing investment toward flexible suite designs accommodating both autologous and allogeneic process requirements.
- Vaccines Development:Viral vector vaccines for infectious disease prophylaxis leverage established adenoviral platforms with lower purity thresholds than therapeutic applications.
- Regenerative Medicine:Tissue engineering and organoid applications utilize specialized vector tropisms for directed differentiation protocols.
Gene Therapy absorbs the deepest manufacturing investments. Cell Therapy is climbing the fastest as pipeline assets transition to Phase II and III.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates viral vector CDMO capacity through dedicated gene therapy clusters, while Switzerland anchors European high-value manufacturing through specialized containment infrastructure. Regulatory divergence between FDA and EMA creates operational friction for dual-territory programs. Facility investments track sponsor pipeline maturation across three dominant geographies.
United States
Massachusetts and North Carolina biopharmaceutical clusters drive demand for AAV and lentiviral production at commercial scale. FDA Chemistry, Manufacturing, and Controls guidance on gene therapy potency assays filters contract manufacturer qualification. Greater Boston anchors dedicated suite investments from sponsors with breakthrough therapy designations requiring compressed timelines.
Switzerland
Gene therapy developers leverage Swissmedic's streamlined ATMP authorization pathway for early commercial access. Basel and Zurich host specialized containment facilities serving EU and global export markets. CDMOs implement dual GMP standards to manage EMA-FDA divergence on replication-competent virus testing requirements.
Germany
Baden-Württemberg and Bavaria concentrate plasmid DNA supply partnerships feeding viral vector upstream production. EMA's ATMP framework revision tightens traceability requirements for starting materials across European supply chains. Heidelberg and Munich facilities specialize in lentiviral vector manufacturing for CAR-T programs.
United Kingdom
Oxford and Cambridge gene therapy spinouts outsource early-phase vector production to CDMOs with MHRA-qualified facilities. The Medicines and Healthcare products Regulatory Agency maintains alignment with FDA standards post-Brexit, preserving transatlantic program continuity. London-based sponsors negotiate multi-year exclusivity agreements securing manufacturing slots.
India
Hyderabad and Bengaluru emerge as cost-competitive locations for plasmid DNA and early-phase viral vector production. The Production Linked Incentive scheme for pharmaceuticals offers capital subsidies for greenfield GMP facilities serving export markets. CDMOs target US and European sponsors seeking capacity diversification beyond traditional high-cost manufacturing bases.
Viral Vector Contract Development and Manufacturing Organization (CDMO) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the viral vector CDMO landscape. The market structure consolidates around three tiers: global life science tools providers with integrated cell and gene therapy platforms, mid-scale biologics specialists with dedicated viral vector suites, and emerging regional players leveraging cost advantages. Strategic archetypes include end-to-end service integrators, vector-type specialists, and geography-focused capacity providers. Capacity reservation agreements and co-development partnerships represent dominant competitive moves as sponsors lock in manufacturing slots ahead of regulatory submissions.
Within the diversified conglomerate tier, Thermo Fisher Scientific exemplifies end-to-end integration spanning clinical through commercial stages, while Lonza anchors global manufacturing footprint strategies through multi-year supply agreements. Among focused viral vector specialists, Oxford Biomedica occupies a position exemplifying lentiviral platform depth, and Catalent represents integrated plasmid-to-vector development compression. These archetypes illustrate how CDMOs balance standardization against bespoke process demands as gene therapy pipelines mature.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Lonza |
| Catalent |
| Charles River Laboratories |
| AGC Biologics |
| Oxford Biomedica |
| FUJIFILM Diosynth Biotechnologies |
| Creative Biogene |
| REGENXBIO |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up CDMO specialists have consolidated manufacturing assets across Massachusetts and North Carolina, concentrating supply-side control among sponsors with multi-year exclusivity agreements. This ownership pattern tightens pricing discipline as portfolio companies prioritize yield-per-suite metrics over volume discounts, while sponsor demand for dedicated capacity locks in premium rate structures regardless of spot-market softness.
Pricing Analysis
Capacity additions in India are reshaping price floors for early-phase viral vector production as Hyderabad and Bengaluru facilities undercut US and European rate cards. Three-tier pricing structure across premium, standard, and economy levels separates GMP-grade commercial batches from preclinical material and shared-suite academic runs. Cost compression in standard-tier lentiviral manufacturing is intensifying because plasmid DNA supply bottlenecks force CDMOs to absorb input volatility rather than pass through surcharges. Academic institutions exhibit highest price sensitivity, while biopharmaceutical companies with breakthrough therapy designations accept premium dedicated-suite rates to secure manufacturing priority.
Supply Chain Analysis
Returns of expired viral seed stocks and failed batch materials to plasmid suppliers for requalification create reverse-logistics flows that complicate traceability under EMA's ATMP framework. Geographic supply concentration centers on the United States, Switzerland, and Germany, with Baden-Württemberg plasmid producers feeding upstream vector manufacturing across Basel and Massachusetts clusters. Raw material dependencies rest on GMP-grade plasmid DNA, fetal bovine serum alternatives, and specialized resin chemistries for empty capsid removal. Single-source vulnerability in plasmid supply creates structural risk as qualified alternative suppliers require months of regulatory requalification. Distribution runs through sponsor-integrated logistics networks with cryogenic chain custody rather than third-party wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
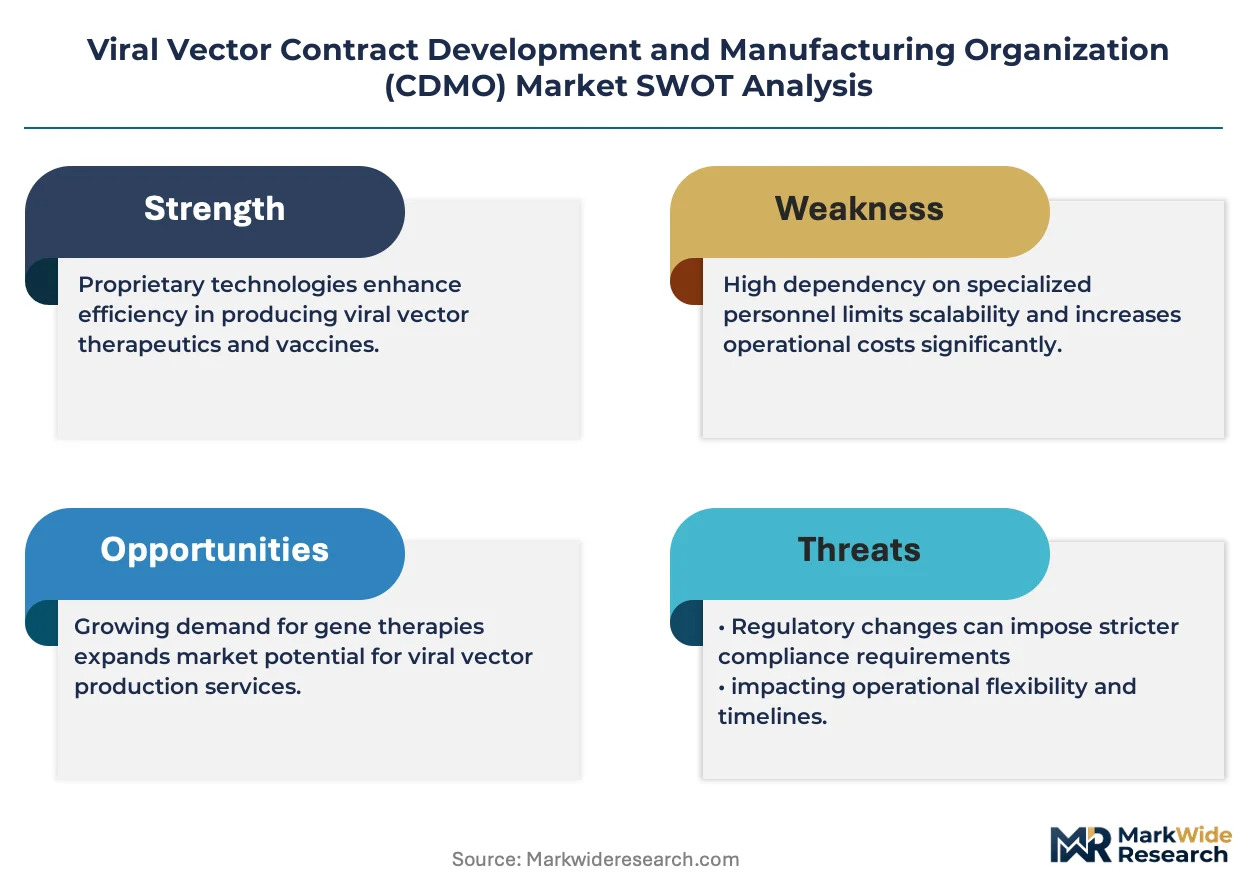
The viral vector CDMO market functions as a regulatory compounder where FDA CMC guidance on gene therapy potency assays continuously filters out underqualified manufacturers and consolidates demand among credentialed providers.
For Market Incumbents: To counter allogeneic cell therapy substitution threatening per-patient viral vector intensity, Lonza and Thermo Fisher Scientific should deepen backward integration into plasmid DNA production to capture margin currently lost to supply bottlenecks. Catalent can defend its integrated plasmid-to-vector platform position by accelerating stable producer cell line adoption to eliminate transfection-related batch variability that triggers FDA scrutiny. For New Entrants and Emerging Players: Enter via India's Production Linked Incentive scheme for pharmaceutical manufacturing, where capital subsidies and tax benefits for greenfield GMP facilities create penetrable cost-positioning against established US and European rate structures. Target academic institution demand for early-phase vector production, as university spinouts proliferate fastest and price sensitivity creates entry wedge before sponsors graduate to commercial-scale contracts. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale biologics specialists with dedicated viral vector suites but limited end-to-end cell and gene therapy integration. Long-term viability over the projection horizon hinges on CDMOs capturing stable cell line technology transitions as gene therapy pipelines mature beyond transient transfection dependence. Watch FDA-EMA convergence on replication-competent virus testing standards as inflection signal—regulatory harmonization would eliminate dual-facility costs currently burdening dual-territory programs.| Strategic Initiative | Industry Significance |
|---|---|
| Stable Producer Cell Line Adoption | Eliminates plasmid supply dependencies and reduces batch-to-batch variability for FDA compliance. |
| India Greenfield Facility Investment | Captures PLI scheme subsidies while positioning for cost-competitive export supply to US sponsors. |
| Integrated Plasmid-to-Vector Platform | Compresses CMC development timelines for gene therapy developers with expedited FDA designations. |
| Multi-Year Exclusivity Agreements | Locks manufacturing priority for sponsors with breakthrough therapy status in Greater Boston clusters. |
| EMA-FDA Dual GMP Certification | Enables single-facility supply for dual-territory programs despite divergent biosafety containment requirements. |
Research Methodology
Multiple input streams — structured interviews with viral vector manufacturing executives, regulatory affairs leads at gene therapy sponsors, and hospital cell therapy program directors — were reconciled against FDA CMC guidance documents, EMA ATMP framework revisions, and ClinicalTrials.gov pipeline tracking. Secondary validation drew from SEC 10-K filings of diversified life science conglomerates, Swissmedic authorization databases, and Indian PLI scheme beneficiary disclosures. Bottom-up capacity modeling across Massachusetts, North Carolina, and California facilities was triangulated against top-down sponsor pipeline expenditure estimates.
Historical capacity utilization patterns were cross-referenced against panel input from CDMO quality unit heads regarding tech transfer timeline compression. Segmentation modeling spanned vector type, manufacturing technology, therapeutic application, and end-user contracting archetype throughout the forecast period. CAGRs were derived from sponsor pipeline maturation velocity and facility investment announcement tracking rather than extrapolated historical growth rates. Industry-specific inputs included FDA breakthrough therapy designation velocity and stable producer cell line adoption curves among late-stage gene therapy developers.
The model holds under sustained FDA-EMA regulatory stringency and continued sponsor preference for outsourced manufacturing; deviation in allogeneic cell therapy substitution rates or plasmid supply disruption severity would shift capacity absorption timelines. Practitioners should monitor FDA potency assay validation requirement evolution and EMA traceability system implementation deadlines for early signals of competitive qualification barriers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Convertible Shipper Display Market
Others
Aerospace Software Testing Market
Others
Spain Feed Additives Market
Others
Iran Commercial Vehicles Lubricants Market
Others
Turbo Mills Market
Others
Canada Feed Additives Market
Others
Asia Pacific Contract Packaging Market
Others
Coalescing Filter Market
Others
Legal Services Market
Others
Deep Sea Mining Market
Others
North America Flexographic Printing Market
Others
Global Augmented Reality in Retail Market
Others
TWS Micro-Battery Market
Others
Gas Holders Market
Others
Pin Mills Market
Others
France Location-Based Services Market