
 Nanomedicine for Drug Delivery Market | 2026-2036
Nanomedicine for Drug Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Nanomedicine for Drug Delivery Market Analysis
Market Context
The pool of formulation scientists trained in lipid nanoparticle engineering is collapsing across North American contract development organizations, tightening capacity for complex nanomedicine programs. Novartis AG leverages its integrated manufacturing network to sustain commercial supply of liposomal oncology products. Moderna, Inc. anchors mRNA-lipid nanoparticle expertise through captive process development teams. Pfizer Inc. competes by extending fill-finish infrastructure originally scaled for vaccine distribution into broader nanomedicine contract services.
Technical Definition and Segment Structure
Nanomedicine for drug delivery encompasses pharmaceutical systems engineered at 1-100 nanometer scale, typically comprising lipid bilayers, polymeric matrices, or inorganic cores designed to modulate pharmacokinetics, target tissue accumulation, or intracellular release kinetics. These systems serve primarily to improve therapeutic indices of small molecules, nucleic acids, and biologics by overcoming solubility barriers, reducing off-target toxicity, or enabling cell-specific uptake. Liposome formulations dominate current revenue pools due to established manufacturing platforms and broad oncology labeling, while lipid nanoparticles represent the fastest-expanding segment driven by mRNA therapeutic validation. Intravenous delivery methods occupy the largest share of administered nanomedicine doses, though subcutaneous formulations are gaining development priority for chronic disease management.
Regulatory Framework and Outlook
The FDA maintains product-specific guidance for nanomaterial-containing drugs, while the EMA's reflection papers on nanomedicine quality requirements shape European development pathways, and China's NMPA implements GB standards for nanomaterial characterization in drug applications. These frameworks collectively elevate barriers for entrants lacking established regulatory affairs capabilities and validated analytical methods. Stakeholders must monitor evolving comparability standards for complex generic nanomedicines as patent cliffs approach for several blockbuster liposomal products.
Market Dynamics
The collapse of formulation scientist pools across North American contract development organizations is tightening capacity for complex nanomedicine programs, forcing pharmaceutical sponsors to internalize lipid nanoparticle expertise or accept extended development timelines.
Growth Catalysts
- FDA Accelerated Approval Pathways:Streamlined commercialization timelines for nanodrug candidates reduce time-to-market for oncology and rare disease therapies, incentivizing sponsor investment in nanoparticle formulation programs.
- mRNA Therapeutic Validation:Successful clinical deployment of lipid nanoparticle-encapsulated nucleic acids has validated the platform beyond vaccines, expanding addressable indications into genetic medicine and immuno-oncology.
- Oncology Department Expansion:Academic medical centers in Boston and San Diego are scaling nanoparticle-based therapeutic protocols, creating concentrated demand pull for next-generation liposomal and polymeric delivery systems.
Market Restraints
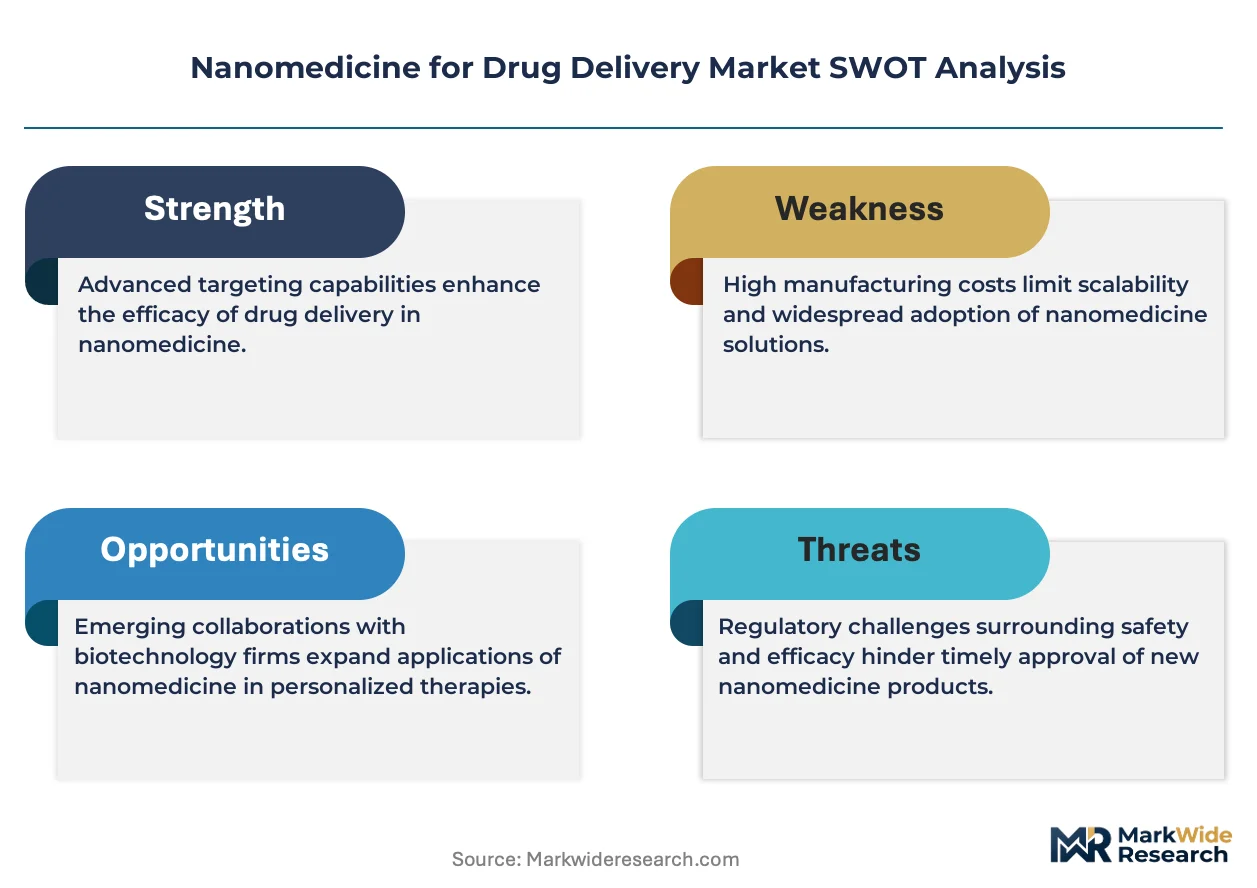
- Specialized Talent Scarcity:The pool of scientists trained in lipid nanoparticle engineering has contracted across North American CMOs, creating bottlenecks for complex program initiation and tech transfer.
- High-Purity Input Concentration:Supply of pharmaceutical-grade phospholipids and ionizable lipids concentrates among a limited set of specialized chemical suppliers, exposing formulation pipelines to single-source risk.
- EEMA Reflection Paper Complexity:Evolving quality requirements for nanomedicine comparability in Europe elevate analytical validation burdens, extending regulatory timelines for products seeking dual US-EU approval.
Strategic Opportunities
- Subcutaneous Formulation White Space:Chronic disease management applications remain underdeveloped relative to intravenous oncology, offering first-mover advantages for shelf-stable lipid nanoparticle systems enabling self-administration.
- China NMPA GB Standard Alignment:Harmonization opportunities exist for sponsors mastering China's nanomaterial characterization requirements ahead of competitors, unlocking access to the country's expanding biopharmaceutical market.
- Artificial Intelligence-Formulation Convergence:Machine learning platforms for predicting nanoparticle stability and biodistribution are reducing empirical screening cycles, compressing development costs for novel delivery architectures.
Industry Challenges
- Analytical Method Validation:Characterization of complex generic nanomedicines requires demonstration of sameness in critical quality attributes that existing guidance does not fully specify, creating regulatory uncertainty.
- Tech Transfer Complexity:Moving lipid nanoparticle processes from development to commercial scale demands reproducible control of particle size distributions and encapsulation efficiencies that laboratory methods cannot guarantee.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanomedicine for Drug Delivery Market |
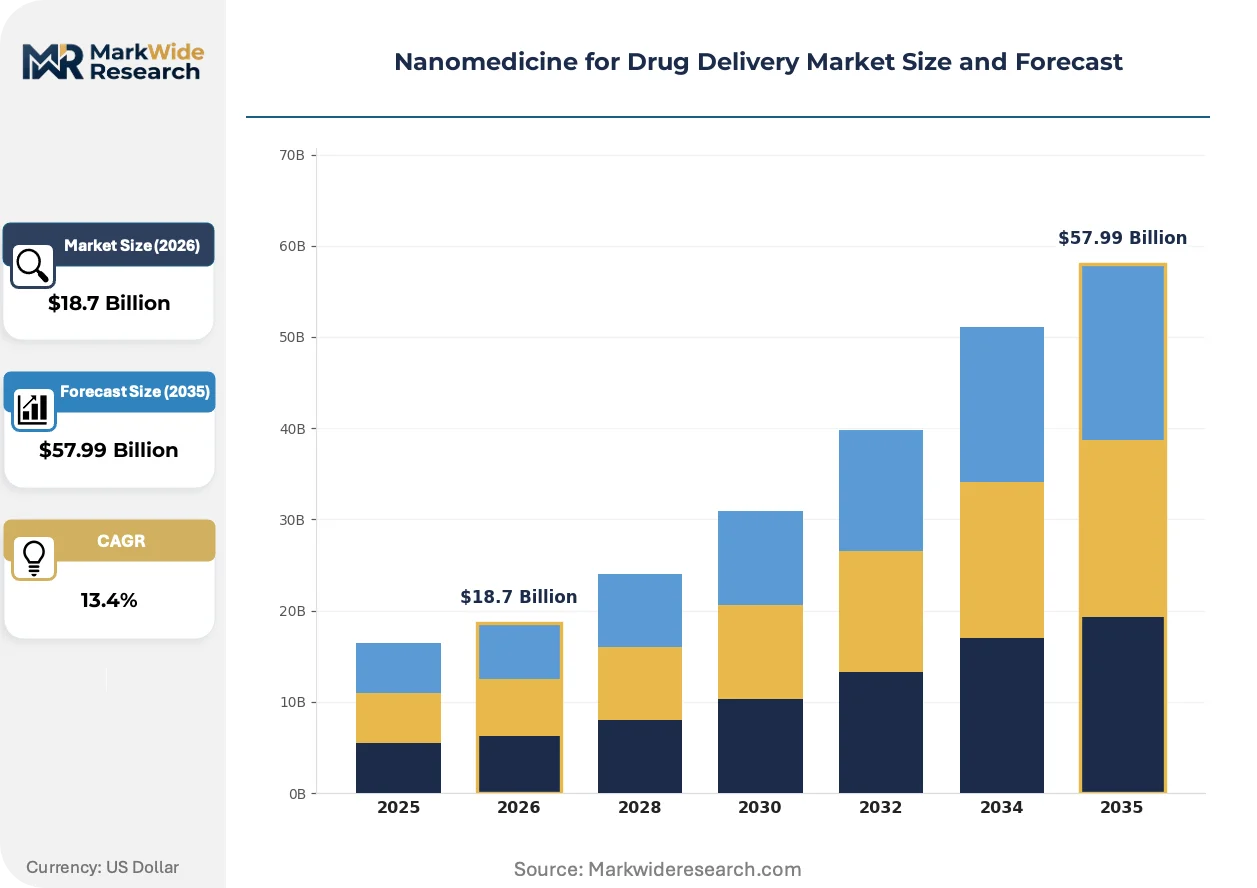
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $57.99 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Formulation Type: Liposomes, Nanoparticles, Micelles, Dendrimers Delivery Method: Oral, Intravenous, Subcutaneous, Transdermal Therapeutic Area: Cancer, Cardiovascular, Neurological, Infectious Diseases End User: Hospitals, Research Institutions, Pharmaceutical Companies, Contract Manufacturing Organizations |
| Companies Covered | Novartis AG, Bristol-Myers Squibb, Moderna, Inc., Gilead Sciences, Inc., Alnylam Pharmaceuticals, Inc., Pfizer Inc., Merck & Co., Inc., AstraZeneca plc, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanomedicine for Drug Delivery Market Emerging Trajectories
Active pharmaceutical ingredient solubility limitations and nucleic acid delivery requirements are forcing rapid architectural innovation in nanoscale formulation platforms, with functional differentiation increasingly determining competitive position.
Lipid nanoparticle engineering is bifurcating between infectious disease vaccine platforms and therapeutic applications requiring distinct organ targeting and extended circulation profiles. Gene therapy sponsors are adopting ionizable lipid libraries at accelerated pace to optimize tissue-specific biodistribution. This architectural split is compressing development timelines for oncology and rare disease programs while straining CMO capacity for multi-product campaigns.
EMA reflection papers on nanomedicine quality are hardening comparability standards for complex generics as blockbuster liposomal patents approach expiration. Sponsors must now demonstrate physicochemical equivalence through validated orthogonal methods that exceed historical bioequivalence thresholds. European developers are responding by investing in proprietary analytical platforms that can differentiate follow-on products from reference listed drugs.
Hospital pharmacy procurement is consolidating nanoparticle oncology formulations under centralized purchasing agreements that favor suppliers with integrated cold chain distribution. Academic medical centers are displacing fragmented distributor relationships with direct manufacturer contracts securing supply continuity for high-cost therapeutics. This concentration is most visible in United States oncology networks where formulary control has shifted toward pharmacy benefit managers with specialized infusion pharmacy capabilities.
Nanomedicine for Drug Delivery Market Segmentation
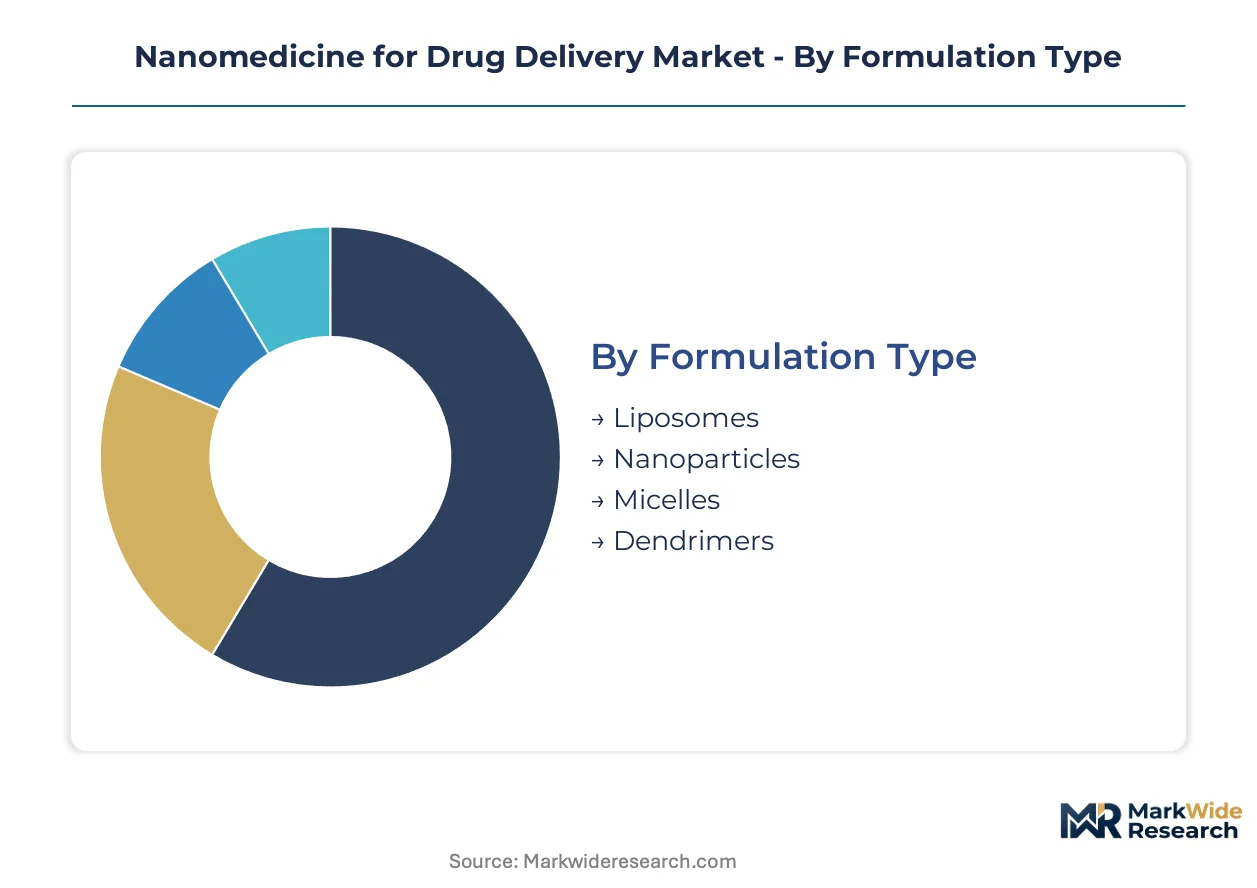
Nanomedicine formulation architectures determine regulatory pathways, manufacturing complexity, and reimbursement positioning. Delivery modality selection constrains addressable patient populations and dosing frequency. Therapeutic focus and procurement channel each reshape competitive dynamics and margin structures across the value chain.
Formulation Type:
FDA product-specific guidance and EMA reflection papers impose distinct characterization requirements on each architecture, elevating analytical validation burdens disproportionately.
- Liposomes:Phospholipid bilayer vesicles with aqueous cores enable encapsulation of hydrophilic small molecules and biologics. Commercial manufacturing platforms are mature, with oncology departments at academic medical centers in Boston and San Diego driving concentrated demand for next-generation liposomal oncology products.
- Nanoparticles:Solid lipid or polymeric matrices modulate pharmacokinetics through controlled release kinetics. Lipid nanoparticles specifically are expanding fastest, validated by mRNA therapeutic deployment and attracting investment into genetic medicine applications beyond infectious disease vaccines.
- Micelles:Amphiphilic block copolymer assemblies improve solubility of hydrophobic APIs. These systems serve primarily as enabling technologies for reformulation of existing small molecule drugs facing bioavailability limitations.
- Dendrimers:Highly branched synthetic macromolecules enable precise surface functionalization for targeted delivery. Complexity of scalable manufacturing has limited commercial penetration relative to lipid-based alternatives.
Established volume favors liposomes; emerging adoption favors nanoparticles.
Delivery Method:
Route of administration determines cold chain requirements, dosing convenience, and addressable care settings, with direct implications for reimbursement coding and patient compliance.
- Intravenous:Infusion-based delivery dominates current nanomedicine administration, particularly for oncology applications requiring precise dosing control. Hospital pharmacy procurement consolidation under centralized purchasing agreements favors suppliers with integrated cold chain distribution capabilities for high-cost therapeutics.
- Subcutaneous:Self-administration potential for chronic disease management remains underdeveloped relative to intravenous oncology, creating white space for shelf-stable lipid nanoparticle systems enabling home-based therapy.
- Oral:Gastrointestinal stability challenges have limited nanomedicine deployment, though polymeric nanoparticles show promise for enhancing bioavailability of poorly soluble small molecules.
- Transdermal:Skin penetration barriers constrain applicability, with current development focused on microneedle-assisted delivery for localized or systemic nucleic acid administration.
Infusion centers anchor current revenue; self-administration formats are climbing the fastest.
Therapeutic Area:
Clinical validation and reimbursement density vary sharply across indications, with oncology commanding premium pricing and genetic medicine expanding the addressable pipeline.
- Cancer:Liposomal formulations of chemotherapeutics command established reimbursement codes, with academic medical centers scaling nanoparticle-based therapeutic protocols. FDA accelerated approval pathways have streamlined commercialization timelines for novel oncology nanodrugs.
- Neurological:Blood-brain barrier penetration requirements drive architectural innovation in surface-functionalized nanoparticles, though clinical validation remains earlier-stage than oncology.
- Cardiovascular:Chronic disease management applications favor subcutaneous or oral formats, with development timelines extended by cardiovascular outcome study requirements.
- Infectious Diseases:mRNA vaccine validation has established lipid nanoparticle manufacturing at unprecedented scale, with platform extension into therapeutic vaccines and antimicrobial delivery.
Oncology concentrates near-term value; genetic medicine within neurological applications shows steepest expansion trajectory.
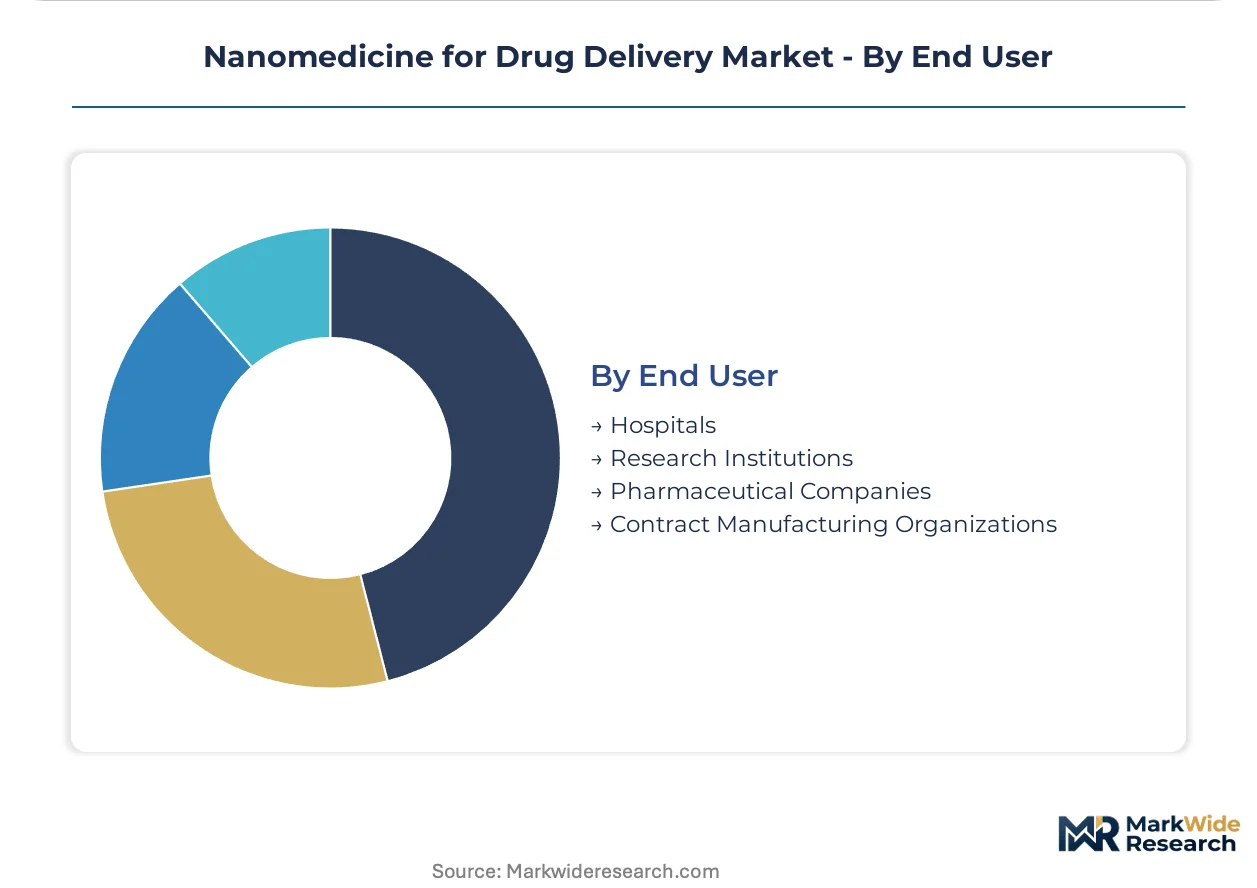
End User:
Procurement sophistication and technical specification authority determine supplier relationship dynamics and contract structures.
- Pharmaceutical Companies:Internal formulation capabilities are expanding as sponsors respond to CMO capacity constraints for complex nanomedicine programs. Captive process development teams anchor strategic programs.
- Contract Manufacturing Organizations:The pool of formulation scientists trained in lipid nanoparticle engineering has contracted across North American CMOs, tightening capacity and extending development timelines for outsourced programs.
- Hospitals:Pharmacy benefit managers with specialized infusion pharmacy capabilities have consolidated formulary control, displacing fragmented distributor relationships with direct manufacturer contracts.
- Research Institutions:Academic medical centers generate clinical validation data and early adoption demand, particularly in Boston and San Diego biotech clusters.
Integrated pharma sponsors capture margin; CMO partnerships face capacity constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA product-specific guidance for nanomaterial-containing drugs anchors the United States as the dominant geography, with concentrated demand pull from academic medical centers and streamlined commercialization pathways accelerating program development.
United States
Oncology departments at academic medical centers in Boston and San Diego are expanding nanoparticle-based therapeutic protocols, creating concentrated demand for next-generation liposomal systems. FDA accelerated approval pathways reduce time-to-market for nanodrug candidates, incentivizing sponsor investment. The Greater Boston biotech cluster anchors lipid nanoparticle process development expertise.
Germany
EMA reflection papers on nanomedicine quality requirements shape European development pathways, elevating analytical validation burdens for products seeking dual US-EU approval. German contract development organizations face tightening capacity for complex nanomedicine programs as formulation scientist pools contract. The Rhine-Main region concentrates regulatory affairs capabilities for nanomaterial characterization.
China
NMPA GB standards for nanomaterial characterization in drug applications create harmonization opportunities for sponsors mastering quality requirements ahead of competitors. Domestic biopharmaceutical market expansion drives demand for lipid nanoparticle manufacturing platforms. Shanghai and Suzhou industrial parks anchor integrated nanomedicine development and production infrastructure.
Switzerland
Swissmedic maintains stringent quality requirements for nanomedicine comparability, supporting premium positioning for complex generic development. Integrated manufacturing networks sustain commercial supply of liposomal oncology products across European markets. Basel anchors pharmaceutical formulation science capabilities with captive process development teams.
United Kingdom
Post-Brexit regulatory divergence from EMA frameworks creates parallel submission requirements for nanomedicine sponsors seeking UK market access. London and Cambridge biotech clusters generate clinical validation data for early-stage nanoparticle programs. MHRA guidance development on nanomaterial-containing drugs proceeds alongside European alignment efforts.
Nanomedicine for Drug Delivery Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidation around companies possessing captive lipid nanoparticle expertise and validated regulatory pathways. The integrated tier commands commercial supply relationships for high-cost oncology therapeutics, while specialists concentrate on platform technology licensing and early-stage development partnerships. Three archetypes dominate: vertically integrated pharmaceutical sponsors with in-house formulation capabilities, technology-focused biotechs with proprietary delivery platforms, and contract manufacturing organizations with specialized nanomedicine capacity. Competitive moves center on strategic partnerships securing ionizable lipid supply and capacity expansion addressing CMO bottlenecks.
Among integrated pharmaceutical sponsors, Novartis AG and Pfizer Inc. exemplify the captive manufacturing archetype, each sustaining commercial supply through controlled production networks. Moderna, Inc. occupies a distinct position anchoring mRNA-lipid nanoparticle expertise through dedicated process development infrastructure. These three companies represent contrasting strategic postures: legacy pharmaceutical integration, vaccine-platform extension, and nucleic acid therapeutic specialization.
| Leading Market Players |
|---|
| Novartis AG |
| Bristol-Myers Squibb |
| Moderna, Inc. |
| Gilead Sciences, Inc. |
| Alnylam Pharmaceuticals, Inc. |
| Pfizer Inc. |
| Merck & Co., Inc. |
| AstraZeneca plc |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
Manufacturing scale advantages at integrated pharmaceutical sponsors create asymmetric pricing power against fragmented contract development organizations, compressing margins for outsourced lipid nanoparticle programs while elevating price floors for in-house production networks. FDA accelerated approval pathways and EMA reflection paper compliance costs concentrate premium pricing among sponsors with validated regulatory affairs capabilities, leaving price-sensitive biotech developers dependent on capacity-constrained CMOs.
Pricing Analysis
United States-based lipid nanoparticle manufacturing commands 15-25% price premiums over European equivalents due to concentrated demand from Boston and San Diego biotech clusters and expedited FDA commercialization timelines. Pricing stratifies across premium, standard, and economy tiers based on ionizable lipid quality grades and analytical validation depth, with GMP-certified phospholipid inputs carrying certification premiums. Cost compression in standard-tier CMO services is intensifying because formulation scientist scarcity extends development timelines and forces expedited scheduling fees. Emerging biotech sponsors exhibit highest price sensitivity, while integrated pharma incumbents prioritize supply security over unit cost optimization.
Supply Chain Analysis
Pharmaceutical-grade ionizable lipid synthesis concentrates among specialized chemical suppliers in Switzerland, Germany, and the United States, creating single-source vulnerability for nucleic acid therapeutic developers scaling beyond clinical quantities. Manufacturing networks draw from high-purity phospholipid feedstocks, cholesterol derivatives, and polyethylene glycol-lipid conjugates anchored in European and North American chemical production hubs. Tariff exposure on specialized lipid imports from Switzerland threatens cost structures for US-based formulation programs. Distribution runs through integrated cold chain networks controlled by hospital pharmacy benefit managers with specialized infusion capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
mRNA therapeutic validation has disrupted traditional small-molecule formulation economics, creating a high-growth disruption where lipid nanoparticle expertise determines competitive survival. FDA accelerated approval pathways and EMA reflection paper complexity reward early movers with captive manufacturing capabilities.
For Market Incumbents: Compound defensive advantages by acquiring specialized ionizable lipid suppliers to secure input concentration against emerging biotech competitors. Expand captive process development teams in Greater Boston to capture formulation scientist talent before CMO capacity constraints worsen. Prioritize backward integration into high-purity phospholipid production to neutralize single-source supplier leverage.
For New Entrants and Emerging Players: Anchor in subcutaneous formulation white space for chronic disease management, where shelf-stable lipid nanoparticle systems remain underdeveloped relative to intravenous oncology saturation. Target China NMPA GB standard alignment ahead of multinational competitors to unlock access to expanding domestic biopharmaceutical demand. Pursue artificial intelligence-formulation convergence partnerships to compress empirical screening cycles and offset CMO capacity bottlenecks.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated platforms with validated regulatory pathways over pure-play delivery technology licensors. Long-term viability across the projection horizon rests on manufacturing scale and EMA/FDA dual-approval track records rather than preclinical platform differentiation. Monitor ionizable lipid library patent filings as the critical inflection signal for next-generation tissue-targeting capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Ionizable Lipid Supply Agreement | Secures pharmaceutical-grade inputs against single-source concentration risk from Swiss and German chemical suppliers. |
| Subcutaneous Formulation Development | Captures chronic disease management white space with shelf-stable systems enabling patient self-administration. |
| AI-Formulation Platform Integration | Compresses nanoparticle stability screening cycles through machine learning prediction of biodistribution profiles. |
| China NMPA Regulatory Alignment | Unlocks access to expanding domestic biopharmaceutical market through GB standard compliance mastery. |
| CMO Capacity Expansion | Addresses formulation scientist scarcity tightening North American outsourced program timelines. |
Methodological Framework
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers anchors the qualitative findings against secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up and top-down triangulation reconciles sponsor pipeline disclosures with CMO capacity utilization estimates across the analysis window.
Sensitivity analysis across formulation type, delivery method, therapeutic area, and regional regulatory cluster dimensions shapes the analytical framework throughout the forecast period. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion, with inputs including ionizable lipid manufacturing capacity additions, academic medical center protocol adoption rates, and nanomedicine comparability guidance evolution.
Underlying assumptions cover sustained FDA accelerated approval pathway utilization and stable ionizable lipid supply concentration, with deviation risk concentrated in EMA reflection paper enforcement intensity and China NMPA regulatory harmonization pace. Practitioners should keep alternative scenarios live as formulation scientist labor market conditions and phospholipid input pricing evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Qatar Smartphone Market
Others
Aboveground Storage Tanks Market
Others
US Automotive LED Lighting Market
Others
North America Commercial Vehicles Lubricants Market
Others
Asia-Pacific 3D Printing Construction Market
Others
Technical Films Market
Others
Insoluble Sulfur Market
Others
Remanufacturing-as-a-Service (RaaS) Market
Others
Middle East and Africa Surface Analysis Market
Others
Roasted Wheat Market
Others
Europe Digital Experience Platform Market
Others
Enterprise Video Content Management Market
Others
Cat Dry Food Market
Others
Global Wireless Asset Management Market
Others
Global B2B Enterprise and Industrial Wearables Market
Others
Thermoformed Plastics Market