
 5G Enabled Healthcare Services Market | 2026-2036
5G Enabled Healthcare Services Market Size, Share, and Industry Trends Forecast 2026-2036
5G Enabled Healthcare Services Market Outlook
Modular service bundling is restructuring how healthcare buyers evaluate 5G connectivity contracts. Ericsson leverages its Open RAN expertise to anchor multi-year infrastructure partnerships with regional hospital networks. Qualcomm competes through purpose-built modem chipsets optimized for ultra-reliable low-latency communication in surgical settings. Nokia Corporation specializes in private 5G network deployments that isolate patient data traffic from public cellular congestion.
5G enabled healthcare services encompass cellular-connected diagnostic, therapeutic, and administrative functions requiring sub-10 millisecond latency and 99.999% reliability for clinical-grade use. These systems integrate network slicing, edge computing nodes, and encrypted health data protocols to support real-time remote interventions and continuous physiological streaming. Telemedicine represents the largest revenue pool, though surgical procedures command the highest per-session margins due to hardware intensity and liability premiums. AI-driven analytics is the fastest-expanding technology segment as radiology departments deploy inference-at-the-edge for immediate anomaly flagging during imaging transfers.
The FDA governs connected device cybersecurity through its premarket guidance, while HIPAA mandates encryption standards for all transmitted protected health information. The FCC's spectrum allocation rules for Citizens Broadband Radio Service directly determine where private 5G networks can operate without interference from incumbent naval radar systems. Stakeholders must monitor how the FCC's pending spectrum auction reforms affect hospital licensing costs for localized network infrastructure.
Market Dynamics
Network slicing architectures are forcing health systems to restructure procurement around latency-grade service tiers rather than bandwidth volume, compressing vendor evaluation cycles and locking in multi-year infrastructure partnerships.
Growth Catalysts
- Remote surgical robotics:Sub-10 millisecond latency requirements from telesurgery suites are mandating 5G infrastructure upgrades in tertiary hospital clusters across Germany, Japan, and the United States.
- FDA Software as a Medical Device guidance:The agency's evolving premarket pathways for connected diagnostic platforms are creating regulatory clarity that accelerates hospital system adoption of cellular-enabled monitoring devices.
- Edge computing node deployment:Radiology departments are installing on-premise inference hardware to process imaging AI locally, reducing backhaul dependency and enabling real-time anomaly detection during patient transfers.
Market Restraints
- Semiconductor supply concentration:Purpose-built 5G modem chipsets for ultra-reliable low-latency communication rely on concentrated foundry capacity in Taiwan, creating procurement vulnerability for surgical equipment manufacturers.
- Spectrum licensing cost volatility:The FCC's Citizens Broadband Radio Service auction mechanics generate uncertainty for hospital systems budgeting private network infrastructure deployments across multi-year capital cycles.
- Cybersecurity compliance burden:HIPAA encryption mandates for protected health information transmission impose architectural constraints that limit vendor flexibility and extend system integration timelines.
Strategic Opportunities
- Rural health system penetration:Federally qualified health centers in the United States are accessing USDA rural development grants to deploy private 5G networks that bypass fiber infrastructure gaps.
- AI-at-the-edge convergence:Machine learning inference hardware is integrating with network slicing controllers to enable predictive patient deterioration alerts without cloud dependency.
- Outcome-based reimbursement models:CMS value-based care programs are incentivizing continuous physiological monitoring that 5G-enabled telemetry platforms can deliver at scale.
Industry Challenges
- Clinical workflow integration:Nursing staff require retraining on telemetry dashboard interpretation, creating adoption friction that delays realized utilization of deployed infrastructure.
- Multi-vendor interoperability certification:Device manufacturers must validate cross-platform data exchange through IHE profiles, extending time-to-revenue for new connected health products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Enabled Healthcare Services Market |
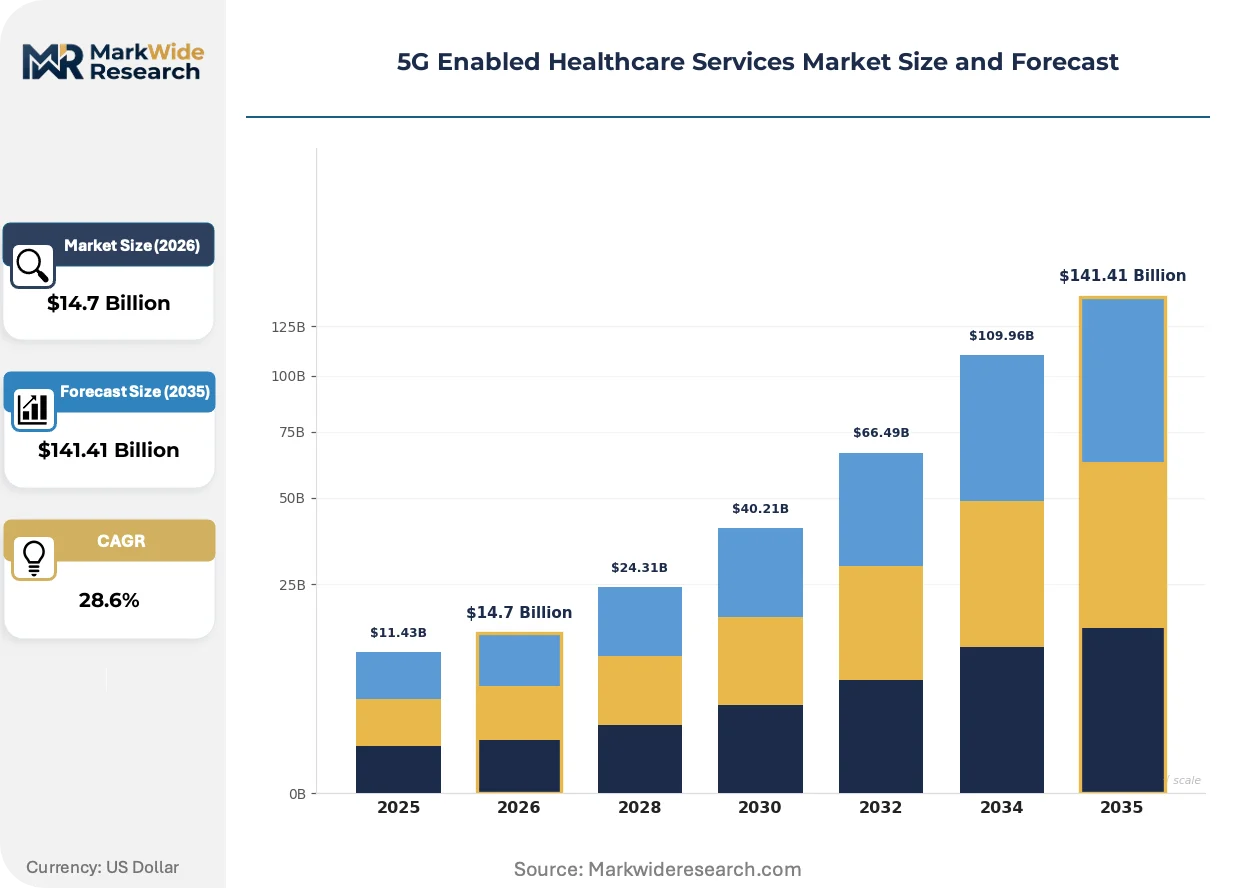
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $141.41 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Telemedicine, Remote Monitoring, Virtual Consultations, Mobile Health Application: Chronic Disease Management, Emergency Services, Surgical Procedures, Wellness Programs Technology: Wearable Devices, IoT Health Solutions, Virtual Reality, AI-Driven Analytics End User: Hospitals, Payors, Patients, Healthcare Providers |
| Companies Covered | AT&T, Verizon, Ericsson, China Mobile Limited, T-Mobile, Cisco Systems, Nokia Corporation, Huawei Technologies, Qualcomm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Enabled Healthcare Services Market Strategic Shifts
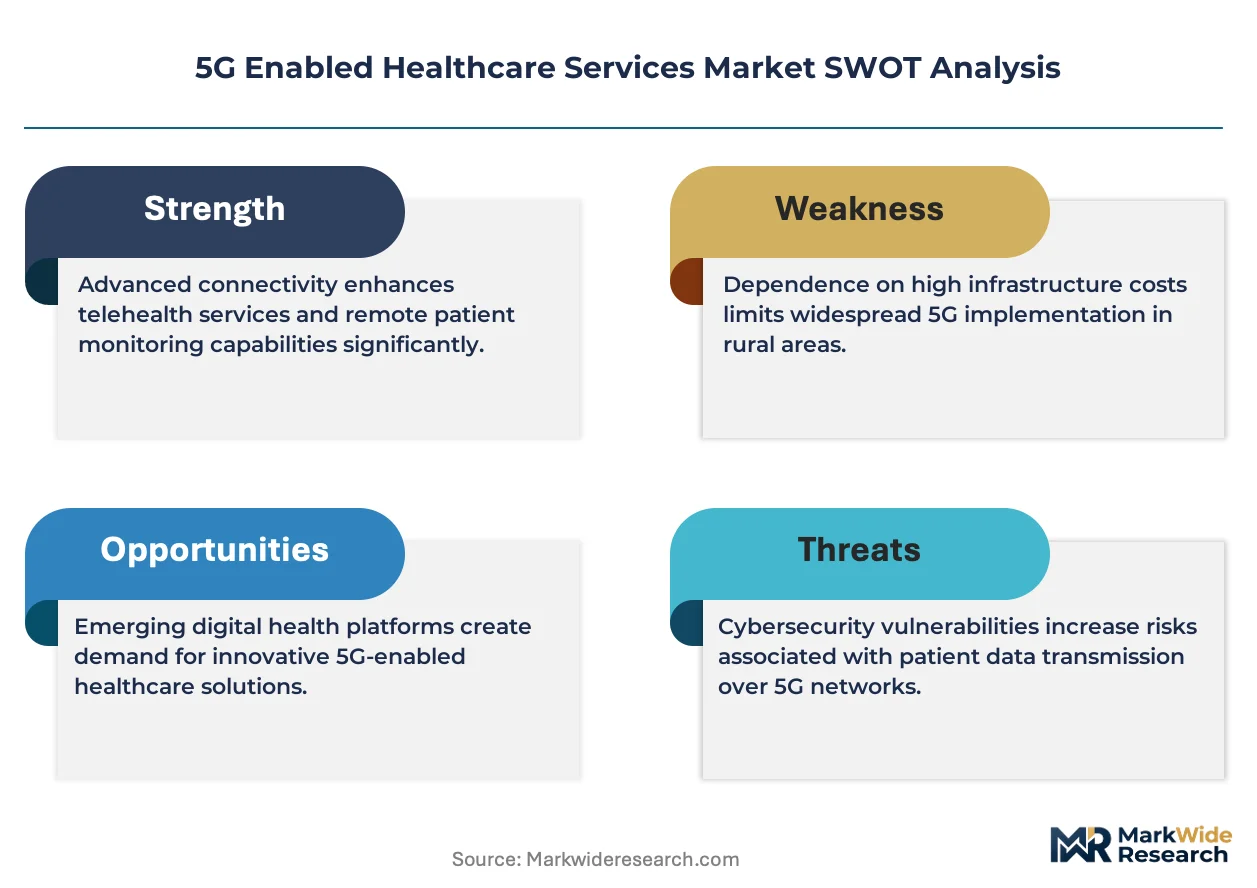
Cellular network architecture is bifurcating between public carrier services and private licensed deployments, with hospital systems increasingly prioritizing traffic isolation over cost optimization in infrastructure decisions.
Network function virtualization is integrating with 5G core architectures to enable dynamic bandwidth allocation between emergency response and routine administrative traffic. Hospital IT departments are adopting software-defined networking controllers that reconfigure slicing parameters without hardware replacement. This flexibility is compressing infrastructure refresh cycles from seven-year hardware rotations to continuous software updates.
The FDA's premarket cybersecurity guidance is mandating SBOM documentation and vulnerability disclosure timelines for all connected diagnostic devices. Device manufacturers are restructuring quality management systems to incorporate continuous monitoring of third-party component security. Radiology and cardiology device categories face the steepest compliance burden due to persistent network connectivity requirements.
Health system procurement teams are consolidating vendor relationships around integrated platform contracts that bundle connectivity, edge hardware, and clinical software. This concentration is displacing point-solution purchasing that characterized early 5G healthcare pilots. Integrated delivery networks in California and Texas are pioneering these consolidated sourcing models, establishing templates that regional hospital alliances are replicating.
5G Enabled Healthcare Services Market Segmentation
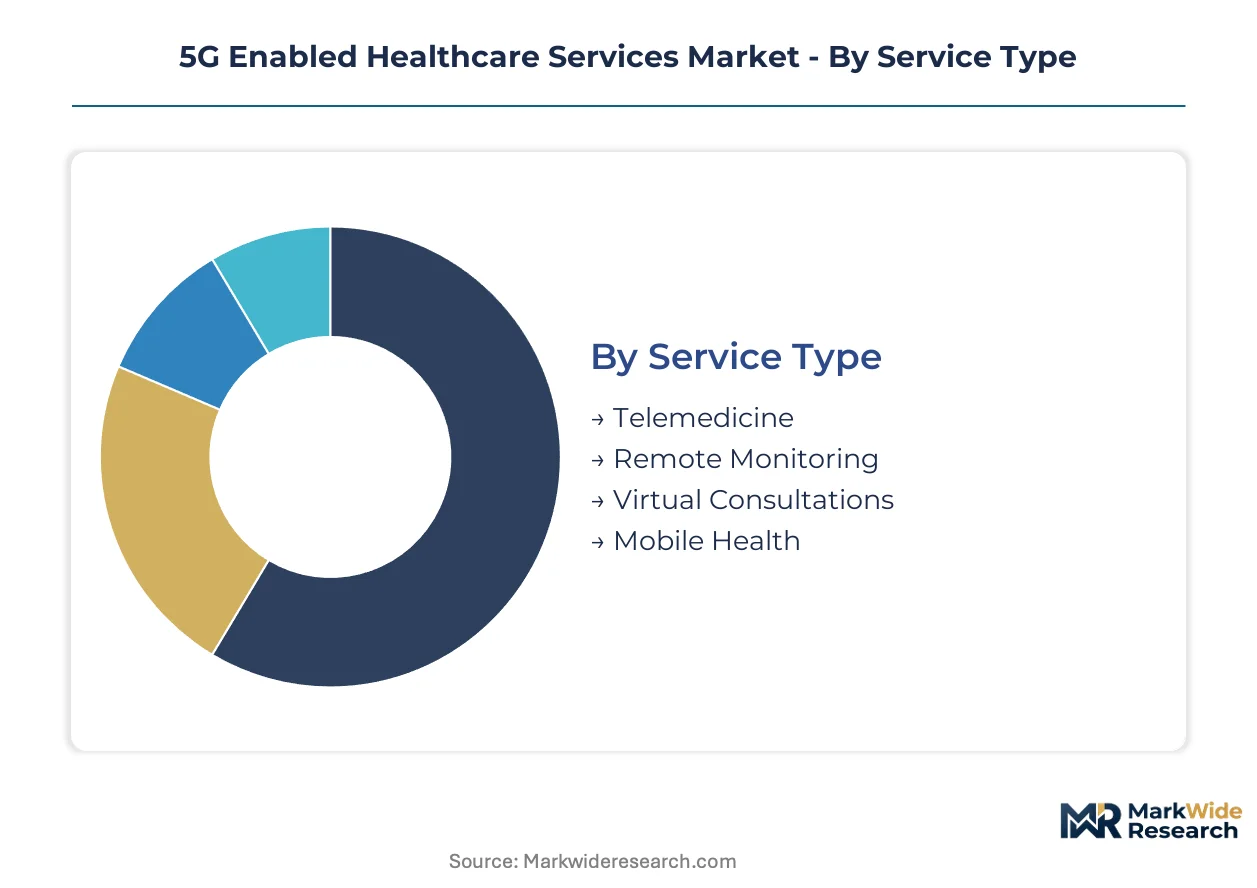
5G healthcare market segmentation reveals distinct procurement patterns across service tiers. Buyers prioritize latency-critical applications over bandwidth-heavy administrative functions, reshaping how vendors structure platform pricing and deployment architectures.
Service Type:
Telemedicine commands volume leadership while surgical-grade remote monitoring captures premium margins through reliability guarantees.
- Telemedicine:Video-based diagnostic and therapeutic consultations requiring 99.9% uptime SLAs. Demand concentrates in United States integrated delivery networks seeking to extend specialist reach into rural catchment areas without fiber dependency.
- Remote Monitoring:Continuous physiological telemetry for post-acute and chronic populations. German hospital clusters and Japanese tertiary centers are mandating sub-10 millisecond latency for cardiac and neurological patient surveillance.
- Virtual Consultations:Scheduled asynchronous exchanges between patients and care teams.
- Mobile Health:Consumer-facing wellness and medication adherence applications.
Today's leader: Telemedicine. Tomorrow's challenger: Remote Monitoring.
Application:
Acute intervention segments outspend preventive programs by factor of three in per-deployment infrastructure investment.
- Surgical Procedures:Telesurgery and robotic-assisted interventions demanding ultra-reliable low-latency communication. United States academic medical centers in California and Texas are piloting cross-state surgical collaboration over private 5G networks.
- Chronic Disease Management:Longitudinal monitoring for diabetes, heart failure, and COPD populations. Federally qualified health centers across rural United States are accessing USDA grants to bypass fiber infrastructure gaps.
- Emergency Services:Pre-hospital triage and ambulance-to-hospital data streaming.
- Wellness Programs:Employer-sponsored preventive health and lifestyle coaching platforms.
Surgical Procedures capture the steepest expansion trajectory as FDA regulatory clarity accelerates hospital system authorization of connected robotic platforms.
Technology:
Edge-native solutions are displacing cloud-dependent architectures as radiology departments prioritize inference latency over storage economics.
- AI-Driven Analytics:Real-time anomaly detection during imaging transfers and predictive deterioration alerts. Radiology departments in Germany and Japan are deploying on-premise inference hardware to eliminate backhaul dependency.
- Wearable Devices:Continuous glucose monitors, cardiac event recorders, and pulse oximetry with cellular connectivity. United States payors are reimbursing remote patient monitoring codes that require FDA-cleared device integration.
- IoT Health Solutions:Connected infusion pumps, smart beds, and environmental sensors.
- Virtual Reality:Surgical training and patient rehabilitation immersion therapy.
AI-Driven Analytics is gaining share fastest as network slicing controllers integrate with machine learning inference hardware.
End User:
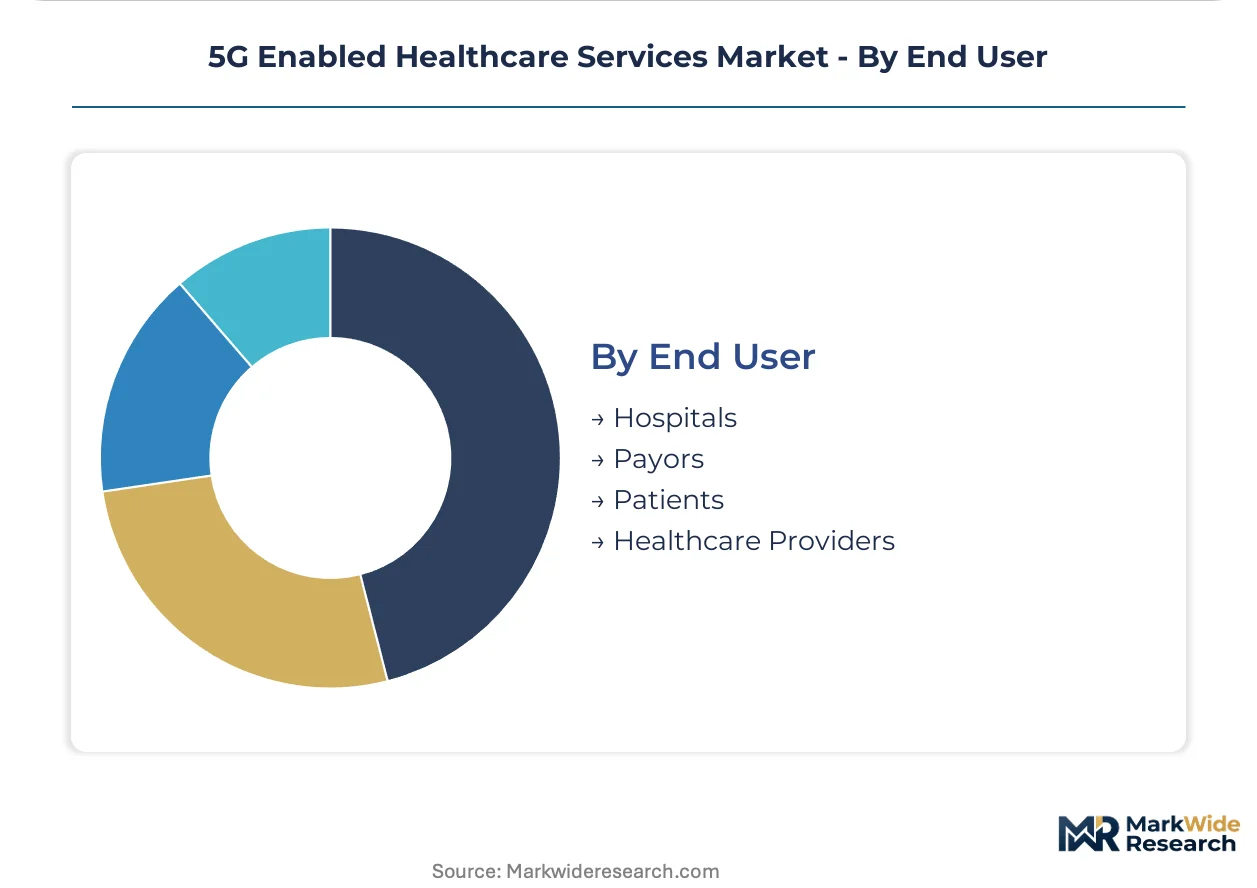
Hospital procurement teams are consolidating vendor relationships around integrated platform contracts that bundle connectivity, edge hardware, and clinical software.
- Hospitals:Tertiary and community systems deploying private 5G networks for traffic isolation. Health system consolidation in United States is accelerating infrastructure investment through centralized capital allocation.
- Healthcare Providers:Individual physician practices and specialty clinics accessing carrier-managed network services.
- Payors:Insurance entities reimbursing remote monitoring and virtual care modalities.
- Patients:Direct-to-consumer acquisition of cellular-connected diagnostic devices.
Hospitals dominate current deployment value. Healthcare Providers represent the addressable expansion base as reimbursement codes broaden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States pioneered cellular-enabled healthcare through early telemedicine pilots at academic medical centers. Germany and Japan scaled surgical robotics infrastructure through coordinated industry-academia partnerships. China's national broadband strategy accelerated hospital digitization through state-directed capital deployment.
United States
Tertiary hospital clusters in California and Texas are deploying private 5G networks to isolate surgical robotics traffic from administrative systems. The FCC's Citizens Broadband Radio Service rules determine licensing costs for localized infrastructure. Academic medical centers in Boston and Houston are piloting cross-state telesurgery collaboration over dedicated spectrum.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia mandate sub-10 millisecond latency for cardiac telemetry platforms. The country's national telecommunications regulator enforces reliability standards for clinical-grade connectivity. Siemens Healthineers anchors a Munich-based ecosystem integrating network slicing with imaging AI deployment.
Japan
Tokyo and Osaka metropolitan hospitals are scaling remote patient monitoring for aging populations through carrier-managed network services. The Ministry of Economy, Trade and Industry coordinates 5G hospital infrastructure through public-private consortia. Nagoya medical device manufacturers supply surgical robotics platforms optimized for ultra-reliable low-latency communication.
China
Provincial hospital systems in Guangdong and Jiangsu are integrating cellular-connected diagnostics through state-backed infrastructure investment. The national medical products administration governs cybersecurity documentation for connected devices. Shenzhen and Shanghai technology clusters produce edge computing hardware for radiology AI inference.
South Korea
Seoul-based hospital networks deploy network slicing to prioritize emergency response traffic over routine administrative data. The national spectrum authority allocates dedicated bands for private healthcare deployments. Busan medical centers pioneer 5G-enabled ambulance-to-hospital streaming for pre-hospital triage.
5G Enabled Healthcare Services Market Competitive Environment
The competitive structure tilts toward telecommunications infrastructure specialists anchoring multi-year hospital partnerships. Vendor relationships concentrate around integrated platform contracts bundling connectivity, edge hardware, and clinical software. Equipment manufacturers and carrier service providers constitute the dominant archetypes. Strategic moves center on private network deployment expertise and regulatory pre-certification for clinical-grade reliability.
Among infrastructure specialists, Ericsson and Nokia Corporation represent the private 5G deployment archetype, while Qualcomm exemplifies purpose-built component optimization for surgical latency requirements. AT&T and Verizon occupy positions within the carrier-managed services tier, anchoring hospital system relationships through dedicated clinical network SLAs. China Mobile Limited sits within the state-coordinated deployment archetype characteristic of national broadband strategies.
| Leading Market Players |
|---|
| AT&T |
| Verizon |
| Ericsson |
| China Mobile Limited |
| T-Mobile |
| Cisco Systems |
| Nokia Corporation |
| Huawei Technologies |
| Qualcomm |
| Others |
Value Chain & Pricing Dynamics
Telecommunications infrastructure specialists rolled up through private-equity consolidation now anchor multi-year hospital partnerships, translating concentrated vendor relationships into pricing discipline that resists commoditization despite carrier competition. Their bundled platform contracts bundle connectivity, edge hardware, and clinical software into subscription structures that lock in recurring revenue while obscuring component-level cost transparency.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates hospital procurement, with premium tiers commanding reliability guarantees for surgical-grade latency while economy tiers serve administrative traffic. Price differentiation hinges on FDA cybersecurity certification tier and geographic density of edge node deployment. Cost compression in standard tiers is intensifying because carrier-managed services compete with private network buildouts. Federally qualified health centers exhibit highest price sensitivity; tertiary academic medical centers prioritize reliability over unit cost.
Supply Chain Analysis
Returns and refurbishment flows for surgical robotics platforms and edge computing hardware are emerging as secondary supply channels, with reconditioned network equipment penetrating rural hospital budgets. Manufacturing concentrates in Taiwan for 5G modem chipsets, South Korea for memory components, and China for edge computing enclosures. Raw material dependencies span gallium nitride substrates, high-frequency laminates, and specialized medical-grade plastics. Single-source vulnerability in Taiwan foundry capacity threatens equipment lead times. Distribution runs through carrier-direct channels and systems integrators serving integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's evolving Software as a Medical Device premarket guidance functions as a regulatory compounder, accelerating hospital authorization timelines for connected diagnostic platforms and expanding addressable infrastructure spend.
For Market Incumbents: Hedge semiconductor supply concentration by diversifying foundry relationships across South Korea and domestic alternatives, insulating surgical equipment manufacturing from Taiwan Strait disruption. Fortify multi-year hospital partnerships through outcome-based contracting that ties infrastructure fees to CMS value-based care metrics, reducing churn risk from carrier price competition. For New Entrants and Emerging Players: Capture USDA rural development grant flows by positioning private 5G networks as fiber bypass solutions for federally qualified health centers in broadband-underserved counties. Penetrate the AI-at-the-edge convergence segment through radiology department partnerships, offering inference hardware that integrates with existing network slicing controllers without cloud dependency. For Investors and Strategic Acquirers: Valuations sit cheapest among regional hospital network infrastructure specialists with Open RAN deployment expertise but limited national scale. Long-term viability centers on regulatory pre-certification assets and exclusive spectrum licenses that compound competitive moats. Monitor FCC Citizens Broadband Radio Service auction mechanics as the critical inflection signal for hospital licensing cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Submission | Accelerates hospital system adoption through regulatory clarity on connected diagnostic cybersecurity. |
| Hospital System Partnership | Locks in multi-year infrastructure contracts with integrated delivery networks in California and Texas. |
| Private Network Deployment | Isolates surgical robotics traffic from administrative systems via dedicated spectrum licensing. |
| Software Companion Development | Enables real-time anomaly detection during imaging transfers through edge-native AI integration. |
| Reimbursement Strategy | Aligns remote patient monitoring platforms with CMS value-based care program incentives. |
Study Parameters
Coverage spans the United States, Germany, Japan, China, and South Korea, with primary inputs from each market through structured interviews with hospital procurement committees, biomedical engineers, GPO contracts managers, and telecommunications infrastructure specialists. Secondary validation draws from FDA premarket filings, FCC spectrum auction records, CMS Medicare reimbursement databases, and hospital capital expenditure disclosures. Bottom-up deployment modeling triangulates against top-down infrastructure investment forecasts.
Rate-of-change decomposition separates network slicing adoption velocity from edge computing hardware refresh cycles across the analysis window. Segmentation dimensions include service type, application criticality, technology architecture, and end-user scale tier. CAGRs derive from hospital capital allocation surveys and carrier infrastructure deployment pipelines, cross-referenced against regulatory authorization timelines for connected surgical platforms.
Semiconductor supply disruption, FCC spectrum licensing reform, and FDA cybersecurity guidance revision are the dominant revision risks to modeled forecasts. Practitioners should monitor foundry utilization rates, auction rulemaking dockets, and premarket submission trends for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Tablet PC Market
Others
HPHT Diamond Cubic Press Market
Others
5G Tester Market
Others
Blockchain in BFSI Market
Others
Receiving Scales Market
Others
UK Automotive LED Lighting Market
Others
Basketball Apparel Market
Others
Global Active Speaker Market
Others
Buchner Funnels Market
Others
UAE Location-Based Services Market
Others
Bakery Packaging Market
Others
Industrial Computers Market
Others
IT Device Market
Others
Caster Wheels Market
Others
Light Meter Market
Others
Global Essential Oils and Plant Extracts for Livestock Market