
 Global Thermally Conductive Grease Market | 2026-2036
Global Thermally Conductive Grease Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thermally Conductive Grease Market Foresight
The split between premium silicone-based formulations and commodity-grade alternatives is realigning procurement strategies across the thermal management supply chain. Dow leverages its integrated silicone feedstock position to sustain cost advantages in high-purity grades. Henkel AG & Co. KGaA differentiates through specialized epoxy-based products targeting power electronics. Shin-Etsu Chemical anchors Asian supply with dominant positions in both raw silicone and finished thermal compounds.
Thermally conductive grease comprises a viscous compound engineered with ceramic or metallic fillers dispersed in silicone, hydrocarbon, or epoxy carrier matrices, typically achieving thermal conductivity values from 0.5 to 6.0 W/m·K for interfacing heat-generating components with dissipating surfaces. Its primary commercial purpose is eliminating air gaps between irregular mating surfaces to minimize thermal resistance in electronic assemblies. Silicone-based products occupy the mature volume core, while non-silicone based formulations capture faster growth in applications demanding low-volatility and broader chemical compatibility. Power electronics and data centers represent the densest margin pools, with semiconductor manufacturers driving specification intensity upward.
REACH and RoHS frameworks in Europe restrict hazardous substance content and mandate material disclosure, while China's GB standards and NMPA-aligned environmental rules shape formulation requirements for imported and domestically produced greases. The US EPA and OSHA guidelines govern worker exposure limits during application and manufacturing processes. Stakeholders must monitor evolving thermal performance benchmarks against tightening chemical compliance thresholds to secure long-term product qualification.
Market Dynamics
Data center thermal loads are compressing specification cycles, forcing grease formulators to certify products against tighter conductivity and outgassing benchmarks before server OEMs refresh hardware platforms.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of high-GWP refrigerants in cooling systems elevates thermal interface materials as passive heat transfer solutions in precision climate control.
- Power electronics:Silicon carbide and gallium nitride switching frequencies generate localized heat fluxes that exceed legacy paste capabilities, pulling advanced silicone-ceramic compounds into traction inverters and charging infrastructure.
- China's domestic semiconductor fabrication:Foundry construction in Shanghai, Hefei, and Beijing concentrates procurement of high-purity, low-ionic thermal greases for wafer processing equipment.
Market Restraints
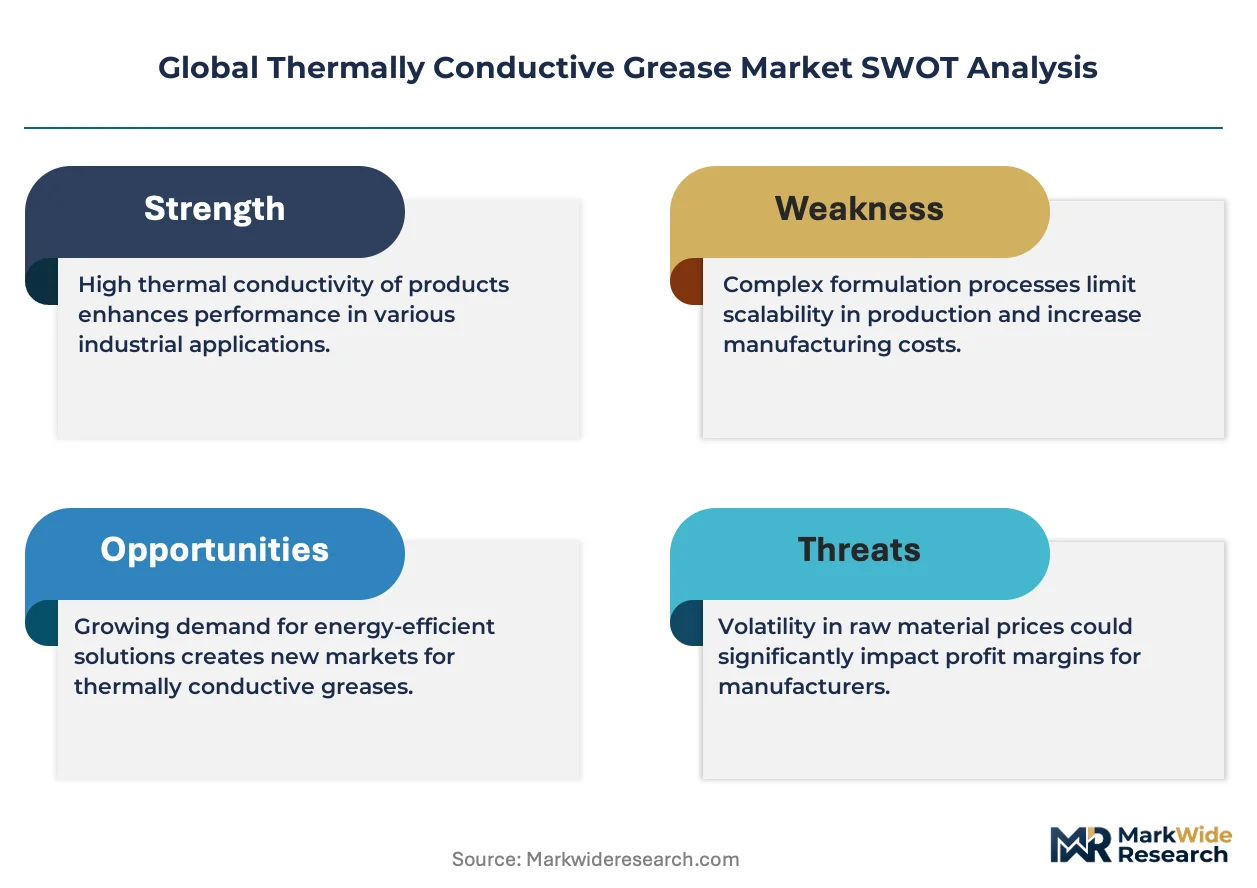
- Silver and boron nitride price volatility:Premium filler materials expose compounders to raw material swings that compress blended margins on fixed-price supply agreements.
- Shin-Etsu and Dow supply concentration:Asian and North American silicone feedstock control limits second-tier formulators' bargaining leverage on high-performance base polymers.
- REACH SVHC disclosure thresholds:Candidate list expansion forces reformulation of legacy products containing boric acid derivatives, extending qualification timelines by 12-18 months.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Subsidized fab and assembly investments in Gujarat and Tamil Nadu create first-mover advantage for grease suppliers establishing local blending operations.
- Two-phase immersion cooling convergence:Dielectric fluid bath systems paired with applied thermal interface layers open specification slots for chemically compatible, non-migrating compounds.
- Direct-to-factory digital distribution:E-procurement platforms serving EMS providers and contract manufacturers bypass traditional distributor markups on standard-grade formulations.
Industry Challenges
- Application engineering talent scarcity:Thin-film deposition expertise for high-volume electronics assembly commands premium compensation, constraining regional technical service expansion.
- Automotive AEC-Q100 and AEC-Q200 certification:Extended thermal cycling and humidity validation for electric powertrain applications stretches R&D calendars and capital equipment utilization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thermally Conductive Grease Market |
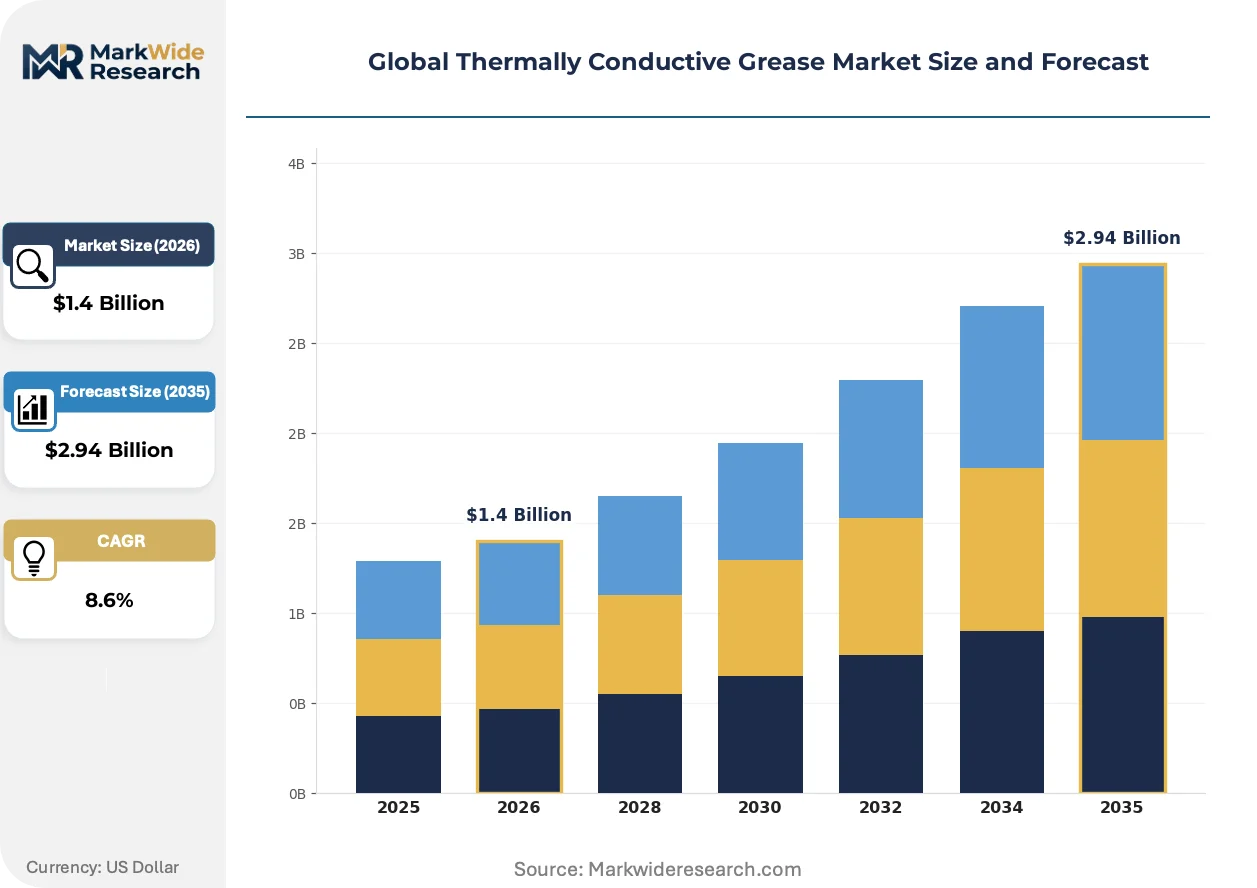
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Based, Non-Silicone Based, Epoxy Based, Acrylic Based Application: Power Electronics, LED Lighting, Telecom Equipment, Consumer Electronics, Industrial Machinery End User Industry: Semiconductor Manufacturers, Data Centers, Telecommunication Providers, Renewable Energy Firms Packaging Type: Tubes, Cartridges, Bulk Containers, Syringes |
| Companies Covered | Dow, 3M Company, Henkel AG & Co. KGaA, Momentive Performance Materials, Laird, Electrolube, Wacker Chemie AG, Parker-Hannifin Corporation, Shin-Etsu Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thermally Conductive Grease Market Shifts & Advancements
Formulation chemistry and application methods are diverging along performance-versus-cost axes, with premium segments absorbing advanced filler loadings while commodity tiers optimize for automated dispensing compatibility.
Hybrid boron nitride-aluminum oxide filler systems are overtaking single-ceramic architectures in data center CPU/GPU interfaces. Hyperscale operators specify these compounds for direct-die attachment in custom accelerator modules. The shift is overtaking legacy alumina-only formulations in procurement volumes above 50,000 kg annually.
REACH Annex XVII restrictions on microplastics and GB standards alignment in China are forcing disclosure of all polymeric additives above 0.1% concentration. Compounders must revalidate supply chains for silicone gum and thickener provenance. European automotive electronics suppliers face the steepest compliance burden, with some suspending legacy product lines pending reformulation.
Consolidated procurement by hyperscale data center operators concentrates annual grease volumes with fewer approved vendors. Tier-1 server OEMs now mandate single-source accountability for thermal performance warranties, displacing multi-supplier qualification practices. This concentration is most visible in Ashburn, Frankfurt, and Singapore metro clusters where co-location providers centralize buying decisions.
Global Thermally Conductive Grease Market Segmentation
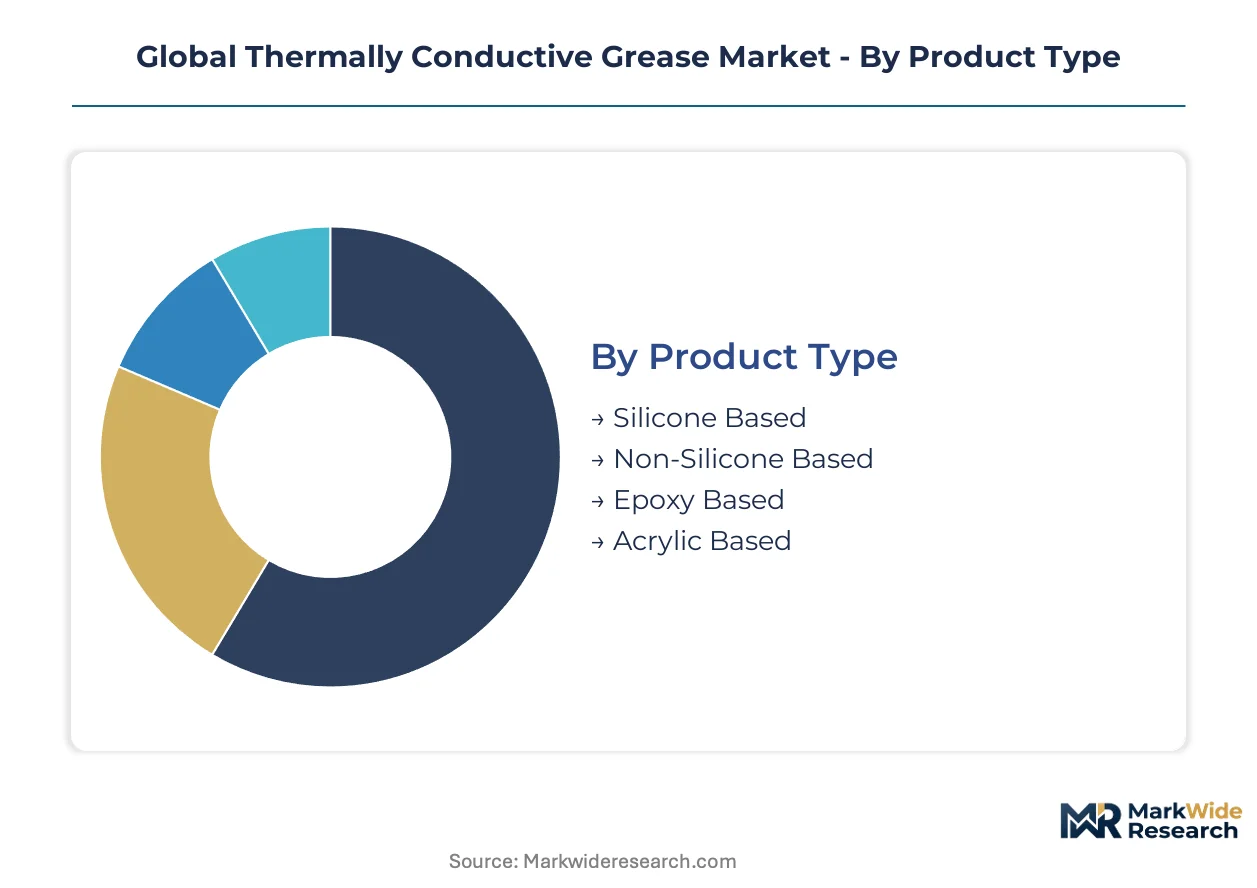
Thermally conductive grease procurement patterns diverge sharply between standalone aftermarket replenishment and embedded OEM specifications. Understanding these integration pathways clarifies why silicone formulations dominate volume while non-silicone alternatives command premium positioning in integrated electronics.
Product Type:
Standalone thermal greases service maintenance and upgrade cycles, while embedded formulations ship pre-applied at component manufacture.
- Silicone Based:Ceramic-filled polydimethylsiloxane matrices achieve 0.5–6.0 W/m·K conductivity across server CPU interfaces and automotive power modules. Data center operators in Ashburn and Frankfurt specify these compounds for direct-die attachment in custom accelerator hardware, though REACH SVHC disclosure thresholds force reformulation of legacy boric acid-containing variants.
- Non-Silicone Based:Hydrocarbon and synthetic ester carriers eliminate silicone outgassing risks in optical and hermetically sealed assemblies. China's domestic semiconductor fabrication in Shanghai and Hefei concentrates procurement of these low-ionic formulations for wafer processing equipment, driven by GB standards alignment and NMPA environmental rules.
- Epoxy Based:Thermally conductive adhesives with permanent bonding characteristics serve power electronics where mechanical fixation accompanies heat transfer.
- Acrylic Based:Lower-cost formulations target consumer electronics with moderate thermal loads and disposable product lifecycles.
Silicone based leads volumes today; non-silicone based is gaining share fastest.
Application:
Cost tier stratification separates mission-critical infrastructure from commodity consumer goods.
- Power Electronics:Silicon carbide and gallium nitride switching frequencies in traction inverters and charging infrastructure generate localized heat fluxes exceeding legacy paste capabilities. Advanced silicone-ceramic compounds with hybrid boron nitride-aluminum oxide fillers capture specification slots in EV powertrain programs subject to AEC-Q100 certification.
- LED Lighting:High-brightness COB arrays and horticultural fixtures demand thermally stable interfaces for 50,000-hour operational lifespans. Formulators optimize viscosity for automated dispensing on high-speed SMT lines serving contract manufacturers in Tamil Nadu and Gujarat.
- Telecom Equipment:5G base station amplifiers and massive MIMO radios require low-volatility compounds compatible with conformal coatings.
- Consumer Electronics:Gaming laptops and premium smartphones drive volume through thin-film application methods, though margin compression limits formulation innovation.
- Industrial Machinery:Variable frequency drives and motor controllers specify greases with extended temperature ranges and contamination resistance.
Power electronics commands premium pricing; LED lighting scales volume fastest.
End User Industry:
Customer type determines specification intensity, with semiconductor and data center buyers driving qualification standards downward through supply chains.
- Semiconductor Manufacturers:Foundry construction in Beijing, Shanghai, and Hefei concentrates procurement of high-purity, low-ionic thermal greases for etch chambers, deposition tools, and probe stations. These users mandate single-source accountability for thermal performance warranties, displacing multi-supplier qualification practices.
- Data Centers:Hyperscale operators in Singapore, Frankfurt, and Ashburn metro clusters consolidate annual grease volumes with fewer approved vendors. Direct-die attachment in custom accelerator modules specifies hybrid filler systems above 50,000 kg annually, overtaking legacy alumina-only formulations.
- Telecommunication Providers:Base station OEMs and network equipment suppliers prioritize supply security over thermal performance optimization.
- Renewable Energy Firms:Solar inverters and wind turbine power converters specify greases with 20-year service life projections and outdoor environmental stability.
Data centers lead procurement scale; semiconductor manufacturers drive specification intensity.
Packaging Type:
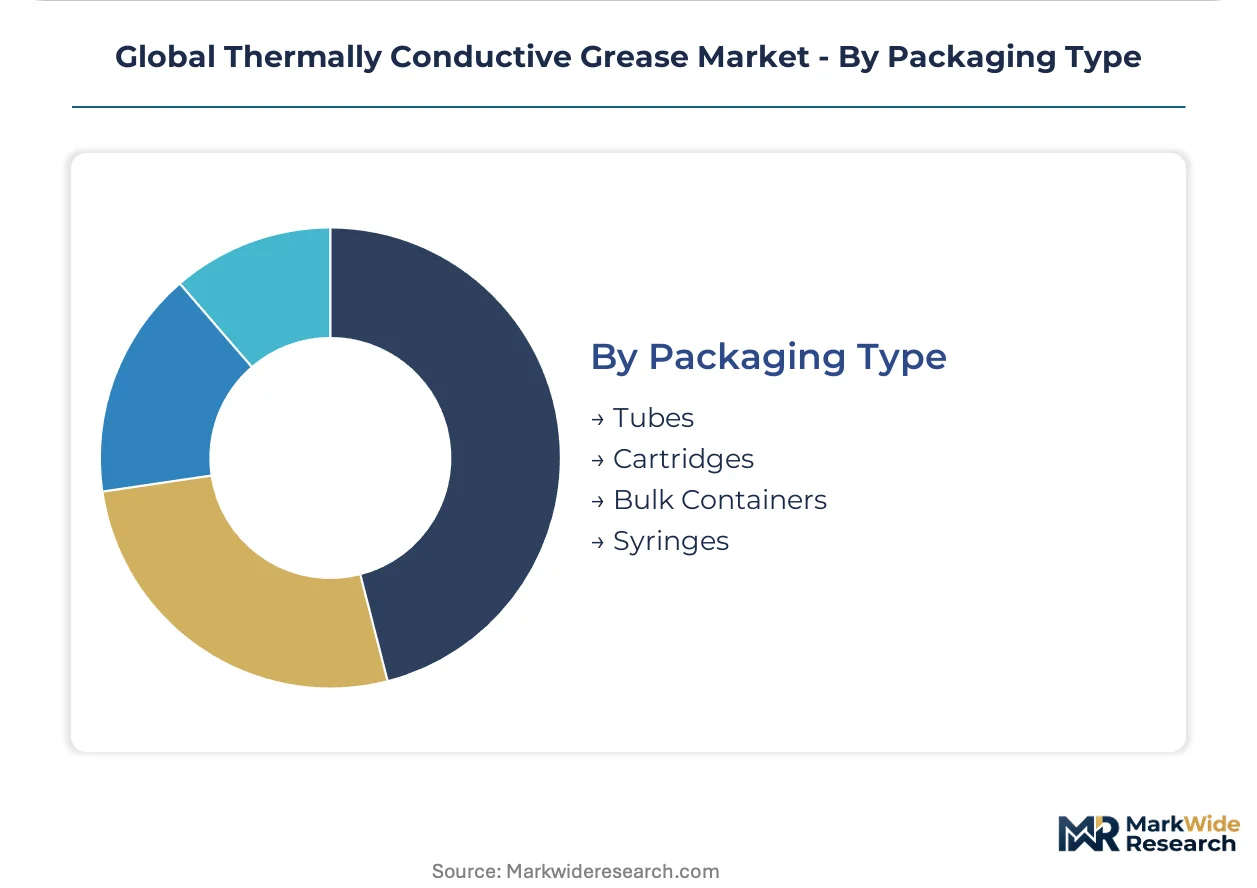
Volume and margin distribute unevenly across packaging formats, with automated assembly favoring precision-delivery systems.
- Syringes:Metered-dose dispensing enables controlled deposition on high-density PCB assemblies. EMS providers in India's PLI-subsidized electronics manufacturing zones specify syringe formats for SMT line integration, bypassing traditional distributor markups through direct-to-factory digital procurement platforms.
- Bulk Containers:Drum and pail formats serve high-volume thermal module manufacturers with in-house dispensing automation. These containers minimize per-gram packaging cost for compounders supplying server OEMs with annual volumes exceeding 100,000 kg.
- Tubes:Squeeze formats target aftermarket service technicians and low-volume maintenance operations.
- Cartridges:Caulk-gun compatible packaging serves industrial equipment installers and field service applications.
Bulk containers dominate OEM volume; syringes expand fastest in automated assembly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists and application engineers cluster around major semiconductor fabrication zones, with talent pools concentrated in East Asian manufacturing corridors and European automotive electronics belts.
United States
Hyperscale data center construction in Ashburn, Virginia and Hillsboro, Oregon drives procurement of hybrid boron nitride-aluminum oxide thermal compounds. EPA and OSHA guidelines govern worker exposure limits during grease application in electronics assembly. The Phoenix-Tucson corridor hosts expanding semiconductor foundry investments requiring high-purity, low-ionic thermal interface materials for wafer processing equipment.
China
Domestic semiconductor fabrication in Shanghai, Hefei, and Beijing concentrates consumption of silicone-based and non-silicone based formulations for etch chambers and deposition tools. GB standards alignment and NMPA environmental rules shape formulation requirements for imported and domestically produced greases. The Yangtze River Delta anchors the densest consumption cluster, with foundry construction accelerating qualification of advanced thermal compounds.
Germany
Automotive power electronics manufacturing for silicon carbide traction inverters pulls advanced silicone-ceramic compounds into EV supply chains. REACH and RoHS frameworks restrict hazardous substance content and mandate material disclosure across European supply chains. The Stuttgart-Munich corridor hosts concentrated R&D for AEC-Q100 certified thermal materials serving electric powertrain programs.
Japan
Raw silicone and finished thermal compound production anchors Asian supply security for high-performance base polymers. METI industrial policy supports domestic advanced materials capabilities in thermal management chemistry. The Nagoya-Osaka manufacturing belt concentrates precision electronics assembly requiring thin-film deposition expertise for high-volume thermal interface application.
India
PLI scheme subsidies for electronics manufacturing in Gujarat and Tamil Nadu create first-mover advantage for grease suppliers establishing local blending operations. BIS standards and CDSCO-aligned environmental rules shape import requirements for thermal interface materials. The Chennai-Bengaluru corridor hosts expanding EMS provider facilities specifying syringe-format compounds for SMT line integration.
Global Thermally Conductive Grease Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the thermal grease value chain, with integrated silicone feedstock operators holding structural advantages in high-purity grades while specialized compounders capture premium niches. The market structure tilts toward upstream concentration, where control of ceramic filler supply and silicone polymer synthesis determines cost position. Three archetypes dominate: integrated chemical conglomerates with captive silicone supply, specialized thermal materials formulators with application engineering depth, and regional blending operations serving price-sensitive assembly markets. Competitive moves center on backward integration into boron nitride and aluminum oxide filler sourcing, plus geographic expansion through local blending facilities in high-growth manufacturing zones.
Within the integrated chemical tier, Dow and Shin-Etsu Chemical exemplify upstream-controlled positioning through silicone feedstock dominance, while Henkel AG & Co. KGaA occupies the specialized formulator archetype with epoxy-based thermal material expertise. Among diversified industrial suppliers, 3M Company and Parker-Hannifin Corporation represent multi-technology portfolios where thermal greases sit within broader electronic materials or sealing solutions businesses. Momentive Performance Materials and Wacker Chemie AG anchor mid-scale positions with regional strength in silicone chemistry, while Electrolube and Laird exemplify focused thermal management specialists competing on application engineering and qualification speed rather than raw material integration.
| Leading Market Players |
|---|
| Dow |
| 3M Company |
| Henkel AG & Co. KGaA |
| Momentive Performance Materials |
| Laird |
| Electrolube |
| Wacker Chemie AG |
| Parker-Hannifin Corporation |
| Shin-Etsu Chemical |
| Others |
Supply & Pricing Matrix
REACH SVHC disclosure thresholds gate qualified supply and premium-tier pricing access by forcing reformulation of legacy boric acid-containing variants, extending qualification timelines and concentrating procurement with compounders who have already cleared compliance hurdles. Buyers seeking AEC-Q100 certified materials for EV powertrains face tightened vendor pools, while data center operators absorb cost premiums for hybrid boron nitride-aluminum oxide formulations that meet outgassing benchmarks.
Pricing Analysis
Bundled application engineering services separate premium compounders from commodity suppliers in this market. Three-tier pricing structure across premium, standard, and economy levels tracks certification intensity, with AEC-Q100 validated products commanding substantial premiums over uncertified alternatives. Cost compression in standard-grade silicone formulations is intensifying because India's PLI-subsidized electronics manufacturing zones are pulling volume toward localized blending operations. Contract manufacturers in Tamil Nadu and Gujarat exhibit the highest price sensitivity, while semiconductor foundries in Shanghai and Beijing prioritize thermal performance warranties over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and North American silicone feedstock control, which limits second-tier formulators' bargaining leverage on high-performance base polymers. Raw material sourcing draws from boron nitride deposits, aluminum oxide refineries, and polydimethylsiloxane polymerization capacity concentrated in Japan, China, and Germany. Commodity price volatility in silver and ceramic fillers exposes compounders to margin compression on fixed-price supply agreements. Distribution runs through authorized distributors serving EMS providers, with direct-to-factory digital procurement platforms gaining share in high-volume assembly zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder justified by the inexorable thermal load escalation in silicon carbide and gallium nitride power electronics, which sustains specification intensity and pricing power for qualified suppliers.
For Market Incumbents: Deploy captive silicone polymer supply to defend margin position against emerging regional blenders in India and Southeast Asia. Backward integration into boron nitride filler sourcing secures cost position for hybrid ceramic formulations, while accelerating REACH-compliant reformulation ahead of candidate list expansion protects qualification pipelines from 12-18 month delays.
For New Entrants and Emerging Players: Tier-2 automotive power electronics suppliers represent the most penetrable buyer archetype, as these users face AEC-Q100 certification burdens that incumbent compounders address slowly. Establishing local blending operations in Gujarat or Tamil Nadu under India's PLI scheme captures subsidized demand from EMS providers, with syringe-format packaging enabling SMT line integration as the primary go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for specialized thermal materials formulators because application engineering talent scarcity constrains organic expansion and creates acquisition premiums for qualified technical service teams. The long-term viability window favors platforms with REACH-compliant product portfolios and established foundry relationships. Watch for hyperscale data center procurement consolidation in Ashburn, Frankfurt, and Singapore as the signal indicating pricing power inflection toward approved vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Fillers | Captive boron nitride supply secures margin position against raw material volatility. |
| REACH-Compliant Reformulation Program | Eliminates SVHC exposure and accelerates qualification with European automotive electronics suppliers. |
| Local Blending Facility in India | PLI scheme subsidies in Gujarat and Tamil Nadu reduce landed cost for EMS provider contracts. |
| AEC-Q100 Certification Investment | Opens specification slots in silicon carbide traction inverter programs across EV supply chains. |
| Direct-to-Factory Digital Distribution | Bypasses distributor markups on standard-grade formulations for high-volume contract manufacturers. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with thermal materials R&D directors, procurement leads at server OEMs, plant managers at semiconductor foundries, and distribution channel partners informed demand-side assumptions. Secondary sources included customs and trade data, SEC filings from diversified chemical conglomerates, EPA and OSHA regulatory guidance documents, and ECHA REACH candidate list updates. Bottom-up volume estimates triangulated against top-down market sizing.
Granularity-level modeling tracked silicone-based, non-silicone based, epoxy based, and acrylic based product types across power electronics, LED lighting, telecom equipment, consumer electronics, and industrial machinery applications. End-user industry segmentation captured semiconductor manufacturers, data center operators, telecommunication providers, and renewable energy firms. CAGRs derived from segment-level growth drivers including foundry construction activity, hyperscale data center capex cycles, and EV powertrain adoption curves across the projection horizon.
Underlying measurement precision varies by segment; data center and semiconductor procurement volumes carry tighter precision than dispersed industrial machinery maintenance demand. Forecasts reflect assumptions about thermal load escalation in wide-bandgap semiconductors, REACH regulatory enforcement intensity, and PLI scheme subsidy continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
US Luxury Travel Market
Others
Electric Pallet Jack Truck Market
Others
Computer on Module Market
Others
Egg Market
Others
Connected Wearable Patches Market
Others
Global Mobile Video Optimization Market
Others
Smart Home Technologies Market
Others
Cremation Furnace Market
Others
Asia-Pacific Laser Hair Removal Market
Others
Folding Smartphone Market
Others
Asia-Pacific Camping and Caravanning Market
Others
India Smart Home Market
Others
Security Bottles Market
Others
Vegetable Carbon Market
Others
Lepidolite Market
Others
US Camping and Caravanning Market