
 Smart Trainers Market | 2026-2036
Smart Trainers Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Trainers Market Insights
Subscription-based leasing models for high-end smart trainer hardware are reshaping competitive access, lowering upfront barriers for boutique fitness studios and individual coaches. Wahoo Fitness leverages direct-to-consumer channel control to sustain premium positioning across North American and European markets. Garmin Ltd. anchors its position through deep integration with its proprietary ecosystem of wearables and navigation devices. Tacx N.V. specializes in electromagnetic resistance systems that dominate pro-cycling team procurement cycles.
Smart trainers are electromechanical cycling devices that simulate road conditions through variable resistance controlled by software algorithms, typically achieving power accuracy within one to two percent and supporting up to two thousand watts of simulated load. Their primary commercial purpose is enabling structured indoor training with real-time performance analytics for athletes and fitness operators. Wearable Devices and Performance Monitors command the strongest margin pools as consumers bundle head units with trainer purchases. Smart Shoes remains an emerging category where sensor miniaturization costs still outpace mass-market price tolerance. Mobile Apps integration generates recurring revenue that equipment-only sales cannot match.
FCC certification governs wireless connectivity compliance for units sold in the United States, while CE marking and GDPR obligations shape product architecture decisions for European market access. The EU AI Act introduces algorithmic transparency requirements that affect adaptive resistance and personalized coaching features. Stakeholders must decide whether to absorb compliance costs across all SKUs or regionalize firmware and data-processing architectures.
Market Dynamics
Electromagnetic resistance architectures are displacing fluid and wind-based systems as the dominant technical foundation, compressing manufacturing cost curves while elevating power accuracy benchmarks that professional cycling teams now mandate in procurement specifications.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for adaptive coaching features are accelerating on-device processing investments, creating technical differentiation for manufacturers with embedded AI capabilities.
- Indoor cycling studio proliferation:Boutique fitness operators in Germany are clustering connected training systems around Cologne and Stuttgart, generating concentrated demand for fleet-scale hardware procurement.
- Sensor miniaturization trajectories:MEMS power meters and integrated strain gauges are achieving cost parity with external crank-based systems, enabling native trainer-embedded measurement without third-party peripherals.
Market Restraints
- Rare earth magnet supply concentration:Neodymium procurement dependencies on Chinese processing facilities expose electromagnetic resistance manufacturers to input cost volatility and export control disruptions.
- GDPR data localization requirements:European cloud storage mandates for biometric performance data inflate operational overhead for subscription-based coaching platforms serving cross-border athlete populations.
- Direct drive mechanical complexity:Precision-machined flywheel assemblies and thermal management systems require specialized manufacturing capabilities concentrated among limited contract equipment suppliers.
Strategic Opportunities
- Subscription bundling models:Hardware-plus-software leasing structures are penetrating boutique fitness studios and individual coaching practices, converting capital expenditure into recurring revenue relationships.
- Wearable ecosystem convergence:Integration protocols linking smart trainers with head units and biometric sensors are creating platform stickiness that equipment-only competitors cannot replicate.
- Performance center certification standards:UCI-affiliated training facilities and national federation programs are mandating calibrated equipment specifications, generating institutional procurement pipelines for validated hardware systems.
Industry Challenges
- FCC certification timeline compression:Wireless connectivity modules for ANT+ and Bluetooth protocols require extended electromagnetic compatibility testing, delaying product launches for firmware-updated hardware variants.
- Embedded firmware security architecture:Resistance control algorithms and athlete performance databases require hardened attack surfaces against remote manipulation, demanding specialized cybersecurity talent scarce among traditional fitness equipment manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Trainers Market |
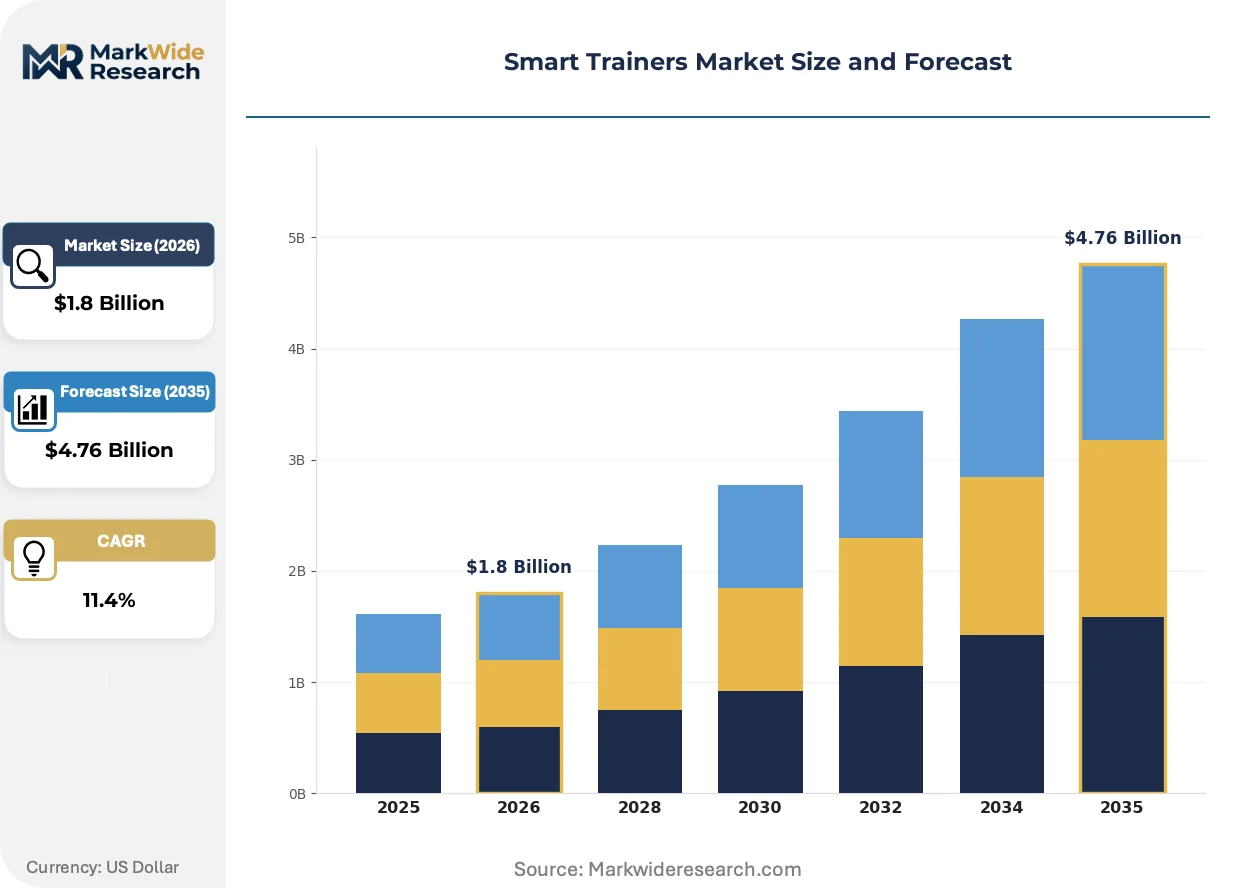
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Smart Shoes, Smart Clothing, Performance Monitors End User: Fitness Enthusiasts, Professional Athletes, Casual Users, Trainers Integration Level: Mobile Apps, Cloud Platforms, Fitness Equipment, Health Monitoring Systems Connectivity: Bluetooth, Wi-Fi, NFC, Zigbee |
| Companies Covered | Peloton Interactive, Inc., Wahoo Fitness, Garmin Ltd., Tacx N.V., Saris Cycling Group, Inc., Elite Srl, Kinetic by Kurt, Stages Cycling LLC, JetBlack Cycling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Trainers Market Trends and Innovations
Algorithmic personalization and edge computing architectures are redrawing competitive boundaries, separating manufacturers with integrated data-processing capabilities from hardware-only suppliers dependent on cloud-dependent software partnerships.
Electromagnetic resistance systems with eddy current braking are migrating from high-end professional equipment into mid-tier consumer hardware. Amateur cycling clubs and dedicated home trainers are adopting these systems at accelerating rates as price points compress toward eight hundred dollar thresholds. The technology shift is enabling power accuracy specifications previously reserved for laboratory ergometers to penetrate mass-market channels.
The EU AI Act introduces mandatory documentation requirements for automated decision-making systems that adjust resistance based on physiological feedback. Manufacturers must maintain algorithmic audit trails and explainability frameworks for adaptive coaching features. Smart trainer product lines with real-time biometric-responsive load modulation face the most acute compliance burdens in German and French market deployments.
Athlete purchasing behavior is fragmenting across direct-to-consumer and specialty retail channels with divergent service expectations. Online buyers demand seamless mobile app onboarding and remote firmware support, while brick-and-mortar purchasers prioritize in-store calibration services and hands-on resistance feel testing. This channel tension is most pronounced in North American markets where REI and independent bike shops maintain significant share against Amazon and manufacturer-direct platforms.
Smart Trainers Market Segmentation
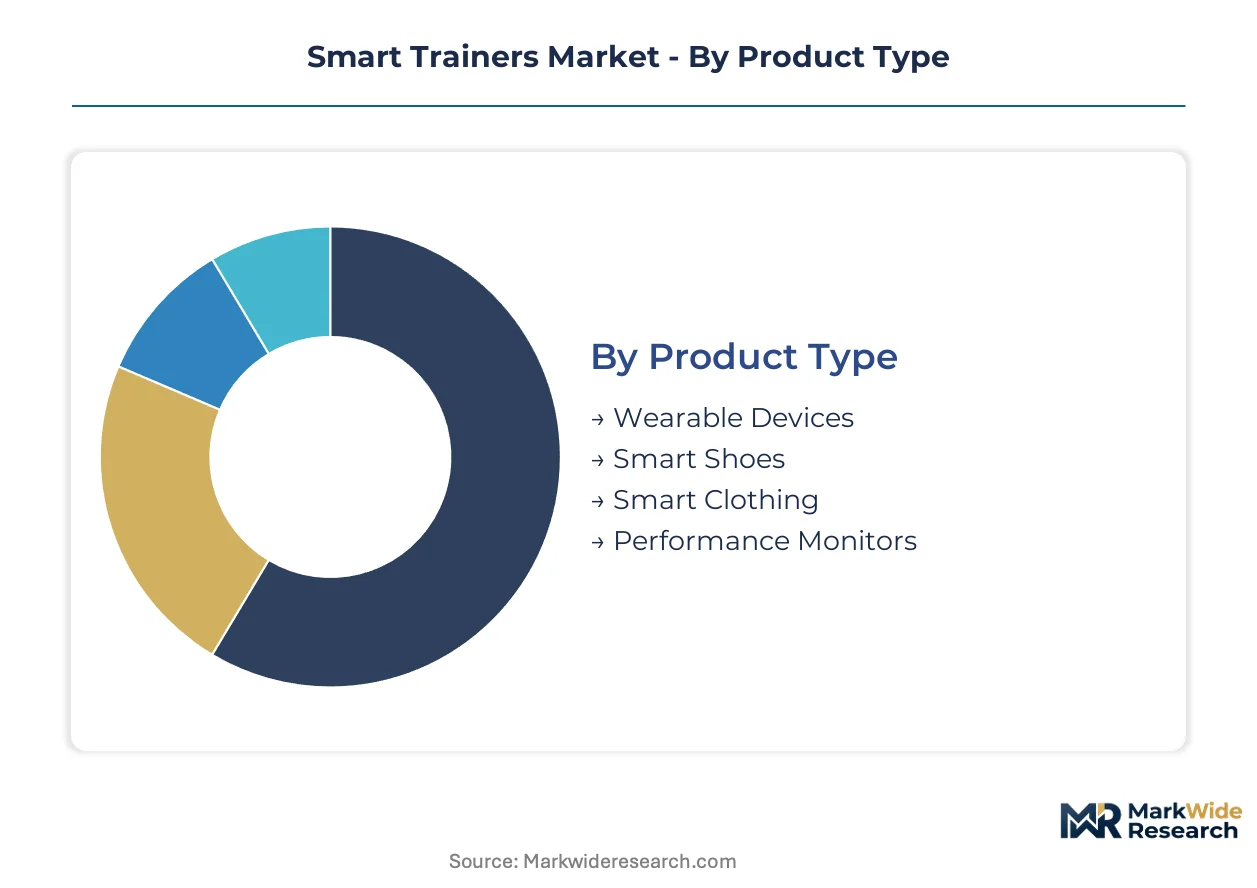
Smart trainer purchasing decisions fragment across hardware form factors, user sophistication levels, and ecosystem integration depth. Manufacturers must align R&D investment with the specific calibration, connectivity, and data-handling requirements that each segment demands.
Product Type:
After-sales service intensity varies dramatically across hardware categories, with embedded sensor systems requiring firmware support cycles that outlast mechanical trainer components by years.
- Wearable Devices:Head units and biometric bands pair with trainer hardware to deliver real-time power, cadence, and heart rate visualization. Demand concentrates in Germany's indoor cycling studio clusters around Cologne and Stuttgart, where fleet operators bundle wearable purchases with electromagnetic resistance system procurement.
- Performance Monitors:Integrated strain gauge and MEMS power meter architectures achieve native trainer-embedded measurement without third-party peripherals. These systems command the strongest margin pools as consumers bundle measurement hardware with trainer purchases, particularly among professional cycling teams mandating laboratory-grade accuracy specifications.
- Smart Shoes:Sensor miniaturization costs still outpace mass-market price tolerance, constraining adoption to early adopter triathletes and biomechanics researchers.
- Smart Clothing:Textile-integrated electromyography and motion capture remain pre-commercial, with pilot deployments limited to national federation training centers.
Wearable Devices holds the largest share; momentum sits with Performance Monitors.
End User:
Cost tier stratification separates capital-intensive fleet procurement from individual consumer purchases, with professional segments absorbing premium pricing for validated calibration protocols.
- Professional Athletes:UCI-affiliated training facilities and national federation programs mandate calibrated equipment specifications, generating institutional procurement pipelines for hardware systems with documented power accuracy within one to two percent.
- Fitness Enthusiasts:Dedicated home trainers drive volume adoption of mid-tier electromagnetic resistance systems as price points compress toward accessible thresholds, particularly in North American direct-to-consumer channels.
- Trainers:Individual coaching practices favor subscription-based leasing models that convert capital expenditure into recurring revenue relationships with hardware-plus-software bundles.
- Casual Users:Price sensitivity and limited feature utilization restrict this segment to entry-level fluid resistance systems and secondhand equipment markets.
Professional Athletes represents the fastest-growing trajectory; Fitness Enthusiasts maintains volume leadership.
Integration Level:
Application architecture determines recurring revenue potential, with cloud-dependent platforms facing GDPR data localization burdens that on-device processing architectures avoid.
- Mobile Apps:Integration generates recurring revenue that equipment-only sales cannot match, with online buyers demanding seamless onboarding and remote firmware support across direct-to-consumer channels.
- Cloud Platforms:European storage mandates for biometric performance data inflate operational overhead for subscription-based coaching platforms serving cross-border athlete populations.
- Fitness Equipment:Proprietary ecosystem integration—exemplified by wearable-to-trainer protocols—creates platform stickiness that equipment-only competitors cannot replicate.
- Health Monitoring Systems:Hospital and clinical rehabilitation programs require HIPAA-compliant data architectures that few fitness-native manufacturers have implemented.
Mobile Apps holds the largest share; momentum sits with Fitness Equipment.
Connectivity:
Supply concentration in wireless module manufacturing creates certification bottlenecks that delay product launches for firmware-updated hardware variants.
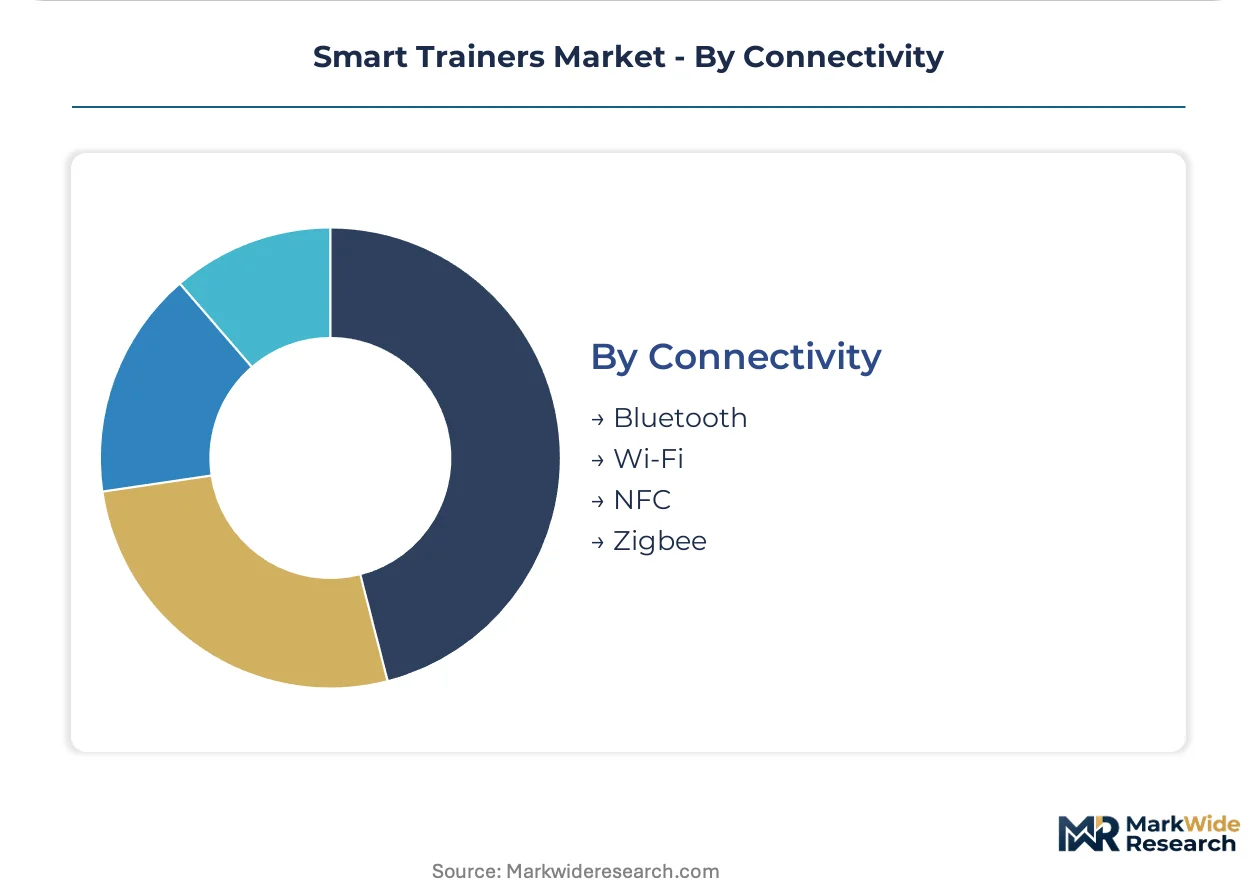
- Bluetooth:FCC certification governs wireless connectivity compliance for units sold in the United States, with electromagnetic compatibility testing extending timelines for protocol-updated trainer generations.
- Wi-Fi:Firmware security architecture for resistance control algorithms demands hardened attack surfaces against remote manipulation, requiring specialized cybersecurity talent scarce among traditional fitness equipment manufacturers.
- ANT+:Proprietary protocol dominance in cycling-specific sensor networks maintains installed base loyalty despite Bluetooth Low Energy encroachment.
- Zigbee:Mesh networking capabilities attract smart home integration scenarios, though fitness applications remain marginal.
- NFC:Tap-to-pair convenience features target boutique studio fleet management, reducing onboarding friction for rotating equipment assignments.
Bluetooth holds the largest share; momentum sits with Wi-Fi.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for neodymium magnets and electromagnetic components tilts the trade balance toward Asian manufacturing centers, while European and North American markets absorb finished hardware through direct-to-consumer channels and boutique studio procurement.
Germany
Indoor cycling studios cluster around Cologne and Stuttgart, driving fleet-scale procurement of electromagnetic resistance systems. The EU AI Act mandates algorithmic transparency for adaptive coaching features, compelling manufacturers to implement on-device processing architectures. Baden-Württemberg's precision engineering ecosystem supplies specialized flywheel machining capabilities to domestic and export markets.
United States
FCC certification timelines for ANT+ and Bluetooth wireless modules delay product launches for firmware-updated trainer generations. Direct-to-consumer channel control sustains premium positioning among fitness enthusiasts and professional coaching programs. The Pacific Northwest and Colorado Front Range host dense concentrations of endurance athletes driving high-end hardware adoption.
China
Rare earth magnet processing concentration exposes electromagnetic resistance manufacturers to input cost volatility and export control disruptions. GB standards and MIIT regulations govern wireless connectivity compliance for domestic market access. The Yangtze River Delta houses contract equipment suppliers specializing in precision-machined flywheel assemblies.
Netherlands
Tacx N.V. anchors domestic electromagnetic resistance system production serving pro-cycling team procurement cycles. GDPR data localization requirements inflate operational overhead for subscription-based coaching platforms serving cross-border athlete populations. The Randstad region concentrates R&D talent for embedded firmware security architecture development.
United Kingdom
Post-Brexit regulatory divergence complicates CE marking alignment for hardware exported to EU markets. London and Southeast England host boutique fitness operators adopting subscription-based leasing models for high-end smart trainer hardware. The country's national data protection regulator enforces biometric performance data storage mandates affecting cloud platform architectures.
Smart Trainers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying resistance modules, sensor arrays, and wireless connectivity subsystems. The vendor base stratifies across three tiers: full-stack ecosystem owners, hardware-focused specialists with proprietary electromagnetic architectures, and contract manufacturers serving white-label channels. Consolidation pressure concentrates among mid-tier players lacking integrated software capabilities. Dominant competitive moves include ecosystem lock-in through wearable-to-trainer integration protocols and geographic expansion via regional certification partnerships.
Within the full-stack ecosystem tier, Garmin Ltd. and Wahoo Fitness exemplify platform integrators leveraging proprietary device networks to create switching costs. Tacx N.V. occupies a position among electromagnetic resistance specialists serving validated procurement pipelines. Peloton Interactive, Inc. represents the content-anchored archetype where hardware margins subsidize recurring subscription revenue. These three companies illustrate the strategic divergence between equipment-only positioning and integrated hardware-software-service architectures reshaping competitive boundaries.
| Leading Market Players |
|---|
| Peloton Interactive, Inc. |
| Wahoo Fitness |
| Garmin Ltd. |
| Tacx N.V. |
| Saris Cycling Group, Inc. |
| Elite Srl |
| Kinetic by Kurt |
| Stages Cycling LLC |
| JetBlack Cycling |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in precision-machined flywheel manufacturing across Baden-Württemberg's supplier base drives both procurement urgency among electromagnetic resistance system producers and pricing leverage for contract equipment specialists with captive thermal management capabilities.
Pricing Analysis
Professional cycling teams and triathlon coaching programs anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on power accuracy certification grade and bundled after-sales calibration protocols. Cost compression in mid-tier electromagnetic systems is intensifying because MEMS sensor integration is eliminating third-party peripheral dependencies. Boutique fitness studios exhibit the highest price sensitivity due to fleet-scale capital constraints, while UCI-affiliated training facilities absorb premium positioning for validated laboratory-grade specifications.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for neodymium magnet procurement. Rare earth processing concentrates in China, with secondary refining capabilities in Malaysia and limited Western alternatives in Australia. Component dependencies span precision-machined flywheel assemblies, eddy current braking modules, and ANT+/Bluetooth wireless chipsets. Single-source vulnerability in neodymium extraction feeds into input cost volatility. Distribution runs through direct-to-consumer platforms and specialty cycling retail channels with divergent service bundling expectations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart trainers market functions as a defensive-moat arena where ecosystem lock-in through wearable-to-trainer integration protocols creates switching costs that hardware-only competitors cannot replicate.
For Market Incumbents: Build data-sovereignty moats through on-device processing architectures that satisfy GDPR and EU AI Act compliance without cloud dependency. Deepen backward integration into electromagnetic resistance module production to offset rare earth magnet supply volatility. Threaten margin compression from white-label contract manufacturers in China's Yangtze River Delta demands preemptive certification investment in FCC and CE marking pathways. For New Entrants and Emerging Players: Southeast Asian boutique fitness markets present the most penetrable white-space for subscription-based hardware-plus-software leasing models. Biomechanics researchers and early adopter triathletes offer entry points in the sensor-embedded Smart Shoes category where miniaturization costs still exclude mass-market incumbents. A go-to-market angle anchored in NFC-enabled tap-to-pair fleet management targets studio operators with rotating equipment assignments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among full-stack ecosystem owners with proprietary wearable-to-trainer integration protocols. Long-term viability over a multi-year horizon favors acquisition targets with embedded firmware security capabilities and validated procurement relationships with UCI-affiliated facilities. Watch for inflection signals in electromagnetic resistance patent filing velocity from precision engineering clusters around Stuttgart.| Strategic Initiative | Industry Significance |
|---|---|
| On-Device AI Processing Migration | EU AI Act compliance enables algorithmic transparency without cloud storage overhead. |
| Electromagnetic Resistance Module Backward Integration | Captive neodymium magnet sourcing mitigates Chinese export control exposure. |
| Subscription Bundling Model Expansion | Hardware-plus-software leasing converts capital expenditure into recurring revenue relationships. |
| Wearable Ecosystem Protocol Lock-In | Head unit and biometric sensor integration creates platform stickiness against hardware-only rivals. |
| Performance Center Certification Pipeline | UCI-affiliated facility validation mandates generate institutional procurement with premium pricing tolerance. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FCC equipment authorization databases, EU CE marking registries, and electromagnetic compatibility test reports. Stakeholder interviews span smart trainer product managers at full-stack ecosystem owners, procurement leads at professional cycling teams, firmware security architects at electromagnetic resistance specialists, and fleet operators at German indoor cycling studios. Secondary validation draws from UCI equipment specification documents, GDPR enforcement actions by European data protection authorities, and rare earth trade flow data. Bottom-up unit economics triangulate against top-down market sizing across hardware form factors and integration levels.
Forecast inputs incorporate electromagnetic resistance technology adoption curves, MEMS sensor cost trajectories, and regulatory compliance burden shifts across the projection horizon. Segmentation dimensions span product type, end user sophistication tier, integration architecture depth, and connectivity protocol. CAGRs derive from fitted growth curves calibrated to observed procurement patterns among professional athletes and boutique fitness operators. Industry-specific inputs include indoor cycling studio proliferation rates in German urban clusters and FCC certification timeline distributions for wireless module updates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated technology conglomerates entering from adjacent wearable markets would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
Stadium and Arena Management Solution Market
Sports & Fitness Technology
UK Sports Promoters Market
Sports & Fitness Technology
Crossfit Apparel Market
Sports & Fitness Technology
Smart Fitness Device Market
Sports & Fitness Technology
Europe Sports Promoter Market
Sports & Fitness Technology
UK Sports Team and Clubs Market
Sports & Fitness Technology
UK Spectator Sports Market
Sports & Fitness Technology
Smart Stadium Market
Sports & Fitness Technology
Asia-Pacific Sports Management Software Market
Sports & Fitness Technology
Smart Swimming Caps Market
Sports & Fitness Technology
Sports App Market
Sports & Fitness Technology
Smart Sports Market
Sports & Fitness Technology
Europe Sports Team and Clubs Market
Sports & Fitness Technology
Sports Sponsorship Market
Sports & Fitness Technology
Asia Pacific Sports Team and Clubs Market
Sports & Fitness Technology
Europe Spectator Sports Market