
 Smart Battery Market | 2026-2036
Smart Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Battery Market Intelligence
The substitution of cobalt with high-nickel or cobalt-free cathodes in lithium-ion batteries is recalibrating cost structures and supply chain ethics for manufacturers. Cadex Electronics specializes in battery testing and diagnostic systems, providing critical tools for lifecycle management. Inspired Energy focuses on custom smart battery packs for medical and industrial devices, while Trojan Battery leverages its legacy in deep-cycle batteries to compete in industrial motive power applications.
A smart battery integrates a battery pack with an onboard electronic circuit, known as a Battery Management System (BMS). This system monitors critical parameters like voltage, current, and temperature to calculate the state of charge and state of health, communicating this data to the host device. Lithium-ion chemistries dominate the product landscape due to their high energy density. The electric vehicle application segment represents the fastest-growing source of demand, followed by consumer electronics where battery safety is a key differentiator.
Market access is shaped by stringent safety and environmental regulations, including the EU's Battery Regulation mandating carbon footprint declarations. In parallel, standards from the US EPA and China's MEE govern battery recycling and end-of-life management, influencing design choices. Stakeholder success will depend on navigating these evolving compliance landscapes while investing in BMS software that optimizes for both performance and circular economy principles.
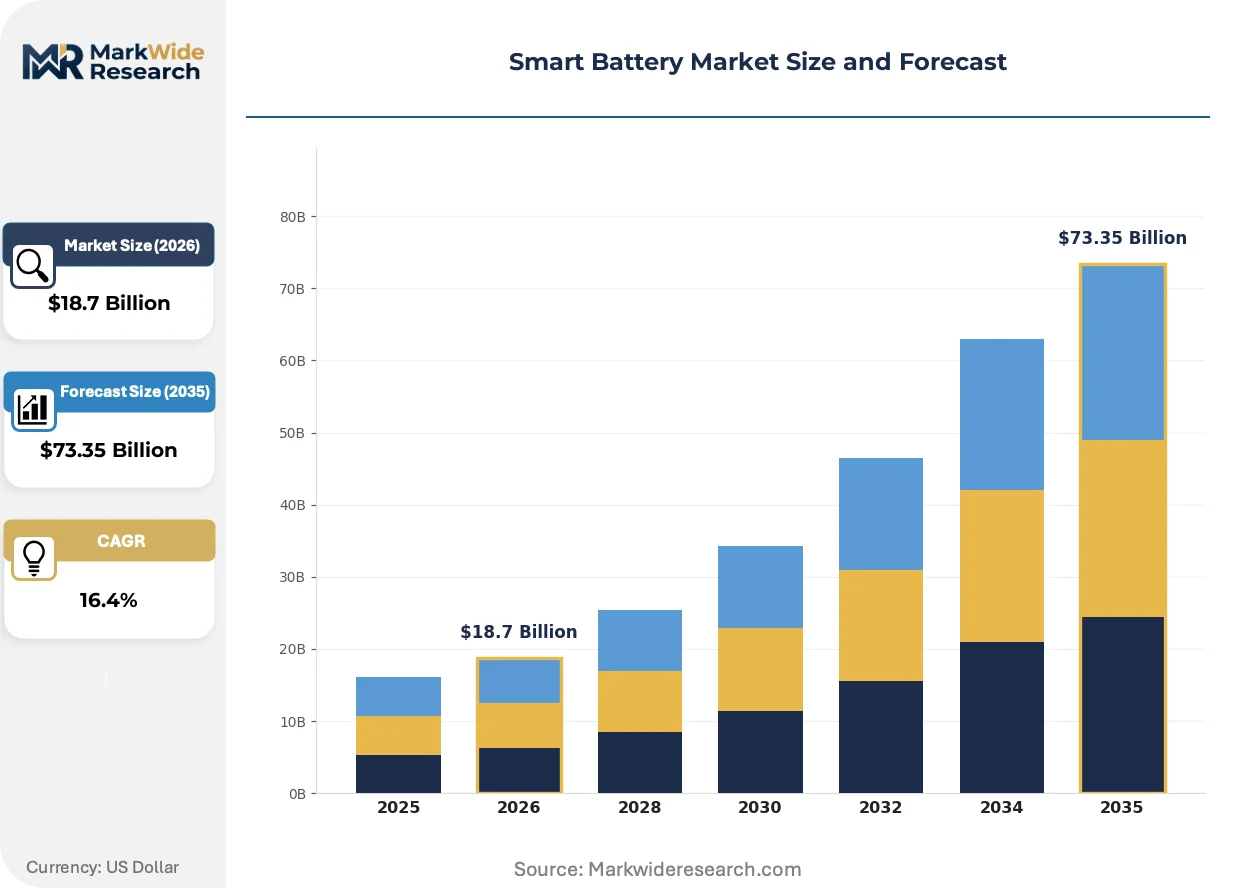
Market Dynamics
The central force shaping the smart battery market is a global regulatory push for lifecycle transparency. Mandates like the EU's Battery Regulation compel manufacturers to embed intelligence into battery packs, transforming them from passive components into data-generating assets.
Growth Catalysts
- Electric Vehicle Adoption:The automotive sector's transition to electric mobility requires sophisticated battery monitoring to maximize range, ensure safety, and manage charging, driving demand for integrated Battery Management Systems.
- Regulatory Mandates:The EU Battery Regulation, with its digital passport requirement, is forcing the integration of advanced monitoring, creating a compliance-driven market for smart battery technology across multiple industries.
- Concentrated Electronics Demand:China's role as a global hub for consumer electronics and electric vehicle assembly creates a massive, concentrated source of demand for smart batteries and their associated components.
Market Restraints
- Cathode Chemistry Volatility:The shift away from cobalt to high-nickel or cobalt-free cathodes, while ethically and strategically beneficial, introduces new material cost uncertainties and technical challenges for battery manufacturers.
- Supply Chain Concentration:Heavy reliance on a few geographies, particularly China, for the processing of critical raw materials and the manufacturing of battery cells creates significant geopolitical and logistical risks for the global market.
- Technical Trade-Offs:A persistent technical restraint involves balancing energy density, charging speed, cycle life, and safety, as improvements in one area often compromise another, slowing the deployment of next-generation chemistries.
Strategic Opportunities
- Second-Life Applications:The data provided by smart batteries enables accurate state-of-health assessments, creating a significant market for repurposing used EV batteries for less demanding applications like stationary energy storage.
- Advanced BMS Software:Developing AI-powered BMS software that offers predictive analytics for battery health and performance optimization presents a high-margin opportunity beyond the hardware itself, enabling new service-based business models.
- Industrial IoT Integration:The expansion of smart batteries into industrial motive power and medical devices, where reliability and remote monitoring are critical, opens new, high-value application segments beyond consumer-facing products.
Industry Challenges
- Regulatory Fragmentation:Manufacturers face the operational challenge of designing products that comply with a patchwork of different environmental and safety standards, such as those from the EU, the US EPA, and China's MEE.
- Protocol Standardization:A lack of universal standards for communication between the BMS, the host device, and charging infrastructure creates integration complexity and limits interoperability, acting as a friction point for OEMs.
- Talent Acquisition:A shortage of engineers with dual expertise in battery chemistry and sophisticated software development for BMS creates a significant bottleneck for innovation and product development across the industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Battery Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Nickel-Metal Hydride, Lead-Acid, Solid-State, Lithium-Polymer Application: Consumer Electronics, Electric Vehicles, Renewable Energy Storage, Telecommunications, Aerospace Technology: Battery Management System, Wireless Charging, Fast Charging, Battery Monitoring, Energy Harvesting End User: Electronics Manufacturers, Vehicle Assemblers, Power Utilities, Network Operators, Defense Contractors |
| Companies Covered | Trojan Battery, Cadex Electronics, Accutronics, Battery Smart, Sealed Energy Systems, Epec, Rose Batteries, Inspired Energy, Cell-Con, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Battery Market Strategic Shifts & Innovations
Intelligence and data are re-architecting the value proposition of batteries. The market is shifting from a hardware-centric view to a software-defined perspective where performance, safety, and lifecycle management are monetized through embedded electronics.
An integrated Battery Management System (BMS) provides critical monitoring and control of battery performance. Adoption is accelerating across electric vehicle and energy storage sectors where reliability is paramount. This integration of advanced software with hardware is unifying individual cells and sensors into a cohesive, intelligent energy asset.
The European Union’s Battery Regulation establishes requirements for a digital battery passport. This policy compels manufacturers to provide extensive data on carbon footprint, material sourcing, and recycling information. Automotive and industrial battery segments are most impacted, accelerating investment in secure, lifecycle-aware BMS architectures to ensure compliance.
End-user focus is shifting from upfront battery cost to predictable lifecycle performance and total cost of ownership. This change disrupts traditional component sales channels, favoring service-oriented models that guarantee battery health and uptime. The trend is most pronounced in commercial EV fleet management and utility-scale energy storage.
Smart Battery Market Segmentation
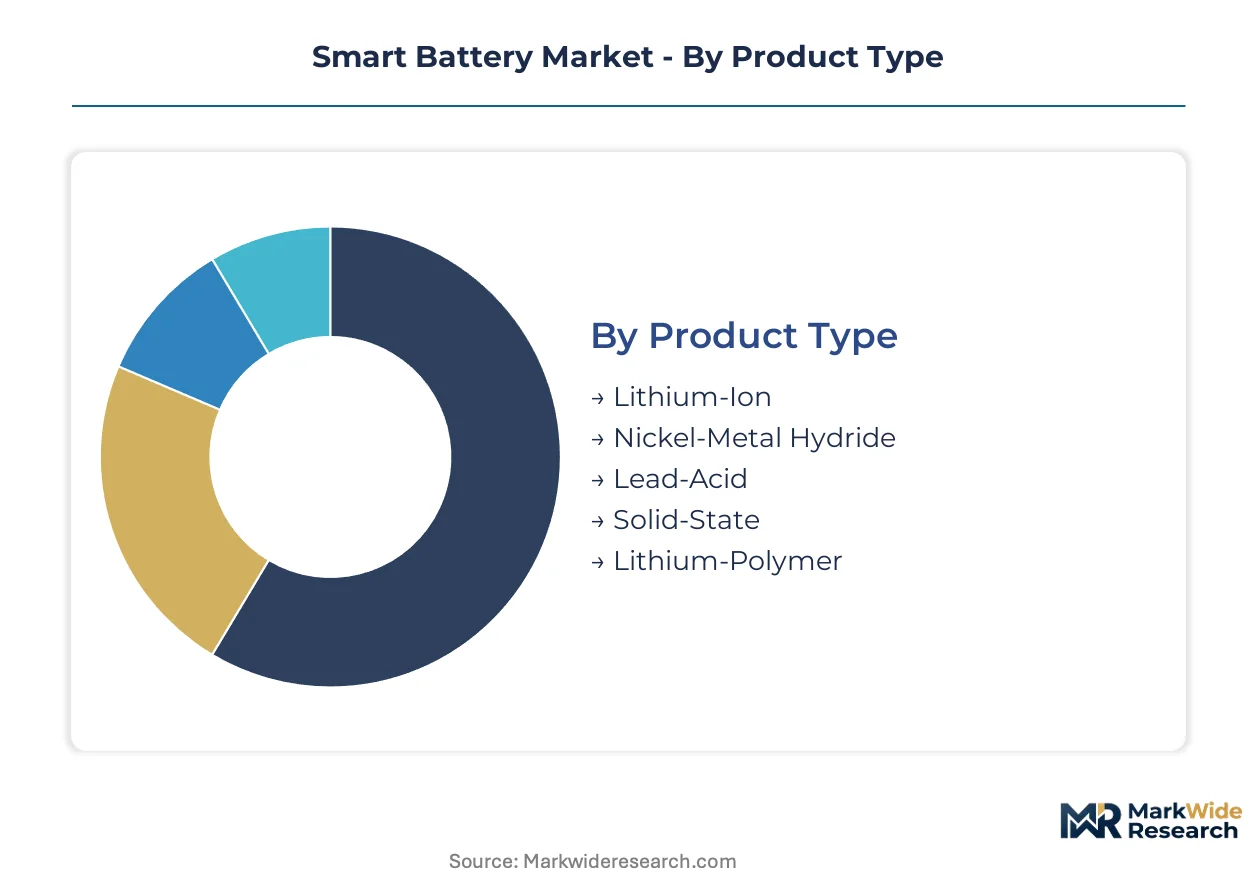
Smart batteries integrate electronic intelligence, making segmentation crucial for understanding varied performance needs and compliance requirements. This analysis dissects the market by product type, application, technology, and end-user, revealing distinct value propositions and growth vectors across the ecosystem.
Product Type:
Buyers in the smart battery market are differentiated by their specific energy density, cycle life, and safety requirements, which directly influence their choice of battery chemistry.
- Lithium-Ion:These batteries offer high energy density and a long cycle life, making them suitable for demanding applications. Demand concentrates in electric vehicles and consumer electronics due to their performance characteristics.
- Solid-State:Solid-state batteries utilize solid electrolytes, promising enhanced safety and higher energy density compared to liquid-electrolyte counterparts. Development is accelerating, driven by automotive manufacturers seeking next-generation EV power solutions.
- Nickel-Metal Hydride:These batteries provide a reliable and mature technology, often used in hybrid electric vehicles and medical devices.
- Lead-Acid:Lead-acid batteries remain a cost-effective solution for stationary backup power and industrial motive applications, offering robust performance.
- Lithium-Polymer:These batteries feature a flexible form factor and high energy density, primarily serving compact consumer electronics and wearables.
Volume sits with Lithium-Ion; growth tilts toward Solid-State.
Application:
The application segment defines the operating environment and performance expectations, influencing design and regulatory compliance for smart battery solutions.
- Electric Vehicles:Smart batteries in electric vehicles require high energy density, rapid charging capabilities, and advanced thermal management for safety. This application represents the fastest-growing source of demand globally, driven by decarbonization mandates.
- Consumer Electronics:Smart batteries for consumer electronics prioritize compact size, safety features, and extended battery life for portable devices. Demand is concentrated in China, reflecting its dominance in electronics assembly.
- Renewable Energy Storage:These applications use smart batteries for grid stabilization and efficient energy management from intermittent sources like solar and wind.
- Telecommunications:Smart batteries provide reliable backup power for critical network infrastructure, ensuring continuous operation during outages.
- Aerospace:Smart batteries in aerospace applications demand extreme reliability, lightweight design, and performance under harsh environmental conditions for avionics.
Demand for Electric Vehicles expands most quickly, while Consumer Electronics maintains significant market share.
Technology:
Technology choices determine the intelligence and functionality embedded within smart batteries, directly impacting their monitoring and communication capabilities.
- Battery Management System (BMS):BMS technology is fundamental to smart batteries, monitoring voltage, current, and temperature to optimize performance and safety. Regulatory mandates like the EU Battery Regulation drive its advanced integration across all segments.
- Battery Monitoring:Battery monitoring encompasses sensors and algorithms that track state of charge and state of health, crucial for predictive maintenance and second-life applications. This technology enables efficient lifecycle management for industrial and automotive batteries.
- Wireless Charging:This technology enables convenient and contact-free power transfer, gaining traction in consumer devices and potentially electric vehicles.
- Fast Charging:Fast charging technologies reduce charging times significantly, enhancing user convenience for electric vehicles and portable electronics.
- Energy Harvesting:Energy harvesting converts ambient energy sources like vibration or light into electrical power, extending battery life in low-power IoT devices.
BMS solutions command the largest share, with Battery Monitoring showing significant momentum.
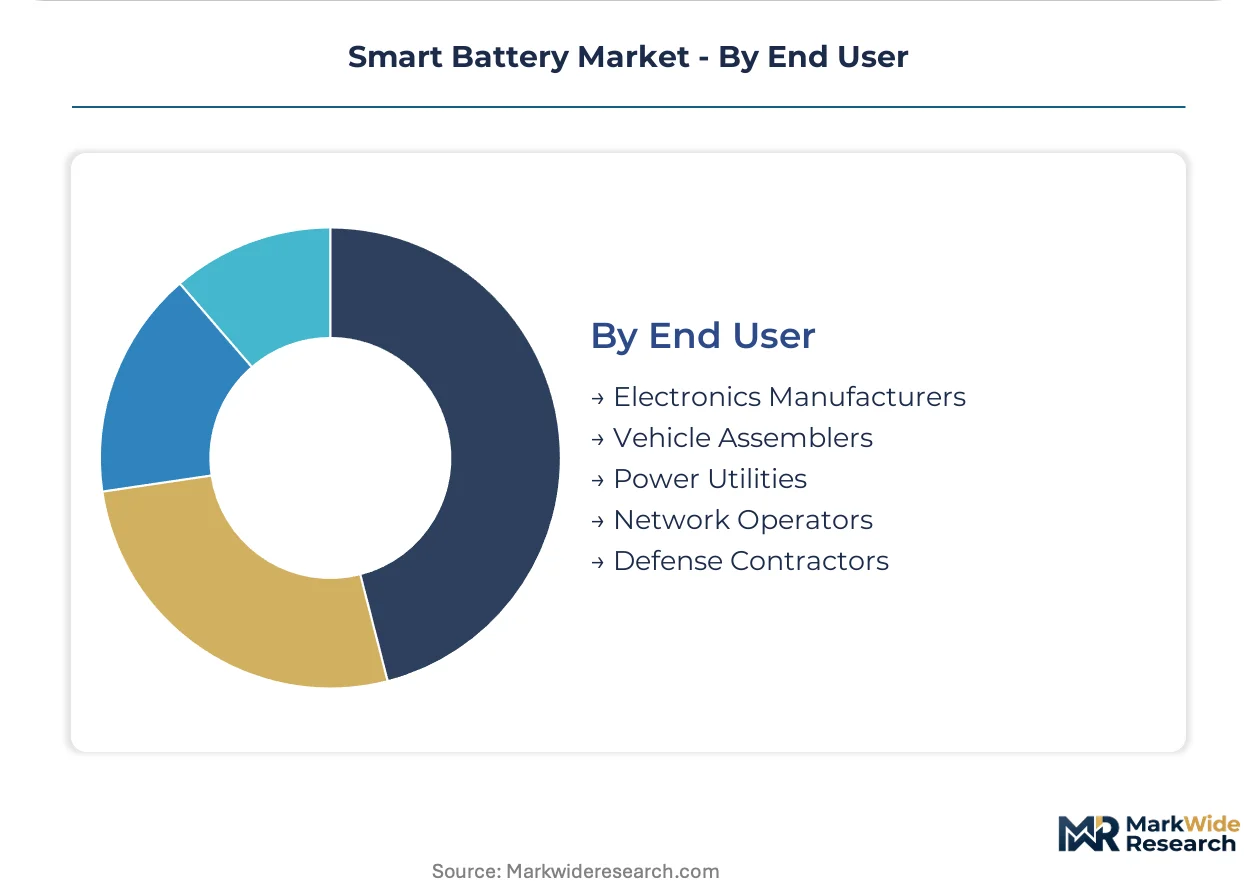
End User:
End users represent the ultimate beneficiaries and integrators of smart battery technology, with their specific industry requirements shaping product development.
- Vehicle Assemblers:Vehicle assemblers integrate smart batteries into electric cars, trucks, and buses, demanding high-performance, safe, and long-lasting power solutions. They are heavily influenced by global automotive safety standards and range requirements.
- Electronics Manufacturers:Electronics manufacturers incorporate smart batteries into smartphones, laptops, and wearables, prioritizing compact size, safety, and cost-efficiency. Their demand is concentrated in Asia, particularly China, for mass production.
- Power Utilities:Power utilities deploy smart batteries for grid-scale energy storage, requiring robust systems for load balancing and renewable energy integration.
- Network Operators:These operators utilize smart batteries for uninterrupted power supply in telecommunication base stations and data centers, ensuring network reliability.
- Defense Contractors:Defense contractors procure highly specialized smart batteries for military equipment, emphasizing extreme durability, security, and performance in harsh environments.
Vehicle Assemblers are driving the steepest expansion trajectory, while Electronics Manufacturers represent the largest volume segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for smart batteries is particularly evident in key manufacturing hubs, reflecting the intense need for advanced power solutions. These regions drive significant innovation and market expansion for integrated battery management systems. Regulatory frameworks in these areas further accelerate adoption across diverse applications.
China
China's electric vehicle market and consumer electronics assembly fuel immense demand for smart batteries. The Ministry of Ecology and Environment (MEE) and national dual carbon goals shape battery design and recycling mandates. Manufacturers in the Yangtze River Delta region actively integrate advanced BMS solutions into their production lines.
United States
The United States automotive sector and renewable energy storage initiatives drive substantial smart battery integration. US EPA regulations influence battery lifecycle management and material sourcing practices. Innovation centers like Silicon Valley and Detroit focus on next-generation EV battery technologies and software development.
Germany
Germany's robust automotive industry and industrial IoT applications create strong demand for intelligent power packs. The European Union's Battery Regulation mandates digital passports, impacting German manufacturers significantly. Engineering clusters in Bavaria and Baden-Württemberg lead development of high-performance smart battery systems.
Japan
Japan's advanced automotive manufacturing and consumer electronics industries require sophisticated smart battery solutions. The Ministry of Economy, Trade and Industry (METI) promotes battery technology innovation and safety standards. Research hubs in Tokyo and Nagoya contribute to solid-state battery advancements and new material development.
Smart Battery Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the smart battery market. The market exhibits a tiered structure, with a few large integrated players and numerous specialized component providers. Strategic archetypes include custom pack assemblers, BMS software developers, and material science innovators. Technology licensing and strategic partnerships represent dominant competitive moves for market participants.
Specialists in custom battery solutions include Inspired Energy, which focuses on medical and industrial devices requiring precise power delivery. Cadex Electronics exemplifies a provider of critical diagnostic and testing systems, essential for smart battery lifecycle management and performance validation across various industries. Trojan Battery leverages its legacy in deep-cycle batteries, extending its offerings into industrial motive power applications that demand robust and reliable smart power. These entities position themselves by addressing niche requirements and offering specialized value propositions in a market increasingly defined by intelligence.
| Leading Market Players |
|---|
| Trojan Battery |
| Cadex Electronics |
| Accutronics |
| Battery Smart |
| Sealed Energy Systems |
| Epec |
| Rose Batteries |
| Inspired Energy |
| Cell-Con |
| Others |
Cost & Logistics Intelligence
Specialized engineering talent concentrations in regions like Germany and China, critical for advanced Battery Management System (BMS) development, influence labor-cost differentials and thus pricing-tier spreads across the smart battery market.
Pricing Analysis
Volume in the smart battery market sits with mass-produced lithium-ion cells, while margin potential shifts towards specialized, high-performance applications. The dominant pricing structure is contract-based long-term offtake for large electric vehicle manufacturers and tiered premium/standard/economy for industrial and medical devices. Price differentiation stems from performance characteristics like energy density and cycle life, alongside stringent safety certifications such as UL or CE. Pricing pressure stems from intense competition in consumer electronics, while demand for advanced solid-state chemistries supports higher price points. Consumer electronics buyers exhibit the highest price sensitivity, whereas aerospace and medical device integrators are least price-sensitive due to critical reliability requirements.
Supply Chain Analysis
Domestic-content mandates, such as those driven by US EPA regulations or China's dual carbon goals, are reshaping sourcing strategies for smart battery components. Geographic supply concentration for battery cells centers on China, South Korea, and Japan, while critical raw materials like lithium and nickel draw from Australia, Chile, and Indonesia. The supply chain relies on specialized BMS components, often sourced from a limited number of suppliers. A structural risk involves single-source vulnerability for rare earth elements essential in some battery chemistries. Distribution runs through direct supply channels to large electric vehicle OEMs and consumer electronics manufacturers, with specialized distributors serving industrial and medical device integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
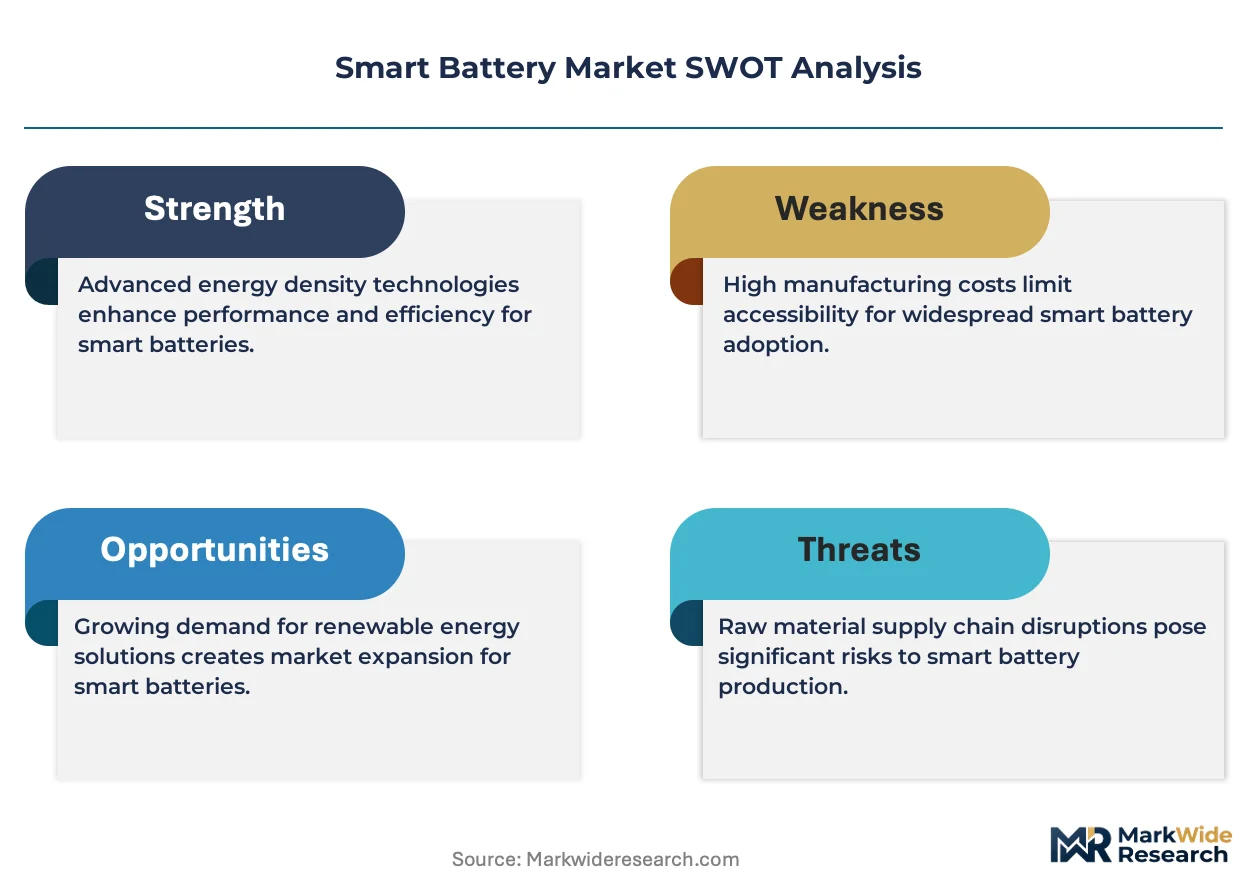
This market is poised for consolidation, driven by the significant capital expenditure required for next-generation battery chemistries and the stringent compliance demands of regulations like the EU Battery Regulation, which forces out undercapitalized players.
For Market Incumbents: To counter rapid technological obsolescence and new entrant innovation, incumbents must invest aggressively in advanced Battery Management System (BMS) software development and secure long-term raw material contracts. Strategic mergers and acquisitions targeting specialized software firms can integrate AI-powered predictive analytics capabilities. Vertical integration into specific cell manufacturing processes for high-performance chemistries provides supply chain control and cost advantages.
For New Entrants and Emerging Players: Enter via niche applications requiring high reliability and specialized performance, such as defense equipment or extreme-environment industrial IoT devices. Focus on developing disruptive solid-state battery component innovations or advanced battery analytics as a service. A strong go-to-market angle involves offering comprehensive lifecycle management solutions that leverage smart battery data for optimized performance and second-life applications, appealing to commercial fleet operators.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized BMS software providers and advanced material science companies given the widespread adoption of digital battery passports and second-life applications. Investors should target firms with proven intellectual property in predictive analytics for battery health or novel cobalt-free cathode materials. The signal to watch is successful commercialization and broad industry adoption of AI-driven battery analytics platforms, indicating a shift towards software-defined battery value.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for High-Nickel Cathodes | This initiative meets the escalating demand from electric vehicle manufacturers, ensuring material availability for next-generation batteries. |
| Advanced BMS Software Development | This enhances data monetization opportunities and optimizes battery performance, supporting new service-based business models for fleet management. |
| Long-term Raw Material Offtake Agreements | These agreements mitigate supply chain risks and stabilize input costs for battery cell producers, ensuring production continuity. |
| Circular Economy Partnerships for Recycling | These collaborations address end-of-life battery management and comply with environmental regulations, improving sustainability credentials. |
| Solid-State Battery R&D Investment | This captures future value by developing safer, higher energy density solutions for electric vehicles and grid storage, driving market leadership. |
Research Approach
Company annual reports, regulatory filings from the US EPA and China's MEE, and industry association publications formed the secondary backbone of this analysis. This initial data was cross-referenced and validated through primary interviews with battery engineers, electric vehicle platform managers, BMS software developers, and raw material suppliers. The approach integrated both bottom-up market sizing and top-down validation to ensure comprehensive coverage.
Historical trendline analysis informed the projection of market trajectories across the analysis window, considering various macroeconomic and technological factors. The analytical framework modeled segmentation dimensions including product type (e.g., lithium-ion, solid-state), application (e.g., electric vehicles, consumer electronics), end-user (e.g., vehicle assemblers, electronics manufacturers), and regional regulatory frameworks. Compound annual growth rates were derived from a multi-variant regression model, with key industry-specific forecast inputs including electric vehicle production targets and raw material price fluctuations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical instability affecting raw material supply or unforeseen technological breakthroughs. These forecasts reflect assumptions regarding market dynamics and regulatory stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
Battery-Powered Riveter Market
Batteries
Forklift Battery Rental Market
Batteries
Advanced Batteries Market
Batteries
East Europe Battery Market
Batteries
Asia-Pacific Rechargeable Battery Market
Batteries
United States SLI Battery Market
Batteries
Molten Salt Battery Market
Batteries
Romania Rechargeable Battery Market
Batteries
Alkaline Secondary Battery Market
Batteries
Absorbed Glass Mat (AGM) Separator Batteries Market
Batteries
Liquid Metal Battery Market
Batteries
Tubular Batteries Market
Batteries
Taiwan Battery Market
Batteries
Portable Battery Market
Batteries
North America Industrial Battery Market