
 South Korea Rechargeable Battery Market | 2026-2036
South Korea Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Rechargeable Battery Market Insights
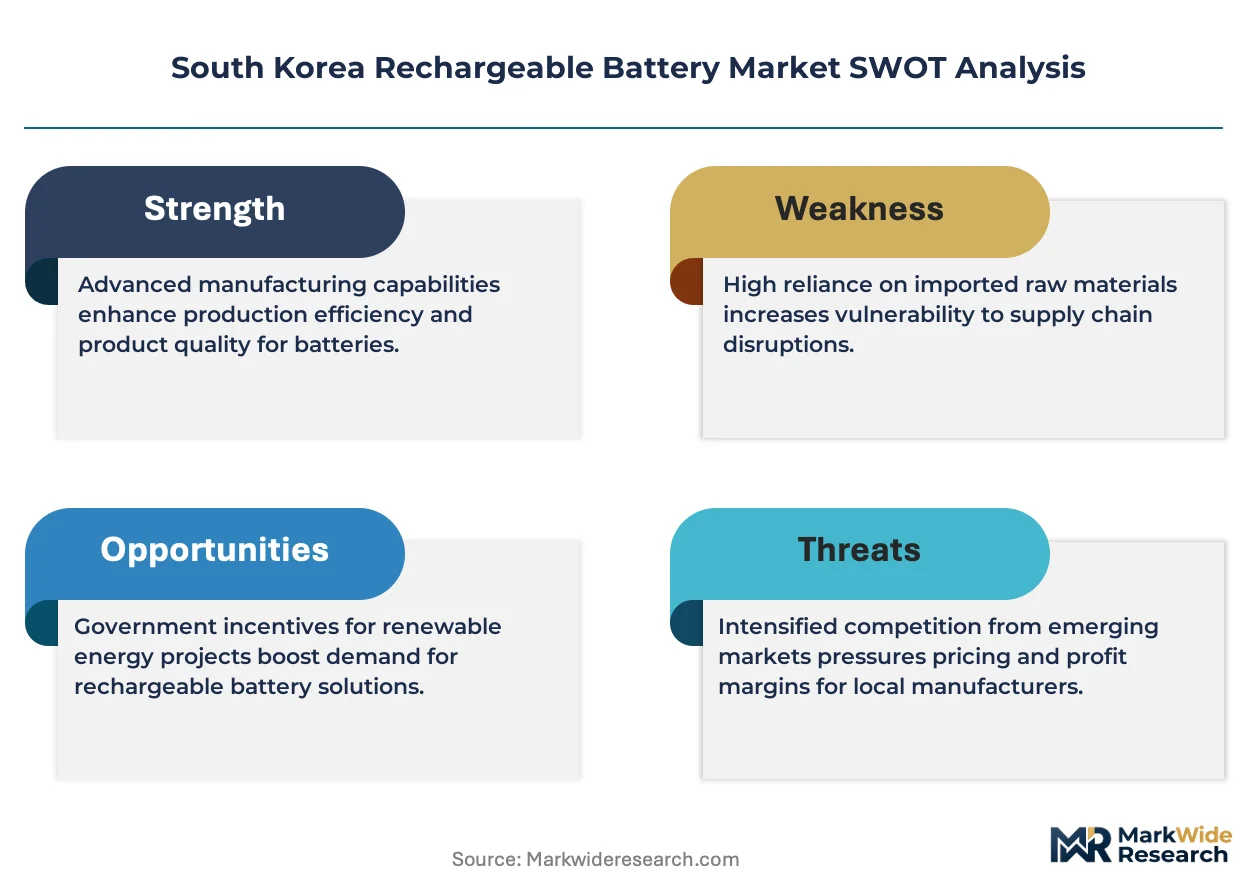
Capital-intensity divergence between fully integrated cathode producers and assembly-only operators is bifurcating competitive tiers in the South Korea Rechargeable Battery Market. LG Energy Solution leverages captive mining partnerships and in-house precursor production to sustain margin capture across the value chain. Samsung SDI anchors its position through silicon-anode R&D intensity and premium automotive qualification programs. SK On competes aggressively on manufacturing scale but navigates narrower upstream control compared to domestic rivals.
A rechargeable battery stores electrochemical energy through reversible redox reactions, with lithium-ion variants employing layered oxide cathodes and graphite or silicon-composite anodes separated by microporous polyolefin membranes to achieve energy densities exceeding 250 Wh/kg for mobility applications. The South Korea Rechargeable Battery Market segments across product type, end user, technology, and application dimensions. Lithium-ion chemistry dominates installed capacity and attracts the majority of capital deployment, while solid-state formats represent the fastest-growing technology segment as manufacturers race to eliminate flammable liquid electrolytes. Electric Vehicles as an end-user category commands the largest revenue pool, though Energy Storage Systems is gaining share as grid-scale deployments accelerate under renewable integration mandates.
MFDS oversight of cell safety certification, KATS administration of KS C IEC 62660 standards, and the Ministry of Trade, Industry and Energy's K-Battery Act collectively shape product approval timelines, domestic content thresholds, and factory investment incentives. The Korea Energy Agency's ESS fire-safety protocols have tightened thermal runaway testing requirements, redirecting R&D budgets toward ceramic separator and flame-retardant electrolyte development. Stakeholders must monitor how evolving EU Battery Regulation carbon-footprint rules will affect Korean export competitiveness and whether domestic recycling quotas under the K-Battery Act will force backward integration into black mass processing.
Market Dynamics
The K-Battery Act's domestic content mandates are restructuring supply chain ownership patterns, forcing manufacturers to localize precursor production and recycling infrastructure or forfeit public procurement eligibility.
Growth Catalysts
- Electric vehicle assembly expansion:Hyundai Motor Group and Kia are scaling dedicated EV platforms, creating captive demand for high-nickel cathode cells produced within national borders.
- MFDS safety certification acceleration:Streamlined cell testing protocols for automotive-grade lithium-ion packs are compressing product approval timelines from eighteen to twelve months.
- Silicon-anode material advances:Domestic R&D consortia are achieving 400 Wh/kg prototype energy densities, positioning Korean suppliers for next-generation mobility contracts.
Market Restraints
- Cobalt and lithium price volatility:Concentrated DRC mining exposure and Chilean-Argentine brine processing bottlenecks are amplifying input cost instability for cathode manufacturers.
- Chinese cathode precursor dominance:Over seventy percent of global NCM precursor refining capacity resides in Chinese industrial zones, creating supply concentration vulnerability.
- Liquid electrolyte flammability ceiling:Thermal runaway propagation risks in high-energy-density cells are limiting pack-level energy density gains and complicating ESS deployment.
Strategic Opportunities
- Black mass recycling infrastructure:K-Battery Act recycling quotas are incentivizing domestic hydrometallurgical recovery facilities for lithium, nickel, and cobalt from end-of-life cells.
- Grid-scale ESS deployment:Korea Energy Agency renewable integration mandates are opening multi-gigawatt-hour procurement tenders for utility-scale battery storage.
- Solid-state electrolyte convergence:Sulfide-based ceramic conductor development is converging with dry electrode coating processes to enable flammable-liquid-free cell architectures.
Industry Challenges
- Electrolyte formulation chemist scarcity:Specialized talent pools for non-flammable ionic liquid development are insufficient relative to solid-state roadmap timelines.
- KS C IEC 62660 certification complexity:Evolving automotive cell testing standards are extending qualification cycles and requiring redundant validation across OEM programs.
- Legacy wet-coating asset stranding:Existing electrode production lines face obsolescence risk as dry electrode processes achieve commercial scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Rechargeable Battery Market |
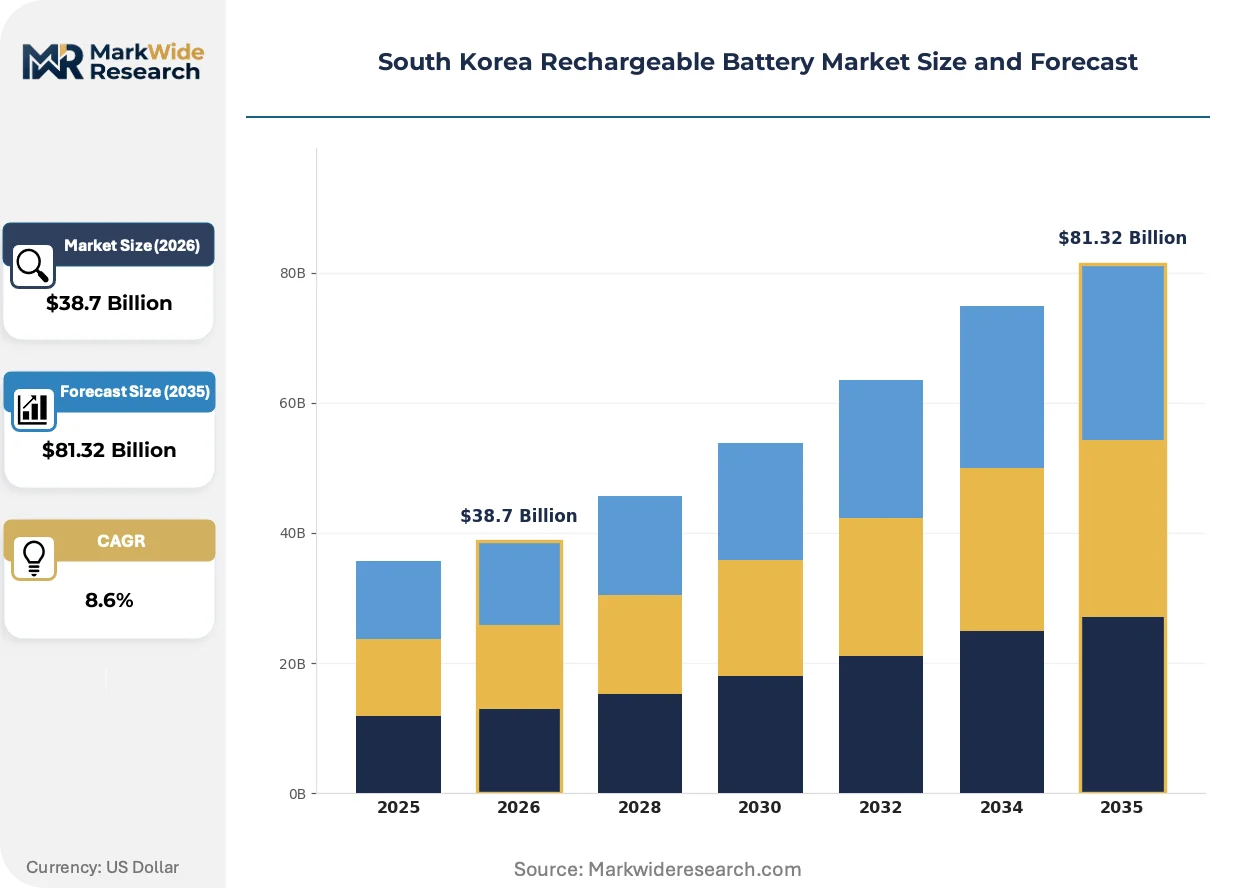
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-Metal Hydride, Lead-Acid, Solid-State End User: Consumer Electronics, Electric Vehicles, Energy Storage Systems, Industrial Equipment Technology: Fast Charging, Wireless Charging, GPS Integrated, Smart Battery Management Application: Mobility Solutions, Renewable Energy, Wearable Devices, Home Appliances |
| Companies Covered | LG Energy Solution, Samsung SDI, SK On, CATL, Panasonic Corporation, BYD Co. Ltd., Contemporary Amperex Technology Co. Ltd., GS Yuasa Corporation, Exide Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Rechargeable Battery Market Trends and Innovations
Materials science breakthroughs and regulatory pressure on thermal safety are converging to accelerate format diversification and manufacturing process reinvention across Korean cell production.
Silicon-composite anode technology is fragmenting the traditional graphite-dominated supply base. Automotive OEMs are qualifying silicon oxide blends for 2026 platform launches, demanding electrode binder reformulations and electrolyte additive packages. This material transition is fragmenting incumbent supplier relationships as anode specialists capture value previously held by integrated graphite producers.
MFDS and KATS are tightening KS C IEC 62660-2 abuse testing protocols for automotive cells, mandating nail penetration without thermal runaway propagation. The regulatory consequence is redirecting R&D expenditure toward ceramic-coated separators and self-extinguishing electrolyte additives. Premium automotive qualification programs are absorbing the compliance burden fastest, while ESS manufacturers lag in thermal management system redesign.
Cell procurement is consolidating around long-term offtake contracts with price-volume flexibility clauses. Tier-one automotive buyers are displacing spot-market purchasing with ten-year supply agreements indexed to cathode metal prices. This contracting evolution is most visible in Seoul and Gyeonggi-do, where LG Energy Solution and Samsung SDI are negotiating directly with Hyundai-Kia platform teams rather than through trading intermediaries.
South Korea Rechargeable Battery Market Segmentation
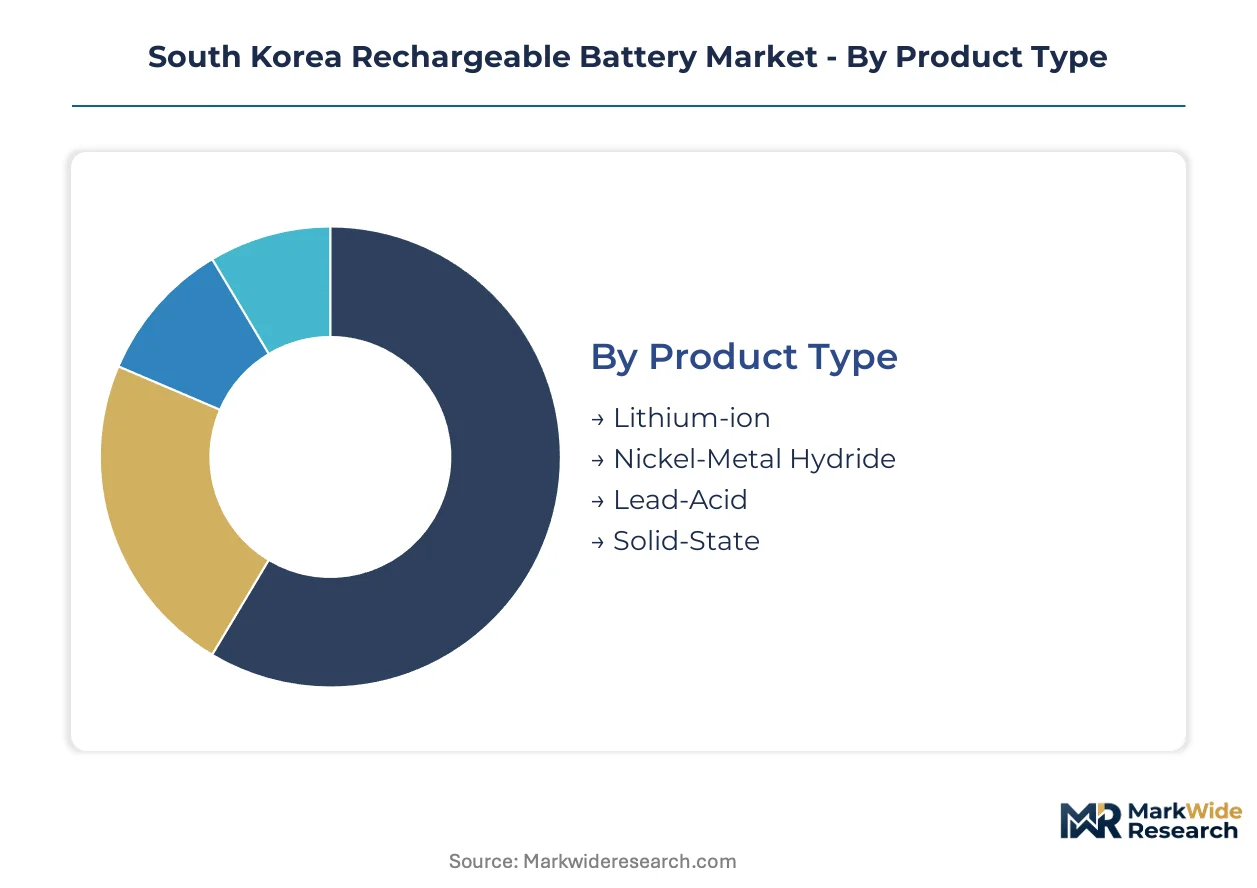
Segmentation in the South Korea Rechargeable Battery Market reveals how regulatory mandates and end-use specifications fragment procurement requirements. The K-Battery Act's domestic content thresholds create divergent compliance burdens across chemistry types and customer categories.
Product Type:
MFDS safety certification intensity varies sharply by electrochemical system, with lithium-ion formats facing the most stringent KS C IEC 62660-2 abuse testing protocols while solid-state architectures encounter evolving approval frameworks.
- Lithium-ion:Layered oxide cathodes paired with graphite or silicon-composite anodes deliver energy densities above 250 Wh/kg. Demand concentrates in Seoul and Gyeonggi-do automotive assembly corridors where Hyundai-Kia platform teams specify high-nickel NCM formulations for dedicated EV architectures. The K-Battery Act's precursor localization mandates force cathode manufacturers to secure domestic refining partnerships or forfeit public procurement eligibility.
- Solid-State:Sulfide-based ceramic conductors eliminate flammable liquid electrolytes through all-solid architectures. Pilot production lines in Daejeon and Ulsan are scaling sulfide electrolyte synthesis for 2026 automotive qualification programs. MFDS has yet to finalize thermal runaway testing protocols for solid-state formats, compressing product approval timelines relative to conventional lithium-ion.
- Nickel-Metal Hydride:Mature chemistry retains position in hybrid electric vehicle auxiliary power units where cost sensitivity outweighs energy density requirements.
- Lead-Acid:Stationary backup and starter-lighting-ignition applications in legacy industrial facilities; minimal R&D investment flows to this segment under K-Battery Act incentive structures.
Established volume favors Lithium-ion; emerging adoption favors Solid-State.
End User:
Customer procurement scale determines contract structure, with automotive OEMs negotiating decade-long offtake agreements while consumer electronics buyers maintain spot-market flexibility.
- Electric Vehicles:Dedicated EV platforms from Hyundai Motor Group and Kia generate captive demand for automotive-grade cells with ten-year cycle life warranties. Gyeonggi-do battery cluster producers are locking in direct supply relationships with platform engineering teams, displacing trading intermediaries. The Korea Energy Agency's renewable integration mandates are accelerating parallel ESS procurement from the same manufacturing base.
- Energy Storage Systems:Grid-scale deployments exceeding 100 MWh per project are gaining share as utility procurement tenders open under renewable portfolio standards. Fire-safety protocols tightened following 2018-2019 thermal runaway incidents now require ceramic separator and flame-retardant electrolyte specifications. Domestic content thresholds under K-Battery Act recycling quotas are redirecting capital toward black mass recovery infrastructure.
- Consumer Electronics:Smartphone and laptop manufacturers in Suwon and Gumi prioritize energy density and form factor flexibility over cycle life.
- Industrial Equipment:Forklift and material handling systems in Busan and Incheon port logistics clusters demand ruggedized thermal management.
Automotive offtake commands premium pricing; utility-scale ESS procurement is expanding most quickly.
Technology:
Manufacturing process maturity fragments competitive positioning, with fast charging already commercial at scale while wireless formats remain niche.
- Fast Charging:Silicon-anode compatibility and electrolyte additive packages enable 10-80% state-of-charge cycles. Domestic R&D consortia are achieving 400 Wh/kg prototype densities for next-generation mobility contracts. SK On and Samsung SDI are prioritizing fast-charge qualification programs with Hyundai-Kia platform teams.
- Smart Battery Management:Cell-level sensing and predictive thermal runaway algorithms are becoming mandatory for ESS deployment under Korea Energy Agency safety protocols. Embedded firmware development is concentrating in Seongnam and Pangyo software clusters.
- Wireless Charging:Inductive pad architectures for premium consumer electronics; limited penetration in automotive due to efficiency losses and alignment sensitivity.
- GPS Integrated:Fleet management and asset tracking applications in logistics and shared mobility services.
Fast Charging dominates capital deployment; Smart Battery Management is climbing the fastest.
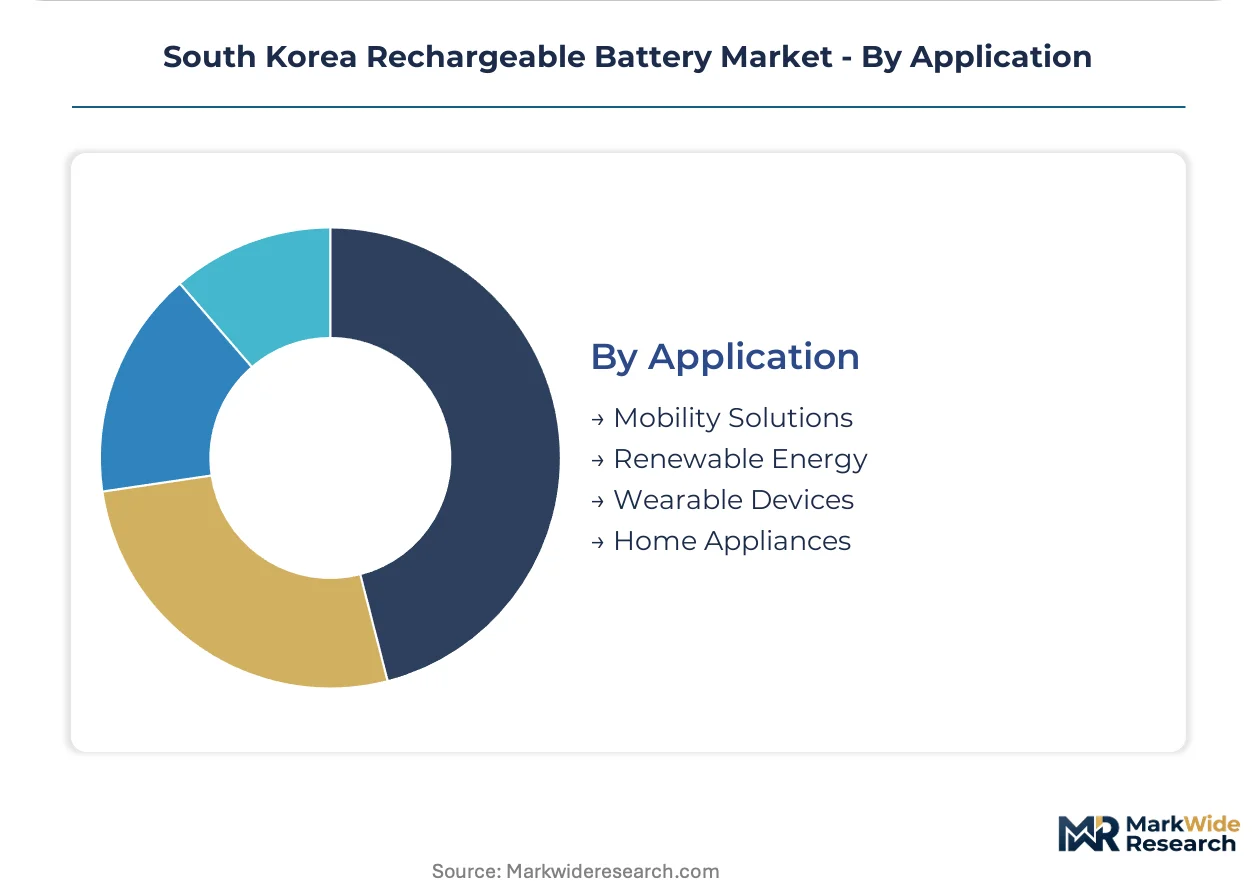
Application:
Performance specifications diverge by mobility intensity, with automotive applications demanding cycle life extremes while wearable formats prioritize mass minimization.
- Mobility Solutions:Electric passenger vehicles, buses, and two-wheelers constitute the largest revenue pool. High-nickel cathode cells from Gyeonggi-do production lines are qualifying for export markets facing EU Battery Regulation carbon-footprint disclosure requirements.
- Renewable Energy:Solar and wind integration mandates are opening multi-gigawatt-hour utility tenders. Korea Energy Agency procurement specifications favor domestic cell assembly and K-Battery Act-compliant recycling infrastructure.
- Wearable Devices:Flexible and curved cell formats for smartwatches and health monitors; Seoul-based design houses specify ultra-thin polymer pouch architectures.
- Home Appliances:Cordless vacuum and power tool battery packs; moderate energy density requirements with emphasis on cost optimization.
Mobility Solutions anchor current volume; Renewable Energy applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul Capital Area concentrates high-nickel cathode production for export-bound automotive cells, while Busan-Ulsan handles precursor refining and port logistics. Daegu-Gyeongbuk and Daejeon-Sejong split solid-state R&D and pilot manufacturing. Gwangju-Honam trails in cell assembly but anchors recycling infrastructure development.
Seoul Capital Area
Hyundai Motor Group and Kia platform teams in Hwaseong and Namyang generate captive demand for automotive-grade cells with ten-year cycle life warranties. MFDS streamlined KS C IEC 62660-2 certification protocols compress approval timelines from eighteen to twelve months. Gyeonggi-do battery cluster producers in Seongnam and Suwon are locking in direct supply relationships, displacing trading intermediaries.
Busan-Ulsan
Port logistics clusters in Busan handle cobalt and lithium concentrate imports from DRC and Chilean-Argentine brine sources. The Ministry of Trade, Industry and Energy's K-Battery Act mandates domestic precursor refining thresholds for public procurement eligibility. Ulsan industrial zones concentrate hydrometallurgical recovery facilities for black mass processing from end-of-life cells.
Daegu-Gyeongbuk
Silicon-anode material advances from domestic R&D consortia are achieving prototype energy densities exceeding 400 Wh/kg for next-generation mobility contracts. Korea Energy Agency ESS fire-safety protocols tightened thermal runaway testing requirements following 2018-2019 incidents. Pohang and Gumi host electrode binder reformulation specialists serving automotive qualification programs.
Daejeon-Sejong
Sulfide-based ceramic conductor development converges with dry electrode coating processes in government-funded pilot lines. MFDS has yet to finalize thermal runaway testing protocols for solid-state formats, compressing product approval timelines relative to conventional lithium-ion. Korea Institute of Science and Technology campuses anchor public-private R&D partnerships for all-solid cell architectures.
Gwangju-Honam
K-Battery Act recycling quotas are incentivizing domestic hydrometallurgical recovery facilities for lithium, nickel, and cobalt recovery. Grid-scale ESS deployment under renewable integration mandates opens multi-gigawatt-hour procurement tenders. Yeosu and Gwangyang industrial zones concentrate black mass preprocessing capacity with coastal access for feedstock logistics.
South Korea Rechargeable Battery Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the South Korea Rechargeable Battery Market. Fully integrated cathode producers with captive mining partnerships and in-house precursor production capture margin across the value chain, while assembly-only operators navigate narrower upstream control. Three archetypes dominate: backward-integrated material specialists, scale-driven manufacturing platforms, and premium automotive qualification anchors. Competitive moves concentrate on long-term offtake contract negotiation and dry electrode process adoption to avoid legacy wet-coating asset stranding.
Within the integrated leader tier, LG Energy Solution, Samsung SDI, and SK On occupy positions that exemplify divergent strategic emphases. LG Energy Solution represents the backward-integrated archetype through captive supply arrangements. Samsung SDI anchors the premium-tier qualification vector with silicon-anode R&D intensity. SK On sits within the scale-driven manufacturing tier, competing aggressively on production volume. These three Korean entities collectively shape domestic content thresholds and supplier relationship structures under K-Battery Act compliance frameworks.
| Leading Market Players |
|---|
| LG Energy Solution |
| Samsung SDI |
| SK On |
| CATL |
| Panasonic Corporation |
| BYD Co. Ltd. |
| Contemporary Amperex Technology Co. Ltd. |
| GS Yuasa Corporation |
| Exide Industries |
| Others |
Pricing and Supply Chain Analysis
Ninety-day cathode precursor inventory buffers at Gyeonggi-do cell plants signal how Korean manufacturers balance Chinese refining concentration against K-Battery Act localization mandates. This lead-time exposure concentrates pricing power with integrated producers holding captive mining partnerships while forcing assembly-only operators into metal-price-indexed contract renegotiations.
Pricing Analysis
Long-term offtake contracts with volume-flexibility clauses dominate automotive procurement, displacing spot-market purchasing for high-nickel cathode cells. Pricing stratifies across premium automotive qualification tiers, standard industrial ESS formats, and economy consumer electronics pouches based on MFDS certification intensity and cycle-life warranties. Cost compression in mid-tier NCM formulations is intensifying because Chinese precursor producers are expanding refining capacity faster than Korean localization mandates can redirect supply chains. Automotive OEMs show least price sensitivity due to platform-level cell qualification lock-ins, while consumer electronics buyers in Suwon and Gumi maintain spot-market flexibility.
Supply Chain Analysis
Port congestion at Busan and Ulsan container terminals amplifies inbound logistics costs for DRC cobalt concentrate and Chilean-Argentine lithium carbonate shipments. Geographic supply concentration centers on Chinese NCM precursor refining zones, Indonesian nickel processing parks, and Australian spodumene mining districts. Raw material dependencies rest on cobalt sulfate, lithium hydroxide, and high-purity nickel cathode feedstocks. Single-source vulnerability from Chinese precursor dominance above seventy percent of global capacity creates structural supply chain risk. Distribution runs through direct OEM supply relationships in Seoul-Gyeonggi automotive corridors rather than trading intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Korea Rechargeable Battery Market sits at a platform-economics inflection where Hyundai-Kia dedicated EV architectures are consolidating cell procurement around standardized module interfaces. This interoperability shift rewards suppliers qualifying across multiple OEM platforms while marginalizing single-program specialists.
For Market Incumbents: Fortify backward integration into black mass hydrometallurgical recovery to meet K-Battery Act recycling quotas and defend margin capture against Chinese cathode precursor price competition. Secure dry electrode coating pilot lines before legacy wet-coating asset stranding accelerates, and deepen MFDS automotive qualification relationships to lock out second-tier challengers.
For New Entrants and Emerging Players: Lead with solid-state electrolyte synthesis specialization targeting Daejeon-Sejong government-funded pilot line partnerships where MFDS approval protocols remain unsettled. The most penetrable white space sits in ceramic separator manufacturing for ESS fire-safety compliance, with a go-to-market angle anchored to Korea Energy Agency grid-scale procurement tenders.
For Investors and Strategic Acquirers: Long-term, this sits as a materials-chemistry consolidation play because cathode precursor localization mandates and recycling infrastructure buildouts will concentrate value capture with integrated hydrometallurgical operators. Target acquisition archetypes include black mass preprocessing facilities with coastal logistics access and sulfide electrolyte synthesis specialists. The signal to watch is MFDS finalization of solid-state thermal runaway testing protocols as inflection indicator for qualification timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Refining | K-Battery Act domestic content thresholds force captive refining capacity to maintain public procurement eligibility. |
| Dry Electrode Process Adoption | Eliminates solvent recovery costs and avoids stranded wet-coating asset risk as manufacturing scales. |
| Solid-State Electrolyte Synthesis Scale-Up | Sulfide-based ceramic conductor development converges with flammable-liquid-free cell architectures for next-generation platforms. |
| Black Mass Recycling Infrastructure Buildout | Hydrometallurgical recovery facilities in Ulsan and Gwangju-Honam secure lithium, nickel, and cobalt from end-of-life cells. |
| Long-Term Automotive Offtake Negotiation | Ten-year supply agreements with Hyundai-Kia platform teams displace spot purchasing and lock in volume commitments. |
Research Methodology
Desk research of customs trade databases, MFDS regulatory filings, and Korea Energy Agency procurement records preceded structured interviews with cathode manufacturing plant managers, automotive platform engineering directors, ESS project developers, and black mass recycling facility operators. Primary fieldwork with Gyeonggi-do battery cluster stakeholders combined with secondary validation from SEC filings of listed Korean cell producers and KATS standards documentation. Bottom-up cell production capacity modeling triangulated against top-down EV platform demand forecasts from Hyundai Motor Group and Kia disclosure patterns.
Variance decomposition across chemistry type, end-user category, and regional production cluster dimensions shaped the analytical framework over the projection horizon. Segmentation modeling captured lithium-ion versus solid-state format splits, automotive versus ESS versus consumer electronics demand pools, and Seoul-Gyeonggi versus Busan-Ulsan versus Daejeon-Sejong supply base concentrations. CAGRs derived from installed capacity buildout timelines and metal price trajectory assumptions. Industry-specific forecast inputs included silicon-anode qualification progress and K-Battery Act recycling quota implementation schedules.
Forecasts assume regulatory continuity in MFDS safety certification protocols and K-Battery Act domestic content regimes; material policy shifts would require re-modeling. Forecasts reflect assumptions regarding DRC mining output stability and Chinese precursor export licensing continuity. Recalibration cycles align with material shifts in cathode metal price volatility and solid-state pilot production yield achievements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Modular Battery Market
Batteries
Indonesia Battery Market
Batteries
North America Industrial Battery Market
Batteries
Aluminium-Sulfur Battery Market
Batteries
GCC Rechargeable Battery Market
Batteries
Global Primary Cells Market
Batteries
Portable Battery Station Market
Batteries
Zinc Carbon Battery Market
Batteries
Lithium Carbon Monofluoride Battery Market
Batteries
AAA Battery Market
Batteries
Zinc Ion Batteries Market
Batteries
Rechargeable Battery Market
Batteries
Global Coke Oven Batteries Market
Batteries
Romania Rechargeable Battery Market
Batteries
3D-Printed Battery Market
Batteries
Zinc-Manganese Oxide Printed Battery Market